
 Australia Food Cans Market | 2026-2036
Australia Food Cans Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Food Cans Market Insights
Market Dynamics
Australia is reshaping food can supply capacity through sustained investment in domestic steel and aluminum can manufacturing. Visy Group leverages its integrated recycling and packaging operations across multiple Australian states. CCL Industries Inc. anchors its position through specialized label and container solutions for food brands. Jamestrong Packaging competes with advanced forming technologies for premium canned goods.
Product Landscape
Australia food cans are cylindrical metal containers, typically fabricated from tinplate steel or aluminum alloy with internal lacquer coatings, designed for thermal sterilization and shelf-stable food preservation. Steel cans retain dominance in vegetable and processed food applications due to structural integrity under retort conditions, while aluminum cans capture share in beverage-adjacent and premium food categories where lightweighting matters. Pull-tab closures lead volume given convenience demands, though twist-off formats gain traction in specialty and resealable food segments. Small and medium container sizes command the strongest demand alignment with single-serve and household consumption patterns.
Regulatory Environment
The Australian Packaging Covenant Organisation (APCO) enforces national targets for recyclable and recycled content that directly shape can design specifications and material sourcing obligations. Food Standards Australia New Zealand (FSANZ) governs food contact material safety, while the National Plastics Plan indirectly pressures metal can alternatives through broader sustainable packaging policy. Stakeholders must monitor evolving extended producer responsibility frameworks and state-level container deposit scheme expansions that will reshape collection infrastructure and circular economy participation requirements.
Market Dynamics
Australia's National Plastics Plan and APCO recycled content mandates are compressing lead times for can manufacturers. Domestic steel and aluminum supply concentration in Victoria and New South Wales creates procurement bottlenecks as processors race to certify circular material streams.
Growth Catalysts
- APCO Packaging Targets:Mandatory recycled content thresholds for metal packaging are pulling forward investment in domestic can-to-can recycling infrastructure. Processors must certify supply chains by 2025 compliance deadlines.
- Canned Seafood Demand:Processors in Tasmania and South Australia are expanding thermal sterilization capacity. This end-use vertical accounts for disproportionate volume growth in two-piece aluminum formats.
- East Coast Manufacturing Clusters:Victoria and New South Wales concentrate food manufacturing. Proximity to Melbourne and Sydney distribution hubs reduces freight costs for shelf-stable goods.
Market Restraints
- Tinplate Steel Price Volatility:Australian dollar fluctuations against USD-denominated steel imports compress margin predictability. Domestic rolling mill capacity constraints amplify input cost swings.
- Container Deposit Scheme Fragmentation:State-level scheme variations in Queensland, New South Wales, and Victoria create compliance complexity. Collection infrastructure gaps in Western Australia and Tasmania limit circular participation.
- Flexible Pouch Substitution:Retort pouches capture shelf-stable seafood and ready-meal share. Lightweighting and microwave convenience are displacing traditional three-piece steel in premium segments.
Strategic Opportunities
- Western Australia Underpenetration:Perth food manufacturing lags east coast density. Establishing regional can supply would capture mining camp and remote community distribution channels.
- Digital Printing Convergence:UV-cured inkjet on metal substrates enables short-run customization. Craft food brands are adopting variable artwork for seasonal and limited-release positioning.
- Queensland Container Deposit Expansion:Pending scheme harmonization will unlock collected aluminum volume. Reverse logistics infrastructure investment precedes can-to-can closed loop completion.
Industry Challenges
- Retort Equipment Technician Scarcity:Thermal sterilization engineering expertise concentrates with aging workforce. Vocational pipeline gaps threaten maintenance capacity expansion.
- FSANZ Food Contact Certification Timelines:New internal lacquer formulations face extended safety assessment queues. Reformulation for recycled content compatibility delays commercialization.
- Legacy ERP Integration with Traceability Systems:Batch-level material provenance requirements strain aluminum smelter-to-can plant data architecture. Middleware development consumes unplanned capex.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Food Cans Market |
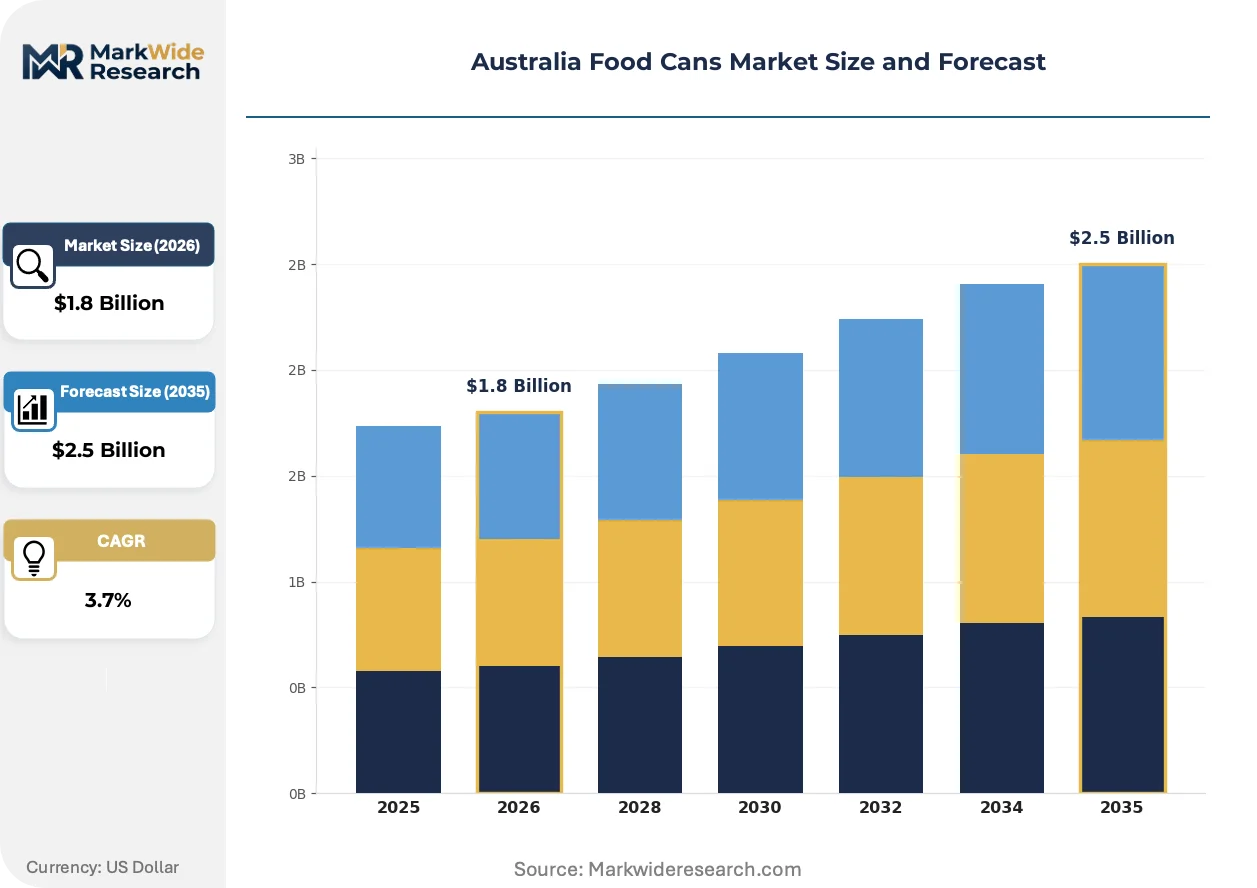
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Cans, Steel Cans, Biodegradable Cans, Composite Cans End User: Retailers, Food Manufacturers, Restaurants, Food Service Providers Container Size: Small Cans, Medium Cans, Large Cans, Extra-Large Cans Closure Type: Pull-Tab, Can Ends, Twist-Off, Screw Caps |
| Companies Covered | CCL Industries Inc., Primepac, Visy Group, Sonoco Products Company, Jamestrong Packaging, Perennial Packaging, Morris McMahon & Co Pvt. Ltd, NCI Packaging, Irwin Packaging Holdings Pty Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Food Cans Market Trends and Innovations
Material science advances and regulatory compression are redefining can design specifications. Australian manufacturers are prioritizing lightweighting, recycled content verification, and digital production flexibility to meet covenant obligations and buyer procurement criteria.
High-strength aluminum alloys with reduced wall thickness are rendering obsolete traditional steel can specifications for non-acidic food categories. Premium ready-meal brands are adopting these substrates for shelf appeal and freight efficiency. The structural consequence is compressing two-piece can lines into configurations previously reserved for beverage applications.
APCO's 2025 recycled content trajectory is mandating mass balance certification for metal packaging. Food Standards Australia New Zealand is aligning food contact safety assessments with circular material documentation requirements. Canned vegetable processors in Victoria face the steepest compliance curve as they retrofit supply chains for post-consumer aluminum verification.
Direct-to-retailer procurement contracts are consolidating buyer power among supermarket chains. Traditional distributor intermediaries are losing volume as Coles and Woolworths mandate supplier sustainability scorecards. This pattern concentrates most visibly in New South Wales, where Sydney-headquartered retailers pilot blockchain-enabled provenance tracking for private-label canned goods.
Australia Food Cans Market Segmentation
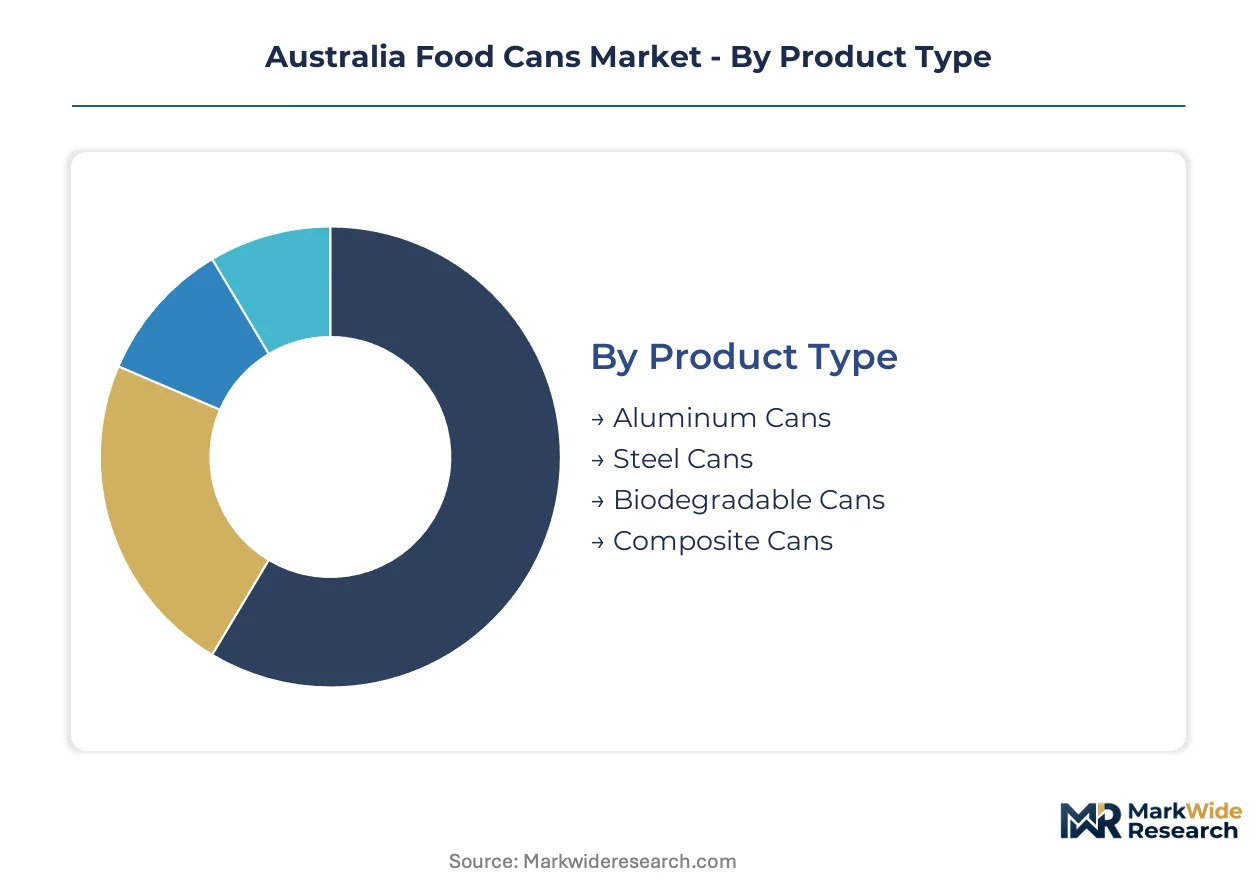
Segmentation in Australian food cans reveals how material science, supply chain configuration, and end-use requirements fragment procurement patterns. Buyers optimize across thermal performance, freight economics, and APCO compliance thresholds.
Product Type:
Material selection in Australian food cans hinges on retort compatibility, recycled content certification timelines, and freight density economics.
- Aluminum Cans:Two-piece drawn-and-walled construction with reduced gauge high-strength alloys enables lightweighting for beverage-adjacent and premium ready-meal categories. Demand concentrates in Tasmania and South Australia where canned seafood processors prioritize thermal sterilization efficiency and shelf appeal. APCO recycled content mandates are accelerating domestic can-to-can recycling infrastructure investment.
- Steel Cans:Three-piece tinplate construction with internal epoxy-phenolic lacquer coatings withstands aggressive retort conditions for vegetable and processed food applications. Victoria's food manufacturing clusters anchor procurement volume due to proximity to Melbourne distribution hubs and legacy canning infrastructure. Australian dollar volatility against USD-denominated steel imports compresses margin predictability.
- Biodegradable Cans:Emerging bio-based barrier coatings on fiber substrates target niche organic and premium positioning where plastic avoidance outweighs shelf-life requirements.
- Composite Cans:Spiral-wound paperboard bodies with metal ends serve dry goods and specialty segments where structural rigidity matters less than graphic surface area.
Steel cans command the established base. The steepest expansion runs through aluminum formats as seafood processors retrofit capacity.
End User:
Customer type determines order scale, sustainability documentation requirements, and direct procurement versus distributor channel selection.
- Food Manufacturers:Integrated canning operations in Victoria and New South Wales purchase direct from domestic producers under long-term supply agreements with APCO compliance riders. Coles and Woolworths sustainability scorecards are consolidating buyer power and squeezing distributor intermediaries.
- Retailers:Supermarket chains are piloting blockchain-enabled provenance tracking for private-label shelf-stable goods, particularly in Sydney-headquartered operations. Direct-to-retailer contracts are reshaping traditional supply hierarchies.
- Food Service Providers:Institutional and mining camp catering operations in Western Australia source through wholesale distributors with less stringent recycled content verification.
- Restaurants:Limited penetration outside premium casual dining where craft presentation drives small-format specialty can adoption.
Food manufacturers absorb the volume concentration. Retailers are capturing share fastest through private-label expansion and sustainability mandate enforcement.
Container Size:
Dimension selection aligns with household composition trends, consumption occasion fragmentation, and retail shelf space economics.
- Small Cans:Single-serve formats for ready-meal and snack categories match aging demographics and solo household growth in Sydney and Melbourne metro areas.
- Medium Cans:Standard household sizes for vegetable and processed staples dominate Victorian production lines serving east coast supermarkets.
- Large Cans:Food service and institutional quantities concentrate in mining camp and remote community distribution channels.
- Extra-Large Cans:Industrial and export-oriented seafood processing in South Australia utilizes bulk formats for ingredient supply to secondary processors.
Medium cans retain the volume anchor. Small formats are climbing the fastest as portion control and convenience reshape purchasing patterns.
Closure Type:
Opening mechanism selection balances consumer convenience, resealability requirements, and manufacturing line compatibility.
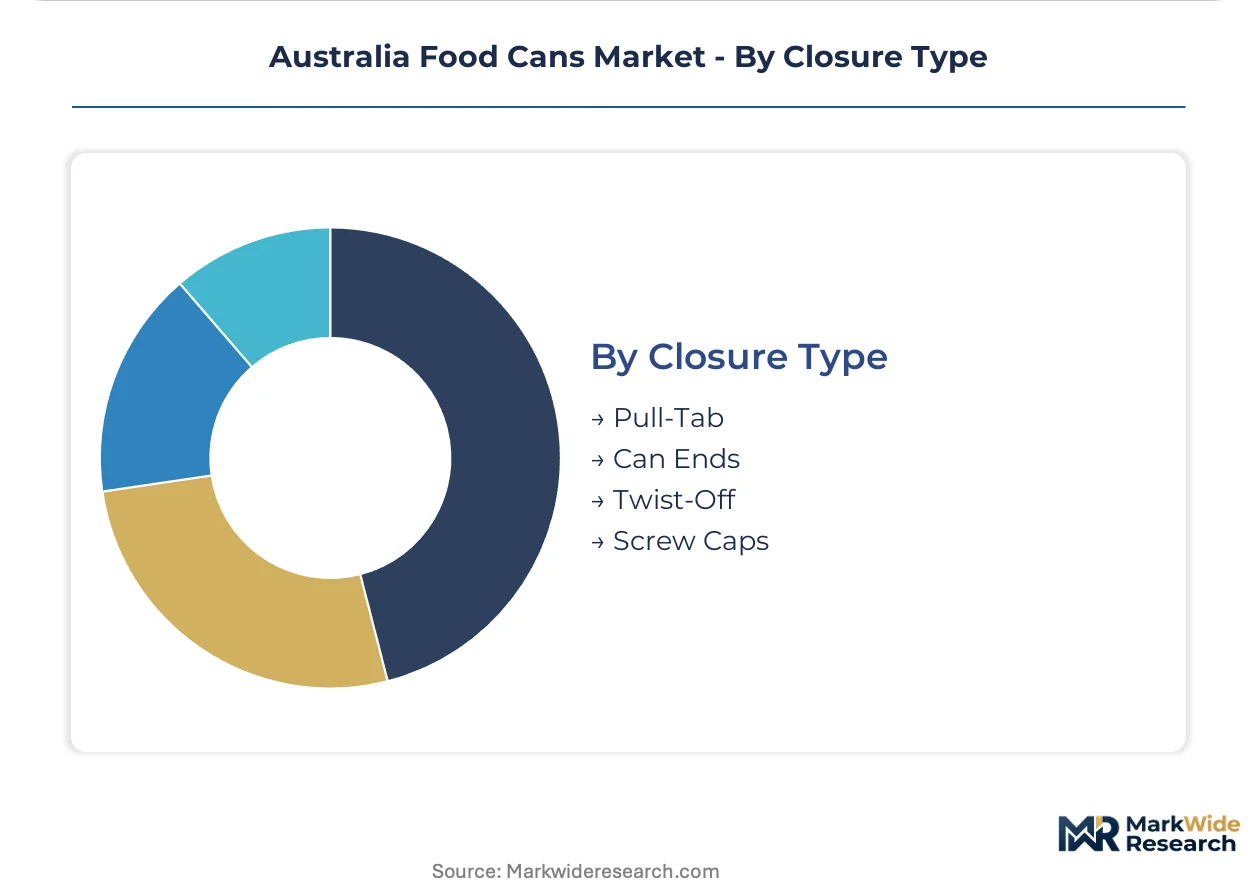
- Pull-Tab:Ring-pull aluminum ends dominate beverage-adjacent and mass-market food categories where one-handed opening and tamper evidence are non-negotiable.
- Can Ends:Traditional seamed steel ends retain cost advantage for high-volume vegetable canning in legacy three-piece lines.
- Twist-Off:Resealable metal closures gain traction in specialty and premium segments where partial consumption and refrigeration continuation matter.
- Screw Caps:Limited adoption in composite can formats for dry goods where repeated access is valued over hermetic seal integrity.
Pull-tab configurations hold the installed base. Twist-off mechanisms are gaining share fastest in premium positioning and resealable convenience segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Melbourne anchors Australia's food can distribution network, handling the majority of tinplate steel imports and finished can exports that feed domestic manufacturing clusters across the southeast.
New South Wales
Sydney-headquartered supermarket chains drive direct-to-retailer procurement consolidation. The state's container deposit scheme creates collection infrastructure complexity that aluminum processors must navigate. Newcastle and Wollongong industrial corridors host legacy canning equipment serving vegetable processors.
Victoria
Melbourne's food manufacturing density generates the nation's highest per-capita can consumption. APCO recycled content mandates are compressing lead times for local steel and aluminum suppliers. The Laverton industrial precinct concentrates thermal sterilization capacity for ready-meal producers.
Queensland
Pending harmonization of container deposit legislation will unlock collected aluminum volume for can-to-can recycling. Brisbane's distribution hubs serve remote mining camp catering operations with bulk-format steel cans. The state's sugar and tropical fruit processors represent emerging demand for specialty can formats.
Western Australia
Perth's underpenetrated food manufacturing base leaves regional can supply dependent on east coast freight. Mining camp institutional demand concentrates in Kalgoorlie and Pilbara distribution channels. Local container deposit scheme gaps limit circular economy participation for aluminum recovery.
South Australia
Tasmanian seafood processors source through Adelaide logistics corridors for export-oriented thermal sterilization. The state's wine industry drives niche demand for premium aluminum formats. Port Adelaide handles bulk tinplate imports for vegetable canning operations serving domestic staples markets.
Australia Food Cans Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope. The vendor base fragments across integrated recycling-packaging conglomerates, specialized label and container solution providers, and regional forming technology specialists. Three archetypes dominate: vertically integrated metal packaging platforms, precision forming equipment specialists, and sustainability-certification-focused contract manufacturers. Capacity expansion and APCO compliance certification represent the dominant competitive moves as 2025 deadlines approach.
Within the integrated platform tier, Visy Group and CCL Industries Inc. exemplify divergent strategic positions. Visy Group leverages cross-state recycling and packaging operations to capture circular material flow advantages. CCL Industries Inc. anchors specialized label and container solutions that food brands require for premium positioning. Jamestrong Packaging occupies a position among advanced forming technology specialists serving premium canned goods segments. These three represent the structural spectrum from raw material integration through precision manufacturing to brand-facing customization.
| Leading Market Players |
|---|
| CCL Industries Inc. |
| Primepac |
| Visy Group |
| Sonoco Products Company |
| Jamestrong Packaging |
| Perennial Packaging |
| Morris McMahon & Co Pvt. Ltd |
| NCI Packaging |
| Irwin Packaging Holdings Pty Ltd |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Victorian aluminum can-to-can recycling facilities is compressing supplier margins and amplifying pricing power for certified circular material streams. Steel rolling mill utilization rates below optimal thresholds are forcing tinplate processors to absorb currency volatility rather than pass through costs.
Pricing Analysis
APCO recycled content mandates dictate the pricing tier structure across Australian food can procurement. Three-tier pricing separates premium certified-circular aluminum from standard domestic-origin steel from economy-grade imported tinplate. Price differentiation rests on mass balance documentation rigor and FSANZ food contact certification status. Cost compression in economy-grade steel is intensifying because Australian dollar weakness against USD-denominated imports squeezes converter margins. Food manufacturers under Coles and Woolworths sustainability scorecards exhibit lowest price sensitivity; mining camp catering distributors in Western Australia show highest sensitivity.
Supply Chain Analysis
Tariff exposure between Australia and China dominates supply chain risk assessment for tinplate steel inputs. Geographic supply concentration centers on China for tinplate coil, Indonesia for aluminum ingot, and domestic Victorian smelters for can-to-can recycled aluminum. Raw material dependencies feed from epoxy-phenolic lacquer formulations, high-strength aluminum alloys, and post-consumer scrap collection infrastructure. Single-source vulnerability in thermal sterilization equipment maintenance threatens production continuity. Distribution runs through Port of Melbourne import corridors feeding east coast manufacturing clusters, with Perth-dependent Western Australia served by higher-cost intermodal freight.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Australian food can manufacturing is entering a high-growth disruption as APCO's 2025 recycled content deadlines force simultaneous supply chain retrofit and certification infrastructure buildout.
For Market Incumbents: Build regulatory compliance moats through captive can-to-can recycling infrastructure in Victoria and New South Wales. Secure mass balance certification ahead of competitor capacity additions. Defend against flexible pouch substitution in premium ready-meal segments by accelerating high-strength aluminum lightweighting programs. Prioritize direct-to-retailer contract consolidation with Coles and Woolworths to disintermediate distributor intermediaries.
For New Entrants and Emerging Players: Pursue Western Australia regional supply gaps where Perth food manufacturing underpenetration creates captive mining camp distribution channels. Target Queensland container deposit scheme harmonization as the unlock moment for collected aluminum volume aggregation. Penetrate through digital printing convergence offering craft food brands variable artwork capabilities for seasonal limited-release positioning.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across can-to-can recycling infrastructure as APCO compliance deadlines approach. Five-to-ten year viability favors platform integrators with backward integration into scrap collection and rolling mill capacity. Acquisition target archetype: regional forming technology specialists with unutilized thermal sterilization equipment capacity. The signal to watch is FSANZ food contact certification queue clearance rates for recycled-content-compatible lacquer formulations.
| Strategic Initiative | Industry Significance |
|---|---|
| Can-to-Can Recycling Infrastructure Buildout | Captures APCO-mandated circular material flows ahead of competitor certification. |
| Digital Printing Technology Adoption | Enables craft brand short-run customization for seasonal positioning in premium segments. |
| Direct-to-Retailer Contract Consolidation | Bypasses distributor intermediaries as Coles and Woolworths enforce sustainability scorecards. |
| Western Australia Regional Supply Expansion | Captures mining camp institutional demand currently served by high-cost east coast freight. |
| High-Strength Aluminum Lightweighting Programs | Displaces steel in non-acidic food categories for freight efficiency and shelf appeal. |
Research Methodology
Cross-validation between regulatory filing analysis and supply chain documentation anchors the qualitative findings. Primary interviews with can manufacturing plant managers, food processor procurement leads, APCO compliance officers, and supermarket category buyers combined with secondary validation from Australian Bureau of Statistics trade data, FSANZ food contact material registers, and state-level container deposit scheme operator reports. Bottom-up segmentation modeling and top-down macroeconomic calibration ensure triangulation integrity.
Calibration against historical capacity utilization patterns and documented APCO compliance investment announcements shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include material substrate, end-use vertical, container size tier, closure mechanism, and state-level regulatory cluster. CAGRs derive from installed capacity expansion timelines and demand elasticity estimates for canned seafood and ready-meal categories. Industry-specific forecast inputs incorporate tinplate steel import volume fluctuations and thermal sterilization equipment commissioning schedules.
Macroeconomic conditions sit as an overlay; deviation in Australian dollar exchange rates against USD and Chinese yuan would shift the trajectory. Forecasts reflect documented assumptions regarding APCO target adherence and FSANZ certification timeline clearance. Specific risk factors include retort equipment technician scarcity and legacy ERP integration delays with traceability systems. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Iran Breakfast Cereals Market
Packaged Foods
North America Ready Meals Market
Packaged Foods
Plant Focused Dips Market
Packaged Foods
Sugar Free Cookies Market
Packaged Foods
China Packaged Food Products Market
Packaged Foods
Canned Goods Market
Packaged Foods
Impulse Ice-Cream Market
Packaged Foods
Tortilla Market
Packaged Foods
Chocolate Based Spreads Market
Packaged Foods
Packaged Burgers Market
Packaged Foods
Cocoa Fillings Market
Packaged Foods
Asia-Pacific Breakfast Cereals Market
Packaged Foods
Instant Soup Market
Packaged Foods
Canned Mushroom Market
Packaged Foods
South America Pasta and Noodles Market
Packaged Foods
Ready Meal Trays Market