
 Packaged Food Market | 2026-2036
Packaged Food Market Size, Share, and Industry Trends Forecast 2026-2036
Packaged Food Market Intelligence
The EU Green Deal is decoupling shelf-stable food demand from virgin plastic dependency across European retail channels. General Mills, Inc. anchors its North American portfolio through in-house grain milling and frozen meal manufacturing scale. Danone SA differentiates through fermented dairy specialization and regenerative agriculture sourcing programs. Yihai Kerry Arawana Holdings Co. Ltd dominates China's edible oil and condiment segments through deep distribution into township markets.
Packaged food comprises industrially processed, preserved, and sealed consumables manufactured to standardized recipes with controlled moisture content, thermal processing parameters, and barrier packaging specifications designed for shelf stability and mass distribution. Ready-to-Eat formats capture premium margin pools as urban time scarcity elevates meal replacement demand across Asian and North American cities. Snack Foods sustain volume leadership through flavor innovation and portion-controlled packaging that penetrates convenience store channels. Frozen Meals represent the fastest-growing structural category as cold chain infrastructure extends into secondary cities across Brazil, India, and Southeast Asia.
The FDA governs nutrition labeling and food safety modernization in the United States while EFSA and REACH coordinate additive approvals and packaging material migration limits across Europe. India's FSSAI enforces fortification mandates and contaminant thresholds that determine import eligibility and domestic manufacturing compliance. Stakeholders must monitor divergence between FDA's proposed front-of-pack labeling rules and EFSA's evolving nanomaterial guidance to avoid reformulation cost duplication.
Market Dynamics
Urban household time scarcity is compressing meal preparation windows across metropolitan corridors, pulling shelf-stable and frozen formats into daily consumption routines previously reserved for fresh ingredients.
Growth Catalysts
- EU Green Deal packaging mandates:Virgin plastic reduction targets are accelerating bio-based barrier material adoption across European retail channels, forcing incumbent reformulation investments that widen competitive moats for compliant producers.
- Cold chain infrastructure buildout:India's refrigerated logistics network expansion is penetrating secondary cities, enabling frozen meal distribution into populations previously restricted to ambient shelf-stable options.
- Regenerative agriculture certification:Carbon-sequestering sourcing programs are capturing premium shelf space as EFSA-aligned environmental claims differentiate private-label and branded portfolios in German and French supermarkets.
Market Restraints
- Input cost volatility:Wheat and palm oil price swings are compressing margin predictability for grain-based and frying oil-dependent manufacturers operating on annual procurement contracts.
- Supply concentration risk:Barrier film production clusters in China's coastal provinces create single-source dependency for oxygen-scavenging packaging technologies critical to shelf-life extension.
- Regulatory friction:Divergent nanomaterial approval pathways between FDA and EFSA are forcing dual-track safety studies that duplicate R&D expenditure for cross-Atlantic product launches.
Strategic Opportunities
- Underpenetrated Brazilian secondary markets:Frozen meal penetration in Brazil's interior cities remains below metropolitan benchmarks, presenting first-mover advantages for cold chain-integrated distributors.
- Regulatory tailwind from FSSAI fortification mandates:India's mandatory micronutrient enrichment rules for staple foods are creating compliant product categories that command government procurement preference and retail shelf priority.
- Technology convergence:High-pressure processing and modified atmosphere packaging combinations are extending refrigerated ready-to-eat shelf life without thermal degradation, opening fresh-like segments previously inaccessible to packaged formats.
Industry Challenges
- Reformulation talent scarcity:Food scientists capable of balancing clean-label ingredient reduction with shelf-stability requirements command compensation premiums that strain mid-tier manufacturer R&D budgets.
- Capex intensity for cold chain compliance:Frozen meal production line upgrades to meet evolving FDA food safety modernization standards require capital deployment that excludes sub-scale regional processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaged Food Market |
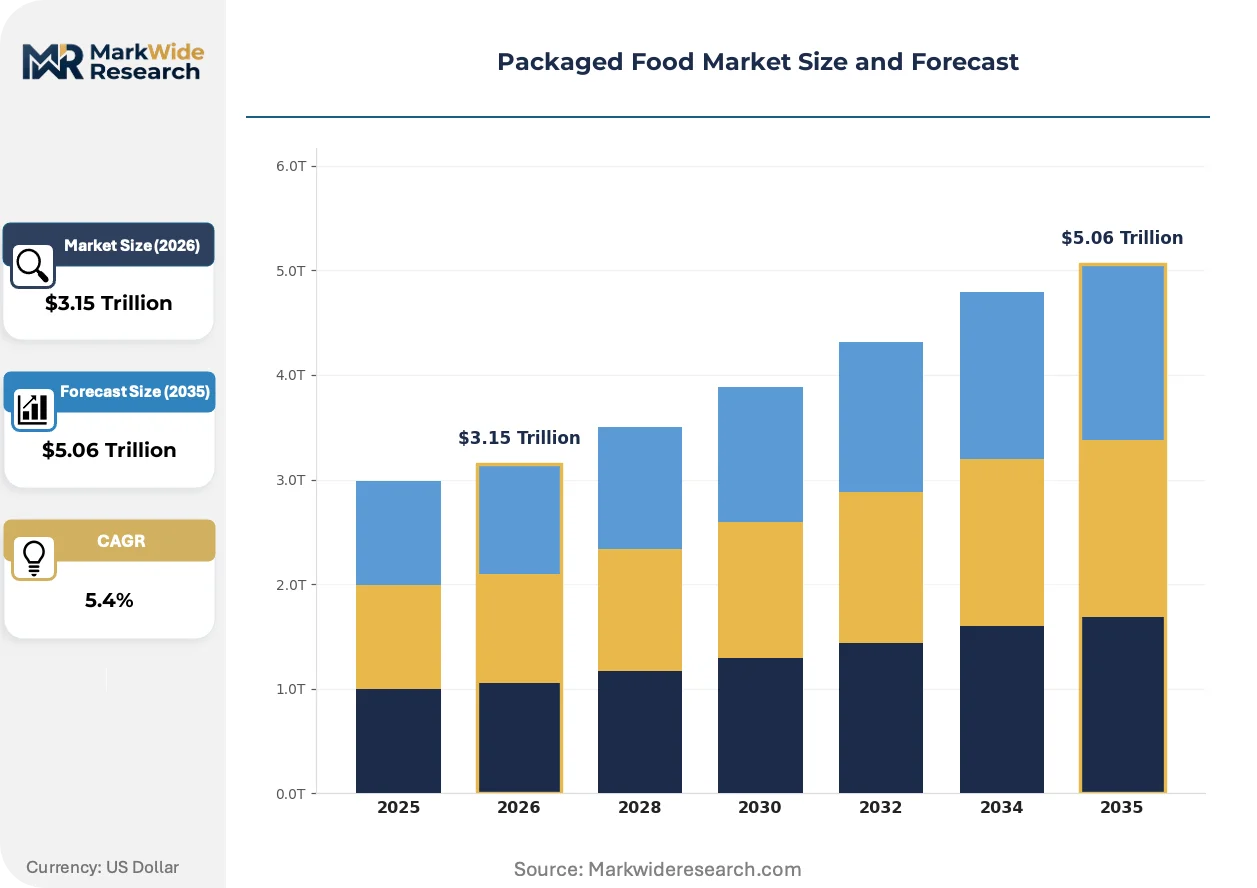
| Market Size in 2026 | $3.15 Trillion |
| Market Size in 2035 | $5.06 Trillion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Meals, Canned Goods, Snack Foods, Ready-to-Eat Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesalers Packaging Type: Bottles, Pouches, Boxes, Tins End User: Households, Restaurants, Hospitals, Catering Services |
| Companies Covered | The Kraft Heinz Company, General Mills, Inc., Danone SA, Ajinomoto Co., Inc., Yihai Kerry Arawana Holdings Co. Ltd, Foshan Haitian Flavouring and Food Company Ltd, Inner Mongolia Yili Industrial Group Co. Ltd, Associated British Foods plc, Kellogg Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaged Food Market Strategic Shifts & Innovations
Active packaging technologies and regulatory transparency mandates are restructuring competitive advantage around provenance verification and shelf-life extension rather than flavor innovation alone.
Modified atmosphere packaging is expanding into fresh-produce-adjacent categories through oxygen-scavenging film laminates that extend refrigerated pasta and prepared salad shelf life. Premium retailers in Japan and South Korea are adopting these formats for grab-and-go meal sections. The technology is expanding into categories previously dependent on chemical preservatives, compressing the clean-label reformulation timeline for multinational portfolios.
REACH packaging material migration limits are tightening permissible substance thresholds for food-contact plastics across European manufacturing. ECHA enforcement is accelerating substitution of legacy phthalate plasticizers with bio-based alternatives in film extrusion processes. Frozen meal and ready-to-eat segments with extended shelf-dating requirements face disproportionate compliance cost burdens relative to short-turnover fresh categories.
Direct-to-retailer procurement contracts are consolidating buyer power as hypermarket chains in India and Southeast Asia bypass traditional distributor networks for private-label sourcing. Branded manufacturers are responding with exclusive SKU development programs that lock shelf space through category captain arrangements. This concentration is most visible in China's edible oil and condiment segments where township market penetration depends on direct store delivery relationships.
Packaged Food Market Segmentation
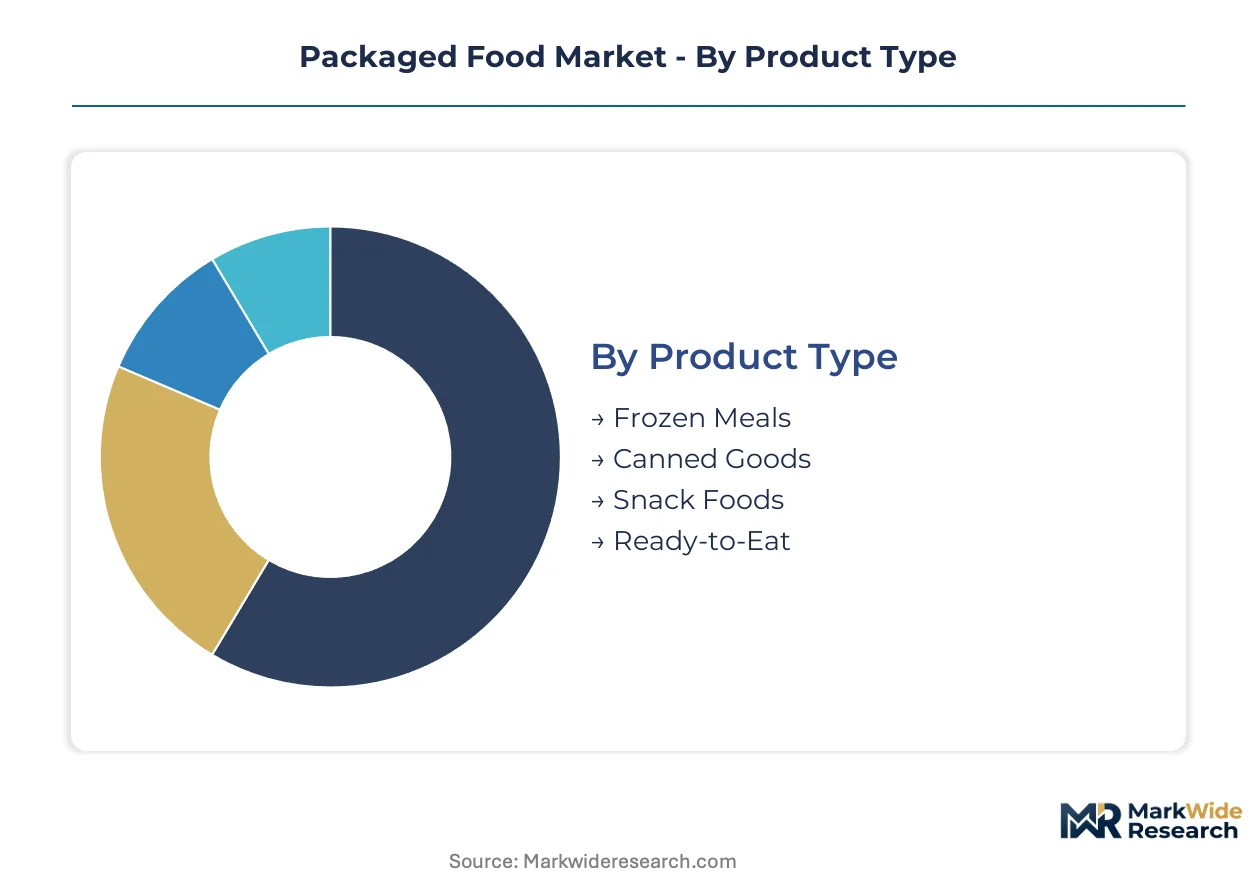
Packaged food segmentation reveals how format innovation and channel specialization create distinct margin architectures. Each dimension exposes different competitive dynamics around shelf-life engineering, cold chain dependency, and procurement consolidation.
Product Type:
Reformulation cycles and packaging material upgrades drive replacement demand across all four product categories, with thermal processing and barrier technology investments determining competitive durability.
- Frozen Meals:Blast-frozen proteins and vegetable components assembled into complete dishes, requiring -18°C maintenance through last-mile distribution. Demand concentrates in India's metropolitan corridors where cold chain expansion enables penetration into time-scarce urban households previously restricted to ambient alternatives.
- Ready-to-Eat:Thermally processed, shelf-stable meals in retort pouches or modified atmosphere trays with 6-18 month stability windows. European retailers prioritize these formats as EU Green Deal packaging mandates accelerate bio-based barrier material adoption, forcing incumbent reformulation investments that widen moats for compliant producers.
- Canned Goods:Metal-container preserved vegetables, proteins, and complete meals using hermetic sealing and thermal sterilization. Established infrastructure in North American and European retail channels sustains volume despite slower innovation velocity.
- Snack Foods:Portion-controlled, flavor-innovated items in flexible packaging targeting convenience store impulse purchase occasions. Shelf placement fees and velocity metrics dominate competitive positioning.
Snack Foods sits at the top of the volume ranking, with Frozen Meals climbing the fastest.
Distribution Channel:
Channel selection determines margin capture through buyer concentration, private-label penetration, and last-mile cost structures.
- Supermarkets:Full-assortment retail with category captain arrangements and exclusive SKU development programs locking shelf space. Direct-to-retailer procurement consolidation in India and Southeast Asia bypasses traditional distributor networks for private-label sourcing.
- Online Retail:Direct-to-consumer fulfillment requiring temperature-controlled logistics investment, particularly critical for frozen meal categories where insulated packaging and same-day delivery expectations compress unit economics.
- Convenience Stores:High-velocity, limited-assortment outlets where snack foods and single-serve ready-to-eat formats dominate through placement fees and checkout-adjacent merchandising.
- Wholesalers:Institutional and foodservice aggregation points serving restaurants, hospitals, and catering operations with pallet-scale procurement and contract pricing structures.
Supermarkets command the largest revenue pool, with Online Retail expanding most quickly.
Packaging Type:
Material selection reflects shelf-life requirements, regulatory compliance burdens, and sustainability positioning investments.
- Pouches:Flexible, multi-layer barrier films with oxygen-scavenging laminates extending refrigerated pasta and prepared salad shelf life without chemical preservatives. REACH migration limits are accelerating substitution of legacy phthalate plasticizers with bio-based alternatives in European manufacturing.
- Boxes:Paperboard-based formats for dry goods and shelf-stable categories, with fiber sourcing certification increasingly required by German and French supermarket chains.
- Bottles:Rigid PET or glass containers for beverages, sauces, and condiments with established recycling infrastructure in developed markets.
- Tins:Metal cans for thermally processed goods with mature supply chains but higher material intensity relative to flexible alternatives.
Boxes generate the highest unit volumes, with Pouches gaining share fastest.
End User:
Customer type dictates formulation specifications, portion sizing, and procurement contract structures.
- Households:Individual and family-scale consumption with convenience-driven preference for single-serve and small-format packaging. Time scarcity in urban corridors pulls shelf-stable and frozen formats into daily routines previously reserved for fresh ingredients.
- Restaurants:Foodservice operations requiring bulk formats, consistent quality specifications, and reliable supply cadence for menu standardization.
- Hospitals:Regulated institutional settings with strict nutritional compliance, allergen control, and therapeutic diet accommodation requirements.
- Catering Services:Event and institutional feeding operations with volume volatility and menu customization demands driving flexible procurement relationships.
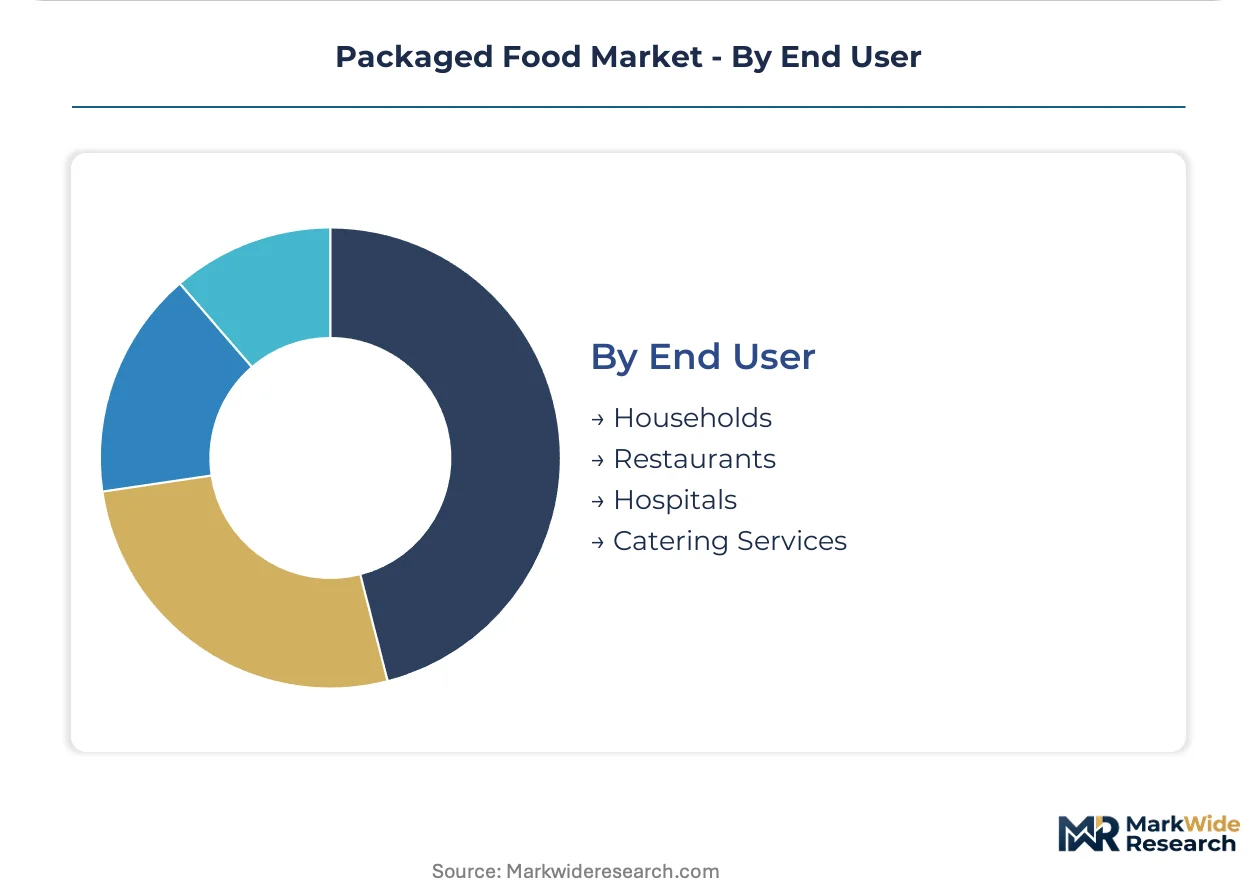
Households anchor absolute demand, with Restaurants showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaged food industrialization traces its modern lineage to post-war United States canning and freezing infrastructure, with subsequent waves of consolidation and format innovation spreading through Western Europe and East Asia before penetrating emerging economies.
United States
Time-scarce urban households in New York, Chicago, and Los Angeles drive frozen meal and ready-to-eat penetration into daily consumption routines. FDA nutrition labeling modernization and food safety standards govern shelf-stable product compliance across interstate commerce. Midwest grain milling clusters in Minnesota and Iowa anchor General Mills' captive supply chains for cereal and snack production.
China
Edible oil and condiment demand concentrates in Yangtze River Delta and Pearl River Delta metropolitan corridors where township distribution networks reach 600 million consumers. SAMR food safety regulations and GB standards enforce contaminant thresholds and labeling requirements for domestic and imported products. Yihai Kerry Arawana Holdings dominates through deep penetration of lower-tier city retail channels.
India
Cold chain expansion in Maharashtra and Karnataka enables frozen meal distribution into Bangalore, Mumbai, and Pune households previously restricted to ambient shelf-stable options. FSSAI fortification mandates for staple foods create compliant product categories commanding government procurement preference. Gujarat dairy processing clusters supply Inner Mongolia Yili Industrial Group's ingredient sourcing requirements.
Germany
EU Green Deal packaging directives accelerate bio-based barrier material adoption across Berlin, Munich, and Hamburg retail channels. EFSA and REACH coordinate additive approvals and migration limits that determine reformulation investments for shelf-stable exports. Baden-Württemberg food technology clusters develop modified atmosphere packaging laminates for extended shelf-life applications.
Brazil
Frozen meal penetration in São Paulo and Rio de Janeiro metropolitan areas exceeds interior city benchmarks by 3:1 margins, presenting first-mover expansion opportunities. ANVISA food safety regulations govern import eligibility and domestic manufacturing compliance for multinational portfolios. Minas Gerais dairy and grain processing infrastructure supports regional packaged food production scale.
Packaged Food Market Key Industry Players
Capital-heavy producers compete with asset-light brand architects across tiered competitive strata. The market structure concentrates around multinational conglomerates with captive manufacturing, mid-tier regional specialists, and private-label suppliers serving consolidated retail buyers. Three archetypes dominate: diversified grain and dairy processors, fermented and condiment specialists, and frozen meal manufacturers with cold chain integration. M&A activity targets distribution network consolidation, while capacity expansion focuses on high-pressure processing and modified atmosphere packaging lines.
Within the diversified processed food tier, General Mills, Inc. and The Kraft Heinz Company occupy positions anchored by North American grain milling and retail brand portfolios. Danone SA exemplifies the fermented dairy specialist archetype with European regenerative agriculture sourcing programs. Yihai Kerry Arawana Holdings Co. Ltd represents the condiment and edible oil concentration model through township market penetration in China.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| General Mills, Inc. |
| Danone SA |
| Ajinomoto Co., Inc. |
| Yihai Kerry Arawana Holdings Co. Ltd |
| Foshan Haitian Flavouring and Food Company Ltd |
| Inner Mongolia Yili Industrial Group Co. Ltd |
| Associated British Foods plc |
| Kellogg Company |
| Others |
Cost & Logistics Intelligence
Clean-label certification tiers split the packaged food market into divergent cost structures, with EU Green Deal compliance and regenerative agriculture sourcing commanding 40-60% procurement premiums while commodity-grade alternatives compete on volume scale and input cost minimization. This bifurcation manifests in supply chain configurations where premium producers anchor captive sourcing programs in named agricultural clusters, while value-tier manufacturers draw from spot-market commodity exchanges with minimal backward integration.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs shelf-stable and frozen categories, with clean-label certification and regenerative agriculture sourcing as primary differentiation drivers alongside cold chain integration depth. Pricing pressure stems from wheat and palm oil input volatility compressing margin predictability for grain-based and frying oil-dependent manufacturers. Foodservice buyers exhibit highest price sensitivity due to contract pricing structures, while premium retail channels absorb certification premiums with minimal volume elasticity.
Supply Chain Analysis
Food scientist talent scarcity in Baden-Württemberg and Minnesota clusters constrains reformulation capacity for clean-label shelf-stable development, forcing compensation premiums that strain mid-tier R&D budgets. Supply concentration rests on China's coastal provinces for oxygen-scavenging barrier films, India's Gujarat dairy processing infrastructure, and Iowa-Minnesota grain milling corridors. Single-source dependency for advanced packaging technologies creates vulnerability to export restriction scenarios. Distribution runs through direct-to-retailer procurement consolidation in India and Southeast Asia, bypassing traditional wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge between EU Green Deal compliance costs in Germany and France versus FSSAI fortification procurement preferences in India, where regulatory alignment unlocks government shelf priority with lower reformulation overhead.
For Market Incumbents: Deepen backward integration into captive grain milling and dairy processing clusters to defend margin position against input cost volatility. Lock shelf space through exclusive SKU development programs with category captain arrangements in India's consolidating hypermarket channels. Prioritize high-pressure processing line upgrades to meet FDA food safety modernization standards and exclude sub-scale regional competitors.
For New Entrants and Emerging Players: Begin with underpenetrated Brazilian interior cities where frozen meal adoption trails São Paulo benchmarks by 3:1 margins, enabling first-mover cold chain partnerships. Target India's FSSAI-compliant staple fortification categories commanding government procurement preference. Deploy direct store delivery relationships bypassing traditional distributor markups in China's township markets.
For Investors and Strategic Acquirers: Consolidation pressure builds where cold chain capex requirements and reformulation talent scarcity exclude sub-scale regional processors from FDA and EFSA compliance. Long-term viability favors diversified processors with captive agricultural sourcing and modified atmosphere packaging capabilities. Watch for divergence between FDA front-of-pack labeling rules and EFSA nanomaterial guidance as inflection signal for reformulation cost duplication risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold Chain Infrastructure Partnership | Enables frozen meal penetration into India's secondary cities through last-mile refrigerated logistics. |
| Bio-Based Barrier Material Adoption | Aligns with EU Green Deal mandates while widening competitive moats against non-compliant incumbents. |
| Regenerative Agriculture Sourcing Program | Captures premium shelf space in German and French supermarkets through EFSA-aligned environmental claims. |
| Direct-to-Retailer Procurement Consolidation | Bypasses traditional distributor networks in Southeast Asia for private-label margin capture. |
| High-Pressure Processing Line Deployment | Extends refrigerated ready-to-eat shelf life without thermal degradation for fresh-like segments. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with food technology R&D directors, retail category buyers, cold chain logistics operators, and regulatory affairs specialists with secondary validation. Secondary sources include FDA food safety modernization filings, EFSA additive approval databases, FSSAI fortification compliance records, Nielsen retail audit data, and customs trade flows. Bottom-up volume modeling triangulates against top-down macroeconomic consumption indicators.
Rate-of-change decomposition separates volume growth from price-mix effects across product type, distribution channel, packaging format, and end user dimensions throughout the forecast period. CAGRs derive from segment-level growth trajectories weighted by base-year revenue contribution. Industry-specific forecast inputs incorporate cold chain infrastructure buildout timelines, regulatory compliance cost curves, and bio-based packaging material adoption rates.
Several conditions sit outside the modeled scope, including abrupt commodity price shocks, trade policy discontinuities affecting barrier film imports, and accelerated nanomaterial regulatory divergence between FDA and EFSA. Forecasts reflect stated assumptions about regulatory stability and input cost normalization. Material deviation in wheat and palm oil volatility, EU packaging mandate enforcement intensity, or India's cold chain investment cadence warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Asia-Pacific Breakfast Cereals Market
Packaged Foods
Global Popping Candy Market
Packaged Foods
Wet Food Pouch Market
Packaged Foods
Sugar Free Cookies Market
Packaged Foods
Packaged Currants Market
Packaged Foods
High-End Instant Noodles Market
Packaged Foods
Fat Free Pasta Market
Packaged Foods
North America Packaged Salad Market
Packaged Foods
Europe Ready-To-Eat Food Market
Packaged Foods
Cookie Pucks Market
Packaged Foods
Ready Meals Market
Packaged Foods
Tortilla Market
Packaged Foods
Carbon Labeled Packaged Meal Market
Packaged Foods
North America Ready-To-Eat Food Market
Packaged Foods
Canned Tropical Fruit Market
Packaged Foods
Dried Soup Market