
 Bangladesh Instant Noodles Market | 2026-2036
Bangladesh Instant Noodles Market Size, Share, and Industry Trends Forecast 2026-2036
Bangladesh Instant Noodles Market Outlook
Single-serve pouch bundling is shifting buyer choice toward multi-pack value formats in urban retail. PRAN-RFL Group Ltd dominates rural distribution through its extensive dealer network. Nestlé SA differentiates via premium positioning in metropolitan supermarkets. SQUARE Food & Beverage Ltd leverages local flavor adaptation to sustain brand loyalty among price-sensitive consumers.
Instant noodles comprise pre-cooked wheat-based strands flash-fried or air-dried, rehydrated in boiling water within three minutes, designed for immediate consumption without culinary preparation. Soup-based formats occupy the largest volume share due to year-round consumer familiarity, while stir-fried variants represent the fastest-growing category as younger buyers seek texture differentiation. Pouch packaging commands the mass-market tier, though plastic cups capture higher margins in transit-oriented consumption occasions.
Bangladesh's Bangladesh Standards and Testing Institution (BSTI) mandates fortification labeling and additive disclosure for processed food products, elevating compliance costs for smaller manufacturers. The country's national food safety authority enforces periodic testing for heavy metal contaminants in imported seasoning inputs. Stakeholders must monitor evolving BSTI standards on sodium content thresholds and imported palm oil traceability requirements.
Market Dynamics
Bangladesh's instant noodles sector faces a structural squeeze between BSTI's escalating fortification mandates and the informal retail network's resistance to premium pricing. Urban working-class households drive volume expansion while regulatory compliance costs compress margins for mid-tier producers.
Growth Catalysts
- Urban working-class household expansion:Dhaka and Chattogram's garment factory zones generate concentrated demand for sub-three-minute meal solutions. Factory canteen procurement contracts now specify instant noodle suppliers with BSTI certification.
- BSTI fortification labeling mandates:Mandatory iron and vitamin disclosure on processed food packaging creates competitive differentiation for compliant manufacturers. Smaller unfortified brands face retail delisting pressure.
- Air-drying technology adoption:Non-fried noodle lines reduce palm oil input exposure while appealing to health-positioned urban buyers. Chattogram-based processors pilot solar-assisted drying to cut energy costs.
Market Restraints
- Palm oil price volatility:Bangladesh's edible oil import dependence exposes manufacturers to global commodity swings. Flash-frying processes require 12-15% oil content by weight, making input cost hedging structurally difficult.
- Imported seasoning concentrate concentration:Heavy metal testing requirements at Chattogram port create 3-4 week clearance delays for Chinese-origin flavor bases. Domestic blending capacity remains underdeveloped.
- Substitution by frozen parathas:Urban convenience stores now stock flash-frozen flatbreads targeting the same 2-3 minute preparation window. Frozen formats carry longer shelf life and perceived freshness advantages.
Strategic Opportunities
- Chattogram Hill Tracts underpenetration:Ethnic minority regions in Rangamati and Bandarban districts lack dedicated instant noodle distribution. Mobile vendor networks could replicate rural dealer models from the plains.
- E-commerce direct-to-household channels:Chaldal and Daraz platforms bypass traditional wholesaler markups for Dhaka apartment complexes. Subscription bundling locks in monthly pantry replenishment cycles.
- PLI scheme alignment for food processing:Bangladesh's production-linked incentive framework for processed foods offers capital subsidy for fortification equipment upgrades. BSTI-compliant lines qualify for 15-20% machinery cost offsets.
Industry Challenges
- Food technologist talent scarcity:Formulation expertise for sodium reduction without taste degradation commands premium salaries. Dhaka University food science graduates migrate to pharmaceutical QA roles.
- Legacy distributor credit systems:Rural dealer networks operate on 45-60 day payment cycles that strain working capital. Digital ledger adoption faces resistance from multi-generational trading houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bangladesh Instant Noodles Market |
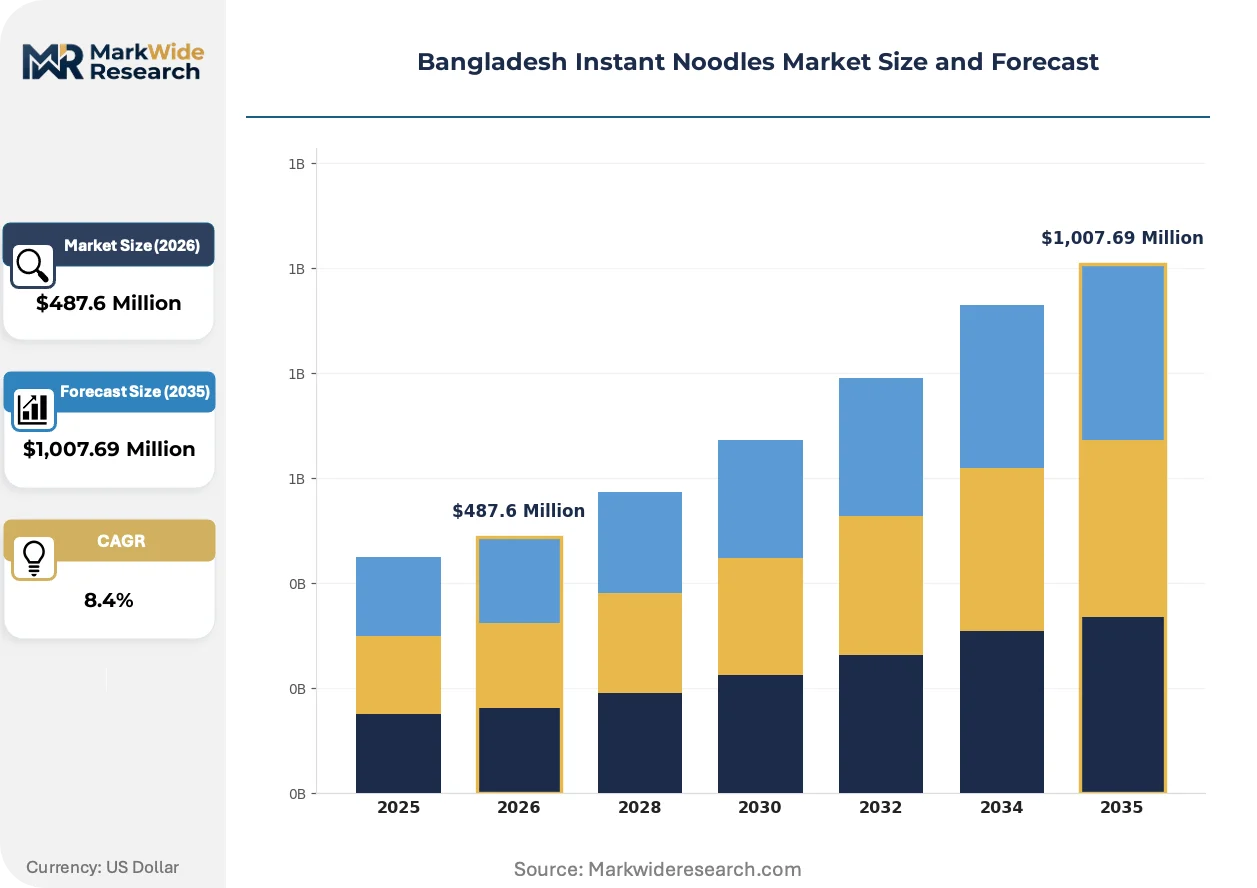
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,007.69 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Stir-Fried, Soup-Based, Instant Cup Flavor Profile: Chicken, Vegetable, Curry, Seafood Packaging Type: Plastic Cups, Bowls, Pouches, Sachets Distribution Channel: Supermarkets, Convenience Stores, Online, Wholesale |
| Companies Covered | IFAD Multi Products Ltd, Samyang Foods Co. Ltd, PRAN-RFL Group Ltd, Fu-Wang Foods Ltd, Cocola Food Products Ltd, Nestlé SA, SQUARE Food & Beverage Ltd, New Zealand Dairy Products Bangladesh Ltd, Unilever PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bangladesh Instant Noodles Market Strategic Shifts
Product format diversification and packaging sustainability pressures are restructuring competitive advantage in Bangladesh's instant noodle trade. Technology adoption patterns diverge sharply between metropolitan supermarkets and traditional retail.
Air-dried noodle production lines are consolidating market share among health-positioned brands seeking to escape palm oil cost cycles. Dhaka-based manufacturers with access to industrial dehumidification equipment deploy these lines for premium supermarket placement. The technology is consolidating supplier bases by eliminating smaller fryer-dependent operators unable to finance drying infrastructure upgrades.
BSTI's draft sodium threshold regulations are forcing reformulation investments across the sector. The proposed 2000mg per 100g dry weight limit threatens existing soup-base recipes reliant on monosodium glutamate enhancement. Stir-fried variants with lower broth dependency face milder compliance pressure and accelerate metropolitan trial rates.
Working-class buyers in garment factory zones are fragmenting purchase occasions across multiple pack sizes rather than bulk monthly stocking. Single-serve cups capture canteen and transit consumption while multi-pouch bundles dominate household pantry loading. This bifurcation pressures manufacturers to maintain dual SKU portfolios with incompatible margin structures.
Bangladesh Instant Noodles Market Segmentation
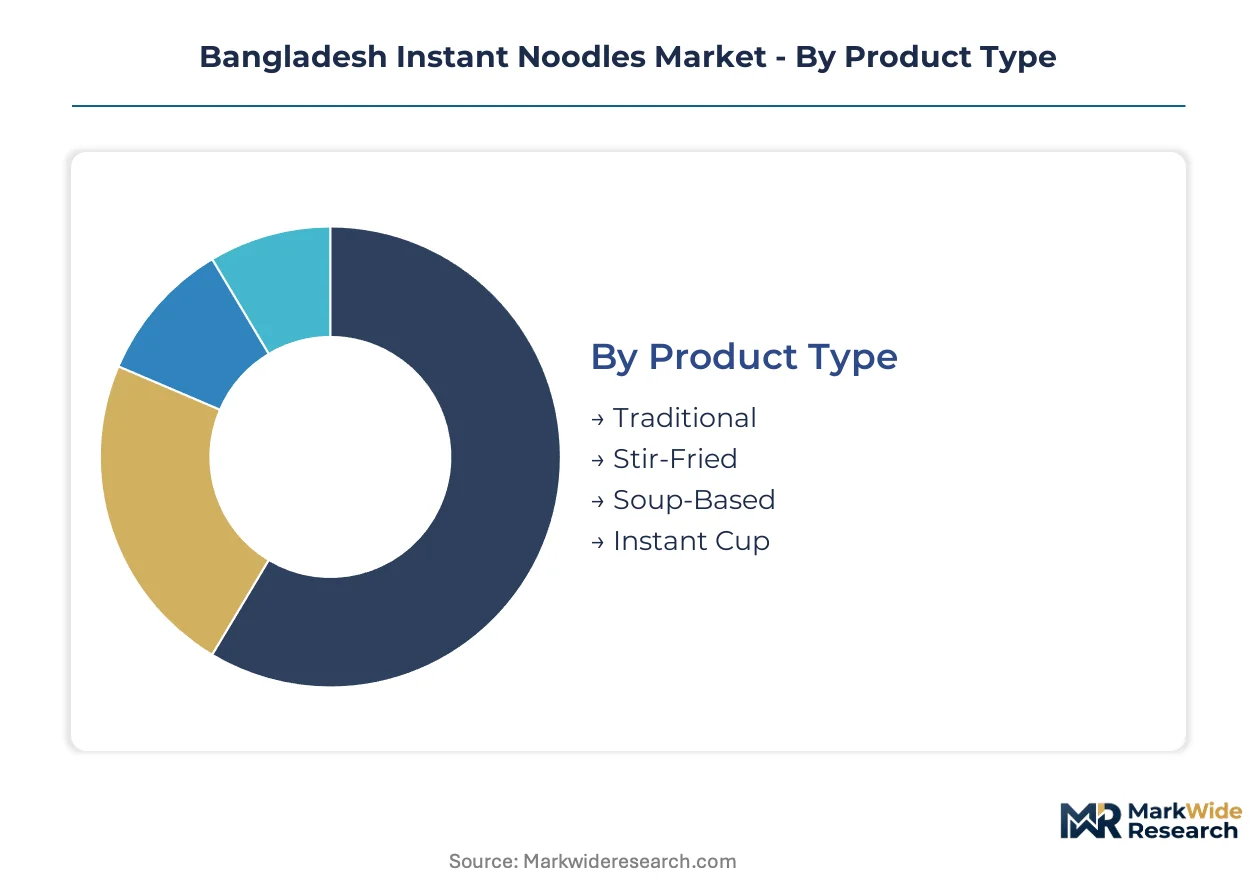
Instant noodle manufacturers in Bangladesh calibrate product portfolios across four distinct segmentation axes. Each dimension carries divergent margin profiles and regulatory exposure, forcing parallel SKU strategies rather than unified platform approaches.
Product Type:
Customization intensity varies sharply across preparation formats, from commodity soup bases to specialized stir-fried lines requiring distinct manufacturing infrastructure.
- Soup-Based:Pre-cooked wheat strands paired with dehydrated broth sachets dominate factory canteen procurement in Dhaka's garment zones. BSTI fortification mandates apply most stringently here due to broth concentrate classification as composite food.
- Stir-Fried:Lower moisture content and sauce-packet separation appeals to Chattogram's younger urban buyers seeking texture differentiation. Air-drying technology adoption concentrates in this segment to reduce palm oil input exposure.
- Traditional:Basic wheat noodle blocks with minimal seasoning represent the rural mass-market entry point.
- Instant Cup:Self-contained formats with integrated bowls capture transit-oriented consumption and command premium placement in convenience stores.
Most installed capacity flows through Soup-Based formats. Expansion is steepest in Stir-Fried variants.
Flavor Profile:
Raw material sourcing geography dictates flavor availability, with seasoning concentrate imports clustering on specific taste archetypes.
- Chicken:The dominant volume driver relies on imported flavor bases from Chinese suppliers, exposing manufacturers to Chattogram port clearance delays for heavy metal testing.
- Curry:Locally blended spice formulations reduce import dependency and align with Bangladeshi palate expectations in rural markets.
- Vegetable:Dehydrated carrot and cabbage inclusions face shorter shelf-life constraints than synthetic flavor alternatives.
- Seafood:Shrimp and fish-based seasonings occupy a niche premium tier with concentrated demand in coastal Chattogram districts.
Chicken flavoring absorbs the largest production runs. Curry variants gain share fastest among price-sensitive segments.
Packaging Type:
Material cost structures and retail channel requirements fragment packaging strategies across urban and rural deployment.
- Pouches:Flexible laminate bags dominate household pantry loading in working-class Dhaka neighborhoods, with multi-unit bundling shifting purchase patterns toward value formats.
- Plastic Cups:Rigid containers with integrated lids capture garment factory canteen contracts and railway station kiosks, carrying higher per-unit margins but requiring dedicated thermoforming equipment.
- Bowls:Expanded polystyrene alternatives target premium supermarket placement with enhanced heat retention properties.
- Sachets:Stand-alone seasoning and oil packets serve as replacement components for institutional bulk noodle procurement.
Pouch packaging channels the majority of unit volume. Plastic Cups generate the steepest margin expansion.
Distribution Channel:
Route-to-market economics vary by payment cycle length and working capital intensity across Bangladesh's fragmented retail landscape.
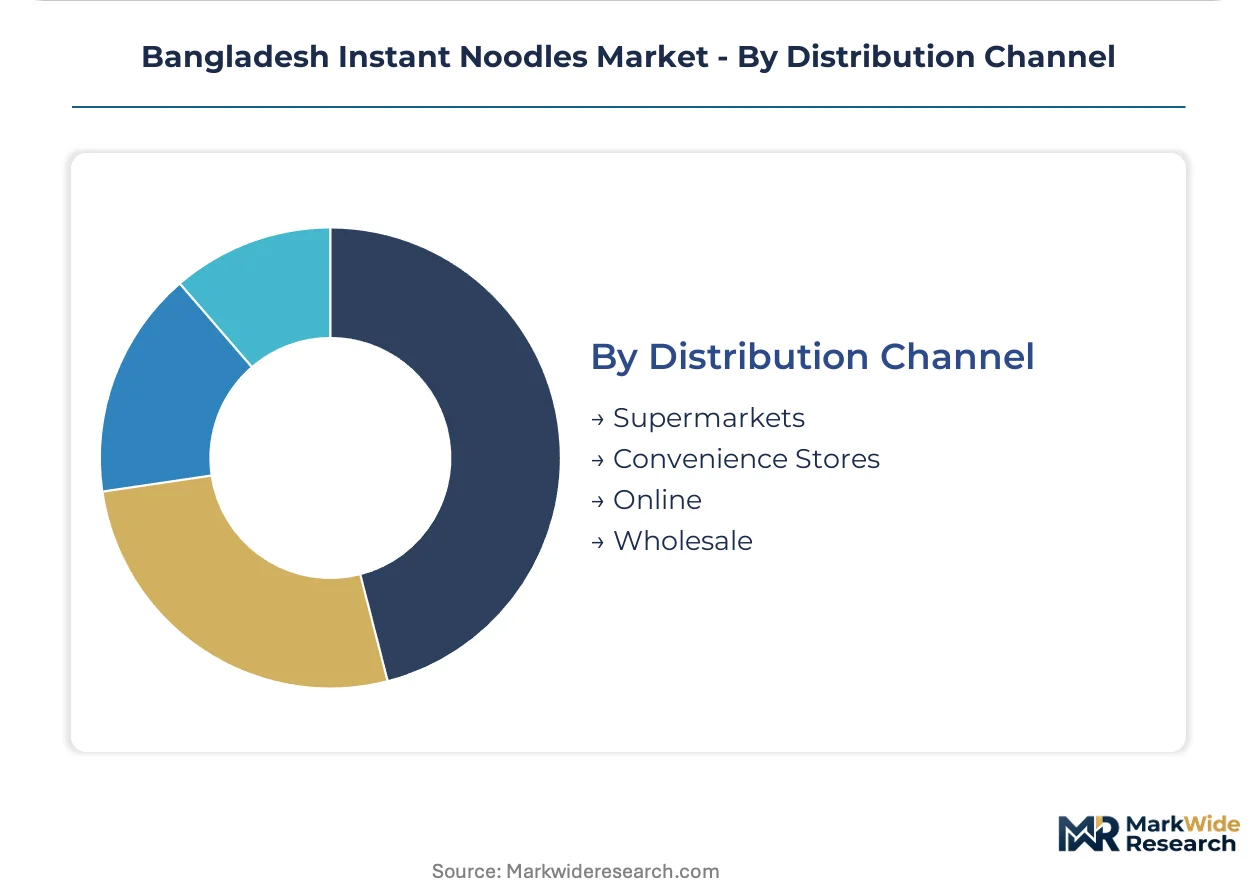
- Wholesale:Traditional dealer networks with 45-60 day credit terms remain the rural penetration backbone, particularly in PRAN-RFL's stronghold districts.
- Supermarkets:Dhaka and Chattogram metropolitan chains enforce BSTI certification prerequisites and slotting fees that filter out smaller manufacturers.
- Convenience Stores:Urban corner shops with rapid inventory turns favor single-serve cups and impulse-oriented pack sizes.
- Online:Chaldal and Daraz platforms enable direct-to-household subscription models that bypass wholesaler markups in apartment-dense zones.
Wholesale networks handle the greatest tonnage. Online channels climb fastest among Dhaka's garment worker households.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Instant noodle manufacturing in Bangladesh traces its commercial scale-up to the early 1990s, when local conglomerates adapted Japanese flash-frying technology for wheat-based strands. Dhaka's garment sector expansion subsequently created concentrated demand pockets that shaped regional distribution priorities.
Dhaka Division
Garment factory zones in Gazipur and Narayanganj generate bulk procurement contracts for canteen feeding programs. BSTI certification requirements now filter supplier eligibility for institutional buyers. Tongi industrial corridor hosts multiple processing facilities with integrated seasoning blending capacity.
Chattogram Division
Port proximity enables direct import of Chinese-origin flavor concentrates, though heavy metal testing delays create inventory management challenges. Stir-fried variant adoption concentrates among younger urban demographics in metropolitan Chattogram. Patenga and Anwara sub-districts anchor emerging processing clusters with solar-assisted drying pilots.
Khulna Division
Jute mill worker housing colonies sustain steady pouch-format demand through traditional dealer networks. Limited cold chain infrastructure restricts frozen paratha substitution threats relative to Dhaka. Bagerhat and Jessore districts exhibit underpenetrated rural distribution relative to PRAN-RFL's northern strongholds.
Rajshahi Division
Wheat cultivation proximity reduces raw material transport costs for regional processors. Bogra and Naogaon districts serve as procurement hubs for domestic wheat sourcing. Seasonal agricultural labor migration creates periodic demand spikes in rural market towns.
Chattogram Hill Tracts
Rangamati, Bandarban and Khagrachari districts lack dedicated instant noodle distribution infrastructure. Ethnic minority consumer preferences favor locally processed rice-based alternatives. Mobile vendor networks remain undeveloped compared to plains-region dealer models.
Bangladesh Instant Noodles Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification and distribution infrastructure dimensions. Market structure exhibits consolidated leadership at the top tier with fragmented mid-scale competition. Three archetypes dominate: diversified food conglomerates with rural dealer networks, multinational subsidiaries with supermarket positioning, and regional processors with local flavor adaptation. Capacity expansion and fortification equipment upgrades constitute the dominant competitive moves as BSTI compliance deadlines approach.
Within the diversified conglomerate tier, PRAN-RFL Group Ltd and SQUARE Food & Beverage Ltd exemplify scale-driven rural penetration models. Nestlé SA occupies a position representing multinational premium-tier positioning in metropolitan retail channels. These three anchors illustrate the strategic divergence between dealer-network depth and supermarket slotting fee absorption capacity.
| Leading Market Players |
|---|
| IFAD Multi Products Ltd |
| Samyang Foods Co. Ltd |
| PRAN-RFL Group Ltd |
| Fu-Wang Foods Ltd |
| Cocola Food Products Ltd |
| Nestlé SA |
| SQUARE Food & Beverage Ltd |
| New Zealand Dairy Products Bangladesh Ltd |
| Unilever PLC |
| Others |
Value Chain & Pricing Dynamics
Garment factory canteen procurement contracts mandating BSTI certification are compressing margins for non-compliant processors while rewarding fortification-ready suppliers with volume commitments. This demand-side specification shift forces mid-tier manufacturers to absorb equipment upgrade costs or exit institutional channels entirely.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and channel access. Premium tiers command supermarket placement fees and air-dried health positioning, while economy pouches compete on palm oil input efficiency in rural wholesale. Cost compression in the standard tier is intensifying because unfortified brands face retail delisting pressure. Garment worker households exhibit highest price sensitivity, whereas metropolitan convenience stores show lowest elasticity for single-serve cups.
Supply Chain Analysis
Single-source vulnerability sits with Chinese-origin flavor concentrate suppliers subject to Chattogram port heavy metal testing delays. Wheat sourcing draws from domestic Rajshahi cultivation and Russian import origins, while palm oil inputs rest on Indonesian and Malaysian export channels. Tariff exposure on edible oil imports creates margin volatility for flash-frying dependent operators. Distribution runs through PRAN-RFL's rural dealer networks with 45-60 day credit cycles and metropolitan supermarket slotting fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bangladesh's instant noodles market has entered late-cycle quality competition where BSTI fortification compliance separates viable suppliers from delisting candidates. Urban working-class buyers are shifting procurement specifications toward certified, iron-fortified formats that command premium shelf placement.
For Market Incumbents: To counter frozen paratha substitution in factory canteens, deepen air-drying technology deployment for health-positioned SKUs and secure long-term palm oil supply agreements with Indonesian suppliers. Channel control through digital ledger adoption in rural dealer networks reduces working capital strain from legacy 60-day credit cycles. For New Entrants and Emerging Players: BSTI's draft sodium threshold regulations in Bangladesh open a window for stir-fried variant specialists with lower broth dependency and milder compliance pressure. Chattogram Hill Tracts mobile vendor networks represent the most penetrable geography, with ethnic minority demand currently served by rice-based alternatives. Go-to-market execution should prioritize subscription bundling through Chaldal and Daraz platforms in Dhaka apartment complexes. For Investors and Strategic Acquirers: Asymmetric upside sits with regional processors possessing local curry flavor adaptation expertise and underutilized fortification equipment capacity. Long-term viability over a multi-year horizon favors acquisition targets with demonstrated BSTI compliance and established supermarket slotting relationships. Monitor sodium threshold regulation finalization as the critical inflection signal for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Air-Drying Technology Deployment | Non-fried lines reduce palm oil exposure while qualifying for health-positioned supermarket placement. |
| Fortification Equipment Upgrade | BSTI-compliant iron and vitamin disclosure unlocks institutional procurement contracts in garment zones. |
| Mobile Vendor Network Expansion | Hill Tracts penetration replicates rural dealer models for ethnic minority markets lacking distribution. |
| E-Commerce Subscription Bundling | Chaldal and Daraz platforms bypass wholesaler markups in Dhaka's apartment-dense garment worker neighborhoods. |
| Local Seasoning Blending Capacity | Domestic curry formulation reduces Chinese import dependency and Chattogram port clearance delays. |
Study Parameters
Coverage spans Dhaka, Chattogram, Khulna, Rajshahi and Hill Tracts divisions, with primary inputs from each. The analysis combines interviews with food processing plant managers, BSTI regulatory affairs officers, garment factory procurement leads, and rural dealer network operators with secondary validation from BSTI fortification guidelines, customs import records, and supermarket slotting fee disclosures. Bottom-up SKU volume modeling and top-down category value estimation provide triangulation across data sources.
Granularity-level modeling operates at product type, flavor profile, packaging format and distribution channel dimensions, with additional disaggregation by urban-rural buyer archetype. CAGRs derive from trend extrapolation of garment sector employment growth, fortification equipment installation rates, and e-commerce penetration curves across the analysis window. Palm oil price volatility assumptions and sodium regulation compliance timelines feed scenario-weighted outputs.
Revisions become necessary when BSTI finalizes sodium thresholds, frozen paratha substitution accelerates beyond current trajectory, or palm oil import tariffs shift materially. Forecasts reflect documented assumptions about regulatory implementation pace and technology adoption rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Eco Bowls Market
Packaged Foods
Instant Ramen Market
Packaged Foods
Spreads Market
Packaged Foods
United Kingdom Food Spreads Market
Packaged Foods
Brio Bowls Market
Packaged Foods
Low Calorie Noodles Market
Packaged Foods
Packaged Rice Market
Packaged Foods
South America Canned Fruits Market
Packaged Foods
US Packaged Salads Market
Packaged Foods
Global Dessert Mixes Market
Packaged Foods
US Packaged Food Market
Packaged Foods
Global Fruit Spreads Market
Packaged Foods
Ready to Use Fillings Market
Packaged Foods
Global Aseptic Packaging in Food Market
Packaged Foods
Asia-Pacific Ready-To-Eat Food Market
Packaged Foods
Instant Cereals Market