
 Canned Legumes Market | 2026-2036
Canned Legumes Market Size, Share, and Industry Trends Forecast 2026-2036
Canned Legumes Market Analysis
Clean-label retort technology is tilting production economics toward shorter processing cycles and firmer bean texture. Goya Foods leverages its vertically integrated sourcing network from Latin American growing regions to sustain year-round supply consistency. Bush Brothers & Company anchors its competitive position through deep regional brand equity in the southeastern United States. Del Monte Foods differentiates via controlled agricultural contracts and in-house canning operations across multiple hemispheres.
Canned legumes comprise thermally processed pulses preserved in hermetically sealed containers with brine or sauce, typically achieving commercial sterility through retort temperatures exceeding 121 degrees Celsius to ensure shelf stability and food safety. The product category serves as a shelf-stable protein source for retail pantries, foodservice kitchens, and industrial ingredient buyers requiring consistent nutritional specifications. Chickpeas and black beans occupy the largest volume positions within product type segmentation, reflecting Mediterranean and Latin American culinary adoption in North American and European kitchens. Flexible pouches represent the fastest-expanding packaging format as retailers reduce shelf weight and consumers prioritize microwave-ready convenience. Foodservice channels command distinct margin pools through institutional procurement contracts specifying custom brine formulations and calibrated drained weights.
FDA enforces acidified food regulations and low-acid canned food rules governing thermal processing validation, while USDA administers organic certification standards that shape premium product positioning and label claims. BIS in India mandates metallic contaminants testing and nutritional labeling compliance for imported and domestically canned pulse products. ISO 22000 and HACCP frameworks further govern supplier qualification protocols across multinational retail chains. Stakeholders must monitor evolving sodium reduction mandates and packaging material sustainability requirements as regulators in multiple jurisdictions tighten environmental performance standards for steel and aluminum can supply chains.
Market Dynamics
Retort processing innovations are compressing thermal cycle times while tightening texture specifications, forcing capital upgrades across canning facilities serving retail and foodservice channels.
Growth Catalysts
- Clean-label retort technology:Shorter sterilization cycles preserve bean firmness and reduce energy input per batch, aligning with processor sustainability targets.
- FSSAI fortification mandates:India's push for micronutrient-enriched packaged foods creates formulation incentives for iron-fortified chickpea and lentil SKUs targeting school feeding programs.
- Foodservice institutional procurement:K-12 districts and hospital systems specify calibrated drained weights and low-sodium brines, locking in multi-year supply agreements with certified processors.
Market Restraints
- Steel and aluminum input volatility:Can sheet costs fluctuate with energy-intensive smelting economics, compressing margins for mid-scale packagers lacking forward-contract coverage.
- Latin American supply concentration:Drought risk in Argentina and Brazil black bean belts creates single-source vulnerability for North American brands dependent on southern hemisphere harvests.
- Retort pouch technical ceiling:Current barrier films cannot match metal can oxygen transmission rates for shelf lives exceeding 36 months, limiting penetration in emergency stockpile channels.
Strategic Opportunities
- India PLI scheme for food processing:Domestic canning infrastructure incentives reduce import dependency for chickpea and kidney bean packagers targeting urban retail expansion.
- Flexible pouch microwave-ready formats:Convenience-seeking younger households in South Korea and Japan drive demand for tear-open, heat-and-serve legume packaging.
- EU Green Deal packaging mandates:Recyclability requirements and extended producer responsibility frameworks favor aluminum can recyclers over multi-layer plastic alternatives.
Industry Challenges
- Thermal process validation expertise:FDA low-acid canned food regulations require specialized microbiologists to file scheduled processes, creating hiring bottlenecks for expanding facilities.
- Legacy ERP-to-traceability integration:Batch-level digital tracking for organic certification claims demands middleware development between decades-old production systems and blockchain verification platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canned Legumes Market |
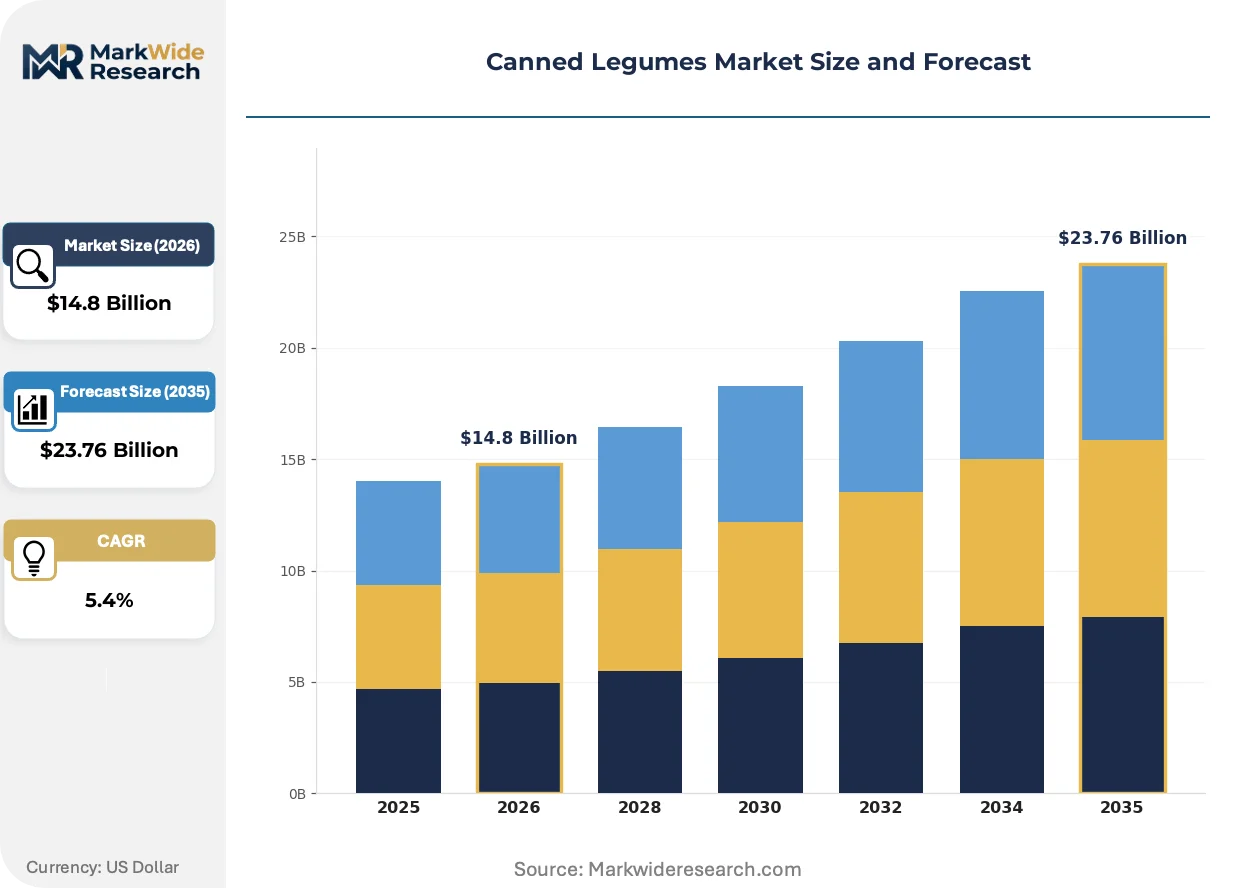
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $23.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chickpeas, Black Beans, Kidney Beans, Lentils Packaging Type: Steel Cans, Aluminum Cans, Glass Jars, Flexible Pouches Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Farmers Markets End User: Households, Restaurants, Food Manufacturers, Foodservice |
| Companies Covered | The Kraft Heinz Company, Goya Foods, Bush Brothers & Company, Del Monte Foods, Conagra Brands, Faribault Foods, KYKNOS, Teasdale Latin Foods, The Hain Celestial Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canned Legumes Market Emerging Trajectories
Processing automation and packaging material science are converging to redefine shelf-stable protein economics, with sustainability metrics now embedded in procurement scorecards.
High-pressure processing adjuncts to traditional retort sterilization are hybridizing thermal and non-thermal preservation pathways. Premium private-label retailers in Germany and the Netherlands adopt these hybrid lines to market "gentler cooked" bean textures. The technology is hybridizing quality differentiation strategies, enabling price premiums against commodity canned alternatives.
EU F-Gas Regulation phase-down schedules are accelerating ammonia-based refrigeration retrofits in canning facilities. Cold chain energy intensity drops as natural refrigerants replace hydrofluorocarbon systems. Spanish and Italian processors face the steepest compliance timelines given their concentration of legacy cooling infrastructure.
Direct-to-foodservice e-procurement platforms are fragmenting traditional distributor relationships. Institutional buyers in US K-12 and healthcare systems now specify custom brine formulations through digital portals, bypassing broadline distributors. The shift concentrates order aggregation with tech-enabled packagers capable of SKU proliferation without minimum run penalties.
Canned Legumes Market Segmentation
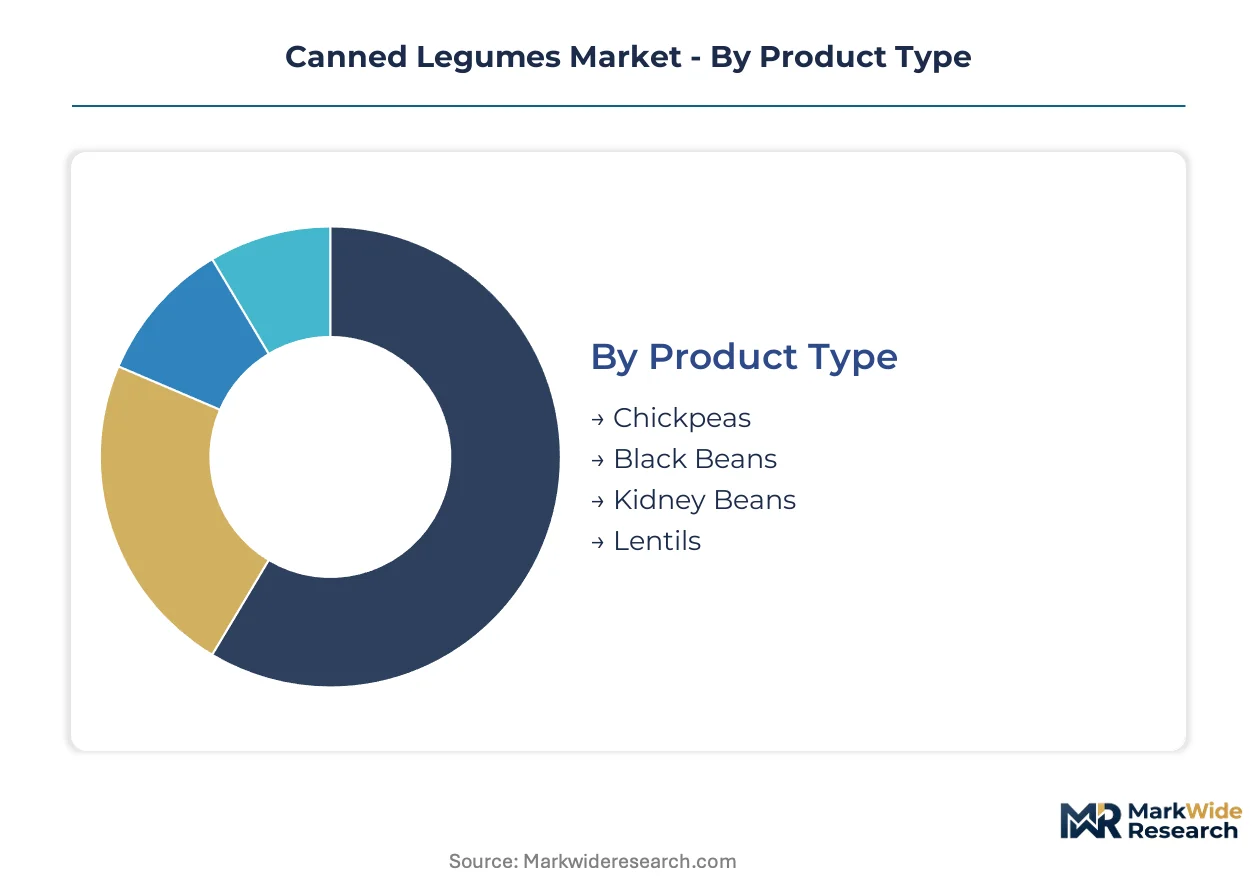
Segmentation in canned legumes reveals distinct margin profiles and technical requirements across product formats and procurement channels. Each dimension carries specific regulatory, logistical, and formulation constraints that reshape competitive positioning.
Product Type:
After-sales service intensity varies sharply by pulse variety, with chickpea and black bean SKUs demanding more technical support for texture consistency and brine formulation troubleshooting than commodity kidney beans.
- Chickpeas:Garbanzo beans require precise hydration control during retort processing to prevent skin splitting and maintain firmness specifications. Mediterranean and Middle Eastern cuisine adoption in Germany and the United Kingdom drives retail volume, while FSSAI fortification mandates in India accelerate iron-enriched chickpea development for school feeding programs.
- Black Beans:These pulses achieve premium positioning in Latin American and Southwestern US culinary applications, with processors calibrating sodium levels to meet FDA low-acid canned food rules while satisfying foodservice demand for calibrated drained weights. Supply vulnerability concentrates in Argentina and Brazil growing belts exposed to drought cycles.
- Kidney Beans:Standardized canning protocols and established buyer specifications reduce technical service overhead for this commodity segment.
- Lentils:Smaller format cans and quicker cooking properties align with convenience-oriented urban households in France and Italy.
Chickpeas hold the largest share; momentum sits with black beans as Latin American culinary influence expands across European retail.
Packaging Type:
Cost tier stratification separates premium-positioned formats from commodity steel can volumes, with barrier technology investments determining shelf-life premiums and recyclability compliance costs.
- Steel Cans:Dominant format for emergency stockpile channels and extended shelf-life applications, with 36-plus month oxygen barrier performance unmatched by flexible alternatives. EU Green Deal packaging mandates and extended producer responsibility frameworks favor steel recyclers, though energy-intensive smelting economics create input cost volatility.
- Flexible Pouches:Microwave-ready convenience drives steepest expansion trajectory in South Korean and Japanese urban households, where tear-open formats reduce preparation friction. Current barrier films cannot match metal can oxygen transmission rates beyond 36 months, limiting penetration in institutional emergency reserves.
- Aluminum Cans:Lightweight properties reduce freight costs for export-oriented processors, with superior recyclability credentials under EU circular economy regulations.
- Glass Jars:Premium retail positioning in Italian and Spanish markets emphasizes visual product integrity and artisan brand storytelling.
Steel cans dominate volume; flexible pouches are climbing the fastest as convenience-seeking younger households reshape format preferences.
Distribution Channel:
Customer type fragmentation separates institutional procurement scale from fragmented retail convenience, with digital platforms disrupting traditional distributor relationships.
- Supermarkets:Category management negotiations and slotting fee structures concentrate volume with vertically integrated packagers capable of year-round supply consistency. Goya Foods and Bush Brothers & Company leverage deep retail relationships to secure shelf positioning across southeastern US and Northeast urban corridors.
- Online Retail:Direct-to-consumer fulfillment demands specialized packaging for last-mile durability, with subscription models emerging for pantry-stocking households in Germany and the Netherlands.
- Convenience Stores:Single-serve and smaller format SKUs target immediate consumption and emergency purchase occasions.
- Farmers Markets:Local and organic positioning commands price premiums through direct producer relationships and minimal processing claims.
Supermarkets retain the largest share; online retail is gaining share fastest as digital procurement platforms fragment traditional distributor aggregation.
End User:
Application-specific requirements separate household convenience priorities from foodservice technical specifications and industrial ingredient consistency demands.
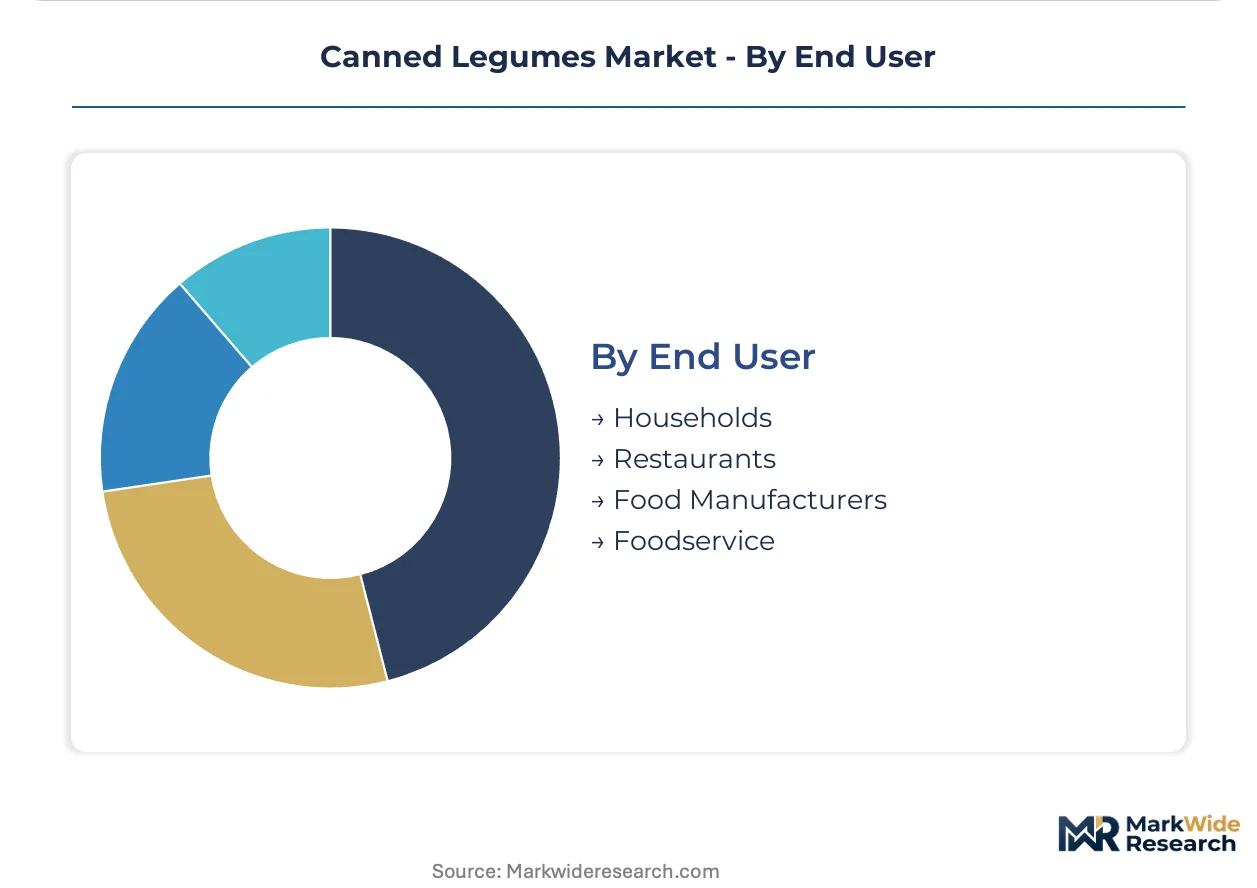
- Foodservice:Institutional procurement contracts with K-12 districts and hospital systems specify custom brine formulations, calibrated drained weights, and low-sodium profiles that lock in multi-year supply agreements. Direct-to-foodservice e-procurement platforms now enable SKU proliferation without minimum run penalties for tech-enabled packagers.
- Food Manufacturers:Industrial buyers require consistent nutritional specifications and batch-level traceability for organic certification claims, demanding middleware integration between legacy ERP systems and blockchain verification platforms.
- Households:Pantry-stocking behavior and recipe versatility drive variety-seeking across chickpea, lentil, and bean formats.
- Restaurants:Independent operators prioritize cost efficiency and preparation speed over formulation customization.
Foodservice holds the largest share; food manufacturers are expanding most quickly as clean-label ingredient demand accelerates across processed food categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency patterns are shifting as regional canning capacity expands to capture value from domestic pulse harvests. Export-oriented processors in Latin America and South Asia now supply North American and European retail channels, reversing historical trade flows.
United States
Foodservice procurement contracts with K-12 districts and hospital systems drive institutional demand for low-sodium, calibrated-drained-weight specifications. FDA low-acid canned food rules govern thermal processing validation across retort facilities. The southeastern United States anchors regional brand equity, with Bush Brothers & Company leveraging deep retail relationships across Georgia, Alabama, and Tennessee.
India
FSSAI fortification mandates for micronutrient-enriched packaged foods accelerate iron-fortified chickpea development targeting school feeding programs. BIS standards mandate metallic contaminants testing and nutritional labeling compliance for imported and domestically canned pulse products. Maharashtra and Gujarat clusters expand domestic canning infrastructure under PLI scheme incentives, reducing import dependency for urban retail expansion.
Germany
Premium private-label retailers adopt hybrid high-pressure processing lines to market "gentler cooked" bean textures against commodity alternatives. EU F-Gas Regulation phase-down schedules accelerate ammonia-based refrigeration retrofits in canning facilities. The Netherlands and German retail corridor concentrates demand for clean-label, organic-certified SKUs with extended shelf-life requirements.
Brazil
Black bean supply vulnerability concentrates in Argentina and Brazil growing belts exposed to drought cycles, creating single-source risk for North American brands. ANVISA regulations align with international food safety frameworks while regional processors expand export capacity. São Paulo state clusters serve as logistics hubs for southern hemisphere harvest timing advantages.
Japan
Microwave-ready flexible pouch formats drive steepest expansion trajectory among convenience-seeking urban households seeking tear-open, heat-and-serve legume packaging. METI standards govern food contact materials and recyclability requirements under circular economy directives. Tokyo-Osaka corridor retailers reduce shelf weight and prioritize format innovation over extended shelf-life specifications.
Canned Legumes Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated processors with captive agricultural sourcing and in-house canning operations. Tiered competitive positioning separates multinational packagers with multi-hemisphere contract networks from regional specialists anchored in single-origin supply basins. Strategic archetypes include: (1) vertically integrated agricultural processors controlling growing-to-canning value chains; (2) brand-equity regionalists with deep retail channel penetration; and (3) private-label contract manufacturers serving retailer-owned specifications. Dominant competitive moves encompass backward integration into Latin American and South Asian growing regions, and portfolio diversification into organic and low-sodium premium SKUs.
Among North American packagers, The Kraft Heinz Company and Conagra Brands exemplify scale-driven multinational archetypes with diversified shelf-stable protein portfolios, while Goya Foods occupies a distinctive position as a vertically integrated specialist with Latin American sourcing networks. Del Monte Foods represents the controlled agricultural contract model, anchoring competitive positioning through in-house canning operations across multiple hemispheres.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| Goya Foods |
| Bush Brothers & Company |
| Del Monte Foods |
| Conagra Brands |
| Faribault Foods |
| KYKNOS |
| Teasdale Latin Foods |
| The Hain Celestial Group |
| Others |
Supply Flow & Price Mechanics
Steel and aluminum input volatility determines both pricing tier spreads and supply chain shape in canned legumes, compressing margins for mid-scale packagers lacking forward-contract coverage while forcing tiered pricing stratification across premium organic, standard conventional, and economy private-label levels.
Pricing Analysis
Retort technology-generation pricing gaps separate legacy thermal processing from clean-label short-cycle systems and emerging high-pressure hybrid lines. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation, with organic-certified SKUs commanding substantial premiums over conventional alternatives. Pricing pressure stems from energy-intensive smelting economics in can sheet production, with commodity spot volatility transmitting downstream. Foodservice institutional buyers exhibit lowest price sensitivity due to multi-year contract locking, while private-label retail channels face acute cost compression.
Supply Chain Analysis
Export-control regime restrictions on advanced barrier film technologies limit flexible pouch penetration in emergency stockpile channels, preserving steel can dominance for shelf lives exceeding 36 months. Geographic supply concentration centers on Argentina, Brazil, and India for pulse sourcing, with can sheet production drawing from energy-intensive smelting operations in China and Russia. Raw material dependencies include steel and aluminum can sheet, retort pouch barrier films, and brine formulation chemicals. Single-source vulnerability concentrates in southern hemisphere black bean belts exposed to drought cycles. Distribution runs through broadline foodservice distributors, retail chain category management, and direct-to-institutional e-procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canned legumes constitute a defensive-moat market anchored by regulatory entrenchment, where FDA low-acid canned food rules and thermal process validation requirements create structural barriers to facility expansion.
For Market Incumbents: Harden competitive positioning through backward integration into Latin American growing regions to secure supply consistency against drought-driven volatility. Invest in clean-label retort technology upgrades to capture premium positioning as FDA sodium reduction mandates tighten. Deepen channel control via direct-to-foodservice e-procurement platforms that fragment traditional distributor relationships and lock in institutional procurement contracts. For New Entrants and Emerging Players: India's underpenetrated urban retail expansion presents the most accessible white-space target, with PLI scheme incentives reducing capital barriers for domestic canning infrastructure. Flexible pouch microwave-ready formats in South Korea and Japan offer second-entry angles for convenience-seeking younger households. Pursue private-label contract manufacturing relationships with premium European retailers seeking "gentler cooked" hybrid processing claims. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated agricultural processors with captive growing-to-canning value chains. Long-term viability rests on multi-hemisphere sourcing networks that mitigate single-origin climate risk. Watch for inflection signals in India PLI scheme disbursement rates and EU Green Deal packaging mandate enforcement timelines as indicators of regional capacity shift acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Growing Regions | Captive supply from Argentina and Brazil mitigates drought-driven black bean shortage risk. |
| Clean-Label Retort Technology Deployment | Shorter sterilization cycles align with FDA sodium reduction mandates and sustainability targets. |
| Direct-to-Foodservice E-Procurement Platform | Bypasses broadline distributors to capture institutional procurement contract aggregation. |
| Flexible Pouch Format Expansion | Microwave-ready convenience targets younger households in South Korea and Japan urban corridors. |
| Organic Certification Investment | Premium SKU positioning leverages USDA standards and EU organic regulations for label claims. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with food processing executives, retail category buyers, foodservice procurement directors, and regulatory compliance officers; and secondary validation through FDA low-acid canned food filings, USDA organic certification databases, BIS standards documentation, and trade customs records. Bottom-up facility capacity modeling and top-down retail audit triangulation anchored volume estimates.
Forecast inputs considered pulse variety segmentation, packaging format technology tiers, distribution channel fragmentation, and end-user application requirements across the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macroeconomic consumption indicators. Industry-specific inputs incorporated FSSAI fortification mandate rollout timelines and EU F-Gas Regulation compliance schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by private-equity-backed contract manufacturers would shift outcomes. Material shifts in steel and aluminum input costs, retort pouch barrier film breakthroughs, or India PLI scheme incentive acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
US Canned Foods Market
Packaged Foods
United Arab Emirates Food Products Market
Packaged Foods
Pre-Packaged Sandwich Market
Packaged Foods
Tortilla Market
Packaged Foods
Middle East and Africa Energy Bar Market
Packaged Foods
Instant Ramen Market
Packaged Foods
Fat Free Pasta Market
Packaged Foods
Canned Pasta Market
Packaged Foods
Hummus Market
Packaged Foods
India Breakfast Cereals Market
Packaged Foods
Jams and Spreads Market
Packaged Foods
Peanut Butter Market
Packaged Foods
Global Dessert Mixes Market
Packaged Foods
South America Breakfast Cereals Market
Packaged Foods
Instant Noodles Market
Packaged Foods
Canned Food Market