
 Vegan Cheese Sauce Market | 2026-2036
Vegan Cheese Sauce Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Cheese Sauce Market Analytics
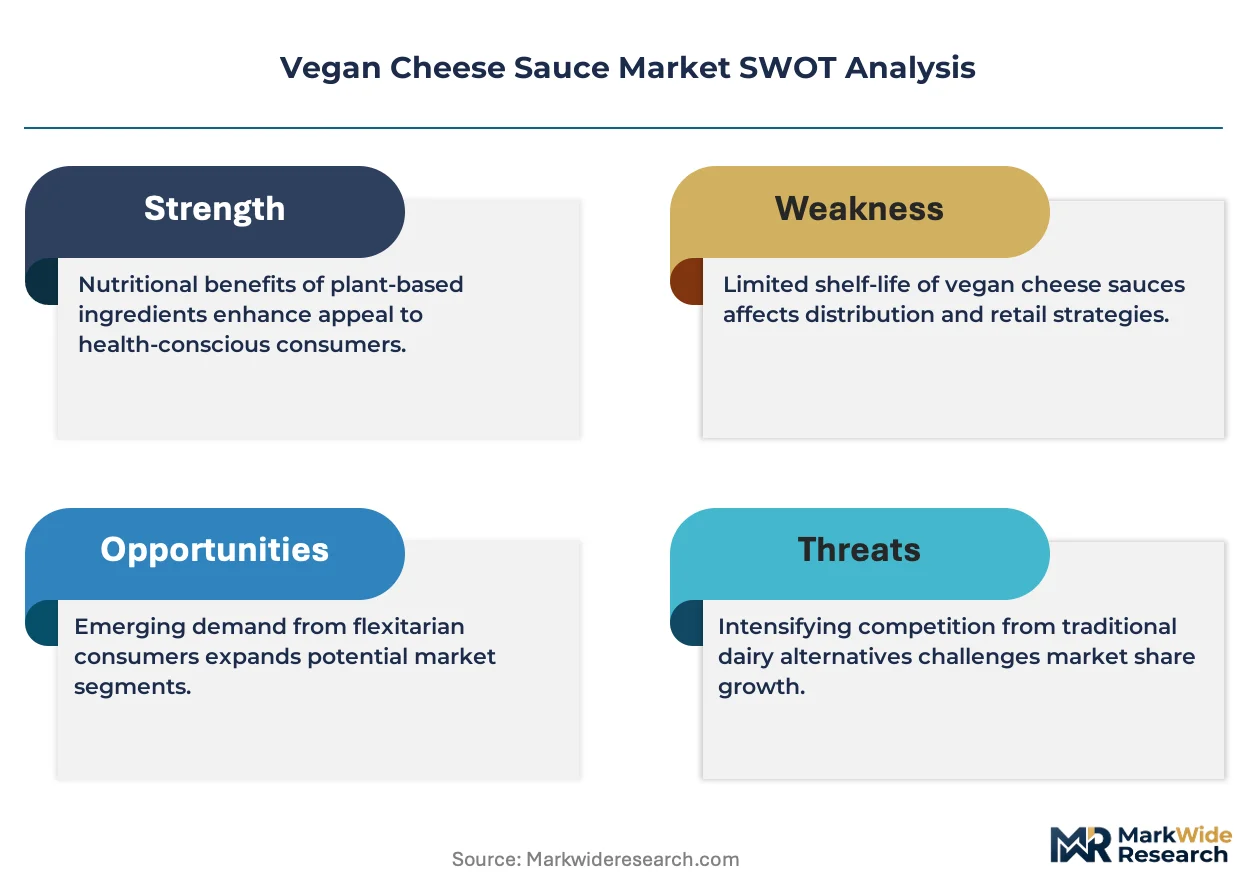
The capital-intensity divergence between artisanal nut-milk fermenters and industrial-scale soy processors is redrawing competitive boundaries in vegan cheese sauce production. Daiya Foods Inc. leverages its established retail distribution network to sustain shelf presence across conventional grocers. Miyoko's Creamery differentiates through cultured cashew fermentation techniques that anchor its premium positioning. Violife Foods competes on price-accessible coconut-oil formulations with broad European retail penetration.
Vegan cheese sauce denotes a plant-derived, emulsified condiment typically formulated from hydrated nut or legume proteins combined with starches, oils, and acidifiers to achieve meltability and flavor profiles mimicking dairy-based cheese sauces. Manufacturers employ high-shear homogenization followed by pasteurization to stabilize oil-in-water emulsions and extend refrigerated shelf life. Cashew-based variants occupy the premium tier due to superior mouthfeel and shorter ingredient decks, while soy-based formats retain volume leadership through lower input costs and established supply chains. Coconut-based alternatives are gaining traction in food service channels where extended hold temperatures demand higher fat stability.
FDA oversight of dairy-term usage on plant-based labels directly shapes permissible marketing claims and retail placement strategies for sauce manufacturers. USDA Organic certification and Non-GMO Project verification function as de facto gatekeepers for shelf placement in mainstream supermarkets and health food stores. Stakeholders must monitor evolving enforcement postures at the FDA and state-level agricultural departments as these determine whether "cheese sauce" nomenclature survives legal challenge.
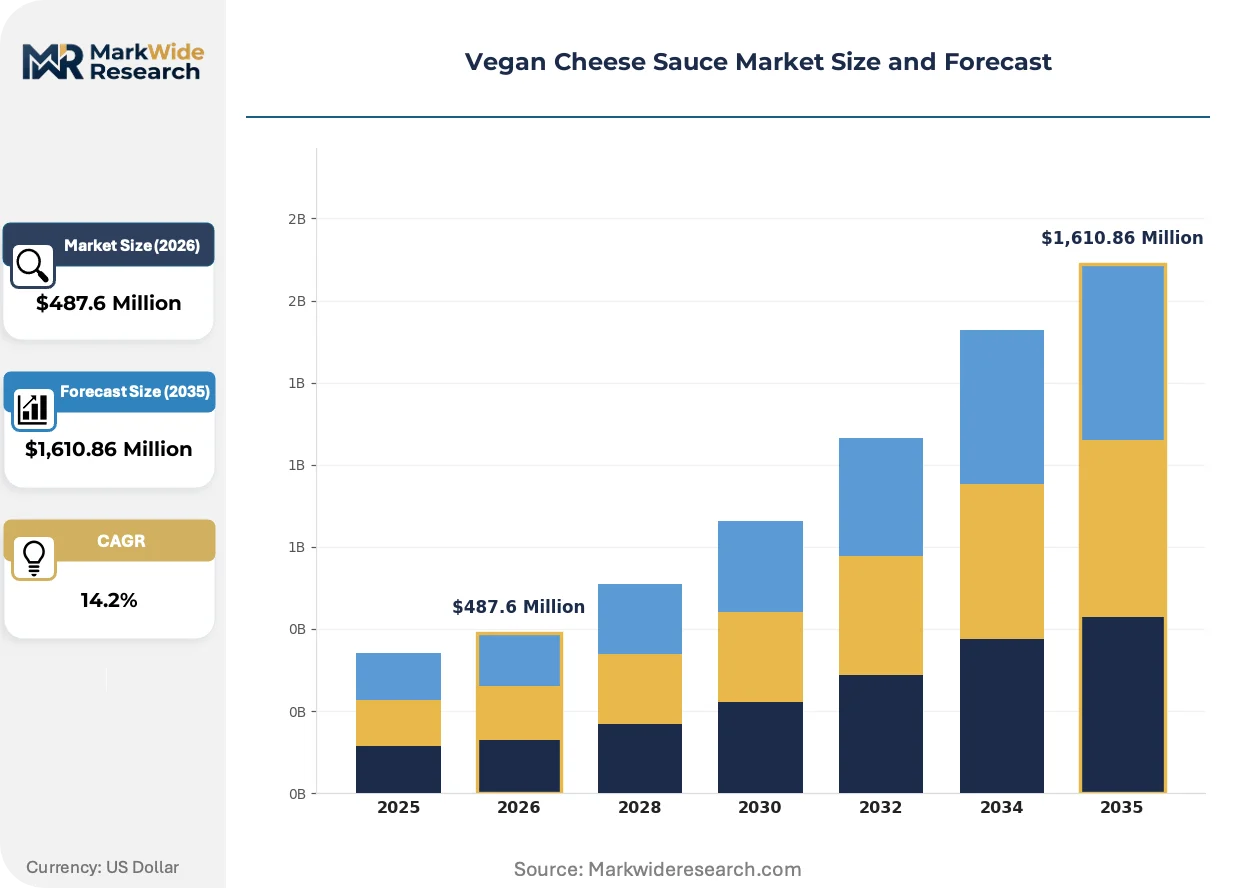
Market Dynamics
High-shear homogenization equipment costs and cashew supply volatility are redrawing production economics across vegan cheese sauce manufacturing, forcing mid-tier processors to choose between premium ingredient positioning and volume-scale soy processing.
Growth Catalysts
- USDA Organic certification:Clean-label requirements from mainstream supermarkets are accelerating reformulation investments among mid-size processors seeking shelf placement in conventional retail channels.
- Food service channel expansion:Quick-service restaurant chains are adding dedicated plant-based menu lines that require heat-stable, extended-hold sauce formulations with coconut-oil fat matrices.
- Cultured fermentation techniques:Advances in cashew-milk acidification are narrowing flavor gaps with dairy-based cheese sauces, drawing premium positioning from specialty grocers.
Market Restraints
- Cashew price volatility:Vietnamese and Indian raw nut supply fluctuations compress margins for premium-tier producers dependent on single-origin sourcing.
- FDA dairy terminology restrictions:Pending enforcement actions on "cheese sauce" labeling create marketing compliance costs and retail placement uncertainty.
- Soy protein supply concentration:Midwestern US processing infrastructure limits geographic diversification options for cost-driven manufacturers.
Strategic Opportunities
- European food service penetration:Violife's established retail presence creates channel knowledge transferable to commercial kitchen supply contracts.
- Precision fermentation proteins:Emerging whey-identical proteins from Perfect Day and competitors enable next-generation meltability without nut allergen concerns.
- Non-GMO Project verification:Accelerating certification timelines capture shelf space in natural products retailers ahead of conventional brand entries.
Industry Challenges
- High-shear equipment capex:Industrial homogenization and pasteurization lines require seven-figure investments that strain mid-cap balance sheets.
- Cultured product scale-up:Maintaining live fermentation consistency across batch production demands specialized microbiology talent in short supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Cheese Sauce Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,610.86 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cashew-Based, Soy-Based, Almond-Based, Coconut-Based Application: Pasta Dishes, Nachos, Pizza Toppings, Dips Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Food Service Consumer Type: Vegetarians, Vegans, Health Conscious, Lactose Intolerant |
| Companies Covered | Daiya Foods Inc., Follow Your Heart, Miyoko’s Creamery, Violife Foods, Kite Hill, Wayfare Foods, Parmela Creamery, Treeline Cheese, Good Planet Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Cheese Sauce Market Evolving Landscape
Equipment miniaturization and precision fermentation are converging to compress minimum viable production scales, enabling distributed manufacturing models that challenge centralized plant economics.
High-pressure processing is decomposing the traditional pasteurization bottleneck in artisanal vegan cheese sauce production. Small-batch producers in Portland and Austin are adopting cold-pressure systems that extend refrigerated shelf life without thermal degradation of cashew proteins. This technology is decomposing the capital barrier between cottage-scale fermenters and regional distribution contracts.
REACH chemical registration requirements in the European Union are tightening emulsifier approval pathways for coconut-based formulations. Manufacturers reformulating for the EU market are substituting lecithin sources and revising additive decks ahead of 2025 compliance deadlines. Food service operators with transatlantic supply chains are consolidating specifications to single formulations meeting both FDA and EFSA standards.
Direct-store-delivery relationships are replacing traditional broker-mediated wholesale arrangements in the natural products channel. Regional processors in California and Colorado are building captive refrigerated logistics networks that bypass conventional distributor markups. This pattern is most visible in the Rocky Mountain and Pacific Northwest metropolitan markets where specialty grocer consolidation has reduced viable wholesale intermediaries.
Vegan Cheese Sauce Market Segmentation
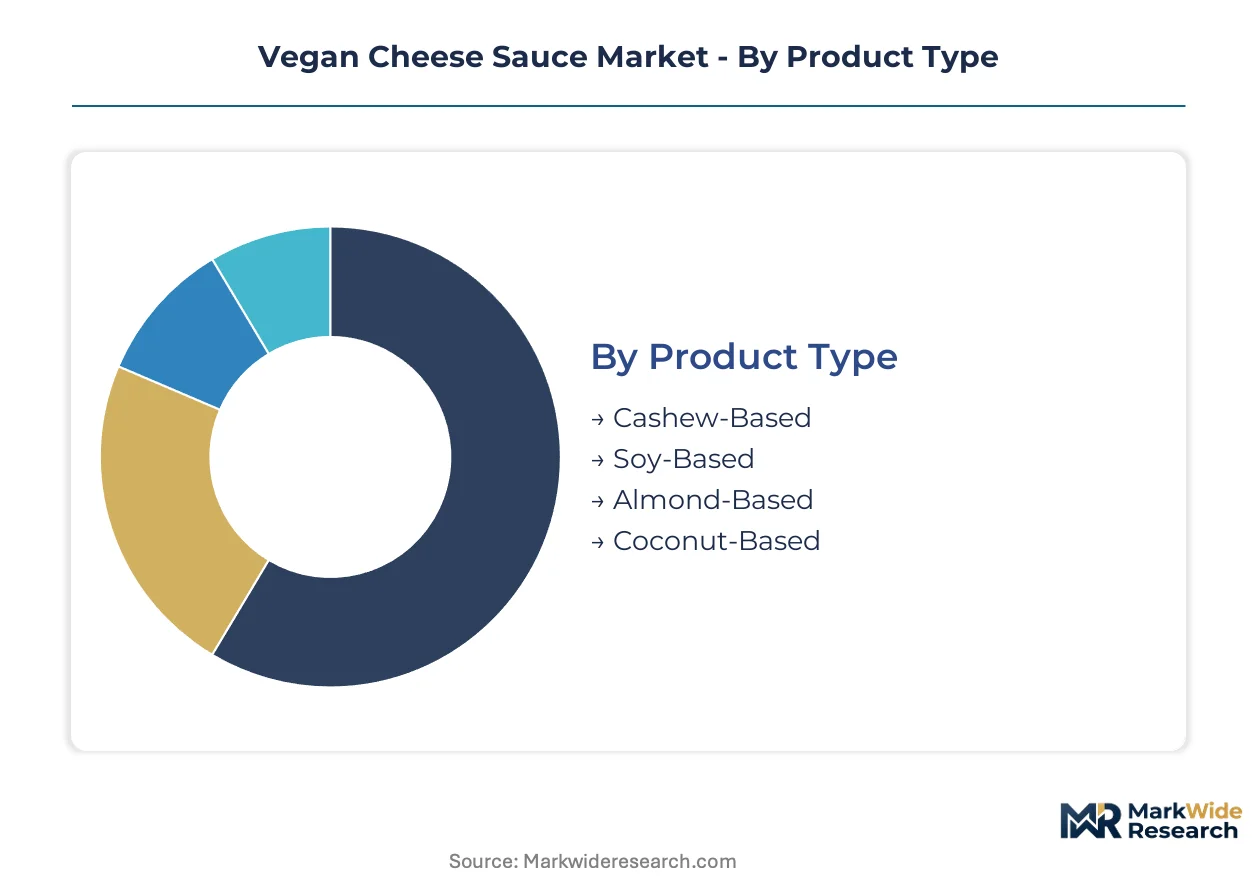
Vegan cheese sauce segmentation reveals divergent supply chain footprints across ingredient bases and channel strategies. Product type and distribution channel choices determine whether manufacturers pursue export-led premium positioning or domestic volume scale.
Product Type:
Cashew-based and coconut-based variants originate primarily from Vietnamese and Southeast Asian nut supply chains, while soy-based production clusters in Midwestern US processing infrastructure. Almond-based sourcing concentrates in California's Central Valley.
- Cashew-Based:Formulated from hydrated cashew proteins with minimal starch binders, delivering superior mouthfeel through high-fat emulsion stability. Demand concentrates in US specialty grocers and European premium retail channels where shorter ingredient decks justify price premiums. Vietnamese supply volatility compresses margins for single-origin dependent producers.
- Soy-Based:Leverages established Midwestern US crushing infrastructure with lower input costs and standardized protein isolates. Volume leadership persists through conventional supermarket placement and institutional food service contracts where cost efficiency dominates procurement criteria.
- Almond-Based:California-sourced nut proteins with lighter flavor profiles suited to health-conscious positioning in natural products retailers.
- Coconut-Based:Southeast Asian oil and cream bases optimized for heat-stable extended-hold applications in quick-service restaurant chains.
Soy-based formulations command the established base. The steepest expansion runs through cashew-based premium positioning.
Application:
Application segmentation tracks divergent technical requirements across food service heat stability demands and retail convenience expectations. Pasta dishes and nachos represent contrasting formulation specifications.
- Pasta Dishes:Requires smooth, pourable viscosity with reheat stability for retail jarred formats and food service steam table applications. Demand concentrates in Italian-themed restaurant chains and meal kit subscription services where sauce integration simplifies kitchen operations.
- Nachos:Demands extended hold temperatures above 140°F without oil separation, driving coconut-oil fat matrix adoption in stadium concessions and cinema chains. QSR partnerships with dedicated plant-based menu lines accelerate specification lock-in.
- Pizza Toppings:Specialized spreadable consistency with bake stability for frozen pizza co-manufacturing contracts.
- Dips:Cold-service formulations with refrigerated shelf life extension through high-pressure processing in artisanal regional brands.
Nachos applications anchor food service volume commitments. Pasta dishes gain share fastest through retail channel expansion.
Distribution Channel:
Channel segmentation reflects capital intensity divergence between broker-mediated wholesale and captive direct-store-delivery logistics. Supermarkets and food service demand distinct packaging formats and shelf life specifications.
- Supermarkets:Requires USDA Organic and Non-GMO Project verification for mainstream shelf placement, with conventional grocers demanding extended refrigerated codes and club formats specifying multi-serve bulk packaging. Slotting fee structures favor established processors with trade promotion budgets.
- Food Service:Specifications prioritize heat stability, extended hold performance, and portion-control packaging for commercial kitchen efficiency. National account contracts with QSR chains drive volume concentration among processors with USDA-inspected manufacturing facilities.
- Online Retail:Direct-to-consumer frozen shipment capability with insulated packaging requirements and subscription model penetration.
- Health Food Stores:Cultured fermentation positioning and clean-label verification for natural products channel placement.
Supermarkets maintain the volume base. Food service contracts expand most quickly through chain restaurant plant-based menu proliferation.
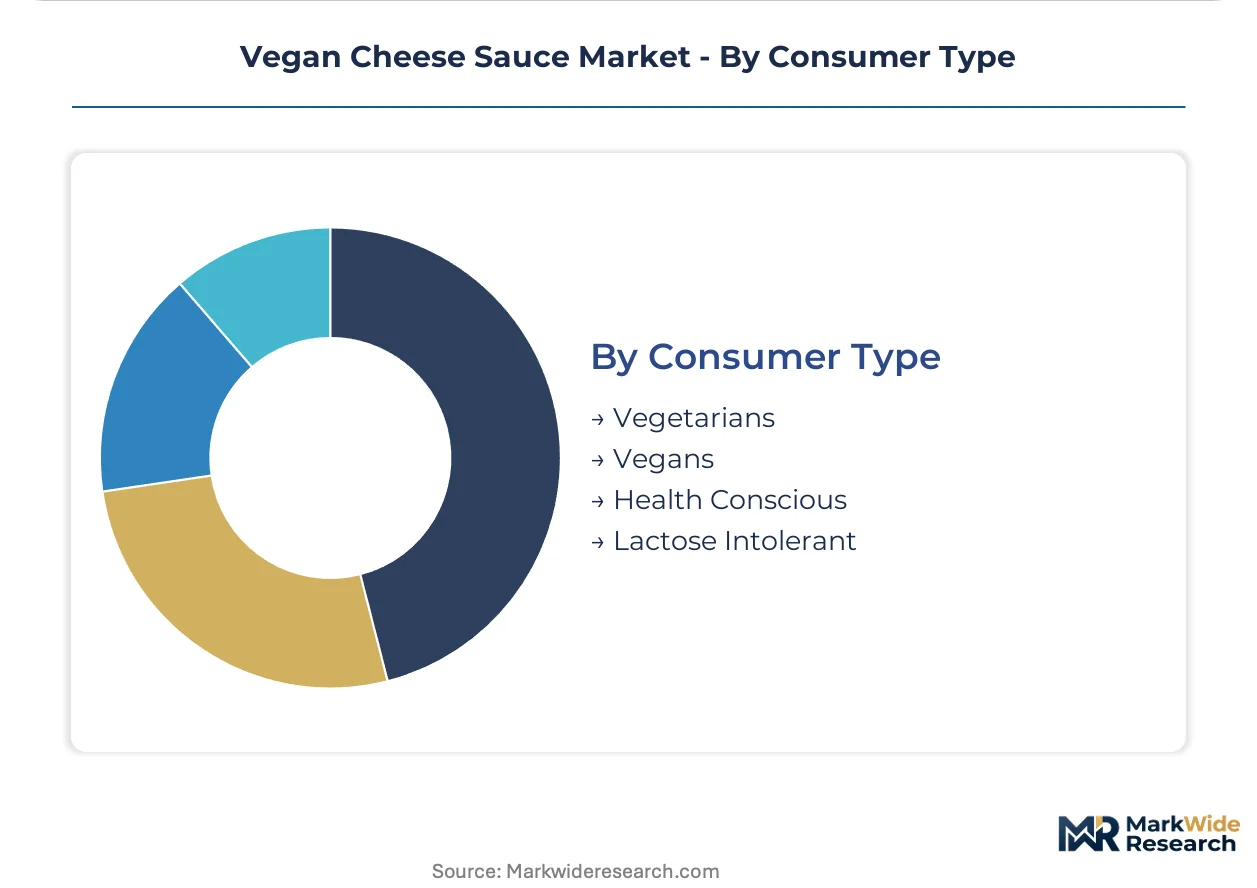
Consumer Type:
Consumer segmentation maps distinct purchasing motivations across dietary restriction management and ethical positioning preferences. Health conscious and lactose intolerant segments drive mainstream retail penetration beyond core vegan demographics.
- Health Conscious:Prioritizes clean-label ingredient decks, reduced sodium formulations, and functional nutrition claims including protein fortification. Demand concentrates in natural products retailers and premium supermarket perimeter departments where nutritional transparency commands price premiums.
- Lactose Intolerant:Functional dietary management without ethical or environmental motivation, representing the largest addressable expansion segment through conventional grocery dairy alternative aisles. Mainstream placement requires flavor parity with dairy-based benchmarks.
- Vegetarians:Flexitarian positioning with occasional dairy consumption, requiring competitive taste profiles to drive substitution.
- Vegans:Core ethical consumers with established brand loyalty and willingness to accept texture trade-offs for verified animal-free supply chains.
Lactose intolerant consumers anchor mass-market expansion. Health conscious positioning climbs the fastest through premium retail channel growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for vegan cheese sauce varies sharply by market maturity. United States buyers absorb premium cashew-based pricing with minimal volume contraction, while emerging markets in Asia-Pacific remain acutely price-sensitive to coconut-oil alternatives.
United States
Health-conscious consumers and lactose-intolerant households drive premium-tier adoption in coastal metropolitan markets. FDA dairy terminology enforcement actions create labeling compliance costs that favor established processors with legal resources. Portland and Austin clusters anchor artisanal production using high-pressure processing systems that bypass thermal pasteurization.
Germany
EU Green Deal sustainability mandates and EFSA emulsifier regulations accelerate reformulation investments for export-compliant formulations. REACH chemical registration deadlines compress product development timelines for coconut-based variants. Berlin and Hamburg processors concentrate on precision fermentation partnerships to reduce nut supply dependencies.
United Kingdom
Quick-service restaurant chains expanding plant-based menu lines generate food service volume commitments with extended-hold specifications. Trading standards enforcement on dairy alternative nomenclature creates retail placement uncertainty. London metropolitan area dominates direct-store-delivery logistics bypassing traditional wholesale intermediaries.
Canada
Health Canada and PMRA oversight of novel food ingredients shapes permissible fermentation-derived protein pathways. USDA Organic equivalency agreements facilitate cross-border supply chain integration. Toronto and Vancouver clusters specialize in clean-label cashew formulations for natural products retail channels.
Australia
TGA-aligned food standards and FSANZ labeling requirements govern permissible health claims on plant-based cheese alternatives. Extended refrigerated supply chains demand shelf life extension technologies. Melbourne and Sydney processors adopt high-pressure processing to serve dispersed metropolitan markets with minimal distributor infrastructure.
Vegan Cheese Sauce Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in vegan cheese sauce manufacturing. Cultured fermentation specialists command premium positioning through live microbiology capabilities, while industrial soy processors dominate volume tiers through Midwestern crushing infrastructure. The competitive terrain separates into three strategic archetypes: artisanal fermenters with regional distribution, mid-tier nut-milk processors balancing quality and scale, and commodity-scale oil-based formulators serving food service contracts. Dominant competitive moves include backward integration into cashew sourcing and captive direct-store-delivery logistics construction.
Within the premium fermentation tier, Miyoko's Creamery and Treeline Cheese exemplify archetypes leveraging live culture techniques to justify price positioning in specialty retail. Daiya Foods Inc. anchors the mass-market vector with established broker networks across conventional grocers. Violife Foods occupies the European-export position with coconut-oil formulations optimized for heat-stable food service applications.
| Leading Market Players |
|---|
| Daiya Foods Inc. |
| Follow Your Heart |
| Miyoko's Creamery |
| Violife Foods |
| Kite Hill |
| Wayfare Foods |
| Parmela Creamery |
| Treeline Cheese |
| Good Planet Foods |
| Others |
Value Network & Pricing Analysis
Mid-cap equipment utilization rates near 85 percent in soy processing clusters compress margin buffers for cashew-dependent artisanal producers, forcing tiered price floors that separate industrial-scale manufacturers from regional fermenters. Vietnamese nut supply volatility transmits directly into premium-tier pricing power, while Midwestern crushing infrastructure anchors volume-grade cost structures.
Pricing Analysis
After-sales service contracts for high-shear homogenization equipment and extended maintenance agreements drive lifetime value capture for processing technology vendors. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade—USDA Organic and Non-GMO Project verification command 15-25 percent premia in conventional supermarkets. Cost compression in cashew-based tiers is intensifying because Vietnamese supply fluctuations force hedging premiums or multi-origin sourcing investments. Institutional food service buyers exhibit lowest price sensitivity due to specification lock-in with heat-stable formulations, while conventional grocery lactose-intolerant segments drive hard bargaining on per-unit costs.
Supply Chain Analysis
Vietnam and India anchor raw cashew supply, while the United States concentrates soy protein isolate production and Southeast Asian markets feed coconut-oil and cream bases. Formulation draws from hydrated nut proteins, starch binders, and emulsifier systems with lecithin substitution pressures under REACH compliance timelines. Single-source vulnerability in Vietnamese cashew procurement exposes premium-tier producers to margin compression during harvest disruptions. Distribution runs through broker-mediated wholesale for conventional supermarkets, shifting toward captive direct-store-delivery logistics in natural products channels across Rocky Mountain and Pacific Northwest metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through quick-service restaurant chain consolidation and specialty grocer roll-ups, fragmenting negotiating leverage among mid-tier processors without national account scale.
For Market Incumbents: Consolidate backward integration into cashew sourcing through Vietnamese processor partnerships or multi-origin supply agreements to defend against nut price volatility. Lock in USDA-inspected manufacturing certifications to secure QSR national account specifications before emerging precision fermentation competitors achieve scale. Channel control through captive refrigerated logistics construction in California and Colorado markets bypasses distributor markups and secures shelf placement independence. For New Entrants and Emerging Players: Differentiate on high-pressure processing technology adoption for cold-pasteurized artisanal positioning in Portland and Austin metropolitan clusters where specialty grocer consolidation has reduced wholesale intermediary options. Target food service white space in European commercial kitchen supply contracts where Violife's retail presence has not yet translated to institutional penetration. Launch through direct-to-consumer frozen subscription models with insulated packaging capabilities to build brand equity before conventional retail slotting fee negotiations. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision fermentation partnerships over nut-milk infrastructure, as Perfect Day and competitors enable whey-identical proteins without agricultural commodity exposure. Long-term viability over the next decade rests on microbiology talent acquisition and live culture consistency at scale rather than equipment depreciation cycles. Monitor FDA enforcement posture on "cheese sauce" dairy terminology as the inflection signal determining whether incumbent marketing investments survive legal challenge or require complete repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cashew Sourcing | Vietnamese processor partnerships reduce margin volatility from single-origin dependence. |
| USDA-Inspected Facility Certification | National account eligibility with QSR chains demands federal inspection compliance. |
| High-Pressure Processing Adoption | Cold-pasteurized shelf life extension differentiates artisanal brands in natural products channels. |
| Precision Fermentation Partnership | Whey-identical proteins from Perfect Day competitors eliminate nut allergen constraints. |
| Captive Direct-Store-Delivery Logistics | Refrigerated distribution networks in California and Colorado bypass conventional wholesale markups. |
Research Methodology
The analysis maps cashew-based, soy-based, coconut-based, and almond-based formulation sub-sectors, each validated through R&D directors at fermentation specialists, procurement leads at QSR chains, category buyers at conventional supermarkets, and plant managers at Midwestern crushing facilities. Primary interview findings triangulate against FDA labeling guidance documents, USDA Organic certification databases, customs import records for Vietnamese cashew shipments, and SEC 10-K filings from publicly traded food manufacturers. Bottom-up volume estimates from processor capacity utilization cross-check against top-down demand modeling from food service channel expansion rates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models ingredient base, application specification, distribution channel structure, and consumer motivation segmentation dimensions. CAGR derivation incorporates high-shear equipment capex depreciation schedules and cashew supply elasticity curves alongside food service contract renewal rates. Forecast inputs include precision fermentation protein commercialization timelines and FDA enforcement probability assessments on dairy terminology restrictions.
The analysis sits within stated boundaries; outcomes outside sustained QSR plant-based menu proliferation or stable Vietnamese agricultural export conditions would require recalibration. Forecasts reflect documented assumptions regarding certification adoption rates and emulsifier regulatory pathways. Recalibration cycles align with material shifts in FDA labeling enforcement, REACH chemical registration deadlines, and precision fermentation protein cost parity achievements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Condiments & Sauces
Fat Free Salad Dressings Market
Condiments & Sauces
Salad Dressings Market
Condiments & Sauces
Egg-Free Mayonnaise Market
Condiments & Sauces
Table Sauce Market
Condiments & Sauces
Low Fat Mayo Market
Condiments & Sauces
UK Prepared Mustard Market
Condiments & Sauces
Barbeque Sauce Market
Condiments & Sauces
Oriental Sauce Market
Condiments & Sauces
Vegan Fish Sauce Market
Condiments & Sauces
Sugar Toppings Market
Condiments & Sauces
Soups and Sauces Market
Condiments & Sauces
Sauces, Condiments, and Dressings Market
Condiments & Sauces
Horseradish Sauce Market
Condiments & Sauces
Europe Hot Sauce Market
Condiments & Sauces
Condiments Market
Condiments & Sauces
Global Fish Sauce Market