
 Freekeh Market | 2026-2036
Freekeh Market Size, Share, and Industry Trends Forecast 2026-2036
Freekeh Market Analysis
Market Context with Strategic Players
Levantine green wheat processing capacity is shifting toward North American and European facilities as export-oriented producers scale operations. Greenwheat Freekeh Pty Ltd anchors Australian-origin supply through controlled roasting infrastructure and long-term grower contracts. Bob's Red Mill Natural Foods leverages its Portland-based milling network to sustain branded distribution across US natural grocery channels. Canaan Freekeh Foods differentiates through Palestinian-origin storytelling and direct relationships with Levantine farming cooperatives.
Technical Definition and Structural Segments
Freekeh denotes immature durum wheat harvested while still green, then fire-roasted and rubbed to remove chaff, yielding a smoky, chewy grain with protein content exceeding fifteen percent and fiber levels comparable to quinoa. The roasting process deactivates enzymes and creates Maillard compounds that extend shelf stability while delivering distinctive flavor profiles valued by chefs and food manufacturers. Whole grain freekeh dominates volume due to minimal processing and strong positioning in clean-label formulations, though cracked freekeh captures margin in quick-cooking convenience segments where preparation time competes with quinoa and bulgur. Online stores represent the fastest-growing distribution channel as direct-to-consumer subscription models bypass traditional specialty shop intermediaries.
Regulatory Frame and Forward-Looking Close
USDA National Organic Program standards and EU organic regulations govern freekeh labeling, while FDA and EFSA food safety frameworks apply to mycotoxin thresholds in roasted grain products. These bodies enforce lot traceability and residue testing that shapes exporter market access and domestic producer compliance costs. Stakeholders must monitor evolving organic equivalency agreements between the United States and major supplying nations, as reciprocal recognition determinations will reshape competitive sourcing options.
Market Dynamics
Freekeh production is consolidating around controlled roasting infrastructure as Australian and Levantine processors expand fire-roasting capacity to meet clean-label demand from North American and European health food retailers.
Growth Catalysts
- USDA Organic Program:Certification requirements for ancient grains are tightening supply chain traceability, compelling processors to invest in lot-tracking systems that differentiate premium-positioned products.
- Clean-label formulation:Food manufacturers are substituting freekeh for refined grains in plant-based protein products, leveraging its fifteen-plus percent protein content and distinctive Maillard flavor compounds.
- German health food retail:Shelf space expansion for ancient grains is accelerating as dm-drogerie markt and Alnatura increase SKU counts for whole grain and cracked variants.
Market Restraints
- Durum wheat input volatility:Climate stress on Australian and Levantine growing regions is compressing margins for processors locked into long-term grower contracts.
- Single-origin supply concentration:Palestinian and Jordanian export volumes depend on regional political stability, creating shipment reliability risk for European importers.
- Quinoa substitution threat:Peruvian and Bolivian quinoa suppliers are matching freekeh's protein positioning while offering established supply chain infrastructure to North American buyers.
Strategic Opportunities
- Direct-to-consumer subscription:Online stores are bypassing specialty shop intermediaries, enabling processors to capture margin and build recurring revenue through meal-kit partnerships.
- EU organic equivalency agreements:Reciprocal recognition determinations between the United States and major supplying nations will reshape competitive sourcing options for certified product lines.
- Quick-cooking cracked segments:Convenience-oriented formulations targeting time-constrained urban consumers are capturing premium positioning against bulgur and instant quinoa.
Industry Challenges
- Fire-roasting skill scarcity:Traditional roasting expertise concentrated in Levantine processing cooperatives is not scaling to mechanized production lines, creating quality consistency gaps.
- Organic certification timelines:USDA and EU organic transition periods for new growing regions are extending eighteen to thirty-six months, delaying market entry for expansion projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freekeh Market |
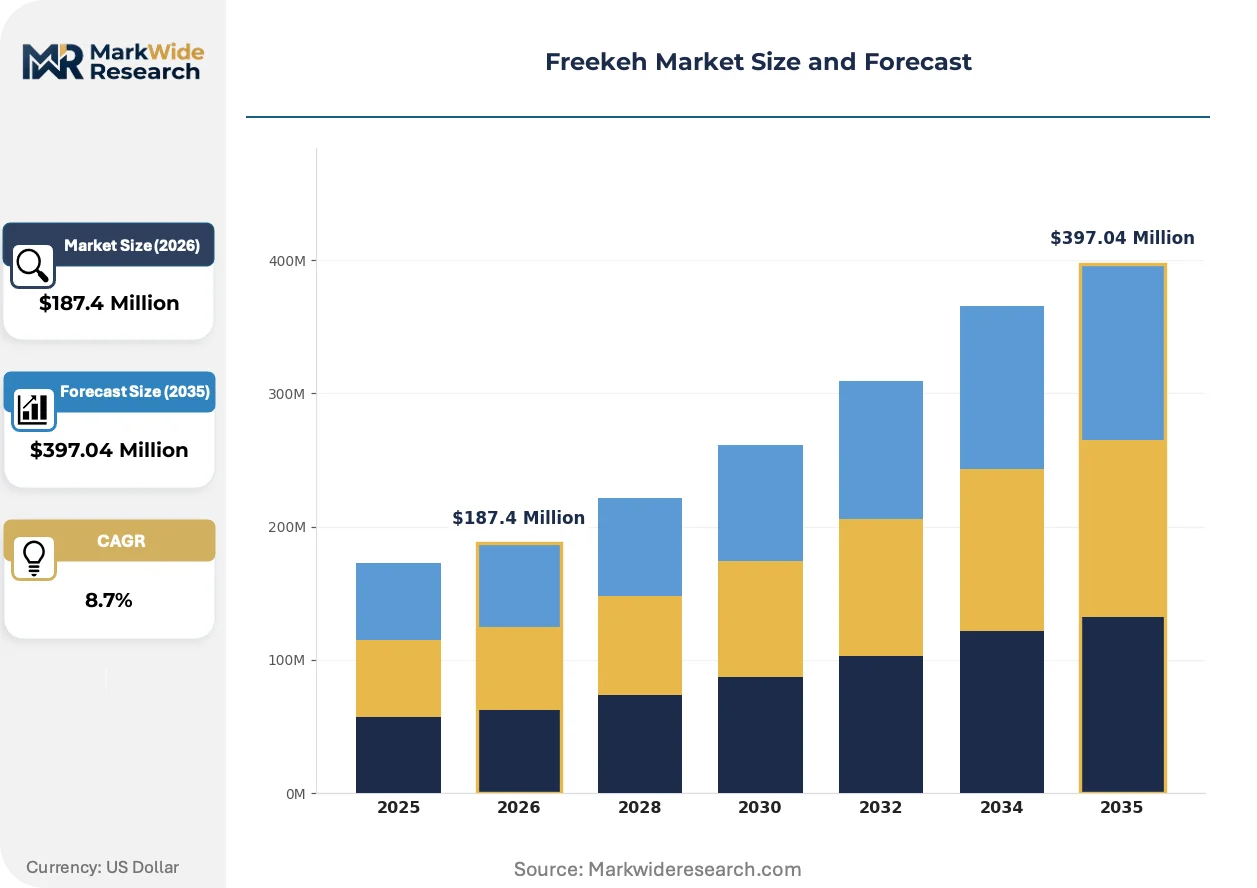
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Grain, Cracked, Roasted, Powdered End User: Households, Restaurants, Food Manufacturers, Health Food Stores Distribution Channel: Online Stores, Supermarkets, Specialty Shops, Farmers' Markets Application: Salads, Soups, Side Dishes, Breakfast Cereal |
| Companies Covered | Bocon SRL, Leathams Ltd, Bob’s Red Mill Natural Foods, First Quality Foods, Freekehlicious, Canaan Freekeh Foods, Freekeh Foods Inc, Lotus Foods, Greenwheat Freekeh Pty Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freekeh Market Emerging Trajectories
Roasting technology and distribution architecture are converging to compress supply chains and reposition freekeh from ethnic specialty to mainstream health ingredient.
Small-batch electric roasting units are decentralizing production capacity away from centralized fire-roasting facilities. Regional millers in Portland and Melbourne are adopting modular equipment to process local green wheat. This technology is decentralizing quality control and enabling farm-to-package traceability claims that command retail premiums.
EFSA mycotoxin thresholds for roasted grain products are tightening residue testing protocols. Exporters to European Union markets must now demonstrate lot-level aflatoxin documentation. Cracked freekeh formulations for quick-cooking segments are absorbing disproportionate compliance costs as they target price-sensitive institutional buyers.
Subscription-based replenishment is displacing periodic bulk purchasing among urban health-conscious consumers. Direct-to-consumer channels are capturing volume from natural grocery intermediaries in Germany and the United Kingdom. This behavioral shift is most visible in London and Berlin, where meal-kit services are featuring freekeh as a quinoa alternative in weekly recipe rotations.
Freekeh Market Segmentation
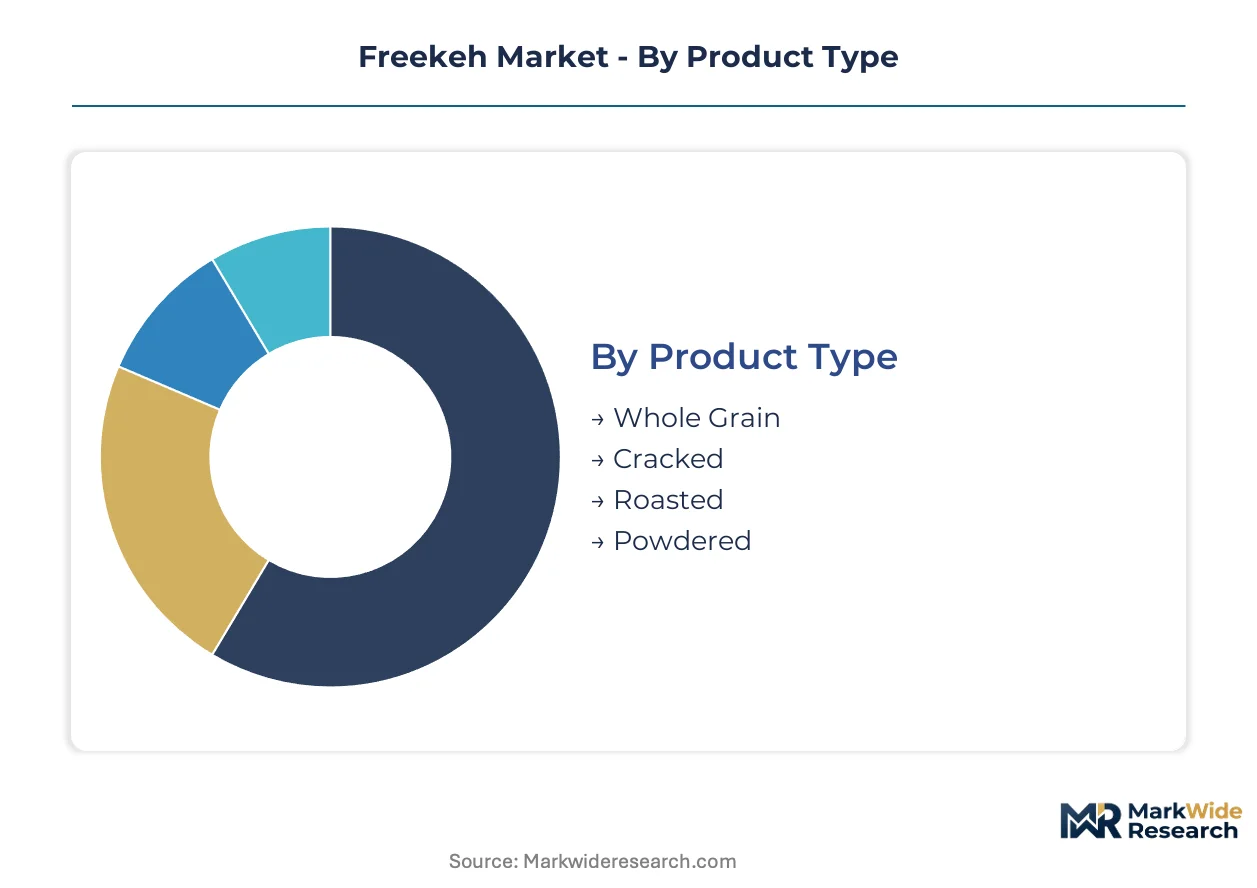
Freekeh's position as a roasted grain specialty creates distinct certification requirements across product formats, while distribution architecture determines which buyer segments processors can profitably serve. Understanding how organic labeling, food safety thresholds, and channel economics intersect with each segment enables targeted resource allocation.
Product Type:
USDA National Organic Program and EFSA mycotoxin protocols apply differentially across formats, with whole grain facing simpler traceability while cracked and powdered variants trigger extended residue testing timelines.
- Whole Grain:Minimal processing preserves the intact roasted wheat berry, delivering the full fiber content and chewy texture that anchors clean-label positioning in German and UK health food retail. Demand concentrates among meal-kit services and natural grocery chains seeking single-ingredient ancient grain credentials, though fire-roasting skill scarcity in mechanized facilities creates quality consistency gaps.
- Cracked:Mechanical fracturing reduces cooking time to fifteen minutes, enabling direct substitution for bulgur and instant quinoa in convenience-oriented urban households. Quick-cooking formulations absorb disproportionate compliance costs as they target price-sensitive institutional buyers under tightening EFSA mycotoxin thresholds.
- Roasted:Intensive fire-roasting produces deeper Maillard compounds for flavor-forward applications in premium restaurant and food manufacturing channels.
- Powdered:Fine milling creates gluten-free flour alternatives for bakery and breakfast cereal formulations, requiring additional allergen segregation protocols.
Leading the category by volume: Whole Grain. Growing fastest: Cracked.
End User:
Procurement patterns diverge sharply between price-sensitive institutional buyers and premium-positioned direct-to-consumer channels, with health food stores commanding the strictest organic certification documentation.
- Households:Subscription-based replenishment is displacing periodic bulk purchasing among urban health-conscious consumers in London and Berlin, where meal-kit services feature freekeh as a quinoa alternative in weekly recipe rotations.
- Restaurants:Chef-driven demand for smoky flavor profiles and protein-forward grain bowls supports premium positioning, though single-origin supply concentration in Palestinian and Jordanian export corridors creates shipment reliability risk.
- Food Manufacturers:Plant-based protein product developers substitute freekeh for refined grains, leveraging fifteen-plus percent protein content and distinctive Maillard compounds in clean-label formulations.
- Health Food Stores:dm-drogerie markt and Alnatura in Germany are expanding SKU counts for whole grain and cracked variants, requiring processors to invest in lot-tracking systems that differentiate premium-positioned products.
Highest margin concentration: Health Food Stores. Steepest expansion trajectory: Food Manufacturers.
Distribution Channel:
Channel selection determines margin capture versus volume scale, with online infrastructure enabling subscription economics that bypass traditional specialty shop intermediaries.
- Online Stores:Direct-to-consumer models capture recurring revenue through meal-kit partnerships, compressing supply chains and repositioning freekeh from ethnic specialty to mainstream health ingredient.
- Supermarkets:Mass retail placement requires price competitiveness with Peruvian and Bolivian quinoa suppliers who match protein positioning while offering established supply chain infrastructure.
- Specialty Shops:Independent natural grocery channels sustain premium pricing for Palestinian-origin storytelling and direct cooperative relationships.
- Farmers' Markets:Regional millers in Portland and Melbourne leverage small-batch electric roasting units to enable farm-to-package traceability claims that command retail premiums.
Dominant volume channel: Supermarkets. Climbing the fastest: Online Stores.
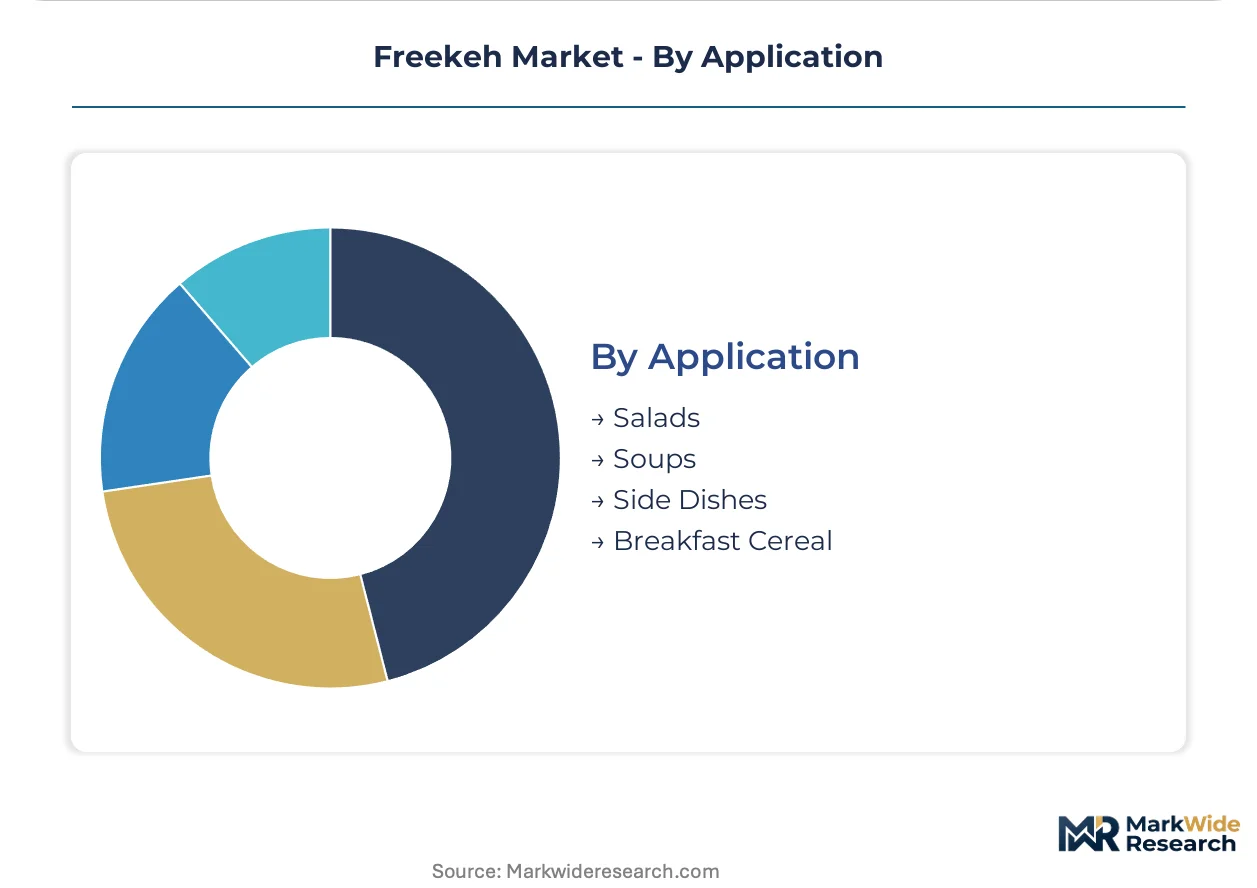
Application:
Application versatility drives repeat purchase frequency, with breakfast cereal and side dish formats creating habitual consumption patterns that salads and soups cannot match.
- Salads:Cold preparation showcases freekeh's chewy texture and smoky flavor, anchoring Mediterranean and Middle Eastern menu positioning in UK and German food service.
- Soups:Broth-absorbing characteristics suit institutional food manufacturing, though durum wheat input volatility from climate stress on Australian and Levantine growing regions compresses margins for processors locked into long-term grower contracts.
- Side Dishes:Pilaf and grain bowl applications dominate household consumption, with convenience-oriented cracked variants capturing urban time-constrained demand.
- Breakfast Cereal:Hot cereal and granola inclusions are gaining share fastest as processors develop quick-cooking formulations targeting the convenience gap between overnight oats and instant grains.
Highest volume application: Side Dishes. Expanding most quickly: Breakfast Cereal.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Levantine green wheat cultivation anchors freekeh's raw-material geography, with fire-roasting expertise concentrated in Palestinian and Jordanian processing cooperatives that supply European and North American health food channels.
Germany
dm-drogerie markt and Alnatura are expanding SKU counts for whole grain and cracked variants across their retail networks. EFSA mycotoxin thresholds enforce lot-level aflatoxin documentation for all roasted grain imports. Berlin anchors demand concentration, with meal-kit services featuring freekeh as a quinoa alternative in weekly recipe rotations.
United States
USDA National Organic Program certification requirements are tightening supply chain traceability for ancient grains sold through natural grocery channels. FDA food safety frameworks apply to residue testing in roasted grain products. Portland-based regional millers are adopting small-batch electric roasting units to enable farm-to-package traceability claims.
United Kingdom
Health food retailers are increasing shelf space for ancient grains as consumer demand shifts toward clean-label formulations. EU organic labeling standards govern import documentation for Levantine-origin products. London concentrates subscription-based replenishment demand, where urban health-conscious consumers bypass traditional specialty shop intermediaries.
Australia
Climate stress on durum wheat growing regions is compressing margins for processors locked into long-term grower contracts. The country's national food safety regulator enforces mycotoxin thresholds parallel to EFSA protocols. Melbourne-based operations are scaling controlled roasting infrastructure to meet clean-label demand from North American exporters.
Canada
Health Canada standards for organic grain labeling align with USDA equivalency agreements, facilitating cross-border trade in certified freekeh products. Health food retail chains in Toronto and Vancouver are expanding ancient grain offerings. Prairie province durum wheat growers are exploring green-harvest contracts for fire-roasting processors seeking North American supply diversification.
Freekeh Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer subscription models and specialty origin storytelling. The vendor base clusters around three distinct strategic positions: Australian-origin suppliers with controlled roasting infrastructure, Levantine processors leveraging cooperative farming relationships, and North American millers integrating regional distribution networks. Dominant competitive moves include capacity expansion in fire-roasting facilities and strategic partnerships with meal-kit services to bypass traditional retail intermediaries.
Within the origin-storytelling tier, Canaan Freekeh Foods and Greenwheat Freekeh Pty Ltd exemplify divergent geographic anchoring strategies. Bob's Red Mill Natural Foods occupies a position representing North American milling integration, with Portland-based operations sustaining branded distribution across natural grocery channels. These three entities collectively illustrate how competitive positioning in freekeh production hinges on controlling either roasting infrastructure, farming cooperative relationships, or downstream distribution networks.
| Leading Market Players |
|---|
| Bocon SRL |
| Leathams Ltd |
| Bob's Red Mill Natural Foods |
| First Quality Foods |
| Freekehlicious |
| Canaan Freekeh Foods |
| Freekeh Foods Inc |
| Lotus Foods |
| Greenwheat Freekeh Pty Ltd |
| Others |
Supply Flow & Price Mechanics
Fire-roasting expertise concentrated in Palestinian and Jordanian processing cooperatives creates labor-cost differentials that widen pricing-tier spreads between artisanal-origin and mechanized-production freekeh. These skill premiums compound with organic certification timelines to stratify end-product positioning across health food retail channels.
Pricing Analysis
After-sales service bundling separates contract-based long-term offtake agreements from spot-market transactions, with subscription models capturing recurring revenue through meal-kit partnerships. Price differentiation centers on USDA organic certification tier and single-origin provenance documentation, with Palestinian-origin storytelling commanding retail premiums. Pricing pressure stems from Peruvian and Bolivian quinoa suppliers matching protein positioning while offering established supply chain infrastructure. Institutional buyers in food manufacturing exhibit highest price sensitivity; health food stores demonstrate lowest sensitivity due to clean-label credential requirements.
Supply Chain Analysis
Durum wheat input rests on Australian and Levantine growing regions, with green-harvest contracting tethered to seasonal climate patterns and long-term grower relationships. Fire-roasting infrastructure and controlled roasting equipment feed from specialized machinery suppliers in Germany and Italy. Single-source vulnerability concentrates in Palestinian and Jordanian export corridors where regional political stability shapes shipment reliability. Distribution runs through health food retail intermediaries in Germany and the United Kingdom, with online direct-to-consumer channels bypassing traditional specialty shop networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Freekeh production is transitioning from traditional fire-roasting cooperatives to mechanized electric roasting units, with small-batch technology replacing legacy centralized facilities in Portland and Melbourne.
For Market Incumbents: Extend backward integration into green wheat contracting to secure durum supply against climate volatility in Australian growing regions. Add controlled roasting capacity in North American facilities to reduce trans-Pacific logistics exposure and capture USDA organic certification premiums. Quinoa substitution threats from established Andean suppliers demand differentiated positioning through Maillard flavor compound marketing. For New Entrants and Emerging Players: Meal-kit services represent the most penetrable channel partner type for bypassing entrenched retail intermediaries. Target subscription-based replenishment models in London and Berlin where urban health-conscious consumers seek quinoa alternatives. White-space exists in quick-cooking cracked segments for time-constrained households; enter through direct-to-consumer platforms featuring farm-to-package traceability claims. For Investors and Strategic Acquirers: Re-rating potential sits with Australian-origin suppliers given controlled roasting infrastructure scarcity and North American export demand acceleration. Long-term viability favors entities with mechanized production capabilities and organic certification pipelines across the five-to-ten year horizon. Watch EU organic equivalency agreement determinations as the inflection indicator for competitive sourcing option expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Mechanized Roasting Capacity Expansion | Electric roasting units in Portland and Melbourne enable farm-to-package traceability claims commanding retail premiums. |
| Direct-to-Consumer Channel Launch | Subscription models bypass dm-drogerie markt and Alnatura intermediaries to capture margin and build recurring revenue. |
| USDA Organic Certification Investment | Lot-tracking systems differentiate premium-positioned products under tightening National Organic Program traceability requirements. |
| Backward Integration into Grower Contracts | Long-term green-harvest agreements with Australian and Levantine farmers secure durum supply against climate stress. |
| Meal-Kit Service Partnership | Weekly recipe rotations featuring freekeh as quinoa alternative anchor habitual consumption in London and Berlin households. |
Methodological Framework
Multi-period observation of SKU expansion rates at German health food retailers anchored the trend analysis, supplemented by interviews with fire-roasting equipment manufacturers, organic certification auditors, and health food store category buyers. Secondary validation drew from USDA National Organic Program filings, EFSA mycotoxin threshold documentation, Australian Bureau of Agricultural and Resource Economics trade data, and customs records for Levantine-origin grain exports. Bottom-up volume estimates from processor capacity triangulated against top-down demand projections from retail channel audits.
Input-output matrices modeled freekeh flows across product type, end user, distribution channel, and application dimensions over the projection horizon. CAGRs were derived from segmented growth trajectory analysis incorporating organic certification adoption curves, meal-kit partnership expansion rates, and climate-adjusted durum wheat yield assumptions. Industry-specific forecast inputs included fire-roasting skill scarcity indices and EU organic equivalency agreement probability assessments.
Several conditions sit outside the modeled scope, including abrupt regulatory discontinuities in trans-Atlantic organic equivalency recognition and acute geopolitical disruptions to Levantine export corridors. Forecasts reflect documented assumptions regarding mechanized roasting technology adoption timelines and consumer substitution elasticity between ancient grains. A small set of named triggers warrants ongoing watch: EFSA mycotoxin threshold revisions, Australian drought severity indices, and German health food retailer SKU rationalization cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Global Gluten-Free Breakfast Cereals Market
Packaged Foods
Instant Ramen Market
Packaged Foods
South America Canned Fruits Market
Packaged Foods
United Kingdom Food Spreads Market
Packaged Foods
Canned Tropical Fruit Market
Packaged Foods
North America Packaged Salad Market
Packaged Foods
North America Chewing Gum Market
Packaged Foods
Chestnut Flour Market
Packaged Foods
North America Breakfast Cereals Market
Packaged Foods
India Packaged Food Products Market
Packaged Foods
Cookie Butter Spread Market
Packaged Foods
Iran Breakfast Cereals Market
Packaged Foods
Prepared Flour Mixes Market
Packaged Foods
Packaged Vegan Foods Market
Packaged Foods
South America Breakfast Cereals Market
Packaged Foods
Instant Rice Market