
 Wet Pet Food Market | 2026-2036
Wet Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Wet Pet Food Market Analysis
High-pressure processing and cold-fill aseptic techniques is tilting wet pet food manufacturing away from traditional retort methods toward nutrient-preserving alternatives. Mars Petcare leverages its global manufacturing scale to standardize these technologies across multiple production facilities. Nestlé Purina PetCare anchors its competitive position through deep R&D investment in palatability science and formulation stability. Champion Petfoods specializes in limited-ingredient wet recipes that command premium positioning in specialty retail channels.
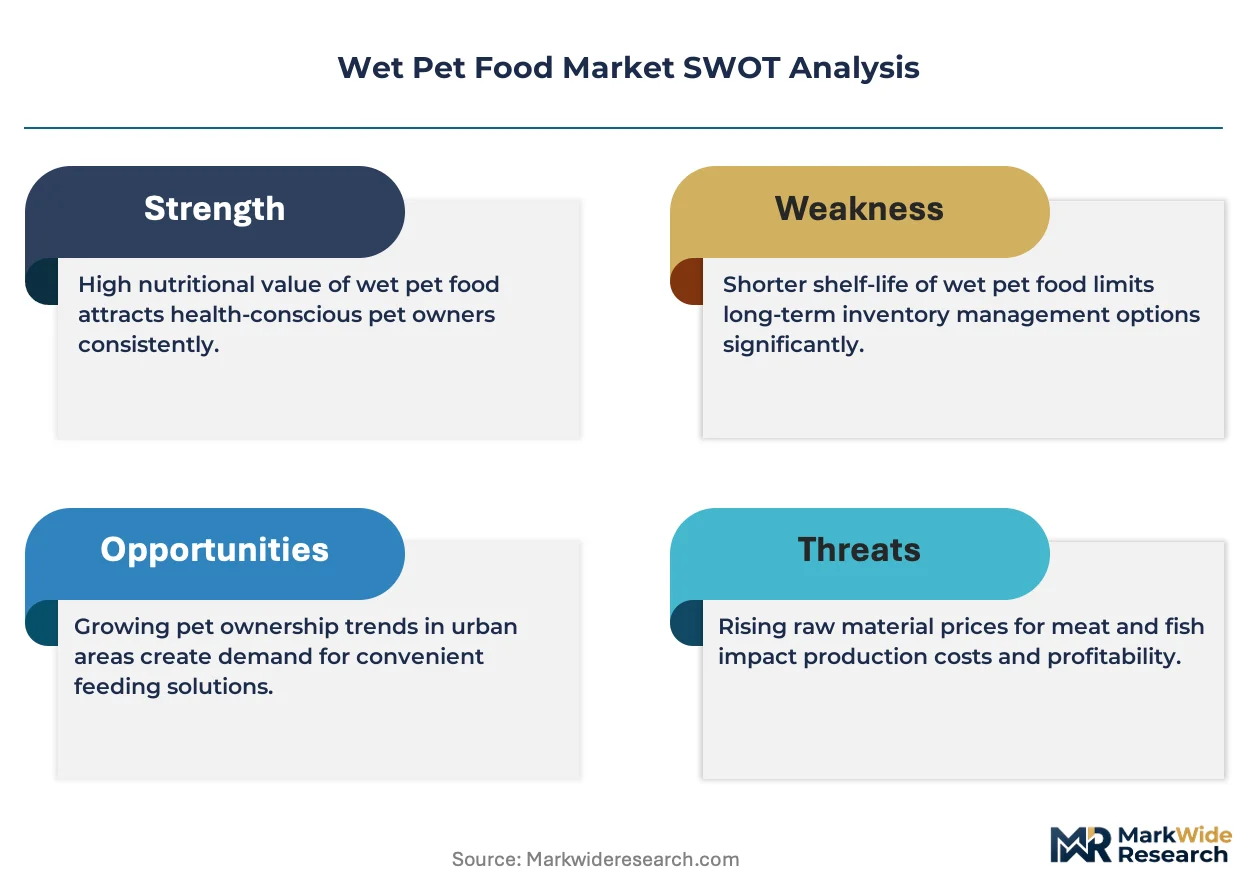
Wet pet food comprises moisture-rich formulations typically containing 60-85% water content, manufactured through either retort sterilization or aseptic processing to achieve commercial sterility while maintaining nutritional bioavailability; its primary purpose is to deliver complete nutrition with enhanced hydration and palatability for companion animals. Canned food remains the dominant format by volume, though pouch food captures the fastest growth trajectory due to convenience and portion-control advantages among urban pet owners. Grain-free ingredient positioning continues to differentiate premium offerings, while the veterinarian distribution channel concentrates margin pools through prescription and therapeutic wet diets.
The FDA's Food Safety Modernization Act and the Association of American Feed Control Officials nutrient profiles collectively govern ingredient sourcing, labeling accuracy, and pathogen control across wet pet food production. State-level feed regulatory programs in California and Texas add supplemental inspection layers that shape regional market access requirements. Stakeholders must monitor evolving AAFCO guidelines on novel proteins and the potential harmonization of state enforcement standards that could reshape compliance costs and competitive barriers.
Market Dynamics
High-pressure processing is collapsing traditional retort sterilization timelines while FDA safety mandates force simultaneous capital reinvestment across wet pet food manufacturing networks. This dual pressure compresses margins for mid-tier producers unable to absorb technology transition costs.
Growth Catalysts
- Premiumization among dog owners:Pet humanization trends drive sustained demand for moisture-rich formulations with elevated protein content and novel ingredient positioning.
- FDA Food Safety Modernization Act:Pathogen control mandates accelerate facility upgrades that favor scaled manufacturers with compliance infrastructure already in place.
- Urban household concentration:Smaller living spaces and single-pet ownership patterns in metropolitan United States clusters favor portion-controlled pouch formats over bulk canned alternatives.
Market Restraints
- Aluminum and steel input volatility:Can packaging costs fluctuate with commodity metal markets, squeezing gross margins for producers lacking long-term supplier contracts.
- Midwestern rendering facility concentration:Protein meal supply chains cluster around Illinois and Iowa processing hubs, creating geographic vulnerability to regional disruption.
- Retort equipment technical limitation:Legacy sterilization systems cannot accommodate high-moisture fresh recipes without nutrient degradation, trapping conventional producers in commodity positioning.
Strategic Opportunities
- Veterinary prescription channel expansion:Therapeutic wet diets for renal, diabetic, and gastrointestinal conditions command margin premiums through clinic-exclusive distribution.
- Cold-chain direct-to-consumer fulfillment:Refrigerated subscription models bypass retail slotting fees while capturing recurring revenue from convenience-seeking pet owners.
- EU Green Deal packaging mandates:Recyclable mono-material pouch requirements create first-mover advantage for manufacturers with sustainable format capabilities.
Industry Challenges
- Food safety microbiologist scarcity:Specialized talent for aseptic processing validation and environmental monitoring commands premium compensation in competitive labor markets.
- AAFCO novel protein approval timelines:Insect and cultivated meat ingredient petitions face multi-year review cycles, delaying product pipeline commercialization.
- Legacy ERP integration friction:Track-and-trace compliance systems require costly middleware to connect with decades-old manufacturing execution platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wet Pet Food Market |
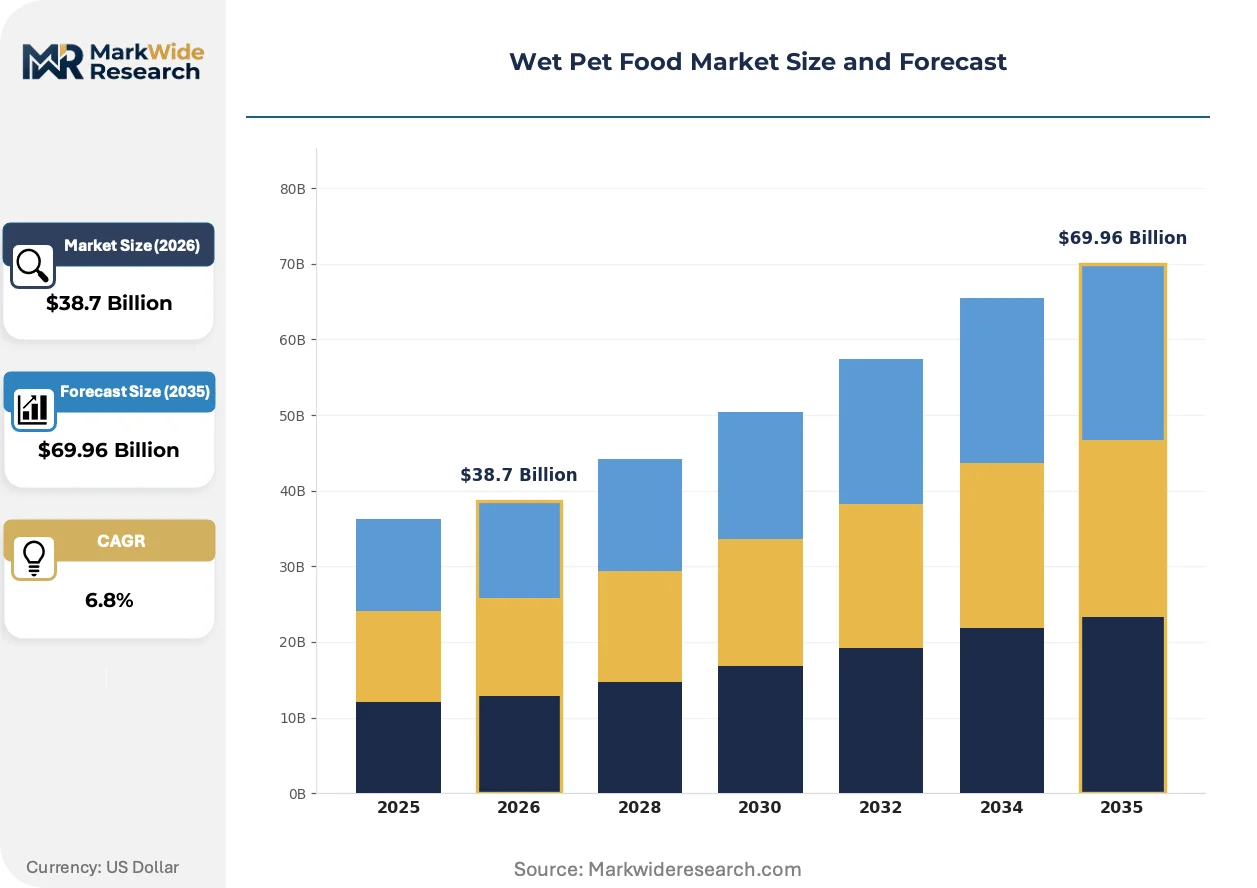
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned Food, Pouch Food, Tub Food, Stew Ingredient Type: Meat, Grain-Free, Vegetarian, Seafood End User: Dog Owners, Cat Owners, Multi-Pet Households, Shelters Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Veterinarians |
| Companies Covered | The J.M. Smucker Company, Blue Buffalo, Mars Petcare, WellPet, Spectrum Brands Holdings, Nestlé Purina PetCare, General Mills, Champion Petfoods, Hill's Pet Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wet Pet Food Market Emerging Trajectories
Processing technology convergence and regulatory packaging mandates are actively restructuring competitive advantage in wet pet food manufacturing. These forces reward capital-intensive innovators while pressuring asset-light competitors.
High-pressure processing is collapsing the nutrient degradation trade-off that previously forced manufacturers to choose between shelf stability and bioavailability preservation. Premium and super-premium brands are adopting HPP systems at accelerating rates, enabling fresh-format positioning without frozen distribution requirements. This technology compression eliminates the historical barrier between refrigerated pet food startups and mass-market shelf-stable incumbents.
REACH chemical restrictions and EU packaging waste directives are forcing reformulation of can linings and adhesive compounds across European manufacturing facilities. Bisphenol-A elimination mandates require coating substitutions that extend production validation cycles by 12-18 months. Wet pet food exporters to Germany, France, and Netherlands must now maintain dual specification streams or abandon European market access entirely.
Veterinary channel consolidation is compressing the independent clinic landscape into corporate hospital networks with centralized procurement authority. Mars Petcare and Nestlé Purina have established dedicated field sales organizations targeting VCA, Banfield, and BluePearl purchasing committees with exclusive therapeutic formulations. This buyer concentration shift is most advanced in United States metropolitan corridors where private practice density has fallen below sustainable thresholds.
Wet Pet Food Market Segmentation
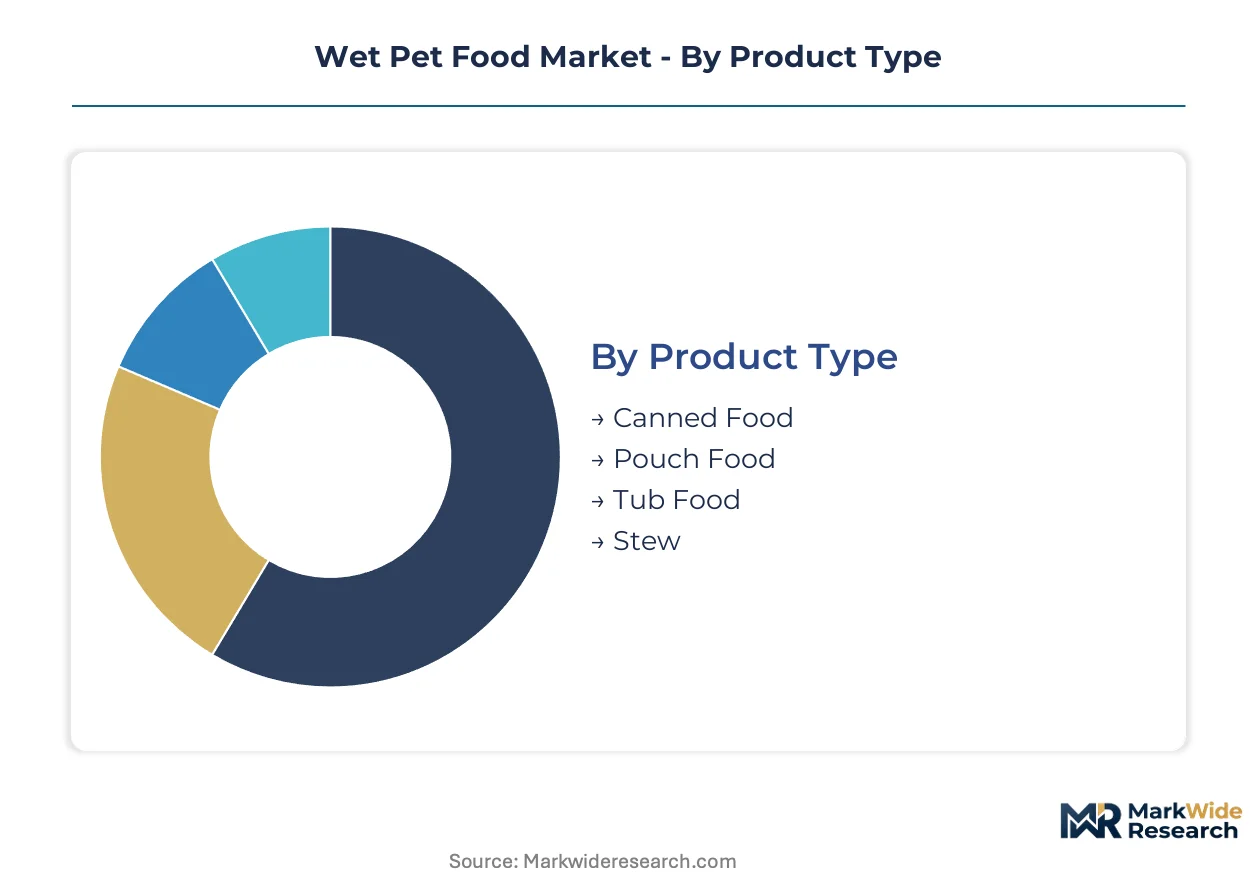
Wet pet food segmentation reveals how packaging format, ingredient positioning, and channel access shape margin capture across distinct consumer clusters. Each dimension carries different regulatory exposure and capital intensity requirements.
Product Type:
Cost tier differentiation separates commodity shelf-stable formats from premium fresh-positioned alternatives requiring specialized processing equipment.
- Canned Food:Aluminum and steel container formats dominate volume throughput in mass retail channels. United States supermarkets and club stores concentrate procurement for this legacy format, though metal input volatility compresses margins for producers lacking long-term supplier contracts.
- Pouch Food:Flexible mono-material packaging enables portion-controlled serving sizes with reduced storage footprint. Urban United States households in metropolitan corridors favor this format for single-pet ownership patterns, driving the steepest expansion trajectory across wet pet food packaging.
- Tub Food:Refrigerated plastic containers support fresh-format positioning with shorter shelf life requirements. Cold-chain distribution networks in California and Texas metropolitan clusters sustain regional availability.
- Stew:Chunk-in-gravy texture formulations target palatability-sensitive pets with visible ingredient pieces. Specialty pet retailers merchandise this format alongside premium kibble for mixed-feeding households.
Canned food commands the established base. The steepest expansion runs through pouch food.
Ingredient Type:
Application-specific nutritional positioning determines regulatory scrutiny levels and veterinary endorsement potential.
- Meat:Traditional animal protein formulations from chicken, beef, and pork sources anchor mainstream wet pet food production. AAFCO nutrient profile compliance remains straightforward for these established ingredients.
- Grain-Free:Legume and potato starch substitutions address digestive sensitivity concerns among premium-seeking dog owners. FDA investigation into canine dilated cardiomyopathy associations has intensified formulation documentation requirements for this positioning.
- Seafood:Tuna, salmon, and whitefish recipes deliver omega-3 fatty acid content for coat and joint health claims. Cat owners demonstrate particular concentration for this ingredient category in coastal United States markets.
- Vegetarian:Plant-protein and synthetic amino acid formulations serve niche ethical positioning and veterinary-prescribed elimination diets. Limited commercial scale constrains manufacturer participation.
Meat-based recipes command the established base. Grain-free positioning shows the steepest regulatory-influenced volatility.
End User:
Customer type segmentation aligns product development with species-specific palatability science and household composition patterns.
- Dog Owners:Larger portion sizes and chewable texture requirements drive formulation differences from feline alternatives. Premiumization trends concentrate most intensely among this segment, with moisture-rich diets supporting hydration in larger breeds.
- Cat Owners:Obligate carnivore nutritional requirements mandate higher protein density and specific taurine supplementation. United States urban households with single-cat ownership favor portion-controlled formats.
- Multi-Pet Households:Cross-species compatible recipes or bulk purchasing patterns characterize this cluster. Value-oriented positioning dominates relative to single-species premium tiers.
- Shelters:Institutional procurement through municipal contracts and nonprofit networks prioritizes cost efficiency over ingredient differentiation. Volume concentration in Midwestern and Southern United States facilities.
Dog owners command the established base. Cat owners are gaining share fastest in premium wet formats.
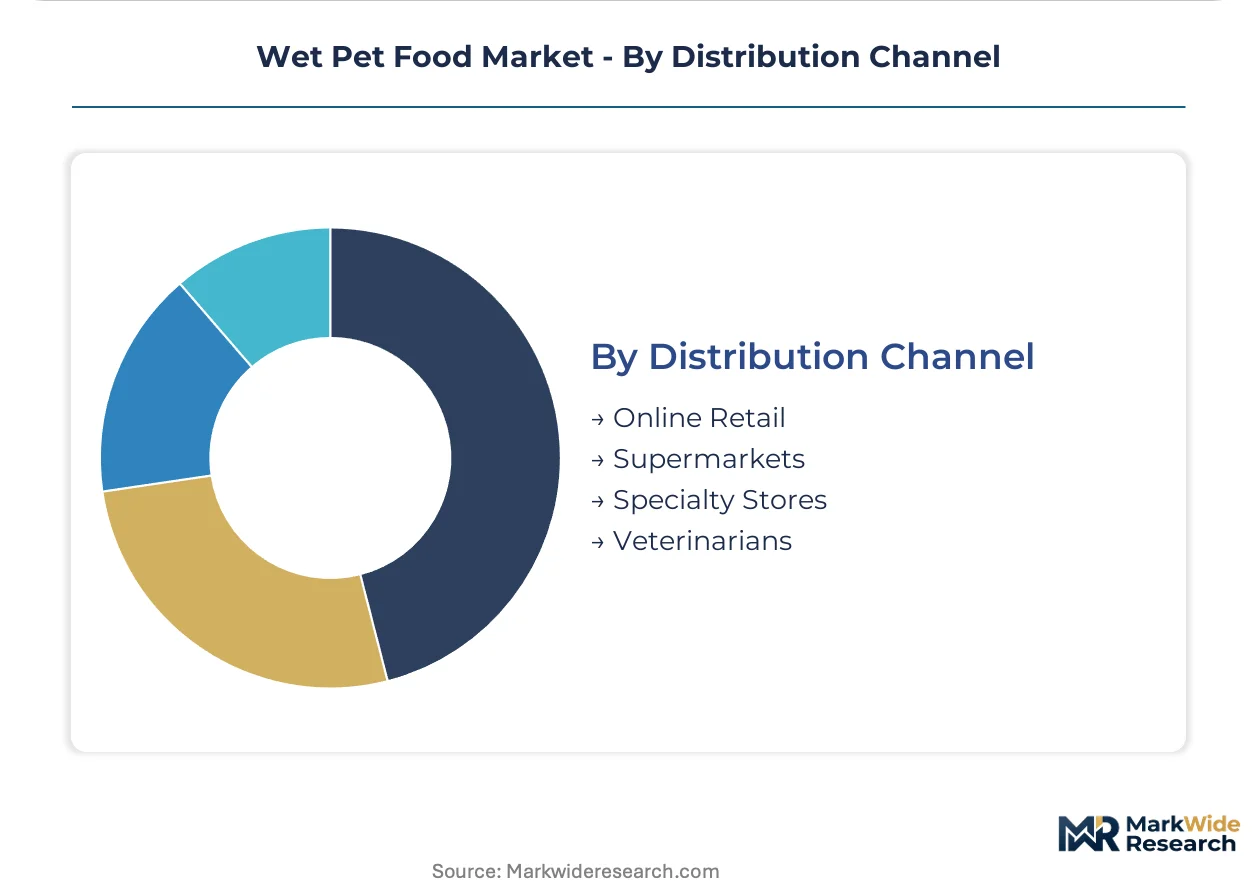
Distribution Channel:
Margin structure and regulatory access permissions vary sharply across channel types, with veterinary exclusivity commanding the highest price realization.
- Veterinarians:Clinic-exclusive therapeutic diets for renal, diabetic, and gastrointestinal conditions require prescription authorization. Mars Petcare and Nestlé Purina field sales organizations target corporate hospital networks with dedicated therapeutic formulations.
- Online Retail:Subscription-based replenishment models bypass retail slotting fees while capturing recurring revenue. Cold-chain direct-to-consumer fulfillment enables fresh-format penetration beyond traditional retail distribution.
- Supermarkets:Mass-market volume concentration for canned and pouch formats with high inventory turnover requirements. Slotting fee structures favor scaled manufacturers with trade promotion budgets.
- Specialty Stores:Independent pet retailers and natural product chains merchandise limited-ingredient and novel protein positioning. Champion Petfoods concentrates distribution through this channel for premium recipe visibility.
Veterinary channels command the established margin base. Online retail is climbing the fastest as subscription models scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium-seeking dog owners concentrate in suburban United States corridors, while urban single-pet households in Western Europe and East Asian metros drive pouch-format adoption. Regulatory divergence across FDA, EFSA, and national feed control offices shapes manufacturing compliance costs.
United States
Suburban dog ownership in Texas and Florida metropolitan clusters sustains bulk canned procurement. The FDA Food Safety Modernization Act mandates pathogen control upgrades that favor scaled manufacturers. Midwestern rendering hubs around Illinois and Iowa anchor protein meal supply chains for national production networks.
Germany
Cat-owning urban households in Berlin and Munich favor portion-controlled wet formats with mono-material packaging. REACH chemical restrictions and EU packaging waste directives force Bisphenol-A elimination from can linings. Bavarian manufacturing facilities now maintain dual specification streams for domestic and export production.
United Kingdom
London and Southeast England concentrate premium wet food demand among single-pet professionals. The Food Standards Agency coordinates with FSAI on cross-border feed safety protocols. Midlands distribution centers handle cold-chain logistics for refrigerated tub formats entering specialty retail.
Japan
Tokyo and Osaka metropolitan cat owners drive single-serve pouch consumption with elevated protein positioning. METI guidelines on pet food labeling enforce strict nutrient declaration standards. Chubu region manufacturing plants specialize in seafood-based formulations for domestic and regional export markets.
Australia
Sydney and Melbourne pet owners sustain demand for grain-free and limited-ingredient wet recipes. TGA-aligned state feed control offices govern therapeutic diet authorization. Queensland rendering facilities supply protein meals to eastern seaboard packaging operations.
Wet Pet Food Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The structure consolidates around multinational consumer goods conglomerates with veterinary distribution arms, while mid-tier specialists occupy premium positioning through ingredient differentiation. Two archetypes dominate: scale-driven mass-market suppliers and limited-recipe premium specialists. Competitive moves center on veterinary channel acquisitions and cold-chain direct-to-consumer infrastructure deployment.
Within the scale-driven tier, Mars Petcare and Nestlé Purina PetCare occupy positions as vertically integrated conglomerates with global manufacturing footprints. Champion Petfoods exemplifies the specialist archetype through premium limited-ingredient positioning. These three anchors represent the competitive spectrum from mass-market volume to super-premium differentiation.
| Leading Market Players |
|---|
| The J.M. Smucker Company |
| Blue Buffalo |
| Mars Petcare |
| WellPet |
| Spectrum Brands Holdings |
| Nestlé Purina PetCare |
| General Mills |
| Champion Petfoods |
| Hill's Pet Nutrition |
| Others |
Supply Flow & Price Mechanics
Midwestern rendering facility concentration around Illinois and Iowa anchors protein meal supply chains, feeding margin pools downstream to veterinary prescription channels and cold-chain direct-to-consumer fulfillment networks that capture recurring revenue premiums.
Pricing Analysis
Cost-plus contracts with aluminum and steel indexation dominate canned format procurement, locking in margin exposure to commodity metal volatility. Three-tier pricing structure across premium, standard, and economy levels separates therapeutic veterinary diets from mass-market shelf-stable and value-positioned institutional formats. Pricing pressure stems from high-pressure processing equipment capital requirements that compress mid-tier producer margins. Shelters and municipal procurement teams exhibit highest price sensitivity; prescription channel buyers demonstrate lowest sensitivity due to clinical endorsement and reimbursement alignment.
Supply Chain Analysis
Export-control restrictions on cold-chain refrigeration technology limit fresh-format equipment flows into select markets, constraining regional production scaling. Protein meal supply concentrates in the United States Midwest and Queensland, Australia; seafood raw materials source from Chubu region, Japan and coastal Chilean fisheries. Aluminum can sheet, flexible mono-material films, and pathogen testing reagents constitute critical input dependencies. Single-source vulnerability runs through Midwestern rendering hub concentration. Distribution runs through corporate veterinary networks, subscription fulfillment centers, and mass retail distribution centers in metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wet pet food markets function as service-attach opportunities where cold-chain subscription replenishment and veterinary therapeutic protocol compliance expand faster than hardware-equivalent product turnover.
For Market Incumbents: Harden cold-chain infrastructure against emerging refrigerated tub format competitors by securing exclusive veterinary clinic network access through corporate hospital procurement committees. Expand backward integration into high-pressure processing equipment manufacturing to lock in technology transition timing. FDA Food Safety Modernization Act compliance infrastructure serves as the defensive lever against mid-tier capital-constrained rivals. For New Entrants and Emerging Players: Establish a beachhead in refrigerated tub formats for metropolitan single-pet households in California and Texas cold-chain clusters. Target grain-free limited-ingredient positioning in specialty retail channels where Champion Petfoods concentration leaves shelf space contested. Deploy direct-to-consumer subscription models with veterinary telehealth partnerships as the go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward cold-chain logistics specialists with captive last-mile refrigerated networks and mono-material pouch manufacturing capabilities. Long-term viability over the medium-term horizon favors assets with FDA-compliant aseptic processing validation and existing veterinary channel relationships. Watch AAFCO novel protein approval timelines as the inflection signal for ingredient pipeline commercialization acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Acquisition | Corporate hospital network access locks in therapeutic diet distribution exclusivity against retail competitors. |
| Cold-Chain Infrastructure Buildout | Refrigerated fulfillment networks enable fresh-format penetration beyond traditional shelf-stable retail constraints. |
| High-Pressure Processing Adoption | Nutrient-preserving sterilization technology collapses the barrier between refrigerated startups and mass-market incumbents. |
| Mono-Material Packaging Transition | EU Green Deal compliance creates first-mover advantage in sustainable pouch formats for German and French export markets. |
| Novel Protein Pipeline Investment | Insect and cultivated meat ingredient petitions position portfolios for post-AAFCO approval commercialization waves. |
Methodological Framework
Operator-level perspectives from wet pet food plant managers, veterinary clinic procurement leads, specialty retail category buyers, and cold-chain logistics coordinators anchored the qualitative base. Secondary validation drew from FDA enforcement reports, AAFCO nutrient profile documentation, USDA rendering facility inspection records, and EU packaging waste directive filings. Bottom-up volume modeling and top-down value triangulation converged on segment-level estimates.
Scenario-bracketing across regulatory compliance cost trajectories and technology adoption curves shaped the analytical framework over the projection horizon. Segmentation dimensions included packaging format, ingredient positioning, species-specific end user, and distribution channel access permissions. CAGRs derived from fitted growth curves against historical volume patterns and elasticity-adjusted price trajectories. Forecast inputs incorporated protein meal commodity price bands and veterinary channel consolidation rates.
Stress conditions across aluminum price volatility, rendering facility disruption events, and novel protein approval delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about FDA enforcement intensity and EU packaging mandate implementation pacing. Material shifts in AAFCO regulatory timelines or cold-chain logistics cost structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Packaged Rice Market
Packaged Foods
Freekeh Market
Packaged Foods
Packaged Food Market
Packaged Foods
Instant Beverage Premix Market
Packaged Foods
Middle East and Africa Energy Bar Market
Packaged Foods
Low Calorie Noodles Market
Packaged Foods
Sugar-Free Biscuits and Cookies Market
Packaged Foods
Europe Ready Meals Market
Packaged Foods
North America Breakfast Cereals Market
Packaged Foods
Canned Goods Market
Packaged Foods
Instant Cereals Market
Packaged Foods
Packaged Corn on the Cob Market
Packaged Foods
Chewing Gum Market
Packaged Foods
South America Pasta and Noodles Market
Packaged Foods
Fat Free Pasta Market
Packaged Foods
UAE Breakfast Cereals Market