
 Canned Soup Market | 2026-2036
Canned Soup Market Size, Share, and Industry Trends Forecast 2026-2036
Canned Soup Market Analysis
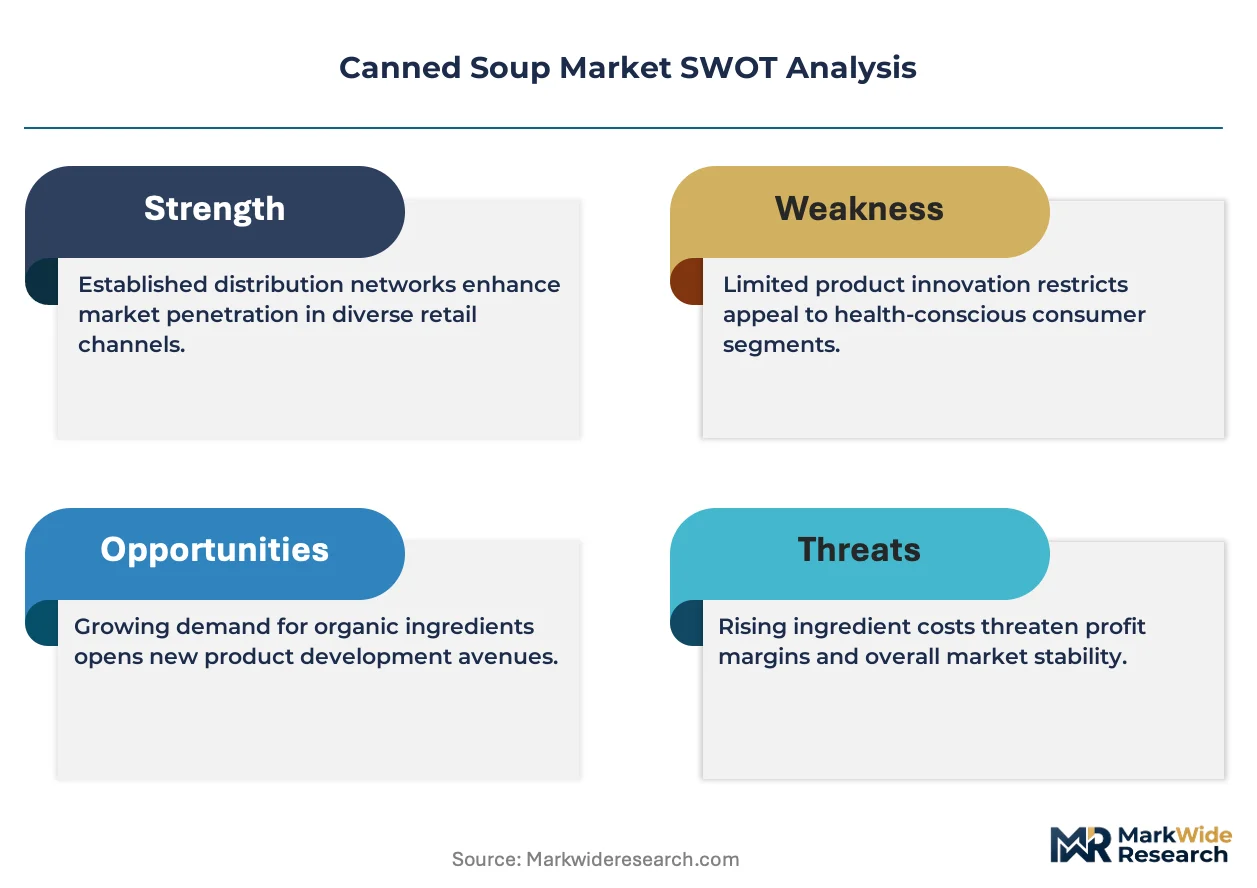
BPA-free linings is pivoting toward polyester-based and oleoresin coatings across the canned soup supply chain, altering cost structures and supplier qualification requirements. Campbell Soup Company leverages its captive can-making operations to control input costs and specification timelines. Conagra Brands sustains a broad private-label and branded portfolio that spans value and premium positioning. Nestlé anchors European supply through specialized retort facilities in France and Portugal.
Canned soup comprises thermally processed, hermetically sealed broths or stews containing vegetables, proteins, or dairy bases, preserved through retort sterilization at temperatures exceeding 121°C to achieve commercial sterility and ambient shelf stability of 24 to 60 months. The primary purpose is to deliver convenient, shelf-stable nourishment for household pantries and institutional food service operations. Tomato soup and cream soup categories carry higher margin profiles due to dairy input complexity and premium positioning, while chicken soup dominates volume through comfort-food familiarity and cross-demographic appeal. Easy open can formats are gaining share against standard cans as aging populations and on-the-go consumption patterns reshape packaging preferences.
The FDA governs acidified and low-acid canned food regulations under 21 CFR Parts 108, 113, and 114, mandating scheduled thermal process filings and facility registrations that create compliance barriers for new entrants. The USDA's Agricultural Marketing Service oversees grade standards for soup ingredients, influencing procurement specifications for tomato and vegetable inputs. State-level extended producer responsibility frameworks in California and Oregon are beginning to impose post-consumer recycling obligations on metal packaging. Stakeholders must monitor whether sodium-target enforcement accelerates reformulation investment or triggers portfolio rationalization toward cleaner-label sub-lines.
Market Dynamics
Retort sterilization technology and sodium-reduction mandates are compressing formulation cycles while BPA-free lining transitions force simultaneous capital redeployment across can-making operations.
Growth Catalysts
- FDA Sodium Targets:The FDA's updated voluntary sodium reduction targets for processed foods are accelerating reformulation investment in cleaner-label sub-lines, creating competitive differentiation through health-positioned SKUs.
- Food Service Procurement:Institutional cafeterias and contract food service operators are expanding ready-to-serve format procurement, pulling volume toward ambient-stable formats with extended holding capacity.
- Easy-Open Packaging:Aging demographics and on-the-go consumption patterns are driving rapid adoption of pull-tab and peel-lid formats, forcing can specification updates across private-label programs.
Market Restraints
- Steel and Aluminum Input Volatility:Tinplate and aluminum coil prices fluctuate with energy costs, compressing margin visibility for processors without captive can-making or long-term supply agreements.
- Retort Facility Concentration:Commercial sterilization capacity clusters in specific manufacturing corridors, creating logistics constraints for regional brands seeking national distribution expansion.
- Clean-Label Substitution:Refrigerated and frozen soup segments positioned around "fresh" perception are capturing premium-positioned consumers despite higher price points and shorter shelf life.
Strategic Opportunities
- Extended Producer Responsibility Tailwinds:California and Oregon post-consumer recycling frameworks are creating first-mover advantages for brands with closed-loop metal packaging partnerships and recycled-content claims.
- Functional Positioning White Space:Protein-fortified and immunity-positioned formulations remain underdeveloped in ambient soup, offering margin expansion beyond traditional comfort-food positioning.
- Direct-to-Institutional Channels:Healthcare and correctional facility procurement platforms are consolidating vendor lists, rewarding suppliers with USDA-grade certification and specialized portion-control formats.
Industry Challenges
- Thermal Process Validation Timelines:FDA 21 CFR Part 113 scheduled process filings require 90-180 day review cycles, delaying new product launches and reformulation rollouts.
- Coating Chemistry Transition:Polyester-based and oleoresin lining qualification demands parallel supply chain validation, straining technical resources at mid-scale processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canned Soup Market |
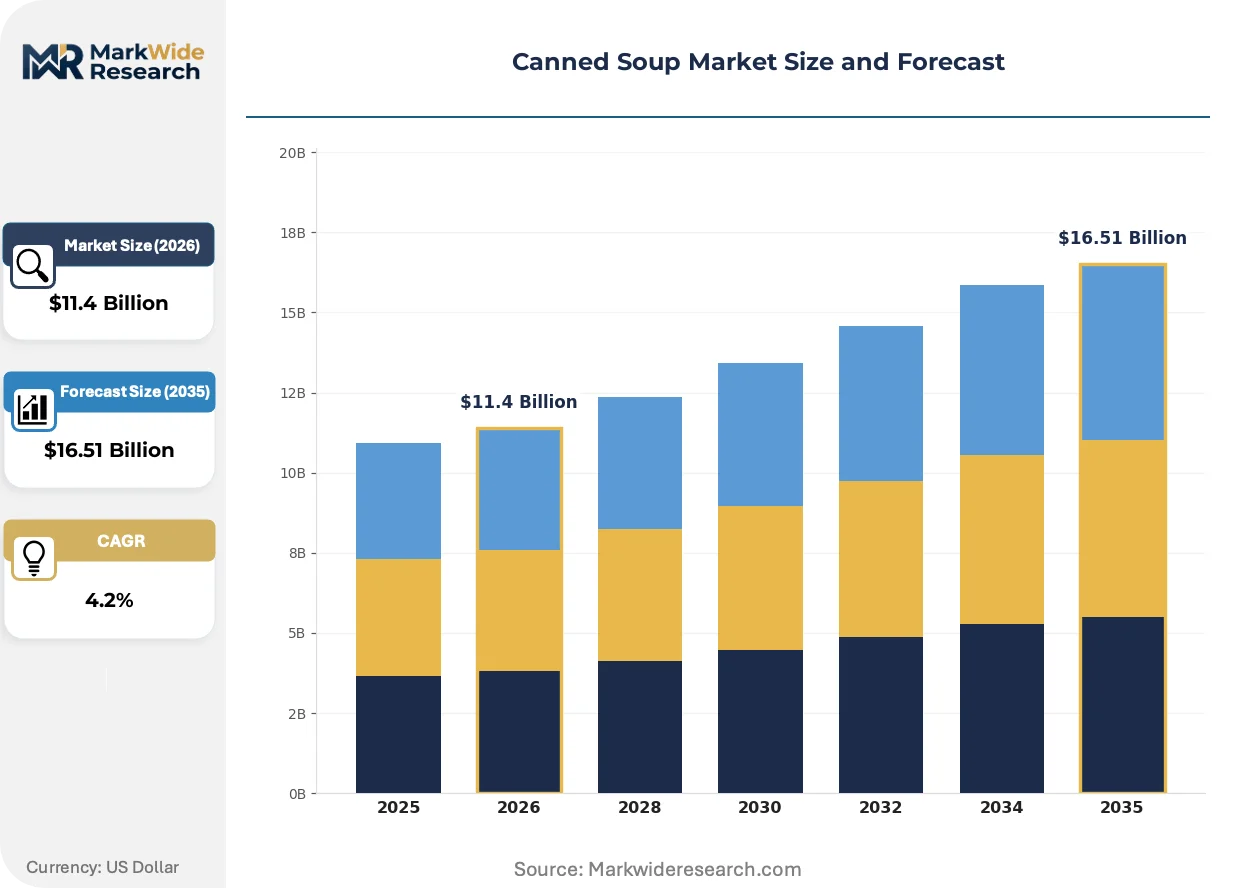
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $16.51 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable Soup, Chicken Soup, Tomato Soup, Cream Soup Packaging Type: Easy Open Can, Standard Can, Pouch, Glass Jar Sales Channel: Supermarket, Online Retail, Convenience Store, Wholesale End User: Households, Restaurants, Cafeterias, Food Service Providers |
| Companies Covered | Conagra Brands, Unilever, Campbell Soup Company, Amy's Kitchen, B&G Foods, General Mills, Kraft Heinz Company, Hain Celestial Group, Nestlé, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canned Soup Market Emerging Trajectories
Formulation science and packaging chemistry are converging to address simultaneous demands for sodium reduction, shelf stability, and material safety, compressing traditional development timelines.
Advanced retort simulation software is rewriting thermal process development by enabling virtual validation of sterilization profiles before physical production runs. Mid-scale processors are adopting these digital twin platforms to reduce FDA filing revision cycles. The technology is compressing time-to-market for reformulated low-sodium lines from 18 months toward 10-12 months.
The FDA's acidified and low-acid canned food regulations under 21 CFR Parts 108, 113, and 114 are tightening facility registration and process filing requirements. Smaller regional brands face compliance cost barriers that favor scaled operators with dedicated regulatory affairs functions. Tomato-based and cream soup categories bear disproportionate scrutiny due to pH borderline classifications and dairy allergen controls.
Pantry-stocking behavior has shifted toward case-quantity purchasing through club and e-commerce channels, displacing single-can impulse buying at conventional grocery. Warehouse retailers are demanding exclusive pack sizes and multi-flavor variety cases, forcing SKU proliferation. This pattern concentrates in United States suburban markets with storage-capable households and subscription-platform adoption.
Canned Soup Market Segmentation
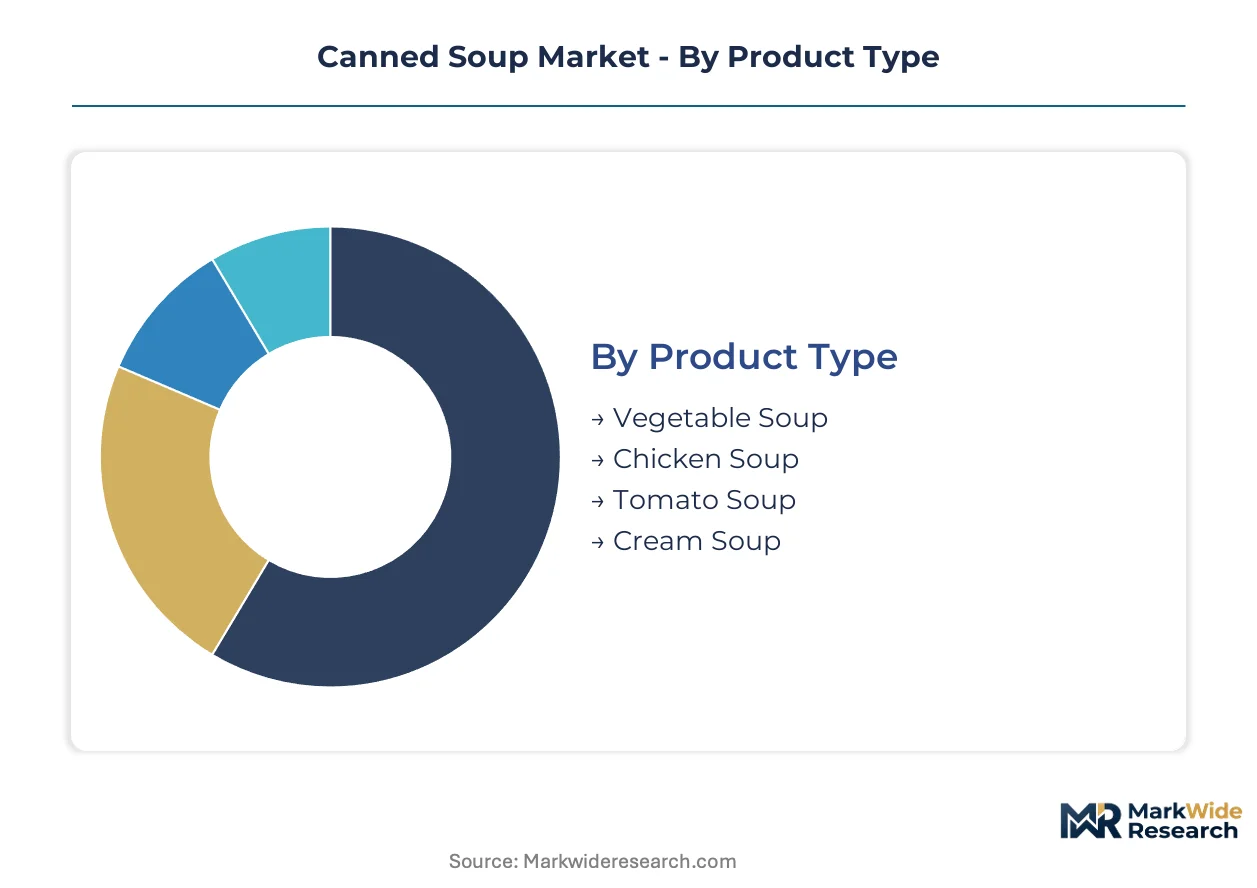
Canned soup segmentation reveals how formulation complexity, packaging chemistry, and channel economics partition margin capture across the supply chain. Distinct thermal processing requirements and sodium-reduction timelines create divergent investment profiles within each category.
Product Type:
Supply concentration clusters around categories with pH stability advantages and established retort validation protocols, leaving reformulation-heavy segments dependent on scaled regulatory affairs functions.
- Chicken Soup:Clear broth formulations with protein particulates achieve commercial sterility through standardized 121°C retort cycles. Demand concentrates in United States suburban households with pantry-stocking behavior, where comfort-food familiarity sustains volume despite sodium-target pressure.
- Tomato Soup:Acidified pH profiles borderline 4.6 threshold trigger heightened FDA 21 CFR Part 114 scrutiny and extended filing timelines. Procurement specifications from institutional cafeterias favor this category for holding stability, though dairy-free positioning limits reformulation complexity relative to cream bases.
- Vegetable Soup:Heterogeneous particulate density creates thermal penetration challenges requiring customized scheduled processes.
- Cream Soup:Dairy emulsion stability demands precise fat-protein ratios and allergen segregation protocols.
Chicken soup absorbs the bulk of installed capacity; cream soup is expanding most quickly as premium positioning justifies reformulation investment.
Packaging Type:
Cost tier stratification separates legacy metal formats from emerging flexible alternatives, with coating chemistry transitions forcing parallel capital deployment across specification tiers.
- Easy Open Can:Pull-tab and peel-lid formats incorporate scored aluminum or steel ends with polyester-based lining systems. Aging demographics in United States markets drive specification updates, while on-the-go consumption patterns pull adoption through convenience store channels.
- Standard Can:Conventional two-piece or three-piece tinplate construction with oleoresin or epoxy-phenolic linings retains cost advantage for club-store case packs. Volume concentrates in private-label programs where specification stability outweighs premium format investment.
- Pouch:Retortable flexible films enable microwave-ready positioning with reduced shipping cube.
- Glass Jar:Premium shelf presence supports artisan and organic sub-lines despite breakage logistics and weight penalties.
Standard can formats retain the majority of production throughput; easy open configurations are climbing the fastest as retailer specifications harden.
Sales Channel:
Channel economics reshape pack size architecture and flavor variety requirements, with consolidation trends rewarding suppliers capable of exclusive SKU development.
- Supermarket:Conventional grocery maintains single-can and multi-pack facings with promotional velocity dependence. United States suburban markets with storage-capable households sustain case-quantity purchasing, though club-channel encroachment compresses traditional shelf space.
- Online Retail:Subscription-platform adoption and direct-to-door logistics favor variety-case configurations with extended shelf-life verification. Fulfillment center inventory turns demand packaging optimized for parcel shipping durability.
- Convenience Store:Grab-and-go occasions prioritize single-serve easy-open formats with immediate consumption positioning.
- Wholesale:Food service and institutional procurement platforms consolidate vendor lists around USDA-grade certification and portion-control specifications.
Supermarket channels anchor current volume; online retail is gaining share fastest as pantry-stocking behavior digitizes.
End User:
Customer type segmentation exposes divergent specification tolerance, with institutional buyers demanding certified processes and households responding to health-positioned claims.
- Households:Pantry-stocking behavior in United States markets drives case-quantity purchasing through club and e-commerce channels. Sodium-reduction targets and clean-label claims influence brand switching, though comfort-food loyalty sustains core SKUs.
- Food Service Providers:Contract operators and institutional cafeterias expand ready-to-serve procurement with extended holding capacity requirements. USDA-grade certification and specialized portion-control formats create qualification barriers favoring scaled suppliers.
- Restaurants:Limited-service operators use ambient soup as back-of-house labor reduction.
- Cafeterias:Healthcare and correctional facilities consolidate vendor lists around nutritional compliance documentation.
Household consumption absorbs the bulk of unit volume; food service providers are expanding most quickly as institutional procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States households drive the majority of global canned soup consumption through pantry-stocking behavior and club-channel case purchasing. Suburban storage-capable demographics sustain volume concentration despite sodium-reduction regulatory pressure from the FDA.
United States
Pantry-stocking behavior and private-label expansion shape volume trends across suburban markets with storage-capable households. The FDA's updated sodium reduction targets under 21 CFR Parts 108, 113, and 114 mandate scheduled thermal process filings that create compliance barriers. Chicago-Naperville and Camden, New Jersey host major retort sterilization corridors where processors deploy advanced simulation software to compress formulation cycles.
Canada
Health-positioned clean-label claims influence brand switching among aging demographics seeking easy-open packaging formats. Health Canada and the PMRA oversee food safety standards for processed soup products with emphasis on allergen controls. Toronto-Oshawa corridor concentration supports national distribution logistics for both branded and private-label programs.
Germany
Functional positioning around protein fortification and immunity claims gains traction among premium-positioned consumers. EFSA and REACH frameworks govern food contact materials and coating chemistry transitions for metal packaging. Baden-Württemberg industrial clusters house specialized can-making operations serving Central European supply chains.
France
Institutional cafeteria procurement expands ready-to-serve format adoption through contract food service consolidation. ANSM and CNIL frameworks intersect with EFSA regulations on processed food labeling and data handling. Nestlé anchors European supply through specialized retort facilities in the Provence-Alpes-Côte d'Azur region.
United Kingdom
Subscription-platform adoption and direct-to-door logistics favor variety-case configurations with extended shelf-life verification. FSA regulations align with EU-derived food safety standards post-Brexit transition periods. London-Southeast distribution hubs concentrate e-commerce fulfillment center inventory turns for parcel-optimized packaging.
Canned Soup Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with scaled operators commanding thermal process validation capabilities that regional brands cannot replicate. The vendor base clusters around three archetypes: diversified packaged food conglomerates with captive can-making, mid-scale processors dependent on toll sterilization networks, and private-label specialists serving retail consolidation. Competitive positioning hardens through M&A activity targeting USDA-grade certification assets and strategic partnerships for BPA-free lining qualification.
Among diversified packaged food conglomerates, Campbell Soup Company and Conagra Brands exemplify scaled operators with captive supply chain control, while Nestlé anchors European positioning through specialized retort infrastructure. These three represent the dominant archetype of vertically integrated processors capable of simultaneous reformulation and packaging chemistry transitions.
| Leading Market Players |
|---|
| Conagra Brands |
| Unilever |
| Campbell Soup Company |
| Amy's Kitchen |
| B&G Foods |
| General Mills |
| Kraft Heinz Company |
| Hain Celestial Group |
| Nestlé |
| Others |
Supply Flow & Price Mechanics
California's extended producer responsibility frameworks gate qualified supply and premium-tier pricing access by mandating closed-loop metal packaging partnerships that only scaled operators can satisfy. The FDA's sodium reduction targets simultaneously force reformulation investment that separates premium-positioned SKUs from commodity broths.
Pricing Analysis
Volume concentrates in standard-can chicken soup SKUs with thin margins, while cream and tomato categories capture premium positioning through dairy complexity and pH-borderline regulatory scrutiny. Price differentiation rests on sodium-reduction certification and easy-open packaging specification, with private-label programs showing highest price sensitivity and institutional procurement demonstrating specification tolerance. Pricing pressure stems from steel and aluminum coil volatility, compressing margin visibility for processors lacking captive can-making or long-term supply agreements.
Supply Chain Analysis
Tinplate and aluminum coil supply rests on integrated steel producers in the United States, Germany, and Japan, with polyester-based and oleoresin lining chemistry transitioning simultaneously across specification tiers. Raw material dependencies center on retort sterilization equipment, BPA-free coating systems, and USDA-grade certified vegetable inputs. Supply chain risk concentrates in retort facility clustering along the Chicago-Naperville and Camden corridors, creating single-source vulnerability for regional brands seeking national expansion. Distribution runs through club-store case packs, e-commerce variety configurations, and institutional procurement platforms with divergent pack size architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retort sterilization capacity constraints prop pricing power by limiting qualified supply for low-acid canned food compliance, creating a supply-constrained market structure favoring scaled operators with dedicated regulatory affairs functions.
For Market Incumbents: Anchor capacity leadership by securing USDA-grade certification assets in healthcare and correctional facility procurement platforms, while accelerating BPA-free lining qualification through oleoresin and polyester-based coating partnerships to preempt regulatory displacement. Defend against clean-label refrigerated substitutes by expanding functional positioning around protein fortification and immunity claims that justify premium shelf placement. For New Entrants and Emerging Players: FDA 21 CFR Part 113 scheduled process filing backlogs in the United States open a window for specialized contract sterilization services targeting mid-scale processors lacking captive retort infrastructure. Target direct-to-institutional channels in consolidating healthcare procurement with USDA-grade compliance documentation, while leveraging advanced retort simulation software to compress thermal process validation timelines below 90-day review cycles. For Investors and Strategic Acquirers: Accelerated M&A activity around BPA-free lining qualification assets is the leading indicator that coating chemistry transition timelines are becoming a binding constraint on output expansion. Long-term viability favors vertically integrated processors with captive can-making and specialized retort facilities in France, Portugal, or the United States Midwest corridor. Watch for sodium-target enforcement acceleration as the signal triggering portfolio rationalization toward cleaner-label sub-lines.| Strategic Initiative | Industry Significance |
|---|---|
| Retort Facility Capacity Expansion | Chicago-Naperville corridor concentration creates logistics advantages for national distribution reach. |
| BPA-Free Lining Qualification Partnership | Oleoresin and polyester-based coating validation separates compliant supply from stranded inventory. |
| USDA-Grade Certification Investment | Healthcare and correctional procurement consolidation rewards certified suppliers with vendor list inclusion. |
| Functional Formulation Development | Protein-fortified and immunity-positioned SKUs capture margin expansion beyond comfort-food positioning. |
| Direct-to-Institutional Channel Buildout | Contract food service operators demand extended holding capacity with specialized portion-control formats. |
Methodological Framework
Multi-period observation of FDA thermal process filing timelines, retort sterilization capacity utilization, and BPA-free lining adoption rates anchored the trend analysis, supplemented by interviews with plant managers at canned soup processors, category buyers at club retailers, regulatory affairs leads at diversified food conglomerates, and procurement officers at institutional food service operators. Secondary validation drew from FDA 21 CFR Part 113 filing databases, USDA Agricultural Marketing Service grade standards, customs records for tinplate and aluminum coil imports, and SEC 10-K disclosures from packaged food manufacturers. Bottom-up volume modeling triangulated against top-down category spend estimates.
Input-output matrix framing connected sodium-reduction reformulation cycles, packaging chemistry transitions, and channel-specific pack size requirements to volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type by thermal processing complexity, packaging format by coating chemistry specification, sales channel by fulfillment logistics, and end user by certification requirement. CAGRs derived from trend extrapolation of pantry-stocking behavior digitization, institutional procurement consolidation, and regulatory compliance cost trajectories.
Caveats apply where FDA enforcement acceleration on sodium targets, retort facility capacity bottlenecks, or steel and aluminum commodity volatility could materially shift the outlook. Forecasts reflect assumptions about regulatory timeline adherence and coating chemistry qualification success rates. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Europe Food Spread Market
Packaged Foods
Freekeh Market
Packaged Foods
Cereal Flakes Market
Packaged Foods
Air-Dried Food Market
Packaged Foods
Sausage Casing Market
Packaged Foods
Global Fruit Spreads Market
Packaged Foods
Prepared Flour Mixes Market
Packaged Foods
Fat Free Pasta Market
Packaged Foods
Dried Honey Market
Packaged Foods
Packaged Vegan Foods Market
Packaged Foods
Impulse Ice-Cream Market
Packaged Foods
China Packaged Food Products Market
Packaged Foods
Singapore Ready-To-Eat Food Market
Packaged Foods
Pastry Fillings Market
Packaged Foods
Morning Goods Market
Packaged Foods
Instant Rice Market