
 North America Chewing Gum Market | 2026-2036
North America Chewing Gum Market Size, Share, and Industry Trends Forecast 2026-2036
North America Chewing Gum Market Insights
Clean-label ingredient technology is narrowing the gap between conventional and functional gum formulations. Mars Incorporated leverages its confectionery R&D infrastructure to sustain innovation in sugar-free bases. Mondelēz International anchors North American distribution through convenience and impulse channels. The PUR Company Inc differentiates via aspartame-free positioning that controls the premium natural segment.
Chewing gum comprises a water-insoluble gum base—typically synthetic elastomers, resins, waxes, and plasticizers—combined with sweeteners, softeners, and flavoring agents, designed for mastication and oral delivery of active ingredients. Functional gum leads product type expansion as caffeine, vitamin, and CBD-infused variants capture margin pools from standard formulations. Sugar-free gum dominates volume through dental health positioning while bubble gum occupies the children's occasion. Online retail grows fastest among sales channels as subscription models for niche functional brands reshape replenishment patterns.
FDA food additive regulations and Health Canada Novel Food assessments govern ingredient approval timelines for functional gum launches, directly conditioning market access speed. The USDA BioPreferred program and EPA sustainable packaging guidelines increasingly influence base material and wrapper sourcing decisions. Stakeholders must monitor evolving state-level THC and hemp-derived cannabinoid rules that could unlock or constrain functional gum innovation pipelines.
Market Dynamics
Convenience store chains are expanding shelf space allocation for functional and sugar-free chewing gum varieties, compressing traditional bubble gum facings while FDA and Health Canada disclosure mandates accelerate reformulation cycles across the supply base.
Growth Catalysts
- Health Canada ingredient disclosure rules:These transparency mandates push manufacturers toward cleaner-label formulations that command retail premiums and expand distribution into pharmacy channels.
- Commuter corridor vending density:High-traffic metropolitan transit hubs in the United States concentrate impulse purchase occasions, sustaining baseline volume for single-serve and multi-pack formats.
- Synthetic elastomer base innovation:Advanced polymer science enables extended flavor release profiles that differentiate functional gum from conventional alternatives on shelf.
Market Restraints
- Petrochemical resin input costs:Gum base formulations depend on synthetic elastomers and petroleum-derived resins, exposing margins to hydrocarbon price volatility without viable bio-based substitutes at scale.
- FDA food additive approval timelines:Novel functional ingredients including cannabinoids and certain vitamin complexes face multi-year safety review queues that delay pipeline commercialization.
- Plasticizer substitution limitations:Technical constraints in matching mouthfeel and chew texture with alternative softening agents restrict rapid clean-label conversion.
Strategic Opportunities
- CBD and hemp-derived cannabinoid rule evolution:State-level regulatory clarifications in the United States could unlock functional gum innovation pipelines currently constrained by legal ambiguity.
- Subscription replenishment models:Direct-to-consumer channels for niche functional brands reshape purchase patterns, capturing recurring revenue outside traditional impulse retail.
- USDA BioPreferred program alignment:Biobased packaging and wrapper sourcing certifications open institutional procurement channels and sustainability-positioned retail placements.
Industry Challenges
- Novel Food assessment expertise scarcity:Health Canada's technical review requirements demand specialized regulatory affairs capacity that mid-tier manufacturers struggle to staff.
- Flavor-active ingredient stability:Extended shelf life requirements for convenience store distribution conflict with degradation-prone functional additives like caffeine and certain vitamins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Chewing Gum Market |
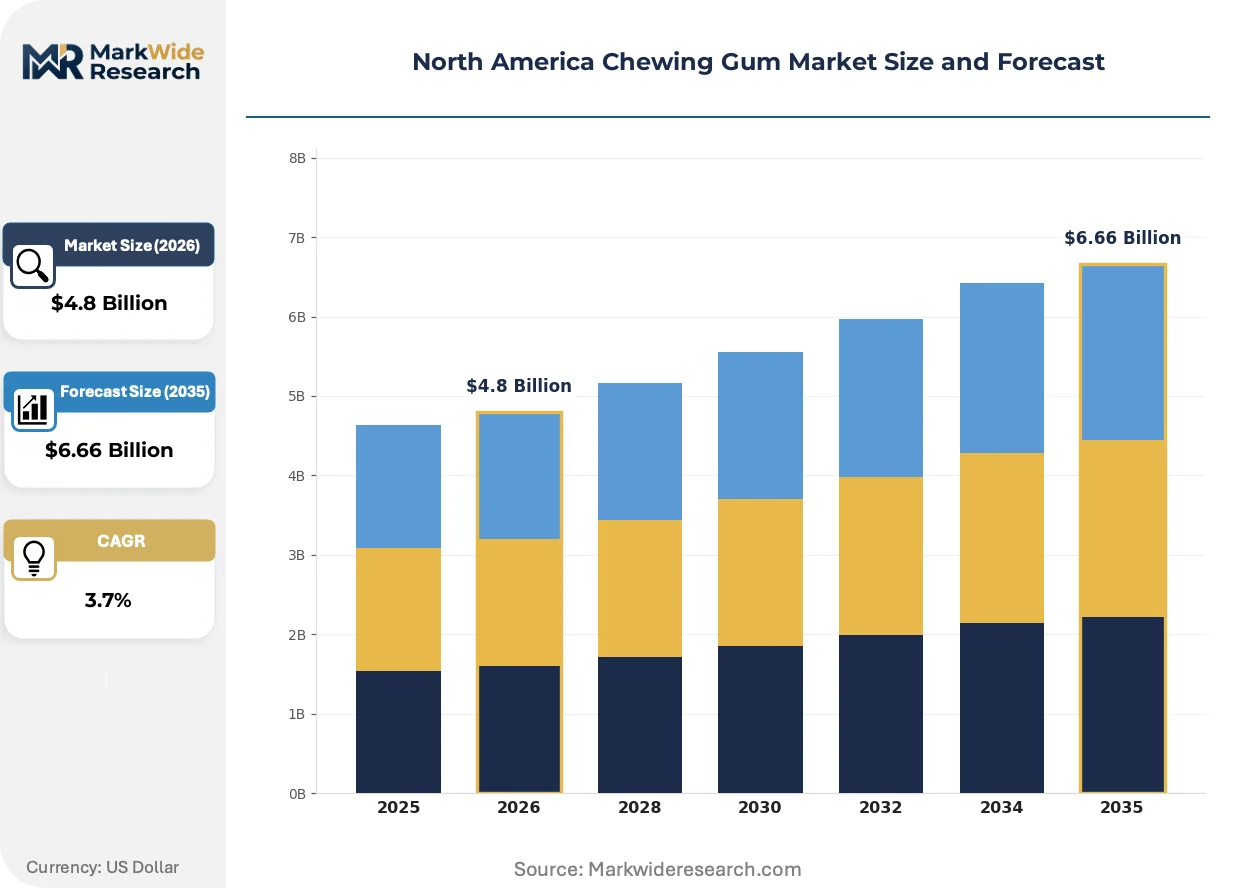
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bubble Gum, Sugar-Free Gum, Functional Gum, Standard Gum Sales Channel: Supermarkets, Convenience Stores, Online Retail, Vending Machines Flavor: Mint, Fruit, Bubblegum, Chocolate Target Audience: Kids, Teenagers, Adults, Health-Conscious Consumers |
| Companies Covered | The Hershey Company, Gerrit J Verburg Co, Mars Incorporated, Focus Foods Inc, Church & Dwight Co Inc, Mondelēz International Inc, The PUR Company Inc, Ford Gum & Machine Company Inc, Perfetti Van Melle BV, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Chewing Gum Market Trends and Innovations
Clean-label ingredient technology is narrowing formulation gaps between conventional and functional chewing gum, while regulatory transparency mandates and channel diversification reshape competitive positioning across the North American supply base.
Microencapsulation technology for active ingredient delivery is collapsing the stability barrier that previously separated functional gum from standard formulations. Caffeine, vitamin, and botanical extract suppliers are adopting pharmaceutical-grade encapsulation systems originally developed for nutraceutical applications. This convergence enables extended shelf life claims that unlock mainstream retail distribution for functional variants previously confined to specialty channels.
Health Canada Novel Food assessments and FDA food additive regulations are compressing launch timelines for ingredient innovation. Manufacturers must front-load toxicology and stability data packages before commercialization, shifting R&D investment toward regulatory science capabilities. Functional gum segments with botanical or cannabinoid positioning face the steepest compliance burdens, driving consolidation around established ingredient suppliers with pre-approved dossiers.
Commuter consumption patterns are fragmenting across channel types as remote work persistence reshapes transit-based purchase occasions. Traditional vending and convenience store channels face volume pressure in dense urban corridors, while pharmacy and online subscription channels capture replenishment-driven demand for dental health and functional positioning. This rotation concentrates growth in suburban and exurban markets where automobile-centric commuting sustains gas station and big-box retail traffic.
North America Chewing Gum Market Segmentation
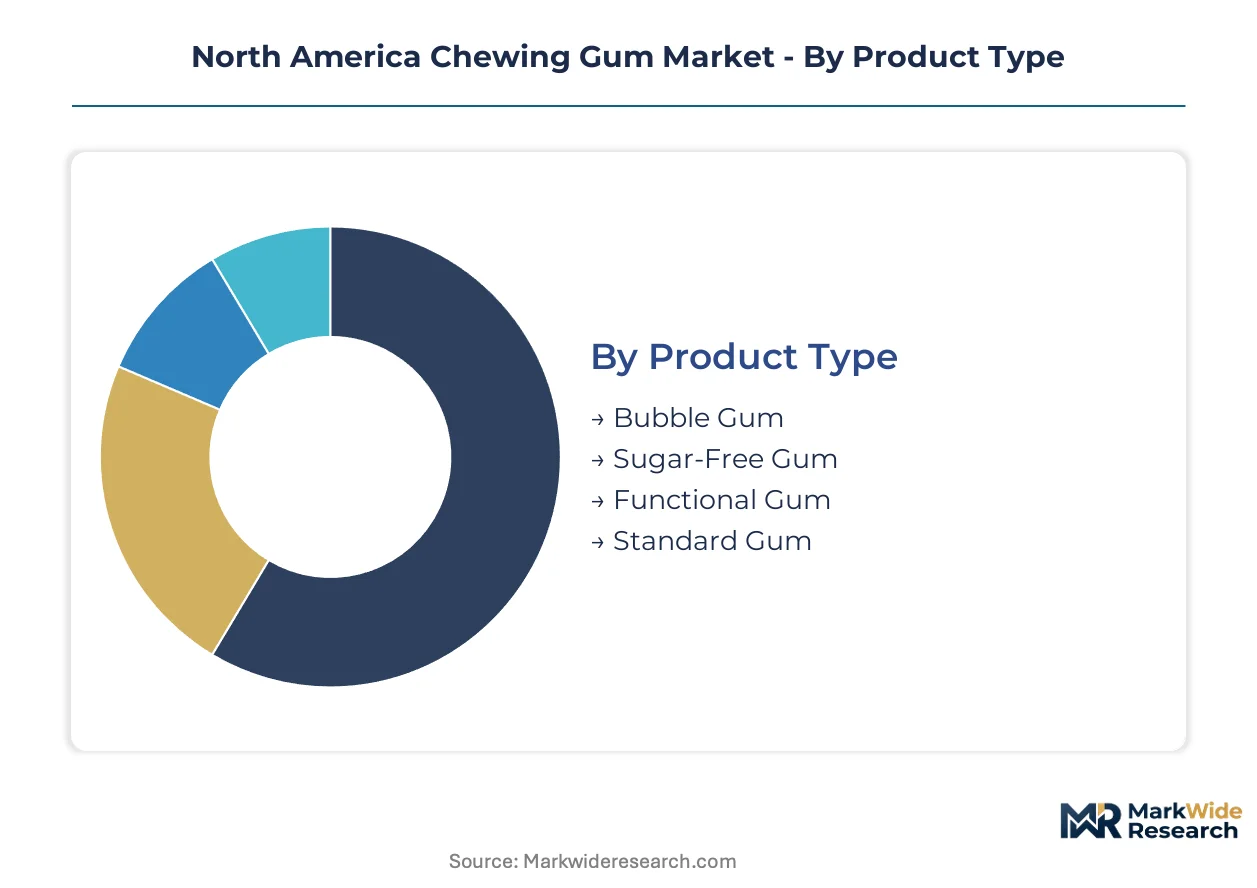
Segmentation in the North America chewing gum market reveals how formulation technology, channel strategy, and consumer occasion interact to create distinct margin pools. Manufacturers align R&D investment and retail execution against these divides to capture premium positioning or volume scale.
Product Type:
Use-case spectrum spans impulse refreshment through targeted physiological delivery, with formulation complexity determining channel access and pricing power.
- Functional Gum:Microencapsulated active ingredients including caffeine, vitamins, and botanical extracts enable extended-release claims. Health-conscious consumers in United States metropolitan corridors drive demand, though FDA food additive approval timelines constrain pipeline velocity for novel compounds.
- Sugar-Free Gum:Polyol-based sweetener systems combined with dental health positioning command pharmacy and professional channel placement. Canadian regulatory alignment with Health Canada ingredient disclosure rules accelerates clean-label conversion in this segment.
- Bubble Gum:Standard synthetic elastomer bases with high-sugar formulations target children's occasions through mass retail and vending.
- Standard Gum:Conventional sucrose or corn syrup sweetened varieties face compression from sugar-free alternatives in United States convenience stores.
The dominant share belongs to Sugar-Free Gum, while Functional Gum is closing the gap fastest.
Sales Channel:
Channel cost tiers separate high-frequency impulse touchpoints from subscription-driven replenishment economics, reshaping working capital requirements and brand building approaches.
- Convenience Stores:High-margin single-serve formats dominate commuter corridor traffic in Chicago, Los Angeles, and New York transit hubs. Shelf space reallocation toward functional and sugar-free varieties compresses traditional bubble gum facings.
- Online Retail:Direct-to-consumer subscription models for niche functional brands capture recurring revenue with superior customer lifetime value metrics. Warehouse fulfillment economics favor multi-pack configurations with extended shelf life requirements.
- Supermarkets:Multi-pack value formats drive household stock-up occasions, particularly in suburban United States markets where automobile-centric shopping patterns persist.
- Vending Machines:Single-serve pricing premiums sustain placement in high-density transit infrastructure, though remote work persistence pressures volume in downtown cores.
Convenience Stores retain the largest transaction volume, yet Online Retail demonstrates the steepest expansion trajectory.
Flavor:
Flavor application profiles align with demographic targeting and consumption occasion, with mint variants commanding the broadest cross-audience penetration.
- Mint:Dominant across adult and health-conscious positioning, menthol and spearmint variants anchor sugar-free and functional formulations. United States pharmacy channel placement depends heavily on mint flavor acceptance for dental health claims.
- Fruit:Berry and citrus profiles capture younger adult and teenage segments, with seasonal limited editions driving promotional calendar activity.
- Bubblegum:Synthetic fruit-ester formulations target children's occasions with bright colorants and aggressive sweetness profiles.
- Chocolate:Niche positioning in premium gifting and adult indulgence segments, limited by temperature stability constraints in convenience retail.
Mint formulations hold the widest distribution footprint, while Fruit variants gain share fastest among emerging functional launches.
Target Audience:
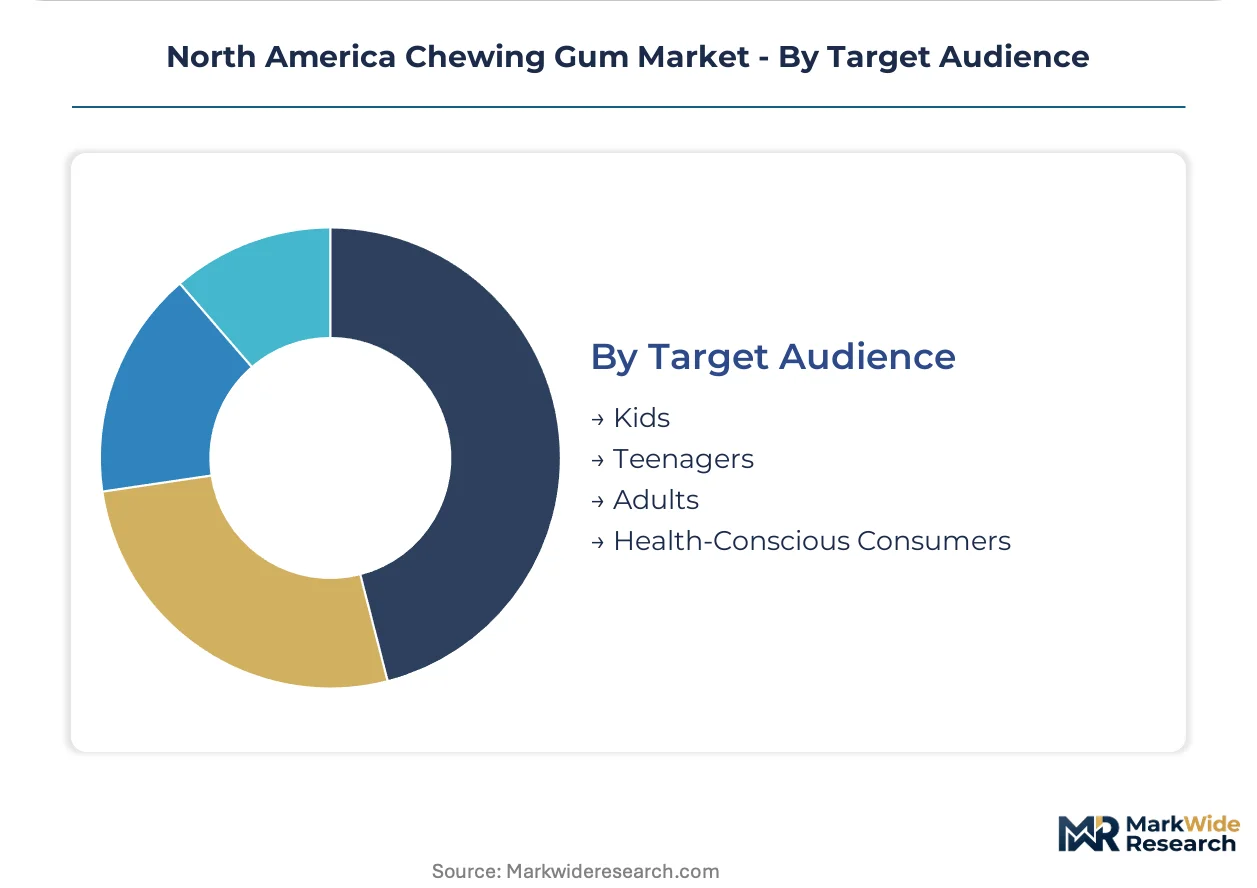
Customer type maturity separates established habit-driven consumption from emerging wellness-motivated trial, with age cohort determining media strategy and retail placement.
- Adults:Sustained habitual consumption in workplace and commuting contexts drives baseline volume. Stress-relief and breath-freshening positioning dominates United States corporate corridor vending placement.
- Health-Conscious Consumers:Clean-label scrutiny and active ingredient transparency demands push reformulation toward aspartame-free and natural positioning. Canadian regulatory disclosure requirements accelerate adoption in Toronto and Vancouver markets.
- Teenagers:Social sharing occasions and flavor novelty drive trial, with convenience store proximity to schools and recreation centers determining access.
- Kids:Parental gatekeeping around sugar content and artificial additives constrains bubble gum volume growth in United States mass retail.
Adults represent the largest established base, though Health-Conscious Consumers are expanding most quickly as functional positioning matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commuter-dependent buyer archetypes concentrate demand in United States metropolitan corridors, while health-conscious segments drive pharmacy channel expansion in Canadian urban markets. Mexican border states capture cross-border impulse purchasing patterns. Regulatory divergence across the three markets conditions formulation and labeling strategies.
United States
Transit-hub vending density and workplace refreshment occasions sustain baseline volume in Chicago, New York, and Los Angeles corridors. FDA food additive regulations govern novel functional ingredient approvals, compressing launch timelines for caffeine and botanical formulations. The Northeast corridor from Boston through Washington DC anchors premium sugar-free and functional gum distribution through pharmacy and convenience channels.
Canada
Health-conscious consumers in Toronto and Vancouver accelerate clean-label adoption, particularly for aspartame-free positioning. Health Canada Novel Food assessments and ingredient disclosure rules mandate transparent labeling that exceeds United States requirements. The Greater Toronto Area concentrates functional gum trial through pharmacy and natural product retail channels.
Mexico
Bubble gum and standard formulations retain volume share through mass retail and traditional trade in Mexico City and Guadalajara. Mexico's national health regulator, COFEPRIS, oversees food additive standards that generally align with Codex Alimentarius frameworks. Northern border states including Baja California and Nuevo León capture United States cross-border purchasing for premium sugar-free varieties.
California
Commuter corridor density along Los Angeles freeways and Bay Area transit systems sustains impulse vending placement for functional and sugar-free formats. California's Proposition 65 chemical disclosure requirements exceed federal standards, pushing reformulation toward cleaner-label ingredients. The Los Angeles-Long Beach metropolitan cluster anchors West Coast distribution infrastructure for national brands.
Texas
Automobile-centric commuting patterns in Houston and Dallas-Fort Worth sustain gas station and convenience store traffic for single-serve formats. Texas state regulations generally defer to FDA standards for food additive approvals, streamlining national product launches. The Dallas-Fort Worth-Arlington metroplex concentrates retail execution resources for Southwest regional distribution.
North America Chewing Gum Market Competitive Landscape
Channel-controlling players compete with product-specialist players across convenience, pharmacy, and online retail touchpoints. The market structure consolidates around confectionery conglomerates with existing retail infrastructure and emerging specialists with clean-label positioning. Two strategic archetypes dominate: diversified confectionery majors leveraging R&D scale, and focused natural-positioned challengers capturing premium segments. Competitive moves center on shelf space reallocation negotiations and direct-to-consumer subscription model deployment.
Within the diversified major tier, Mars Incorporated and Mondelēz International exemplify scale-driven players with confectionery R&D infrastructure and established North American distribution networks. The PUR Company Inc occupies a position representing the natural-segment specialist archetype, differentiating through aspartame-free formulations that command retail premiums. These three companies collectively illustrate the competitive tension between volume-scale efficiency and premium-positioned specialization reshaping category dynamics.
| Leading Market Players |
|---|
| The Hershey Company |
| Gerrit J Verburg Co |
| Mars Incorporated |
| Focus Foods Inc |
| Church & Dwight Co Inc |
| Mondelēz International Inc |
| The PUR Company Inc |
| Ford Gum & Machine Company Inc |
| Perfetti Van Melle BV |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in United States synthetic elastomer production drives supplier consolidation and pricing leverage among base-material producers, compressing margins for mid-tier gum manufacturers while rewarding scale players with volume-commitment discounts.
Pricing Analysis
Cost-plus contracts with petrochemical indexation dominate base-material procurement, with polyol sweetener and synthetic resin costs tracking crude oil derivatives. Three-tier pricing structure across premium functional, standard sugar-free, and economy bubble gum levels separates dental-health-certified pharmacy placement from mass retail. Pricing pressure stems from Health Canada disclosure compliance costs and clean-label reformulation investments. Health-conscious consumers in Toronto and Vancouver show lowest price sensitivity, while children's bubble gum segments in Mexican mass retail face intense competition.
Supply Chain Analysis
Export-control restrictions on advanced polymer processing equipment limit domestic capacity expansion for microencapsulation systems, constraining functional gum innovation timelines. Synthetic elastomer production concentrates in United States Gulf Coast petrochemical corridors and select Canadian specialty chemical facilities. Gum base formulations draw from petroleum-derived resins, plasticizer additives, and polyol sweetener systems. Single-source vulnerability runs through concentrated elastomer suppliers exposed to hydrocarbon price swings. Distribution runs through Mars Incorporated and Mondelēz International controlled retail networks, with direct-to-consumer subscription channels emerging for niche functional brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as commuter consumption patterns split between transit-hub impulse and suburban replenishment, creating distinct channel niches for specialized positioning.
For Market Incumbents: Entrench pharmacy channel control through dental health certification investment and sugar-free formulation exclusivity. Consolidate synthetic elastomer supply through backward integration into petrochemical partnerships or captive resin production. Remote work persistence threatens downtown vending volume; defend through suburban gas station and big-box retail expansion.
For New Entrants and Emerging Players: Build out direct-to-consumer subscription infrastructure targeting health-conscious consumers in Canadian urban markets and United States coastal metros. White-space concentrates in aspartame-free functional positioning and CBD-infused variants pending regulatory clarity. Pharmacy channel placement offers highest margin access for clean-label specialists with Health Canada pre-approval.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among functional gum subscription models with microencapsulation technology differentiation. Long-term viability favors acquisition targets with established Health Canada Novel Food dossiers and USDA BioPreferred packaging certifications. Watch state-level THC and hemp-derived cannabinoid rule finalization as pipeline unlock signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Program | Health Canada disclosure rules accelerate aspartame-free conversion in Toronto pharmacy channels. |
| Microencapsulation R&D Partnership | Pharmaceutical-grade active delivery systems unlock extended shelf life for functional variants. |
| Subscription Model Launch | Direct-to-consumer recurring revenue captures health-conscious consumers outside impulse retail. |
| USDA BioPreferred Certification | Biobased packaging sourcing opens institutional procurement and sustainability-positioned placement. |
| Regulatory Pre-Approval Investment | Front-loaded toxicology data packages compress FDA food additive timelines for novel ingredients. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary research phases, including brand managers at confectionery majors, category buyers at convenience store chains, regulatory affairs specialists, and polymer R&D directors. Secondary validation drew from FDA food additive filings, Health Canada Novel Food assessments, USDA BioPreferred program databases, and Nielsen retail audit data. Bottom-up volume modeling triangulated against top-down category spend estimates.
Calibration anchored historical growth patterns against elasticity-adjusted projections across the analysis window, with segmentation by product type, sales channel, flavor profile, and target audience. CAGRs derived from fitted trend lines incorporating commuter traffic recovery assumptions, clean-label adoption curves, and functional ingredient approval velocity. Model inputs included vending machine placement density indices and pharmacy channel expansion rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by private-label entrants or cross-category wellness brands would shift outcomes. Material shifts in FDA cannabinoid scheduling or Health Canada encapsulation technology approvals would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Pre-Packaged Sandwich Market
Packaged Foods
Peanut Butter Market
Packaged Foods
Ready to Use Fillings Market
Packaged Foods
Instant Soup Market
Packaged Foods
Canned Legumes Market
Packaged Foods
Global Aseptic Packaging in Food Market
Packaged Foods
Quinoa Pasta Market
Packaged Foods
Pre-Packaged Food Market
Packaged Foods
Packaged Food Market
Packaged Foods
Europe Ready Meals Market
Packaged Foods
China Packaged Food Products Market
Packaged Foods
Singapore Ready-To-Eat Food Market
Packaged Foods
Bangladesh Instant Noodles Market
Packaged Foods
Canned Goods Market
Packaged Foods
Cookie Pucks Market
Packaged Foods
Low Calorie Noodles Market