
 Morning Goods Market | 2026-2036
Morning Goods Market Size, Share, and Industry Trends Forecast 2026-2036
Morning Goods Market Foresight
Single-serve bundling is hardening as the dominant packaging configuration, reshaping how retailers merchandise and consumers stock pantries. Grupo Bimbo leverages its North American bakery network to control shelf placement across convenience channels. Britannia Industries anchors its position in South Asia with localized muffin and rusk portfolios. General Mills Inc competes through R&D intensity in better-for-you cereal extensions.
Morning goods comprise baked and ready-to-eat breakfast items formulated from wheat, oats, yeast, and functional additives, produced through continuous baking, extrusion, or retort processes to deliver shelf-stable or fresh consumption options. Cereal and granola segments sustain margin pools where fortification claims command retail premiums, while bagels face maturation in saturated urban markets. The distribution channel dimension shows supermarkets retaining volume leadership as online retailers capture fastest growth in subscription-based repeat purchases.
The FDA governs nutrition labeling and health claims for U.S. morning goods, while EFSA and the EU Green Deal shape reformulation mandates on sugar content and sustainable sourcing across European markets. BIS standards in India enforce quality parameters for packaged baked products, affecting import access and domestic manufacturing compliance. Stakeholders must monitor evolving front-of-pack labeling regimes and carbon-footprint disclosure requirements as procurement criteria tighten across retail banners.
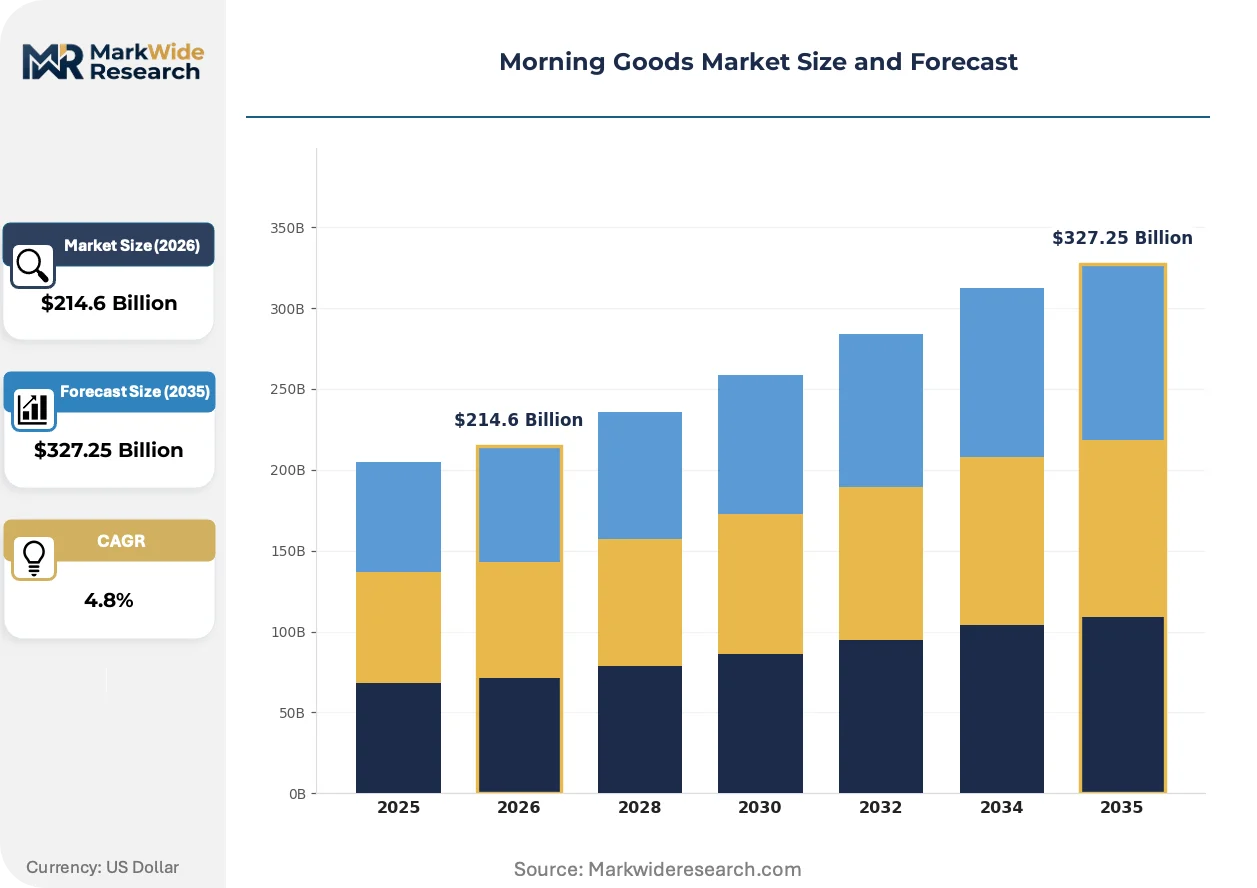
Market Dynamics
Single-serve packaging configurations and clean-label reformulation mandates are compressing legacy production economics while forcing capital reallocation toward flexible manufacturing lines and ingredient substitution R&D.
Growth Catalysts
- EU Green Deal sugar-reduction mandates:Manufacturers reformulating with alternative sweeteners and fiber fortification to maintain shelf placement across German and French retail banners.
- Urban breakfast habit shifts in China:Tier-1 city professionals adopting packaged baked goods over traditional morning meals, expanding convenience store distribution networks.
- Extrusion technology advances:Continuous processing equipment enabling real-time texture modification for gluten-free and high-protein cereal extensions without batch interruption.
Market Restraints
- Wheat and oat input volatility:Commodity price swings compressing margin pools for mid-tier producers lacking forward-contract coverage.
- Yeast supply concentration in Western Europe:Dependence on specialized fermentation capacity creates vulnerability to energy-cost spikes and logistics disruption.
- Retort-process technical ceiling:Thermal degradation limits on fortification nutrient retention constrain functional claim credibility in ambient-stable formats.
Strategic Opportunities
- Subscription-based repeat purchase channels:Direct-to-consumer platforms capturing pantry-stocking behavior among dual-income households in United States metropolitan areas.
- India BIS quality standard alignment:Domestic manufacturers leveraging compliance to displace informal sector production in packaged rusk and biscuit segments.
- AI-driven formulation optimization:Machine learning convergence with sensory science accelerating clean-label prototype development cycles.
Industry Challenges
- Industrial bakery technician scarcity:Specialized skills in continuous baking system maintenance and troubleshooting command premium wages and extend hiring timelines.
- Front-of-pack labeling compliance fragmentation:Divergent interpretive guidance across FDA nutrition claim rules and emerging state-level disclosure requirements multiplies legal review burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Morning Goods Market |
| Market Size in 2026 | $214.6 Billion |
| Market Size in 2035 | $327.25 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cereal, Granola, Muffins, Bagels Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Farmers' Markets Consumer Type: Health-Conscious, Families, Students, Busy Professionals Flavor Profile: Sweet, Savory, Nutty, Fruity |
| Companies Covered | Finsbury Food Group Plc, Dawn Food Products, Inc., Grupo Bimbo, Britannia Industries, Chipita SA, General Mills Inc, Dan Cake A / S, Barilla G. e R. Fratelli SpA, Yıldız Holding Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Morning Goods Market Shifts & Advancements
Active fermentation control systems and precision extrusion architectures are displacing batch-dependent processing, while regulatory disclosure regimes and direct-to-consumer channel growth reshape how morning goods reach end-users.
Precision fermentation for alternative protein enrichment is rewriting the ingredient cost structure for high-margin granola and cereal segments. Mid-sized manufacturers in the United States and Germany are adopting these systems at pilot scale. The technology is rewriting procurement relationships between ingredient suppliers and finished goods producers, compressing traditional dairy and egg additive supply chains.
EFSA front-of-pack nutrition scoring implementation across EU member states is forcing reformulation of sugar-dense muffin and pastry lines. Industrial bakeries are accelerating stealth reduction programs and fiber fortification to maintain retail distribution. Breakfast biscuit and cereal bar categories in France and Spain face the steepest label-score pressure and are responding with accelerated clean-label R&D cycles.
Pantry-stocking behavior among remote-work professionals is fragmenting traditional supermarket volume concentration. Direct-to-consumer subscription platforms and convenience channel micro-fulfillment are displacing weekly big-box trips for core morning goods categories. This shift is most visible in United States coastal metropolitan markets where same-day delivery density supports perishable baked goods logistics.
Morning Goods Market Segmentation
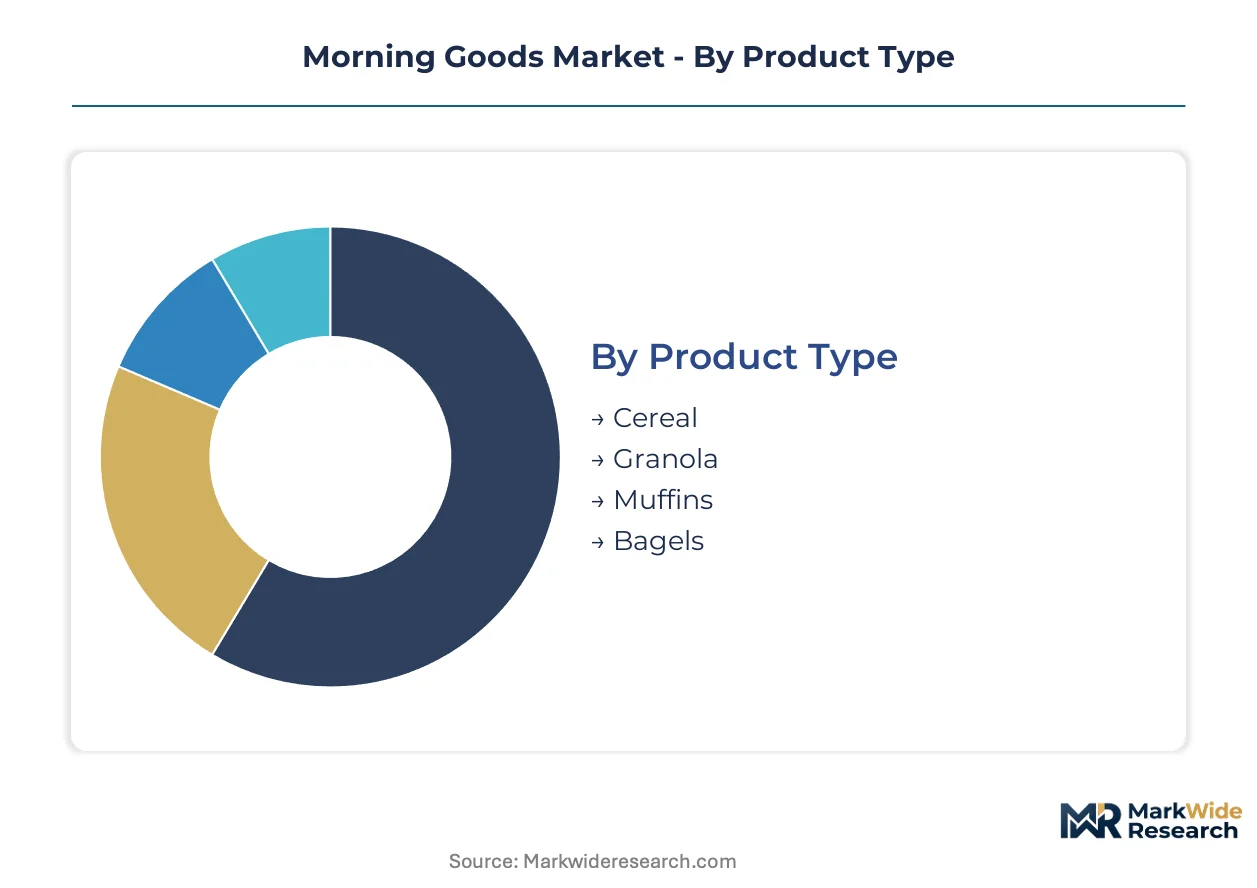
Segmentation in morning goods reveals how formulation specifications and channel access determine margin capture. Technical differentiation in processing methods and packaging configurations separates premium-positioned offerings from commodity alternatives.
Product Type:
Continuous processing architectures and fortification capabilities differentiate segments by shelf stability and nutritional claim viability.
- Cereal:Extruded or flaked grain matrices with vitamin and mineral fortification at the coating stage. Demand concentrates in United States households with children, where fortification claims justify retail price premiums and drive repeat purchase loyalty.
- Granola:Baked oat clusters bound with syrups and oils, enabling higher protein and fiber loading through ingredient inclusions. German and French retail banners prioritize clean-label granola with reduced added sugars to meet EU Green Deal reformulation mandates.
- Muffins:Chemically leavened individual portions with ambient or fresh distribution requirements.
- Bagels:Boiled-then-baked ring shapes with dense crumb structure and extended shelf life limitations.
Mature deployment sits with Cereal. Newer deployment is concentrated in Granola.
Distribution Channel:
Channel economics hinge on perishability windows, case configuration flexibility, and direct consumer data capture.
- Supermarkets:Full assortment merchandising with temperature-controlled bakery sections and promotional slotting fees. United States and German volume leadership persists here, though basket fragmentation is eroding weekly trip frequency among remote-work professionals.
- Online Retailers:Subscription-based replenishment models with predictive inventory and same-day delivery density in metropolitan corridors. Coastal United States markets show steepest expansion trajectory as pantry-stocking behavior shifts to digital platforms.
- Convenience Stores:Single-serve and immediate-consumption formats with limited shelf space and rapid turnover requirements.
- Farmers' Markets:Artisan-positioned fresh baked goods with minimal packaging and direct producer-consumer relationships.
Volume leadership remains with Supermarkets. Subscription mechanics are expanding most quickly in Online Retailers.
Consumer Type:
Purchase occasion and nutritional priority segmentation determines formulation intensity and packaging configuration.
- Health-Conscious:Clean-label seekers prioritizing fiber content, reduced sugars, and functional ingredient claims. China Tier-1 city professionals are adopting packaged baked goods over traditional morning meals, expanding convenience store distribution for protein-fortified options.
- Families:Multi-serve packaging with child-appealing flavors and fortification messaging. Bulk purchasing and pantry stocking behavior in United States suburban households sustains volume for value-positioned cereal and granola formats.
- Students:Price-sensitive single-serve consumption with portability requirements.
- Busy Professionals:On-the-go formats with minimal preparation and premium positioning tolerance.
Established demand concentration sits with Families. Health-Conscious segmentation is gaining share fastest as regulatory disclosure regimes intensify.
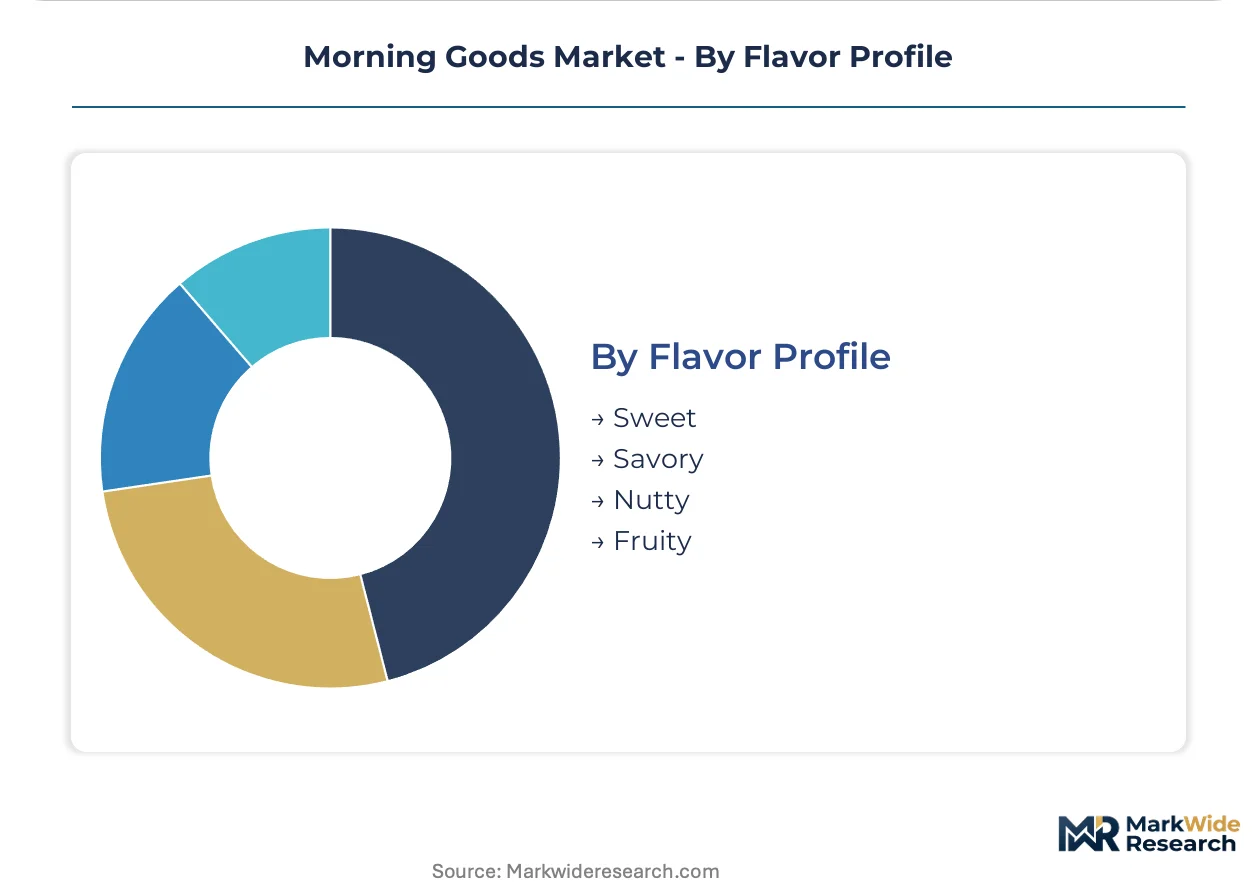
Flavor Profile:
Sensory positioning and ingredient cost structures vary sharply across taste territories.
- Sweet:Sugar-syrup coatings, dried fruit inclusions, and chocolate or honey flavor systems. EFSA front-of-pack scoring pressure in France and Spain is forcing stealth reduction programs in sweet muffin and pastry lines.
- Savory:Cheese, herb, and vegetable inclusions with lower sugar content and extended ambient stability. German retail banners are expanding savory bagel and breakfast biscuit assortments to meet clean-label preferences without nutrition score penalties.
- Nutty:Almond, walnut, and seed inclusions with premium positioning and allergen management requirements.
- Fruity:Berry and citrus flavor systems with natural color and acidity regulation challenges.
Volume concentration sits with Sweet. Reformulation investment is concentrating in Savory as sugar reduction mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in the United Arab Emirates and bonded warehouse districts in the Netherlands concentrate re-export activity for packaged baked goods destined for adjacent markets.
United States
Remote-work professionals in coastal metropolitan areas are shifting pantry-stocking behavior toward subscription-based replenishment models. The FDA governs nutrition labeling and health claims for morning goods sold across state lines. Chicago and Minneapolis-St. Paul anchor industrial baking capacity serving national distribution networks.
Germany
Clean-label reformulation pressures from EU Green Deal sugar-reduction mandates are accelerating stealth reduction programs in muffin and pastry lines. EFSA front-of-pack nutrition scoring implementation shapes retail shelf placement decisions. The Rhine-Ruhr industrial corridor hosts specialized fermentation capacity supplying yeast-dependent production across Western Europe.
China
Tier-1 city professionals in Beijing and Shanghai are adopting packaged baked goods over traditional morning meals. SAMR and GB standards enforce quality parameters for imported and domestically produced baked products. The Yangtze River Delta concentrates convenience store distribution network expansion for protein-fortified breakfast options.
India
Urban breakfast habit shifts in Mumbai and Delhi-NCR are displacing informal sector production with packaged rusk and biscuit consumption. BIS standards enforce quality parameters affecting import access and domestic manufacturing compliance. Gujarat and Maharashtra host industrial baking clusters scaling output to meet rising middle-class demand.
France
Breakfast biscuit and cereal bar categories face steep front-of-pack label-score pressure from EFSA implementation. ANSM and national health authorities coordinate with EU-wide reformulation timelines. The Île-de-France region concentrates R&D activity for clean-label prototype development serving pan-European retail banners.
Morning Goods Market Competitive Landscape
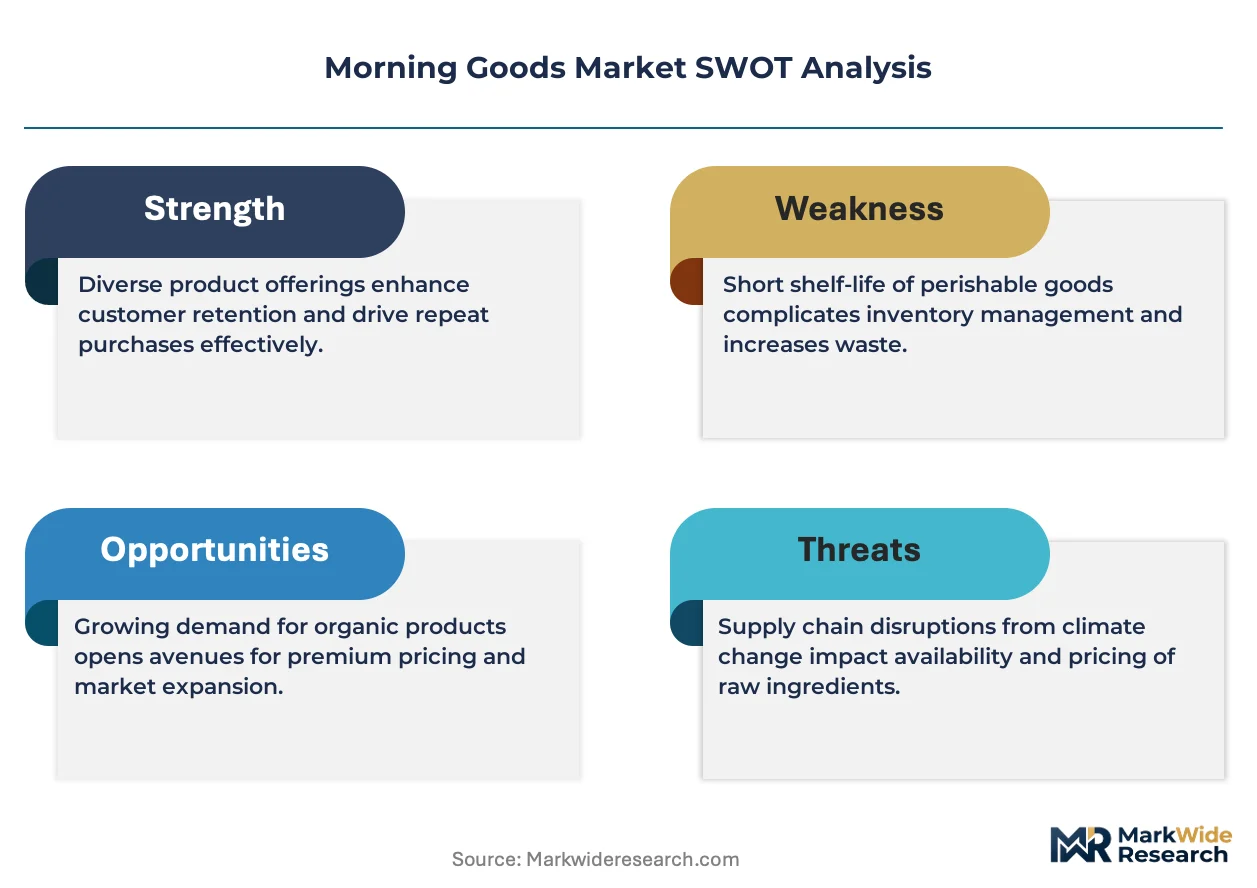
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: multinational packaged food conglomerates with bakery divisions, regional specialists with localized portfolio depth, and private-label manufacturers serving retail banners. Capacity expansion and portfolio diversification represent the dominant competitive moves as producers respond to clean-label reformulation mandates and channel fragmentation.
Among diversified conglomerates with bakery networks, Grupo Bimbo, General Mills Inc, and Britannia Industries exemplify scale-driven positioning across distinct geographic strongholds. Grupo Bimbo represents North American convenience channel penetration through shelf placement control. General Mills Inc occupies a position in better-for-you cereal extension development. Britannia Industries anchors South Asian market presence with localized product portfolios.
| Leading Market Players |
|---|
| Finsbury Food Group Plc |
| Dawn Food Products, Inc. |
| Grupo Bimbo |
| Britannia Industries |
| Chipita SA |
| General Mills Inc |
| Dan Cake A / S |
| Barilla G. e R. Fratelli SpA |
| Yıldız Holding Inc. |
| Others |
Supply & Pricing Matrix
Clean-label certification divergence between EU-compliant reformulated lines and legacy sugar-dense formulations manifests in both shelf placement premiums and ingredient sourcing complexity. Manufacturers serving German and French retail banners face dual cost structures as stealth reduction programs and fiber fortification requirements reshape procurement relationships.
Pricing Analysis
Short lead-time premiums for fresh-baked morning goods command retail markups over ambient-stable alternatives stocked on promotion. Subscription-based replenishment models in United States coastal markets stratify pricing across premium, standard, and economy tiers tied to fortification intensity and delivery frequency. Cost compression in commodity cereal segments stems from wheat and oat input volatility, while health-conscious households show lowest price sensitivity for protein-fortified granola. Families purchasing multi-serve formats at supermarkets demonstrate highest elasticity, shifting volume toward private-label alternatives when slotting fees drive branded price gaps.
Supply Chain Analysis
Industrial bakery technician scarcity in United States Midwest and Rhine-Ruhr corridor clusters constrains continuous baking system expansion and extends commissioning timelines. Manufacturing gravity centers on Germany, United States, and China, with each market drawing from specialized fermentation capacity and extrusion equipment suppliers. Raw material dependencies on wheat futures, yeast cultures, and alternative sweetener supply chains expose producers to commodity price swings and energy-cost spikes. Single-source vulnerability in Western European yeast supply creates structural risk for bagel and chemically leavened formats. Distribution runs through supermarket temperature-controlled bakery sections, convenience channel micro-fulfillment nodes, and direct-to-consumer cold-chain logistics for subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active fermentation control systems and precision extrusion architectures are displacing batch-dependent processing, forcing capital reallocation toward flexible manufacturing lines.
For Market Incumbents: Extend clean-label R&D pipelines to preempt EFSA front-of-pack scoring displacement in French and Spanish breakfast biscuit categories. Acquire specialized fermentation capacity in Rhine-Ruhr corridor to secure yeast supply continuity against energy-cost volatility. Deepen backward integration into alternative protein ingredient streams before precision fermentation suppliers consolidate pricing power. For New Entrants and Emerging Players: Capture pantry-stocking behavior among remote-work professionals in United States coastal metropolitan corridors through direct-to-consumer subscription mechanics. Target India BIS quality standard alignment as regulatory moat against informal sector rusk and biscuit production. Lead with AI-driven formulation optimization to compress prototype development cycles and outpace legacy R&D timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified packaged food conglomerates seeking bakery division scale. Long-term viability favors manufacturers with demonstrated compliance across FDA nutrition claim rules and emerging state-level disclosure requirements. Watch for inflection in front-of-pack labeling compliance fragmentation as signal for consolidation pressure on mid-tier producers lacking legal review bandwidth.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Program | EFSA front-of-pack scoring compliance secures shelf placement in German and French retail banners. |
| Precision Fermentation Scale-Up | Alternative protein enrichment rewrites ingredient cost structures for high-margin granola segments. |
| Subscription Platform Launch | Direct-to-consumer capture of pantry-stocking behavior in United States coastal metropolitan markets. |
| Flexible Manufacturing Line Investment | Real-time texture modification enables gluten-free and high-protein cereal extensions without batch interruption. |
| BIS Quality Standard Alignment | Regulatory compliance displaces informal sector production in India packaged rusk and biscuit segments. |
Research Methodology
Document review covered FDA nutrition labeling guidance, EFSA reformulation mandates, BIS packaged baked product standards, and customs trade data, complemented by interviews with industrial bakery operations directors, retail category buyers, ingredient procurement leads, and continuous baking system technicians. Secondary validation drew from Nielsen retail audit data, SEC 10-K filings of diversified packaged food conglomerates, and EU Green Deal implementation timelines. Bottom-up demand modeling triangulated against top-down macroeconomic consumption projections.
Output metrics span volume and value across the analysis window, with segmentation dimensions covering product type, distribution channel, consumer archetype, and flavor profile. CAGRs derive from regression analysis against historical consumption patterns and regulatory phase-in schedules. Forecast inputs incorporate wheat and oat commodity futures curves, urbanization rates in China Tier-1 cities, and subscription platform penetration trajectories in United States metropolitan corridors.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU sugar-reduction mandate enforcement intensity and yeast supply disruption scenarios. Projections reflect assumptions on clean-label adoption velocity and convenience channel expansion density. Material deviation in wheat input volatility or front-of-pack labeling compliance timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Saudi Arabia Ready Meals Market
Packaged Foods
United Kingdom Food Spreads Market
Packaged Foods
Ready Meals Market
Packaged Foods
On-The-Go Breakfast Cereals Market
Packaged Foods
Tortilla Market
Packaged Foods
Dinner Ready-To-Eat (RTE) Food Market
Packaged Foods
North America Ready Meals Market
Packaged Foods
Canned Legumes Market
Packaged Foods
Packaged Sprouts Market
Packaged Foods
Pasta and Noodles Market
Packaged Foods
South America Pasta and Noodles Market
Packaged Foods
Asia-Pacific Ready-To-Eat Food Market
Packaged Foods
Peanut Butter Market
Packaged Foods
Canned Mushroom Market
Packaged Foods
Packaged Salad Market
Packaged Foods
Sugar-Free Biscuits and Cookies Market