
 Club Store Packs Market | 2026-2036
Club Store Packs Market Size, Share, and Industry Trends Forecast 2026-2036
Club Store Packs Market Analytics
The warehouse club channel is rewriting procurement patterns for volume-packaged consumer goods. Costco Wholesale leverages its Kirkland Signature private label to control shelf positioning and margin capture across food and household categories. Sam's Club competes through Scan & Go technology integration and curbside fulfillment infrastructure. BJ's Wholesale Club anchors its footprint in dense Eastern US corridors with localized assortment strategies.
Club store packs encompass bulk and multi-unit packaging formats engineered for pallet-ready display, typically incorporating reinforced corrugate or rigid plastic structures with integrated handling apertures and high-visibility lithographic printing. These configurations serve retail environments where consumers self-select large-quantity merchandise with minimal staff intervention. Bulk packaging dominates unit economics in food and beverage due to perishability constraints and turnover velocity, while combo packs concentrate margin pools in personal care where cross-category bundling lifts basket values. Multi-pack formats in household supplies show structural momentum as club operators optimize warehouse cube utilization and reduce stockout frequency.
US FDA food contact notification requirements govern substrate safety for edible product packaging, while EPA sustainable materials management frameworks pressure operators toward post-consumer recycled content thresholds. California's extended producer responsibility statutes and New York's pending packaging reduction legislation are forcing format redesigns toward fiber-based alternatives. Stakeholders must monitor how state-level regulatory fragmentation reshapes national pack specifications and supplier qualification costs.
Market Dynamics
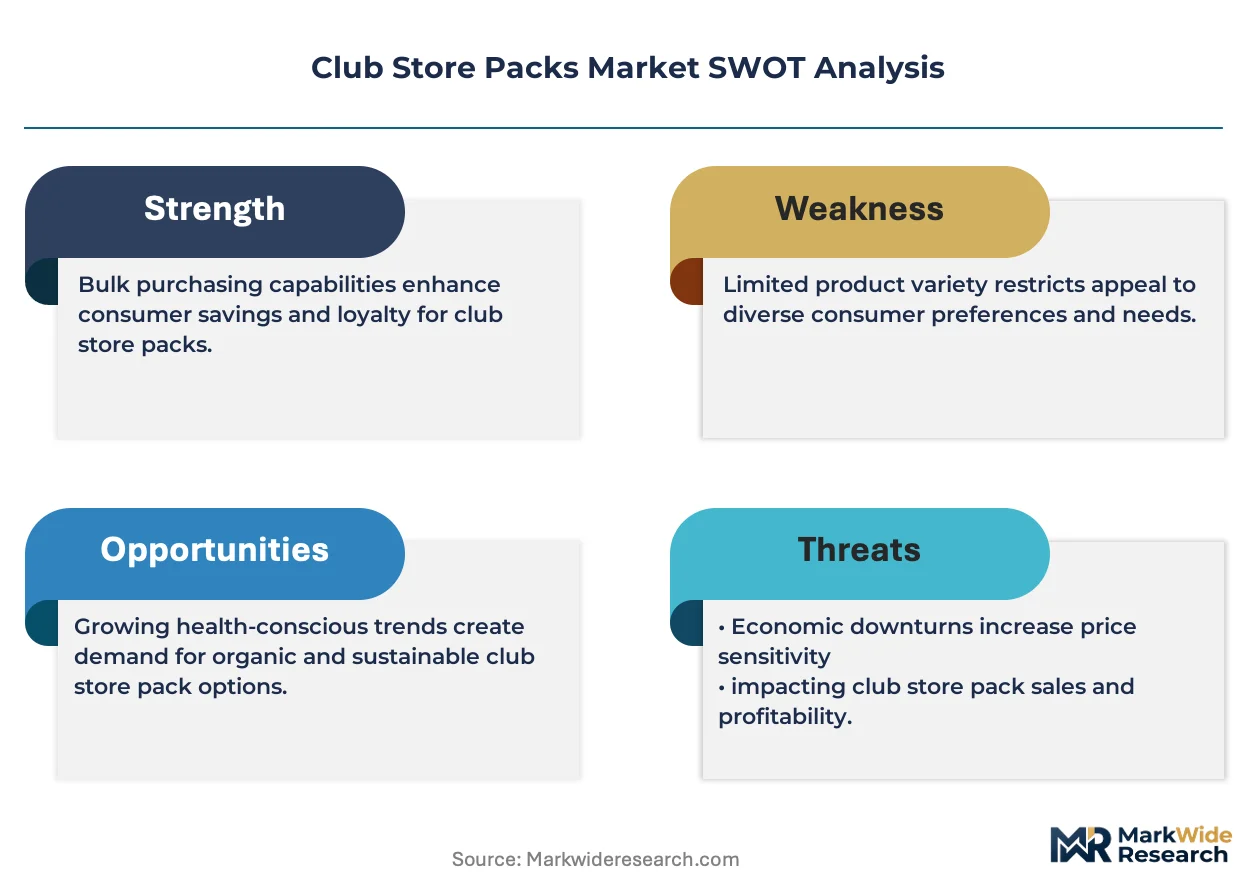
US state-level plastic reduction mandates are forcing club store pack formats toward fiber-based substrates, while warehouse club operators simultaneously compress supplier margins through private label expansion and pallet-ready display requirements.
Growth Catalysts
- Sun Belt migration corridors:Population inflow into Texas, Florida, and Arizona is clustering new club store openings and bulk consumption patterns in these high-growth metropolitan zones.
- Extended Producer Responsibility statutes:California's EPR framework is accelerating recyclable bulk packaging transitions among suppliers seeking qualification for club channel distribution.
- Small business procurement consolidation:Independent retailers and foodservice operators are migrating inventory purchases to warehouse clubs, deepening B2B penetration for multi-unit pack formats.
Market Restraints
- OCC fiber price volatility:Old corrugated container input costs swing with municipal recycling collection rates, compressing margin predictability for fiber-based club pack converters.
- Supply concentration in Southeast Asia:Rigid plastic component molding concentrates in Vietnamese and Thai manufacturing zones, exposing lead time vulnerability to regional logistics disruptions.
- FDA food contact notification timelines:Pre-market safety reviews for novel substrates extend supplier qualification cycles, delaying format innovation deployment.
Strategic Opportunities
- Curbside fulfillment infrastructure:Club operators investing in pickup logistics create demand for shelf-ready packs optimized for automated retrieval and reduced handling damage.
- Scan & Go technology convergence:Mobile checkout integration with RFID-enabled packaging opens white space for serialized bulk units that streamline inventory tracking.
- New York pending packaging reduction legislation:Anticipated state mandates will force format redesigns, rewarding early movers with fiber-based pallet-ready solutions.
Industry Challenges
- Structural design engineering talent scarcity:Packaging engineers capable of optimizing cube utilization while meeting load-bearing specifications for pallet display are concentrated among a limited pool of specialized firms.
- Legacy ERP integration friction:Supplier systems for batch tracking and substrate certification often lack API compatibility with club operator procurement platforms, complicating real-time inventory visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Club Store Packs Market |
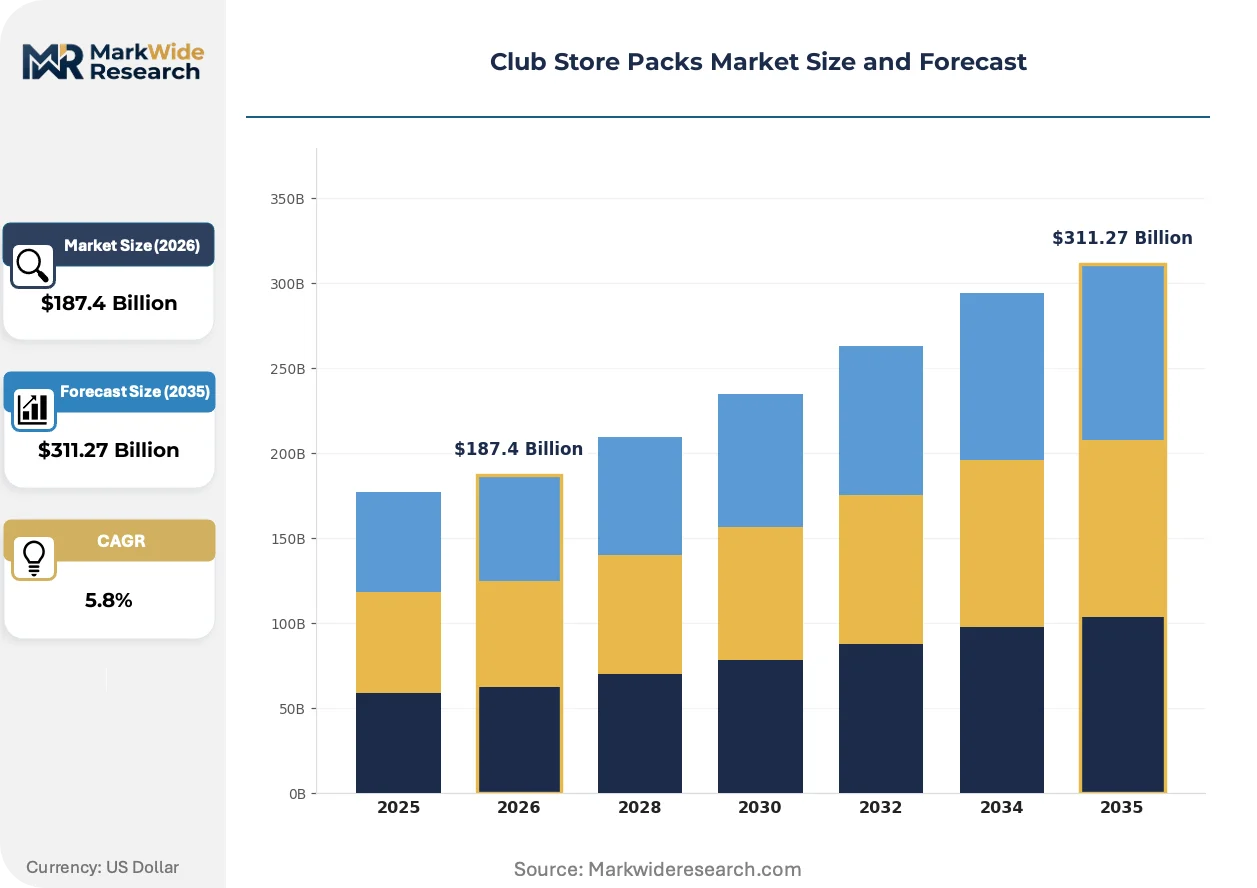
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $311.27 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food & Beverage, Household Supplies, Personal Care, Electronics Packaging Type: Bulk Packaging, Multi-Pack, Combo Packs, Trial Packs Customer Type: Retail Customers, Wholesalers, Businesses, Institutions Price Tier: Premium, Mid-Range, Economy, Discount |
| Companies Covered | Costco Wholesale, Sam's Club, BJ's Wholesale Club, Walmart, Assemblies Unlimited, Creative Displays Now, Accurate Box Company, Transparent Container, PriceSmart, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Club Store Packs Market Evolving Landscape
Active format experimentation is compressing traditional pack development cycles. Club operators now demand prototype-to-shelf timelines measured in months rather than seasons, while substrate innovators race to qualify fiber alternatives before state plastic bans take effect.
Reinforced corrugate with integrated handling apertures is hybridizing with water-resistant barrier coatings derived from agricultural waste streams. Food and beverage category managers at warehouse clubs are piloting these formats for frozen and refrigerated bulk SKUs. The technology is hybridizing moisture protection standards previously exclusive to rigid plastic, enabling fiber-based penetration into perishable categories.
California's extended producer responsibility statutes are forcing national pack specification convergence. Suppliers serving multi-state club operators must now design to the strictest state standard rather than maintaining regional format variations. The personal care and household supplies segments are absorbing the highest compliance costs, with pack redesigns prioritizing post-consumer recycled content thresholds.
Small business buyers are consolidating procurement through warehouse club channels previously dominated by household consumers. Foodservice operators and independent retailers now represent a measurable B2B demand stream for bulk and combo pack formats. This behavioral shift concentrates most visibly in Texas and Florida metropolitan corridors, where club operators are expanding dedicated business membership tiers with customized assortment and credit terms.
Club Store Packs Market Segmentation
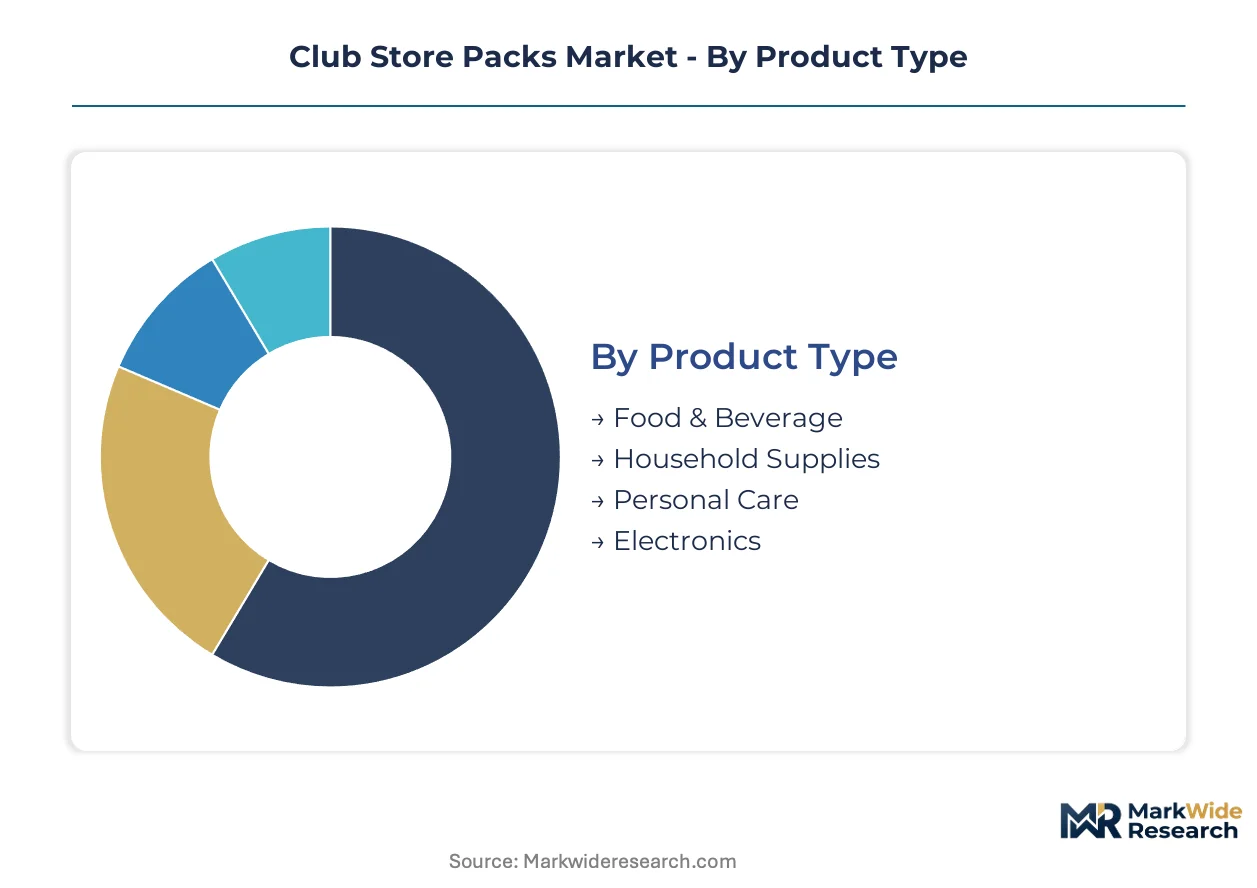
Warehouse club operators configure pack specifications around distinct consumption velocities and handling requirements. Category-specific segmentation reveals where fiber-based transitions encounter technical barriers versus where pallet-ready formats unlock margin capture.
Product Type:
Perishability constraints and turnover velocity shape substrate selection across the consumption spectrum.
- Food & Beverage:Refrigerated and frozen bulk SKUs demand moisture-resistant barrier coatings derived from agricultural waste streams. Texas and Florida metropolitan corridors concentrate club operator pilot programs for fiber-based alternatives in perishable categories, though FDA food contact notification timelines delay substrate qualification.
- Household Supplies:Non-perishable categories absorb the highest post-consumer recycled content thresholds under California extended producer responsibility statutes. Detergent and cleaning product bulk packs prioritize cube utilization optimization over barrier properties, enabling faster fiber transitions.
- Personal Care:Cross-category bundling in combo pack formats lifts basket values where margin pools concentrate.
- Electronics:Fragility protection requirements sustain rigid plastic dominance despite state-level reduction mandates.
Established volume favors Household Supplies; emerging adoption favors Food & Beverage.
Packaging Type:
Format engineering trade-offs between handling efficiency and material compliance intensity vary by club channel operational model.
- Bulk Packaging:Pallet-ready corrugate structures with integrated handling apertures dominate unit economics in high-velocity categories. Sam's Club curbside fulfillment infrastructure creates demand for shelf-ready packs optimized for automated retrieval and damage reduction.
- Multi-Pack:Structural momentum concentrates in household supplies as club operators optimize warehouse cube utilization and reduce stockout frequency. Scan & Go technology integration opens white space for serialized bulk units that streamline inventory tracking.
- Combo Packs:Cross-category bundling concentrates margin pools in personal care where basket value expansion justifies format complexity.
- Trial Packs:Smaller unit configurations serve new member acquisition and category experimentation objectives.
Operational scale favors Bulk Packaging; technology convergence favors Multi-Pack.
Customer Type:
Procurement consolidation patterns reshape demand concentration across household and commercial endpoints.
- Retail Customers:Traditional household consumption patterns concentrate in Sun Belt migration corridors where population inflow clusters new club store openings.
- Wholesalers:Inventory economies drive secondary distribution channel sourcing from warehouse clubs.
- Businesses:Independent retailers and foodservice operators in Texas and Florida metropolitan zones now represent measurable B2B demand streams for bulk and combo pack formats, deepening penetration through dedicated membership tiers with customized credit terms.
- Institutions:Schools, healthcare facilities, and government entities consolidate procurement through club channels for standardized assortment and volume pricing.
Membership scale favors Retail Customers; fastest expansion trajectory sits with Businesses.
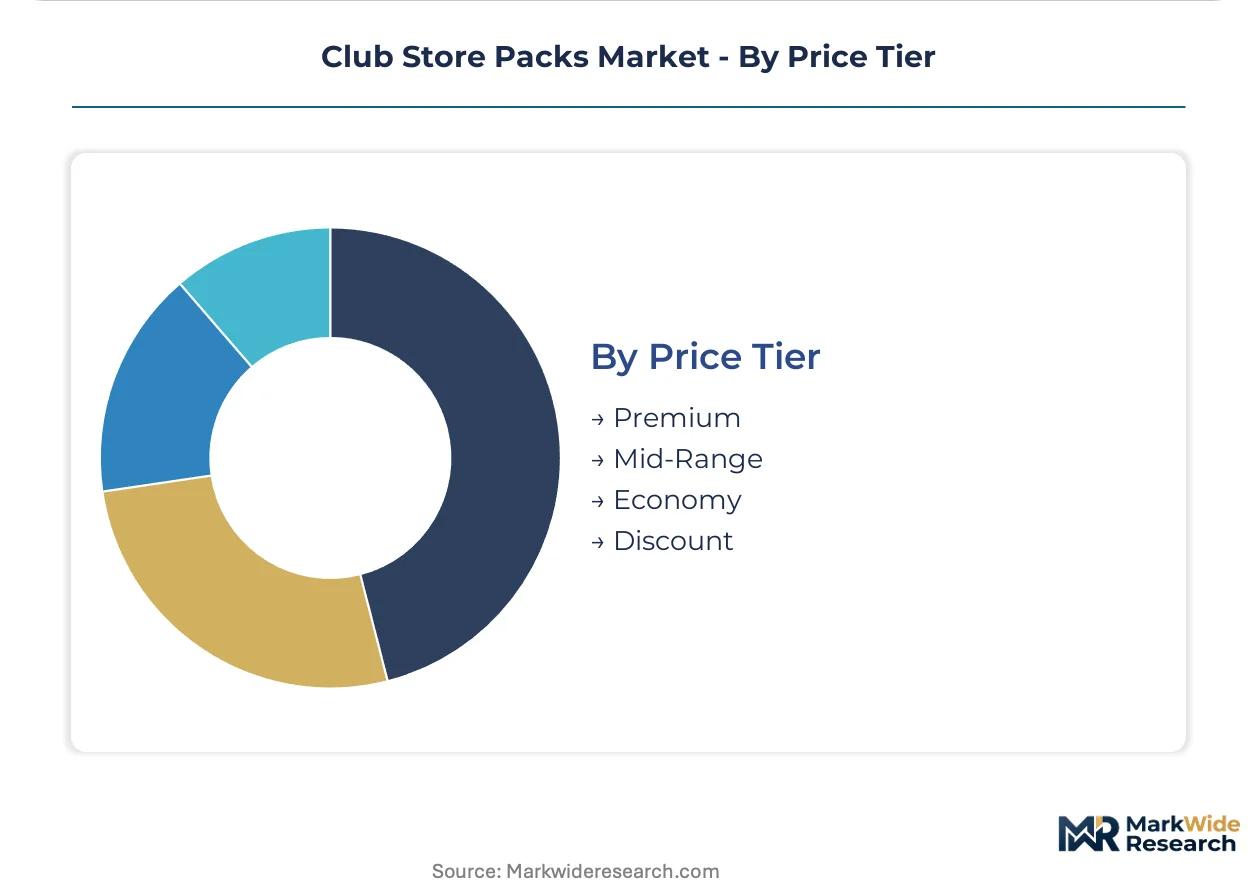
Price Tier:
Private label positioning and substrate cost structures stratify pack economics across consumption segments.
- Premium:Kirkland Signature and comparable private labels control shelf positioning through reinforced corrugate with high-visibility lithographic printing, capturing margin pools in categories where brand equity transfers to club-exclusive formats.
- Mid-Range:National brand multi-packs balance recognition value with volume discount mechanics.
- Economy:OCC fiber price volatility compresses margin predictability for converters serving price-sensitive segments where post-consumer recycled content thresholds add compliance cost layers.
- Discount:Promotional and closeout pack configurations serve inventory liquidation and member acquisition objectives.
Margin stability favors Premium; volume throughput favors Economy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States Sun Belt corridor while European converters absorb higher compliance costs under EPR frameworks. This asymmetry shapes investment allocation across fiber-based substrate transitions and pallet-ready format engineering.
United States
Texas and Florida metropolitan corridors cluster new club store openings alongside small business procurement consolidation. FDA food contact notification requirements govern substrate safety for edible product packaging, extending supplier qualification timelines. Houston and Miami anchor pilot programs for fiber-based frozen bulk SKUs with agricultural waste-derived barrier coatings.
California
Extended producer responsibility statutes force national pack specification convergence among multi-state suppliers. State-level plastic reduction mandates accelerate recyclable bulk packaging transitions, concentrating compliance costs in personal care and household supplies segments. Los Angeles and San Francisco Bay Area club operators prioritize post-consumer recycled content thresholds in procurement specifications.
Germany
REACH compliance frameworks pressure substrate innovators toward fiber alternative qualification before state-level plastic bans proliferate. ECHA substance restrictions reshape material selection for pallet-ready display structures. Bavaria and North Rhine-Westphalia host specialized packaging engineering firms optimizing cube utilization specifications.
China
SAMR quality supervision and GB standards govern rigid plastic component molding concentrated in Yangtze River Delta manufacturing zones. Dual carbon goals accelerate domestic fiber-based packaging capacity expansion. Shanghai and Suzhou industrial clusters supply reinforced corrugate structures to Southeast Asian converter networks.
Mexico
Nuevo León and Mexico City Metro corridors absorb nearshoring demand from US club operators seeking supply chain proximity. COFEPRIS food contact regulations align partially with FDA frameworks, easing cross-border substrate qualification. Monterrey-based converters specialize in pallet-ready lithographic printing for US-bound bulk pack exports.
Club Store Packs Market Competitive Landscape
Club operators and specialized converters split the market through divergent margin capture mechanisms. Three archetypes dominate: warehouse club chains controlling shelf positioning through private label expansion, regional packaging converters engineering pallet-ready specifications, and integrated retail conglomerates leveraging procurement scale. Competitive moves concentrate on curbside fulfillment infrastructure deployment and fiber-based substrate qualification ahead of regulatory deadlines.
Among US-based warehouse club chains, Costco Wholesale and Sam's Club exemplify operator archetypes competing through Kirkland Signature private label control versus Scan & Go technology integration. BJ's Wholesale Club occupies a position within the regional density-focused tier, anchoring Eastern US corridors with localized assortment strategies. These three entities represent how club operators compress supplier margins while dictating national pack specification standards.
| Leading Market Players |
|---|
| Costco Wholesale |
| Sam's Club |
| BJ's Wholesale Club |
| Walmart |
| Assemblies Unlimited |
| Creative Displays Now |
| Accurate Box Company |
| Transparent Container |
| PriceSmart |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta fiber substrate capacity expansion feeds directly into US club operator procurement leverage, compressing converter margins as pallet-ready specification demands intensify. Old corrugated container input swings translate unpredictably into pack economics, forcing tiered pricing structures that separate premium private label tiers from economy bulk configurations.
Pricing Analysis
Configured-to-order pallet-ready specifications command substantial premiums over standard bulk pack formats, with price differentiation driven by FDA food contact certification tiers and lithographic printing complexity. Premium private labels like Kirkland Signature capture margin pools through reinforced corrugate with high-visibility finishing, while economy segments suffer cost compression from OCC fiber volatility and post-consumer recycled content mandates. Small business buyers in Texas and Florida metropolitan zones exhibit highest price sensitivity, whereas institutional procurement through dedicated membership tiers absorbs premium positioning with minimal volume discount pressure.
Supply Chain Analysis
Upstream feedstock dynamics center on Chinese agricultural waste-derived barrier coating innovators and Vietnamese rigid plastic component molding clusters, with raw material dependencies spanning OCC fiber streams, post-consumer recycled resin grades, and lithographic ink formulations. Single-source vulnerability concentrates in Southeast Asian manufacturing zones where regional logistics disruptions cascade into club channel stockout risk. Distribution runs through regional converter networks anchored in Monterrey and Nuevo León for US-bound pallet-ready exports, with final-mile coordination managed through club operator curbside fulfillment infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across US states creates supplier qualification niches, as California EPR statutes and New York pending mandates force format redesign cycles that reward agile substrate innovators.
For Market Incumbents: Pre-empt fiber-based qualification bottlenecks by anchoring engineering talent pools in Bavaria and North Rhine-Westphalia packaging clusters before FDA notification timelines extend. Vertical integration into agricultural waste-derived barrier coating capacity secures margin capture in perishable bulk SKUs where emerging entrants threaten specification control. Defensive patent positioning around water-resistant fiber hybridization blocks substitute technology displacement in frozen club pack categories.
For New Entrants and Emerging Players: Build out curbside-optimized shelf-ready pack capabilities targeting Sam's Club automated retrieval infrastructure as the most penetrable white-space channel. Texas and Florida metropolitan corridors offer geographic entry points where small business procurement consolidation outpaces incumbent capacity expansion. Go-to-market positioning through Scan & Go RFID serialization differentiates against legacy batch-tracking systems lacking API compatibility with club operator platforms.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized packaging engineering firms with demonstrated FDA food contact notification success and cube utilization optimization credentials. Long-term viability over the next decade hinges on substrate innovators qualifying fiber alternatives ahead of state plastic ban proliferation. The signal to watch is California EPR enforcement intensity accelerating national pack specification convergence beyond voluntary compliance thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Fiber-Based Substrate Qualification | California EPR statutes force national pack specification convergence among multi-state suppliers. |
| Curbside Fulfillment Pack Optimization | Sam's Club automated retrieval infrastructure creates demand for damage-resistant shelf-ready configurations. |
| Scan & Go RFID Integration | Serialized bulk units streamline inventory tracking for club operators deploying mobile checkout technology. |
| Agricultural Waste Barrier Coating Scale-Up | Houston and Miami pilot programs validate moisture protection for fiber-based frozen SKU penetration. |
| Small Business Membership Tier Expansion | Texas and Florida foodservice operators deepen B2B demand streams through customized credit terms. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA food contact notification databases, EPA sustainable materials management frameworks, and state-level EPR statute filings. Packaging engineering directors at specialized converter firms, club operator category managers, and substrate innovation leads provided qualitative input. SEC filings from warehouse club chains, customs records for corrugated container trade flows, and municipal recycling collection rate data furnished secondary validation. Bottom-up SKU-level volume estimates triangulated against top-down channel revenue analysis.
Forecast inputs incorporate product type segmentation across food and beverage, household supplies, personal care, and electronics categories; packaging type dimensions spanning bulk, multi-pack, combo, and trial configurations; and customer type stratification among retail, wholesale, business, and institutional endpoints. CAGRs were derived from trend extrapolation moderated by regulatory phase-in assumptions and club store opening pipelines across Sun Belt corridors. Fiber substrate cost trajectories and post-consumer recycled content threshold compliance costs informed industry-specific forecast adjustments.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated retail conglomerates or rapid EPR enforcement acceleration would shift outcomes beyond modeled ranges. Cross-checking against club operator capital expenditure disclosures and state legislative tracking databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Chewing Gum Market
Packaged Foods
Mexico Packaged Food Products Market
Packaged Foods
Breakfast Food Market
Packaged Foods
Asia-Pacific Sweet Biscuits Market
Packaged Foods
Europe Breakfast Cereals Market
Packaged Foods
Reduced Fat Packaged Food Market
Packaged Foods
Instant Soup Market
Packaged Foods
Dried Soup Market
Packaged Foods
Instant Noodles Market
Packaged Foods
Packaged Vegan Foods Market
Packaged Foods
United Kingdom Food Spreads Market
Packaged Foods
Singapore Ready-To-Eat Food Market
Packaged Foods
North America Instant Noodles Market
Packaged Foods
Canned Goods Market
Packaged Foods
Cookie Pucks Market
Packaged Foods
US Canned Foods Market