
 Reduced Fat Packaged Food Market | 2026-2036
Reduced Fat Packaged Food Market Size, Share, and Industry Trends Forecast 2026-2036
Reduced Fat Packaged Food Market Analysis
A capital-intensity divergence between multinational dairy specialists and snack conglomerates is rotating competitive investment toward proprietary fat-replacement technologies. Danone S.A. leverages its fermentation expertise to sustain clean-label positioning in reduced-fat yogurt. Mondelēz Global LLC anchors its portfolio through reformulated biscuit platforms that compete on taste parity.
Reduced fat packaged food encompasses industrially manufactured items with fat content lowered by at least 25 percent versus standard formulations, typically achieved through emulsion restructuring, protein-based fat mimetics, or water-binding hydrocolloids to preserve mouthfeel and shelf stability. The category serves retail and foodservice channels seeking compliance with nutritional labeling regimes without sacrificing sensory performance. Snacks and dairy segments lead volume contribution, with fortified ingredient variants commanding premium placement in health food shops and online retail. Low-fat and light classifications occupy mature supermarket shelf sets, while reduced-fat condiments and deli meats represent faster-growing margin pools as protein-forward diets expand.
The FDA enforces nutrient content claims and serving-size disclosures that dictate permissible "reduced" and "light" descriptors, directly influencing formulation targets and label architecture. EFSA's health claim authorization framework under EU Regulation 1924/2006 constrains which physiological benefits manufacturers may communicate, shaping European R&D priorities and market access conditions. Stakeholders must monitor evolving front-of-package warning systems and sugar-reduction mandates that increasingly couple with fat-modification requirements.
Market Dynamics
Clean-label mandates from FDA and EFSA are forcing simultaneous fat reduction and ingredient list simplification, compressing the viable formulation space for reformulated snacks and dairy.
Growth Catalysts
- Front-of-Package Labeling Mandates:FDA disclosure requirements for added sugars and saturated fat push manufacturers toward reformulation. Retailers in the United States expand dedicated reduced-fat shelf space to capture health-conscious millennial shoppers.
- Fermentation-Derived Fat Mimetics:Protein-based texturizing systems derived from microbial fermentation achieve mouthfeel parity in reduced-fat yogurt applications. Clean-label positioning commands premium placement in urban health food channels.
- Urban Snack Consumption Patterns:Office workers in Tokyo, Berlin, and New York City drive single-serve reduced-fat packaged snack adoption. Convenience formats align with protein-forward dietary trends among younger demographics.
Market Restraints
- Specialty Ingredient Cost Volatility:Hydrocolloid stabilizers and protein isolates face supply pressure from agricultural commodity swings. Reformulation economics tighten when input costs exceed standard fat pricing.
- Technical Sensory Limitations:Water-binding systems struggle to replicate fat's flavor-carrying capacity in fried snack applications. Taste parity gaps persist in certain biscuit and cracker categories despite emulsion advances.
- Regulatory Claim Friction:EFSA's health claim authorization framework under EU Regulation 1924/2006 constrains permissible physiological benefit communication. European R&D priorities narrow to compliant formulation targets.
Strategic Opportunities
- Reduced-Fat Condiment White Space:Mayonnaise, dressings, and spreads remain underpenetrated versus snacks and dairy. Protein-forward diet expansion creates margin pool expansion in deli meat accompaniments.
- Foodservice Channel Penetration:Institutional buyers in Germany and Japan seek compliant reduced-fat bases for menu development. Bulk format adoption lags retail, offering volume scaling potential.
- Sugar-Fat Dual Reformulation:Front-of-package warning systems in select jurisdictions couple sugar reduction with fat modification. Integrated formulation platforms capture regulatory tailwind advantages.
Industry Challenges
- Clean-Label Talent Scarcity:Food scientists skilled in natural emulsion restructuring and fermentation-derived texturizers command premium compensation. R&D pipeline velocity constrains competitive response timing.
- Legacy Equipment Retrofit Costs:Existing production lines require capital-intensive modification to handle altered viscosity profiles and water-activity levels in reduced-fat formulations.
- Dual Certification Complexity:Simultaneous USDA organic and non-GMO verification extends timeline to shelf for reformulated products. Compliance documentation burdens smaller mid-cap specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reduced Fat Packaged Food Market |
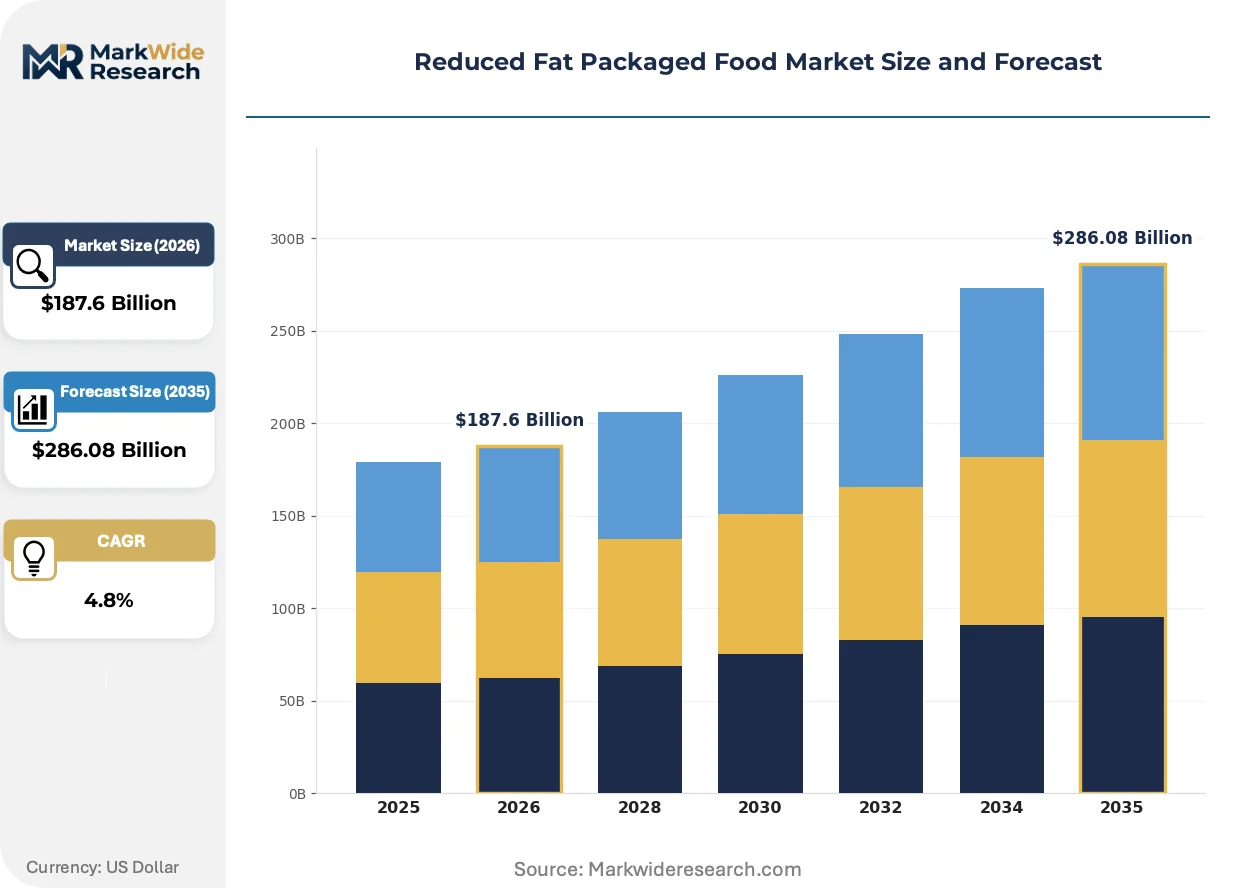
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $286.08 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Snacks, Dairy, Condiments, Deli Meats Ingredient Type: Low-Fat, Reduced-Fat, Light, Fortified Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Health Food Shops Consumer Segment: Health-Conscious, Diabetic, Weight Watchers, Families |
| Companies Covered | Danone S.A., The Kraft Heinz Company, Nestlé S.A., Unilever PLC, Mondelēz Global LLC, General Mills Inc., PepsiCo, Inc., Arla Foods Inc., Kellogg Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reduced Fat Packaged Food Market Emerging Trajectories
Active reformulation is compressing the gap between sensory performance and nutritional compliance. Technology convergence and regulatory disclosure mandates are reshaping competitive investment priorities across the value chain.
Micro-encapsulated flavor systems are displacing traditional fat-based flavor carriers in reduced-fat cracker and biscuit applications. Mid-tier snack manufacturers in the United States adopt these systems to maintain taste parity without clean-label penalties. The technology is displacing older spray-dried flavor methods that required higher fat loads for stability.
EFSA's evolving interpretation of nutrient profiles under EU Regulation 1924/2006 is tightening permissible health claim thresholds for reduced-fat products. Manufacturers must now demonstrate compositional superiority beyond simple fat reduction to retain marketing advantages. Dairy segments in Germany and France face the steepest reformulation requirements as front-of-package scoring systems expand.
Direct-to-consumer subscription models for reduced-fat specialty snacks are fragmenting traditional retail concentration. Urban millennials in Tokyo and New York bypass conventional grocery channels for curated monthly deliveries. This channel shift is most visible in premium fortified variants that command price premiums unavailable in mass retail.
Reduced Fat Packaged Food Market Segmentation
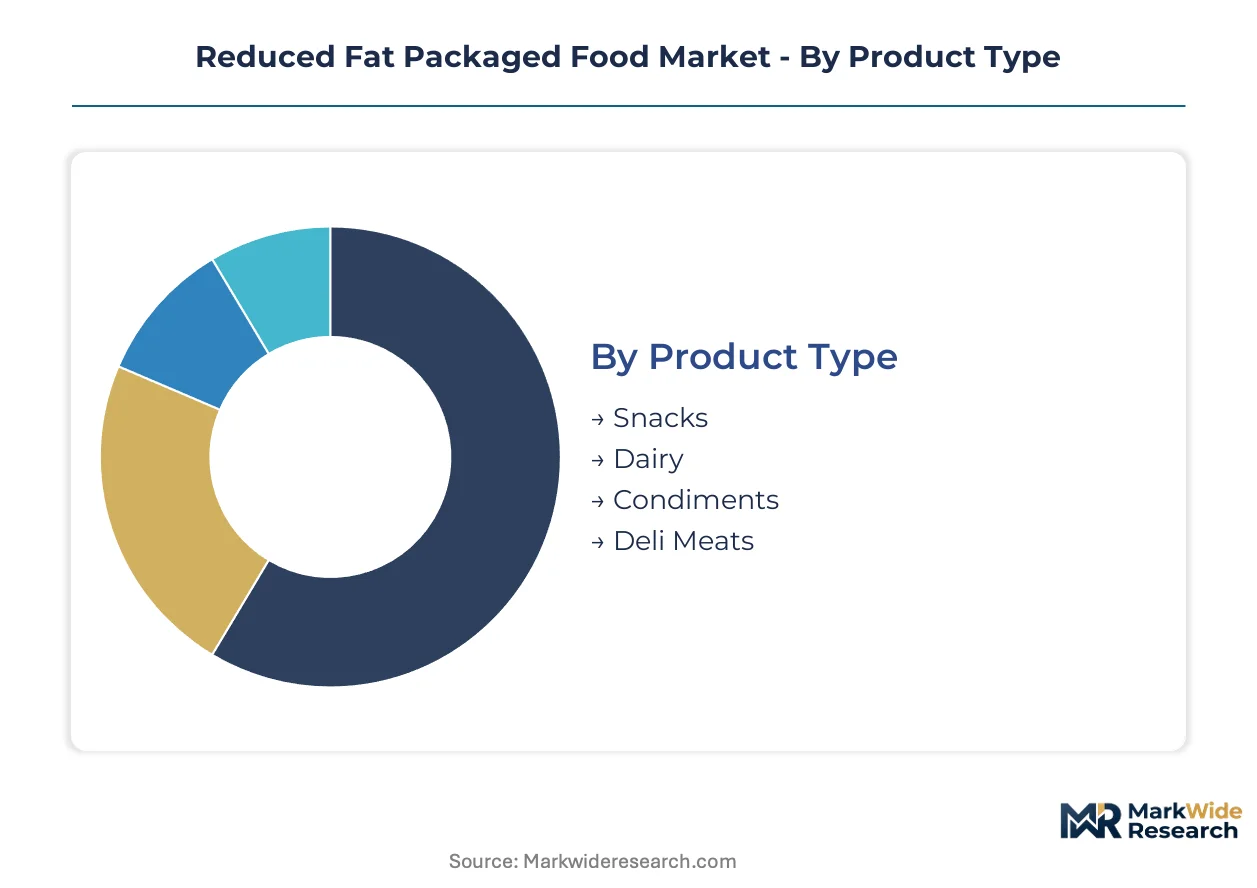
Segmentation in reduced fat packaged food determines formulation architecture, channel strategy, and regulatory compliance pathways. Product and ingredient classifications dictate permissible health claims, while distribution and consumer dimensions shape pricing and placement decisions.
Product Type:
FDA and EFSA labeling thresholds vary by product category, forcing distinct reformulation investments across snacks versus dairy versus condiments.
- Snacks:Cracker, biscuit, and chip formulations achieve fat reduction through emulsion restructuring and micro-encapsulated flavor systems. Demand concentrates in single-serve formats for office workers in Tokyo, Berlin, and New York City where convenience aligns with protein-forward dietary trends. Taste parity gaps persist in fried applications despite hydrocolloid advances.
- Dairy:Yogurt and cheese variants leverage fermentation-derived protein texturizers to maintain mouthfeel at lower fat loads. German and French retailers face steepest reformulation requirements as front-of-package scoring systems expand, compressing viable formulation space for clean-label positioning.
- Condiments:Mayonnaise, dressings, and spreads remain underpenetrated versus snacks and dairy, creating white space for protein-forward diet expansion in deli meat accompaniments.
- Deli Meats:Fat-modified sliced meats target foodservice institutional buyers in Germany and Japan seeking compliant menu development bases.
Snacks handles the majority of throughput; condiments is gaining share fastest as protein-forward diets expand meal-accompaniment demand.
Ingredient Type:
Cost tier differentiation separates mass-market penetration from premium placement in health food channels.
- Low-Fat:Formulations meeting strict regulatory thresholds for fat content claims command standard supermarket shelf placement. Urban millennials in the United States drive adoption through dedicated reduced-fat shelf space expansion.
- Reduced-Fat:Products achieving 25 percent minimum fat reduction versus standard formulations represent the technical baseline for the category. EFSA's health claim authorization framework under EU Regulation 1924/2006 constrains permissible physiological benefit communication, narrowing European R&D priorities to compliant targets.
- Light:Descriptors require precise serving-size disclosures per FDA mandates, directly influencing label architecture and portion control packaging.
- Fortified:Added micronutrient variants achieve premium placement in health food shops and online retail channels, commanding price premiums unavailable in mass retail.
Reduced-Fat maintains volume leadership across retail channels; fortified is expanding most quickly through direct-to-consumer subscription models in Tokyo and New York.
Distribution Channel:
Channel selection determines margin structure and customer acquisition economics, with digital fragmentation reshaping traditional retail concentration.
- Supermarkets:Mature shelf sets for low-fat and light classifications dominate volume, with retailers in the United States, Germany, and Japan expanding dedicated reduced-fat space to capture health-conscious millennial shoppers.
- Online Retail:Direct-to-consumer subscription models fragment traditional concentration, enabling curated monthly deliveries of premium fortified variants that bypass conventional grocery channels.
- Convenience Stores:Single-serve formats align with urban snack consumption patterns among office workers seeking protein-forward options.
- Health Food Shops:Clean-label positioning and fermentation-derived fat mimetics achieve premium placement, with microbial fermentation expertise commanding urban channel access.
Supermarkets handle the majority of throughput; online retail is climbing the fastest as millennial subscription adoption accelerates.
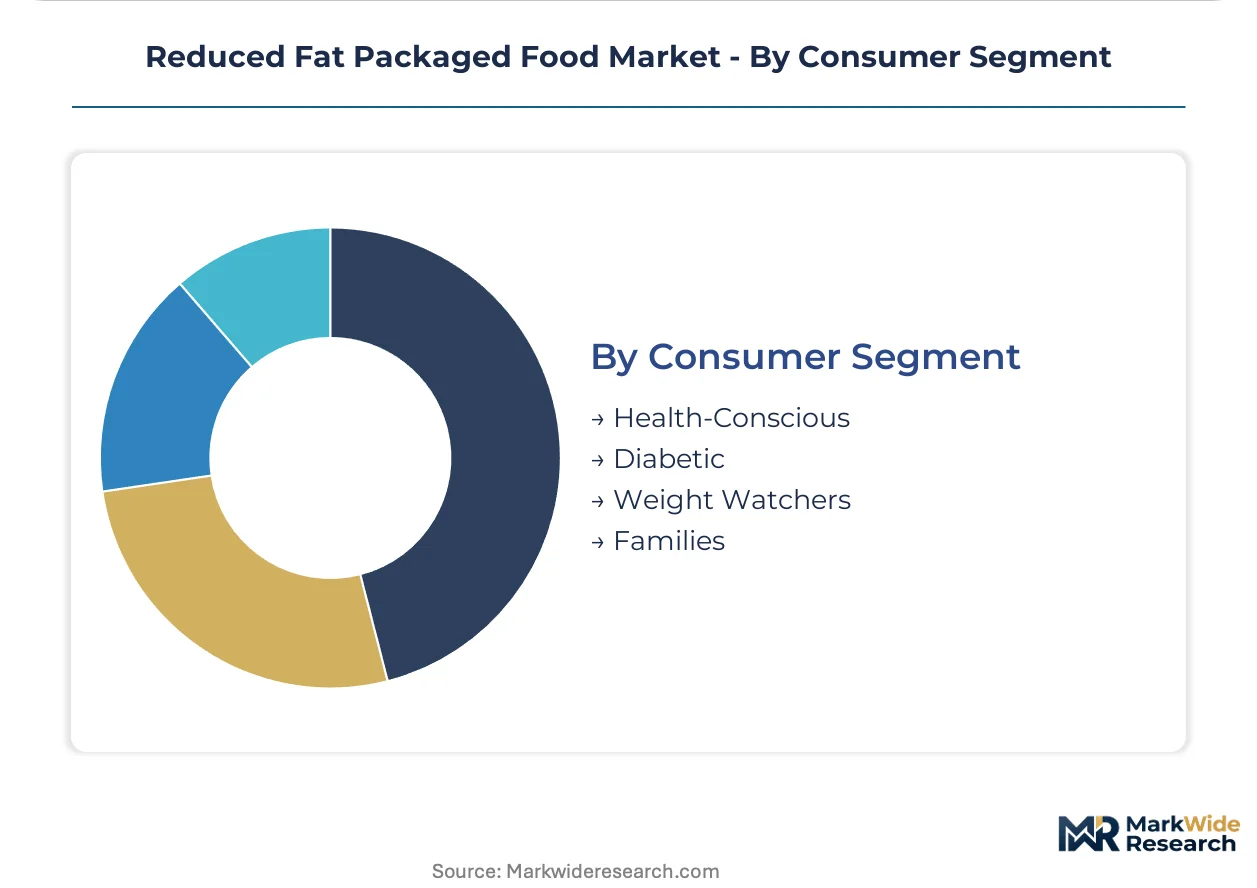
Consumer Segment:
Application-specific dietary requirements drive formulation intensity and certification burden, from diabetic glycemic management to family-oriented taste parity.
- Health-Conscious:Urban millennials prioritize clean-label ingredient lists alongside fat reduction, forcing simultaneous simplification and nutritional compliance. FDA disclosure requirements for added sugars and saturated fat push manufacturers toward integrated reformulation platforms.
- Diabetic:Glycemic management requirements couple fat modification with carbohydrate control, creating dual reformulation complexity under front-of-package warning systems in select jurisdictions.
- Weight Watchers:Calorie-counting frameworks demand precise portion control and transparent labeling, favoring single-serve packaging formats.
- Families:Taste parity requirements intensify as household purchasing decisions prioritize acceptance across age demographics, constraining water-binding system adoption in categories where flavor-carrying capacity gaps persist.
Health-Conscious handles the majority of throughput; diabetic is gaining share fastest as sugar-fat dual reformulation mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where retailers command dedicated reduced-fat shelf space, while Japanese consumers absorb premium positioning for fermentation-derived clean-label products. Urban millennial density in Tokyo, Berlin, and New York City drives format innovation and subscription channel penetration. Regulatory fragmentation between FDA disclosure mandates and EFSA health claim constraints forces multinationals to maintain parallel formulation portfolios.
United States
Millennial health consciousness and front-of-package labeling mandates from the FDA reshape supermarket shelf architecture. Retailers expand dedicated reduced-fat space to capture urban office-worker demand. New York City and Los Angeles anchor single-serve snack innovation where convenience formats align with protein-forward dietary trends.
Germany
EFSA's evolving interpretation of nutrient profiles under EU Regulation 1924/2006 compresses permissible health claim thresholds. Front-of-package scoring systems expand across Bavaria and North Rhine-Westphalia, forcing steepest reformulation requirements in yogurt and cheese segments. Berlin retailers pilot integrated sugar-fat dual reformulation platforms ahead of broader European adoption.
Japan
Tokyo office workers drive premium adoption of fermentation-derived fat mimetics in reduced-fat dairy applications. METI standards on nutritional disclosure align with clean-label positioning in urban health food channels. Osaka and Nagoya clusters concentrate R&D investment in microbial fermentation expertise for mouthfeel parity.
United Kingdom
Post-regulatory alignment with EU frameworks maintains EFSA-constrained health claim authorization while allowing national flexibility on front-of-package implementation. London health food shops command premium placement for fortified variants. Midlands manufacturing bases retrofit legacy equipment to handle altered viscosity profiles in reformulated condiments.
France
Dairy segment concentration in Île-de-France and Auvergne-Rhône-Alpes faces tightening compositional superiority requirements beyond simple fat reduction. ANSM oversight of nutritional claims intersects with EFSA frameworks. Lyon and Paris retail clusters drive clean-label talent competition among fermentation specialists.
Reduced Fat Packaged Food Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with fermentation specialists commanding premium positioning while scale manufacturers optimize standard emulsion platforms. The vendor base separates into three tiers: multinational dairy conglomerates with captive R&D infrastructure, snack conglomerates leveraging cross-category formulation expertise, and mid-cap clean-label specialists dependent on external ingredient partnerships. Dominant competitive moves include strategic partnerships for proprietary fat-replacement licensing and geographic expansion through direct-to-consumer subscription channels.
Among European dairy conglomerates, Danone S.A. and Arla Foods Inc. exemplify the fermentation-technology archetype, occupying positions where microbial expertise commands urban health food channel access. Nestlé S.A. and Unilever PLC represent diversified multinationals with cross-category formulation platforms spanning snacks, dairy, and condiments. Mondelēz Global LLC anchors the snack-specialist tier with reformulated biscuit portfolios competing on taste parity. These named entities illustrate how competitive positioning fragments between clean-label premium vectors and scale-driven mass-market penetration.
| Leading Market Players |
|---|
| Danone S.A. |
| The Kraft Heinz Company |
| Nestlé S.A. |
| Unilever PLC |
| Mondelēz Global LLC |
| General Mills Inc. |
| PepsiCo, Inc. |
| Arla Foods Inc. |
| Kellogg Co. |
| Others |
Supply Flow & Price Mechanics
Scale economies in hydrocolloid stabilizer production anchor price floors across reduced-fat formulation tiers, concentrating margin leverage among multinational ingredient suppliers while compressing viable pricing bands for mid-tier snack manufacturers. Capacity utilization at protein isolate facilities in the United States and Germany directly shapes the customization-premium spread that separates mass-market emulsion platforms from fermentation-derived clean-label alternatives.
Pricing Analysis
The customization-premium spread separates standard emulsion-based formulations from fermentation-derived protein texturizers, with the latter commanding placement premiums in urban health food channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—USDA organic and non-GMO verification tiers lift shelf price positioning. Pricing pressure stems from specialty ingredient cost volatility as agricultural commodity swings tighten reformulation economics. Health-conscious urban millennials show lowest price sensitivity for clean-label positioning, while family-oriented segments prioritize taste parity at standard price points.
Supply Chain Analysis
Soy protein isolate processing concentration in the United States and Brazil creates chokepoint vulnerability for water-binding hydrocolloid systems deployed across reduced-fat dairy applications. Microbial fermentation capacity clusters in Germany and Japan supply protein-based fat mimetics, while palm-derived emulsifier sourcing rests on Southeast Asian agricultural processing. Single-source vulnerability intensifies as EFSA health claim authorization narrows approved ingredient lists. Distribution runs through supermarket retail concentration in the United States, Germany, and Japan, with direct-to-consumer subscription channels fragmenting downstream access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as retail consolidation in the United States and Germany expands dedicated reduced-fat shelf space, shifting margin capture toward category captains with formulation scale.
For Market Incumbents: Shield clean-label positioning through captive fermentation infrastructure investments that lock in microbial expertise scarcity. Defend against mid-cap clean-label specialists by securing exclusive hydrocolloid supply agreements. Priority lever: backward integration into protein isolate processing to buffer agricultural commodity volatility. For New Entrants and Emerging Players: Direct-to-consumer subscription service gaps in condiment categories offer white-space penetration where incumbent snack and dairy concentration leaves mayonnaise and dressing segments underdeveloped. Target foodservice institutional buyers in Germany and Japan seeking compliant reduced-fat bases for menu development. Go-to-market angle: curated monthly deliveries of fortified variants bypassing supermarket slotting fee barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fermentation-technology specialists with proprietary fat-replacement licensing pipelines. Long-term viability favors mid-cap clean-label players with established urban health food channel access rather than scale manufacturers facing legacy equipment retrofit burdens. Signal to watch: front-of-package warning system expansion coupling sugar-fat dual reformulation mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Technology Licensing | Proprietary microbial expertise unlocks premium placement in EFSA-regulated European markets. |
| Direct-to-Consumer Channel Launch | Subscription models bypass retailer slotting fees and capture urban millennial price premiums. |
| Clean-Label Certification Investment | Dual USDA organic and non-GMO verification commands shelf positioning in health food channels. |
| Foodservice Bulk Format Expansion | Institutional buyer adoption in Germany and Japan offers volume scaling beyond retail concentration. |
| Sugar-Fat Dual Reformulation Platform | Integrated formulation captures regulatory tailwind as FDA and EFSA couple disclosure mandates. |
Methodological Framework
A spread of perspectives from R&D directors at multinational dairy conglomerates, category buyers at German and Japanese retailers, fermentation technology specialists, and regulatory affairs leads converged on the working assumptions. Primary interviews combined with secondary validation from FDA guidance documents, EFSA health claim authorization databases, Nielsen retail audit data, and customs records on hydrocolloid and protein isolate trade flows. Bottom-up volume modeling triangulated against top-down market sizing across the projection horizon.
Segmentation dimensions modeled include product type (snacks, dairy, condiments, deli meats), ingredient classification (low-fat, reduced-fat, light, fortified), distribution channel (supermarkets, online retail, convenience stores, health food shops), and consumer segment (health-conscious, diabetic, weight watchers, families). CAGRs were derived from trend extrapolation calibrated to regulatory milestone impacts. Forecast inputs incorporated front-of-package labeling mandate rollout schedules and fermentation technology adoption curves.
Forecasts assume regulatory continuity in FDA disclosure frameworks and EFSA health claim authorization regimes; material policy shifts would require re-modeling. Specific risk factors include sugar-reduction mandate coupling that accelerates dual reformulation cost burdens, and agricultural commodity price spikes that destabilize hydrocolloid economics. Practitioners should keep alternative scenarios live as front-of-package scoring system expansion and clean-label talent scarcity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Packaged Zhug Market
Packaged Foods
Convenience Food Market
Packaged Foods
Food and Beverages Market
Packaged Foods
Dinner Ready-To-Eat (RTE) Food Market
Packaged Foods
Chestnut Flour Market
Packaged Foods
Burritos Market
Packaged Foods
Asia-Pacific Sweet Biscuits Market
Packaged Foods
High-End Instant Noodles Market
Packaged Foods
Organic Energy Bar Market
Packaged Foods
Injectable Cocoa Fillings Market
Packaged Foods
Global Packed Food Market
Packaged Foods
Pastry Fillings Market
Packaged Foods
Prepared Flour Mixes Market
Packaged Foods
Cereal Flakes Market
Packaged Foods
Dehydrated and Dried Beans Market
Packaged Foods
Canned Beans Market