
 Japan Packaged Food Products Market | 2026-2036
Japan Packaged Food Products Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Packaged Food Products Market Insights
Convenience store procurement fragmentation is expanding across Japan's retail landscape as Seven-Eleven Japan, Lawson, and FamilyMart diversify supplier bases beyond traditional keiretsu relationships. Meiji Holdings leverages its dairy and confectionery integration to sustain shelf presence in these channels. NH Foods anchors the processed meat segment through chilled distribution networks that dominate suburban Tokyo and Osaka corridors. Yamazaki Baking competes aggressively in bakery-style packaged goods, while Kikkoman controls the soy sauce and seasoning pouch categories that convenience stores rely upon for bento assembly.
Japan packaged food products encompass shelf-stable and refrigerated consumables sealed in barrier materials to extend edibility without immediate preparation, typically employing retort sterilization, aseptic filling, or modified atmosphere packaging to achieve 3–24 month stability at ambient or chilled conditions. Frozen meals lead product type revenue pools due to aging demographics seeking minimal-preparation dinner solutions, while flexible packaging displaces rigid formats as manufacturers respond to METI plastic reduction guidelines. Instant noodles occupy a mature volume position with thin margin profiles, whereas premium price tier offerings in vacuum-packed prepared foods capture disproportionate profit concentration in Tokyo and Kansu urban centers.
PMDA oversees food additive safety approvals under the Food Sanitation Act, while JIS standards govern packaging material specifications for migration limits and recyclability compliance. METI's Resource Circulation Strategy for Plastics forces reformulation of multilayer films, directly elevating R&D costs for manufacturers serving convenience store and household channels. Stakeholders must monitor whether upcoming container deposit legislation in prefectural assemblies accelerates glass jar adoption for premium sauces and preserves, reshaping packaging type investment priorities without awaiting national mandate consolidation.
Market Dynamics
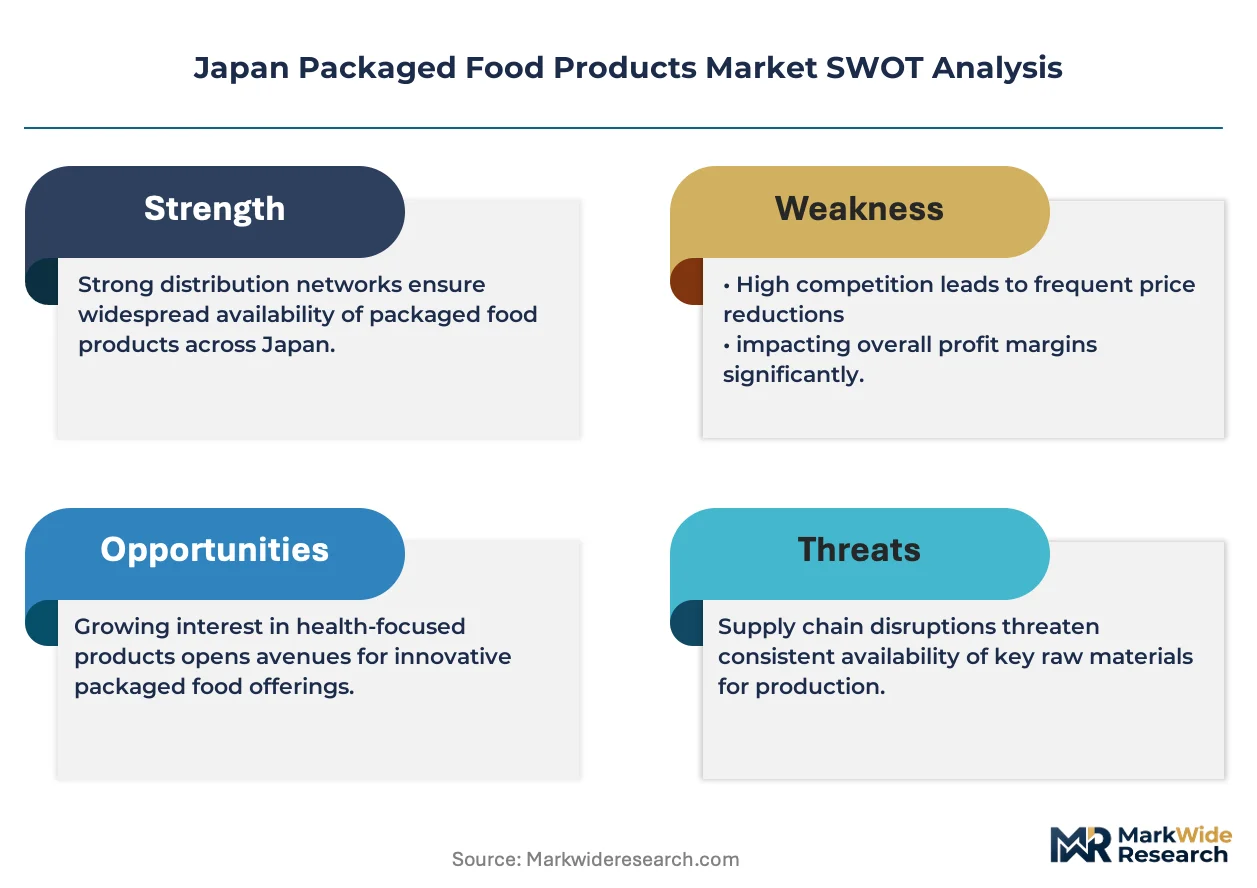
METI's Resource Circulation Strategy for Plastics is forcing multilayer film reformulation across Japan's convenience store supply chains, elevating R&D costs while compressing margin structures for mid-tier manufacturers.
Growth Catalysts
- Urban household density:Greater Tokyo's single-person household concentration drives demand for portion-controlled, shelf-stable meals requiring minimal preparation infrastructure.
- Food Recycling Law revisions:METI's packaging sustainability mandates create first-mover advantages for manufacturers investing in mono-material barrier films ahead of compliance deadlines.
- Chilled distribution network expansion:Processed meat and prepared food categories leverage NH Foods' suburban Tokyo-Osaka corridor infrastructure to extend product freshness windows.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and polyethylene resin prices fluctuate with naphtha cracking economics, squeezing flexible packaging converters serving private-label convenience store programs.
- Keiretsu procurement lock-in:Traditional supplier relationships between Seven-Eleven Japan and legacy dairy processors limit market access for emerging plant-based entrants.
- Retort sterilization energy intensity:Natural gas price exposure at thermal processing facilities elevates unit costs for shelf-stable rice and curry pouch production.
Strategic Opportunities
- Kansai premium corridor:Osaka and Kyoto urban centers underindex in vacuum-packed prepared food penetration relative to Tokyo, presenting white space for bento-style chilled meals.
- Prefectural container deposit trials:Glass jar adoption for premium sauces and preserves accelerates in Hyogo and Fukuoka assemblies ahead of national mandate consolidation.
- Mono-material film + digital printing convergence:Recyclable barrier packaging paired with variable-data labeling enables convenience store chains to execute hyperlocal promotional campaigns.
Industry Challenges
- Migration testing bottleneck:PMDA's food additive safety approval timelines extend 18-24 months for novel barrier coatings, delaying product launches.
- Legacy ERP integration:Mid-tier manufacturers struggle to connect batch-level traceability systems with METI's impending digital waste-tracking requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Packaged Food Products Market |
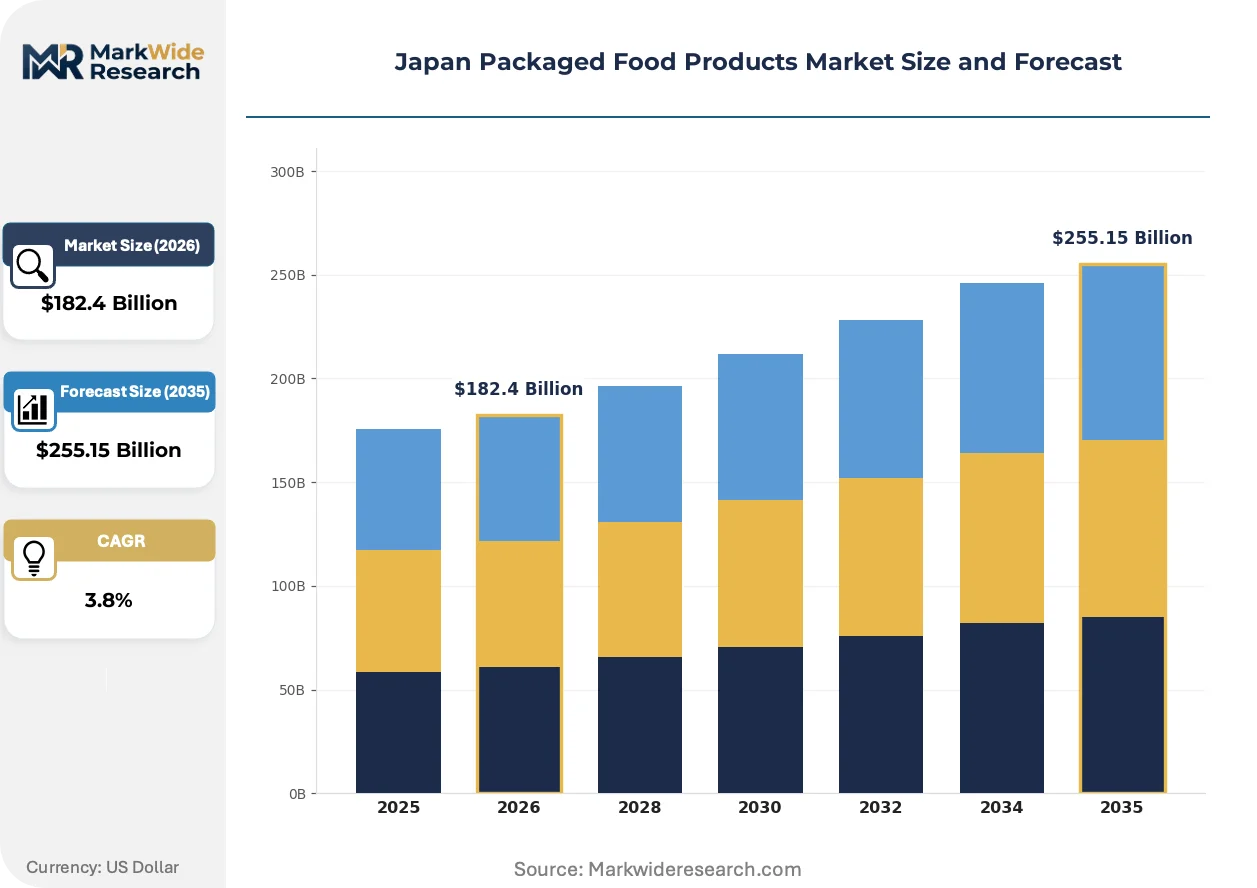
| Market Size in 2026 | $182.4 Billion |
| Market Size in 2035 | $255.15 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Meals, Snacks, Instant Noodles, Canned Goods Packaging Type: Flexible Packaging, Rigid Containers, Vacuum Packs, Glass Jars End User: Households, Restaurants, Convenience Stores, Catering Services Price Tier: Premium, Mid-Range, Budget, Discount |
| Companies Covered | Meiji Holdings Co. Ltd, NH Foods Ltd, Ajinomoto Co., Inc., Kewpie Corp, Yamazaki Baking Co. Ltd, Kikkoman Corp, Nissin Foods Holdings Co.,Ltd., Nisshin Seifun Group, Inc., Toyo Suisan Kaisha Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Packaged Food Products Market Trends and Innovations
Japan's packaged food sector is experiencing simultaneous pressure from regulatory packaging mandates and shifting urban consumption patterns, with technology investment concentrating on shelf-life extension and material circularity.
Mono-material polypropylene barrier films with enhanced oxygen scavenging properties are electrifying the flexible packaging segment. Yamazaki Baking and chilled prepared food specialists adopt these films at accelerated pace to maintain JIS-compliant migration limits while satisfying METI recyclability targets. The technology is electrifying competitive positioning by enabling premium price tiers previously reserved for multilayer constructions.
METI's Resource Circulation Strategy for Plastics mandates 25% recycled content in household plastic packaging by 2030, with interim reporting obligations beginning in 2025. Manufacturers serving convenience store channels face immediate reformulation costs for retort pouches and seasoning sachets. The processed meat and frozen meal segments absorb disproportionate compliance burden due to stringent barrier requirements.
Single-person households in dense urban corridors now purchase packaged food through convenience store mobile ordering with designated pickup lockers. This channel innovation displaces traditional supermarket weekly stock-up trips among Tokyo's under-40 demographic. The behavior shift concentrates demand volatility in Greater Tokyo's 23 wards, forcing manufacturers to compress production batch cycles.
Japan Packaged Food Products Market Segmentation
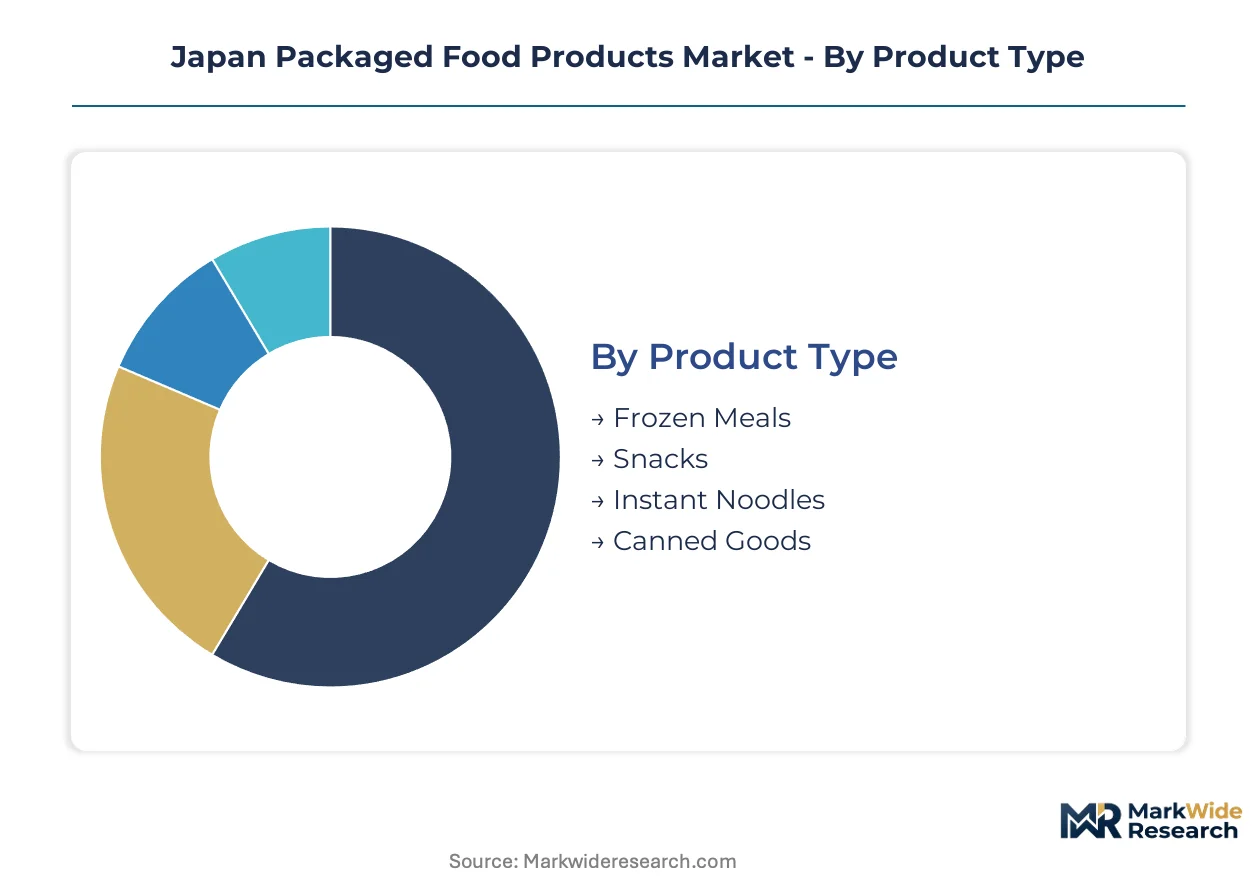
Segmentation in Japan's packaged food market reveals how METI regulatory pressure and convenience store channel evolution concentrate investment across specific product configurations. Understanding these divides exposes where margin compression and first-mover advantages collide.
Product Type:
Supply concentration clusters around categories demanding specialized thermal processing infrastructure and chilled distribution networks.
- Frozen Meals:Complete dinner solutions requiring blast freezing and -18°C logistics chains. Demand concentrates in Greater Tokyo's single-person households where microwave preparation replaces cooking infrastructure. METI plastic guidelines force tray-to-film transitions that elevate unit costs.
- Instant Noodles:Shelf-stable wheat flour blocks with dehydrated seasoning sachets. Volume leadership masks thin margins; manufacturers defend position through portion-size fragmentation targeting convenience store lunch-hour traffic.
- Snacks:Confectionery and savory items employing modified atmosphere packaging.
- Canned Goods:Retort-sterilized vegetables, fish, and curry products in steel or aluminum containers.
Frozen meals absorb the bulk of installed capacity; snacks are expanding most quickly.
Packaging Type:
Cost tier differentiation separates premium shelf presence from mass-market efficiency.
- Flexible Packaging:Multilayer films and emerging mono-material barriers for retort pouches and snack bags. Premium tiers in Tokyo and Osaka command price multiples for matte-finish digital printing and oxygen-scavenging liners compliant with JIS migration limits.
- Vacuum Packs:Barrier film enclosures with oxygen evacuation for processed meats and prepared foods. Chilled distribution through NH Foods' suburban Tokyo-Osaka corridors extends freshness windows for convenience store bento assembly.
- Rigid Containers:Polypropylene and polyethylene tubs for refrigerated salads and deli items.
- Glass Jars:Premium sauces and preserves facing prefectural deposit trial momentum in Hyogo and Fukuoka.
Flexible packaging absorbs the bulk of installed capacity; glass jars are climbing the fastest on sustainability positioning.
End User:
Application concentration tracks urban household density and foodservice labor shortages.
- Households:Weekly stock-up purchases at supermarkets and online platforms. Single-person units in Tokyo's 23 wards displace bulk buying with convenience store mobile ordering and pickup locker retrieval.
- Convenience Stores:24-hour retail chains diversifying private-label portfolios beyond traditional keiretsu relationships. Mobile pre-ordering concentrates demand volatility, forcing manufacturers into compressed batch cycles.
- Restaurants:Ingredient sourcing for menu items and staff meal programs.
- Catering Services:Bento and buffet provisioning for corporate and institutional clients.
Households absorb the bulk of installed capacity; convenience stores are gaining share fastest on channel innovation.
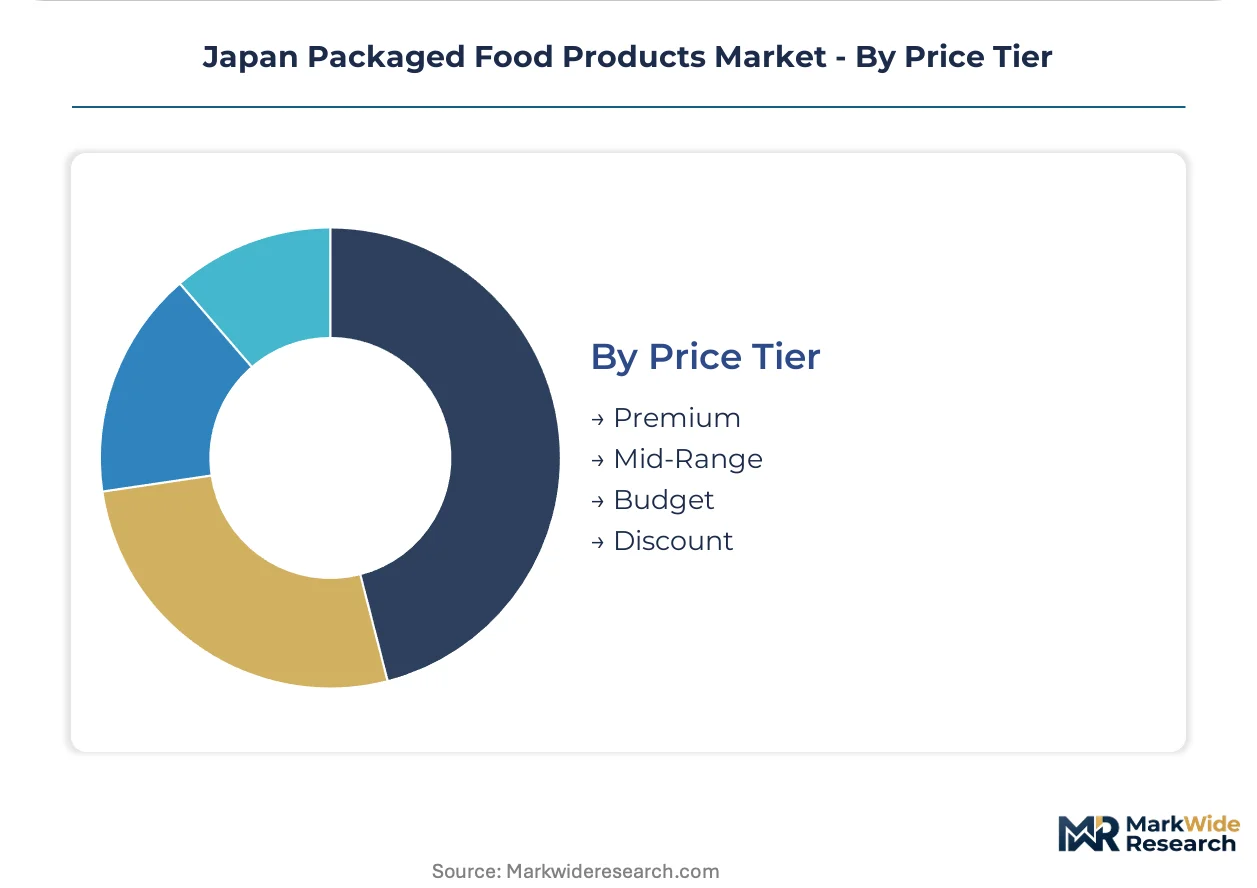
Price Tier:
Customer type stratification mirrors urban income polarization and aging demographic sensitivity to preparation time versus cost.
- Premium:Vacuum-packed prepared foods and artisanal preserves with extended shelf-life claims. Tokyo and Kansai urban centers underindex in penetration relative to latent demand, creating white space for bento-style chilled meals.
- Mid-Range:Standard frozen meals and retort curry pouches balancing quality signals with accessibility.
- Budget:Value-positioned instant noodles and canned vegetables for price-sensitive households.
- Discount:Private-label offerings through convenience store chains leveraging procurement fragmentation.
Premium absorbs the bulk of profit concentration; discount is expanding most quickly on private-label proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock availability from the Keiyo Industrial Zone anchors packaged food production across eastern Japan. Chilled distribution networks radiate from this coastal corridor to serve dense urban consumption clusters. METI's regional industrial policy reinforces this geographic concentration through infrastructure subsidies.
Kanto/Tokyo
Single-person households in the 23 wards drive demand for portion-controlled frozen meals and retort pouches. METI's Food Recycling Law revisions apply stringent packaging compliance timelines to manufacturers operating within the capital region. Seven-Eleven Japan and Lawson headquarters in Tokyo concentrate procurement decision-making for national convenience store networks.
Kansai/Osaka
Osaka and Kyoto urban centers underindex in vacuum-packed prepared food penetration relative to latent demand capacity. PMDA's regional inspection offices coordinate food additive safety approvals for manufacturers across the western corridor. NH Foods anchors processed meat distribution through chilled logistics hubs in suburban Osaka.
Chubu/Nagoya
Automotive industry density supports bento and prepared meal demand from factory shift workers. JIS standards enforcement from Nagoya-based certification bodies governs packaging material specifications for regional converters. Aichi prefecture's food manufacturing clusters specialize in retort-sterilized curry and rice pouch production.
Kyushu
Fukuoka prefectural assembly trials container deposit legislation for glass jar packaging of premium sauces and preserves. METI's Resource Circulation Strategy for Plastics imposes recycled content mandates on regional flexible packaging converters. Local soy sauce and seasoning manufacturers face elevated reformulation costs for mono-material barrier compliance.
Hokkaido
Dairy and wheat flour raw material production supports packaged bread and confectionery manufacturing for national distribution. Cold chain infrastructure investments from the Ministry of Agriculture extend frozen meal shelf-life windows for remote prefecture delivery. Sapporo-based food processors leverage lower energy costs for thermal processing operations.
Japan Packaged Food Products Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue plant-based and functional food adjacencies through differentiated positioning. The market exhibits tiered concentration with integrated dairy-confectionery groups, chilled protein specialists, and seasoning conglomerates commanding distinct shelf-space allocations. Three archetypes dominate: keiretsu-anchored legacy processors, convenience store supply chain integrators, and regional fermentation specialists. Competitive moves center on backward integration into raw material sourcing and mono-material packaging R&D partnerships with film converters.
Within the integrated dairy-confectionery tier, Meiji Holdings Co. Ltd and NH Foods Ltd exemplify scale-driven vertical control from ingredient processing through retail distribution. Among seasoning and condiment specialists, Kikkoman Corp occupies a position reflecting centuries-long fermentation expertise adapted to pouch and sachet convenience formats. Yamazaki Baking Co. Ltd represents the bakery-style packaged goods archetype, competing through chilled distribution density in Greater Tokyo's convenience store channels.
| Leading Market Players |
|---|
| Meiji Holdings Co. Ltd |
| NH Foods Ltd |
| Ajinomoto Co., Inc. |
| Kewpie Corp |
| Yamazaki Baking Co. Ltd |
| Kikkoman Corp |
| Nissin Foods Holdings Co.,Ltd. |
| Nisshin Seifun Group, Inc. |
| Toyo Suisan Kaisha Ltd |
| Others |
Pricing and Supply Chain Analysis
Premium-mid-economy pricing differentiation across Japan's packaged food sector manifests in divergent supply chain configurations, with premium vacuum-packed prepared foods commanding dedicated chilled distribution networks while budget instant noodles flow through high-volume, low-margin Keiyo Industrial Zone corridors. METI's recycled content mandates compress margins most severely in mid-tier retort pouches, forcing manufacturers to absorb reformulation costs or surrender shelf space to private-label convenience store alternatives.
Pricing Analysis
Warranty-equivalent freshness guarantees separate premium vacuum-packed prepared foods from unbundled budget instant noodles, with oxygen-scavenging film technology and extended shelf-life claims justifying price multiples in Tokyo's 23 wards. Three-tier pricing structure across premium, standard, and economy levels tracks JIS migration compliance tiers and mono-material barrier adoption status. Pricing pressure stems from polypropylene resin volatility squeezing flexible packaging converters serving Seven-Eleven Japan's private-label programs. Budget instant noodle buyers exhibit highest price sensitivity, while premium chilled meal purchasers prioritize preparation convenience over per-unit cost.
Supply Chain Analysis
Regional distribution centers radiating from the Keiyo Industrial Zone anchor national replenishment, with hub-and-spoke patterns extending frozen meal cold chains to Greater Tokyo's convenience store networks. Domestic production concentrates in Chiba and Kanagawa prefectures, with Hokkaido dairy inputs and Kyushu soy sauce fermentation supplying critical raw materials. Supply chain risk centers on single-source vulnerability for oxygen-scavenging film substrates from limited domestic converters. Distribution runs through NH Foods' suburban Tokyo-Osaka chilled corridors for processed meats, while ambient shelf-stable goods leverage consolidated truckload routing to supermarket distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's packaged food market represents a consolidation play as METI packaging compliance costs and convenience store procurement fragmentation force sub-scale manufacturers toward exit or acquisition. Smaller players lacking mono-material R&D partnerships or backward integration into film converting face irreversible margin compression.
For Market Incumbents: Anticipate keiretsu relationship erosion by diversifying supplier portfolios beyond traditional Seven-Eleven Japan and Lawson networks before emerging plant-based entrants capture shelf space. Prioritize captive supply of mono-material barrier films through partnerships with Chiba-based converters to defend margin position against METI-mandated reformulation costs. Accelerate digital printing capabilities for hyperlocal promotional campaigns targeting convenience store mobile ordering platforms.
For New Entrants and Emerging Players: Launch via direct-to-convenience-store distribution models bypassing legacy keiretsu procurement lock-in, targeting the Kansai premium corridor where vacuum-packed prepared food penetration underindexes relative to latent demand capacity. Prioritize Osaka and Kyoto urban centers for bento-style chilled meal introduction, leveraging NH Foods' underutilized suburban chilled infrastructure. Pursue mono-material film certification ahead of national mandate consolidation to establish first-mover positioning.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-tier retort pouch specialists with stranded multilayer film assets and insufficient R&D scale to achieve METI compliance deadlines. Long-term viability hinges on backward integration into packaging material production or captive convenience store channel relationships. Watch prefectural container deposit legislation momentum in Hyogo and Fukuoka as inflection indicator for glass jar premium sauce segment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Barrier Film Adoption | METI's 2030 recycled content mandates force reformulation of multilayer retort pouches for JIS compliance. |
| Chilled Distribution Network Expansion | NH Foods' Tokyo-Osaka corridor infrastructure extends freshness windows for convenience store bento assembly. |
| Digital Printing + Variable Data Labeling | Enables Seven-Eleven Japan and Lawson to execute hyperlocal promotional campaigns through mobile ordering platforms. |
| Prefectural Container Deposit Preparation | Hyogo and Fukuoka assembly trials signal glass jar adoption acceleration for premium sauces ahead of national mandates. |
| Plant-Based Protein Portfolio Entry | Keiretsu procurement lock-in creates white space for differentiated positioning in convenience store channels. |
Research Methodology
Independent corroboration across convenience store category managers, flexible packaging converters, and METI policy specialists underwrites the qualitative findings in this analysis. Primary interviews with chilled distribution logistics directors, mono-material film R&D leads, and private-label procurement officers at Lawson and FamilyMart combined with secondary validation from JIS standards documentation, PMDA food additive safety filings, and prefectural assembly legislative records. Bottom-up demand modeling across Tokyo's 23 wards and top-down supply capacity assessment from Keiyo Industrial Zone production data provided triangulation anchors.
Rate-of-change decomposition across the projection horizon separates volume growth from price tier mix shifts and packaging format transitions. Segmentation dimensions modeled include product type, packaging material configuration, end-user channel, and regional consumption cluster. CAGRs derived from historical production volume trends adjusted for METI regulatory phase-in schedules and convenience store channel share trajectories. Industry-specific forecast inputs incorporate polypropylene resin price volatility assumptions and PMDA approval timeline distributions for novel barrier coatings.
Feedstock price shocks, PMDA approval delays for oxygen-scavenging formulations, and prefectural container deposit legislation acceleration are the dominant revision risks that could alter trajectory assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Global Aseptic Packaging in Food Market
Packaged Foods
Spreads Market
Packaged Foods
High-End Instant Noodles Market
Packaged Foods
Asia-Pacific Breakfast Cereals Market
Packaged Foods
Iran Breakfast Cereals Market
Packaged Foods
Ready Meals Market
Packaged Foods
Instant Noodles Market
Packaged Foods
Wet Food Pouch Market
Packaged Foods
China Packaged Food Products Market
Packaged Foods
Wet Pet Food Market
Packaged Foods
Plant Focused Dips Market
Packaged Foods
Mexico Packaged Food Products Market
Packaged Foods
Prepared Flour Mixes Market
Packaged Foods
Instant Ramen Market
Packaged Foods
Instant Rice Market
Packaged Foods
Eco Bowls Market