
 Pasta and Noodles Market | 2026-2036
Pasta and Noodles Market Size, Share, and Industry Trends Forecast 2026-2036
Pasta and Noodles Market Intelligence
Buyer concentration among Asian quick-service restaurant chains is hardening as regional franchise networks consolidate purchasing decisions across thousands of outlets. Nestlé S.A. leverages its Maggi brand infrastructure to anchor supply contracts with these expanding foodservice operators. Barilla Group competes through specialized durum wheat sourcing that sustains premium positioning in European retail channels. Nissin Foods Holdings Co., Ltd. dominates instant noodle innovation with localized flavor R&D facilities across multiple Asian markets.
Pasta and noodles comprise wheat-based or alternative-flour dough products formed into elongated or shaped configurations, then dried, fresh-frozen, or pre-cooked through extrusion, lamination, or flash-frying processes to deliver shelf-stable carbohydrate staples for household and commercial meal preparation. Dry pasta occupies the largest value pool in European and North American retail, while instant noodles generate the fastest volume growth across emerging Asian foodservice channels. Gluten-free ingredient formulations command premium shelf placement as celiac certification and rice-flour processing technology mature.
FDA nutrition labeling rules and USDA organic certification standards shape product formulation and market access for North American suppliers, while EFSA's Farm to Fork additive restrictions and EU Green Deal sustainability metrics redirect European manufacturing toward reduced-emission durum wheat processing. China's SAMR enforces GB standards for instant noodle sodium content and packaging integrity. Stakeholders must monitor diverging regulatory thresholds for sodium reduction, clean-label claims, and carbon footprint disclosure across these jurisdictions to align R&D investment with compliance requirements.
Market Dynamics
Quick-service restaurant chains across Southeast Asia are consolidating procurement decisions into centralized purchasing hubs, compressing supplier margins while demanding customized instant noodle formulations at foodservice scale.
Growth Catalysts
- Urban corridor demand concentration:Indonesia's Jakarta-Surabaya axis generates sustained volume pull from rising middle-class households and expanding franchise networks.
- EFSA Farm to Fork additive restrictions:Clean-label mandates are accelerating reformulation investments that open premium shelf placement for compliant manufacturers.
- Flash-frying process improvements:Energy-efficient frying technology reduces production costs for instant noodle lines serving price-sensitive emerging markets.
Market Restraints
- Durum wheat supply concentration:Canadian and Australian harvest volatility transmits directly into input cost instability for premium pasta manufacturers.
- Sodium reduction mandates:China's SAMR GB standards enforce strict caps that degrade taste profiles and increase R&D expenditure for flavor recovery.
- Fresh-frozen substitution threat:Refrigerated pasta formats in European retail are capturing convenience-oriented consumers from traditional dry pasta.
Strategic Opportunities
- Rice-flour gluten-free convergence:Celiac certification protocols combined with improved extrusion technology are opening premium positioning in North American specialty retail.
- Direct-to-foodservice channel expansion:Bypassing wholesale distributors to contract directly with consolidated QSR chains captures margin and locks volume commitments.
- USDA organic certification tailwind:Organic durum wheat sourcing commands price premiums in US natural grocery channels with expanding shelf allocation.
Industry Challenges
- Clean-label reformulation timelines:EFSA additive prohibitions require 18-24 month certification cycles that delay product launches and strain R&D bandwidth.
- Legacy equipment retrofit costs:Transitioning extrusion lines to handle alternative flours demands capital outlays that mid-tier manufacturers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pasta and Noodles Market |
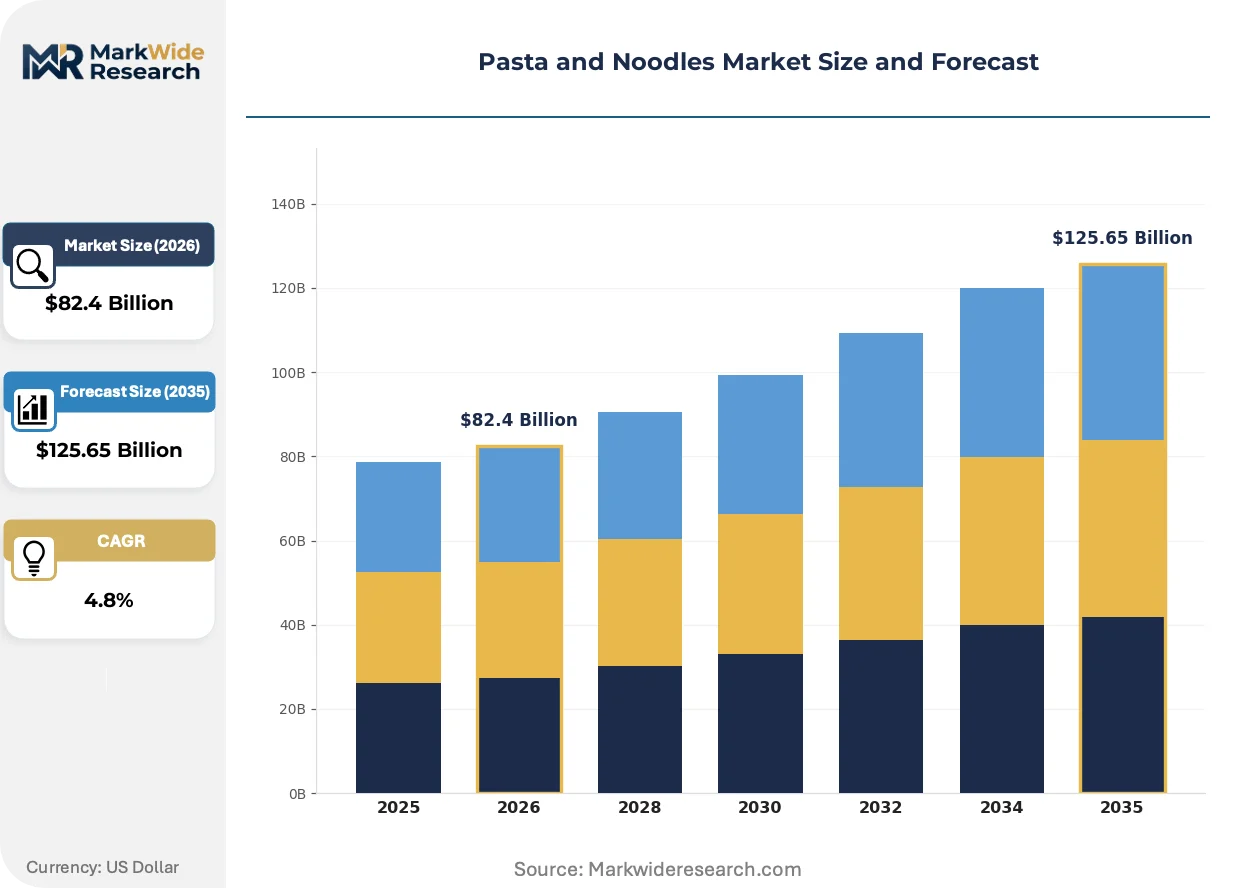
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $125.65 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Pasta, Fresh Pasta, Frozen Noodles, Instant Noodles Ingredient Type: Wheat Flour, Rice Flour, Gluten-Free, Egg Noodles Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesale End User: Households, Restaurants, Foodservice, Catering |
| Companies Covered | Nestlé S.A., Barilla Group, Nissin Foods Holdings Co., Ltd., The Kraft Heinz Company, Conagra Brands, Inc., The Campbell Soup Company, Unilever PLC, Ebro Foods S.A., Toyo Suisan Kaisha, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pasta and Noodles Market Strategic Shifts & Innovations
Extrusion technology advances and regulatory pressure on sodium and additive content are forcing simultaneous reinvention of product formulation and manufacturing processes across both retail and foodservice channels.
High-pressure extrusion systems with precision temperature control are rewriting the texture possibilities for gluten-free pasta made from rice, chickpea, and lentil flours. European specialty manufacturers are adopting these systems to serve celiac-certified retail segments that previously accepted inferior mouthfeel. The technology is compressing the quality gap between wheat and alternative-flour products, enabling premium pricing in health-focused channels.
EFSA's phased implementation of Farm to Fork additive restrictions is eliminating synthetic preservatives and colorants from European processed staple foods. Reformulation costs are falling disproportionately on instant noodle producers reliant on established flavor enhancement protocols. Manufacturers are responding with natural fermentation-derived alternatives that extend shelf life without triggering mandatory warning labels.
Consolidated procurement by Southeast Asian QSR chains is compressing supplier negotiation cycles and demanding dedicated production lines for customized formulations. Foodservice operators in Indonesia and Vietnam are replacing fragmented wholesale purchasing with direct manufacturer contracts that specify sodium levels, portion sizing, and regional flavor profiles. This concentration is visible across the Jakarta-Bandung-Surabaya corridor where franchise density supports dedicated supply infrastructure.
Pasta and Noodles Market Segmentation
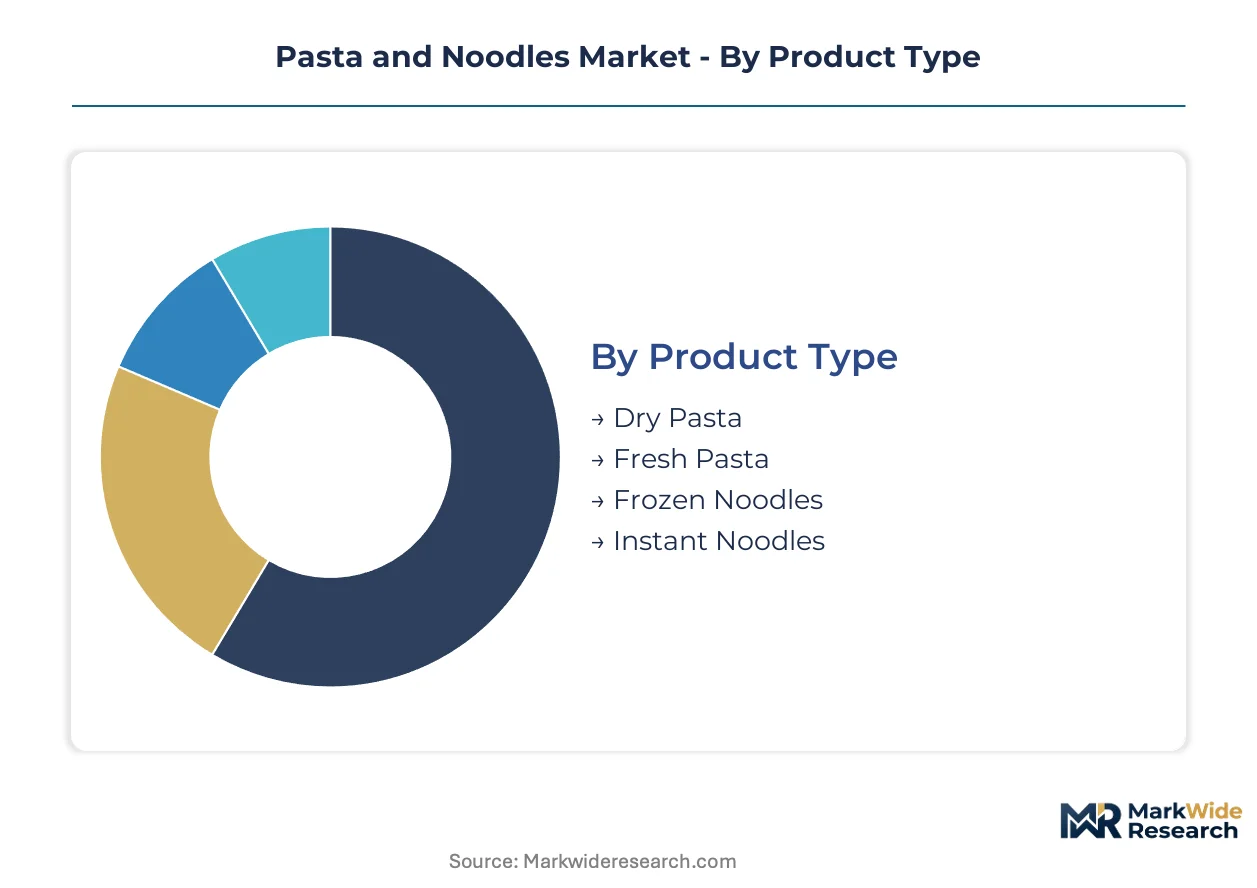
Pasta and noodles manufacturers align production assets with distinct demand profiles across product formats, ingredient specifications, and channel requirements. Segmentation discipline determines capital allocation between shelf-stable retail lines and customized foodservice production.
Product Type:
Extrusion and preservation technology defines shelf stability, rehydration speed, and margin structure across consumption occasions.
- Dry Pasta:Durum wheat semolina extruded through bronze or Teflon dies creates porous or smooth surfaces that hold sauce differently. European retail channels in Italy and France sustain volume concentration for traditional semolina formats, though refrigerated alternatives are displacing share in convenience-oriented urban households.
- Instant Noodles:Wheat-flour dough steamed and flash-fried or air-dried delivers sub-three-minute preparation. Southeast Asian QSR chains from Jakarta to Ho Chi Minh City are consolidating procurement of customized instant formats with specified sodium levels and portion sizing.
- Fresh Pasta:Refrigerated distribution limits geographic reach but commands premium positioning in specialty retail.
- Frozen Noodles:Blast-frozen precooked strands serve foodservice operators requiring extended holding times without texture degradation.
Mature deployment sits with Dry Pasta. Newer deployment is concentrated in Instant Noodles.
Ingredient Type:
Raw material sourcing strategy and certification requirements segment manufacturers by technical capability and price positioning.
- Wheat Flour:Hard wheat varieties with protein content above 12 percent deliver the gluten network required for al dente texture in extruded pasta. Canadian and Australian harvest volatility transmits directly into input cost instability for manufacturers dependent on premium durum supply.
- Gluten-Free:Rice, chickpea, and lentil flours processed through high-pressure extrusion systems now achieve texture parity with wheat-based products. North American specialty retail channels with celiac certification protocols are expanding shelf allocation for these formulations.
- Rice Flour:Traditional Asian noodle base with distinct mouthfeel properties in fresh and dried applications.
- Egg Noodles:Enriched dough with whole egg content creates yellow color and tender bite profile.
Conventional wheat dominates volume scale. Gluten-Free formats are climbing the fastest on certification tailwinds.
Distribution Channel:
Channel selection determines pack sizing, margin retention, and relationship intensity with downstream buyers.
- Supermarkets:Multi-SKU shelf sets with tiered pricing across private-label and branded offerings. European retail consolidation in Germany and France is compressing slotting fee negotiations while demanding clean-label compliance.
- Wholesale:Pallet-scale distribution to foodservice operators and institutional buyers. Southeast Asian QSR procurement hubs are bypassing traditional distributors for direct manufacturer contracts with customized formulation requirements.
- Online Retail:Subscription and bulk formats gaining traction in North American urban markets.
- Convenience Stores:Single-serve instant noodle cups and ready-to-eat pasta meals targeting immediate consumption.
Established volume flows through Supermarkets. Direct Wholesale contracting is gaining share fastest on foodservice consolidation.
End User:
Final consumption context dictates portion engineering, sodium targets, and preparation instruction complexity.
- Restaurants:Customized dry and fresh pasta specifications with defined cook times and sauce adhesion properties. Italian full-service chains in Milan and Rome maintain stringent supplier qualification programs around bronze-extruded heritage formats.
- Foodservice:High-volume institutional feeding with cost-controlled instant noodle and frozen pasta formats. Indonesian franchise networks from Jakarta to Surabaya are specifying regional flavor profiles and sodium-reduced formulations at contract scale.
- Households:Retail pack sizes with preparation flexibility for variable household composition.
- Catering:Bulk formats with holding stability for event service environments.
Restaurant procurement sustains premium positioning. Foodservice volume is expanding most quickly on QSR network growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's urban corridor from Jakarta to Surabaya concentrates demand volume for instant noodle formats, while regulatory divergence across FDA, EFSA, and SAMR jurisdictions shapes manufacturer compliance strategies worldwide.
United States
USDA organic certification standards and FDA nutrition labeling rules drive premium positioning in natural grocery channels. The USDA enforces strict durum wheat sourcing protocols for organic pasta claims. California's specialty food manufacturers lead gluten-free innovation with rice-flour extrusion systems serving celiac-certified retail segments.
Italy
Heritage durum wheat pasta consumption sustains volume in traditional retail, though refrigerated formats displace dry pasta share in Milan and Rome convenience-oriented households. EFSA's Farm to Fork Strategy tightens additive restrictions on processed staple foods. Emilia-Romagna's bronze-extrusion specialists maintain supplier qualification programs with full-service restaurant chains.
China
SAMR enforces GB standards for instant noodle sodium content and packaging integrity, forcing reformulation investments from manufacturers serving domestic foodservice. The regulator's strict caps degrade taste profiles and increase R&D expenditure for flavor recovery. Shanghai's procurement hubs consolidate purchasing for QSR networks spanning the Yangtze River Delta.
Indonesia
Rising middle-class households and expanding franchise networks generate sustained volume pull across the Jakarta-Bandung-Surabaya axis. The national food and drug regulator monitors sodium labeling compliance for processed staple imports. Surabaya's foodservice operators specify regional flavor profiles and sodium-reduced formulations at contract scale.
Germany
EU Green Deal sustainability metrics redirect manufacturing toward reduced-emission durum wheat processing for export-oriented pasta producers. EFSA additive prohibitions require 18-24 month certification cycles that delay product launches. Bavaria's specialty manufacturers adopt high-pressure extrusion systems to serve celiac-certified retail segments across European markets.
Pasta and Noodles Market Key Industry Players
European producers anchor one tier; Asian specialists hold instant noodle innovation capacity. The vendor base stratifies across three tiers: multinational conglomerates with diversified pantry portfolios, regional wheat-millers with captive semolina supply, and niche gluten-free formulators with alternative-flour extrusion expertise. Consolidation pressure intensifies as Southeast Asian QSR chains centralize procurement into fewer supplier relationships. Competitive moves center on direct-to-foodservice channel expansion and clean-label reformulation certification.
Among diversified consumer goods conglomerates, Nestlé S.A. and Unilever PLC occupy positions defined by brand infrastructure scale and cross-category pantry presence. Barilla Group exemplifies the heritage durum wheat specialist archetype with European retail anchoring. Nissin Foods Holdings Co., Ltd. represents the Asian instant noodle innovation tier with localized flavor R&D capabilities. These three anchors illustrate the geographic and capability split shaping competitive dynamics.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Barilla Group |
| Nissin Foods Holdings Co., Ltd. |
| The Kraft Heinz Company |
| Conagra Brands, Inc. |
| The Campbell Soup Company |
| Unilever PLC |
| Ebro Foods S.A. |
| Toyo Suisan Kaisha, Ltd. |
| Others |
Cost & Logistics Intelligence
Extrusion equipment specialists concentrated in Emilia-Romagna and Stuttgart anchor premium tier spreads, with labor-cost differentials between European heritage manufacturers and Southeast Asian flash-frying operators creating pricing-tier spreads across instant noodle and dry pasta categories.
Pricing Analysis
Volume scale separates commodity instant noodles from premium bronze-extruded pasta, with pricing stratifying across premium, standard, and economy tiers. Certification grade under EFSA Farm to Fork protocols and USDA organic standards drives price differentiation alongside volume scale and geographic delivery cost. Cost compression in foodservice instant noodles is intensifying because Southeast Asian QSR procurement consolidation demands customized formulations at contract scale. Household retail segments show least price sensitivity for heritage durum wheat formats, while institutional foodservice buyers exhibit maximum price elasticity.
Supply Chain Analysis
Domestic-content mandates under Indonesia's national food regulator and China's SAMR GB standards are reshaping sourcing toward localized wheat milling and regional flavor ingredient procurement. Supply concentrates in Canada, Australia, and Italy for premium durum wheat semolina, while flash-fried instant noodle production centers on Indonesia, Vietnam, and China. Raw material dependencies include Canadian durum wheat, Australian hard wheat varieties, and palm oil for frying processes. Single-source vulnerability in Canadian harvest cycles creates structural risk. Distribution runs through consolidated QSR procurement hubs bypassing traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where EFSA additive prohibition timelines and clean-label certification costs force weaker capitalized manufacturers toward exit or acquisition.
For Market Incumbents: To counter Southeast Asian QSR procurement consolidation, anchor direct-to-foodservice contracts with sodium-reduced formulation capabilities and lock volume commitments through dedicated production line investments. Backward integration into durum wheat sourcing mitigates Canadian harvest volatility exposure. For New Entrants and Emerging Players: Direct-to-consumer subscription channels offer white-space entry with celiac-certified gluten-free pasta formats targeting North American specialty retail. Premium rice-flour extrusion systems serve underpenetrated European health-food channels. Partner with established co-manufacturers to bypass legacy equipment retrofit capital requirements. For Investors and Strategic Acquirers: Re-rating potential sits with gluten-free formulators possessing high-pressure extrusion expertise given EFSA clean-label mandates accelerating premium positioning. Long-term viability favors manufacturers with dual capability across wheat and alternative-flour processing. Watch SAMR sodium enforcement stringency as inflection indicator for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Certification | EFSA Farm to Fork compliance unlocks premium shelf placement in European retail consolidation. |
| Direct-to-Foodservice Channel Expansion | Bypassing wholesale distributors captures margin from Indonesian QSR procurement hub consolidation. |
| Alternative-Flour Extrusion Scale-Up | High-pressure systems for rice and chickpea flours serve celiac-certified North American specialty retail. |
| Backward Integration into Durum Wheat | Captive sourcing from Canadian and Australian suppliers insulates against harvest volatility transmission. |
| Regional Flavor R&D Localization | Jakarta and Surabaya innovation facilities lock contract scale with Indonesian franchise network specifications. |
Research Approach
Trade publications, customs databases, and regulatory filings formed the secondary backbone, supplemented by primary interviews with extrusion equipment manufacturers, QSR procurement directors, and durum wheat commodity traders. Category buyers at European retail consolidators and foodservice supply planners at Indonesian franchise operators provided downstream demand validation. Bottom-up capacity assessments across Italian and Southeast Asian production facilities were triangulated against top-down consumption estimates from household panel data.
Historical trendline analysis across production volume, trade flows, and price indices established baseline growth patterns. Segmentation modeling incorporated product format, ingredient certification tier, distribution channel, and end-use application dimensions. CAGRs were derived from slope analysis of normalized trendlines adjusted for regulatory phase-in schedules and procurement consolidation trajectories. SAMR enforcement intensity and EFSA additive prohibition timelines served as scenario-weighting inputs.
Inputs from commodity exchanges and equipment manufacturers were available through the study window; gaps in private-label contract terms and QSR formulation specifications introduce uncertainty bands around foodservice volume allocations. Forecasts reflect documented assumptions regarding regulatory implementation pacing and harvest cycle normalization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
North America Packaged Salad Market
Packaged Foods
US Packaged Food Market
Packaged Foods
Spreads Market
Packaged Foods
Global Packed Food Market
Packaged Foods
Global Breakfast Cereals Market
Packaged Foods
Hummus Market
Packaged Foods
Tortilla Market
Packaged Foods
Organic Energy Bar Market
Packaged Foods
Middle East and Africa Energy Bar Market
Packaged Foods
India Packaged Food Products Market
Packaged Foods
Packaged Food Market
Packaged Foods
Global Aseptic Packaging in Food Market
Packaged Foods
Canned Goods Market
Packaged Foods
UAE Breakfast Cereals Market
Packaged Foods
Pre-Packaged Sandwich Market
Packaged Foods
Packaged Rice Noodles Market