
 Packaged Fresh Fruits Market | 2026-2036
Packaged Fresh Fruits Market Size, Share, and Industry Trends Forecast 2026-2036
Packaged Fresh Fruits Market Analytics
Harvest labor availability is rotating toward seasonal bottlenecks in major growing regions, pressuring packers to automate sorting and washing lines. Dole Food Company leverages its integrated plantation-to-retail network to secure consistent supply. Fresh Del Monte Produce anchors its position through controlled-atmosphere shipping infrastructure. Driscoll specializes in berry varietal development that commands premium shelf placement.
Packaged fresh fruits comprise raw or minimally processed fruit products sealed in protective materials to maintain organoleptic quality, typically requiring cold chain maintenance at zero to four degrees Celsius and controlled humidity to retard respiration and microbial spoilage. The category serves retail and food service channels seeking portion-ready formats with traceable origin documentation. Whole fruits occupy the largest volume share within product type segmentation due to lower processing overhead and broader household penetration. Sliced fruits generate faster growth as convenience demand from cafes and quick-service restaurants accelerates. Flexible pouches within packaging type segmentation capture expanding margin pools through reduced freight weight and extended shelf life.
The FDA enforces produce safety rules under FSMA that mandate preventive controls for packing operations, while USDA organic certification shapes premium positioning for pesticide-free claims. EPA regulations on agricultural chemical residues directly influence supplier qualification protocols for major retail contracts. Stakeholders must monitor evolving state-level packaging waste legislation that could mandate material transitions ahead of federal standardization.
Market Dynamics
Modified atmosphere packaging is compressing spoilage losses and extending retail windows, forcing packers to retool lines around gas-flush sealing and humidity-controlled films. This single technology shift is redistributing margin from logistics providers toward equipment suppliers and film converters.
Growth Catalysts
- FSMA Produce Safety Rule:The FDA's preventive controls mandate drives packers toward certified cold-chain documentation systems, creating pull for traceability software and temperature-logging hardware.
- Quick-service restaurant procurement:Chains like Starbucks and McDonald's are specifying pre-cut fruit SKUs for consistency, concentrating volume with packers capable of daily replenishment.
- Ethylene-absorbing sachets:This active packaging technology reduces respiration rates in transit, enabling longer sourcing radii from Central American growing regions to US distribution centers.
Market Restraints
- Harvest labor volatility:Seasonal worker shortages in California's Central Valley and Florida's citrus belt compress picking windows and force packers to absorb yield uncertainty.
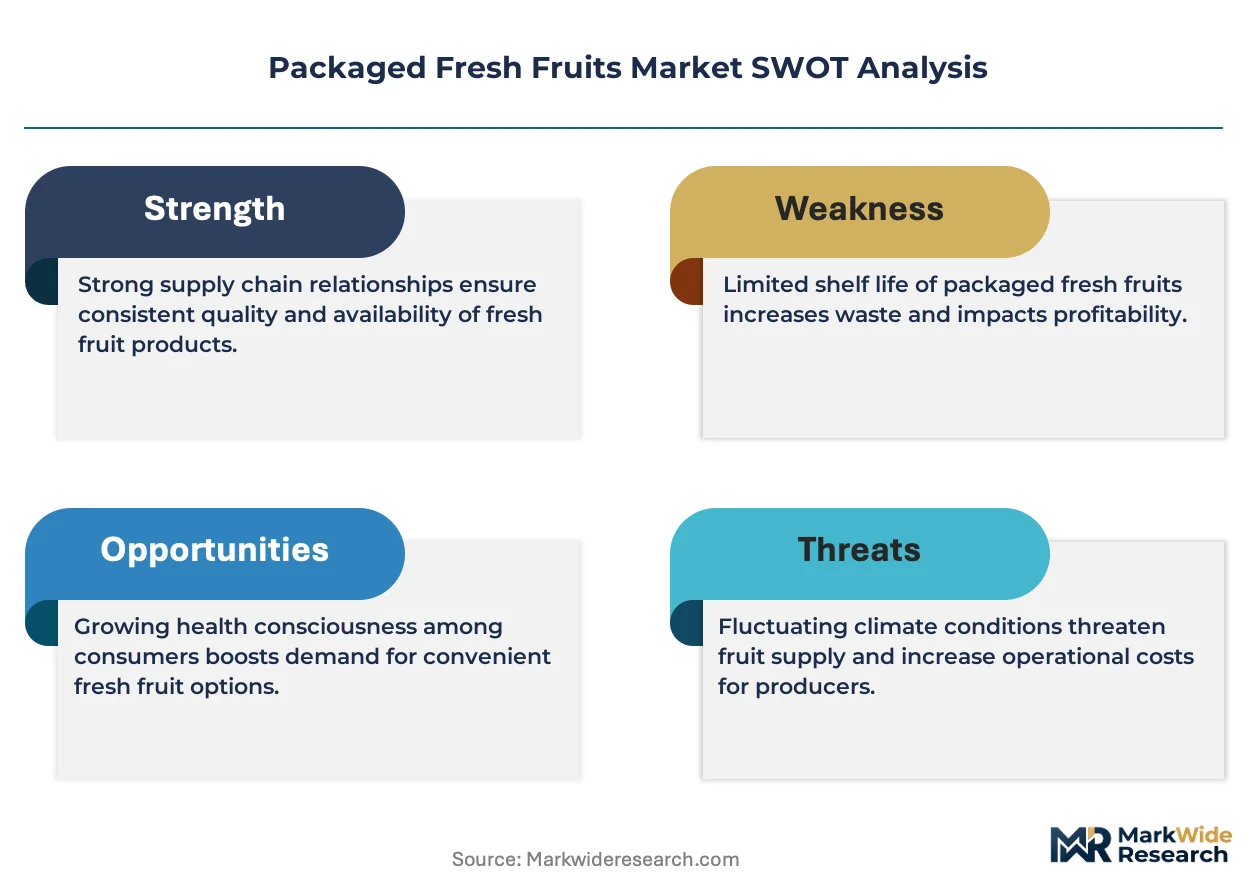
- Petroleum-based film dependency:Linear low-density polyethylene prices track crude oil benchmarks, exposing margin to energy market swings with limited near-term bio-alternative scale.
- Perishability physics:Respiration rates in berries and stone fruits impose hard ceiling on shelf life regardless of packaging innovation, limiting inventory positioning flexibility.
Strategic Opportunities
- USDA organic premium tier:The certification's 20%+ price premium in retail produce sections rewards packers who can segregate organic handling lines and maintain pesticide-free chain of custody.
- Direct-to-institutional channels:Hospitals and corporate cafeterias are bypassing broadline distributors to contract directly with regional packers for customized portion formats.
- Compostable film convergence:PLA and cellulose-based barrier films are reaching performance parity with conventional plastics, aligning with municipal composting infrastructure expansion in the Pacific Northwest and Northeast corridors.
Industry Challenges
- FSMA compliance timeline:Smaller packers face 12-18 month certification cycles for preventive control qualified individual training and facility upgrades.
- Cold-chain integration complexity:Retrofitting legacy warehouses with continuous temperature monitoring and automated alerts requires capital outlays that strain mid-tier operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaged Fresh Fruits Market |
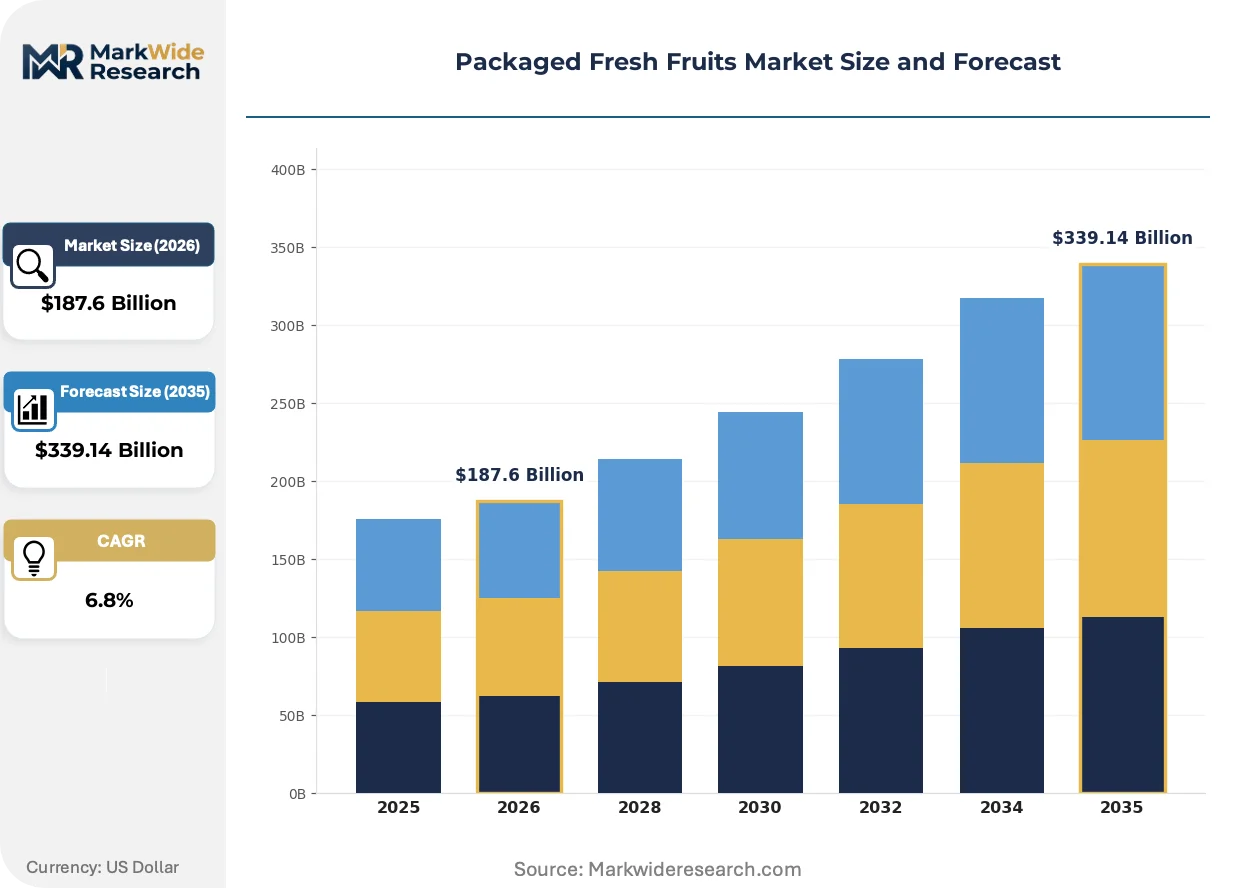
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $339.14 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Fruits, Sliced Fruits, Diced Fruits, Mixed Fruits Packaging Type: Plastic Containers, Glass Jars, Flexible Pouches, Paper Bags Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Farmers' Markets Customer Type: Individuals, Restaurants, Cafes, Food Services |
| Companies Covered | Dole Food Company, Del Monte Foods, Chiquita Brands International, Fresh Del Monte Produce, Driscoll, Nature Fresh Farms, Naturipe Farms, Berry Gardens, Keelings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaged Fresh Fruits Market Evolving Landscape
Packaging material science and regulatory disclosure requirements are simultaneously tightening specifications and opening premium positioning vectors. Three developments are actively restructuring competitive advantage.
High-barrier coextruded films with embedded ethylene scavengers are decomposing the traditional tradeoff between shelf life and synthetic additive use. Retail chains including Whole Foods and Kroger are specifying these materials for private-label lines to support clean-label claims. The technology is compressing demand for traditional MAP systems that rely on nitrogen flushing alone.
State-level extended producer responsibility laws in California, Oregon, and Washington are mandating post-consumer recycled content minimums and funding mechanisms for packaging recovery. These frameworks are accelerating capital deployment into film recycling infrastructure and reshaping supplier qualification criteria for multi-state retail contracts. Berry and grape packers in these jurisdictions face compressed timelines for material transitions ahead of 2027 compliance deadlines.
Food service operators are consolidating produce procurement through group purchasing organizations that specify lot-level traceability and third-party audit documentation. This concentration is displacing spot-market purchasing and favoring packers with integrated ERP systems capable of real-time origin verification. Quick-service and fast-casual chains in the US Southeast are most advanced in this transition, driven by liability concerns following recent produce-linked illness outbreaks.
Packaged Fresh Fruits Market Segmentation
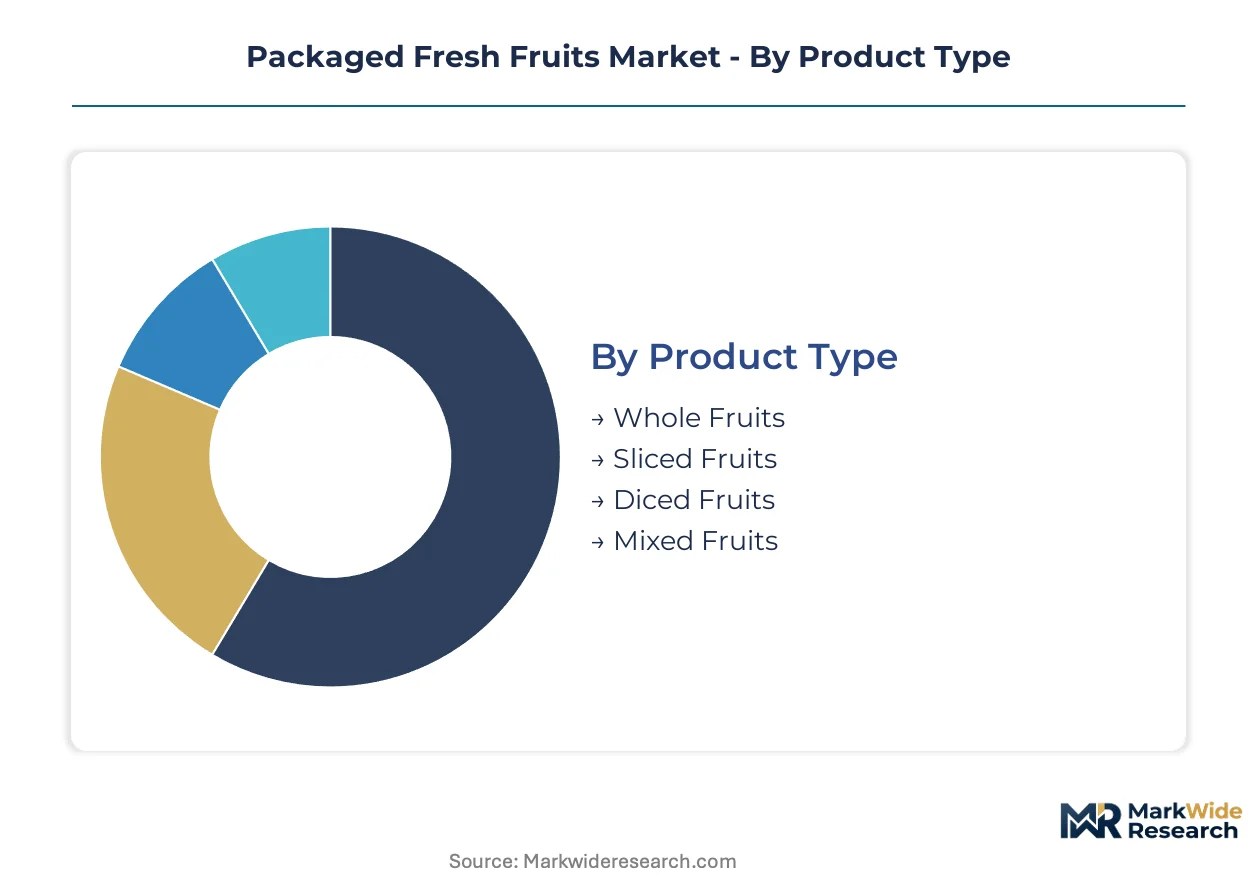
Segmentation in packaged fresh fruits reveals where convenience premiums command pricing power and where commodity pressure erodes margin. Product format and packaging material choices determine cold-chain intensity, spoilage risk, and retail placement economics.
Product Type:
Whole fruits face substitution pressure from loose produce bins in conventional grocery, while processed formats defend share through labor savings and portion control.
- Whole Fruits:Unprocessed single-variety items retain stem, peel, or rind intact, minimizing handling cost and maximizing shelf stability through natural protective barriers. Demand concentrates in US suburban supermarkets where bulk pricing and visual quality inspection drive household procurement decisions, constrained by labor cost inflation in produce department restocking.
- Sliced Fruits:Pre-cut segments in standardized thickness reduce kitchen labor for food service operators and eliminate knife-safety training overhead. Quick-service restaurants in the US Southeast specify these SKUs for consistency, pulling volume toward packers with daily replenishment capability and HACCP-certified processing lines.
- Diced Fruits:Uniform cube formats for salad bars and yogurt parfait assembly.
- Mixed Fruits:Multi-variety blends targeting single-serve snacking and institutional food service.
Whole fruits anchors the volume base while sliced fruits gains share at the steepest rate.
Packaging Type:
Material cost tiers separate premium positioning from commodity competition, with barrier performance determining permissible sourcing radius.
- Flexible Pouches:Multi-layer coextruded films with oxygen scavenger layers reduce freight weight and enable gas-flush sealing for extended shelf life. Pacific Northwest retail chains specify these for private-label organic lines, driven by municipal composting infrastructure expansion and EPR compliance timelines in Oregon and Washington.
- Plastic Containers:Rigid PET or PP clamshells with resealable lids protect structural integrity of soft berries and stone fruits. US convenience store chains favor these for grab-and-go placement near checkout, constrained by petroleum-based resin price volatility tracking crude oil benchmarks.
- Glass Jars:Premium positioning for gift-oriented and specialty retail channels.
- Paper Bags:Limited barrier protection restricting use to short-turnover whole fruit SKUs.
Plastic containers dominate current volume while flexible pouches expand most quickly in premium private-label contracts.
Distribution Channel:
Channel selection determines traceability documentation depth and temperature monitoring stringency required for contract qualification.
- Supermarkets:Full-service produce departments with cold-case infrastructure and dedicated stock rotation protocols. US regional chains like Kroger and Whole Foods mandate lot-level traceability and third-party audit documentation, concentrating procurement with packers running integrated ERP systems for real-time origin verification.
- Online Retailers:Direct-to-door fulfillment requiring insulated packaging and gel-pack cooling for last-mile temperature maintenance. Fulfillment centers in Texas and Florida prioritize packers with automated order consolidation and dynamic route optimization to minimize transit time exposure.
- Convenience Stores:High-velocity, limited-SKU formats emphasizing single-serve and immediate consumption.
- Farmers' Markets:Direct producer-to-consumer sales with minimal packaging and shortest supply chain.
Supermarkets anchor the volume base while online retailers gains share at the steepest rate.
Customer Type:
End-use concentration shapes portion specification, delivery frequency, and price sensitivity across the demand base.
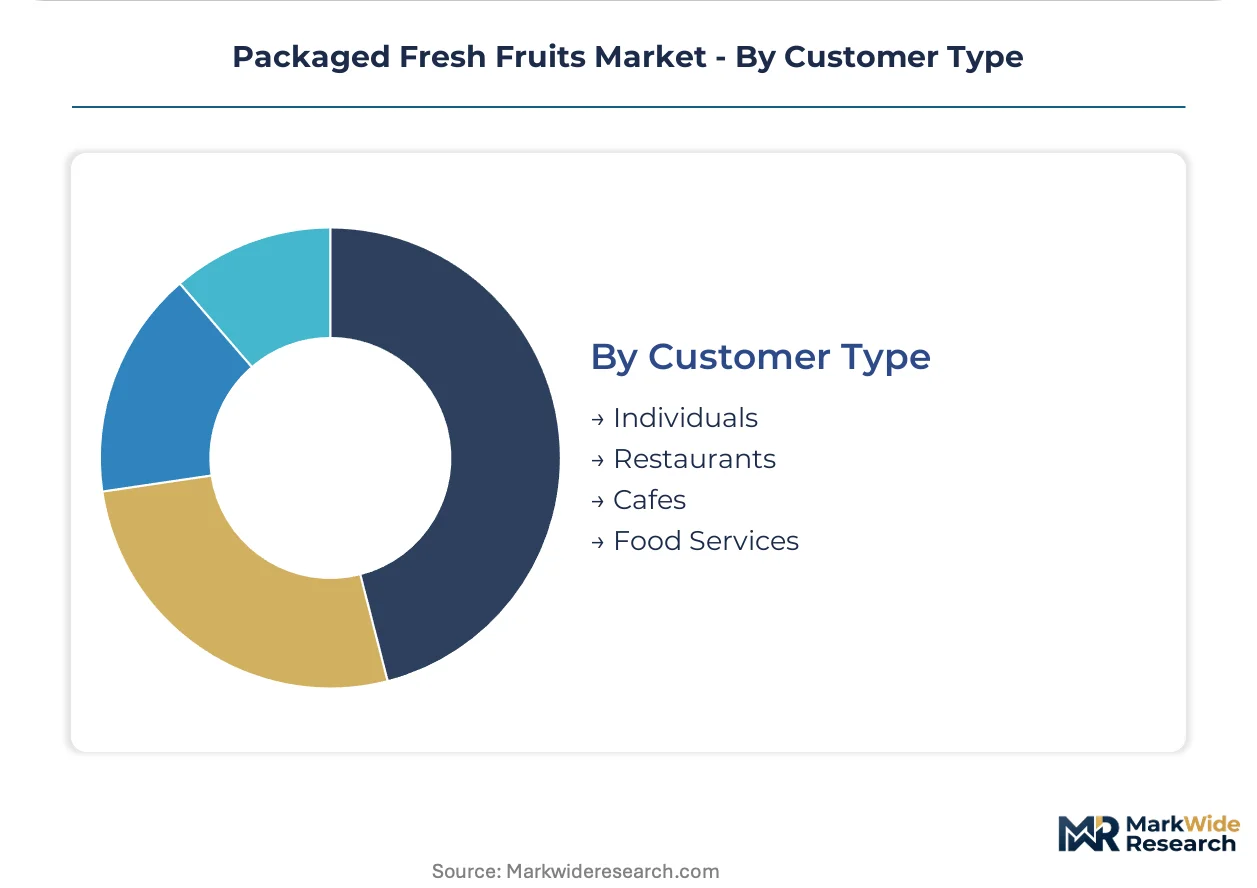
- Food Services:Institutional and commercial kitchens requiring consistent portion weights and predictable delivery windows for menu planning. Hospital and corporate cafeteria operators in the US Northeast are bypassing broadline distributors to contract directly with regional packers for customized formats, driven by cost transparency and origin documentation requirements.
- Restaurants:Full-service and fast-casual operators with plate-presentation standards and variable daily demand. Chains like Starbucks specify pre-cut fruit for beverage and food accompaniment consistency, concentrating volume with packers capable of multi-drop daily delivery routes.
- Individuals:Household consumers with high price elasticity and brand switching behavior.
- Cafes:Smaller-format operators with limited cold storage and high turnover requirements.
Food services anchors the volume base while restaurants gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between markets prioritizing convenience-ready formats and those anchored in traditional whole-fruit procurement. The United States channels disproportionate volume into food service pre-cut specifications, while European retail emphasizes extended shelf-life technologies for reduced-trip household purchasing.
United States
Quick-service restaurant chains and hospital cafeterias drive demand for diced and sliced fruit SKUs with HACCP documentation. FDA enforcement of FSMA preventive controls compels packers to deploy temperature-logging hardware across distribution networks. California's Central Valley hosts the densest concentration of automated sorting and washing facilities serving West Coast retail consolidation centers.
Germany
Discounter chains Aldi and Lidl specify modified atmosphere packaging for private-label organic lines, compressing spoilage allowances in supplier contracts. EFSA guidance on clean-label claims shapes film converter R&D priorities around additive-free barrier layers. The Lower Saxony region anchors Northern European distribution hubs handling Central American banana and pineapple volumes.
China
Fresh e-commerce platforms including Hema and Missfresh specify portion-controlled formats for tier-one city fulfillment centers. SAMR implementation of stricter produce safety standards accelerates packer investment in traceability ERP systems. The Yangtze River Delta clusters cold-chain infrastructure serving Shanghai's high-velocity retail and food service channels.
Brazil
Export-oriented packers in São Paulo state concentrate on citrus and tropical fruit value-added processing for North American winter markets. ANVISA pharmaceutical-grade facility standards are migrating into fresh produce packing house certification protocols. The Minas Gerais interior hosts expanding table grape and mango packing capacity targeting Asian premium segments.
Netherlands
Rotterdam port logistics operators intermediate re-export flows from Latin American and African origins to European hinterlands. EU Green Deal packaging waste directives mandate recycled content minimums in film specifications from 2027. The Randstad corridor concentrates controlled-atmosphere storage and ripening facilities serving German and French retail procurement offices.
Packaged Fresh Fruits Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in a structure that rewards captive supply control and cold-chain asset ownership. The upper tier commands retail shelf placement through plantation-to-retail traceability systems. Mid-scale regional packers defend position through customized portion formats for institutional food service. Dominant competitive moves include backward integration into growing operations and strategic deployment of modified atmosphere packaging licensing.
Among vertically integrated plantation operators, Dole Food Company and Fresh Del Monte Produce exemplify the scale-driven archetype through captive sourcing networks spanning Central America. Del Monte Foods occupies a position within the branded consumer goods tier, while Driscoll represents the varietal-specialist archetype commanding premium placement through berry genetics programs. Nature Fresh Farms and Naturipe Farms sit within the North American cooperative structure, aggregating regional grower output for retail and food service consolidation.
| Leading Market Players |
|---|
| Dole Food Company |
| Del Monte Foods |
| Chiquita Brands International |
| Fresh Del Monte Produce |
| Driscoll |
| Nature Fresh Farms |
| Naturipe Farms |
| Berry Gardens |
| Keelings |
| Others |
Value Network & Pricing Analysis
Ethylene-absorbing sachets displacing traditional nitrogen-flush MAP systems are redrawing sourcing radii from Central American growing regions to US distribution centers while compressing per-unit packaging economics and shifting margin capture toward film converters with active barrier capabilities.
Pricing Analysis
Contract structures favor long-term offtake agreements between quick-service restaurant chains and packers with daily replenishment capability, though spot purchasing persists in loose produce bins at conventional grocery. Three-tier pricing structure across USDA organic certified, conventional packaged, and economy-grade whole fruit separates premium claims from commodity positioning. Cost compression in conventional sliced fruit SKUs is intensifying because petroleum-based LLDPE resin prices track crude oil benchmarks with limited bio-alternative scale. Food service operators show lowest price sensitivity due to labor-cost substitution value, while individual household consumers exhibit highest elasticity and brand switching behavior.
Supply Chain Analysis
Inventory strategy preferences split between just-in-time daily replenishment for quick-service restaurant contracts and strategic stockpiling of whole fruits with natural protective barriers for suburban supermarket bulk pricing programs. Geographic supply concentration centers on Costa Rica and Guatemala for tropical fruits, California's Central Valley for berries and stone fruits, and Florida's citrus belt for orange and grapefruit varieties. Raw material dependencies draw from linear low-density polyethylene resins, ethylene-absorbing scavenger substrates, and cold-chain refrigerants. Single-source vulnerability runs through seasonal harvest labor availability in California and Florida. Distribution runs through controlled-atmosphere shipping infrastructure serving retail consolidation centers and direct-to-institutional channels bypassing broadline distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Traceability ERP platforms are reconfiguring this market around platform-economics dynamics where packers with real-time origin verification capabilities capture preferential procurement contracts from group purchasing organizations consolidating food service produce buying.
For Market Incumbents: Fortify backward integration into captive growing operations in Costa Rica and Guatemala to secure supply continuity against harvest labor volatility in domestic production regions. Invest in HACCP-certified processing lines and FSMA preventive control documentation systems to defend shelf placement against emerging regional packers targeting direct-to-institutional channels. Cold-chain asset ownership remains the critical lever for margin defense. For New Entrants and Emerging Players: Direct-to-institutional channel service gaps where incumbent packers under-serve hospital and corporate cafeteria operators with customized portion formats present the most penetrable white-space target. Pacific Northwest municipal composting infrastructure expansion creates entry opportunity for PLA and cellulose-based barrier film specialists targeting EPR compliance deadlines. A go-to-market angle anchored in compostable packaging certification alignment with state-level extended producer responsibility laws enables rapid qualification with multi-state retail contracts. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-scale regional packers with integrated ERP traceability systems and established direct-to-institutional relationships over pure commodity handlers. Acquisition targets should demonstrate lot-level origin verification capability and HACCP-certified processing infrastructure. The signal to watch as inflection indicator is group purchasing organization consolidation velocity in the US Southeast quick-service and fast-casual segments.| Strategic Initiative | Industry Significance |
|---|---|
| Modified Atmosphere Packaging Licensing | Gas-flush sealing technology transfers margin from logistics providers toward equipment suppliers and film converters serving Kroger and Whole Foods private-label lines. |
| Backward Integration into Growing Operations | Captive sourcing networks spanning Central America secure consistent supply for Dole Food Company and Fresh Del Monte Produce against seasonal labor bottlenecks. |
| Traceability ERP System Deployment | Real-time origin verification capability qualifies packers for group purchasing organization contracts specifying lot-level documentation and third-party audit requirements. |
| Compostable Film Transition | PLA and cellulose-based barrier films reaching performance parity with conventional plastics align with California, Oregon, and Washington EPR compliance timelines. |
| Direct-to-Institutional Channel Development | Hospital and corporate cafeteria operators in the US Northeast bypass broadline distributors for customized portion formats with cost transparency and origin documentation. |
Research Methodology
A standing panel of produce packing operations managers, cold-chain logistics coordinators, retail category buyers at Kroger and Whole Foods, food service procurement directors at quick-service restaurant chains, and FSMA compliance officers provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against FDA produce safety rule guidance documents, USDA organic certification standards, EPA agricultural chemical residue regulations, customs and trade data on Central American fruit imports, and SEC filings from publicly traded packers. Bottom-up volume modeling across product type, packaging material, distribution channel, and customer type segments triangulated against top-down market sizing from trade association publications.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product format intensity, barrier performance tier, cold-chain documentation depth, and regional regulatory cluster. CAGRs were derived from trend extrapolation anchored in historical growth patterns and structural shift assumptions. Industry-specific forecast inputs incorporated modified atmosphere packaging penetration rates and ethylene-absorbing sachet adoption curves in transit applications.
Underlying assumptions cover FSMA compliance timeline adherence, cold-chain infrastructure expansion in the Yangtze River Delta and US Southeast, and petroleum-based resin price stability, with deviation risk concentrated in harvest labor availability volatility and state-level packaging waste legislation acceleration. Revision becomes warranted when seasonal worker shortages in California's Central Valley and Florida's citrus belt compress picking windows beyond historical variance bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Freeze Dried Fruits and Vegetables Market
Fruits and Vegetables
Apple Concentrate Market
Fruits and Vegetables
Fermented Cucumber Market
Fruits and Vegetables
Brown Shimeji Mushroom Market
Fruits and Vegetables
Grapefruit Peel Market
Fruits and Vegetables
Fresh Lemons Market
Fruits and Vegetables
Camellia Oil Market
Fruits and Vegetables
Clean Label Fruit and Vegetable Powder Market
Fruits and Vegetables
United States Guacamole Market
Fruits and Vegetables
Europe Kiwi Fruit Market
Fruits and Vegetables
Global Not from Concentrate (NFC) Puree Market
Fruits and Vegetables
Oman Fruits and Vegetables Market
Fruits and Vegetables
Plums and Sloes Market
Fruits and Vegetables
Avocado-Based Products Market
Fruits and Vegetables
Global Fresh Cranberries Market
Fruits and Vegetables
Sea Buckthorn Market