
 Packaged Corn on the Cob Market | 2026-2036
Packaged Corn on the Cob Market Size, Share, and Industry Trends Forecast 2026-2036
Packaged Corn on the Cob Market Insights
The gap between premium and commodity tiers is broadening as organic and heritage varietal offerings command shelf-space separation from standard yellow corn lines. Green Giant leverages its backward integration into Midwest processing facilities to sustain cost discipline across frozen formats. Birds Eye anchors its retail presence through controlled freezer-aisle positioning in major supermarket chains.
Packaged corn on the cob denotes husked, trimmed, and preserved whole corn ears sold in retail-ready formats, typically blanched and quick-frozen at minus forty degrees Celsius to preserve kernel texture and sugar content for home preparation or food service reheating. Frozen corn dominates volume throughput due to twelve-month shelf stability and established cold-chain infrastructure, while vacuum-packed fresh segments capture margin pools through shorter-turn distribution to specialty food shops. Eco-friendly packaging is gaining traction as supermarkets impose sustainability procurement criteria on frozen vegetable suppliers.
USDA grading standards and FDA Good Manufacturing Practices govern kernel quality thresholds and facility sanitation protocols, directly influencing which processors qualify for national retail distribution. The EPA regulates water discharge from corn processing plants, raising capital requirements for Midwest concentration facilities. Stakeholders must monitor evolving state-level plastic packaging bans and their interaction with existing freezer-grade material specifications.
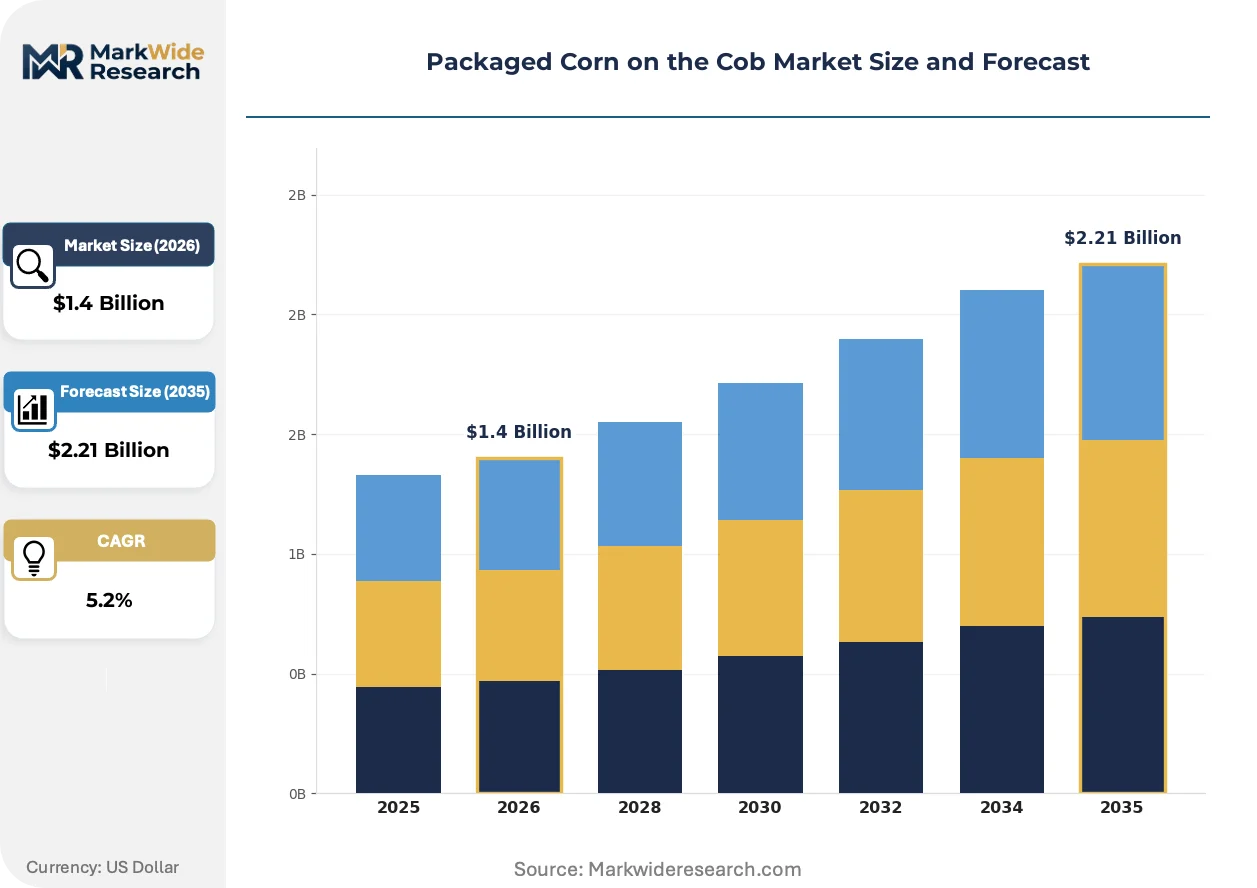
Market Dynamics
Frozen format dominance is restructuring the Packaged Corn on the Cob Market as retailers consolidate shelf space toward twelve-month shelf-stable SKUs and away from fresh-chilled alternatives. This shift concentrates procurement power among cold-chain-equipped distributors.
Growth Catalysts
- USDA Organic Certification:Premium tier separation creates margin expansion for processors meeting National Organic Program standards. Retailers allocate dedicated freezer sections to certified lines.
- Quick-freezing at minus forty degrees Celsius:Industrial blast freezing preserves kernel texture and sugar content, enabling year-round supply from Mexico's Sinaloa belt to North American retail.
- Food service reheating protocols:Standardized steam-table preparation methods expand institutional adoption in K-12 cafeterias and hospital systems.
Market Restraints
- Input cost volatility:Natural gas prices drive energy-intensive freezing and cold-storage economics across Midwest processing clusters.
- Supply concentration risk:Jalisco and Sinaloa growing belts shoulder disproportionate North American volume, exposing buyers to regional weather disruption.
- Substitution threat:IQF kernel products offer equivalent convenience with lower shipping cube and preparation labor.
Strategic Opportunities
- Specialty food shops:Vacuum-packed fresh segments command margin pools through shorter-turn distribution in underpenetrated urban markets.
- EU Green Deal packaging mandates:Biodegradable freezer-grade materials create first-mover positioning for compliant suppliers.
- Heritage varietal development:Controlled freezer-aisle positioning separates Anson Mills and similar heirloom lines from commodity yellow corn.
Industry Challenges
- State-level plastic packaging bans:California and New York restrictions conflict with existing freezer-grade material specifications, forcing dual-SKU complexity.
- EPA water discharge compliance:Corn processing plants face capital-intensive wastewater treatment upgrades at Midwest concentration facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaged Corn on the Cob Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.21 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Corn, Canned Corn, Vacuum-Packed Corn, Fresh Corn Distribution Channel: Supermarkets, Online Stores, Convenience Stores, Specialty Food Shops End User: Retail Consumers, Food Service Providers, Catering Services, Food Manufacturers Packaging Type: Plastic Wrap, Cardboard Box, Vacuum Sealed, Eco-Friendly Packaging |
| Companies Covered | Green Giant, Birds Eye, Del Monte Foods, Bonduelle Group, Pictsweet Farms, McCain Foods, Simplot Foods, GloriAnn Farms, Farm Harvest, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaged Corn on the Cob Market Trends and Innovations
Active reshaping in this market centers on cold-chain technology maturation, sustainability-driven material substitution, and retailer consolidation of frozen vegetable procurement. These forces are compressing legacy fresh-chilled distribution models.
Individually quick-frozen cob packaging with modified atmosphere sealing is decentralizing production geography by enabling smaller-scale regional processors to achieve shelf-parity with centralized Midwest facilities. Mid-size cooperatives in Minnesota and Iowa are adopting this equipment. The technology is decentralizing volume concentration away from legacy concentration plants toward distributed freezing nodes.
EU F-Gas Regulation phase-down schedules are accelerating hydrofluorocarbon replacement in industrial refrigeration systems serving frozen vegetable warehouses. Cold-storage operators face retrofit timelines through 2030. Frozen corn processors in Germany and the Netherlands are prioritizing ammonia-CO2 cascade systems to maintain operating permits.
Supermarket sustainability procurement criteria are unbundling traditional supplier relationships as buyers impose recycled-content minimums and carbon-disclosure requirements on frozen vegetable vendors. Specialty retailers in Scandinavia and the Pacific Northwest lead this specification tightening. Certification-driven preference shifts favor processors with verified agricultural water stewardship and renewable energy sourcing.
Packaged Corn on the Cob Market Segmentation
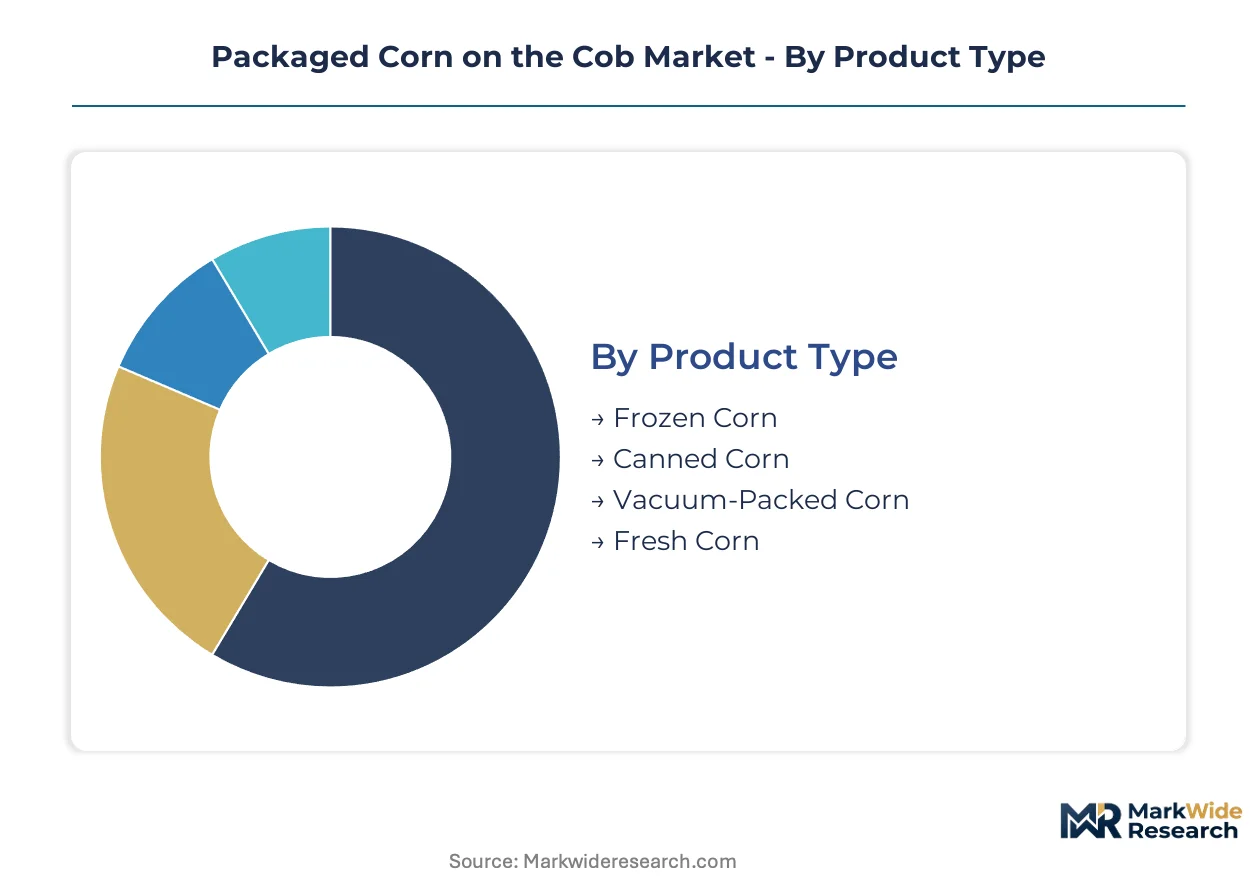
Segmentation in the Packaged Corn on the Cob Market reveals divergent margin architectures across preservation formats and channel access. Frozen formats dominate volume throughput while vacuum-packed fresh and eco-friendly alternatives capture premium positioning.
Product Type:
Frozen corn anchors volume economics through twelve-month shelf stability, while vacuum-packed fresh and canned alternatives fragment the premium and convenience tiers.
- Frozen Corn:Blanched whole ears undergo industrial blast freezing at minus forty degrees Celsius to lock kernel texture and sugar content. Retail procurement concentrates in Walmart and Kroger freezer aisles where year-round supply from Mexico's Sinaloa belt supports consistent replenishment cycles.
- Vacuum-Packed Corn:Modified atmosphere sealing extends chilled shelf life to twenty-one days, enabling shorter-turn distribution to urban specialty retailers. Demand clusters in Pacific Northwest and Northeast metropolitan markets where consumers trade price premiums for perceived freshness.
- Canned Corn:Thermal processing in brine or water delivers ambient stability for pantry-stockpiling households. Volume concentrates in price-sensitive rural markets and institutional procurement channels.
- Fresh Corn:Unprocessed husked ears with minimal preservation target immediate-consumption occasions. Supply windows constrain availability to summer harvest periods in temperate growing zones.
Today's leader: Frozen Corn. Tomorrow's challenger: Vacuum-Packed Corn.
Distribution Channel:
Channel segmentation tracks cold-chain capability against purchase-occasion convenience, with supermarket dominance eroding under digital and specialty retail pressure.
- Supermarkets:Controlled freezer-aisle positioning and promotional slotting fees sustain volume concentration. Kroger and Albertsons capture the bulk of frozen corn transactions through dedicated vegetable sections.
- Online Stores:Direct-to-door frozen delivery requires insulated packaging and same-day fulfillment infrastructure. Amazon Fresh and Instacart are expanding their frozen vegetable SKUs in suburban markets.
- Convenience Stores:Limited freezer capacity restricts assortment to single-serve canned and microwaveable formats. Urban grab-and-go demand drives placement in 7-Eleven and Circle K locations.
- Specialty Food Shops:Curated heritage varietals and organic certification command shelf-space separation from commodity lines. Whole Foods and regional co-ops prioritize USDA Organic and local sourcing credentials.
Supermarkets retain transaction volume. Specialty shops gain margin share fastest.
End User:
End-user segmentation splits between household preparation convenience and institutional reheating standardization, with food service protocols driving format specifications.
- Retail Consumers:Home preparation demands microwave-ready packaging and portion-controlled sizing. Frozen cob segments dominate household purchase frequency.
- Food Service Providers:K-12 cafeterias and hospital systems require steam-table compatible formats with standardized holding times. USDA commodity programs influence procurement specifications.
- Catering Services:Event-scale volume needs drive bulk frozen purchases with flexible preparation windows. Regional catering operators source through broadline distributors.
- Food Manufacturers:Ingredient-grade corn supplies processed food production lines for soups, snacks, and ready meals. Specifications prioritize kernel count consistency and sugar content thresholds.
Food service procurement expands most quickly. Retail consumer volume remains the baseline.
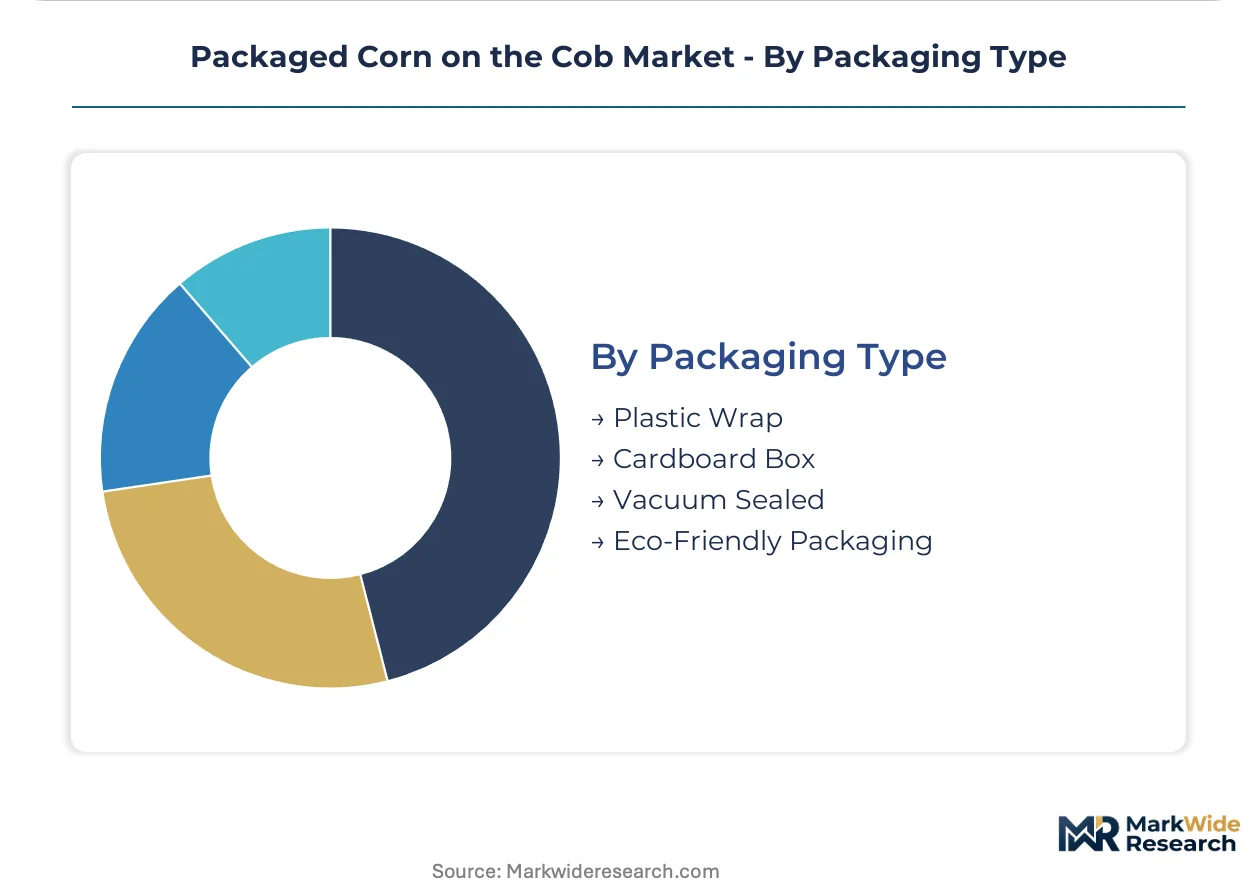
Packaging Type:
Packaging segmentation reflects tension between freezer-grade material performance and emerging sustainability procurement criteria from major retailers.
- Plastic Wrap:Polyethylene films deliver cost-effective moisture barrier protection for frozen cobs. California and New York state-level restrictions are forcing material reformulation.
- Vacuum Sealed:Multi-layer barrier films with modified atmosphere capability extend chilled shelf life. Premium positioning in specialty retail channels justifies higher unit economics.
- Cardboard Box:Outer containment for multi-cob frozen packs enables brand billboard space and stacking strength. Recycled-content minimums are tightening across Scandinavian retail buyers.
- Eco-Friendly Packaging:Biodegradable freezer-grade materials and agricultural fiber trays respond to EU Green Deal mandates. Early compliant suppliers secure preferential shelf placement in sustainability-focused chains.
Plastic wrap holds cost advantage. Eco-friendly alternatives climb the fastest on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processing specialists cluster in Mexico's Sinaloa belt and the US Midwest, anchoring North American frozen corn supply chains through year-round production capabilities and integrated cold-chain infrastructure.
United States
Retail procurement concentrates in Walmart and Kroger freezer aisles, driving demand for twelve-month shelf-stable SKUs. FDA Good Manufacturing Practices govern facility sanitation protocols for national distribution qualification. Midwest processing clusters in Minnesota and Iowa host Green Giant's backward integration into captive freezing facilities.
Mexico
Sinaloa and Jalisco growing belts shoulder disproportionate North American volume through climate-enabled year-round harvest cycles. USDA organic certification requirements tighten product standards for cross-border retail placement. Jalisco-based cooperatives supply blast-frozen cobs to US supermarket chains via established cold-chain corridors.
Canada
Supermarket sustainability procurement criteria from Loblaw and Sobeys impose recycled-content minimums on frozen vegetable vendors. Health Canada and PMRA regulate pesticide residue thresholds for imported corn products. Ontario distribution hubs connect to US Midwest processing networks through integrated cold-storage infrastructure.
Germany
EU F-Gas Regulation phase-down schedules accelerate hydrofluorocarbon replacement in industrial refrigeration systems serving frozen vegetable warehouses. Frozen corn processors prioritize ammonia-CO2 cascade systems to maintain operating permits through 2030. Edeka and REWE sustainability specifications favor suppliers with verified agricultural water stewardship.
Netherlands
EU Green Deal packaging mandates drive biodegradable freezer-grade material adoption among Dutch frozen vegetable traders. Rotterdam cold-storage terminals serve as distribution nodes for North African and Latin American corn imports. Unilever's legacy frozen vegetable operations anchor procurement relationships with sustainability-focused retailers.
Packaged Corn on the Cob Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across frozen corn processing tiers, creating a bifurcated structure where integrated Midwest facilities face specialized regional cooperatives. The vendor base concentrates among multinational frozen vegetable portfolios and mid-size agricultural cooperatives with captive growing operations. Three archetypes dominate: backward-integrated processors with captive supply chains, brand-licensing specialists leveraging third-party manufacturing, and cooperative aggregators pooling regional harvest volumes. Competitive moves center on freezer-aisle positioning negotiations with supermarket chains and sustainability certification acquisition to meet retailer procurement criteria.
Among US-based processors, Green Giant and Birds Eye occupy positions exemplifying the integrated multinational archetype, while Bonduelle Group represents European cooperative-origin competitors with sustainability-forward positioning. Green Giant anchors cost discipline through captive Midwest processing infrastructure. Birds Eye exemplifies controlled retail placement strategies in major supermarket chains. Bonduelle Group sits within the EU regulatory compliance tier, navigating F-Gas refrigeration mandates and Green Deal packaging requirements.
| Leading Market Players |
|---|
| Green Giant |
| Birds Eye |
| Del Monte Foods |
| Bonduelle Group |
| Pictsweet Farms |
| McCain Foods |
| Simplot Foods |
| GloriAnn Farms |
| Farm Harvest |
| Others |
Pricing and Supply Chain Analysis
Natural gas pricing volatility feeds directly through frozen corn tier structures, with energy-intensive blast freezing at minus forty degrees Celsius anchoring cost differentials between commodity yellow lines and certified organic offerings. Buyers face escalating input pass-through as Midwest processing clusters absorb tariff-exposed equipment and Mexican cold-chain logistics.
Pricing Analysis
Bundle-unbundle splits separate cob-in-bag commodity sales from value-added microwave-ready and heritage varietal SKUs. Three-tier pricing structure across premium, standard, and economy levels tracks USDA organic certification, controlled freezer-aisle positioning, and volume scale. Pricing pressure stems from IQF kernel substitution eroding cob-format convenience premiums. Food service procurement exhibits lowest price sensitivity; rural pantry-stockpiling households show highest.
Supply Chain Analysis
Dual-sourcing requirements from Walmart and Kroger procurement desks mandate simultaneous qualification of Sinaloa and Jalisco cooperatives alongside Midwest processing nodes. Raw material flows draw from Mexican year-round harvest belts, Iowa-Minnesota seasonal volumes, and nitrogen fertilizer inputs tethered to natural gas benchmarks. Single-source vulnerability concentrates in Jalisco weather exposure. Distribution runs through cold-chain-equipped broadline distributors serving supermarket freezer aisles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
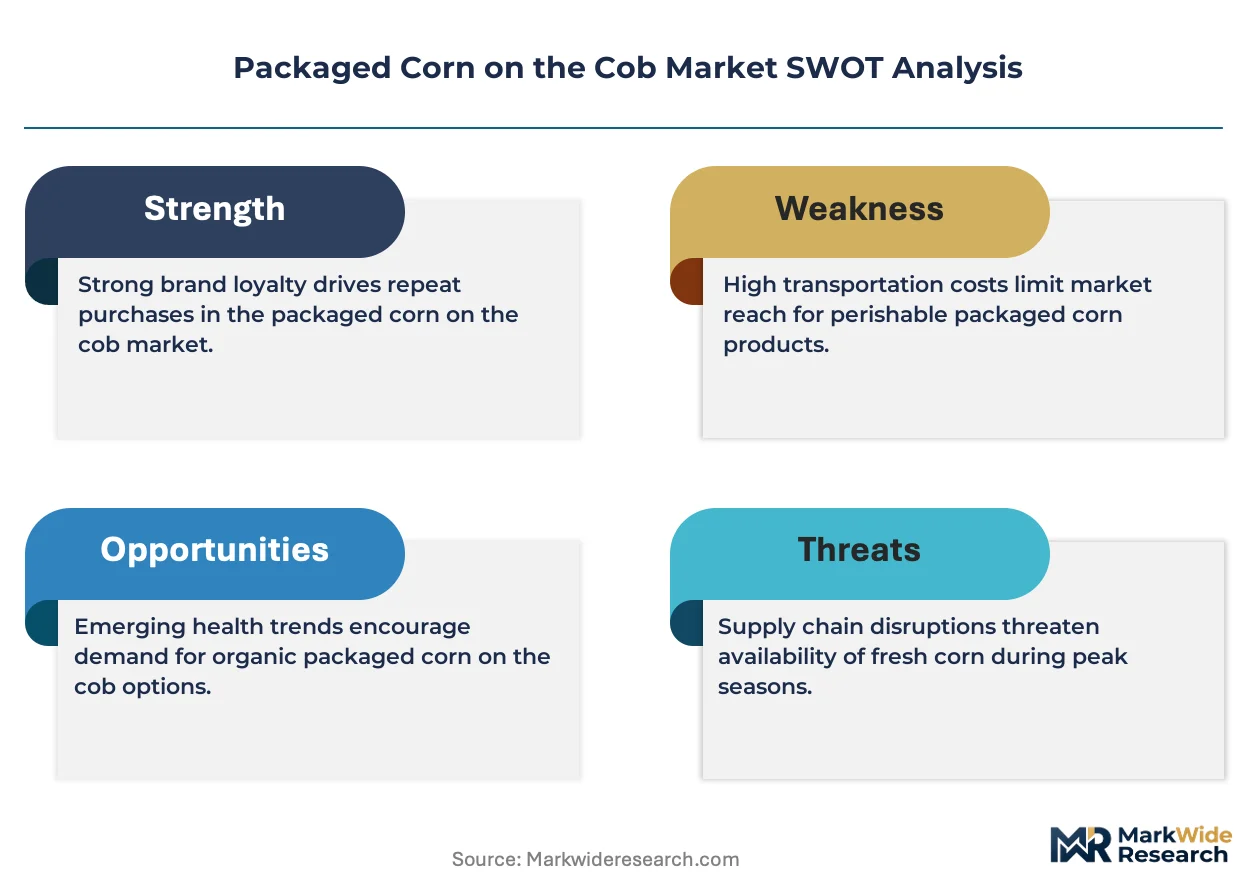
Packaged corn on the cob functions as a stable compounder anchored by frozen format shelf-stability and recurring household replenishment cycles. Convenience-driven format shifts sustain baseline demand across economic cycles.
For Market Incumbents: Deploy backward integration into captive freezing infrastructure to lock in cost discipline against natural gas volatility. Secure controlled freezer-aisle positioning through multi-year promotional slotting agreements with Kroger and Albertsons. IQF kernel substitution and state-level plastic packaging bans threaten legacy cob-format margins. For New Entrants and Emerging Players: Enter via vacuum-packed fresh segments in underpenetrated urban specialty retail corridors. Target Pacific Northwest and Northeast metropolitan markets with twenty-one-day chilled shelf-life offerings. Lead with USDA organic certification and biodegradable packaging compliance to bypass incumbent slotting fee barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-size cooperatives lack capital for EPA wastewater treatment upgrades and F-Gas refrigeration retrofits. Five-to-ten-year viability favors processors with verified agricultural water stewardship and renewable energy sourcing. Watch ammonia-CO2 cascade system adoption rates as inflection signal for regulatory compliance positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Freezing Infrastructure | Green Giant's captive Midwest facilities demonstrate cost discipline against energy volatility. |
| USDA Organic Certification Investment | Retailer procurement criteria allocate dedicated freezer sections to certified lines. |
| Biodegradable Packaging Transition | EU Green Deal mandates and California plastic bans force material reformulation timelines. |
| Specialty Retail Channel Expansion | Whole Foods and regional co-ops prioritize heritage varietals with shelf-space separation. |
| Ammonia-CO2 Cascade Refrigeration Retrofit | German and Dutch processors secure operating permits under F-Gas phase-down schedules. |
Research Methodology
Bottom-up food service and retail consumer modeling reconciled against top-down processing capacity tracking forms the analytical core. Primary interviews with frozen vegetable procurement managers, supermarket category buyers, agricultural cooperative operations directors, and cold-chain logistics specialists combined with secondary validation from USDA National Agricultural Statistics Service, FDA food facility registration databases, EPA discharge monitoring reports, and customs trade records. Triangulation against Nielsen retail audit data and supermarket sustainability procurement disclosures anchored volume estimates.
Input-output matrices mapped corn harvest volumes through blast freezing capacity to downstream channel shipments across the analysis window. Segmentation dimensions modeled include preservation format, distribution channel, end-user category, and packaging material tier. CAGRs derived from regression analysis of historical volume trajectories against macroeconomic indicators and regulatory implementation schedules. Forecast inputs incorporated natural gas price scenarios and F-Gas refrigeration retrofit timelines.
Inputs from FDA facility inspection records and EPA enforcement databases were available through the study window; gaps in real-time cold-chain temperature monitoring data introduce uncertainty bands around spoilage rate assumptions. Deviation in Mexican peso-denominated input costs or Jalisco regional weather patterns would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Canned Legumes Market
Packaged Foods
North America Instant Noodles Market
Packaged Foods
Sausage Casing Market
Packaged Foods
Plant Focused Dips Market
Packaged Foods
Air-Dried Food Market
Packaged Foods
Ready Meals Market
Packaged Foods
On-The-Go Breakfast Cereals Market
Packaged Foods
Canned Pasta Market
Packaged Foods
Chocolate Based Spreads Market
Packaged Foods
Global Gluten-Free Breakfast Cereals Market
Packaged Foods
Private Label Food and Beverage Market
Packaged Foods
Canned Goods Market
Packaged Foods
Breakfast Food Market
Packaged Foods
Instant Rice Market
Packaged Foods
Packaged Food Market
Packaged Foods
Injectable Cocoa Fillings Market