
 Military Forces Ready to Eat Meals Market | 2026-2036
Military Forces Ready to Eat Meals Market Size, Share, and Industry Trends Forecast 2026-2036
Military Forces Ready to Eat Meals Market Insights
Aftermarket service revenue is narrowing as original manufacturers embed longer shelf-life guarantees into initial contracts, compressing the refurbishment window for expired inventory. SOPAKCO leverages its retort pouch expertise to sustain multi-year defense supply agreements. Wornick Foods anchors large-scale thermostabilized production capacity for bulk military orders.
Military Forces Ready to Eat Meals are individually packaged, fully prepared food rations engineered to withstand extreme climates without refrigeration, typically achieving shelf lives of three to five years through controlled water activity, oxygen exclusion, and thermal processing. Their primary purpose is to deliver complete nutritional profiles under austere field conditions where conventional food logistics fail. Retort pouched meals dominate procurement volumes due to proven battlefield durability and compact cube efficiency, while freeze-dried formats represent the fastest-expanding margin pool as ultralight requirements spread across special operations and airborne units. Government procurement channels control the largest value flow, though defense contractors are capturing incremental share by acting as system integrators for multi-nation feeding programs.
The U.S. Defense Logistics Agency enforces shelf-life standards and nutritional compliance through its Subsistence supply chain, while the FDA's low-acid canned food regulations and USDA meat inspection requirements shape ingredient sourcing and processing protocols for domestic manufacturers. The EU's General Food Law and NATO standardization agreements create additional compliance layers for cross-border military feeding contracts. Stakeholders must monitor how emerging near-peer conflict scenarios reshape ration portability requirements and thermal processing specifications.
Market Dynamics
The U.S. Defense Logistics Agency's shelf-life extension protocols are compressing procurement cycles and forcing manufacturers toward accelerated testing regimes and improved barrier packaging investments.
Growth Catalysts
- Special Operations Procurement:Expeditionary units are driving demand for ultralight, extended-shelf-life rations. This end-use segment prioritizes calorie density and cube efficiency over standard issue formats.
- REACH Compliance Evolution:The EU's chemical safety framework is accelerating migration toward PFAS-free packaging substrates. European defense contractors must certify alternative barrier materials to maintain cross-border supply eligibility.
- Thermostabilization Advances:Retort processing improvements are enabling protein quality retention at higher temperatures. This technology shift reduces thermal degradation while maintaining pathogen elimination standards.
Market Restraints
- Aluminum Foil Supply Concentration:Multi-layer retort pouch production depends on Chinese and Russian primary aluminum smelters. Geopolitical friction creates input cost volatility and forced substitution risks.
- USDA Inspection Bottlenecks:Domestic meat ingredient sourcing requires continuous federal inspection presence. Plant scheduling constraints limit production surge capacity during procurement spikes.
- Freeze-Dry Energy Intensity:Sublimation processing consumes three to four times the energy of retort stabilization. European electricity pricing pressures margin viability for lightweight format producers.
Strategic Opportunities
- Indigenous Arctic Feeding:Canadian and Nordic defense modernization programs under-specify cold-weather ration performance. Manufacturers can capture share by validating meals at minus forty degrees Celsius.
- Modular Component Systems:Separating entrees from accessories and flameless heaters enables mission-tailored kitting. This distribution innovation reduces waste in short-duration deployments.
- USDA BioPreferred Procurement Preference:Federal purchasing mandates now weight biobased content in packaging materials. Qualifying films gain scoring advantages in DLA competitive solicitations.
Industry Challenges
- Accelerated Shelf-Life Validation:Contracting officers now demand real-time aging data rather than accelerated test projections. Analytical chemistry capacity for lipid oxidation and vitamin degradation testing is scarce.
- Legacy ERP Integration:Defense supply chain visibility requirements mandate RFID and lot-traceability data exchange. Smaller processors face capex burdens to retrofit production lines for serialized packaging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Forces Ready to Eat Meals Market |
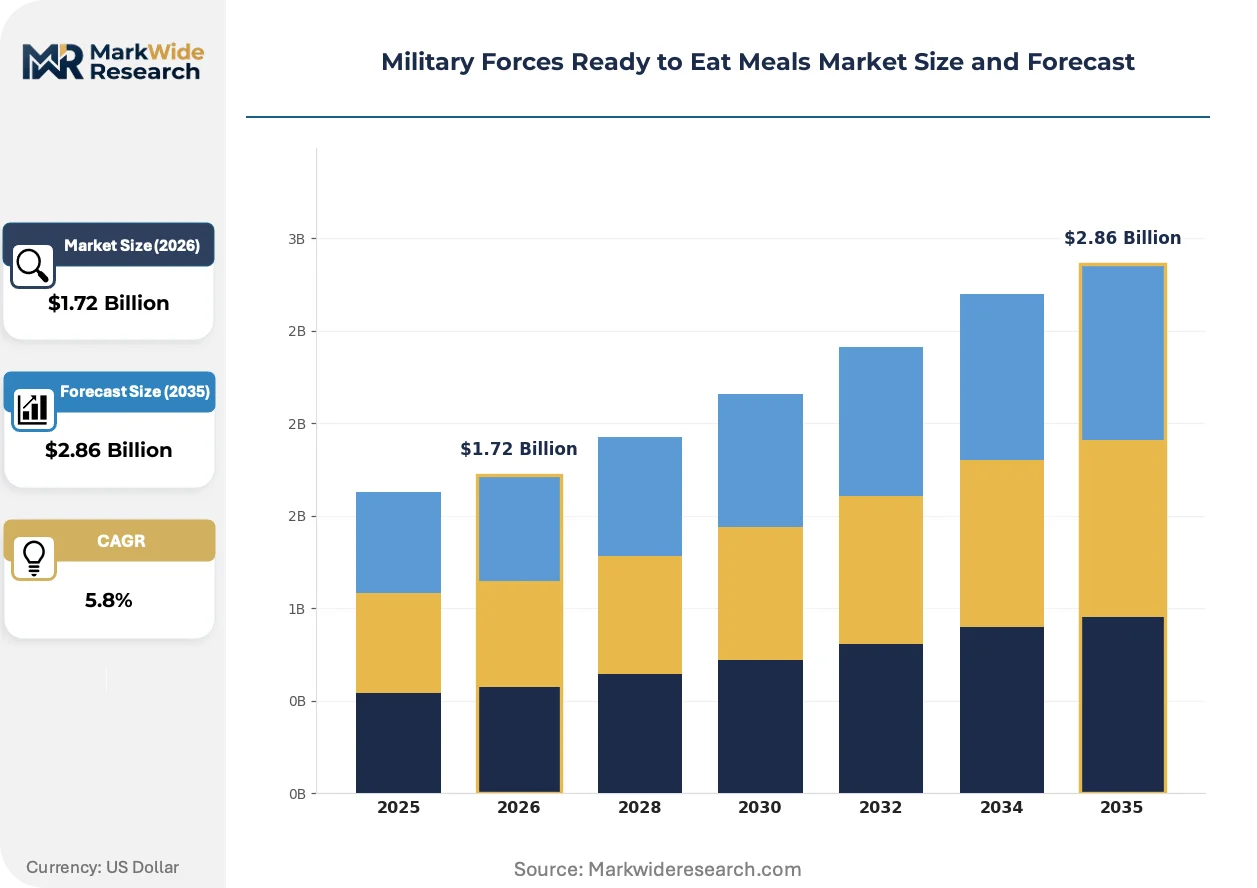
| Market Size in 2026 | $1.72 Billion |
| Market Size in 2035 | $2.86 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Meal Type: Freeze-Dried, Retort Pouched, Thermostabilized, Dehydrated, Baked Packaging Type: Vacuum Sealed, Hydrated Pouch, Boxed, Canned, Flexible Pouch End User: Army Units, Naval Forces, Air Squadrons, Special Operation Teams, Paramilitary Groups Distribution Channel: Government Procurement, Defense Contractors, Direct Supply, Military Depots, Authorized Retailers |
| Companies Covered | Meal Kit Supply LLC, Alder Foods, Inc., ThermoPac LLC, Matthews Associates, Wornick Foods, GA Foods, SOPAKCO, Golden Wolf Enterprises, Long Life Food Depot LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Forces Ready to Eat Meals Market Trends and Innovations
Active packaging intelligence and alternative protein integration are reshaping ration design priorities. Manufacturers now compete on traceability depth and nutritional customization rather than shelf-life alone.
Smart oxygen-scavenging films with embedded color-change indicators are digitizing quality assurance workflows. Special Operations Commands in the United States and United Kingdom are piloting these sensors for real-time consumption safety verification. The technology is digitizing inventory rotation decisions and reducing reliance on date-code inspections in forward logistics nodes.
The EU's Packaging and Packaging Waste Regulation is mandating recyclability quotas for military exemption categories by 2030. This industrial consequence forces reformulation of multi-layer retort structures currently dependent on incompatible polymer laminations. French and German defense procurement agencies are pre-qualifying mono-material alternatives ahead of compliance deadlines.
Unit-level menu customization through digital pre-positioning platforms is altering demand aggregation patterns. Brigade combat teams now submit component preferences through supply chain portals rather than accepting standardized pallet configurations. This behavioral shift is most visible in Pacific theater pre-positioning stocks, where rotation frequency and dietary restriction accommodation have become competitive bid evaluation criteria.
Military Forces Ready to Eat Meals Market Segmentation
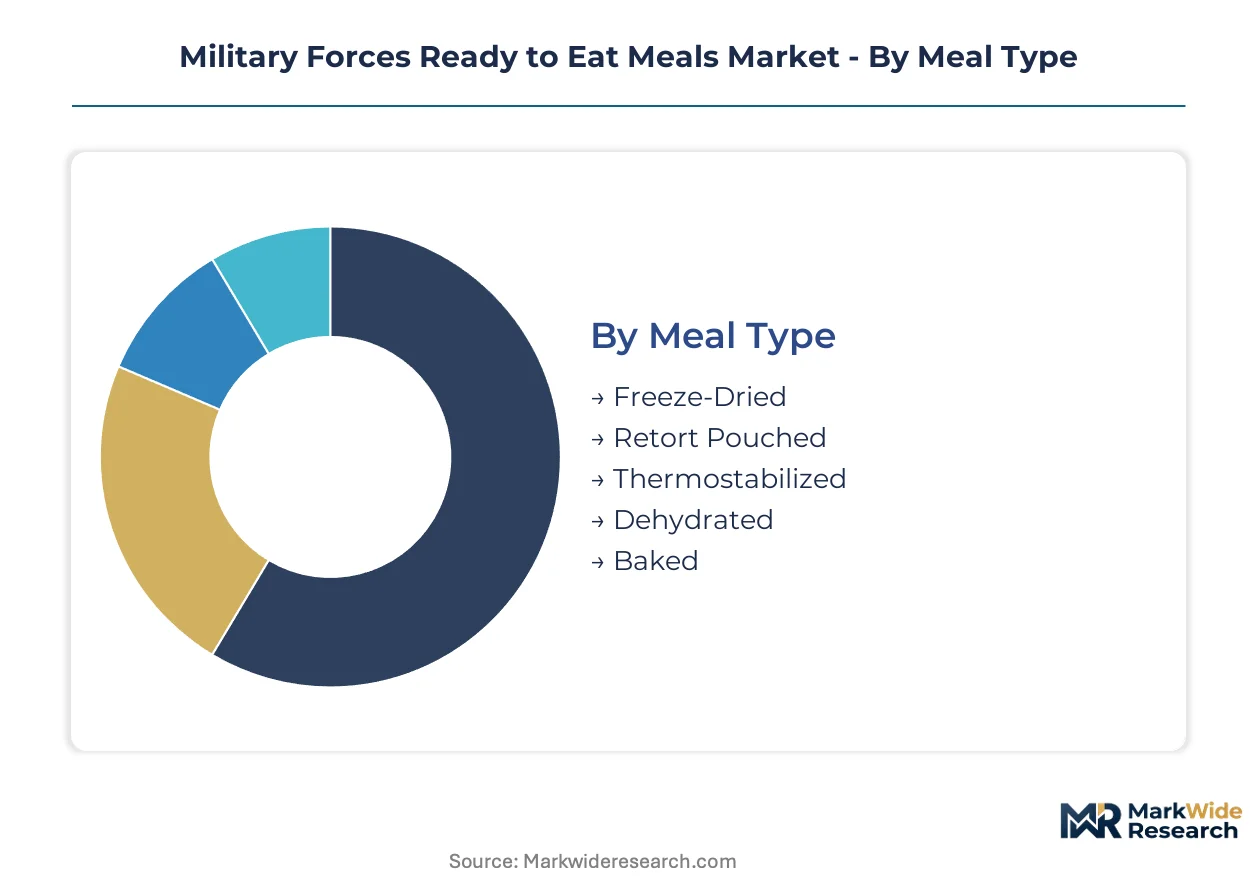
Segmentation in military feeding systems reveals how procurement priorities diverge across operational environments. Shelf-life requirements, weight constraints, and distribution logistics create distinct demand profiles that manufacturers must address through specialized production lines.
Meal Type:
Freeze-dried formats turn over fastest in special operations procurement cycles, while thermostabilized products maintain the longest replacement intervals in strategic stockpiles.
- Freeze-Dried:Sublimation processing removes moisture through ice-to-vapor transition, yielding sub-200 gram entrees with 25-year stability. Special Operation Teams in the United States drive procurement for high-altitude and arctic insertions where every gram compounds mobility advantage. Energy-intensive production limits European manufacturing scale.
- Retort Pouched:Multi-layer aluminum-polymer laminates withstand 121°C sterilization while maintaining flexible cube efficiency. The U.S. Defense Logistics Agency channels the majority of bulk orders through this format for temperate-zone field operations. Barrier material costs fluctuate with primary aluminum supply from Chinese smelters.
- Thermostabilized:Metal can or rigid tray formats endure extreme mechanical abuse during airdrop and maritime resupply.
- Dehydrated:Convection-dried components reconstitute with ambient water, occupying middle ground between weight and preparation simplicity.
- Baked:Shelf-stable bread and confectionery items round out nutritional profiles in extended-deployment menus.
Retort Pouched anchors the volume base while Freeze-Dried gains share at the steepest rate.
Packaging Type:
Cost tiers separate single-use field consumption from multi-meal logistical configurations, with material specifications scaling to mission duration.
- Flexible Pouch:Laminated films achieve the highest cube efficiency for dismounted infantry loadouts. U.S. Army infantry brigades specify this format for 72-hour assault packs where space competes with ammunition priority. REACH compliance is forcing PFAS-free adhesive migration.
- Vacuum Sealed:Oxygen exclusion extends lipid stability in high-fat protein components across multi-year storage. NATO pre-positioning stocks in Poland and Romania favor this construction for reduced inspection frequency. Barrier integrity testing consumes significant analytical chemistry capacity.
- Hydrated Pouch:Pre-moistened formats eliminate field water requirements for specific medical or extreme-cold applications.
- Boxed:Corrugated outer shells protect inner pouches during palletized movement through contested logistics nodes.
- Canned:Steel or aluminum rigid containers survive deep-water submersion and structural crushing.
Flexible Pouch commands the largest procurement value while Vacuum Sealed expands most quickly in allied nation stockpiling programs.
End User:
Application intensity varies from garrison training consumption to combat expeditionary rates, with nutritional specifications scaling to metabolic demand.
- Army Units:Ground forces generate baseline demand volume through mechanized and light infantry formations. Brigade combat teams in the Pacific theater specify modular component systems for island-hopping scenarios. Menu fatigue mitigation drives rotation requirements.
- Special Operation Teams:Small-unit autonomy demands the highest calorie density per kilogram. United Kingdom Special Forces validation protocols for arctic performance are emerging as a de facto quality benchmark. Procurement bypasses standard DLA channels through direct service-level contracting.
- Naval Forces:Submarine and surface vessel crews require compact storage for extended blue-water patrols.
- Air Squadrons:Flight line and aircrew survival kits prioritize space constraints over extended shelf life.
- Paramilitary Groups:Border security and coast guard units operate under dual civilian-military procurement frameworks.
Army Units sustain the procurement foundation while Special Operation Teams pull innovation investment at the sharpest trajectory.
Distribution Channel:
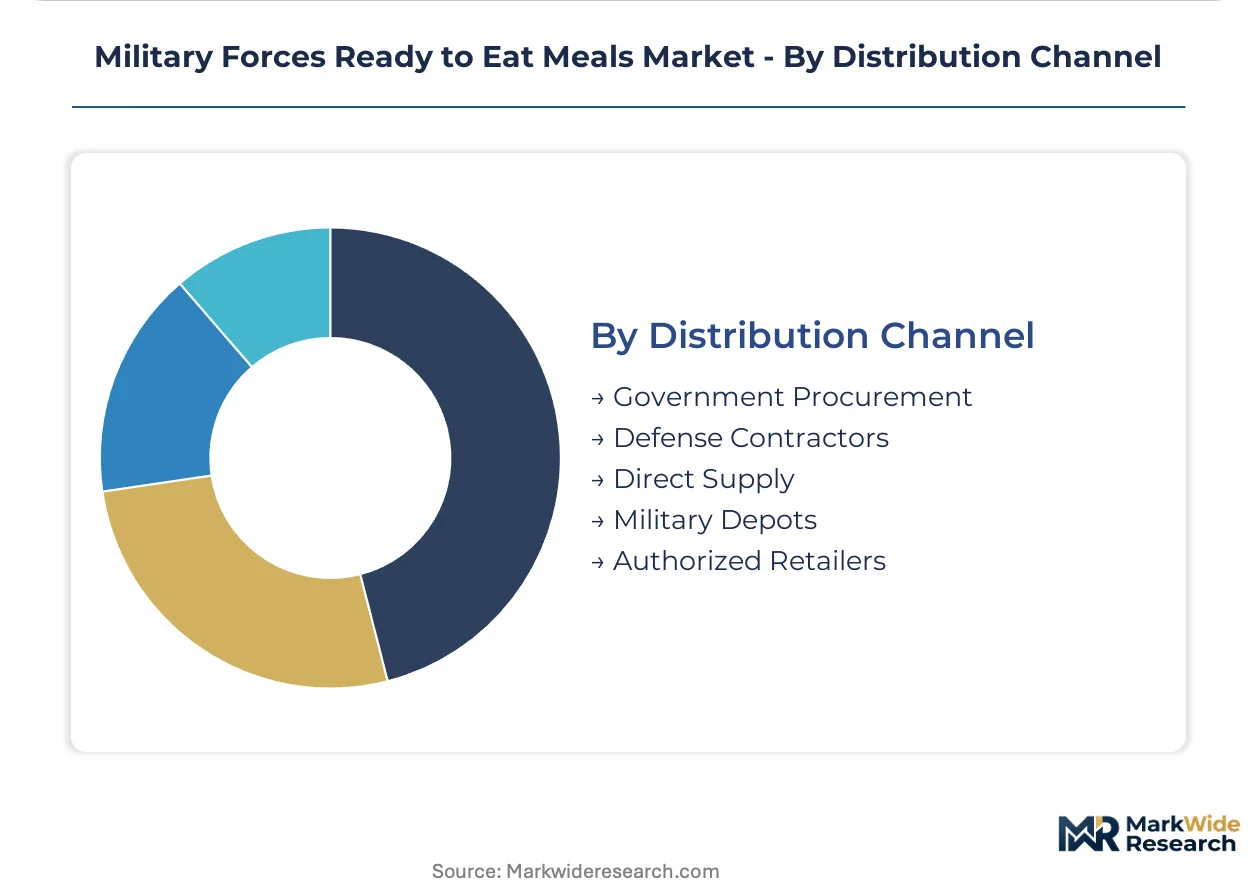
Customer type determines contract structure complexity, with direct military relationships favoring multi-year supply agreements over transactional purchasing.
- Government Procurement:Defense Logistics Agency solicitations dominate U.S. market value through indefinite-delivery contracts. Federal purchasing mandates now weight biobased packaging content in competitive scoring. Shelf-life extension protocols compress testing cycle demands on suppliers.
- Defense Contractors:System integrators aggregate multi-nation feeding programs under NATO standardization agreements. French and German contractors are pre-qualifying mono-material packaging alternatives ahead of EU recyclability deadlines. Integration requirements mandate serialized RFID lot traceability.
- Direct Supply:Service-specific channels bypass central procurement for specialized operational needs.
- Military Depots:Strategic stockpile rotation generates predictable refurbishment demand.
- Authorized Retailers:Surplus and civilian outdoor markets provide secondary revenue streams.
Government Procurement holds the contract value core while Defense Contractors capture share fastest through allied nation integration mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes military rations through centralized Defense Logistics Agency channels, while allied nations increasingly source through defense contractor aggregators. Procurement modality splits the market between direct government contracting and multi-nation integration frameworks.
United States
Defense Logistics Agency indefinite-delivery contracts dominate procurement volume through shelf-life extension protocols. USDA continuous inspection requirements shape domestic meat ingredient sourcing. South Carolina and Ohio host retort pouch fabrication clusters where barrier film lamination capacity concentrates.
United Kingdom
Special Forces validation protocols for arctic performance establish quality benchmarks adopted across NATO standardization agreements. Ministry of Defence procurement channels bypass central EU frameworks for operational feeding systems. Salisbury Plain and Catterick Garrison anchor field-testing infrastructure for cold-weather ration validation.
Germany
Bundeswehr modernization programs drive demand for modular component systems compatible with rapid deployment logistics. ECHA REACH compliance mandates PFAS-free packaging substrate migration ahead of 2030 deadlines. Bavaria hosts thermostabilized production facilities serving joint NATO pre-positioning stocks in Poland and Romania.
France
Direction Générale de l'Armement pre-qualifies mono-material packaging alternatives under EU Packaging and Packaging Waste Regulation timelines. Expeditionary forces in Sahel operations prioritize lightweight formats for airborne resupply. Toulouse and Lyon clusters specialize in smart oxygen-scavenging film integration for quality assurance digitization.
Canada
Indigenous Arctic feeding requirements under-specify cold-weather performance, creating validation opportunities at minus forty degrees Celsius. Canadian Armed Forces procurement channels emphasize biobased packaging content under federal purchasing mandates. Edmonton and Calgary host freeze-dry processing capacity for high-altitude and northern deployment scenarios.
Military Forces Ready to Eat Meals Market Competitive Landscape
Capability concentration sits with specialized thermostabilization and retort pouch fabricators; scale advantage sits with diversified food processors holding multi-year defense supply agreements. The market structures around three tiers: legacy military contractors with DLA indefinite-delivery contracts, commercial food manufacturers pivoting into defense channels, and system integrators aggregating multi-nation NATO feeding programs. Dominant competitive moves include capacity expansion for barrier film lamination and strategic partnerships for PFAS-free packaging substrate certification.
Within the legacy contractor tier, SOPAKCO and Wornick Foods occupy positions defined by retort pouch expertise and thermostabilized production scale respectively. SOPAKCO represents specialized barrier packaging capability sustaining multi-year defense agreements. Wornick Foods exemplifies large-format production capacity anchoring bulk military orders. GA Foods sits within the diversified nutrition services segment, bridging military and institutional feeding channels.
| Leading Market Players |
|---|
| Meal Kit Supply LLC |
| Alder Foods, Inc. |
| ThermoPac LLC |
| Matthews Associates |
| Wornick Foods |
| GA Foods |
| SOPAKCO |
| Golden Wolf Enterprises |
| Long Life Food Depot LLC |
| Others |
Pricing and Supply Chain Analysis
Retort pouch lamination undercapacity in the Ohio-South Carolina corridor is compressing supplier margins and forcing Defense Logistics Agency contractors into longer-term offtake commitments to secure barrier film allocation.
Pricing Analysis
Long-term indefinite-delivery contracts dominate procurement, with pricing stratifying across premium freeze-dried formats, standard retort-pouched rations, and economy dehydrated components. Price differentiation rests on certification grade for arctic performance and volume scale for brigade-level orders. Cost compression in standard thermostabilized tiers is intensifying because aluminum-polymer laminate input costs fluctuate with Chinese smelter output. Special Operation Teams show least price sensitivity due to mission-critical ultralight requirements, while garrison training units exhibit highest elasticity to per-unit costs.
Supply Chain Analysis
Contract-manufacturing concentration sits with SOPAKCO and Wornick Foods holding retort sterilization capacity, while ThermoPac LLC anchors freeze-dry processing. Geographic supply concentration centers on the United States, Germany, and Canada for thermostabilized production; China and Russia for primary aluminum; and Southeast Asia for specialty polymer films. Raw material dependencies draw from aluminum foil, oxygen-scavenging adhesive laminates, and USDA-inspected meat proteins. Single-source vulnerability in Chinese aluminum supply creates forced substitution risk during geopolitical friction. Distribution runs through Defense Logistics Agency central depots with RFID-tracked lot traceability to forward logistics nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barrier packaging chemistry expertise is scarce relative to procurement demand, creating acquisition premiums for manufacturers holding validated PFAS-free substrate certifications.
For Market Incumbents: Harden analytical chemistry capacity for real-time shelf-life validation as contracting officers abandon accelerated test projections. Secure backward integration into oxygen-scavenging film production to reduce aluminum-polymer laminate cost volatility. Anchor capacity expansion in South Carolina and Ohio clusters where USDA inspection infrastructure is pre-established. For New Entrants and Emerging Players: Build out modular component kitting capabilities for Pacific theater brigade combat teams demanding mission-tailored configurations rather than standardized pallet loads. Target Canadian Armed Forces indigenous arctic feeding programs where minus forty degrees Celsius validation requirements are under-specified. Pursue direct supply relationships with United Kingdom Special Forces bypassing central NATO procurement channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among retort pouch fabricators holding multi-year DLA indefinite-delivery contracts with embedded shelf-life extension guarantees. Long-term viability favors specialists with certified PFAS-free packaging pathways ahead of EU REACH deadlines. Watch for accelerated shelf-life validation mandates from U.S. Defense Logistics Agency as inflection signal for analytical chemistry capacity scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Packaging Certification | ECHA REACH compliance mandates alternative barrier substrates for EU defense supply eligibility. |
| Real-Time Shelf-Life Validation | DLA contracting officers now demand lipid oxidation and vitamin degradation data from actual aging. |
| Modular Component Kitting | Pacific theater brigades submit digital preferences reducing waste in short-duration deployments. |
| Arctic Performance Validation | Canadian and Nordic defense programs under-specify cold-weather testing at minus forty degrees Celsius. |
| RFID Lot Traceability Integration | Defense supply chain visibility mandates serialized packaging data exchange with DLA systems. |
Research Methodology
Initial hypotheses were tested against primary input from defense procurement officers, retort pouch manufacturing engineers, USDA inspection coordinators, and barrier film chemists, and refined through secondary validation against Defense Logistics Agency solicitation records, FDA low-acid canned food filings, ECHA REACH substance registration databases, and NATO standardization agreement documentation. Bottom-up production capacity estimates from Ohio and South Carolina fabrication clusters were triangulated against top-down DLA contract award values.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with segmentation modeled by meal type, packaging format, end-user intensity, and distribution channel structure. CAGRs were derived from procurement volume trajectories and replacement cycle compression. Forecast inputs incorporated Special Operations Command ultralight requirement evolution and EU Packaging and Packaging Waste Regulation recyclability quota timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by commercial food manufacturers pivoting into defense channels would shift outcomes. Quarterly review of DLA shelf-life extension protocol amendments and ECHA PFAS restriction proposal advancements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Jams, Jellies & Preserves Market
Specialty Foods
Sofrito Market
Specialty Foods
Global Hispanic Foods Market
Specialty Foods
Free-From Food Market
Specialty Foods
Super Foods Market
Specialty Foods
Healthy Low-Fat Desserts Market
Specialty Foods
Natural Honey Market
Specialty Foods
Carbonic Maceration Market
Specialty Foods
Thai Cuisine Market
Specialty Foods
Zhacai Market
Specialty Foods
Curculin Market
Specialty Foods
Mexico Guacamole Market
Specialty Foods
Cultures Market
Specialty Foods
Aloe Vera Gel Market
Specialty Foods
Low Calorie Oatmeal Market
Specialty Foods
Low Salt Low Fat Meals Market