
 Europe Frozen Desserts Market | 2026-2036
Europe Frozen Desserts Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Frozen Desserts Market Foresight
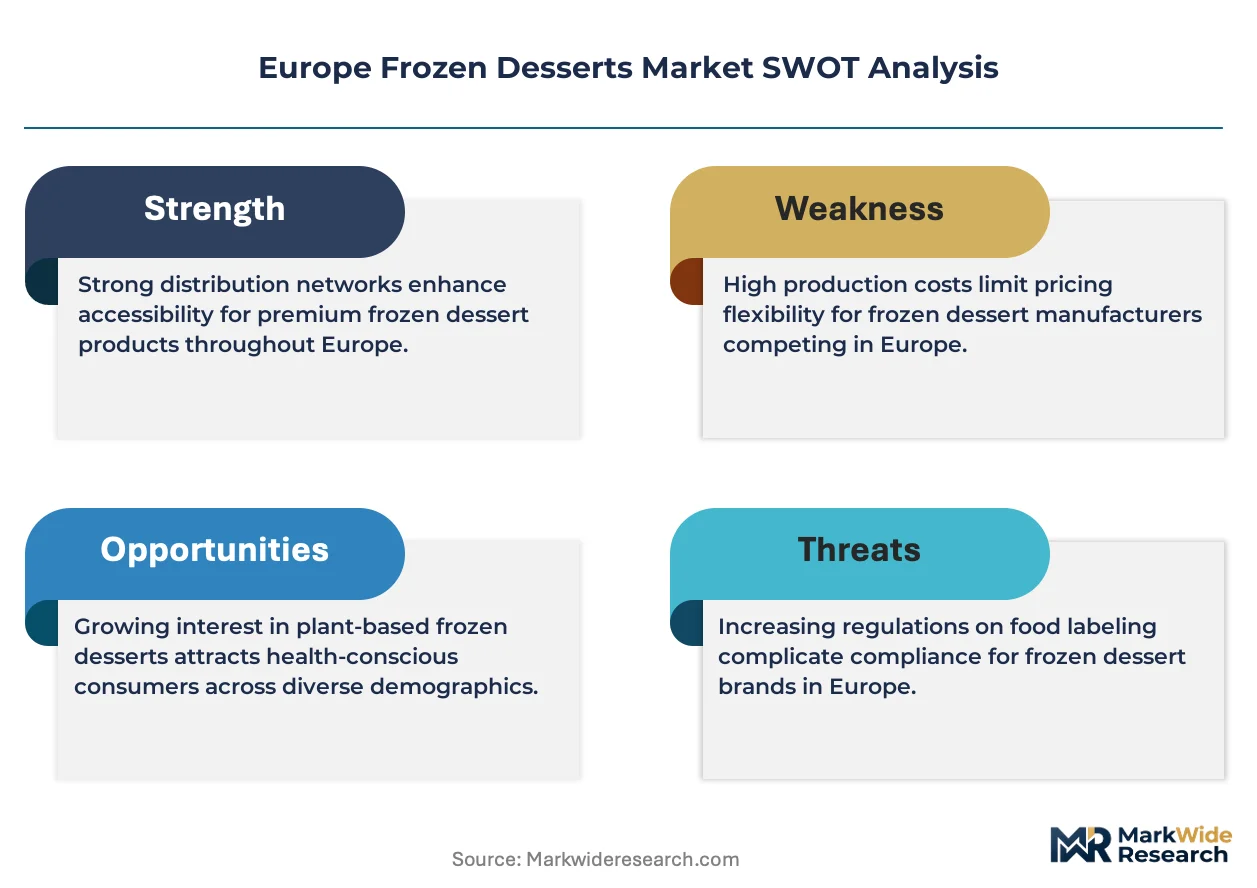
Premium clean-label tiering is rotating the competitive landscape toward higher-margin positioning. Nestlé leverages its European dairy supply network to sustain cost discipline across multiple price bands. Unilever anchors category visibility through intensive freezer-door placement in British and German supermarkets. Ferrero Group differentiates via indulgence-focused formulations that occupy the gift and seasonal occasion segments.
Europe frozen desserts comprise formulated, blast-frozen or hardened sweet preparations typically containing minimum 2.5% milkfat or alternative lipid bases, stabilized for scoopable texture at -18°C and designed for direct consumer consumption without further thermal processing. Ice cream maintains mature volume leadership while plant-based ingredient type claims capture the fastest structural expansion as oat and almond bases displace conventional dairy in Nordic and Benelux markets. Gelato's lower overrun density and warmer serving temperature sustain premium margin pools in Italian and Spanish specialty store channels where artisan credentials command price separation from mass-market tubs.
EFSA governs novel food approvals for emerging protein bases while the EU Green Deal's Farm to Fork Strategy tightens pesticide residue thresholds across dairy feed crops, directly elevating raw material compliance costs. REACH and the EU Packaging and Packaging Waste Regulation force reformulation of stabilizer chemistries and accelerate fiber-based single-serve packaging transitions. Stakeholders must monitor how ECHA's expanding candidate list of substances of very high concern reshapes emulsifier and flavor additive portfolios before next-generation clean-label claims crystallize into regulatory minimums.
Market Dynamics
The EU Green Deal's Farm to Fork Strategy is compressing formulation timelines across European frozen dessert manufacturing, forcing simultaneous reformulation of stabilizer chemistries and dairy sourcing standards before compliance deadlines crystallize into market access barriers.
Growth Catalysts
- REACH compliance acceleration:ECHA's expanding candidate list of substances of very high concern is pushing manufacturers toward clean-label emulsifier portfolios ahead of mandatory restrictions, creating first-mover positioning for reformulated product lines.
- Plant-base protein transition:EFSA novel food approvals for emerging oat and almond protein bases are unlocking formulation flexibility in Nordic and Benelux retail channels where dairy-free claims command shelf space premiums.
- Specialty gelateria channel expansion:Artisan credentials in Italian and Spanish urban centers sustain price separation from mass-market tubs, drawing investment toward lower-overrun production equipment and warmer serving infrastructure.
Market Restraints
- Dairy feed crop compliance costs:The EU Green Deal's tightened pesticide residue thresholds across European dairy supply chains elevate raw material procurement expenses before clean-label premiums fully offset input inflation.
- Stabilizer chemistry concentration:REACH-mandated reformulation of hydrocolloid and emulsifier portfolios concentrates supplier power among specialty ingredient houses with pre-approved clean-label alternatives.
- Fiber-based packaging cost premium:The EU Packaging and Packaging Waste Regulation accelerates transitions away from plastic single-serve formats toward molded fiber alternatives that carry 15-25% unit cost premiums at current scale.
Strategic Opportunities
- German discount supermarket channel:Aldi and Lidl's expanding private-label frozen dessert assortments create volume anchoring opportunities for manufacturers with flexible co-packing capacity and cost-disciplined dairy networks.
- Clean-label certification convergence:Dual pursuit of organic and carbon-neutral claims under the EU Green Deal's climate targets enables price tier separation in French and British premium retail segments.
- Artisan equipment technology:Continuous freezing technology miniaturization is lowering capital barriers for small-batch gelato production, enabling regional brand proliferation in underserved Eastern European urban markets.
Industry Challenges
- Reformulation timeline compression:Simultaneous EFSA novel food approval processes for alternative proteins and ECHA substance restriction timelines strain R&D bandwidth across mid-tier manufacturers without dedicated regulatory affairs functions.
- Legacy cold chain asset stranding:Existing -25°C distribution infrastructure designed for high-overrun ice cream products faces utilization risk as lower-density gelato formats requiring -18°C storage gain share in specialty channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Frozen Desserts Market |
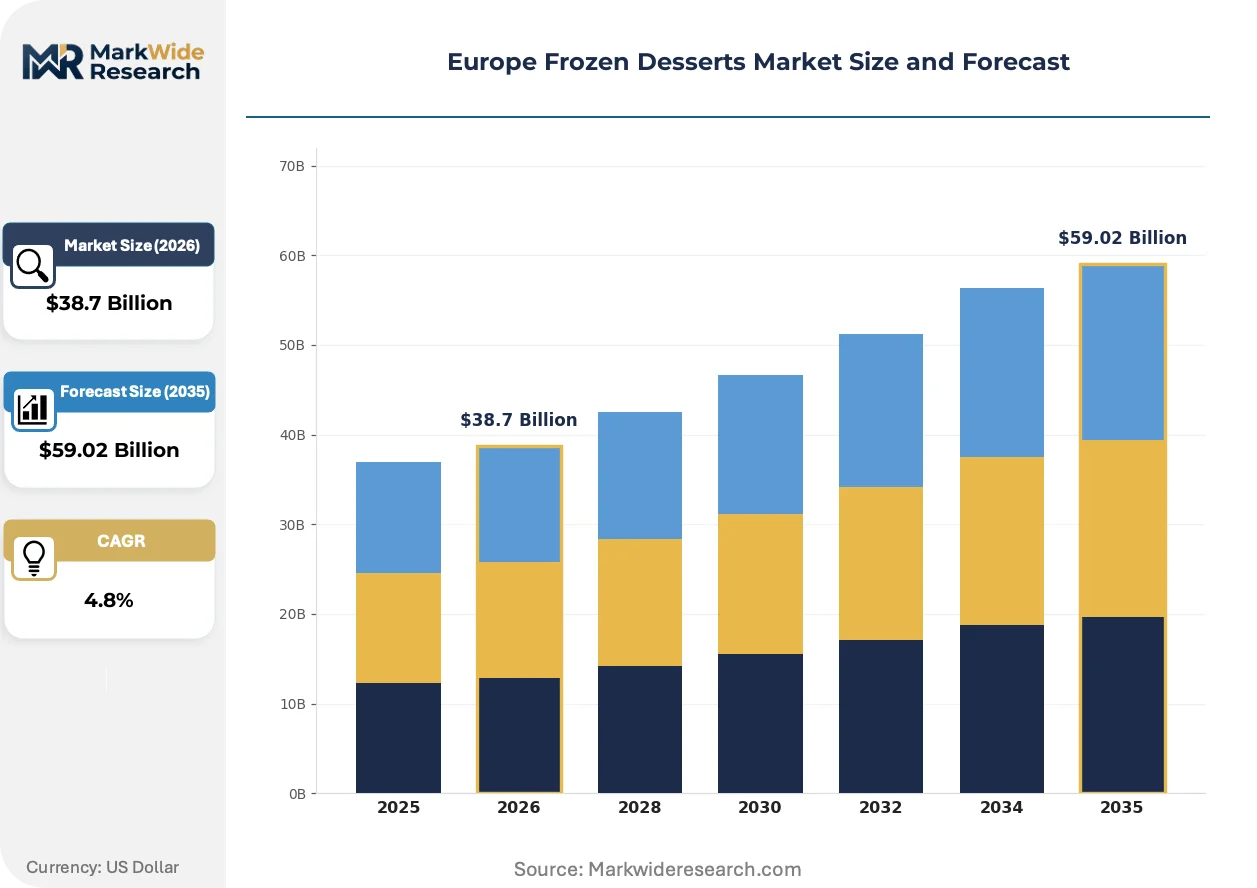
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ice Cream, Sorbet, Gelato, Frozen Yogurt Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores Ingredient Type: Dairy-based, Plant-based, Sugar-free, Organic Consumer Type: Kids, Adults, Health-conscious, Gourmet Foodies |
| Companies Covered | Mondelēz International, Dunkin' Brands, Nestlé, Fonterra Co-operative Group, Chobani, Unilever, Ferrero Group, Lindt & Sprüngli, General Mills, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Frozen Desserts Market Shifts & Advancements
Formulation science and packaging engineering are converging to redefine product architecture across European frozen desserts, with regulatory pressure acting as the primary accelerant rather than consumer pull alone.
Continuous freezing technology for artisan-scale production is miniaturizing from industrial batch systems toward compact 50-200 liter hourly capacity units suitable for in-store gelateria installation. Italian equipment manufacturers are deploying these systems across Spanish and Portuguese specialty retail chains, compressing the capital recovery period for location-specific production and eroding the distribution economics that previously favored centralized manufacturing.
The EU Packaging and Packaging Waste Regulation is mandating fiber-based single-serve format transitions by 2030, forcing reformulation of barrier coatings and seal integrity specifications for frozen dessert sticks and cones. Manufacturers with captive paperboard converting operations in France and Germany are internalizing these transitions faster than competitors dependent on third-party packaging procurement, creating compliance timeline fragmentation across the supply base.
Buyer concentration in British and German supermarket channels is compressing supplier negotiation cycles from annual to quarterly frameworks, with private-label buyers demanding real-time cost transparency on dairy and alternative protein inputs. This procurement rhythm shift favors manufacturers with vertically integrated dairy networks or long-term oat base supply agreements, disadvantaging spot-market dependent competitors in price negotiation leverage.
Europe Frozen Desserts Market Segmentation
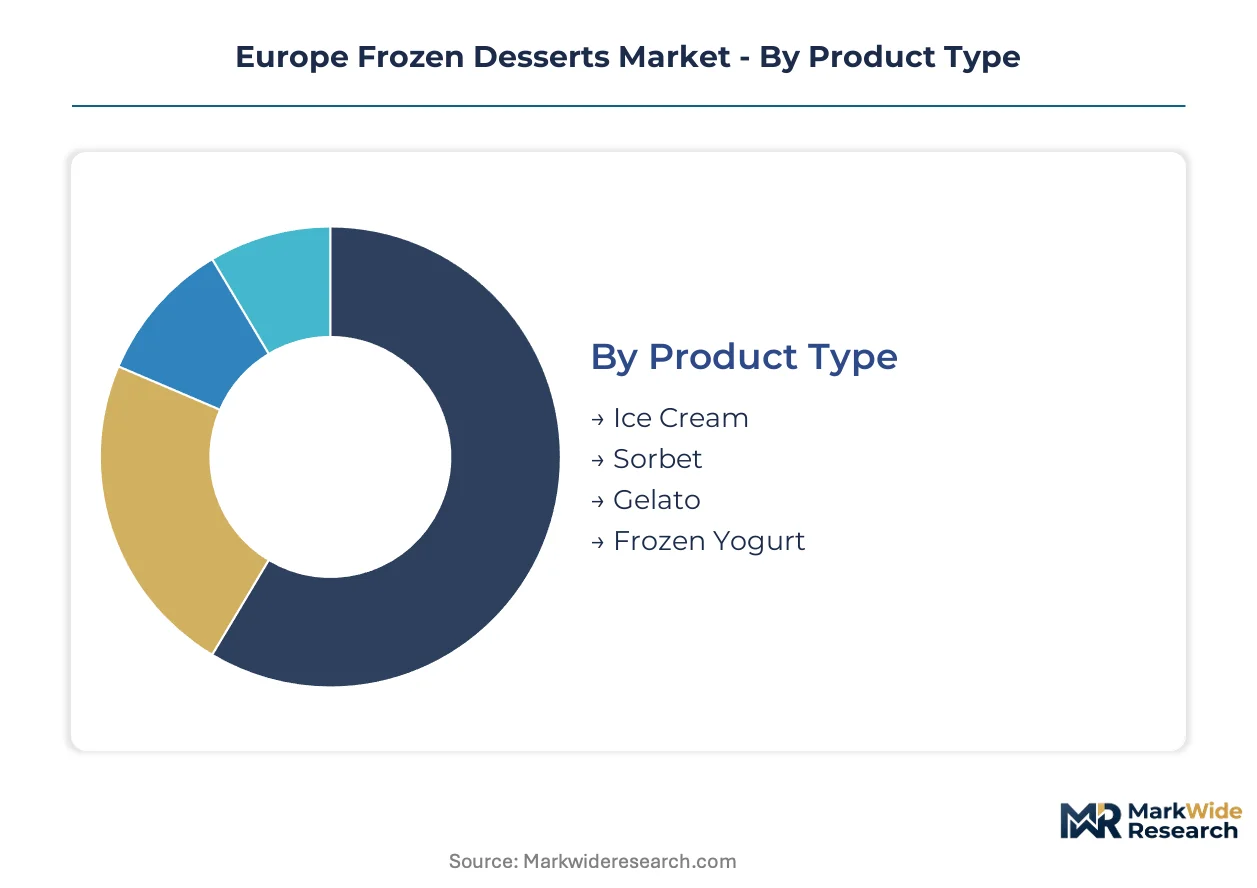
Channel dynamics and ingredient sourcing standards are fragmenting the Europe frozen desserts landscape into distinct competitive arenas. Each segmentation dimension carries specific regulatory exposure under EFSA and REACH frameworks, forcing manufacturers to align portfolio architecture with compliance timelines.
Product Type:
Channel-mix patterns vary sharply across formats, with mass-market tubs dominating German supermarket freezers while artisan formats concentrate in Italian and Spanish specialty retail.
- Ice Cream:Formulated with minimum 2.5% milkfat, blast-frozen to -18°C for scoopable texture. German discount supermarkets anchor volume demand, though ECHA-mandated stabilizer reformulation is elevating R&D costs for mass-market producers.
- Gelato:Lower overrun density and warmer serving temperature sustain premium positioning. Italian urban specialty channels command price separation through artisan credentials, drawing equipment investment toward continuous freezing technology miniaturization.
- Sorbet:Fruit-based formulations without dairy lipid bases. French and British premium retail segments favor clean-label sorbet for allergen-free positioning.
- Frozen Yogurt:Cultured dairy base with tart flavor profile. Nordic convenience channels show concentrated demand for probiotic-positioned variants.
Ice Cream dominates installed base. Gelato is where expansion concentrates.
Distribution Channel:
Cost tier alignment determines channel access, with private-label suppliers anchoring discount tiers and artisan producers capturing premium shelf economics.
- Supermarkets:British and German buyers compress negotiation cycles to quarterly frameworks, demanding real-time cost transparency on dairy and oat protein inputs.
- Convenience Stores:Impulse-format single-serve sticks and cones drive volume. Fiber-based packaging transitions under EU Packaging and Packaging Waste Regulation elevate unit costs 15-25% at current scale.
- Online Retail:Direct-to-consumer frozen logistics require specialized -18°C last-mile infrastructure. Benelux urban corridors show strongest penetration for subscription-based artisan delivery.
- Specialty Stores:In-store production equipment enables location-specific gelato manufacturing. Spanish and Portuguese retail chains are deploying Italian-origin continuous freezing systems.
Supermarkets capture volume concentration. Specialty Stores represent the steepest expansion trajectory.
Ingredient Type:
Application-specific formulation requirements are splitting R&D bandwidth between legacy dairy optimization and novel protein base approval pathways.
- Dairy-based:Conventional milkfat formulations face elevated raw material costs from EU Green Deal pesticide residue thresholds across European dairy feed crops.
- Plant-based:EFSA novel food approvals for oat and almond protein bases unlock formulation flexibility. Nordic and Benelux retail channels award shelf space premiums for dairy-free claims.
- Sugar-free:Alternative sweetener portfolios require reformulation for freeze-thaw stability. German health-conscious consumer segments drive demand concentration.
- Organic:Dual organic-carbon-neutral certification enables price tier separation in French and British premium segments under EU Green Deal climate targets.
Dairy-based commands current revenue share. Plant-based is climbing the fastest.
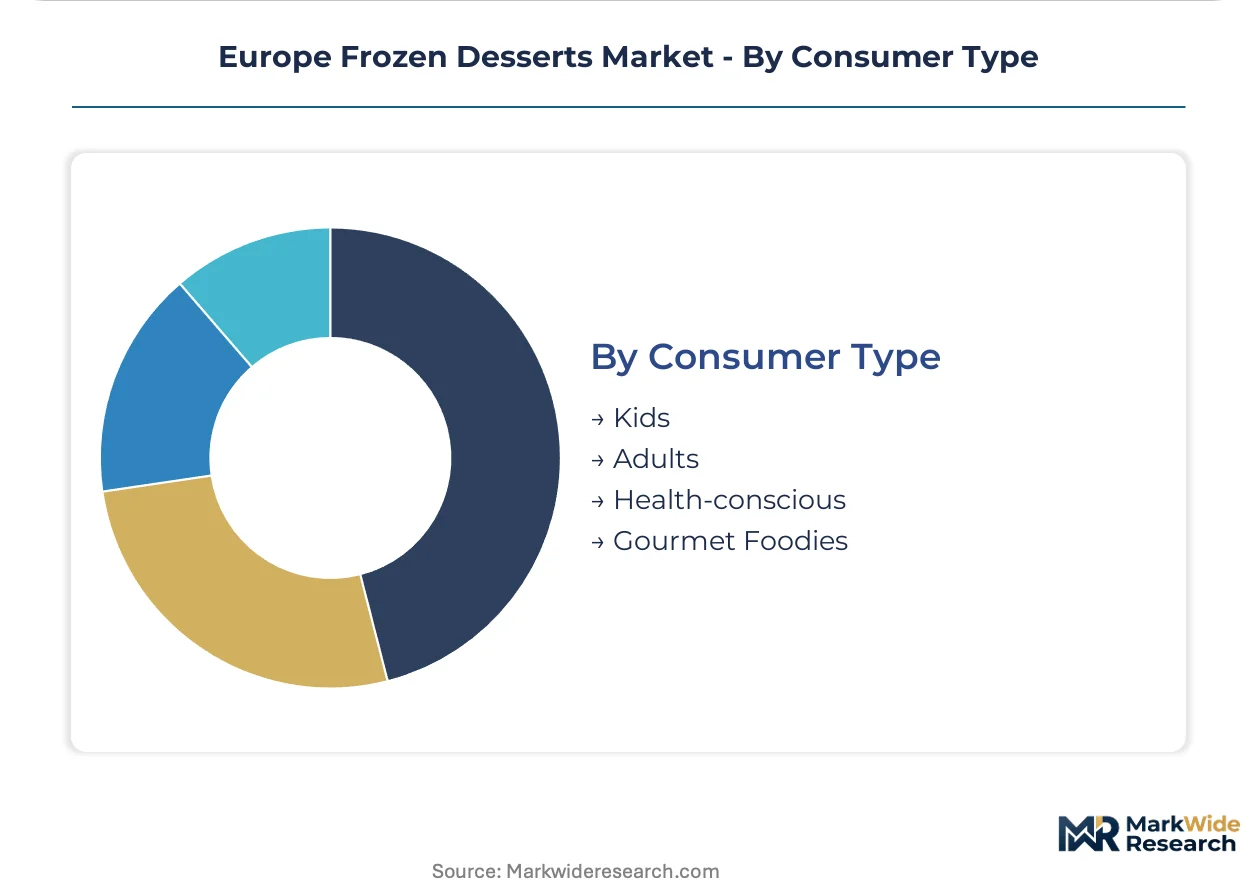
Consumer Type:
Margin structure varies by consumer archetype, with health-conscious and gourmet segments tolerating ingredient cost premiums that kids-oriented mass-market lines cannot absorb.
- Kids:Character-licensed formats and portion-controlled single-serve packaging dominate. British supermarket private-label buyers drive volume procurement.
- Adults:Indulgence-positioned premium tubs sustain higher price points. Italian and French retail channels favor sophisticated flavor profiles.
- Health-conscious:Protein-fortified and reduced-sugar claims command formulation investment. Nordic markets show strongest per-capita demand intensity.
- Gourmet Foodies:Artisan provenance and limited-batch positioning support margin extraction. Spanish urban specialty gelateria channels concentrate this segment.
Adults anchor mass-market revenue. Health-conscious consumers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentrates in Germany's discount supermarket networks and Italy's artisan gelateria clusters, with regulatory pressure from the EU Green Deal fragmenting manufacturing footprints across national compliance timelines.
Germany
Aldi and Lidl's private-label frozen dessert assortments drive volume procurement at continental scale. REACH-mandated stabilizer reformulation elevates R&D costs for mass-market producers serving these channels. Bavaria's dairy processing corridor anchors co-packing capacity for flexible manufacturers.
Italy
Artisan gelato credentials command price separation in Milan and Rome specialty retail. EFSA novel food approvals for alternative protein bases unlock formulation flexibility for traditional producers. Emilia-Romagna's equipment manufacturers deploy continuous freezing systems across urban gelateria chains.
France
Premium clean-label tiering rotates competitive positioning toward higher-margin organic and carbon-neutral claims. The EU Green Deal's Farm to Fork Strategy tightens pesticide residue thresholds across dairy feed crops. Parisian retail channels favor sophisticated indulgence-positioned formats.
United Kingdom
Supermarket buyer concentration compresses supplier negotiation cycles to quarterly frameworks demanding real-time cost transparency. ECHA's expanding candidate list of substances of very high concern reshapes emulsifier portfolios. London's specialty food halls sustain artisan delivery subscription growth.
Spain
Specialty gelateria channel expansion draws Italian-origin equipment investment toward Barcelona and Madrid urban centers. The EU Packaging and Packaging Waste Regulation accelerates fiber-based single-serve transitions. Andalusian dairy networks face elevated compliance costs from tightened sourcing standards.
Europe Frozen Desserts Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with consolidated multinational dairy networks anchoring volume tiers and artisan specialists capturing premium positioning. The market structures around three strategic archetypes: vertically integrated dairy conglomerates with flexible co-packing capacity, equipment-integrated artisan producers with location-specific manufacturing, and private-label specialists serving discount channel procurement rhythms. Dominant competitive moves include portfolio diversification across plant-based and dairy-based ingredient platforms and geographic expansion through equipment technology licensing.
Among diversified multinational conglomerates, Nestlé, Unilever, and Ferrero Group occupy positions spanning multiple price bands and occasion segments. Nestlé exemplifies cost discipline through captive European dairy supply networks. Unilever anchors category visibility through intensive freezer-door placement in British and German supermarkets. Ferrero Group represents indulgence-focused formulation strategies targeting gift and seasonal occasion segments.
| Leading Market Players |
|---|
| Mondelēz International |
| Dunkin' Brands |
| Nestlé |
| Fonterra Co-operative Group |
| Chobani |
| Unilever |
| Ferrero Group |
| Lindt & Sprüngli |
| General Mills |
| Others |
Supply & Pricing Matrix
Discount supermarket scale economies in Germany compress unit economics across mass-market tiers while elevating price floors for artisan-positioned formats. Aldi and Lidl's procurement rhythms force simultaneous cost discipline on dairy networks and stabilizer reformulation investments, squeezing mid-tier producers between volume pressure and compliance premiums.
Pricing Analysis
The EU Green Deal's Farm to Fork Strategy dictates the pricing tier structure across European frozen desserts, separating organic-carbon-neutral certified premiums from conventional dairy-base standards and discount private-label economy tiers. Price differentiation rests on dual certification grade and channel positioning, with French and British premium retail awarding shelf space premiums for clean-label claims while German discount buyers suppress margin extraction through quarterly negotiation cycles. Cost compression in the mid-tier standard segment is intensifying because REACH-mandated stabilizer reformulation elevates R&D outlays before clean-label premiums fully offset input inflation. Kids-oriented mass-market lines show highest price sensitivity, while gourmet foodies in Italian urban specialty channels tolerate ingredient cost premiums that mass-market producers cannot absorb.
Supply Chain Analysis
Just-in-time dairy procurement dominates mass-market production while artisan gelateria operators prefer strategic stockpiles of specialty ingredients to buffer seasonal demand spikes. Geographic supply concentration centers on Germany's Bavarian dairy processing corridor, Italy's Emilia-Romagna equipment manufacturing cluster, and France's paperboard converting operations for fiber-based packaging transitions. Raw material dependencies draw from European dairy feed crops, oat and almond protein bases, and hydrocolloid stabilizer portfolios. Single-source vulnerability concentrates among specialty ingredient houses with pre-approved clean-label emulsifier alternatives. Distribution runs through British and German supermarket freezer-door networks for volume tiers, with Italian and Spanish specialty retail chains deploying location-specific production equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant-based ingredient penetration in Nordic and Benelux markets signals early-cycle expansion, with EFSA novel food approvals unlocking formulation flexibility ahead of mainstream dairy displacement.
For Market Incumbents: Consolidate backward integration into captive European dairy supply networks to sustain cost discipline across multiple price bands. Nestlé's network architecture exemplifies defensive positioning against plant-based entrants. Channel control through intensive freezer-door placement in British and German supermarkets anchors volume visibility. Certification investment in dual organic-carbon-neutral claims under EU Green Deal climate targets enables premium tier separation.
For New Entrants and Emerging Players: Subscription-based artisan delivery in Benelux urban corridors represents a service-layer gap where incumbents under-serve direct-to-consumer frozen logistics. Eastern European urban markets show lowest equipment penetration for continuous freezing technology miniaturization. Spanish and Portuguese specialty retail chains offer the most penetrable geography for Italian-origin equipment licensing partnerships. Go-to-market through equipment-integrated production rather than centralized manufacturing differentiates capital efficiency.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among equipment-integrated artisan producers with location-specific manufacturing and subscription delivery capabilities. Long-term viability over the five-to-ten year window favors manufacturers with flexible co-packing capacity and pre-approved clean-label ingredient portfolios. Acquisition target archetype: mid-tier producers with stranded legacy cold chain assets requiring -25°C infrastructure but lacking -18°C gelato distribution capabilities. Signal to monitor: ECHA candidate list expansion timelines for substances of very high concern reshaping emulsifier portfolios.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Stabilizer Reformulation | REACH compliance creates first-mover positioning for reformulated product lines ahead of mandatory restrictions. |
| Continuous Freezing Technology Licensing | Italian equipment manufacturers compress capital recovery periods for Spanish and Portuguese specialty retail chains. |
| Fiber-Based Packaging Transition | EU Packaging and Packaging Waste Regulation mandates 2030 deadlines that favor captive paperboard converters in France and Germany. |
| Plant-Based Protein Platform Expansion | EFSA novel food approvals for oat and almond bases unlock formulation flexibility in Nordic and Benelux retail channels. |
| Discount Channel Co-Packing Capacity | Aldi and Lidl procurement rhythms favor manufacturers with flexible dairy networks and real-time cost transparency systems. |
Research Methodology
Operator-level perspectives from brand managers at multinational conglomerates, category buyers at British and German supermarket chains, supply planners in Bavarian dairy processing corridors, and technical R&D directors at Italian equipment manufacturers anchored the qualitative base. Primary interview insights combined with secondary validation from EFSA novel food approval databases, ECHA substance restriction candidate lists, EU Green Deal Farm to Fork Strategy implementation documents, and Nielsen retail audit data for frozen dessert categories. Bottom-up channel volume assessments and top-down regulatory impact triangulation converged on segment-level estimates.
Sensitivity analysis tested forecast robustness across alternative protein adoption scenarios and REACH compliance timeline variations. The analytical framework modeled product type, distribution channel, ingredient platform, and consumer archetype dimensions across the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific forecast inputs included EFSA approval pipeline timelines for emerging protein bases and equipment miniaturization cost curves for artisan-scale production.
Underlying assumptions cover ECHA substance restriction implementation schedules and EU Packaging and Packaging Waste Regulation fiber-based format transition compliance rates, with deviation risk concentrated in EFSA novel food approval delays and dairy feed crop pesticide threshold enforcement intensity. Forecasts reflect these assumption layers without claiming predictive certainty. Revision becomes warranted when plant-based volume share crosses thresholds that trigger supermarket buyer reallocation of freezer-door placement economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed and Frozen Foods
Frozen Mackerel Market
Processed and Frozen Foods
Global Frozen Fish and Seafood Market
Processed and Frozen Foods
Chilled Meal Kits Market
Processed and Frozen Foods
North America Frozen Pizza Market
Processed and Frozen Foods
Frozen Pork Belly Market
Processed and Frozen Foods
North America French Fries Market
Processed and Frozen Foods
Frozen Snacks Market
Processed and Frozen Foods
Refrigerated Liquid Eggs Market
Processed and Frozen Foods
Frozen Meat and Fish Market
Processed and Frozen Foods
Processed and Frozen Fruits Market
Processed and Frozen Foods
Frozen Fruit Bars Market
Processed and Frozen Foods
Asia-Pacific Frozen Food Market
Processed and Frozen Foods
Freeze Dried Vegetables Market
Processed and Frozen Foods
Freeze Dried Mangos Market
Processed and Frozen Foods
Freeze-Dried Food Market
Processed and Frozen Foods
Frozen Meat Market