
 Dehydrated and Dried Beans Market | 2026-2036
Dehydrated and Dried Beans Market Size, Share, and Industry Trends Forecast 2026-2036
Dehydrated and Dried Beans Market Intelligence
Subscription-based ingredient replenishment programs for food service accounts is realigning how dehydrated beans move through supply chains. SunOpta leverages its integrated organic sourcing network to secure consistent supply of chickpeas and kidney beans. Van Drunen Farms anchors its position through specialized air-drying and freeze-drying capabilities that preserve nutritional profiles. Harmony House differentiates via direct-to-consumer retail packs targeting backpacking and emergency preparedness segments.
Dehydrated and dried beans are legumes processed through thermal drying, freeze-drying, or air-drying to reduce moisture content below 10%, extending shelf life without refrigeration while retaining protein and fiber content for food manufacturing and consumer preparation. The product type dimension shows chickpeas commanding premium positioning in health food channels due to protein density and versatility in plant-based formulations, while black beans dominate food service volumes through Latin American and Southwestern cuisine adoption. Packaging type reveals bulk bags capturing institutional procurement for manufacturing, whereas vacuum sealed formats extract margin premiums in specialty retail by emphasizing flavor preservation and extended storage stability.
FDA food safety modernization rules and USDA organic certification requirements govern domestic market access, while EU REACH and EFSA residue limits shape import eligibility for European-bound shipments. These frameworks elevate compliance costs for smaller processors but create barriers that favor scaled operators with dedicated quality assurance infrastructure. Stakeholders must monitor evolving carbon border adjustments and regenerative agriculture verification standards that will increasingly determine supplier eligibility in priority export corridors.
Market Dynamics
Food service operators are accelerating procurement of shelf-stable legume ingredients to reduce cold-chain dependency and buffer against energy cost volatility. This operational pivot is compressing traditional wholesale distribution layers and elevating direct processor relationships.
Growth Catalysts
- EU Green Deal traceability mandates:Sustainable agriculture requirements are tightening documentation standards for imported pulses, favoring processors with integrated organic sourcing networks who can verify regenerative practices.
- Freeze-drying technology maturation:Advanced dehydration methods preserve nutritional profiles and rehydration performance, unlocking premium positioning in health food channels and plant-based formulations.
- Brazil export infrastructure scaling:Domestic processors are expanding dehydration capacity to capture share in European and North American markets seeking non-Asian supply alternatives.
Market Restraints
- Energy cost volatility:Thermal drying and freeze-drying processes consume substantial electricity and natural gas, exposing margins to input cost swings without long-term hedging instruments.
- Supply concentration in drought-prone regions:Chickpea and black bean sourcing clusters in specific agricultural belts create yield risk exposure that processors cannot easily diversify.
- Regulatory friction from FDA modernization rules:Enhanced food safety documentation and preventive control requirements impose compliance burdens that disproportionately strain smaller dehydration facilities.
Strategic Opportunities
- Subscription replenishment models:Food service accounts are piloting automated ingredient restocking programs that bypass traditional distributor markups and lock in volume commitments.
- Carbon border adjustment readiness:Early investment in regenerative agriculture verification and lifecycle carbon accounting positions suppliers for preferential access to EU markets as CBAM phases in.
- Emergency preparedness retail channel:Direct-to-consumer vacuum-sealed packs for backpacking and disaster readiness segments command margin premiums through specialty outdoor retailers.
Industry Challenges
- Certification timeline compression:USDA organic and EU organic equivalency approvals now require 18-24 month validation cycles that delay new supplier market entry.
- Legacy ERP integration friction:Food manufacturers demand real-time lot traceability data feeds that smaller dehydration facilities cannot support without capital-intensive system overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dehydrated and Dried Beans Market |
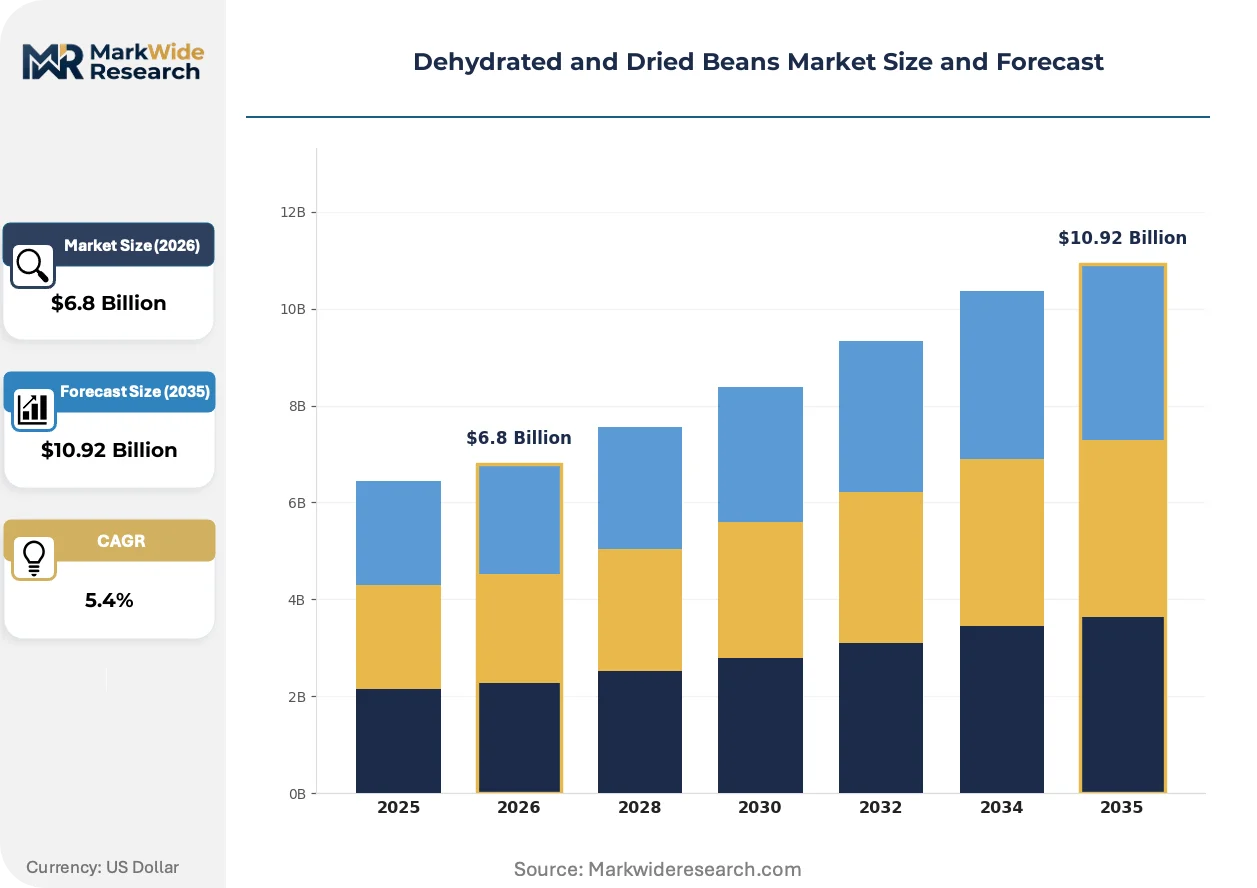
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Black Beans, Pinto Beans, Kidney Beans, Chickpeas Packaging Type: Bulk Bags, Retail Packs, Cans, Vacuum Sealed End Use Industry: Food Service, Retail, Hospitality, Health Food Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesalers |
| Companies Covered | B.C. Foods, Van Drunen Farms, Harmony House, Chelmer Foods Limited, Colin Ingredients, SunOpta, Garlico Industries, Silva International, OFD Foods LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dehydrated and Dried Beans Market Strategic Shifts & Innovations
Processing technology convergence and procurement model reinvention are compressing traditional supply chain intermediaries while elevating transparency requirements. These forces favor capitalized operators capable of integrating traceability infrastructure with flexible production formats.
Infrared-assisted drying combined with precision moisture sensing is electrifying throughput efficiency in dehydration facilities. Mid-scale processors serving food manufacturers are retrofitting production lines to capture energy savings and reduce rehydration time variability. This technology compression is enabling same-day turnaround on custom bean blends that previously required week-long scheduling windows.
REACH substance restrictions and EFSA residue limit updates are tightening import eligibility criteria for European-bound pulse shipments. Dehydration facilities must now maintain dual-certified cleaning protocols and contaminant testing regimens to maintain market access. Black bean and kidney bean suppliers targeting EU food service channels are absorbing elevated compliance costs or ceding volume to domestic European processors.
Ingredient buyers are consolidating supplier relationships around processors offering integrated organic certification and carbon footprint documentation. Large food manufacturers are displacing multi-source procurement with single-source accountability partnerships that bundle quality assurance and sustainability verification. This concentration pattern is most visible in North American plant-based meat and dairy alternative segments where clean-label positioning drives sourcing decisions.
Dehydrated and Dried Beans Market Segmentation
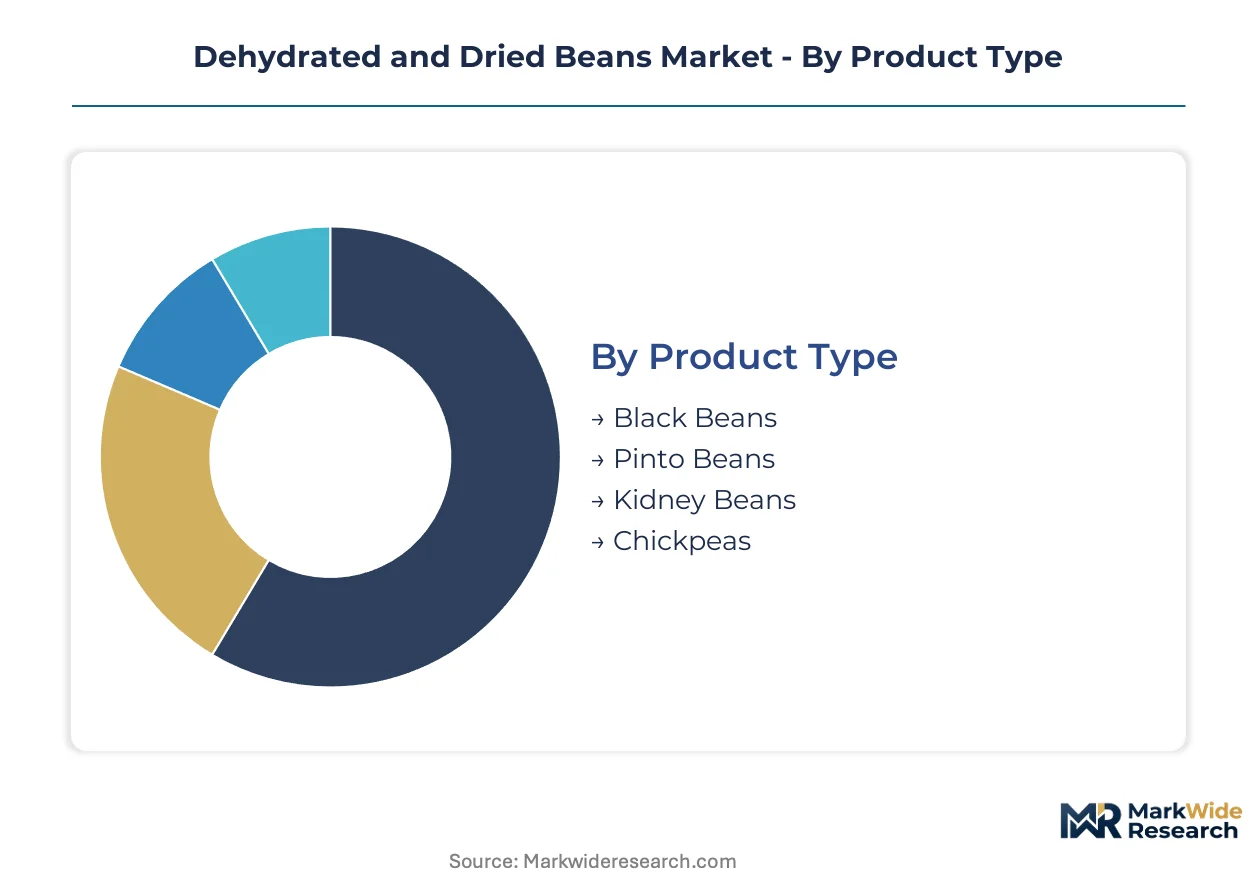
Dehydrated and dried beans fragment across four intersecting dimensions that determine margin capture and supply chain configuration. Product type dictates nutritional positioning and cuisine alignment. Packaging, end use, and distribution channel collectively determine price realization and customer access economics.
Product Type:
Standardization dominates commodity pulses while specialty varieties command premium positioning through protein density and functional versatility.
- Chickpeas:Higher protein concentration and superior rehydration performance anchor premium pricing in plant-based meat formulations. Demand concentrates in North American health food channels where clean-label positioning drives procurement decisions.
- Black Beans:Latin American and Southwestern cuisine adoption generates institutional volumes through food service distributors. Mexican and Central American processors leverage proximity advantages for US market supply.
- Pinto Beans:Versatile culinary applications across Tex-Mex and traditional American cooking sustain steady manufacturing demand.
- Kidney Beans:Chili and salad bar applications dominate institutional procurement with color-grade specifications determining lot acceptance.
Leading the category by volume: Black Beans. Expanding most quickly: Chickpeas.
Packaging Type:
Volume scale and shelf-life requirements create distinct margin tiers across format selection.
- Bulk Bags:25-50kg polywoven containers serve food manufacturers with high-throughput processing lines and captive grinding operations. Brazilian and US Midwest dehydration facilities optimize freight economics through rail-car loading.
- Vacuum Sealed:Multi-layer barrier films extract 40-60% price premiums over standard retail by guaranteeing 24-month stability without oxygen degradation. Emergency preparedness and backpacking segments absorb elevated unit costs.
- Retail Packs:Stand-up pouches and paperboard cartons target household rehydration with portion-controlled formats.
- Cans:Ready-to-heat convenience positioning captures time-constrained consumers despite higher moisture content and shipping weight.
Highest volume flows through Bulk Bags. Steepest expansion trajectory: Vacuum Sealed.
End Use Industry:
Operational requirements around cold-chain independence and labor intensity separate procurement patterns.
- Food Service:College dining, military feeding, and contract catering operations prioritize shelf-stable inventory that eliminates refrigeration capital and energy costs. Menu versatility across chili, burrito bowls, and salad bars sustains consistent offtake.
- Health Food:Plant-based meat and dairy alternative manufacturers specify organic-certified chickpeas with documented amino acid profiles for protein fortification claims.
- Retail:Grocery and club store channels balance turnover velocity with margin preservation through private-label and branded assortment.
- Hospitality:Hotel breakfast buffets and banquet operations value speed-scratch preparation with minimal kitchen labor.
Food Service generates the largest procurement volumes. Health Food climbs fastest on plant-based formulation demand.
Distribution Channel:
Customer scale and technical service requirements determine channel economics and relationship intensity.
- Wholesalers:Broadline distributors aggregate fragmented food service demand and provide credit terms that smaller operators cannot match directly. Sysco and US Foods procurement specifications drive processor quality system investments.
- Online Retail:Direct-to-consumer subscription models bypass distributor markups and capture recurring revenue with automated replenishment algorithms.
- Supermarkets:Mass-market retail placement requires slotting fee negotiations and promotional calendar coordination.
- Specialty Stores:Outdoor recreation and preparedness retailers command margin premiums through curated assortment and expert staff recommendation.
Wholesalers move the greatest tonnage. Online Retail gains share fastest on subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors North American processing capacity through SunOpta's integrated organic sourcing network that supplies chickpeas and kidney beans to plant-based meat manufacturers. The metropolitan corridor concentrates dehydration infrastructure and food-grade warehousing that serves both domestic and export channels.
United States
Food service operators across college dining and military feeding systems are consolidating procurement around shelf-stable legume ingredients that eliminate refrigeration capital. FDA food safety modernization rules impose preventive control documentation that favors scaled dehydration facilities with dedicated quality assurance staff. The Upper Midwest corridor spanning Minnesota and Wisconsin hosts the densest concentration of thermal drying and freeze-drying capacity serving North American manufacturing demand.
Brazil
Domestic processors are scaling dehydration infrastructure to capture European and North American market share as buyers seek non-Asian supply alternatives. ANVISA alignment with international food safety standards enables export eligibility while the EU Green Deal traceability mandates drive investment in regenerative agriculture verification. The central-west agricultural belt surrounding Goiânia concentrates black bean and pinto bean sourcing with new dehydration facilities coming online near Brasília.
Germany
REACH substance restrictions and EFSA residue limit updates are tightening import eligibility for pulse shipments from non-EU sources. The country's national food safety regulator enforces dual-certified cleaning protocols that smaller foreign processors struggle to maintain. The Hamburg port cluster serves as the primary entry point for dehydrated bean imports destined to Central European food manufacturers and food service distributors.
Netherlands
Rotterdam's logistics hub status positions the country as the distribution gateway for dehydrated beans entering European manufacturing channels. EU organic equivalency requirements and carbon border adjustment preparations are elevating documentation standards for suppliers seeking preferential market access. The Eindhoven region hosts specialized ingredient brokers that aggregate demand from plant-based meat startups and health food channels across Northern Europe.
India
FSSAI food safety standards and export promotion schemes are driving investment in dehydration capacity for chickpea processing destined to Middle Eastern and European markets. The country's national agricultural regulator enforces residue testing protocols that align with EFSA requirements for premium export segments. The Indore corridor in Madhya Pradesh concentrates domestic chickpea sourcing with new dehydration facilities scaling to serve international procurement from health food channels.
Dehydrated and Dried Beans Market Key Industry Players
Capital-heavy dehydration facility operators compete with asset-light ingredient brokers and specialty retailers in a market that fragments across scale tiers and certification levels. Mid-scale processors serving food manufacturers face consolidation pressure as large buyers demand integrated organic certification and real-time lot traceability. Three strategic archetypes dominate: vertically integrated organic specialists, technology-differentiated dehydration engineers, and direct-to-consumer retail packagers. Competitive intensity centers on M&A activity targeting regional dehydration assets and strategic partnerships that bundle quality assurance with carbon footprint documentation.
Within the technology-differentiated tier, Van Drunen Farms and SunOpta exemplify divergent approaches to value capture. Van Drunen Farms occupies a position defined by specialized air-drying and freeze-drying capabilities. SunOpta anchors the integrated organic sourcing archetype through its Minneapolis-based network. Harmony House sits within the direct-to-consumer specialty tier targeting emergency preparedness and outdoor recreation segments.
| Leading Market Players |
|---|
| B.C. Foods |
| Van Drunen Farms |
| Harmony House |
| Chelmer Foods Limited |
| Colin Ingredients |
| SunOpta |
| Garlico Industries |
| Silva International |
| OFD Foods LLC |
| Others |
Cost & Logistics Intelligence
Skilled dehydration technicians in the Upper Midwest corridor create labor-cost differentials that widen pricing-tier spreads between freeze-dried premium chickpeas and commodity thermal-dried black beans. Brazilian processing clusters leverage lower wage structures to undercut North American spot pricing while EU organic certification premiums absorb elevated compliance labor.
Pricing Analysis
Yield-based pricing anchors the dehydrated beans market, with contract structures tying processor payments to rehydration performance ratios and protein retention metrics. Three-tier pricing stratifies across organic-certified premium, conventional standard, and commodity economy levels, with EU organic equivalency and carbon footprint documentation commanding the widest spreads. Cost compression in the economy tier intensifies as Brazilian capacity expansion floods spot markets with undifferentiated pinto and black bean volumes. Food service distributors exhibit the highest price sensitivity due to thin menu-margin structures, while plant-based meat manufacturers absorb premiums for documented amino acid profiles.
Supply Chain Analysis
Return flows of non-conforming lots and packaging material recovery programs operate minimally in dehydrated beans, with most reverse logistics limited to bulk bag reclamation at food manufacturing facilities. Supply concentrates in Brazil, the United States, and India, with the central-west Brazilian belt feeding export markets and the Upper Midwest corridor serving North American manufacturing. Raw material dependencies center on chickpea, black bean, and pinto bean harvests from drought-prone agricultural belts in North Dakota, Saskatchewan, and Madhya Pradesh. Single-source vulnerability from concentrated organic acreage in specific counties creates yield risk exposure. Distribution runs through broadline food service wholesalers and direct processor relationships with plant-based meat manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dehydrated and dried beans is becoming a vertical-integration race, with processors pursuing backward integration into organic acreage to lock in regenerative agriculture verification for EU Green Deal compliance.
For Market Incumbents: To counter margin erosion from Brazilian spot-market flooding, SunOpta and Van Drunen Farms should deepen captive supply of organic chickpea acreage in Minnesota and North Dakota while retrofitting legacy thermal dryers with infrared-assisted precision moisture systems. Certification investment in EU organic equivalency and carbon border adjustment readiness creates switching costs that smaller processors cannot match. For New Entrants and Emerging Players: Begin with vacuum-sealed retail packs targeting the emergency preparedness and backpacking segments, where Harmony House has proven margin extraction through specialty outdoor retailers. The direct-to-consumer subscription channel remains underpenetrated relative to food service volumes, offering automated replenishment algorithms that bypass Sysco and US Foods markups. A go-to-market angle bundling regenerative agriculture storytelling with 24-month shelf-life guarantees unlocks premium positioning. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale dehydration facilities holding dual USDA-EU organic certification and existing food manufacturer relationships, given carbon border adjustment implementation and traceability mandate tightening. Long-term viability favors processors with integrated sourcing networks rather than toll-dehydration operators exposed to commodity margin cycles. Monitor EU Green Deal secondary legislation releases for inflection signals on regenerative agriculture verification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Acreage | Captive chickpea supply from Minnesota farmers secures EU Green Deal traceability documentation. |
| Infrared-Assisted Drying Retrofit | Precision moisture sensing at Van Drunen Farms reduces rehydration time variability for plant-based meat clients. |
| EU Organic Equivalency Certification | Dual-certified cleaning protocols at SunOpta unlock preferential access to Rotterdam distribution channels. |
| Direct-to-Consumer Subscription Launch | Automated replenishment algorithms bypass broadline distributor markups in emergency preparedness segments. |
| Carbon Border Adjustment Readiness Program | Lifecycle carbon accounting positions Brazilian processors for phased EU import preference eligibility. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with dehydration facility plant managers, organic certification auditors, food service procurement directors at Sysco and US Foods, and plant-based meat manufacturer sourcing leads. FDA food safety modernization documentation, USDA organic certification databases, ANVISA export eligibility records, and EU REACH substance restriction updates provided triangulation points. Bottom-up volume modeling across product type, packaging format, and end-use segments converged with top-down trade flow analysis.
Granularity-level modeling operated at the processor-facility level for capacity utilization, the crop-belt level for yield assumptions, and the customer-segment level for price realization. Segmentation dimensions included product type, packaging type, end-use industry, and distribution channel, with organic certification status and dehydration technology type as cross-cutting variables. CAGRs derived from regression against historical trade volumes and forward projection of food service cold-chain reduction trends. Energy cost volatility assumptions and drought frequency patterns informed scenario-weighted outcomes.
Underlying measurement precision varies by segment; vacuum-sealed retail and health food channel data carry tighter precision than commodity bulk bag flows through informal brokers. Forecasts reflect assumptions around EU Green Deal implementation pace, Brazilian real exchange rate stability, and freeze-drying technology cost curves. Practitioners should monitor EU carbon border adjustment phase-in announcements, Upper Midwest drought severity indices, and plant-based meat manufacturer inventory destocking cycles for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
North America Instant Noodles Market
Packaged Foods
UAE Breakfast Cereals Market
Packaged Foods
Convenience Food Market
Packaged Foods
Global Popping Candy Market
Packaged Foods
Global Oven Bags Market
Packaged Foods
North America Ready Meals Market
Packaged Foods
Cookie Pucks Market
Packaged Foods
Canned Fruits Market
Packaged Foods
Instant Noodles Market
Packaged Foods
Private Label Food and Beverage Market
Packaged Foods
Carbon Labeled Packaged Meal Market
Packaged Foods
Asia-Pacific Pasta and Noodles Market
Packaged Foods
Europe Noodles and Pasta Market
Packaged Foods
Europe Ready Meals Market
Packaged Foods
Club Store Packs Market
Packaged Foods
Pre-Packaged Food Market