
 Australia Anti Caking Market | 2026-2036
Australia Anti Caking Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Anti Caking Market Outlook
Specialized formulation chemists with silicate surface-modification expertise is unwinding capacity constraints across domestic manufacturing. Evonik Industries AG leverages its precipitated silica technology portfolio to anchor premium supply relationships with Australian food processors. BASF SE competes through sustained investment in food-grade calcium silicate production tailored to FSANZ-compliant applications. Cargill Incorporated dominates distribution channels, extending its agricultural inputs network into anti-caking procurement for fertilizer and feed segments.
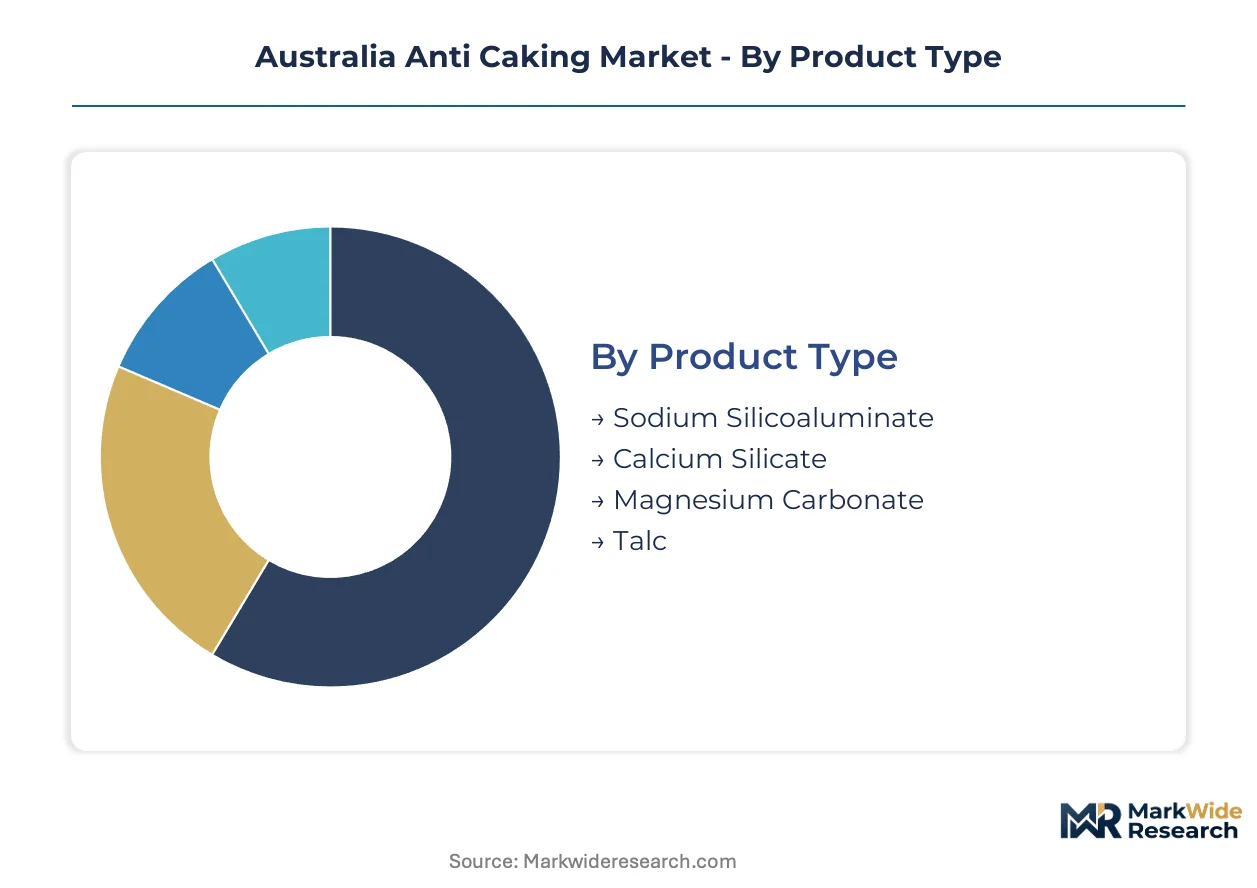
Anti-caking agents are hygroscopic powder additives, typically comprising silicate salts or carbonate minerals processed to specific particle sizes between 2-10 microns, designed to absorb moisture and maintain free-flow characteristics in bulk solids. These agents prevent agglomeration in powdered foods, pharmaceuticals, and agricultural inputs during storage and transport under variable humidity conditions. Sodium silicoaluminate formulations lead product type demand due to established cost-performance ratios in salt and seasoning applications, while magnesium carbonate variants represent the fastest-growing category driven by clean-label positioning among natural product manufacturers. Powder form maintains structural dominance across end-user procurement, though granule formats are gaining share among chemical companies seeking reduced dust exposure during handling.
FSANZ governs food additive permissions through Schedule 15-16 of the Australia New Zealand Food Standards Code, directly determining which silicate compounds qualify for domestic food manufacturing. TGA (Therapeutic Goods Administration) oversees pharmaceutical-grade anti-caking specifications for tablet and capsule excipients, creating parallel compliance pathways for manufacturers serving both food and drug channels. Chemical companies must additionally navigate NICNAS chemical inventory requirements for industrial anti-caking formulations. Stakeholders should monitor pending FSANZ reviews on silicate additive maximum permitted levels, as tightening thresholds would force reformulation investments and reshape supplier qualification criteria across the value chain.
Market Dynamics
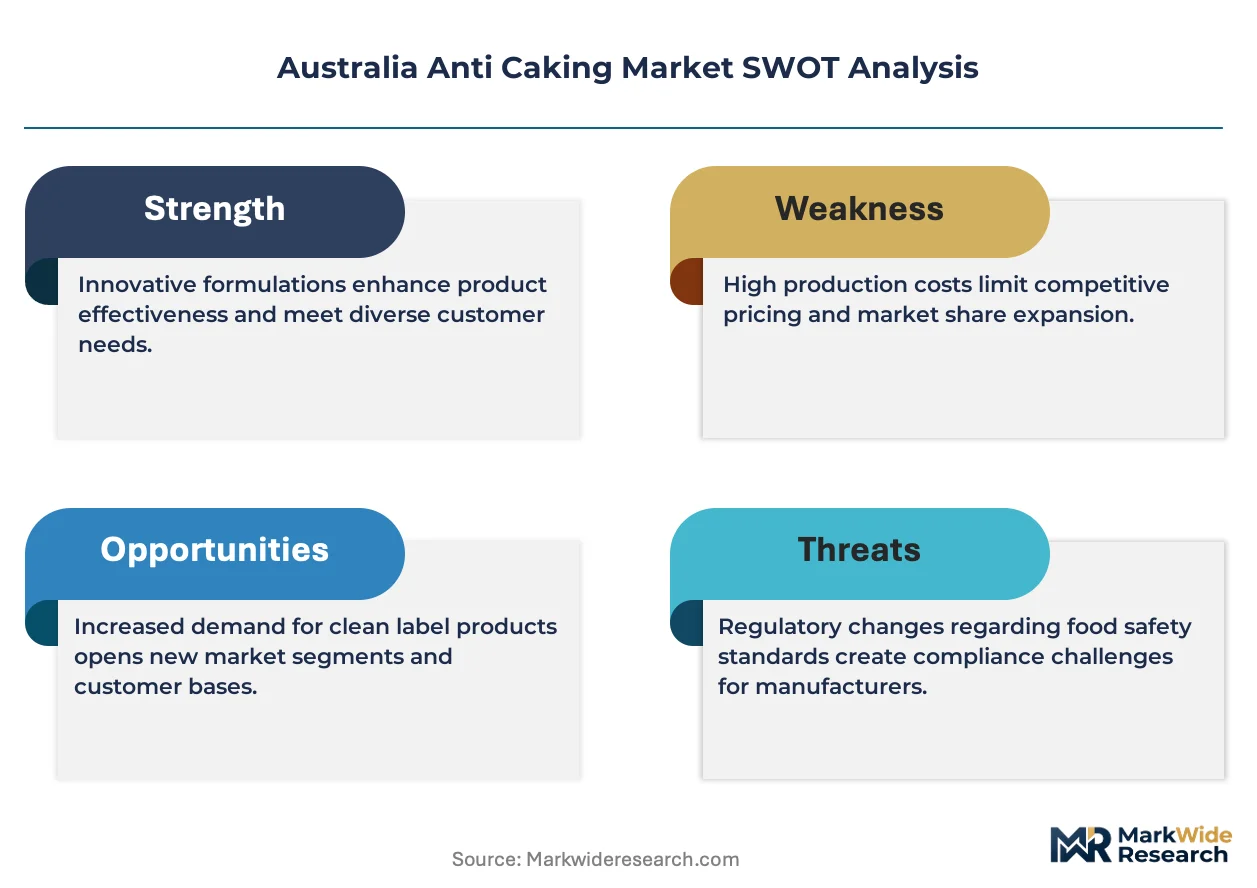
FSANZ code revisions on silicate additive permissions are compressing supplier qualification timelines while elevating purity benchmarks, forcing domestic manufacturers to accelerate reformulation cycles ahead of enforcement deadlines.
Growth Catalysts
- Processed food expansion:Industrial bakers across Victoria and New South Wales are scaling anti-caking procurement for humidity-resistant seasoning blends and instant soup powders.
- Schedule 15-16 permissions:FSANZ's clarified additive codes provide regulatory certainty for silicate-based flow agents in salt applications, reducing compliance ambiguity for domestic formulators.
- Precipitated silica technology:Advanced surface-modification techniques are unlocking moisture absorption performance previously restricted to imported formulations.
Market Restraints
- Specialized chemist scarcity:Domestic capacity for silicate surface-modification expertise remains concentrated among a limited pool of formulation specialists in Sydney and Melbourne.
- Import dependency for premium grades:Food-grade calcium silicate meeting tightened FSANZ purity thresholds relies heavily on European and North American supply channels.
- Clean-label substitution pressure:Magnesium carbonate variants face cost-performance gaps against established sodium silicoaluminate formulations in high-volume salt applications.
Strategic Opportunities
- Queensland manufacturing corridor:Underdeveloped anti-caking formulation infrastructure in Brisbane and surrounding industrial zones offers first-mover positioning for regional supply hubs.
- Pharmaceutical excipient crossover:TGA-compliant tablet and capsule applications create parallel demand channels for manufacturers holding dual food-drug certifications.
- Granule format adoption:Chemical companies handling industrial agricultural inputs are migrating toward reduced-dust granule formats, opening equipment upgrade and formulation service revenue streams.
Industry Challenges
- Dual certification complexity:Manufacturers serving both FSANZ food channels and TGA pharmaceutical specifications face divergent documentation and audit timelines.
- Reformulation capex cycles:Pending FSANZ maximum permitted level reviews threaten forced capital deployment into alternative silicate compounds before amortization of existing production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Anti Caking Market |
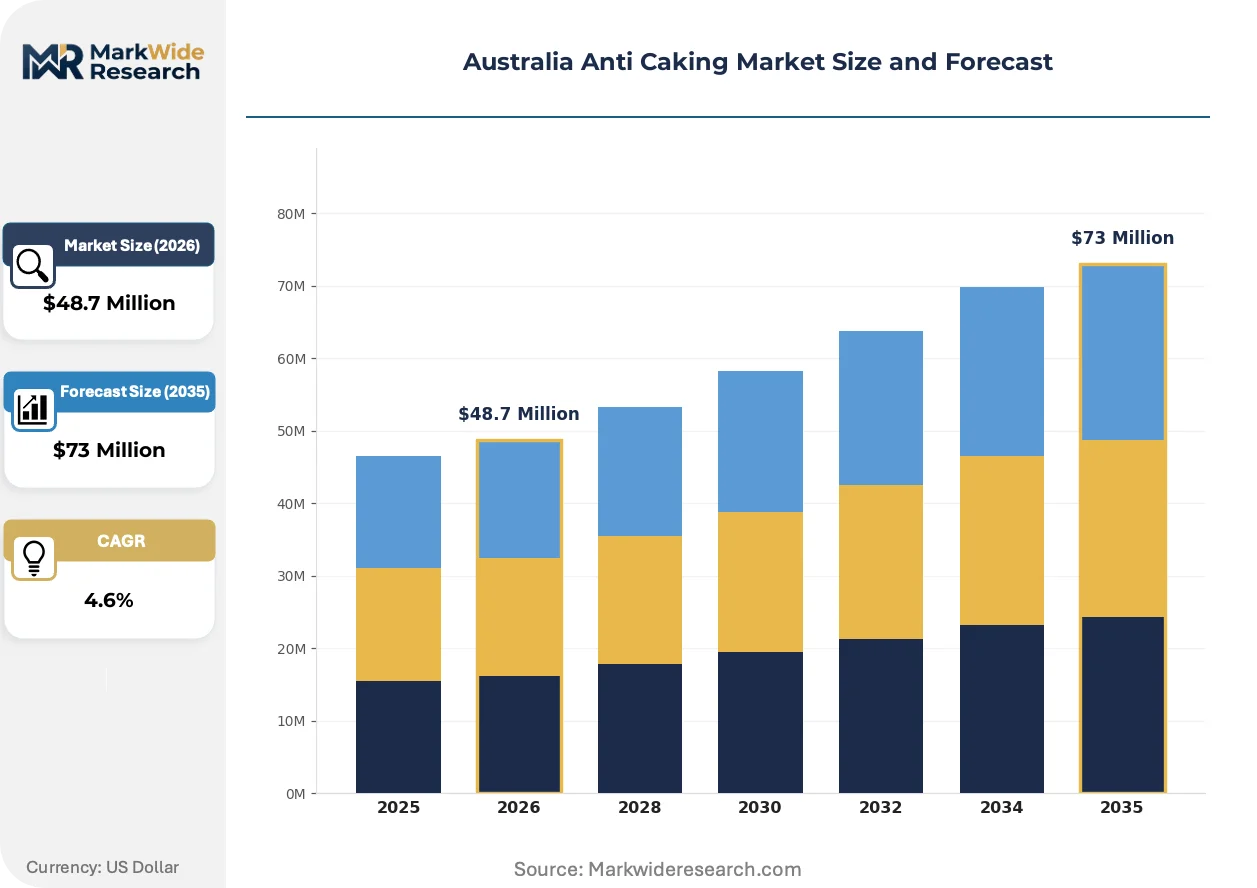
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $73 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Silicoaluminate, Calcium Silicate, Magnesium Carbonate, Talc Application: Food, Pharmaceuticals, Chemicals, Agriculture End User: Bakers, Food Manufacturers, Chemical Companies, Agrochemical Providers Form: Powder, Granule, Pellet, Liquid |
| Companies Covered | Evonik Industries AG, The Agropur Dairy Cooperative, Merck KGaA, Brenntag GmbH, BASF SE, Cargill Incorporated, PPG Industries, Huber Engineered Materials, Solvay, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Anti Caking Market Strategic Shifts
Moisture-resistant formulation architectures are fragmenting traditional procurement patterns as end-users segment specifications by humidity exposure severity rather than commodity-grade standardization.
Surface-modified precipitated silica is bifurcating the mid-tier additive segment. Premium food processors in Melbourne are adopting these formulations for seasoning applications requiring sub-5% moisture pickup under tropical storage conditions. The technology is bifurcating supplier tiers into performance-certified specialists versus commodity distributors unable to document particle-size consistency below 10 microns.
FSANZ's pending Schedule 16 silicate threshold reviews are compressing formulation development cycles. Domestic manufacturers must pre-validate alternative compounds before final rule publication to maintain uninterrupted supply relationships. Salt and seasoning blend producers face the steepest compliance recertification burdens given their reliance on sodium silicoaluminate at current maximum permitted levels.
Specification-driven procurement is displacing spot-market purchasing among industrial food processors. Sydney-based bakers and soup manufacturers are locking multi-year supply agreements with documented humidity-stability performance guarantees. This behavioral shift concentrates contract volume among three to four qualified domestic distributors while marginalizing import-reliant traders lacking local technical support capabilities.
Australia Anti Caking Market Segmentation
Australian anti-caking procurement splits sharply between commodity salt applications and precision-formulated food processing needs. FSANZ Schedule 15-16 permissions create divergent compliance pathways across each segment cluster, forcing buyers to qualify suppliers against additive-specific purity benchmarks rather than generic food-grade certifications.
Product Type:
Magnesium carbonate faces the most acute substitution pressure from clean-label positioning, while sodium silicoaluminate defends its installed base through cost-performance advantages in high-volume salt applications.
- Sodium Silicoaluminate:Synthetic amorphous aluminosilicate processed to 2-10 micron particle sizes delivers established moisture absorption in salt and seasoning blends. Victorian and New South Wales food manufacturers specify this compound for humidity-resistant instant soup powders where FSANZ maximum permitted levels currently allow sufficient loading rates.
- Calcium Silicate:Porous synthetic silicate manufactured through precipitation reactions offers lower bulk density and enhanced oil absorption capacity. Premium food processors in Sydney and Melbourne are qualifying calcium silicate for seasoning applications requiring sub-5% moisture pickup under tropical storage conditions, though import dependency constrains domestic supply security.
- Magnesium Carbonate:Naturally sourced carbonate mineral appeals to clean-label manufacturers seeking non-synthetic flow agents.
- Talc:Hydrated magnesium silicate with lamellar crystal structure serves niche pharmaceutical and agricultural applications outside core food channels.
Sodium silicoaluminate retains volume leadership; magnesium carbonate holds the steepest expansion curve.
Application:
Cost tier stratification separates premium pharmaceutical specifications from commodity agricultural procurement, with food-grade applications occupying the contested middle ground where FSANZ compliance investments concentrate.
- Food:Powdered seasonings, salt, baking mixes, and instant soup formulations require humidity-stable flow characteristics under variable Australian climate conditions. Melbourne and Sydney industrial bakers drive specification intensity for moisture-resistant architectures.
- Pharmaceuticals:Tablet and capsule excipients demand TGA-compliant documentation parallel to FSANZ food additive permissions. Dual-certified manufacturers capture premium positioning by serving both regulatory channels with unified quality systems.
- Chemicals:Industrial powder processing applications prioritize dust reduction and handling efficiency over purity metrics.
- Agriculture:Fertilizer and feed additive applications specify anti-caking agents for bulk storage stability during extended transport.
Food applications dominate procurement volume; pharmaceuticals generate the highest margin premiums per kilogram.
End User:
Customer type fragmentation creates distinct service requirements, from technical formulation support for bakers to logistics-centric procurement for agrochemical distributors.
- Bakers:Industrial baking operations across Victoria specify anti-caking agents for flour blends and leavening systems where humidity-induced clumping disrupts automated dosing equipment.
- Food Manufacturers:Processed seasoning blend and soup powder producers in Sydney and Melbourne lock multi-year supply agreements with documented humidity-stability performance guarantees.
- Chemical Companies:Industrial chemical processors handling bulk powders prioritize granule formats to reduce dust exposure during handling.
- Agrochemical Providers:Fertilizer and feed additive distributors specify anti-caking agents for bulk storage stability during extended transport.
Food manufacturers concentrate contract volume; chemical companies are migrating fastest toward granule format adoption.
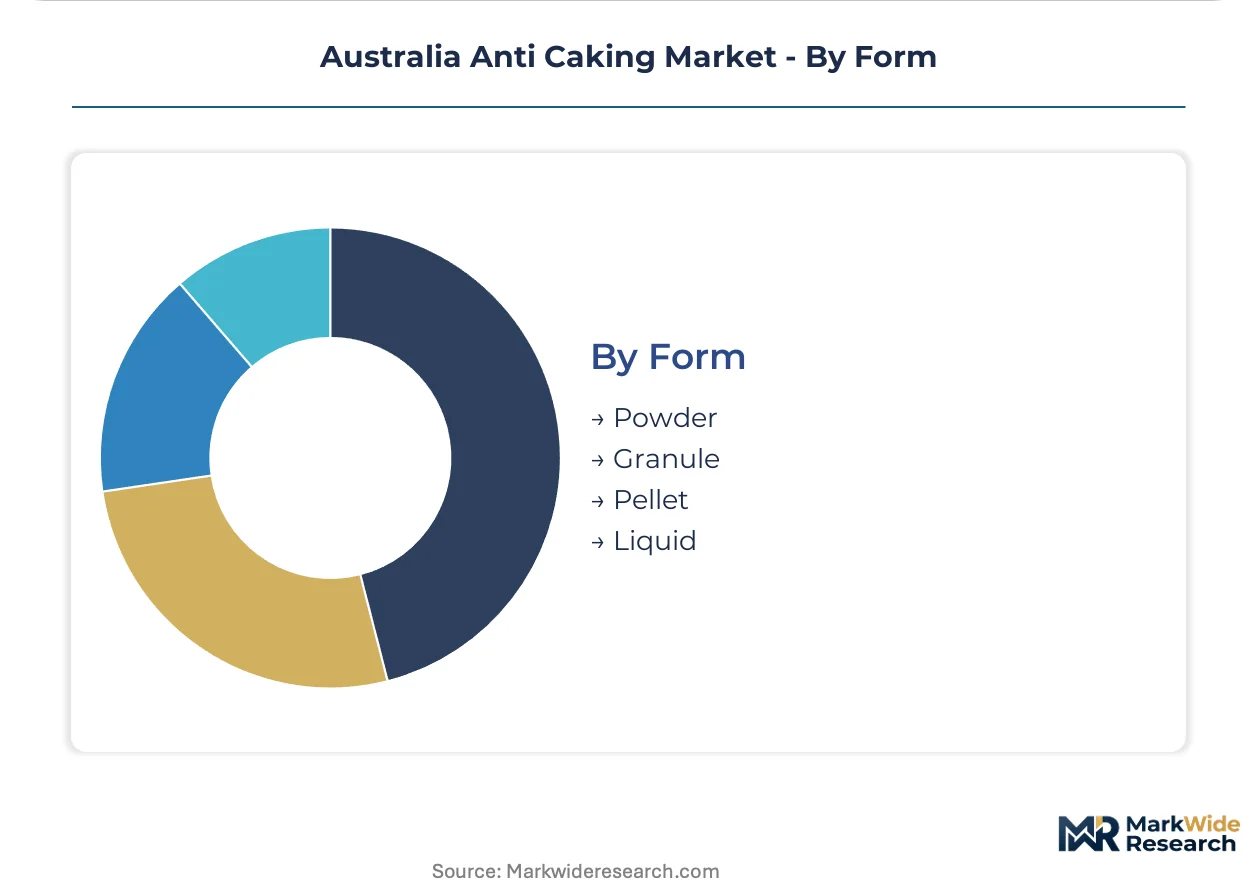
Form:
Supply concentration in powder processing infrastructure resists format shifts, though granule and liquid alternatives gain traction where handling efficiency outweighs formulation flexibility.
- Powder:Standard 2-10 micron particulate form maintains structural dominance across Australian procurement. Sydney and Melbourne food processors specify powder for maximum surface area and rapid moisture absorption in seasoning applications.
- Granule:Agglomerated particles reduce dust generation during pneumatic conveying and manual handling. Chemical companies in industrial zones outside Brisbane are qualifying granule formats for agricultural input applications.
- Pellet:Compressed cylindrical forms serve specialized pharmaceutical tablet pressing where precise dosing accuracy matters.
- Liquid:Dispersed colloidal suspensions address niche coating applications where dry blending is impractical.
Powder retains volume leadership; granule formats are climbing the fastest as chemical companies prioritize handling safety.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Australian states diverge sharply based on humidity exposure severity and industrial base composition. Victoria and New South Wales concentrate precision food manufacturing demand, while Queensland and Western Australia present underdeveloped procurement infrastructure with divergent climate-driven specification requirements.
New South Wales
Sydney-based industrial bakers and soup manufacturers drive specification intensity for moisture-resistant anti-caking formulations. FSANZ Schedule 15-16 compliance investments concentrate procurement decisions among qualified domestic distributors with documented technical support capabilities. The Sydney metropolitan corridor anchors multi-year supply agreements with humidity-stability performance guarantees locked through 2028.
Victoria
Melbourne food processors lead adoption of surface-modified precipitated silica for seasoning applications requiring sub-5% moisture pickup. TGA pharmaceutical excipient specifications create parallel demand channels for dual-certified manufacturers serving tablet and capsule applications. The Port of Melbourne logistics cluster supports import-dependent supply chains for premium calcium silicate grades.
Queensland
Brisbane and surrounding industrial zones present first-mover positioning opportunities for regional anti-caking formulation hubs. Tropical storage conditions elevate specification requirements for humidity-resistant architectures beyond commodity-grade standardization. Chemical companies handling agricultural inputs are qualifying granule formats to reduce dust exposure during pneumatic conveying.
Western Australia
Mining and resource sector procurement prioritizes industrial powder processing applications over food-grade purity metrics. Geographic isolation from eastern manufacturing centers extends lead times for FSANZ-compliant formulations. Perth-based chemical distributors serve fertilizer and feed additive segments with logistics-centric procurement rather than technical formulation support.
South Australia
Adelaide's food manufacturing base operates at smaller scale than eastern state counterparts, limiting contract volume concentration. Clean-label positioning among regional natural product manufacturers drives magnesium carbonate substitution trials against established sodium silicoaluminate formulations. Local bakers face humidity-induced clumping challenges in automated dosing equipment during seasonal moisture spikes.
Australia Anti Caking Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding premium positioning through dual food-pharmaceutical certification capabilities. Mid-scale domestic distributors compete on technical service intensity rather than price alone. The competitive landscape features three archetypes: multinational chemical conglomerates with precipitated silica technology portfolios, agricultural input distributors extending into food-grade procurement, and specialized excipient manufacturers holding TGA compliance. Dominant competitive moves include strategic partnerships with industrial bakers for co-development of humidity-resistant formulations and geographic expansion into underdeveloped Queensland manufacturing corridors.
Within the multinational chemical tier, Evonik Industries AG and BASF SE exemplify integrated leaders leveraging European-based manufacturing networks to serve Australian FSANZ-compliant demand. Among agricultural input distributors, Cargill Incorporated occupies a position bridging fertilizer and feed additive procurement into food-grade anti-caking channels. These three companies represent the primary competitive anchors shaping supplier qualification criteria and purity benchmark elevation across the value chain.
| Leading Market Players |
|---|
| Evonik Industries AG |
| The Agropur Dairy Cooperative |
| Merck KGaA |
| Brenntag GmbH |
| BASF SE |
| Cargill Incorporated |
| PPG Industries |
| Huber Engineered Materials |
| Solvay |
| Others |
Value Chain & Pricing Dynamics
FSANZ Schedule 15-16 compliance gates both supplier qualification timelines and price differentiation tiers simultaneously, compressing domestic manufacturers into accelerated reformulation cycles while elevating premium positioning for dual-certified distributors with documented technical support capabilities.
Pricing Analysis
Long-term offtake contracts dominate procurement between Sydney and Melbourne food manufacturers and qualified domestic distributors, locking humidity-stability performance guarantees through multi-year supply agreements. Price differentiation hinges on certification grade — FSANZ-compliant versus dual FSANZ-TGA certified — and volume scale, with industrial bakers commanding standard-tier rates while pharmaceutical excipient buyers absorb premium markups. Cost compression in sodium silicoaluminate formulations is intensifying because clean-label substitution trials force competitive repositioning. Agrochemical distributors prove most price-sensitive, prioritizing logistics efficiency over purity metrics, whereas pharmaceutical tablet manufacturers exhibit lowest sensitivity due to TGA documentation requirements.
Supply Chain Analysis
Import dependency for food-grade calcium silicate meeting tightened FSANZ purity thresholds creates a chokepoint anchoring premium supply security to European and North American manufacturing networks. Domestic formulation draws from precipitated silica feedstocks, carbonate mineral inputs, and surface-modification chemical additives. Single-source vulnerability concentrates among specialized chemists with silicate surface-modification expertise in Sydney and Melbourne. Distribution runs through agricultural input networks extending into food-grade channels, with Cargill Incorporated bridging fertilizer procurement into anti-caking supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnesium carbonate clean-label positioning threatens sodium silicoaluminate incumbents with accelerated substitution timelines, forcing defensive capability investments to maintain specification-grade relationships with humidity-sensitive food processors.
For Market Incumbents: Shield installed base relationships by deepening technical service intensity for Melbourne and Sydney industrial bakers facing automated dosing equipment challenges. Accelerate dual FSANZ-TGA certification investments to capture pharmaceutical excipient crossover premiums before specialized competitors consolidate tablet and capsule supply channels. Vertical integration into precipitated silica surface-modification technology reduces import dependency exposure for premium calcium silicate grades. For New Entrants and Emerging Players: Technical formulation support gaps in Queensland's underdeveloped Brisbane corridor offer first-mover positioning for regional anti-caking hubs serving tropical storage specification requirements. Target granule format adoption among chemical companies handling agricultural inputs outside established powder processing infrastructure. Partner with Port of Melbourne logistics clusters to anchor import-dependent supply security for premium European calcium silicate grades. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational chemical conglomerates seeking to divest non-core food additive portfolios lacking dual certification capabilities. Long-term viability centers on manufacturers with unified quality systems spanning FSANZ food channels and TGA pharmaceutical specifications. Monitor FSANZ Schedule 16 silicate threshold review timelines as inflection indicators forcing reformulation capex cycles and supplier qualification reshuffling.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | Unified FSANZ-TGA quality systems capture pharmaceutical excipient premiums from tablet manufacturers. |
| Surface-Modification Technology Acquisition | Precipitated silica expertise reduces European import dependency for humidity-resistant formulations. |
| Queensland Regional Hub Development | Brisbane corridor positioning addresses tropical storage specification gaps in underdeveloped markets. |
| Granule Format Production Scale-Up | Dust-reduction architectures align with chemical company handling safety priorities in agricultural inputs. |
| Long-Term Performance Guarantee Contracts | Humidity-stability documentation locks multi-year supply relationships with Sydney and Melbourne bakers. |
Study Parameters
A spread of perspectives from formulation chemists, procurement leads at industrial bakeries, distribution channel partners, and regulatory affairs specialists converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against FSANZ code documentation, TGA excipient specifications, customs and trade flow records, and chemical inventory filings. Bottom-up segment sizing triangulated with top-down market envelope checks to constrain projection variance.
Segmentation dimensions modeled span product type, application, end user, and form, with additional granularity on regional humidity exposure severity and certification tier. Volume and value outputs across the projection horizon reflect derived CAGRs anchored to documented procurement expansion at Victorian and New South Wales food manufacturers. Forecast inputs incorporated FSANZ regulatory review timelines, precipitated silica technology adoption curves, and granule format migration patterns among chemical companies.
Material uncertainties — pending FSANZ maximum permitted level revisions, specialized chemist availability constraints, and clean-label substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement timelines and technology diffusion rates among domestic manufacturers. Practitioners should keep alternative scenarios live as Schedule 16 silicate threshold determinations and Queensland infrastructure development timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Protective Cultures Market
Food Additives and Ingredients
Gelatin Films Market
Food Additives and Ingredients
Food Grade Magnesium Derivatives Market
Food Additives and Ingredients
Egypt Feed Additives Market
Food Additives and Ingredients
Clean Label Food Ingredient Market
Food Additives and Ingredients
Global Food Anti Caking Agents Market
Food Additives and Ingredients
UK Food Enzymes Market
Food Additives and Ingredients
Global Lactase Market
Food Additives and Ingredients
Fat-Replacing Starch Market
Food Additives and Ingredients
Spain Food Additives Market
Food Additives and Ingredients
Potassium Polymetaphosphate Food Additives Market
Food Additives and Ingredients
Carrageenan Market
Food Additives and Ingredients
Oxidized Starch Market
Food Additives and Ingredients
Australia Food Emulsifiers Market
Food Additives and Ingredients
Anti-Caking Agents Market
Food Additives and Ingredients
Global Food Release Agents Market