
 Rail Fasteners Market | 2026-2036
Rail Fasteners Market Size, Share, and Industry Trends Forecast 2026-2036
Rail Fasteners Market Intelligence
The capital-intensity divergence between integrated fastener-forging operations and component-assemblers is collapsing as Chinese producers achieve captive steelmaking. Vossloh AG leverages its German forging heritage to dominate premium European high-speed contracts. CRRC Corporation Limited anchors procurement across China's state railway procurement system through backward integration into specialty alloy production. Pandrol Limited differentiates via clip-system intellectual property that commands specification in British and Australian tenders.
Rail fasteners comprise threaded, clipped, and plate-based mechanical devices manufactured from high-carbon or alloy steel through hot-forging and heat-treatment processes, designed to maintain rail-to-sleeper geometry under dynamic axle loads exceeding 30 tonnes. Elastic clips generate controlled toe-load to resist rail longitudinal movement, while Pandrol clips employ a e-clip geometry optimized for automated installation. High-speed rail applications command premium alloy-steel specifications, whereas freight railways sustain volume demand for screw spikes and base plates in emerging economies. Composite material formulations remain niche but occupy maintenance-reduction value pools in corrosive environments.
The Federal Railroad Administration enforces Track Safety Standards that mandate fastener fatigue-life testing, while China's NMPA-aligned railway standards body governs alloy composition through GB/T specifications. The EU's F-Gas Regulation indirectly shapes fastener demand by accelerating rail electrification projects requiring new track hardware. Stakeholders must monitor divergence between Chinese state-procurement price ceilings and Western specification premiums when allocating manufacturing capacity.
Market Dynamics
China's state-funded corridor expansion programs are compressing procurement timelines while forcing Western suppliers to absorb alloy-steel cost premiums to retain specification compliance in European high-speed tenders.
Growth Catalysts
- EN 13481 Certification Mandate:Europe's fatigue-life testing requirements are accelerating material upgrades from cast iron to alloy steel formulations across continental networks.
- High-Speed Rail Electrification:The EU's F-Gas Regulation is driving new track hardware demand through accelerated rail electrification projects requiring elastic clip systems.
- Axle Load Thresholds:Freight corridors exceeding 30-tonne dynamic loads are expanding specification requirements for heat-treated high-carbon fasteners in heavy-haul applications.
Market Restraints
- Alloy Steel Price Volatility:Nickel and chromium input cost swings are compressing margin structures for non-integrated forging operations dependent on spot market sourcing.
- Procurement Concentration Risk:China's state railway procurement system anchors volume demand, creating dependency exposure for suppliers without backward integration into specialty alloy production.
- Composite Substitution Ceiling:Fiber-reinforced polymer formulations face technical limitations in toe-load retention above 15 kN, capping penetration in mainline applications.
Strategic Opportunities
- Corrosive Environment Maintenance Pools:Coastal and chemical-belt installations in Australia and Saudi Arabia are creating specification openings for stainless-clad clip systems with extended service intervals.
- Automated Installation Convergence:Robotics and e-clip geometry standardization are converging to enable track-laying speed improvements in greenfield corridor construction.
- Indian PLI Scheme Tailwinds:India's production-linked incentive scheme for specialty steel is attracting forging capacity investments targeting domestic freight network modernization.
Industry Challenges
- Heat-Treatment Skill Scarcity:Precision quenching and tempering expertise for alloy-steel fatigue resistance is concentrating among German and Japanese engineering workforces.
- Dual Certification Timelines:Parallel GB/T and EN 13481 approval processes are extending product qualification cycles to 18-24 months for cross-border suppliers.
- Legacy Track Interface Complexity:Retrofit installations on timber-sleeper infrastructure require custom base-plate geometries that fragment production runs and elevate tooling costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rail Fasteners Market |
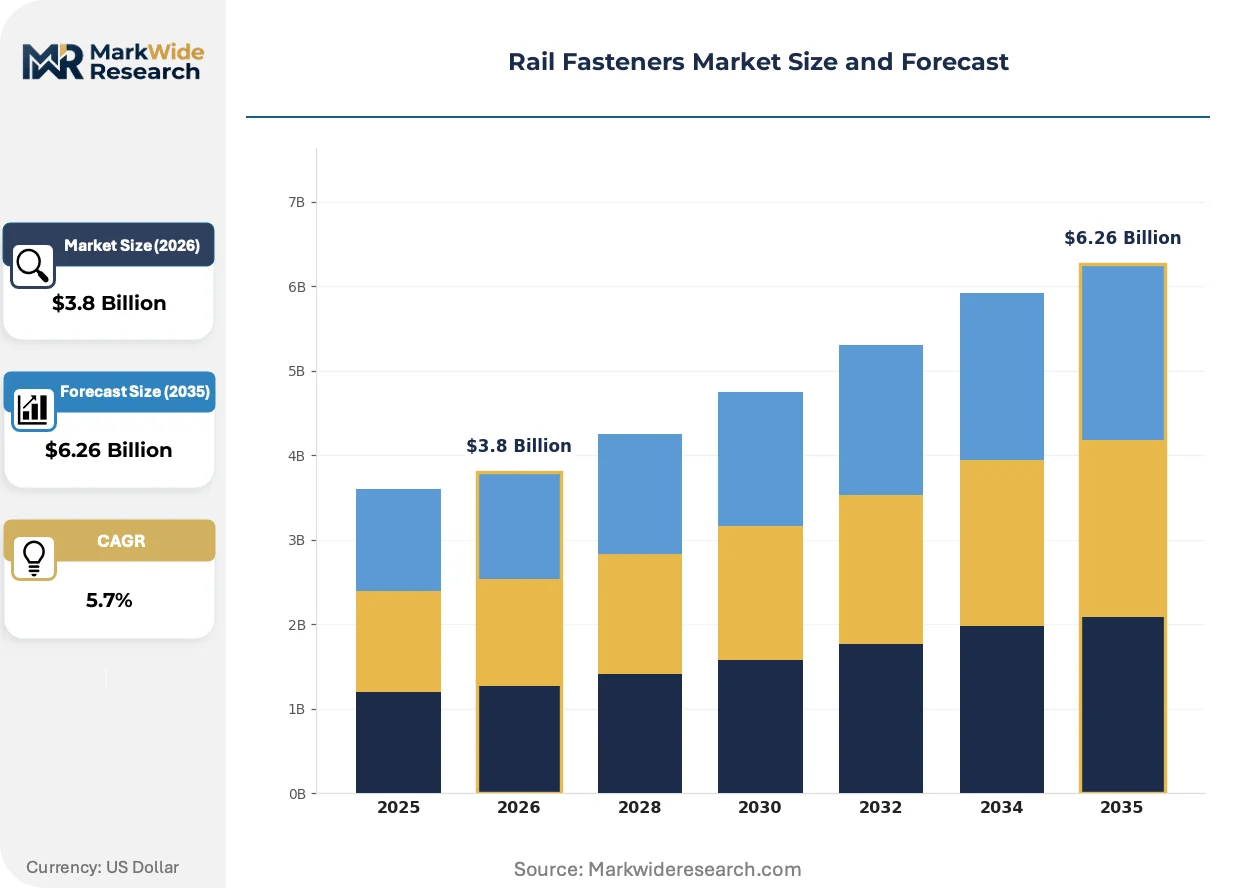
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Elastic Clips, Pandrol Clips, Screw Spikes, Rail Anchors, Base Plates Material: High Carbon Steel, Stainless Steel, Alloy Steel, Cast Iron, Composite Materials Application: High-Speed Rail, Metro Systems, Freight Railways, Light Rail Transit, Heritage Railways End User: Rail Infrastructure Companies, Maintenance Contractors, Government Rail Authorities, Private Railway Operators |
| Companies Covered | Cooper & Turner Limited, Sateba International SAS, Vossloh AG, CRRC Corporation Limited, Progress Rail Services Corporation, Pandrol Limited, Taicang Zhongbo Railway Fastening, AGICO, L.B. Foster Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rail Fasteners Market Strategic Shifts & Innovations
Material science advances and installation automation are bifurcating competitive positions between premium alloy-steel specialists and volume screw-spike producers serving diverging end-use requirements.
Elastic clip metallurgy is bifurcating around fatigue-performance thresholds. High-carbon spring steel formulations dominate freight applications where cyclic loading stays below 10 million cycles. Premium alloy grades with vanadium micro-alloying are capturing high-speed specifications requiring 30 million cycle lifespans under EN 13481 testing protocols. This metallurgical split is compressing mid-grade product viability in tender specifications.
Europe's F-Gas Regulation is accelerating rail electrification infrastructure deployment. The policy mandate is expanding conductor-rail and overhead-catenary hardware demand that shares fastener procurement channels with mainline track systems. Railway operators in Germany and France are bundling electrification and track-renewal contracts, forcing fastener suppliers to certify across both hardware categories.
Buyer concentration among state railway procurement bodies is consolidating vendor qualification lists. China's NMPA-aligned standards body and India's Ministry of Railways are narrowing approved-supplier registries to firms with captive metallurgical testing facilities. Western suppliers are responding by establishing joint-venture forging partnerships within target markets rather than exporting finished components.
Rail Fasteners Market Segmentation
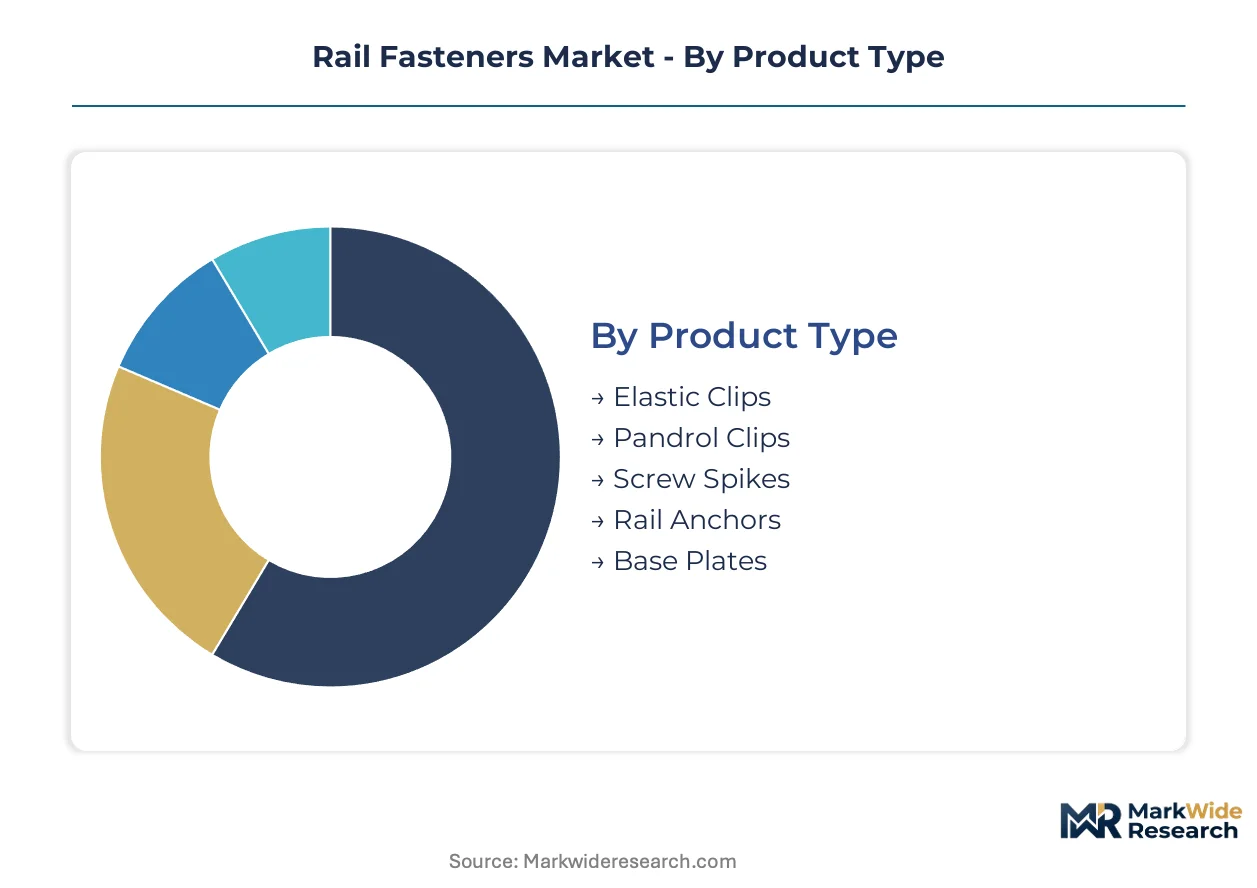
Segmentation in rail fasteners reflects divergent certification regimes and metallurgical requirements across operational environments. Procurement specifications from EN 13481, GB/T standards, and FRA Track Safety Standards create non-interchangeable product categories that lock vendors into distinct qualification pathways.
Product Type:
EN 13481 fatigue-life testing mandates separate elastic clip systems into certified and non-certified tiers, with automated installation compatibility becoming a secondary sorting mechanism in high-speed tenders.
- Elastic Clips:Spring-steel components generating controlled toe-load through optimized beam geometry. Demand concentrates in China's state-funded corridor programs where 30 million cycle specifications command premium alloy formulations from captive steelmaking operations.
- Pandrol Clips:Proprietary e-clip geometry enabling automated track-laying at speed. British and Australian tenders specify this intellectual property for coastal installations requiring extended maintenance intervals against corrosion.
- Screw Spikes:Threaded timber-sleeper fasteners dominant in freight corridors with sub-10 million cycle loading profiles.
- Rail Anchors:Longitudinal movement restraints for jointed track on legacy infrastructure.
- Base Plates:Load-distribution interfaces between rail foot and sleeper, critical in 30-tonne axle load applications.
Established volume favors screw spikes in freight corridors; emerging adoption favors Pandrol clip systems in electrified high-speed networks.
Material:
Cost tier stratification follows nickel and chromium input exposure, with integrated forging operations capturing margin from spot-market-dependent competitors.
- Alloy Steel:Vanadium micro-alloyed grades meeting EN 13481 30 million cycle thresholds. European high-speed rail electrification under the F-Gas Regulation accelerates specification upgrades from German and French bundled procurement.
- High Carbon Steel:Spring-grade formulations for freight applications below 10 million cycles. India's PLI scheme for specialty steel attracts forging investments targeting domestic network modernization with cost-competitive heat treatment.
- Stainless Steel:Coastal and chemical-belt specifications in Saudi Arabia and Australia demanding extended service intervals.
- Cast Iron:Legacy material facing displacement by EN 13481 certification mandates across continental European networks.
- Composite Materials:Fiber-reinforced polymers capped at 15 kN toe-load retention, limiting penetration to maintenance-reduction niches.
Volume concentration sits with high carbon steel in heavy-haul freight; specification premiums flow to alloy steel in electrified passenger corridors.
Application:
Customer type differentiation separates state-procurement price ceilings from Western specification premiums, with tender bundling reshaping vendor qualification requirements.
- High-Speed Rail:Electrified passenger corridors requiring elastic clip systems with overhead-catenary hardware certification. Germany and France bundle track-renewal with conductor-rail contracts, forcing dual-category supplier approval.
- Freight Railways:Heavy-haul corridors exceeding 30-tonne dynamic axle loads. China's NMPA-aligned procurement anchors volume demand for heat-treated high-carbon fasteners through backward-integrated domestic suppliers.
- Metro Systems:Urban passenger networks with standardized gauge and moderate cyclic loading profiles.
- Light Rail Transit:Mixed-traffic street-running installations with noise-dampening fastener requirements.
- Heritage Railways:Preservation-sector demand for timber-sleeper compatible base plates with custom geometries.
Procurement scale favors freight railways through state concentration; margin expansion favors high-speed rail through bundled electrification certification.
End User:
Supply concentration tracks captive metallurgical testing capabilities, with approved-supplier registries narrowing to firms with in-house forging and quality verification.
- Government Rail Authorities:China's state railway procurement system and India's Ministry of Railways operate narrowing vendor qualification lists requiring domestic joint-venture partnerships from Western suppliers.
- Rail Infrastructure Companies:Greenfield corridor developers in Asia-Pacific specifying automated installation compatibility for elastic clip systems.
- Maintenance Contractors:Retrofit-focused demand for legacy timber-sleeper interface solutions with fragmented production runs.
- Private Railway Operators:Mining and industrial freight lines in Australia and Brazil with corrosive-environment stainless-clad specifications.
Contract flow concentrates with government rail authorities; technical differentiation opens with private operators in specialized environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across procurement regimes. China's state railway system enforces rigid cost ceilings that compress margins for imported alloy formulations. European high-speed tenders tolerate 40-60% specification premiums for EN 13481-certified fatigue performance.
China
State-funded corridor expansion programs drive procurement volume through backward-integrated domestic suppliers. NMPA-aligned GB/T specifications govern alloy composition for captive steelmaking operations. CRRC Corporation anchors supply chains across the Yangtze River Delta cluster.
Germany
F-Gas Regulation accelerates bundled electrification and track-renewal contracts requiring dual-category hardware certification. KBA oversight ensures EN 13481 compliance for high-speed elastic clip systems. Vossloh AG leverages Ruhr Valley forging heritage for premium European tenders.
India
Ministry of Railways narrowing approved-supplier registries attracts PLI scheme investments in specialty steel forging. BIS standards align with heat-treatment capacity expansion. Maharashtra and Gujarat industrial corridors concentrate new domestic production capacity.
United States
FRA Track Safety Standards mandate fatigue-life testing for heavy-haul freight corridors exceeding 30-tonne axle loads. Progress Rail Services dominates procurement across Class I railroad maintenance programs. Midwest forging clusters supply screw spike and base plate volume.
Saudi Arabia
Coastal installations and chemical-belt corridors create specification openings for stainless-clad clip systems with extended service intervals. SFDA-aligned procurement frameworks govern infrastructure material standards. Riyadh and Eastern Province developments concentrate greenfield rail projects.
Rail Fasteners Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in rail fastener supply. German and Chinese producers with captive metallurgical operations capture margin from spot-market-dependent competitors. Three archetypes dominate: state-linked champions with backward integration into specialty alloys, European heritage forgers with EN 13481 certification dominance, and regional assemblers serving price-sensitive freight corridors. Competitive moves concentrate on joint-venture forging partnerships in target markets and dual-certification capacity for cross-border tender participation.
Within the integrated champion tier, Vossloh AG and CRRC Corporation occupy positions at opposite ends of the pricing spectrum. Vossloh exemplifies European premium-forging heritage with Ruhr Valley metallurgical expertise. CRRC represents state-linked supply chain control through NMPA-aligned procurement anchoring. Pandrol Limited sits within the intellectual property specialist archetype, its proprietary clip geometry commanding specification in British and Australian coastal tenders. Among North American fabricators, Progress Rail Services anchors freight corridor supply through FRA-compliant maintenance contractor relationships.
| Leading Market Players |
|---|
| Cooper & Turner Limited |
| Sateba International SAS |
| Vossloh AG |
| CRRC Corporation Limited |
| Progress Rail Services Corporation |
| Pandrol Limited |
| Taicang Zhongbo Railway Fastening |
| AGICO |
| L.B. Foster Company |
| Others |
Cost & Logistics Intelligence
Long-term bundled procurement contracts with EN 13481 certification requirements lock in both alloy-steel supply access and price visibility for European high-speed rail tenders, while China's state-procurement price ceilings compress margin predictability for spot-market-dependent competitors.
Pricing Analysis
After-sales service contracts for fatigue-life monitoring and clip replacement scheduling drive lifetime value beyond initial hardware sales. Pricing stratifies across EN 13481-certified premium tiers, uncertified mid-grade formulations, and high-carbon economy grades for freight corridors. Cost compression in the mid-grade tier intensifies because Chinese backward-integrated producers absorb alloy premiums that Western spot-market buyers cannot match. Government rail authorities in China exhibit highest price sensitivity; private mining operators in Australia and Brazil tolerate specification premiums for stainless-clad corrosion resistance.
Supply Chain Analysis
China and Germany anchor specialty alloy forging for elastic clip systems, with India's Maharashtra and Gujarat clusters emerging under PLI scheme incentives. Nickel and chromium feedstock sourcing draws from Indonesian nickel processing and South African chromium mining. Single-source vulnerability concentrates in German heat-treatment engineering expertise for 30 million cycle fatigue resistance. Distribution runs through state railway procurement bodies with narrowing approved-supplier registries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Maintenance service bundling and extended certification support contracts expand faster than hardware unit sales, creating attach-rate opportunities for vendors with metallurgical testing capabilities.
For Market Incumbents: Shield specification compliance by deepening captive alloy production and securing dual GB/T-EN 13481 certification capacity before procurement timelines compress further. Composite substitution threats in sub-15 kN applications demand accelerated stainless-clad product development for coastal maintenance pools. Joint-venture forging partnerships in India and Saudi Arabia preserve registry access as state procurement localizes. For New Entrants and Emerging Players: Differentiate on automated installation compatibility and e-clip geometry licensing for greenfield Asia-Pacific corridor developers. Heritage railway retrofit demand for timber-sleeper base plates offers penetrable white space with fragmented tooling requirements and limited incumbent focus. Pursue direct technical certification relationships with Australia's TGA-aligned infrastructure standards body to bypass established vendor lists. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier forging specialists with heat-treatment skill scarcity and pending dual-certification completion across the analysis window. Long-term viability favors producers with captive metallurgical testing rather than component assemblers exposed to Chinese state-procurement price ceilings. Watch for inflection when India's Ministry of Railways publishes revised approved-supplier registry criteria.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloy Production | Captive nickel and chromium processing insulates margin from spot volatility under China's NMPA procurement. |
| Dual Certification Capacity Investment | Parallel GB/T and EN 13481 approval reduces 18-24 month qualification cycles for cross-border tender participation. |
| Joint-Venture Forging Partnerships | Local production in Maharashtra and Gujarat secures India's narrowing approved-supplier registry access. |
| Stainless-Clad Clip System Development | Extended service intervals meet Saudi SFDA and Australian coastal specifications for corrosive environments. |
| Automated Installation Technology Licensing | E-clip geometry standardization enables track-laying speed improvements in Asia-Pacific greenfield corridors. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across primary interviews with railway procurement officers, forging plant managers, metallurgical testing laboratory directors, and maintenance contractor field engineers. Secondary validation drew from FRA Track Safety Standards filings, EN 13481 certification registries, China's NMPA-aligned GB/T specifications, and customs trade data for alloy-steel inputs. Bottom-up volume estimates from individual corridor procurement programs were triangulated against top-down spending projections from state railway budget disclosures.
Across the analysis window, the forecasting framework modeled product type segmentation by certification tier, material grade by fatigue-performance threshold, application by axle-load profile, and end user by procurement concentration. CAGRs were derived from weighted average growth across these dimensions, incorporating electrification project pipelines under the EU's F-Gas Regulation and India's PLI scheme capacity buildout schedules as industry-specific inputs.
Material uncertainties — alloy price volatility, dual-certification timeline extensions, and state-procurement localization shifts — sit outside the modeled envelope. Forecasts reflect assumptions about continued EN 13481 enforcement and NMPA procurement stability. Recalibration cycles align with material shifts in electrification policy mandates and approved-supplier registry revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Railway After-Cooler Market
Railway Transportation
Railway Track Fittings Market
Railway Transportation
United States Rail Freight Transport Market
Railway Transportation
Railway Li-Ion Battery Market
Railway Transportation
Global Rail Freight Transport Market
Railway Transportation
Global Train Signalling System Market
Railway Transportation
Canada Rail Freight Transport Market
Railway Transportation
Germany Rail Freight Transport Market
Railway Transportation
Railway Station Lighting Market
Railway Transportation
Railway Hydraulic Damper Market
Railway Transportation
Point Machine Market
Railway Transportation
Railway Sleepers Market
Railway Transportation
Railcar Movers Market
Railway Transportation
Rail Switch Point Heating System Market
Railway Transportation
Australia Rail Freight Transport Market
Railway Transportation
Global Railcar Leasing Market