
 Global Railcar Leasing Market | 2026-2036
Global Railcar Leasing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Railcar Leasing Market Intelligence
The use of high-strength, low-alloy (HSLA) steel in railcar construction is expanding the payload capacity and operational lifespan of modern fleets. Trinity Industries Inc. specializes in manufacturing these advanced railcars, integrating them into its extensive leasing portfolio. GATX Corp. leverages its large, diversified fleet to serve industries that benefit from higher capacity cars, such as agriculture and mining. The Greenbrier Companies Inc. competes through its combined manufacturing and leasing model, offering customized car designs to shippers.
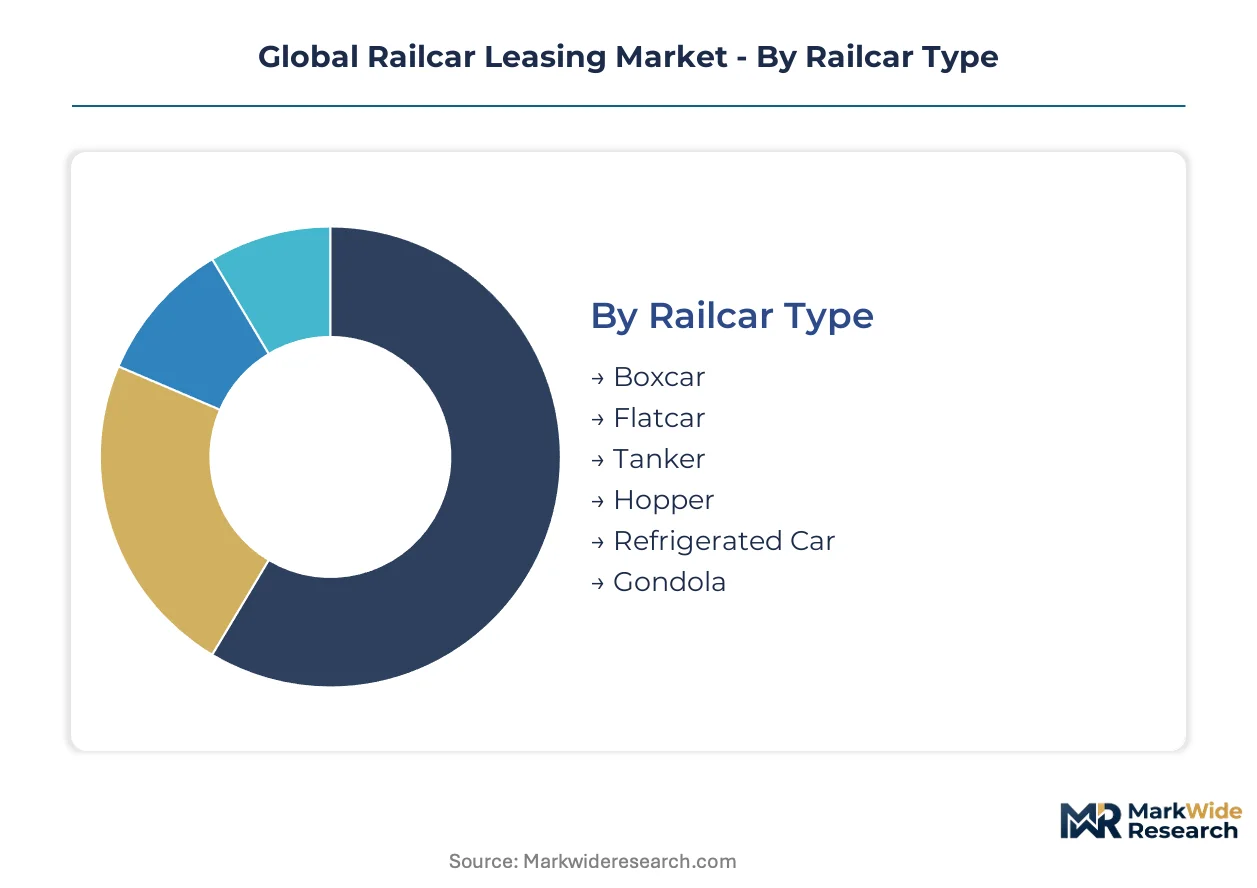
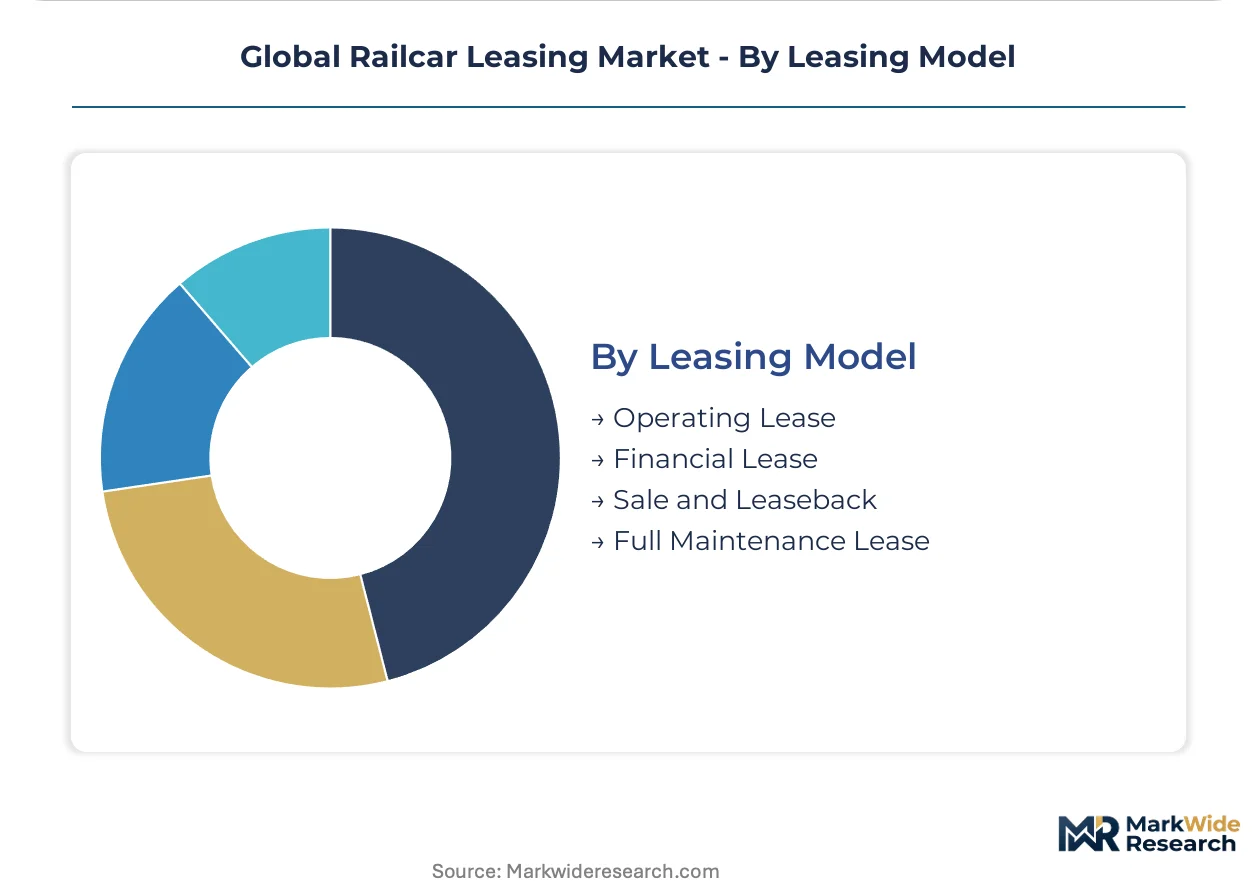
Railcar leasing involves the contractual agreement for the use of freight rolling stock by shippers or carriers without capital purchase. These agreements specify terms for various car types, such as tankers designed to transport liquids under specific pressure and temperature ratings, or hoppers built for gravity-based unloading of bulk commodities. Tanker and hopper cars constitute the largest segments by value, driven by chemical and agricultural transport needs. Analysis of leasing models shows that full maintenance leases and long-term contracts are prevalent for specialized assets, while operating leases offer flexibility for cyclical demand in sectors like construction.
Fleet safety and interoperability standards are enforced by entities like the Federal Railroad Administration (FRA) in the United States and the European Union Agency for Railways (ERA). These regulations, including the Association of American Railroads' interchange rules, dictate railcar design, maintenance schedules, and component specifications, directly influencing lessor costs and asset management strategies. Decisions on fleet renewal versus retrofitting older cars to meet new standards represent a central strategic challenge for lessors.
Market Dynamics
The central tension in the railcar leasing market is the long lifecycle of physical assets against the accelerating pace of regulatory mandates for safety and efficiency, such as Positive Train Control (PTC) systems, which forces continuous fleet evaluation.
Growth Catalysts
- Advanced Materials:Use of high-strength, low-alloy steel increases payload capacity and asset lifespan, boosting demand from agriculture and mining shippers.
- Specialized Fleet Demand:Rising chemical production elevates leasing for specialized tanker cars built for specific temperature and pressure transport needs.
- Regulatory Modernization:The Federal Railroad Administration's (FRA) Positive Train Control (PTC) mandate in the United States necessitates fleet renewal with compatible rolling stock.
Market Restraints
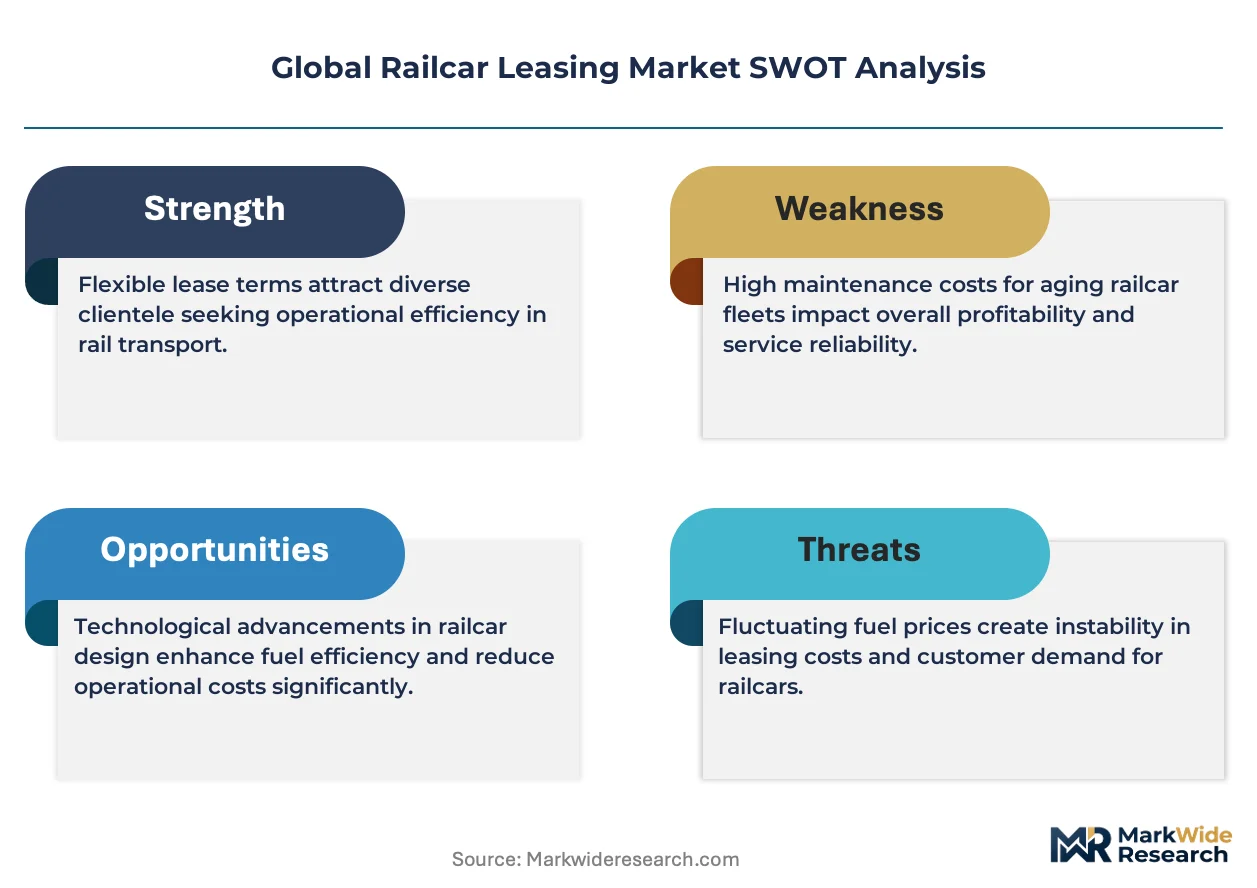
- High Capital Costs:Manufacturing specialized railcars requires substantial upfront investment, creating a high barrier to entry for new market participants.
- Regulatory Fragmentation:Navigating differing standards from the US Federal Railroad Administration and the EU Agency for Railways increases compliance costs for global operators.
- Component Bottlenecks:Concentrated supply of critical components like advanced braking systems creates vulnerability to price volatility and lead-time extensions.
Strategic Opportunities
- Emerging Market Rail:Modernizing freight rail networks in countries like India presents leasing opportunities, especially for bulk commodity transport.
- Green Energy Logistics:An opportunity exists in leasing specialized cars for transporting materials for the energy transition, such as biofuels or hydrogen.
- Digital Fleet Management:Integrating IoT sensors for real-time tracking and predictive maintenance offers a new value-added service layer beyond the physical lease.
Industry Challenges
- Fleet Renewal Decisions:Lessors face the difficult strategic choice between costly retrofitting of older cars to meet new standards and the higher capital outlay for new builds.
- System Integration Hurdles:Achieving seamless data exchange between different proprietary telematics platforms and railroad operator systems remains an operational challenge for lessors offering digital services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Railcar Leasing Market |
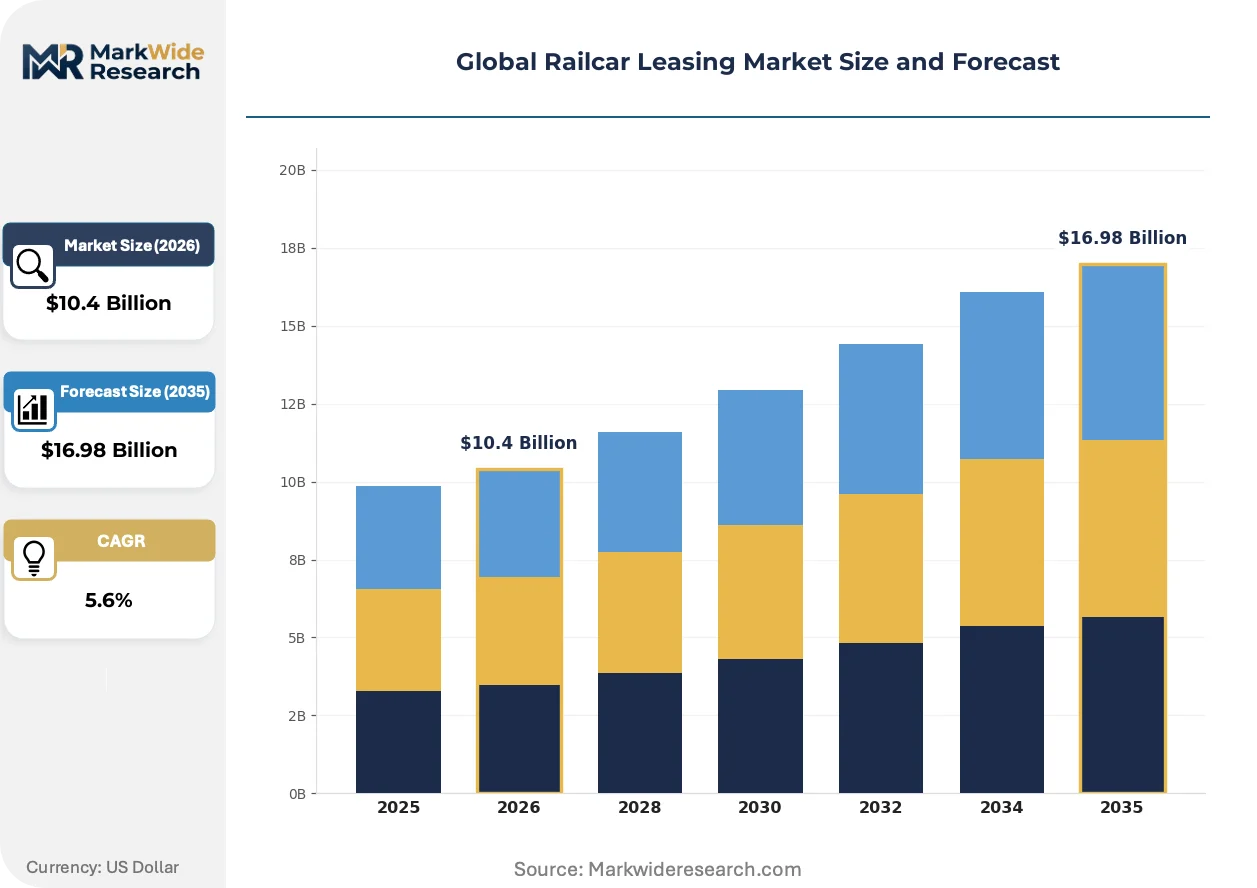
| Market Size in 2026 | $10.4 Billion |
| Market Size in 2035 | $16.98 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Railcar Type: Boxcar, Flatcar, Tanker, Hopper, Refrigerated Car, Gondola Lease Duration: Short-term, Medium-term, Long-term, Flexible Term End User Industry: Mining, Agriculture, Construction, Energy, Manufacturing, Chemical Production Leasing Model: Operating Lease, Financial Lease, Sale and Leaseback, Full Maintenance Lease |
| Companies Covered | Akiem Group SAS, The Greenbrier Companies Inc., Trinity Industries Inc., VTG GmbH, Touax SCA, GATX Corp., RAILPOOL GmbH, Procor Ltd., Berkshire Hathaway Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Railcar Leasing Market Strategic Shifts & Innovations
The nature of railcar leasing is shifting from passive asset provision to active, data-driven fleet optimization. This evolution is driven by technological advancements in materials and monitoring, alongside new regulatory pressures on safety and interoperability.
High-strength, low-alloy (HSLA) steel is a material used in railcar construction to increase payload capacity and extend operational lifespan. Shippers in bulk sectors like agriculture and mining increasingly specify these cars for new leases. Consequently, HSLA steel in new car builds is overtaking traditional carbon steel construction, establishing a new benchmark for asset productivity.
Stricter technical specifications for interoperability are enforced by the European Union Agency for Railways (ERA) to create a seamless pan-European freight network. These rules mandate common signaling and safety systems, impacting the design of new rolling stock. Lessors now prioritize investment in ERA-compliant assets, especially for intermodal and chemical fleets, to maximize operational flexibility.
Shippers are moving from simple dry leases toward full-service agreements that bundle maintenance, insurance, and compliance management. This model shifts the burden of operational uptime and regulatory adherence to the lessor, disrupting traditional asset-only contracts. This preference is most pronounced in North America's chemical sector, where safety documentation is critical.
Global Railcar Leasing Market Segmentation
The Global Railcar Leasing Market segmentation offers a granular view of asset deployment, contract structures, and industry-specific demand patterns. Understanding these distinctions helps lessors tailor their fleets and service offerings to meet diverse operational requirements across various economic sectors. Each segment reflects unique technical specifications, financial arrangements, or end-user needs that shape market dynamics.
Railcar Type:
Railcar specifications, often driven by cargo characteristics, critically influence leasing demand and asset design within the market.
- Tanker:These specialized cars transport liquids and gases under specific pressure and temperature ratings, including chemicals, petroleum products, and food-grade commodities. Demand concentrates in the chemical production and energy sectors, requiring rigorous safety compliance and technical precision.
- Hopper:Designed for gravity-based unloading of bulk dry commodities, hopper cars efficiently move grains, coal, and aggregates. Agricultural and mining industries drive significant demand for these high-capacity units, prioritizing rapid loading and unloading capabilities.
- Boxcar:Enclosed cars protect general merchandise and palletized goods from weather, offering versatility for various manufactured products.
- Flatcar:Open, flat platforms transport oversized or heavy items, including machinery, lumber, and intermodal containers.
- Refrigerated Car:Temperature-controlled units maintain specific conditions for perishable goods, serving the food and beverage industry.
- Gondola:Open-top cars transport bulk materials such as scrap metal, aggregates, and lumber, often used in construction and recycling.
Tanker cars lead on scale due to high value cargo; hopper cars lead on momentum with increasing agricultural and mining output.
Lease Duration:
The commitment period for railcar leases reflects operational flexibility and financial planning needs of shippers and carriers.
- Long-term:These contracts typically span several years, providing lessees with stable access to specialized rolling stock and predictable costs. Industries with consistent, high-volume transport needs, such as chemical production, favor long-term agreements to secure capacity.
- Short-term:Agreements lasting less than one year offer maximum flexibility for seasonal demand or temporary project-based transport requirements. Construction and agricultural sectors often utilize short-term leases to manage fluctuating commodity flows.
- Medium-term:Leases ranging from one to three years balance flexibility with some level of commitment, suitable for projects with defined timelines.
- Flexible Term:These leases offer adaptable durations, often with renewal options, catering to dynamic market conditions and evolving operational needs.
Short-term leases offer agility for fluctuating needs, while long-term agreements secure consistent capacity.
End User Industry:
Demand for railcar leasing is directly influenced by the specific transport requirements and economic cycles of various industrial sectors.
- Chemical Production:This industry requires highly specialized tanker cars for transporting diverse liquid and gaseous chemicals, often under strict safety and environmental regulations. Rising global chemical output directly elevates leasing demand for these critical assets.
- Agriculture:Transport of grains, fertilizers, and other agricultural commodities primarily drives demand for hopper cars, particularly along key North American freight corridors. Seasonal harvest cycles create significant leasing fluctuations for bulk transport.
- Mining:Bulk commodities like coal, iron ore, and aggregates are transported in hopper and gondola cars, supporting global industrial production.
- Energy:Crude oil, refined petroleum products, and biofuels require specialized tanker cars, with demand influenced by energy policy and production levels.
- Manufacturing:Finished goods, raw materials, and components move in boxcars and flatcars, supporting diverse industrial processes.
- Construction:Aggregates, cement, and heavy equipment are transported using gondolas and flatcars, tied to infrastructure development.
Chemical Production and Agriculture consistently drive demand for specialized assets, reflecting core economic transport needs.
Leasing Model:
The chosen leasing model dictates the allocation of financial risk, maintenance responsibilities, and service breadth between lessor and lessee.
- Full Maintenance Lease:This comprehensive model includes the railcar, all maintenance, repairs, and often regulatory compliance management, shifting operational burdens to the lessor. Shippers in North America's chemical sector increasingly prefer this model for critical safety documentation and uptime.
- Operating Lease:Offering financial flexibility, this model allows lessees to use assets without ownership, keeping the railcar off their balance sheet. Cyclical demand sectors like construction frequently utilize operating leases to manage fleet capacity efficiently.
- Financial Lease:Structured more like a loan, this model provides the lessee with effective ownership rights and responsibilities, often leading to asset purchase at the end of the term.
- Sale and Leaseback:Companies sell their existing railcar fleets to a lessor and then lease them back, freeing up capital while maintaining operational control.
Full Maintenance Leases reduce operational burdens for lessees, while Operating Leases provide financial flexibility for asset utilization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dominant industrial clusters in North America drive significant demand for railcar leasing, particularly for specialized assets supporting energy and agriculture. These regions benefit from established freight networks and a clear regulatory framework. European and Asian markets also exhibit strong growth, fueled by industrial output and infrastructure modernization.
United States
Agricultural output and chemical production necessitate high-capacity railcars across the United States. The Federal Railroad Administration (FRA) mandates Positive Train Control (PTC) systems, influencing fleet renewal decisions. Key North American freight corridors, connecting energy and agricultural production zones, show concentrated leasing activity.
Germany
European industrial production generates consistent demand for specialized railcar fleets, especially for chemical transport in Germany. The European Union Agency for Railways (ERA) sets stringent interoperability standards for cross-border freight operations. The Rhine-Ruhr industrial region utilizes extensive rail networks for distributing manufactured goods and bulk materials.
India
Modernizing freight rail networks and increasing bulk commodity transport underpin leasing opportunities in India. The PLI scheme supports domestic manufacturing, indirectly boosting demand for raw material transport. The Delhi-Mumbai Industrial Corridor represents a significant infrastructure project requiring substantial freight logistics.
China
Robust industrial output and agricultural commodity movements sustain a strong railcar leasing market in China. GB standards dictate technical specifications for new rolling stock and maintenance protocols. The Yangtze River Delta region, a major manufacturing hub, relies heavily on rail for inter-province goods movement.
Canada
Agricultural exports and natural resource extraction create substantial demand for hopper and specialized tank cars in Canada. Transport Canada regulations govern rail safety and equipment standards across the national network. Alberta's energy sector drives leasing for specialized cars transporting petroleum products and other resources.
Global Railcar Leasing Market Key Industry Players
Global majors compete with regional champions across fleet size, specialization, and service offerings. The market exhibits a tiered structure, with large lessors providing diversified fleets and smaller players focusing on niche segments. Companies pursue portfolio diversification and strategic partnerships to enhance market reach and operational efficiency.
On the diversified leasing vector, GATX Corp. operates a substantial fleet across various industries, exemplifying broad market coverage. Trinity Industries Inc. represents a vertically integrated model, manufacturing advanced railcars and integrating them into its leasing portfolio. The Greenbrier Companies Inc. sits within the combined manufacturing and leasing archetype, offering customized car designs to shippers.
| Leading Market Players |
|---|
| Akiem Group SAS |
| The Greenbrier Companies Inc. |
| Trinity Industries Inc. |
| VTG GmbH |
| Touax SCA |
| GATX Corp. |
| RAILPOOL GmbH |
| Procor Ltd. |
| Berkshire Hathaway Inc. |
| Others |
Cost & Logistics Intelligence
Vertical integration, exemplified by companies manufacturing railcars for their own leasing fleets, anchors both supply position and pricing power. This model allows lessors to control asset quality and leverage specialized designs in their long-term contracts.
Pricing Analysis
Input-cost pass-through for advanced materials like HSLA steel directly influences lease rates for specialized railcars. The dominant pricing structure involves contract-based long-term offtake, particularly for full maintenance leases. Price differentiation stems from car type specialization, such as tankers for chemical transport, and the level of customization offered by lessors. Regulatory compliance costs, including PTC system integration, create upward pricing pressure. Construction sectors exhibit the most price-sensitive demand, while chemical production prioritizes long-term stability over lowest cost.
Supply Chain Analysis
Regional distribution centers for railcar maintenance and component warehousing support fleet operations across North America and Europe. Geographic supply concentration for railcar manufacturing centers in countries like China and the United States. The industry draws from specialized raw materials, including high-strength, low-alloy (HSLA) steel, and critical components such as advanced braking systems. Component bottlenecks for these specialized parts present a structural supply chain risk. The dominant distribution model involves direct leasing agreements between lessors and end-user shippers or carriers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage exists in global railcar leasing, driven by the varying pace of regulatory modernization, where US PTC mandates necessitate different fleet investments compared to European ERA interoperability standards. This creates distinct regional market dynamics for asset deployment.
For Market Incumbents: Deepen vertical integration by expanding in-house manufacturing capabilities for advanced railcars. This secures supply for specialized assets and mitigates component bottlenecks, a named threat to operational continuity. Diversifying fleet portfolios with both PTC-compliant and ERA-interoperable rolling stock ensures broad market access. Investing in digital fleet management platforms provides a lever for differentiating service offerings and optimizing asset utilization. For New Entrants and Emerging Players: Launch via a full-service leasing model, bundling maintenance and compliance, to penetrate niche segments. The most penetrable segments include specialized green energy logistics, such as hydrogen transport, and modernizing freight networks in emerging markets like India. Focus on providing data-driven fleet optimization as a key go-to-market angle. Offer customized car designs for specific industrial requirements to differentiate from larger, more generalized fleets. For Investors and Strategic Acquirers: Roll-up economics work for mid-sized lessors because the market remains fragmented with high capital barriers to entry for new fleet development. Long-term viability rests on securing specialized asset portfolios that meet evolving regulatory and industrial demands over the next decade. Target acquisition archetypes include regional lessors with strong customer relationships in specific industrial verticals, like chemical production. Consolidation activity among regional players serves as a signal to watch for market inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Expand Full Maintenance Lease Offerings | Lessors shift operational burden and regulatory adherence to meet shipper demands in the North American chemical sector. |
| Invest in HSLA Steel Railcar Manufacturing | Manufacturers enhance payload capacity and extend operational lifespan for agricultural and mining industry clients. |
| Develop Digital Fleet Management Solutions | Lessors provide real-time tracking and predictive maintenance, adding value beyond physical asset provision. |
| Acquire Specialized Tanker Fleet Operators | Companies gain critical assets and expertise for transporting chemicals under specific pressure and temperature ratings. |
| Target Emerging Market Rail Modernization | Lessors capitalize on infrastructure development and bulk commodity transport needs in countries like India. |
Research Approach
Multiple input streams—industry reports, company financial filings, and expert interviews—were reconciled to build a robust market view. Primary engagement included discussions with railcar lessors, specialized manufacturers, chemical logistics managers, and agricultural commodity traders. Secondary data sources comprised FRA regulations, ERA standards, AAR interchange rules, and various company annual reports. Both bottom-up and top-down triangulation methods validated market size and growth projections.
Cross-referencing historical market performance with panel input from industry experts informed the analytical framework across the modeling period. The segmentation dimensions modeled included railcar type, lease duration, end-user industry, leasing model, and regional deployment patterns. Compound annual growth rates were derived from a multi-factor regression analysis, incorporating industry-specific forecast inputs such as global chemical production and agricultural output projections.
Forecast precision tightens around the base case; tail outcomes carry wider variance under unforeseen regulatory shifts or significant economic downturns. Forecasts reflect documented assumptions regarding technological adoption and infrastructure investment. Geopolitical instability impacting trade routes represents a specific risk factor that could revise projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Railway Air Conditioning System Market
Railway Transportation
Automatic Train Protection Signaling Market
Railway Transportation
Railway Track Fittings Market
Railway Transportation
Railcar Movers Market
Railway Transportation
Urban Rail Transit Signaling Market
Railway Transportation
Railway Hydraulic Damper Market
Railway Transportation
High Speed Rail Coating Market
Railway Transportation
Train Transformer Market
Railway Transportation
Railway Sleepers Market
Railway Transportation
Autonomous Train Technology Market
Railway Transportation
Railway Connectors Market
Railway Transportation
Rail Gangways Market
Railway Transportation
Global Train Signalling System Market
Railway Transportation
Overhead Catenary System Market
Railway Transportation
Railway After-Cooler Market
Railway Transportation
Digital Railway Market