
 Railcar Movers Market | 2026-2036
Railcar Movers Market Size, Share, and Industry Trends Forecast 2026-2036
Railcar Movers Market Analysis
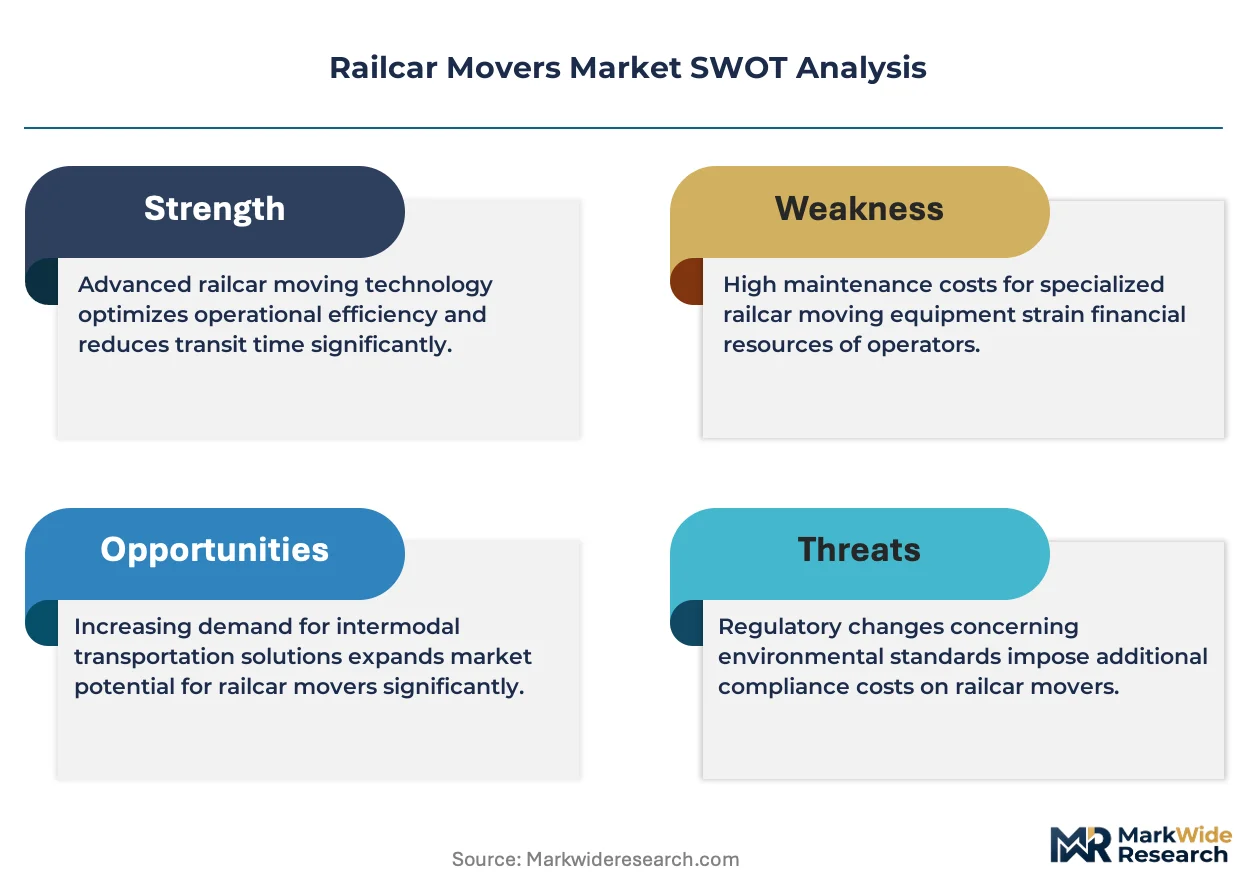
The EPA Tier 4 Final emissions mandate is decoupling diesel-dependent procurement from yard operations across North American freight networks. Trackmobile LLC leverages in-house electric powertrain development to sustain technology leadership in zero-emission switching. Nordco Inc. anchors its position through backward integration into traction control systems. Mitchell Equipment Corp. differentiates via specialized railcar mover configurations for constrained industrial sites.
Railcar movers are self-propelled vehicles designed to pull and position railcars on non-mainline track, typically generating tractive effort between 25,000 and 100,000 pounds and operating on standard-gauge rail with rubber-tire or steel-wheel propulsion systems for industrial switching, yard classification, and loading-dock alignment. Diesel railcar movers still occupy the largest installed base, though electric variants are capturing disproportionate capital allocation as battery energy density improves and charging infrastructure penetrates port and intermodal terminals. Medium railcar movers dominate unit volume among freight rail operators, while specialty railcar movers command premium positioning in nuclear material handling and aerospace component transport where precision control and redundant braking systems are mandated.
FAA coordination protocols for airport-adjacent rail spurs, OSHA confined-space operating requirements, and EPA locomotive emissions regulations collectively shape product certification pathways and operator training burdens. The convergence of these standards is forcing manufacturers to engineer modular powertrain architectures that can be retrofitted across installed fleets rather than replaced entirely. Stakeholders must monitor how rapidly Class I railroads internalize yard electrification targets versus delegating switching to third-party leasing operators with shorter asset replacement cycles.
Market Dynamics
The EPA Tier 4 Final emissions mandate is forcing diesel-to-electric conversion across North American freight yards, decoupling traditional procurement from yard operations as battery energy density improvements enable viable electrification at scale.
Growth Catalysts
- EPA Tier 4 Final:The emissions mandate accelerates capital allocation toward zero-emission switching equipment, with freight rail operators modernizing fleets to avoid regulatory penalties and operational restrictions in the United States Midwest rail corridor.
- Battery energy density gains:Lithium-ion cell improvements enable electric railcar movers to match diesel tractive effort ranges, penetrating port and intermodal terminals where charging infrastructure investments concentrate.
- Freight rail fleet modernization:Class I railroads and short-line operators expand capital programs to replace aging switching assets, concentrating demand in industrial switching and yard classification applications.
Market Restraints
- Charging infrastructure gaps:Rural switching yards and remote industrial spurs lack grid capacity for high-power charging, limiting electric railcar mover deployment to terminals with existing electrical infrastructure.
- Lithium supply concentration:Battery cell manufacturing and raw material refining concentrate in China, exposing North American manufacturers to supply chain volatility and geopolitical sourcing risk for critical powertrain components.
- Steel-wheel traction limitations:Rubber-tire propulsion systems maintain switching dominance on poorly maintained track and tight-radius curves where steel-wheel alternatives face adhesion and derailment constraints.
Strategic Opportunities
- Port electrification mandates:California's CARB regulations and pending federal port decarbonization incentives create dedicated demand for zero-emission switching at Los Angeles, Long Beach, and Oakland container terminals.
- Modular powertrain retrofits:Manufacturers can engineer swappable battery-electric conversion kits for installed diesel fleets, extending asset life without full replacement and capturing aftermarket revenue from Class I railroads with long depreciation cycles.
- Nuclear material handling specialization:Precision control and redundant braking requirements in Department of Energy facilities command premium positioning for specialty railcar mover configurations with demonstrated safety certification.
Industry Challenges
- Skilled technician scarcity:High-voltage powertrain maintenance and battery thermal management require specialized training that existing rail equipment mechanics lack, forcing manufacturers to absorb training costs or partner with technical institutes.
- FAA coordination complexity:Airport-adjacent rail spur operations demand simultaneous compliance with FAA protocols for runway proximity, OSHA confined-space requirements, and EPA emissions standards, multiplying certification timelines and documentation burdens.
- Legacy fleet integration:Electric railcar movers must interoperate with century-old track infrastructure, non-standard couplers, and analog signaling systems that resist digital retrofit without substantial yard reconfiguration investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railcar Movers Market |
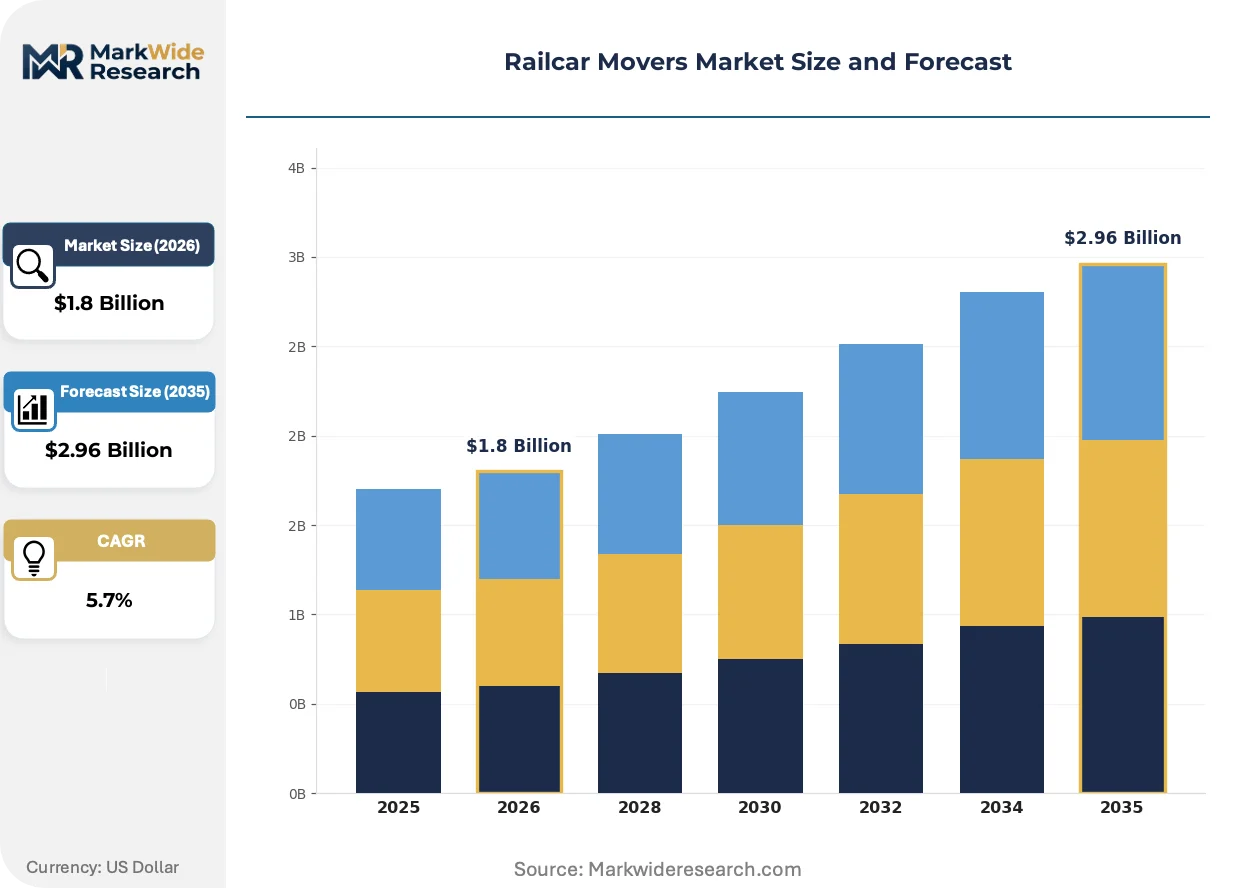
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Railcar Movers, Diesel Railcar Movers, Hybrid Railcar Movers, Manual Railcar Movers End User: Freight Rail Operators, Railcar Leasing Companies, Industrial Facilities, Maintenance Shops Application: Rail Yard Operations, Maintenance, Assembly Lines, Loading and Unloading Size: Small Railcar Movers, Medium Railcar Movers, Large Railcar Movers, Specialty Railcar Movers |
| Companies Covered | Nordco Inc., Mitchell Equipment Corp., Trackmobile LLC, Stewart & Stevenson LLC, Railquip Inc., BOSS RAILCAR MOVERS, Calbrandt, Rail King, Shuttlewagon Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railcar Movers Market Emerging Trajectories
Electrification is consolidating switching equipment architecture as battery chemistry improvements and charging infrastructure penetration reshape capital allocation patterns across freight rail networks.
Lithium-iron-phosphate battery packs are consolidating as the dominant energy storage technology for yard switching applications, offering thermal stability and cycle life advantages over nickel-manganese-cobalt alternatives. Port authorities and intermodal terminal operators in California and New Jersey are specifying these chemistry configurations in procurement tenders. The technology is consolidating supplier tiers as cell manufacturers with automotive scale advantages capture rail-specific powertrain contracts.
EPA locomotive emissions regulations are tightening certification pathways for diesel-powered switching equipment, forcing manufacturers to engineer modular architectures that accommodate future electrification retrofits. The industrial consequence is extended product development cycles and higher upfront engineering costs. Medium railcar mover segments serving freight rail operators face the steepest compliance burden, with manufacturers responding through captive powertrain development or strategic battery supplier partnerships.
Leasing-based procurement is displacing direct ownership among third-party switching operators with shorter asset replacement cycles and lower capital reserves. Equipment finance firms and rail service providers are capturing yard switching contracts from Class I railroads seeking to outsource electrification risk. This shift concentrates most visibly in the United States Midwest rail corridor, where regional short-line operators and industrial shippers prioritize operational flexibility over long-term asset ownership.
Railcar Movers Market Segmentation
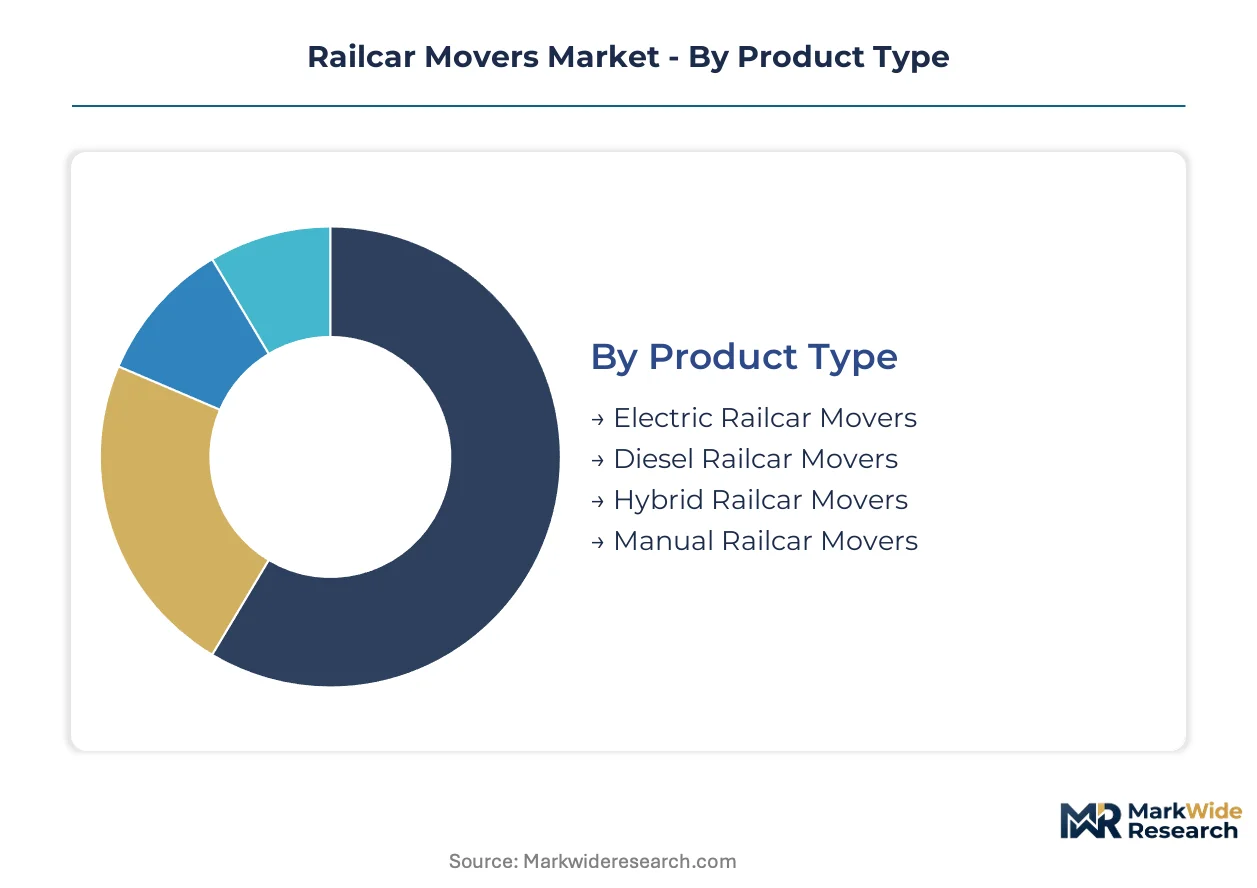
Railcar mover procurement patterns diverge sharply across powertrain technologies, end-user capital cycles, and yard operational requirements. Understanding these segment boundaries clarifies where electrification investments concentrate versus where legacy diesel assets retain residual value.
Product Type:
Powertrain selection separates buyers by emissions compliance urgency and charging infrastructure access.
- Electric Railcar Movers:Battery-electric units utilizing lithium-iron-phosphate packs deliver zero-emission switching with 25,000–100,000 pounds tractive effort. Demand concentrates at California ports and intermodal terminals where CARB mandates and federal decarbonization incentives override capital cost premiums.
- Diesel Railcar Movers:Compression-ignition engines with EPA Tier 4 Final aftertreatment systems still dominate rural switching yards and remote industrial spurs lacking grid capacity for high-power charging infrastructure.
- Hybrid Railcar Movers:Diesel-electric architectures bridge electrification gaps for operators with partial charging access.
- Manual Railcar Movers:Human-powered units serve maintenance shops and constrained industrial sites with minimal switching volumes.
Diesel railcar movers lead volumes today; electric variants are gaining share fastest.
End User:
Capital deployment horizons and regulatory exposure differentiate buyer categories.
- Freight Rail Operators:Class I railroads and short-line operators with 20–30-year asset depreciation cycles prioritize fleet modernization programs, concentrating procurement in the United States Midwest rail corridor where EPA enforcement tightens fastest.
- Railcar Leasing Companies:Third-party lessors with shorter replacement cycles and lower capital reserves favor leasing-based procurement models that outsource electrification risk.
- Industrial Facilities:Captive shippers and manufacturing plants with private rail spurs require specialized configurations for constrained sites.
- Maintenance Shops:Repair and overhaul facilities need precision positioning equipment for railcar inspection and component replacement.
Freight rail operators anchor current demand; leasing companies are expanding most quickly.
Application:
Operational intensity and precision requirements shape equipment specification.
- Rail Yard Operations:High-frequency switching and classification duties in freight terminals demand robust tractive effort and rapid cycle times.
- Maintenance:Inspection and repair positioning requires slow-speed precision control and redundant braking systems.
- Assembly Lines:Aerospace and automotive manufacturing integration mandates alignment accuracy for component loading.
- Loading and Unloading:Dock alignment operations at warehouses and distribution centers prioritize maneuverability in tight spaces.
Rail yard operations generate the largest equipment base; maintenance applications show steepest expansion trajectory.
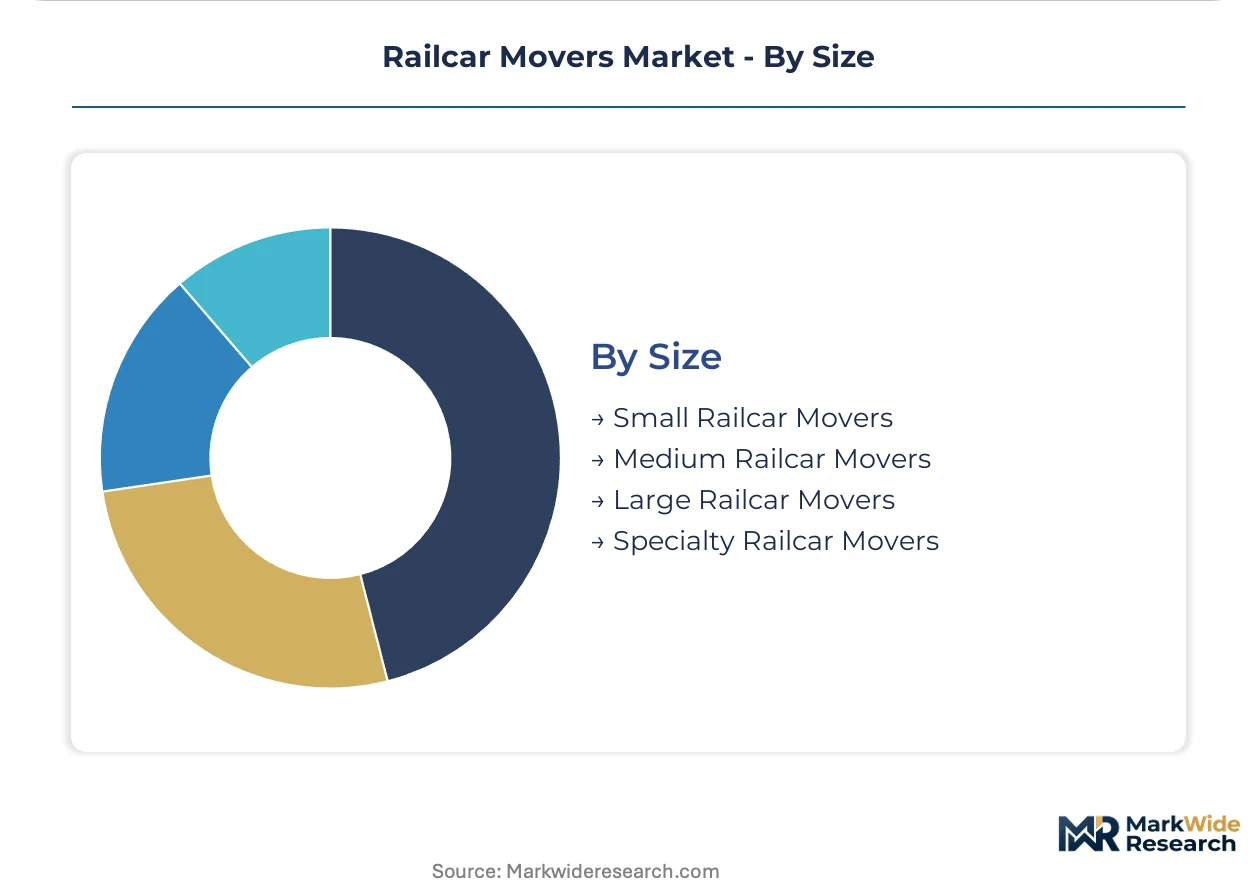
Size:
Tractive effort ratings and site constraints segment the installed fleet.
- Medium Railcar Movers:Units generating 40,000–70,000 pounds tractive effort dominate unit volume among freight rail operators facing the steepest EPA compliance burdens.
- Specialty Railcar Movers:Precision-control configurations with redundant braking systems command premium positioning in Department of Energy nuclear material handling facilities.
- Small Railcar Movers:Compact units serve light-duty switching and confined industrial environments.
- Large Railcar Movers:Heavy-haul configurations address bulk commodity terminals and unit train operations.
Medium railcar movers lead volumes today; specialty configurations are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Railcar mover manufacturing originated in the United States Midwest during the mid-20th century, with industrial switching demands from steel mills and automotive plants driving early mechanization. Today, regional markets diverge sharply based on electrification infrastructure maturity and emissions enforcement intensity.
United States
Freight rail operators in the Midwest rail corridor are executing the largest fleet modernization programs globally. EPA Tier 4 Final emissions standards are accelerating diesel-to-electric conversions across Illinois, Ohio, and Michigan switching yards. Chicago anchors North American demand concentration, with Union Pacific and BNSF Railway deploying capital toward zero-emission yard equipment.
Germany
Rail infrastructure operators prioritize precision switching equipment for dense industrial networks. EU Green Deal locomotive emissions targets and national rail decarbonization roadmaps are reshaping procurement specifications. The Ruhr industrial cluster and Bavarian manufacturing belt concentrate demand for advanced traction control systems in steel and automotive logistics.
China
State-owned rail operators are expanding port and intermodal terminal electrification at unprecedented scale. MIIT industrial equipment standards and dual carbon policy targets mandate zero-emission switching across Yangtze River Delta container terminals. Shanghai and Ningbo port authorities specify domestic lithium-iron-phosphate powertrains in procurement tenders.
India
Diesel railcar movers retain dominance across fragmented short-line networks and industrial spurs. PLI scheme incentives for domestic manufacturing and CEA grid modernization programs are slowly enabling electrification pilots. Gujarat and Maharashtra industrial corridors show earliest adoption of battery-electric switching at private port facilities.
Canada
Class I railroads operating transcontinental networks are synchronizing yard electrification with US regulatory timelines. Transport Canada locomotive emissions regulations and provincial carbon pricing mechanisms in British Columbia and Quebec accelerate capital allocation toward zero-emission equipment. Vancouver and Prince Rupert port terminals lead Pacific gateway electrification investments.
Railcar Movers Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technology integration depth and certification complexity. The vendor base organizes into three discernible tiers: integrated powertrain developers with captive battery engineering, specialized fabricators focused on constrained-site configurations, and regional assemblers serving price-sensitive short-line operators. Strategic differentiation concentrates on modular electrification architectures and aftermarket retrofit kits rather than unit manufacturing scale. Dominant competitive moves include backward integration into traction control electronics and strategic partnerships with port authorities for charging infrastructure co-development.
Within the integrated powertrain tier, Trackmobile LLC and Nordco Inc. exemplify manufacturers with in-house electric propulsion development capabilities. Mitchell Equipment Corp. occupies a distinct position among specialized fabricators serving nuclear material handling and aerospace component transport applications where redundant braking certification commands pricing premiums. Stewart & Stevenson LLC represents the diversified industrial equipment conglomerate archetype, leveraging cross-sector manufacturing scale to serve rail-specific demand. These three company structures illustrate how competitive positioning stratifies across technology ownership depth and application specialization.
| Leading Market Players |
|---|
| Nordco Inc. |
| Mitchell Equipment Corp. |
| Trackmobile LLC |
| Stewart & Stevenson LLC |
| Railquip Inc. |
| BOSS RAILCAR MOVERS |
| Calbrandt |
| Rail King |
| Shuttlewagon Inc. |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up specialists in railcar mover manufacturing exercise pricing discipline through captive powertrain engineering while absorbing lithium-ion cell volatility from concentrated Asian suppliers. Their ownership structure favors modular retrofit architectures that extend asset life and capture aftermarket revenue, insulating margins from commodity-tier competition.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates integrated powertrain developers from specialized fabricators and regional assemblers. Price differentiation hinges on EPA Tier 4 Final certification grade and captive battery engineering depth. Pricing pressure stems from lithium supply concentration in China exposing North American manufacturers to sourcing volatility. Leasing-based procurement models among third-party switching operators demonstrate highest price sensitivity, while nuclear material handling buyers prioritize redundant braking certification over unit cost.
Supply Chain Analysis
Welding technician and high-voltage powertrain specialist scarcity across Illinois, Ohio, and Michigan constrains production scaling for electric railcar mover assembly. Manufacturing draws from Chinese lithium-iron-phosphate cell production, German traction control electronics, and domestic steel fabrication. Single-source vulnerability in battery cell supply exposes lead times to geopolitical disruption. Distribution runs through Class I railroad procurement departments, equipment finance firms, and regional short-line operator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Railcar mover procurement functions as a geographic-arbitrage play between EPA-enforced Midwest switching yards and diesel-retaining rural industrial spurs, with regulatory cost differentials exceeding electrification infrastructure premiums.
For Market Incumbents: Anticipate leasing-based procurement displacement by developing swappable battery-electric retrofit kits for installed diesel fleets. Backward integration into traction control electronics defends margin position against emerging powertrain specialists. Prioritize FAA coordination protocol certification for airport-adjacent rail spur contracts where compliance complexity creates barriers. For New Entrants and Emerging Players: Modular battery-electric conversion technology offers entry into Class I railroad aftermarket services with shorter payback periods than full unit manufacturing. Nuclear material handling and aerospace component transport applications show lowest competitive density and highest certification premiums. Partner with California port authorities on charging infrastructure co-development to secure zero-emission switching tenders. For Investors and Strategic Acquirers: Valuations sit cheapest among regional assemblers lacking captive powertrain engineering but holding established short-line operator relationships. Five-to-ten-year viability hinges on electrification retrofit capability rather than diesel unit production scale. Monitor EPA enforcement intensity in the United States Midwest rail corridor as inflection indicator for capital allocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Powertrain Retrofit Development | Captures aftermarket revenue from Class I railroads with long depreciation cycles and electrification mandates. |
| Backward Integration into Traction Control | Reduces dependency on German electronics suppliers and secures EPA certification pathway control. |
| Port Authority Charging Partnership | Locks in zero-emission switching demand at Los Angeles, Long Beach, and Oakland container terminals. |
| Nuclear Material Handling Certification | Commands premium positioning in Department of Energy facilities with precision control requirements. |
| Leasing-Based Procurement Model | Outsources electrification risk for third-party operators with shorter asset replacement cycles. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Class I railroad procurement directors, port authority equipment managers, railcar leasing company executives, and aftermarket service heads with secondary validation against EPA enforcement databases, FRA safety filings, and equipment finance firm portfolio disclosures. Bottom-up unit deployment estimates triangulated against top-down capital expenditure patterns across freight rail operators.
Historical reference periods anchored the projection horizon to pre-pandemic baseline switching volumes and post-Tier 4 Final implementation fleet modernization cycles. The analytical framework modeled powertrain technology, end-user capital cycle, application intensity, and tractive effort rating segmentation dimensions. CAGRs derived from equipment replacement cycle analysis and regulatory compliance deadline clustering, incorporating lithium-ion cell cost curves and charging infrastructure penetration assumptions specific to port and intermodal terminal electrification.
The model holds under sustained EPA enforcement intensity and lithium supply chain continuity; deviation in federal emissions regulation timing or geopolitical trade restrictions would shift fleet modernization trajectories. Forecasts reflect these base condition assumptions with acknowledged sensitivity to Class I railroad capital allocation prioritization and battery chemistry substitution patterns. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Digital Axle Counter Market
Railway Transportation
Railway Hydraulic Damper Market
Railway Transportation
Australia Rail Freight Transport Market
Railway Transportation
United States Rail Freight Transport Market
Railway Transportation
Railway Connectors Market
Railway Transportation
Urban Rail Transit Signaling Market
Railway Transportation
Railway Traction Inverter Market
Railway Transportation
Canada Rail Freight Transport Market
Railway Transportation
Railway Roof Switches Market
Railway Transportation
Urban Rail Transit Market
Railway Transportation
High Speed Rail Coating Market
Railway Transportation
Railway Li-Ion Battery Market
Railway Transportation
Autonomous Train Technology Market
Railway Transportation
Rail Gangways Market
Railway Transportation
Global Train Signalling System Market
Railway Transportation
Railway Sleepers Market