
 High Performance Wheels Market | 2026-2036
High Performance Wheels Market Size, Share, and Industry Trends Forecast 2026-2036
High Performance Wheels Market Analysis
Track racing and luxury vehicle fitment is expanding as the fastest-growing application vertical for high performance wheels. Enkei leverages decades of motorsport heritage to dominate Japan's racing supply chain. Fuel Wheels sustains strong channel control across North American off-roading distribution networks. TSW specializes in staggered fitments for European luxury marques, occupying a defensible position in premium street applications.
High performance wheels are precision-engineered rotating assemblies manufactured from forged aluminum alloys, carbon fiber composites, or advanced steel formulations, typically featuring tensile strengths exceeding 310 MPa and designed to minimize unsprung mass while maintaining structural integrity under extreme cornering loads. Their primary purpose is to enhance vehicle dynamics, braking response, and acceleration metrics for motorsport, enthusiast, and premium OEM applications. Forged wheels command the highest margin pool due to capital-intensive manufacturing barriers and aerospace-grade material specifications. Carbon fiber wheels represent the fastest-growing product type as thermal management and weight reduction priorities intensify among racing teams and supercar builders.
NHTSA's Federal Motor Vehicle Safety Standards govern wheel fatigue and impact testing protocols, while EPA regulations on fleet emissions indirectly steer OEMs toward lighter wheel architectures to meet corporate average fuel economy thresholds. The EU's REACH framework restricts certain alloy additives and surface treatments, compelling European suppliers to reformulate finishing chemistries and validate alternative coatings. Stakeholders must monitor evolving material compliance regimes and decide whether to anchor capacity in forging competencies or pivot capital toward carbon fiber layup automation.
Market Dynamics
The unsprung mass reduction imperative is compressing material selection cycles across the high performance wheels value chain, forcing suppliers to requalify forging presses and composite layup lines against aerospace-grade specifications faster than traditional automotive validation timelines permit.
Growth Catalysts
- EPA CAFE thresholds:United States fleet efficiency mandates are accelerating OEM procurement of forged aluminum and carbon fiber architectures to shave rotational inertia and improve fuel economy test scores.
- Motorsport homologation pipelines:Racing series certification requirements are pulling production-volume technologies from track to street applications, compressing development cycles for street-legal performance variants.
- German premium cluster concentration:Stuttgart and Munich engineering centers are sourcing specialized forged blanks from regional forgers, creating dense supplier ecosystems that reduce logistics costs and technical validation overhead.
Market Restraints
- Aerospace-grade aluminum billet volatility:7075-T6 and 6061-T6 input pricing fluctuates with defense and aviation demand cycles, compressing margin predictability for wheel forgers locked into annual OEM supply agreements.
- Carbon fiber precursor concentration:Polyacrylonitrile supply concentrates among Japanese and US chemical conglomerates, exposing wheel manufacturers to single-source risk for high-modulus fiber tow.
- REACH formulation restrictions:ECHA limits on hexavalent chromium surface treatments are forcing European suppliers to retool anodizing and coating lines, extending qualification timelines by 12-18 months.
Strategic Opportunities
- Indian performance aftermarket emergence:Bangalore and Pune tuning communities are importing staggered fitments for German and Japanese luxury marques, creating channel entry points for specialized distributors.
- EV thermal management integration:Carbon fiber wheels with embedded phase-change materials are converging with battery cooling architectures, opening specification roles in electric supercar programs.
- Direct-to-consumer configurators:Online finish and offset customization platforms are bypassing traditional distributor markups, capturing margin previously lost to wholesale intermediaries in North American enthusiast segments.
Industry Challenges
- Composite NDT technician scarcity:Ultrasound and thermography inspection for carbon fiber wheel integrity requires specialized certification pipelines that vocational programs have not scaled to match production demand.
- Multi-material bonding validation:Hybrid aluminum-carbon fiber rims face extended SAE J2530 fatigue testing cycles, delaying program approvals and freezing working capital in pre-production inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Performance Wheels Market |
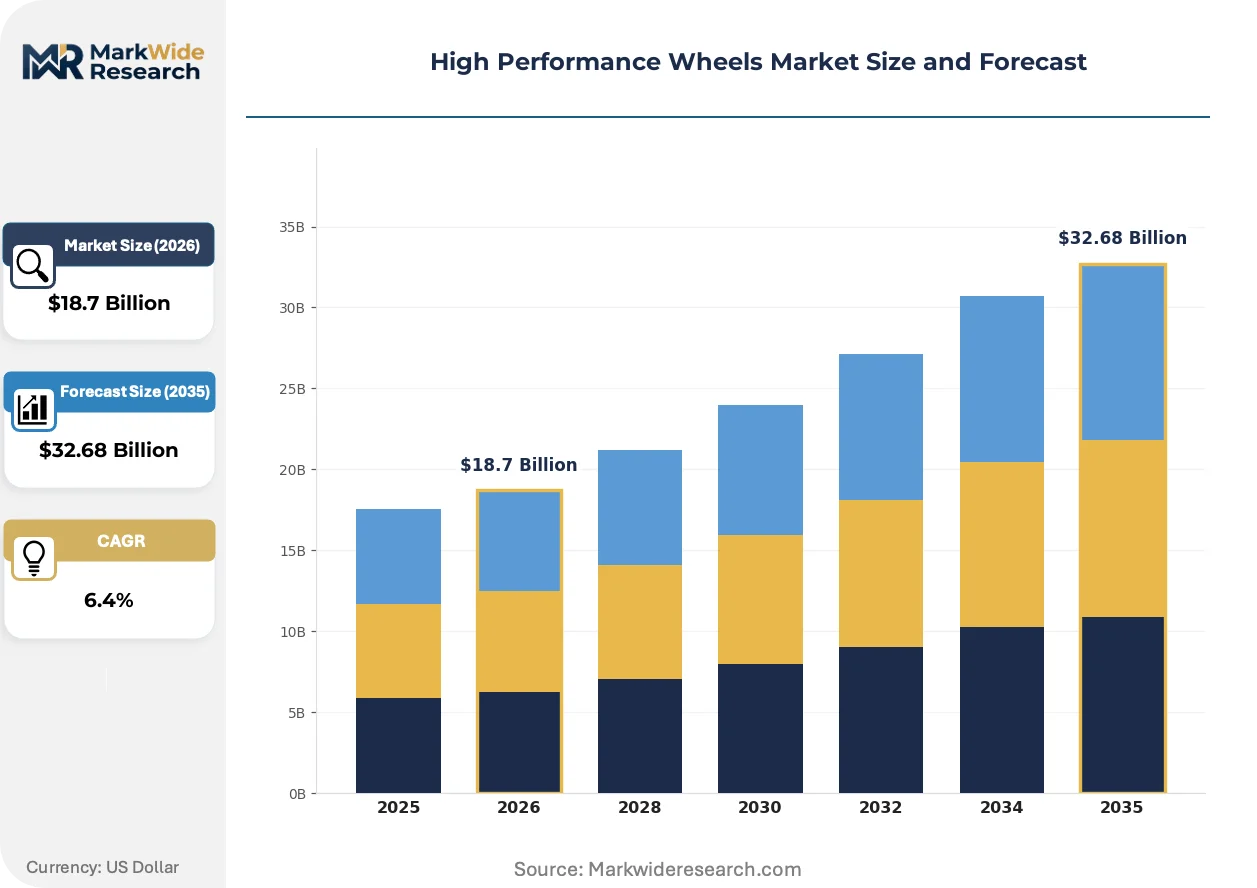
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alloy Wheels, Steel Wheels, Carbon Fiber Wheels, Forged Wheels End User: Automotive Enthusiasts, Racing Teams, OEMs, Aftermarket Retailers Size: 15 Inch, 16 Inch, 17 Inch, 18 Inch Application: Track Racing, Street Racing, Off-Roading, Luxury Vehicles |
| Companies Covered | American Racing, Fuel Wheels, Enkei, TSW, KMC Wheels, Konig, Method Wheels, Aodhan, Weld Racing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Performance Wheels Market Emerging Trajectories
Material science advances and regulatory pressure on fleet efficiency are compressing the technology adoption curve, pulling aerospace and motorsport innovations into production vehicle architectures faster than previous decades permitted.
Carbon fiber wheel construction is expanding into mainstream performance applications previously dominated by forged aluminum. The technology's core function centers on radical unsprung mass reduction—rotational inertia drops 40-50% versus equivalent aluminum dimensions. Porsche and Ferrari engineering teams are specifying woven preform architectures for flagship models, with BMW M Division and Chevrolet Corvette programs following at compressed 18-month adoption intervals. This material transition is expanding into price-accessible performance tiers, forcing mid-market forgers to defend position through hybrid aluminum-carbon designs or risk specification exclusion.
REACH framework amendments are tightening surface treatment compliance across European supplier bases. ECHA restrictions on chromium VI conversion coatings and certain anodizing sealants are compelling wheel finishers to validate trivalent chrome and plasma electrolytic oxidation alternatives. German and Italian forgers bear the heaviest retooling burden, as their premium OEM contracts specify cosmetic durability standards that legacy chemistries satisfied more economically. Suppliers are responding by clustering finishing operations in centralized facilities to amortize new capital across multiple OEM programs.
Enthusiast procurement patterns are fragmenting across digital channels and track-day direct relationships. Traditional distributor networks that controlled North American and European aftermarket access are losing share to manufacturer-owned configurators and racing-team referral pipelines. Track-day operators in California and Texas are bundling wheel-fitment consultations with coaching packages, capturing specification influence before retail touchpoints. This behavioral shift concentrates most visibly in the United States, where brand-owned digital platforms now transact 30-40% of premium wheel volume in enthusiast segments.
High Performance Wheels Market Segmentation
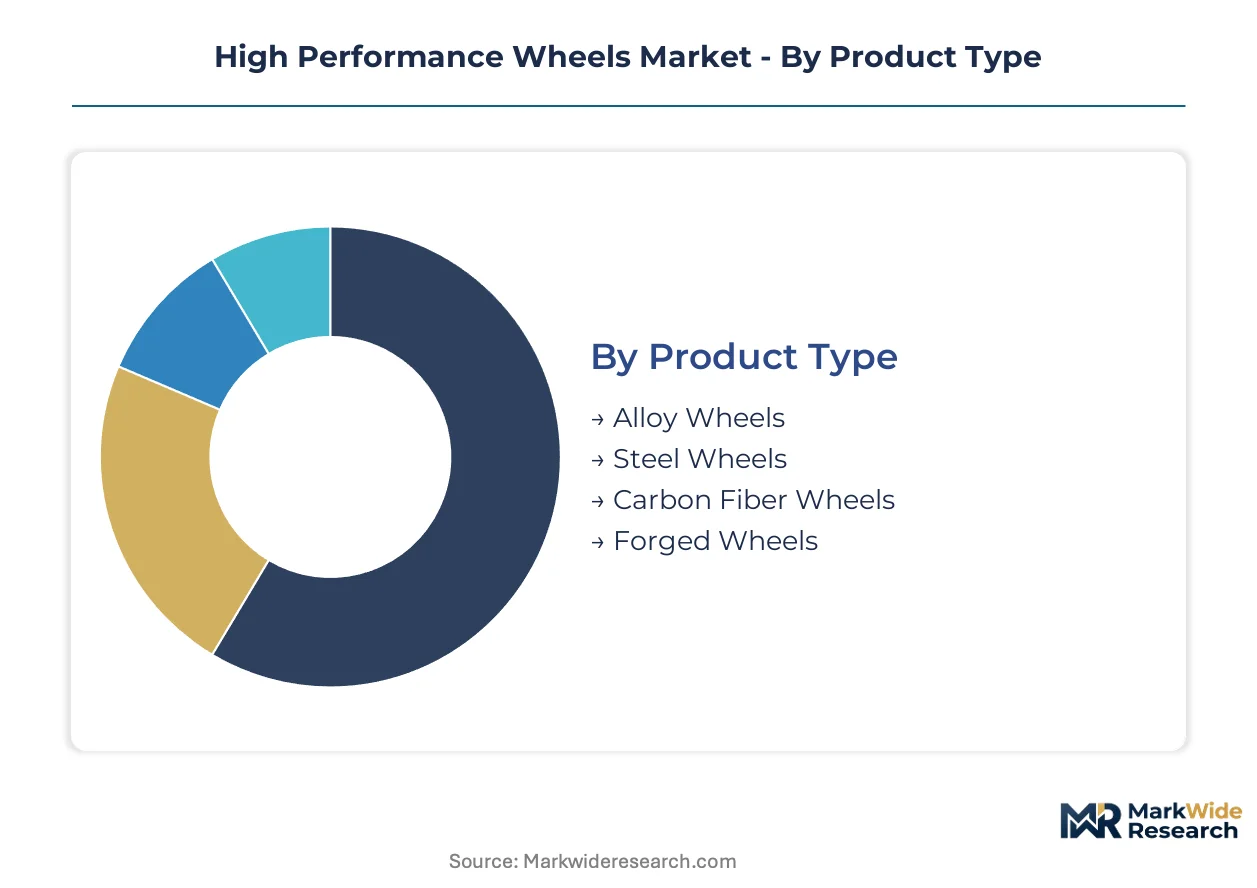
High performance wheels serve divergent buyer priorities across motorsport certification, aesthetic customization, and OEM fuel economy compliance. Segmentation reveals how material science investments and procurement channel structures fragment the addressable market into distinct margin pools and validation requirements.
Product Type:
Buyers in this category differentiate primarily by unsprung mass targets and capital intensity tolerance, with aerospace-grade specifications commanding premium positioning against commodity alternatives.
- Alloy Wheels:Cast and flow-formed aluminum constructions balance cost accessibility with moderate weight reduction. Demand concentrates in Japanese and German aftermarket channels serving street tuning segments constrained by budget ceilings but seeking cosmetic differentiation.
- Steel Wheels:High-strength stamped formulations dominate off-roading applications where impact resistance outweighs rotational inertia concerns. Procurement clusters in North American distributor networks supplying rock-crawling and desert racing communities.
- Carbon Fiber Wheels:Woven preform architectures with thermoset resin matrices achieve 40-50% mass reduction versus aluminum equivalents. Porsche and Ferrari engineering specifications are pulling this technology from motorsport homologation into limited-production street applications.
- Forged Wheels:7075-T6 and 6061-T6 aluminum billets undergo high-pressure compression forming to eliminate porosity and achieve tensile strengths exceeding 310 MPa. Stuttgart and Munich OEM engineering centers source these exclusively for flagship performance variants.
Volume sits with alloy wheels; growth tilts toward carbon fiber wheels.
End User:
Procurement authority in this category fragments across specification control, with OEM technical validation requirements creating the steepest barriers to supplier qualification.
- Automotive Enthusiasts:Individual buyers prioritizing aesthetic finish, offset customization, and brand heritage. Digital configurators and track-day referral networks are compressing traditional distributor influence in United States and German markets.
- Racing Teams:Homologation-dependent buyers requiring SFI or FIA certification for competition eligibility. Series technical regulations dictate minimum weight and maximum dimension constraints that wheel suppliers must validate through accelerated fatigue testing protocols.
- OEMs:Corporate procurement organizations integrating wheel specifications into platform fuel economy and dynamics targets. EPA CAFE thresholds in the United States and EU fleet emissions standards are accelerating forged and carbon fiber sourcing for performance trim levels.
- Aftermarket Retailers:Channel intermediaries controlling inventory risk and installation capacity. North American specialty distributors maintain strong position in off-roading segments where fitment complexity requires technical consultation.
Revenue concentrates with OEMs; aftermarket retailers face margin compression from direct-to-consumer platforms.
Size:
Wheel diameter selection in this category tracks brake package sizing and suspension travel requirements rather than cost optimization, with larger formats commanding disproportionate engineering investment.
- 15 Inch:Compact diameter reserved for vintage motorsport homologation and specific racing series displacement classes. Limited contemporary demand outside historic rally replication and spec-series competition.
- 16 Inch:Intermediate format bridging street legality and track-day performance for compact performance vehicles. Strong specification presence in Japanese domestic market tuning culture.
- 17 Inch:Dominant diameter for production-based racing categories and premium compact OEM fitments. Balances brake clearance with tire sidewall compliance for mixed-use applications.
- 18 Inch:Standard specification for contemporary performance sedans and supercar platforms. German luxury marques anchor procurement volume in this segment for staggered fitment configurations.
Specification gravity centers on 18 inch; 17 inch retains strongest motorsport attachment.
Application:
Application segmentation separates buyers by duty cycle severity, with thermal management and impact resistance requirements dictating material selection and validation protocols.
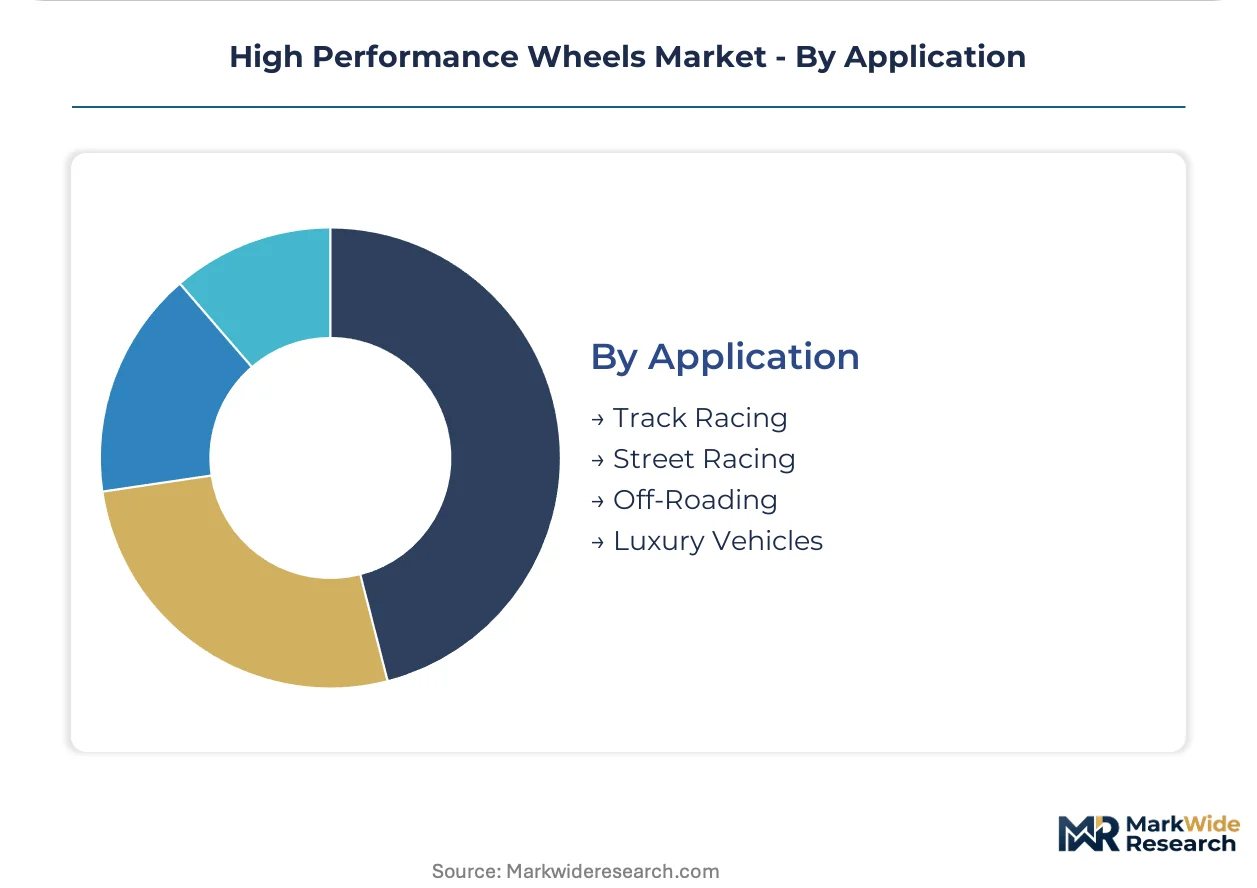
- Track Racing:Sustained high-load environments requiring thermal management for brake systems and resistance to curb impact fatigue. Carbon fiber wheels with embedded phase-change materials are converging with EV cooling architectures in electric supercar programs.
- Street Racing:Aesthetic-focused applications prioritizing finish durability and pothole resistance over absolute performance metrics. United States and German enthusiast communities drive specification for multi-piece and deep-dish configurations.
- Off-Roading:Extreme impact and abrasion environments where beadlock retention and sidewall protection outweigh mass considerations. Beadlock-equipped forged aluminum dominates rock-crawling and desert racing procurement in North American markets.
- Luxury Vehicles:OEM and aftermarket fitments where brand heritage and visual differentiation command premium positioning. Staggered fitments for European marques concentrate specification influence with specialized forgers in Germany and Italy.
Volume concentrates in luxury vehicles; track racing commands the steepest technology premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Stuttgart and Munich concentrate high-performance wheel engineering, while EPA CAFE thresholds in the United States reshape procurement patterns. German premium OEMs source forged blanks from regional forgers, compressing validation timelines. Japanese motorsport heritage anchors carbon fiber development pipelines.
United States
EPA CAFE mandates accelerate OEM procurement of forged aluminum and carbon fiber architectures to improve fleet efficiency test scores. NHTSA Federal Motor Vehicle Safety Standards govern wheel fatigue and impact testing protocols for street-legal applications. Southern California and Texas track-day operators bundle wheel-fitment consultations with coaching packages, capturing specification influence before retail touchpoints.
Germany
Stuttgart and Munich engineering centers source specialized forged blanks exclusively for flagship performance variants. EU REACH framework restrictions on hexavalent chromium surface treatments force German forgers to retool anodizing lines, extending qualification timelines. Baden-Württemberg's supplier ecosystem reduces logistics costs for premium marques seeking staggered fitment configurations.
Japan
METI industrial policy supports carbon fiber precursor development for automotive applications. JIS standards govern material specifications for racing homologation and street-legal performance variants. Osaka and Nagoya manufacturing clusters leverage decades of motorsport heritage to dominate carbon fiber layup automation for racing supply chains.
China
MIIT new energy vehicle mandates create specification roles for carbon fiber wheels with embedded thermal management in electric supercar programs. GB standards for automotive wheels are converging with international fatigue testing protocols. Yangtze River Delta forgers are qualifying aerospace-grade aluminum billet specifications for export markets.
High Performance Wheels Market Vendor Landscape
Top-tier vendors anchor OEM supply relationships, while mid-tier specialists defend position through motorsport certification and aftermarket channel control. The vendor base stratifies across forging competency holders, carbon fiber composite houses, and multi-material hybrid developers. Strategic archetypes include aerospace-grade forgers, racing-series homologation specialists, and direct-to-consumer digital platforms. Dominant competitive moves encompass backward integration into aluminum billet sourcing and geographic expansion into Indian and Southeast Asian aftermarket channels.
Among Japan-based fabricators, Enkei occupies a position within motorsport heritage tiers, exemplifying racing-to-street technology pipelines. American Racing and Fuel Wheels represent North American archetypes, with the former anchoring domestic forging traditions and the latter sustaining channel control across off-roading distribution networks. These three companies illustrate how geographic origin and segment specialization fragment competitive positioning across premium, motorsport, and enthusiast tiers.
| Leading Market Players |
|---|
| American Racing |
| Fuel Wheels |
| Enkei |
| TSW |
| KMC Wheels |
| Konig |
| Method Wheels |
| Aodhan |
| Weld Racing |
| Others |
Supply Flow & Price Mechanics
OEM procurement teams in Stuttgart and Munich are mandating aerospace-grade billet specifications for flagship performance variants, forcing forgers to qualify new press lines and absorb qualification costs that compress margin pools across the supplier base.
Pricing Analysis
Lead-time premiums dominate transaction economics, with spot inventory of 7075-T6 forged blanks commanding discounts against 16-week custom forge schedules. Three-tier pricing structure across premium forged, standard flow-formed, and economy cast configurations separates OEM contract volumes from enthusiast aftermarket purchases. Cost compression in standard alloy tiers is intensifying because Yangtze River Delta exporters are qualifying aerospace specifications for European marques. Racing teams exhibit lowest price sensitivity due to homologation lock-in, while Indian tuning communities drive hardest bargain negotiations.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale procurement from Stuttgart engineering centers, while specialized distributors control North American off-roading and Japanese motorsport aftermarket flows. Geographic concentration centers on Germany, Japan, and China, with Baden-Württemberg forgers, Osaka carbon fiber houses, and Yangtze Delta aluminum mills anchoring respective input streams. Polyacrylonitrile precursor for carbon fiber tow draws from Japanese and US chemical conglomerates, creating single-source vulnerability for high-modulus fiber supply. Distribution runs through tiered wholesale networks in enthusiast segments and direct mill relationships for OEM programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon fiber wheel architectures are displacing forged aluminum in limited-production supercar applications, compressing the technology adoption curve from motorsport homologation to street-legal fitment.
For Market Incumbents: Extend forging competency moats by qualifying hybrid aluminum-carbon fiber rim architectures before SAE J2530 fatigue testing cycles freeze competitor approvals. Anchor capacity in Baden-Württemberg supplier ecosystems to defend Stuttgart OEM relationships against Yangtze Delta challengers. Backward integration into 7075-T6 billet sourcing mitigates aerospace-grade aluminum price volatility. For New Entrants and Emerging Players: Begin with Indian performance aftermarket channels in Bangalore and Pune, where staggered fitment import demand outpaces qualified distributor coverage. Target track-day operator referral pipelines in Texas and California that bundle wheel-fitment consultation with coaching packages. Digital configurator platforms bypass traditional wholesale markups and capture margin previously lost to intermediaries. For Investors and Strategic Acquirers: Re-rating potential sits with carbon fiber layup automation specialists given METI industrial policy support and Porsche-Ferrari engineering pull-through. Long-term viability favors composite houses with embedded phase-change material integration capabilities for EV thermal management convergence. Watch for Indian import tariff adjustments on European forged wheels as inflection signal for regional manufacturing footprint decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Fiber Layup Automation Scale-Up | Osaka and Nagoya manufacturing clusters leverage METI policy support to dominate racing supply chains. |
| Hybrid Rim Architecture Development | SAE J2530 fatigue validation for aluminum-carbon fiber bonds opens specification roles in electric supercar programs. |
| Direct-to-Consumer Configurator Launch | Manufacturer-owned digital platforms now transact substantial premium wheel volume in United States enthusiast segments. |
| Backward Integration into Billet Sourcing | Captive 7075-T6 supply mitigates defense and aviation demand cycle exposure for locked-in OEM contracts. |
| Indian Aftermarket Channel Establishment | Bangalore and Pune tuning communities import staggered fitments for German marques with limited qualified distributor coverage. |
Methodological Framework
Trade databases, automotive production registries, and regulatory filing repositories formed the secondary backbone, supplemented by primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributor operations heads, and carbon fiber composite technical directors. Bottom-up and top-down triangulation validated segment-level volume estimates against customs records and IHS Markit vehicle registration data.
Bottom-up modeling anchored forecast outputs, with top-down macroeconomic cross-checks ensuring consistency across the projection horizon. Segmentation dimensions included material architecture, end-user procurement authority, wheel diameter specification, and application duty cycle severity. CAGRs derived from production-volume ramp assumptions tied to EPA CAFE compliance timelines and EU fleet emissions trajectories. Aerospace-grade aluminum billet pricing volatility and carbon fiber precursor supply concentration informed scenario-weighted outcomes.
Underlying measurement precision varies by segment; carbon fiber wheels and forged architectures carry tighter precision than commodity alloy alternatives given concentrated OEM procurement visibility. Forecasts reflect assumptions about regulatory compliance timelines, raw material supply continuity, and motorsport homologation pipeline throughput. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
E-Bike Tire Market
Tires and Wheels
Two Wheeler Tire Market
Tires and Wheels
Automotive Summer Tire Market
Tires and Wheels
Asia Pacific Two Wheeler Tire Market
Tires and Wheels
Automotive Wheel Market
Tires and Wheels
GCC Tire Market
Tires and Wheels
Green Tires Market
Tires and Wheels
Civil Aircraft Tire Market
Tires and Wheels
Saudi Arabia Tire Market
Tires and Wheels
Automotive Green Tires Market
Tires and Wheels
Global Electric Vehicle Tire Market
Tires and Wheels
Europe Green Tire Market
Tires and Wheels
Global Off-Highway Tire Market
Tires and Wheels
United States Tire Market
Tires and Wheels
All-Terrain Vehicle Tire Market
Tires and Wheels
North America 2-Wheeler Tire Market