
 Railway Track Fittings Market | 2026-2036
Railway Track Fittings Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Track Fittings Market Analytics
The EU Green Deal is restructuring procurement criteria across European rail networks, mandating lower-carbon track materials and extended durability benchmarks. Vossloh AG leverages its integrated manufacturing footprint across Germany and France to supply compliant fastening systems. Pandrol Ltd. anchors its competitive position through R&D intensity in elastomer-based rail clip technologies. AGICO Group dominates volume production of cast steel rail joints for Asian and African export markets.
Railway track fittings comprise the mechanical assemblies that secure rails to sleepers or slabs, maintain gauge alignment, and absorb dynamic loads from rolling stock. Elastic rail clips manufactured from spring steel with specified tensile strength above 1,400 MPa generate clamping force to resist rail creep under thermal expansion and braking stress. Fastening systems command the largest value share across product categories, while composite insulators represent the fastest-expanding material segment as networks replace thermit-welded joints with glued insulated joints for signaling compatibility. High-speed rail applications concentrate premium demand due to stringent fatigue resistance and aerodynamic stability requirements.
The European Union Agency for Railways (ERA) enforces interoperability standards through the TSIs that dictate track component certification for cross-border corridors. China's National Railway Administration (NRA) and India's Ministry of Railways impose domestic content requirements that shape supplier qualification and market access. The US Federal Railroad Administration (FRA) mandates Part 213 track safety standards that drive replacement cycles for worn fastening hardware. Stakeholders must monitor evolving decarbonization mandates and localization policies that will determine competitive positioning in the next phase of infrastructure renewal.
Market Dynamics
Railway track fittings markets face structural pressure from the EU Green Deal's modal shift mandates, which are redirecting capital from road infrastructure toward rail corridors and reshaping procurement specifications across European networks.
Growth Catalysts
- EU Green Deal modal shift targets:European Union policy mandates a 75% rail freight increase by 2030, forcing national operators to accelerate track renewal programs and expand electrified corridors.
- High-speed rail expansion:China, India, and Spain are commissioning new dedicated passenger lines that require fatigue-resistant fastening systems with extended maintenance intervals.
- Composite material substitution:Thermoset polymer insulators and fiber-reinforced elastomers are replacing cast steel components in signaling-critical track sections, opening premium product categories.
Market Restraints
- Spring steel price volatility:Elastic rail clip manufacturing depends on high-tensile alloy steel whose spot prices fluctuate with scrap metal and energy input costs.
- Domestic content requirements:China's National Railway Administration and India's Ministry of Railways impose local sourcing thresholds that exclude foreign suppliers from flagship corridor tenders.
- Welded joint durability limits:Thermit welding remains cost-competitive for low-speed freight lines, slowing adoption of glued insulated joints despite signaling advantages.
Strategic Opportunities
- African rail rehabilitation:Addis Ababa-Djibouti and Lagos-Kano corridors require complete track fitting replacement, creating export demand for cast steel rail joints and fastening hardware.
- Digital twin integration:Track condition monitoring systems are converging with predictive maintenance platforms, enabling sensor-embedded fastening systems as a new product tier.
- CSRD disclosure mandates:European Corporate Sustainability Reporting Directive rules are forcing operators to document lifecycle carbon in track materials, favoring suppliers with verified environmental product declarations.
Industry Challenges
- Interoperability certification timelines:European Union Agency for Railways Technical Specifications for Interoperability approval cycles extend 18-24 months, delaying product launches on cross-border corridors.
- Skilled welder shortages:Glued insulated joint installation requires certified technicians trained in epoxy chemistry and rail geometry, creating bottlenecks in renewal program execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Track Fittings Market |
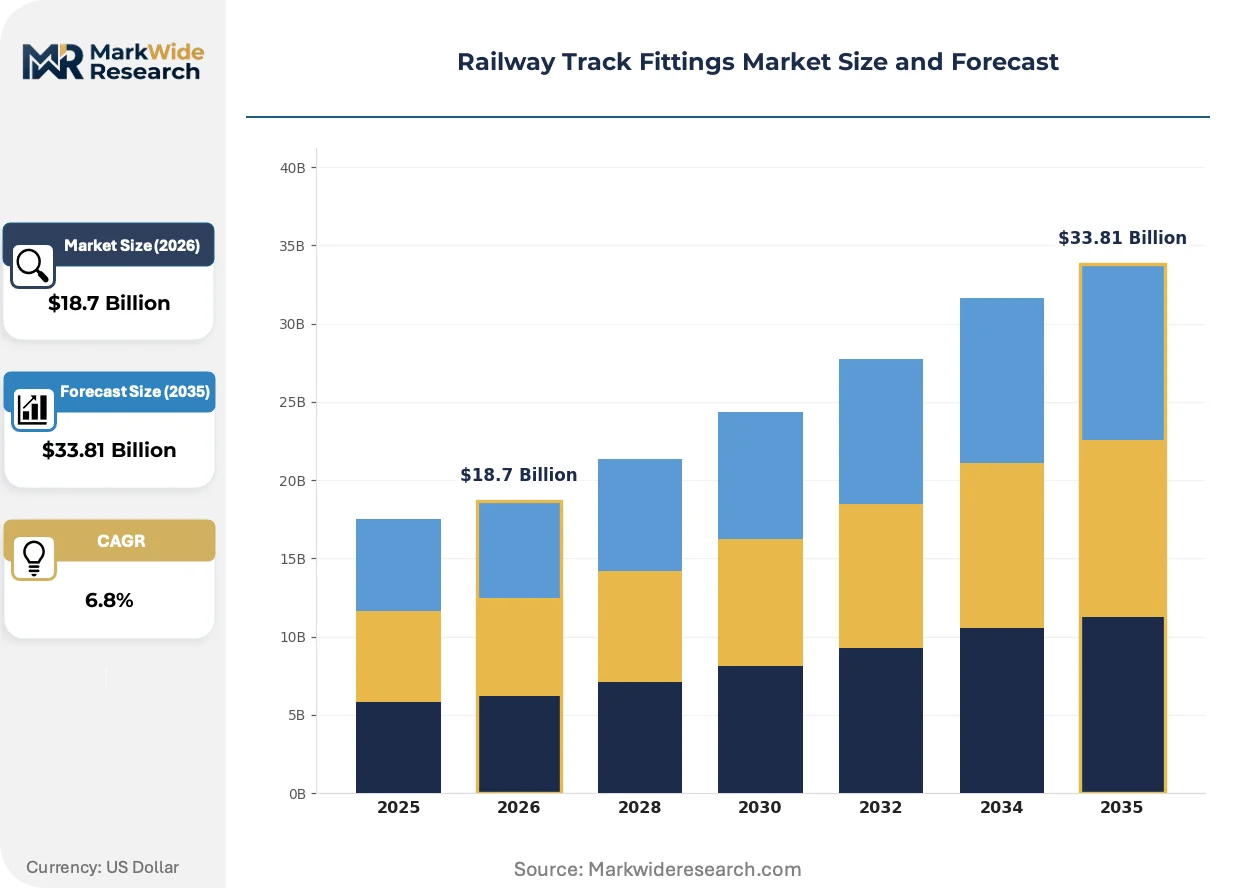
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rail Clips, Fastening Systems, Rail Joints, Insulators Material: Steel, Aluminum, Composite, Plastic Application: Heavy Rail, Light Rail, Metro, High-Speed Rail End User: Rail Operators, Infrastructure Developers, Maintenance Agencies, Contractors |
| Companies Covered | Pandrol Ltd., International Track Systems, AGICO Group, Progress Rail, KVT-Fastening, Harsco Corporation, ArcelorMittal Europe, Kingrail, Vossloh AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Track Fittings Market Evolving Landscape
Track fitting suppliers are repositioning around predictive maintenance integration and carbon-accounting compliance, with material science advances enabling longer service intervals and embedded sensing capabilities.
Sensor-embedded elastic rail clips are integrating micro-accelerometers and temperature monitors that transmit real-time clamping force data to centralized maintenance platforms. Deutsche Bahn and SNCF Réseau are piloting these systems on high-stress curves and switch zones. This convergence is compressing reactive maintenance schedules and enabling condition-based replacement cycles that reduce total track possession time.
REACH substance restrictions are phasing out chromate conversion coatings and certain epoxy hardeners in European track component manufacturing. Suppliers must reformulate surface treatments and adhesive systems to maintain corrosion resistance without restricted chemicals. Fastening system producers with in-house polymer chemistry capabilities are securing first-mover advantage in requalified product portfolios.
Lifecycle costing frameworks are displacing lowest-bid procurement for track renewals in Nordic and Alpine networks. Operators in Norway and Switzerland now specify total cost of ownership over 30-year horizons, weighting durability premiums against installation labor and possession windows. This behavioral shift elevates suppliers with verified fatigue test data and established field performance records.
Railway Track Fittings Market Segmentation
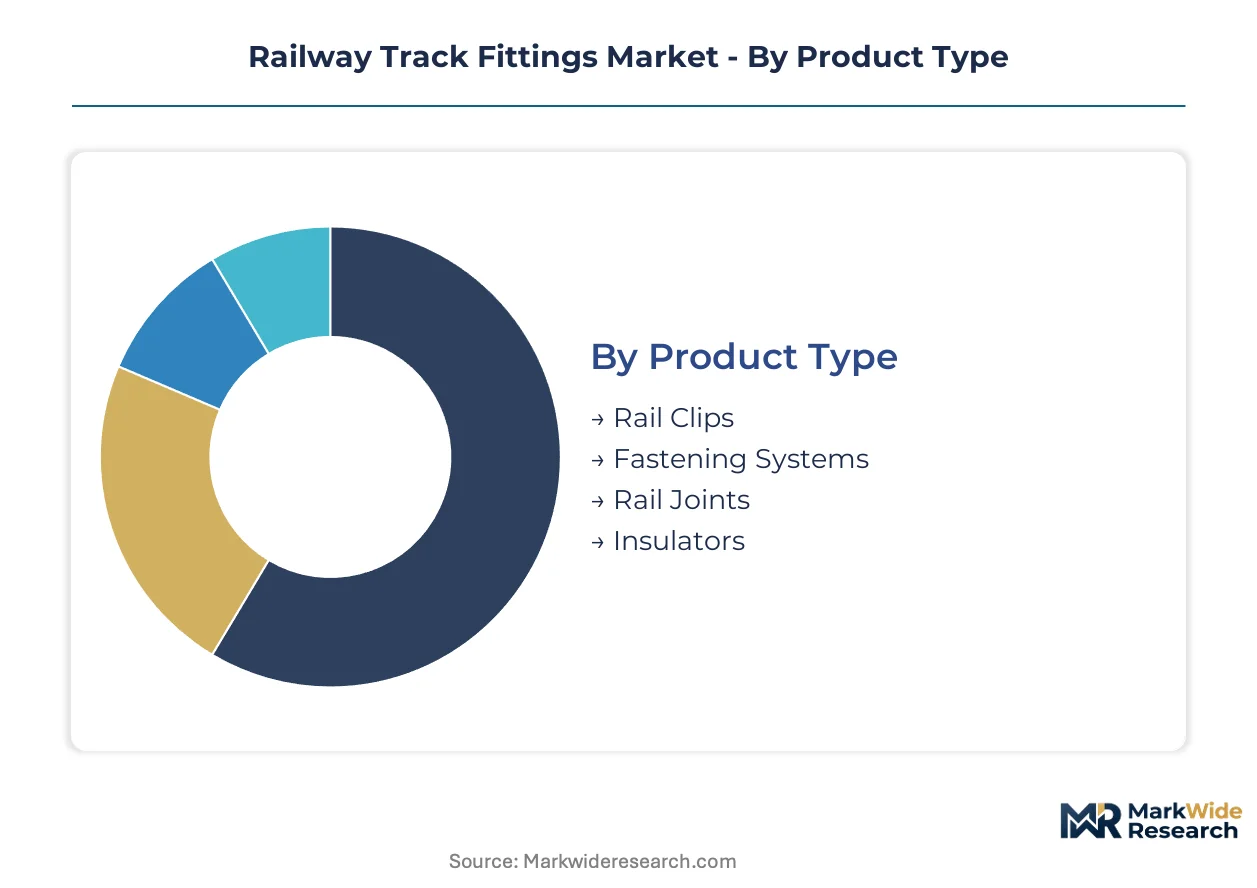
Track fitting procurement diverges sharply across operating regimes. Heavy-haul freight corridors prioritize fatigue-resistant steel hardware, while urban metro systems favor low-vibration composite assemblies. Understanding these segment boundaries clarifies where specification premiums apply and where commoditization pressures dominate.
Product Type:
Standalone fastening components serve discrete replacement cycles, whereas integrated systems demand synchronized procurement across multiple sub-assemblies.
- Fastening Systems:Integrated assemblies combining rail clips, baseplates, and elastic pads that maintain gauge under dynamic loading. Chinese and Indian high-speed corridors specify these for 30-year maintenance intervals, accepting 40% unit premiums to reduce track possession windows.
- Rail Clips:Spring steel components generating clamping force above 1,400 MPa tensile strength to resist rail creep. European networks concentrate demand here as ERA interoperability mandates force standardization across cross-border corridors.
- Rail Joints:Mechanical connections for rail continuity at expansion gaps or insulated sections. AGICO Group and regional foundries supply cast steel variants for African and Southeast Asian rehabilitation projects.
- Insulators:Dielectric barriers maintaining signaling circuit integrity. Thermoset polymer formulations are displacing porcelain in new installations.
Fastening systems lead volumes today; insulators are gaining share fastest.
Material:
Cost tier stratification separates specification-grade alloys from commodity substitutes, with carbon-accounting rules now inserting a third tier between them.
- Steel:High-tensile alloy grades dominate elastic rail clip and baseplate production. Spring steel price volatility tied to scrap metal and energy inputs compresses margins for producers without long-term raw material contracts.
- Composite:Fiber-reinforced thermosets and engineered elastomers enable glued insulated joints with superior signaling compatibility. EU Green Deal procurement criteria favor these for reduced lifecycle carbon footprints.
- Aluminum:Lightweight extrusions serve specialty fastening brackets in corrosion-sensitive coastal installations.
- Plastic:Injection-molded housings for cable protection and non-structural spacers in low-load applications.
Steel commands installed base volumes; composite exhibits the steepest expansion trajectory.
Application:
Speed rating determines fatigue specification severity, creating four distinct qualification regimes from urban metro to dedicated high-speed corridors.
- High-Speed Rail:Dedicated passenger lines above 250 km/h requiring aerodynamic stability and million-cycle fatigue resistance. Spain's AVE network and China's expanding NRA-supervised corridors concentrate premium demand here.
- Heavy Rail:Mixed-traffic and freight-dominant lines with axle loads exceeding 25 tonnes. Indian Railways and Russian Railways drive volume through continuous welded rail conversion programs.
- Metro:Urban rapid transit with tight curvature and vibration-sensitive tunnel environments. Composite pad and low-height fastening systems predominate.
- Light Rail:Street-running and semi-exclusive alignments with embedded track and surface-mounted fastening variants.
Heavy rail maintains installed base dominance; high-speed rail climbs fastest on value per kilometer metrics.
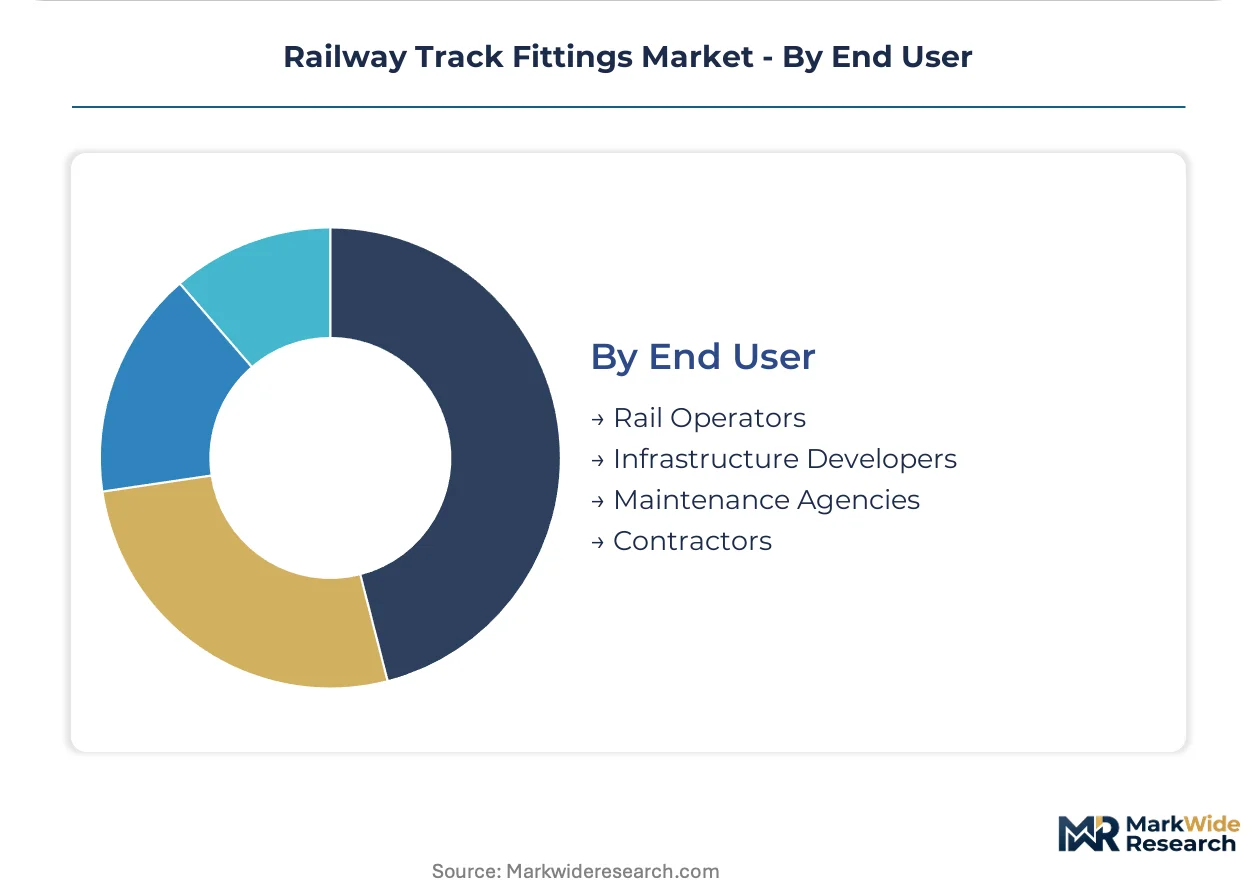
End User:
Procurement authority fragmentation splits demand between state operators with in-house engineering capabilities and project developers outsourcing full system integration.
- Rail Operators:National incumbents like Deutsche Bahn and SNCF Réseau specifying system-wide standards with 30-year lifecycle costing frameworks. These buyers leverage volume concentration to enforce supplier certification requirements.
- Infrastructure Developers:Greenfield project entities bundling track, electrification, and signaling through design-build contracts. Chinese state-owned enterprises and European joint ventures dominate this procurement channel.
- Maintenance Agencies:Specialized renewal contractors executing possession-window replacements on operational lines.
- Contractors:Civil engineering firms subcontracting track fitting supply to tier-2 specialists.
Rail operators lead procurement volumes today; infrastructure developers are expanding their share fastest through bundled greenfield awards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Railway track fitting manufacturing originated in 19th-century European steel centers, with Germany and Britain pioneering spring steel clip technologies. Contemporary demand concentrates in corridors where high-speed rail expansion and freight electrification programs are reshaping procurement volumes.
China
China's National Railway Administration supervises the world's largest high-speed track renewal program, with dedicated passenger lines exceeding 45,000 kilometers. Domestic content requirements mandate local sourcing thresholds above 70% for flagship corridor tenders. CRRC subsidiaries and Zhengzhou-based fabricators dominate supply chains serving the Beijing-Shanghai and Chengdu-Guiyang corridors.
Germany
Deutsche Bahn's 30-year lifecycle costing frameworks prioritize fastening systems with verified fatigue resistance data. The EU Green Deal's modal shift mandates are redirecting capital toward rail freight corridors through the Rhine-Alpine and Scandinavian-Mediterranean TEN-T networks. Vossloh AG anchors supply from integrated manufacturing footprints across Werdohl and La Rochelle.
India
Indian Railways converts continuous welded rail across 68,000 route kilometers, driving demand for cast steel rail joints and elastic clips. The Ministry of Railways imposes phased manufacturing program requirements that escalate local content from 50% to 75% on dedicated freight corridors. Foundry clusters in Jhansi and Bengaluru supply hardware for the Delhi-Mumbai and Ludhiana-Kolkata industrial freight routes.
Spain
Renfe's AVE network expansion concentrates premium demand for aerodynamic stability-compliant fastening systems. ADIF's procurement specifications align with ERA Technical Specifications for Interoperability, forcing cross-border certification compliance. Basque Country manufacturers supply integrated fastening assemblies for the Madrid-Barcelona and Mediterranean Corridor high-speed segments.
United States
Class I railroads execute continuous welded rail conversion across 140,000 route miles under Federal Railroad Administration Part 213 safety standards. Freight-dominant procurement prioritizes fatigue-resistant steel hardware for 32-tonne axle load corridors. Progress Rail and regional fabricators serve the Chicago hub and Powder River Basin heavy-haul networks from manufacturing positions in Illinois and Wyoming.
Railway Track Fittings Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and raw material contract security. The vendor base stratifies into three tiers: integrated fastening system suppliers with ERA approval portfolios, regional foundries serving rehabilitation markets, and specialty composite formulators. Consolidation pressures are intensifying as lifecycle costing frameworks favor suppliers with 30-year field performance records. Dominant competitive moves include backward integration into spring steel supply and strategic partnerships for sensor-embedded product development.
Within the integrated system tier, Vossloh AG and Pandrol Ltd. exemplify archetypes with European regulatory anchoring. AGICO Group occupies a position among volume-focused foundries supplying cast steel joints to Asian and African export corridors. These three entities represent distinct strategic postures: certification-led premium positioning, R&D-intensive elastomer specialization, and scale-driven emerging market penetration.
| Leading Market Players |
|---|
| Pandrol Ltd. |
| International Track Systems |
| AGICO Group |
| Progress Rail |
| KVT-Fastening |
| Harsco Corporation |
| ArcelorMittal Europe |
| Kingrail |
| Vossloh AG |
| Others |
Value Network & Pricing Analysis
Spring steel alloy costs cascade through Railway Track Fittings Market pricing tiers, with high-tensile grades above 1,400 MPa anchoring premium fastening system quotations while scrap metal volatility compresses margins for spot-market clip producers serving African rehabilitation corridors.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between national operators and integrated system suppliers, with price differentiation resting on ERA certification tier and verified fatigue test data rather than unit manufacturing cost. Three-tier pricing structure across premium, standard, and economy levels separates Vossloh-grade interoperability-compliant systems from regional foundry output and unbranded commodity clips. Cost compression in the economy tier is intensifying because Chinese state-owned enterprises are absorbing steel input volatility to maintain domestic content compliance. Maintenance agencies exhibit highest price sensitivity due to possession-window budget constraints, while high-speed rail developers prioritize lifecycle costing over upfront unit cost.
Supply Chain Analysis
Certified welder shortages in Germany's Ruhr industrial cluster and spring steel rolling capacity constraints in China's Henan province are forcing lead time extensions for glued insulated joint assemblies. Manufacturing gravity centers on Germany, China, and India, with raw material feeds drawing from Swedish specialty steel mills, domestic scrap recycling networks, and Korean elastomer compounders. Single-source vulnerability concentrates in spring steel supply where three European mills control specification-grade output. Distribution runs through operator-direct procurement for flagship corridors and tier-2 fabricator networks for rehabilitation projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Railway Track Fittings Market operates as a stable compounder where infrastructure renewal cycles and modal shift policy create predictable replacement demand regardless of macroeconomic cyclicality.
For Market Incumbents: Extend field performance databases to capture 30-year fatigue records that lifecycle costing frameworks now require, while deepening backward integration into spring steel supply to buffer scrap metal volatility. Domestic content requirements in India and China threaten exclusion from flagship corridor tenders unless local manufacturing footprints expand. For New Entrants and Emerging Players: The 40% unit premium gap between ERA-certified European systems and unbranded Asian foundry output creates entry space for mid-tier composite insulator specialists. African rail rehabilitation corridors offer lowest certification barriers, while sensor-embedded fastening pilot programs with Deutsche Bahn provide reference customer pathways. For Investors and Strategic Acquirers: Roll-up economics work for regional foundry clusters because lifecycle costing frameworks are consolidating procurement toward suppliers with multi-decade track records. Five-to-ten year viability hinges on CSRD-compliant environmental product declarations. Monitor EU Green Deal modal shift fund disbursement velocity as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spring Steel | Captive supply of 1,400 MPa alloy grades buffers scrap metal price volatility for clip manufacturers. |
| Sensor-Embedded Fastening Development | Micro-accelerometer integration with Deutsche Bahn pilot programs opens predictive maintenance product tier. |
| ERA Certification Investment | TSI approval portfolios unlock cross-border corridor procurement across Rhine-Alpine and Scandinavian-Mediterranean networks. |
| African Export Capacity Expansion | Addis Ababa-Djibouti and Lagos-Kano rehabilitation projects demand cast steel rail joints at volume scale. |
| REACH-Compliant Formulation Reformulation | Chromate-free surface treatments secure European market access under evolving chemical restrictions. |
Research Methodology
Direct dialogue with track maintenance directors, infrastructure procurement officers at national operators, fastening system R&D leads, and African rehabilitation project engineers grounded qualitative findings, cross-referenced against ERA technical specifications, FRA Part 213 safety standards, National Railway Administration procurement disclosures, and continuous welded rail conversion databases. Bottom-up unit economics triangulated with top-down infrastructure investment flows.
Segment-level outputs across product type, material grade, speed-rated application, and end-user procurement authority were generated across the analysis window, with expansion trajectories derived from modal shift policy intensity and corridor commissioning schedules. Spring steel price elasticity and domestic content threshold escalation served as primary demand shifters in the analytical framework.
Caveats apply where EU Green Deal fund disbursement delays or NRA localization requirement tightening could materially shift the outlook. Practitioners should monitor ERA interoperability certification backlog durations and glued insulated joint technician training pipeline capacity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Railway Sliding Bearing Market
Railway Transportation
High Speed Rail Coating Market
Railway Transportation
Urban Rail Transit Signaling Market
Railway Transportation
Rail Switch Point Heating System Market
Railway Transportation
Railway Radiator Market
Railway Transportation
Railway Li-Ion Battery Market
Railway Transportation
Global Autonomous Trains Market
Railway Transportation
Railway Traction Inverter Market
Railway Transportation
Railway Connectors Market
Railway Transportation
Train Transformer Market
Railway Transportation
Digital Railway Market
Railway Transportation
Urban Rail Transit Market
Railway Transportation
Rail Pads Market
Railway Transportation
Rail Fasteners Market
Railway Transportation
Composites in Passenger Rail Market
Railway Transportation
Canada Rail Freight Transport Market