
 Railway Sleepers Market | 2026-2036
Railway Sleepers Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Sleepers Market Analysis
Modular precast sleeper systems bundled with fastening kits and under-sleeper pads is hardening as the standard procurement configuration for large track renewals. Patil Group leverages integrated concrete casting and logistics networks across South Asia to dominate project bundling. Kirchdorfer Group anchors Central European supply through specialized pre-stressed concrete sleeper plants with captive aggregate sourcing.
A railway sleeper is a transverse support member placed beneath rail tracks to distribute wheel loads to the track bed, with concrete variants typically pre-tensioned to 900-1200 MPa and cast in steel molds to precise dimensional tolerances. Its primary function is to maintain rail gauge, absorb dynamic stresses, and transfer vertical and lateral forces to the ballast or slab foundation. Concrete sleepers command the largest installed base across heavy-haul and high-speed networks due to superior fatigue resistance and 50-year design life, while composite segments gain traction in corrosion-prone coastal and chemically aggressive environments where reduced lifecycle maintenance justifies premium positioning. Steel sleepers occupy specialized niches in sharp curves and constrained gauge applications where space and weight restrictions override material cost considerations.
The European Union's F-Gas Regulation and Construction Products Regulation (CPR) mandate embodied carbon disclosure and recyclability thresholds for infrastructure materials, compelling sleeper manufacturers to certify environmental product declarations. India's BIS certification for precast concrete sleepers and China's GB standards for high-speed rail components enforce dimensional and strength consistency that gates market participation. Stakeholders must monitor evolving green procurement criteria and alignment between national rail modernization budgets and domestic content requirements to calibrate capacity and certification investments.
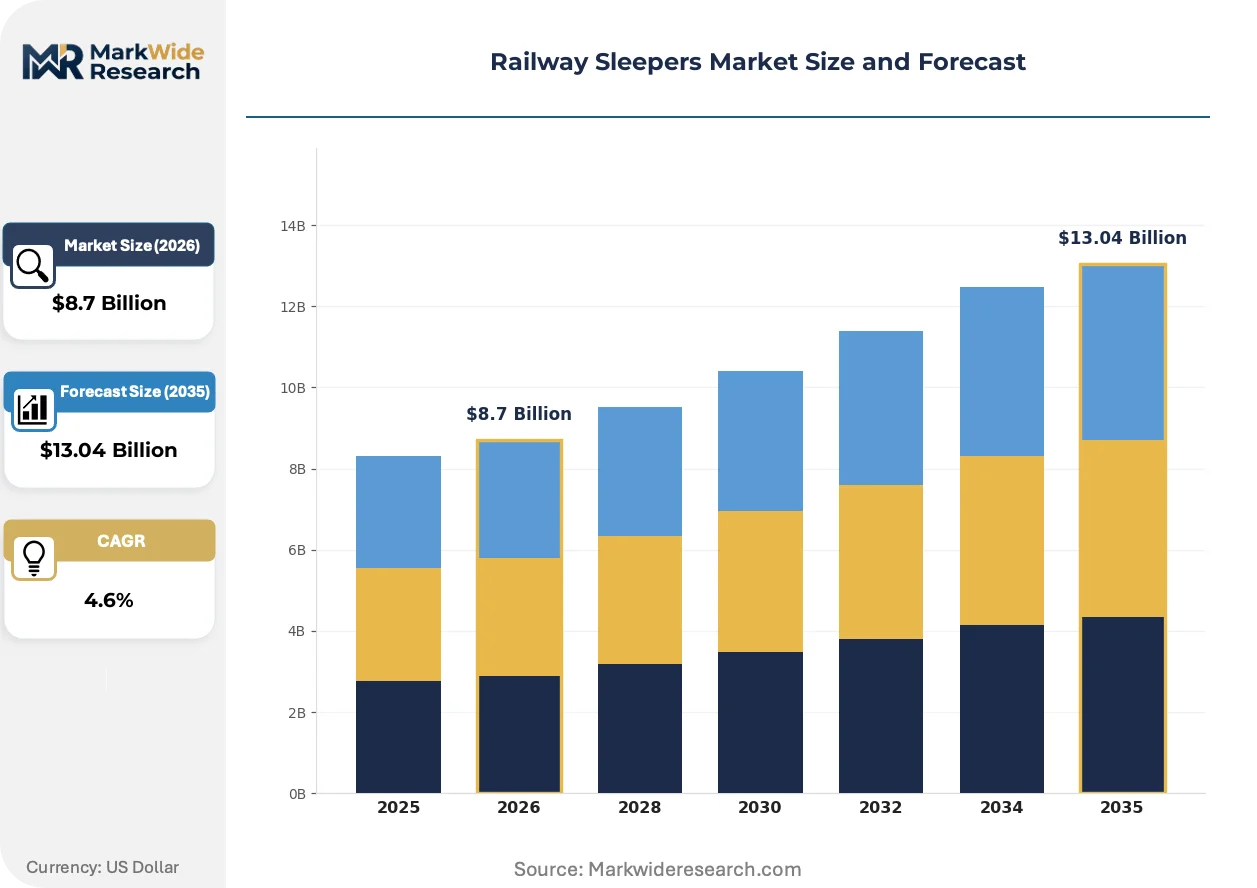
Market Dynamics
Heavy-haul corridors in Brazil and Australia are compressing sleeper replacement cycles from 40 years toward 25-year intervals, while India's PLI scheme for rail infrastructure components accelerates domestic concrete sleeper production capacity. This structural pressure on asset longevity is reshaping procurement volumes and manufacturer capacity planning across three continents simultaneously.
Growth Catalysts
- High-speed rail maintenance programs:China's GB standards for high-speed rail components mandate systematic sleeper replacement, generating sustained demand for pre-stressed concrete units with 900-1200 MPa tension ratings.
- F-Gas Regulation compliance:The European Union's embodied carbon disclosure requirements for infrastructure materials compel sleeper manufacturers to certify environmental product declarations, creating competitive differentiation for low-carbon precast systems.
- Composite material adoption:Coastal networks in chemically aggressive environments are specifying fiber-reinforced polymer sleepers to reduce lifecycle maintenance expenditure despite premium upfront positioning.
Market Restraints
- Cement price volatility:Input cost swings for Ordinary Portland Cement and high-grade aggregates compress margins for pre-stressed concrete sleeper producers operating on fixed-price rail contracts.
- Supply concentration risk:Central European precast capacity clusters around captive aggregate quarries, creating geographic vulnerability to localized logistics disruptions or energy price spikes.
- Steel sleeper substitution ceiling:Weight and space constraints in sharp curves limit concrete sleeper deployment, preserving niche demand for steel variants despite inferior fatigue performance.
Strategic Opportunities
- Modular bundling protocols:Large track renewal projects in Germany and Austria now specify integrated procurement of sleepers with fastening kits and under-sleeper pads, opening service-revenue streams for systems integrators.
- Corrosion-resistant coastal deployment:Australia's Pilbara iron ore rail corridors present untapped demand for composite sleepers in salt-laden environments where concrete spalling accelerates asset degradation.
- BIS certification acceleration:India's domestic content requirements for rail modernization budgets create protected market access for certified precast concrete sleeper manufacturers with localized casting infrastructure.
Industry Challenges
- Pre-tensioning technician scarcity:Specialized skills for 900-1200 MPa steel tendon tensioning in automated casting beds are concentrated among aging workforces in Central Europe and Japan.
- Multi-standard certification burden:Concurrent compliance with EU Construction Products Regulation, China's GB standards, and India's BIS protocols fragments quality assurance resources for exporters.
- Ballast-sleeper interface validation:Dynamic load transfer modeling between new sleeper geometries and existing track beds requires extended field testing before network approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Sleepers Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Wooden, Concrete, Composite, Steel Installation Method: Ballasted, Slab Track, Direct Fixation, Floating End User: Railway Operators, Construction Firms, Infrastructure Developers, Government Agencies Geographical Application: Urban Transit, High-Speed Rail, Freight Rail, Regional Rail |
| Companies Covered | Patil Group, Aveng Infraset, Abetong, Shandong High Speed Rail Equipment Material, China Railway Material Sleeper of Pingdingshan, Kirchdorfer Group, The Indian Hume Pipe, Trackwork Moll, Austrak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Sleepers Market Emerging Trajectories
Digital precasting workflows and alternative reinforcement materials are restructuring how sleeper manufacturers achieve dimensional precision and fatigue resistance. Three developments are altering competitive positioning.
Fiber-reinforced polymer composite sleepers are decentralizing supply chain geography for corrosion-critical installations. Mining operators in Western Australia's salt-flat corridors specify these units for 50-year design life without concrete spalling. The technology is decentralizing procurement authority from national rail agencies toward site-specific engineering contractors with localized composite molding capacity.
The EU's F-Gas Regulation and Construction Products Regulation now mandate recyclability thresholds and embodied carbon disclosure for infrastructure materials placed on European markets. Sleeper manufacturers must certify environmental product declarations through third-party verification to maintain eligibility for public procurement frameworks. German and Austrian rail infrastructure managers are prioritizing low-carbon precast suppliers in tender evaluations.
Integrated procurement of sleepers with elastic fastening systems and under-sleeper pads is displacing component-separated purchasing in large renewal contracts. European track engineering firms now specify bundled solutions to reduce interface liability and accelerate installation schedules. This pattern concentrates most visibly in Germany's Rhine-Alpine freight corridor modernization programs.
Railway Sleepers Market Segmentation
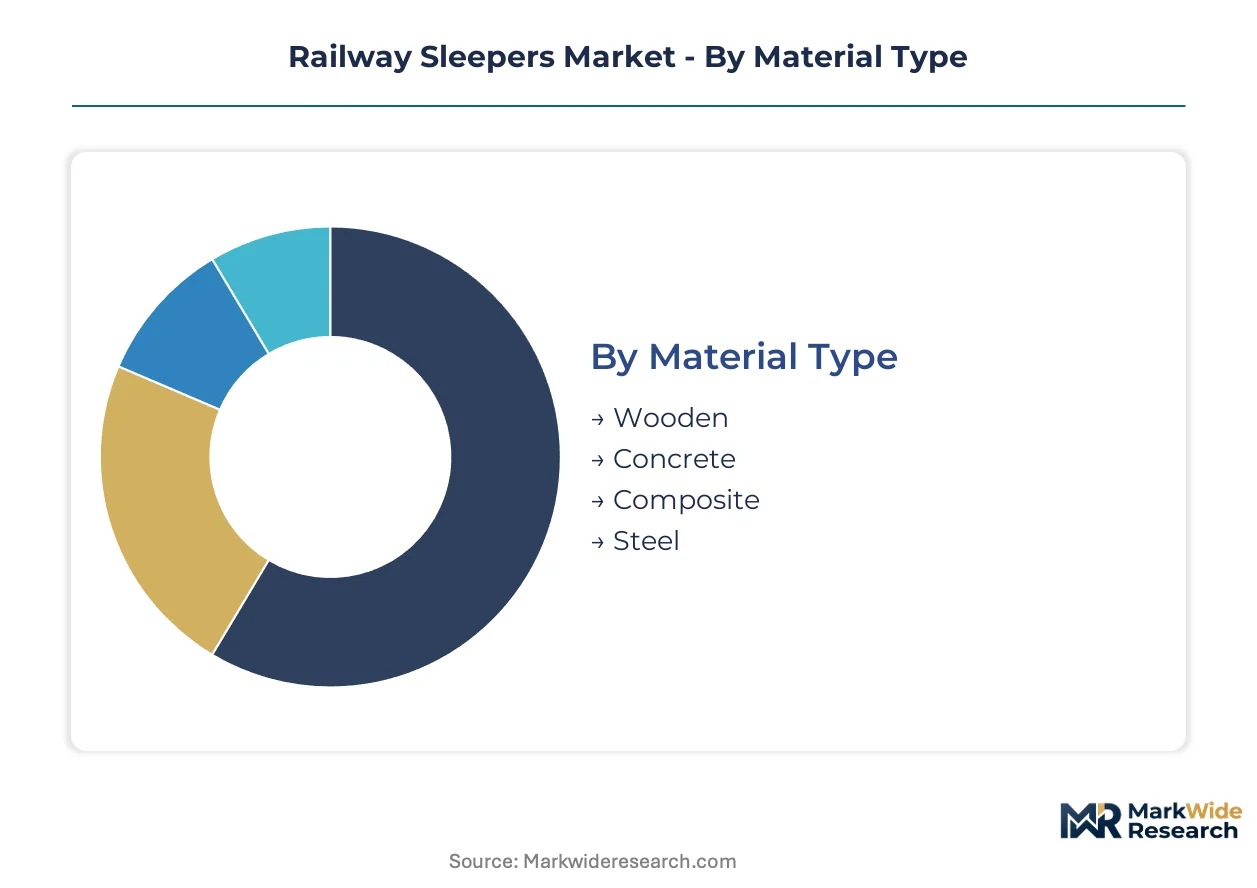
Railway sleeper procurement specifications diverge sharply across load-bearing requirements and environmental exposure. Material selection and installation geometry determine lifecycle cost trajectories for asset managers operating under divergent regulatory and climatic constraints.
Material Type:
Pre-tensioning specifications and corrosion resistance define the technology axis for material selection in heavy-haul and coastal deployments.
- Concrete:Pre-stressed units with 900-1200 MPa tendon ratings dominate heavy-haul corridors in Australia and Brazil where 50-year design life offsets higher capital outlay. India's PLI scheme accelerates domestic casting capacity for concrete variants.
- Composite:Fiber-reinforced polymer formulations resist salt-laden degradation in Western Australia's Pilbara iron ore networks. Site-specific engineering contractors with localized molding capacity are displacing centralized procurement for these corrosion-critical installations.
- Wooden:Hardwood timbers persist in heritage track preservation and noise-sensitive urban corridors where elasticity dampens vibration transmission.
- Steel:Rolled steel profiles occupy sharp curves and constrained gauge applications where weight and dimensional restrictions override fatigue performance limitations.
Mature deployment sits with Concrete. Newer deployment is concentrated in Composite.
Installation Method:
Foundation geometry and load transfer mechanics shape procurement bundling patterns across renewal and greenfield projects.
- Ballasted:Crushed stone bed systems with elastic fastening kits remain standard for heavy-haul freight in Brazil and Australia. Modular bundling with under-sleeper pads now dominates large renewal contracts in Germany's Rhine-Alpine corridor.
- Slab Track:Continuous concrete foundations eliminate ballast maintenance for high-speed networks adhering to China's GB standards. Systematic sleeper replacement programs generate sustained demand for pre-stressed units in this configuration.
- Direct Fixation:Rail-to-sleeper mechanical anchoring suits constrained-geometry tunnels and bridge decks where ballast depth is impractical.
- Floating:Elastic isolation layers decouple track from substrate in vibration-sensitive urban transit installations.
Ballasted systems retain the largest installed base. Slab Track configurations are climbing the fastest among high-speed rail modernization programs.
End User:
Procurement authority concentration varies with asset ownership structures and public-private contracting models.
- Railway Operators:State-owned incumbents in China and India drive volume through systematic maintenance schedules and domestic content mandates. BIS certification requirements protect localized casting infrastructure for these buyers.
- Infrastructure Developers:Greenfield project sponsors in Australia's mining corridors specify composite sleepers for salt-flat environments where lifecycle maintenance reduction justifies premium positioning.
- Construction Firms:Track engineering contractors in Germany and Austria increasingly specify bundled sleeper-fastening-pad solutions to compress installation schedules and reduce interface liability.
- Government Agencies:National rail modernization budgets in India enforce PLI-aligned procurement that gates market access for certified domestic manufacturers.
Railway Operators command the largest procurement volumes. Infrastructure Developers are gaining share fastest in resource-corridor expansions.
Geographical Application:
Speed regime and traffic density dictate sleeper specification intensity and replacement cycle compression.
- Freight Rail:Heavy-haul corridors in Brazil and Australia compress replacement cycles from 40 years toward 25-year intervals under extreme axle loads. Concrete sleepers with enhanced fatigue resistance dominate these specifications.
- High-Speed Rail:China's maintenance programs generate sustained demand for dimensionally precise pre-stressed units meeting GB standards for slab track foundations. Systematic replacement creates predictable procurement windows.
- Urban Transit:Noise and vibration constraints in European cities favor floating slab installations with elastic fastening systems.
- Regional Rail:Mixed-traffic lines balance capital constraints against maintenance burden through tiered material selection.
Freight Rail maintains the deepest installed base. High-Speed Rail represents the steepest expansion trajectory among maintenance-driven demand segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Concrete sleeper production clusters in Central Europe and South Asia while consumption concentrates in heavy-haul freight corridors across Brazil and Australia. China's high-speed rail maintenance programs absorb significant pre-stressed concrete volumes. India's PLI scheme redirects import dependency toward domestic casting infrastructure.
Germany
Rhine-Alpine freight corridor modernization drives bundled procurement of sleepers with fastening kits and under-sleeper pads. The EU's F-Gas Regulation and Construction Products Regulation mandate embodied carbon disclosure for infrastructure materials. Kirchdorfer Group anchors Central European supply through specialized pre-stressed concrete sleeper plants with captive aggregate sourcing in Austria and southern Germany.
China
Systematic sleeper replacement programs for high-speed rail networks generate sustained demand for pre-stressed concrete units meeting GB standards. The Ministry of Industry and Information Technology enforces dimensional and strength consistency through national standards that gate market participation. Shandong High Speed Rail Equipment Material and China Railway Material Sleeper of Pingdingshan represent state-linked production capacity concentrated in northern industrial provinces.
India
Rail modernization budgets under the PLI scheme for rail infrastructure components accelerate domestic concrete sleeper production capacity. BIS certification for precast concrete sleepers enforces quality thresholds that protect localized casting infrastructure. Patil Group leverages integrated concrete casting and logistics networks across South Asia to dominate project bundling for national track renewal programs.
Australia
Heavy-haul iron ore corridors in the Pilbara region compress sleeper replacement cycles from 40 years toward 25-year intervals under extreme axle loads. Salt-laden coastal environments generate specification demand for corrosion-resistant composite alternatives. Austrak and specialized engineering contractors with localized composite molding capacity displace centralized procurement authority for these degradation-critical installations.
Brazil
Carajás and other heavy-haul freight corridors expand maintenance volumes as traffic density accelerates asset fatigue. The national rail regulator enforces safety standards for track components that align with international heavy-haul protocols. Aveng Infraset anchors supply capacity for South American project bundling through regional precast infrastructure.
Railway Sleepers Market Vendor Landscape
The competitive structure tilts toward integrated precast specialists with captive raw material access and project bundling capability. Tier-one positions concentrate among manufacturers combining automated steel tendon tensioning with logistics networks spanning multiple rail corridors. Three archetypes dominate: integrated concrete casters with quarry ownership, composite molding specialists for corrosion-critical niches, and state-linked producers serving domestic high-speed rail programs. Capacity expansion and modular bundling protocols constitute the dominant competitive moves, with manufacturers adding fastening kit integration and under-sleeper pad procurement to core sleeper offerings.
Within the integrated precast tier, Patil Group and Kirchdorfer Group exemplify contrasting geographic anchoring strategies—South Asian project bundling versus Central European quarry-captive production. Trackwork Moll occupies a position among specialized fastening and track component integrators. Shandong High Speed Rail Equipment Material represents state-capital-linked production scale serving systematic replacement demand under China's GB standards regime. These three anchors illustrate how certification alignment with national procurement frameworks determines market access more than pure manufacturing scale.
| Leading Market Players |
|---|
| Patil Group |
| Aveng Infraset |
| Abetong |
| Shandong High Speed Rail Equipment Material |
| China Railway Material Sleeper of Pingdingshan |
| Kirchdorfer Group |
| The Indian Hume Pipe |
| Trackwork Moll |
| Austrak |
| Others |
Supply Flow & Price Mechanics
Captive aggregate sourcing in Central Europe and South Asia anchors both supply security and pricing power for pre-stressed concrete sleeper manufacturers. Quarry ownership by Kirchdorfer Group and Patil Group insulates production costs from cement price volatility while enabling fixed-price contract bidding that smaller casters cannot match.
Pricing Analysis
Margin tightening in standard-grade concrete sleepers reflects fixed-price rail contracts confronting Ordinary Portland Cement cost swings. Three-tier pricing structure across premium-certified, standard-compliant, and economy-grade levels separates suppliers by BIS and GB certification attainment. Pricing pressure accelerates in ballasted track segments as Indian PLI scheme beneficiaries expand casting capacity. State-owned railway operators in China and India exhibit lowest price sensitivity due to domestic content mandates, while Australian mining contractors negotiate hardest on lifecycle cost metrics.
Supply Chain Analysis
India's domestic content requirements under the PLI scheme and China's GB standards enforcement are redirecting sourcing toward localized precast infrastructure. Production gravity centers on Germany, Austria, India, and China, with captive limestone quarries feeding Central European plants. Supply chains draw from high-grade aggregate deposits, pre-tensioning steel tendons, and synthetic fiber reinforcements. Single-source vulnerability concentrates in specialized 900-1200 MPa tensioning equipment from aging Japanese and European workforces. Distribution runs through project-bundled procurement with fastening kit and under-sleeper pad integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated precast specialists with quarry ownership and certification alignment. Cement price volatility and pre-tensioning technician scarcity are forcing sub-scale casters toward acquisition or exit.
For Market Incumbents: Hedge against input cost volatility through backward integration into captive aggregate quarries and long-term steel tendon supply agreements. Expand certification scope to cover concurrent BIS, GB, and EU Construction Products Regulation compliance, reducing exporter quality assurance fragmentation. Prioritize modular bundling capabilities integrating fastening systems and under-sleeper pads to capture service-revenue streams in German and Austrian renewal contracts. For New Entrants and Emerging Players: Composite molding technology for corrosion-critical installations offers the most penetrable wedge against entrenched concrete specialists. Target Australia's Pilbara iron ore corridors and other salt-laden coastal environments where fiber-reinforced polymer sleepers command premium positioning against concrete spalling. Pursue site-specific engineering contractor relationships rather than national rail agency channels to bypass incumbent procurement lock-in. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap precast specialists with regional quarry access and pending certification completion. Five-to-ten-year viability favors manufacturers with demonstrated project bundling execution and captive raw material positions. Monitor pre-tensioning technician training pipeline expansion as inflection indicator for capacity scalability constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Aggregate Quarry Acquisition | Secures limestone supply for Kirchdorfer Group and Patil Group against cement price volatility. |
| Multi-Standard Certification Investment | Enables market access across India's BIS, China's GB, and EU Construction Products Regulation regimes. |
| Modular Bundling Capability Buildout | Captures fastening kit and under-sleeper pad revenue in Germany's Rhine-Alpine corridor renewals. |
| Composite Molding Capacity Expansion | Addresses corrosion-critical demand in Western Australia's Pilbara salt-flat rail networks. |
| Pre-Tensioning Technician Training Programs | Alleviates workforce scarcity constraining 900-1200 MPa steel tendon production scale-up. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with track engineering contractors, rail infrastructure procurement managers, precast plant operations directors, and composite materials R&D leads combined with secondary validation from BIS certification databases, EU Construction Products Regulation declarations, and China Ministry of Industry and Information Technology standards filings. Bottom-up casting capacity estimates and top-down rail modernization budget allocations were triangulated to derive market sizing.
Granularity-level modeling addressed material type, installation method, end-user procurement authority, and geographical application across the projection horizon. Concrete, composite, wooden, and steel sleeper segments were modeled separately with pre-tensioning specifications and corrosion resistance attributes. CAGRs were derived from replacement cycle compression analysis and domestic content mandate implementation timelines. Heavy-haul axle load trajectories and high-speed rail maintenance program schedules served as volume drivers.
Several conditions sit outside the modeled scope, including geopolitical disruption to Central European energy supply, abrupt shifts in F-Gas Regulation enforcement stringency, and unanticipated composite material failure rates in field deployment. Forecasts reflect assumptions regarding PLI scheme continuation and GB standards stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Global Railcar Leasing Market
Railway Transportation
Railway Control Stands Market
Railway Transportation
Railway Connectors Market
Railway Transportation
Overhead Catenary System Market
Railway Transportation
Railway Air Conditioning System Market
Railway Transportation
Railway Roof Switches Market
Railway Transportation
Canada Rail Freight Transport Market
Railway Transportation
Global Autonomous Trains Market
Railway Transportation
China-Europe Rail Freight Transport Market
Railway Transportation
Japan Rail Freight Transport Market
Railway Transportation
Rail Switch Point Heating System Market
Railway Transportation
Poland Rail Freight Transport Market
Railway Transportation
Railway Station Lighting Market
Railway Transportation
Railcar Spill Containment Materials Market
Railway Transportation
Railway Traction Inverter Market
Railway Transportation
Global Railway Wiring Harness Market