
 Railway After-Cooler Market | 2026-2036
Railway After-Cooler Market Size, Share, and Industry Trends Forecast 2026-2036
Railway After-Cooler Market Analytics
Asian foundry capacity for aluminum heat exchanger cores is rebalancing toward railway-certified production lines. Luvata leverages its copper fabrication expertise to dominate traction motor cooling supply in European rail networks. Knorr-Bremse AG anchors its position through captive brake system integration with after-cooler modules. Wabtec Corporation competes aggressively in the North American freight retrofit segment.
A railway after-cooler is a heat exchange device that reduces compressed air or charge air temperature between turbocharger stages or prior to engine intake, typically constructed with aluminum fin-and-tube cores rated for vibration resistance up to 5-2000 Hz and pressure cycles exceeding 10 bar in locomotive duty. Its primary purpose is protecting engine components from thermal degradation while maintaining combustion efficiency under variable load profiles. Air cooled systems occupy the largest installed base across legacy diesel fleets, though water cooled architectures are displacing legacy designs in high-speed train applications where space constraints and thermal density requirements intensify. Maintenance providers represent a concentrated margin pool as fleet operators extend asset life cycles and outsource thermal system overhauls.
The EPA governs locomotive emissions tiers in the United States, while the EU Green Deal and F-Gas Regulation shape thermal system refrigerant transitions across European rail networks. China's MIIT enforces GB standards for rolling stock component certification, creating divergent compliance pathways for multinational suppliers. Stakeholders must monitor how regional decarbonization timelines redefine cooling load specifications as hybrid and hydrogen traction architectures proliferate.
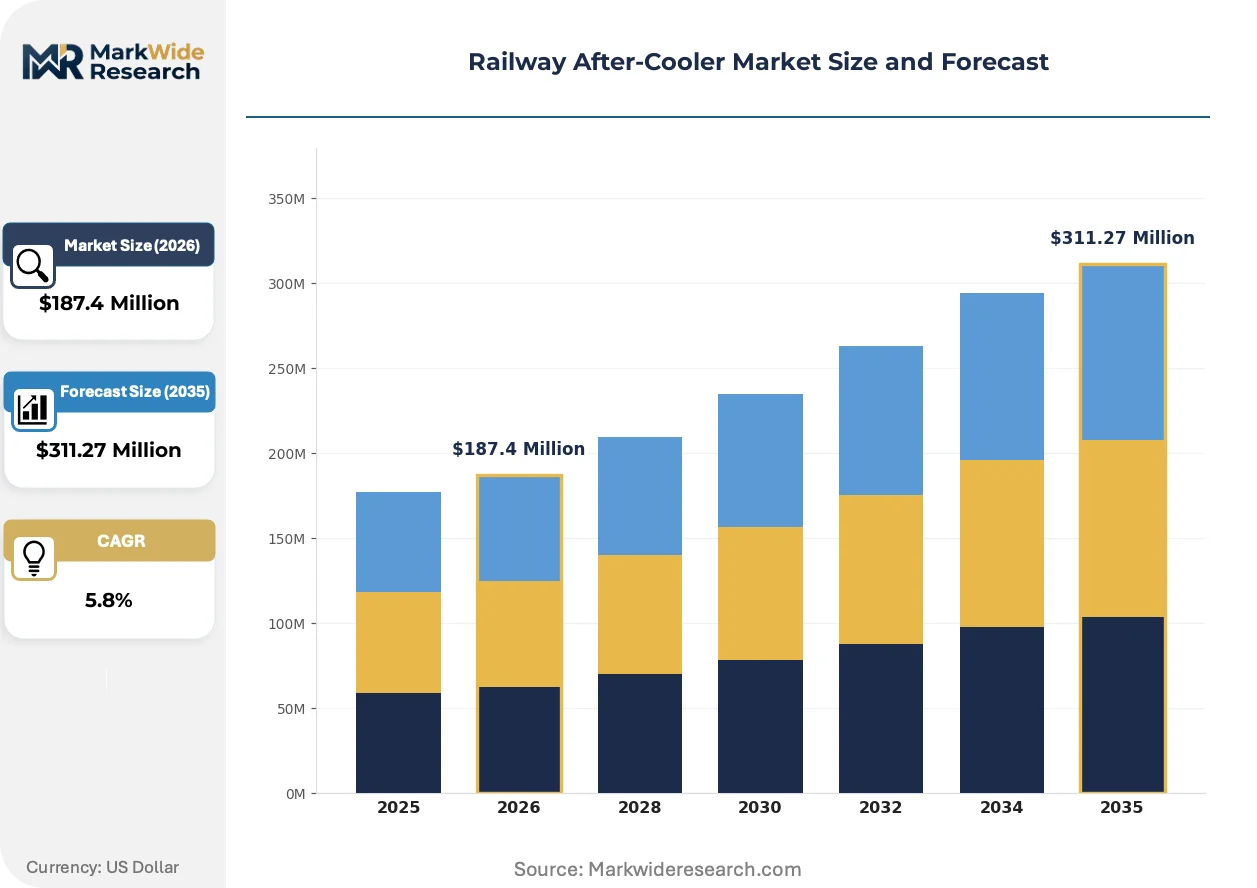
Market Dynamics
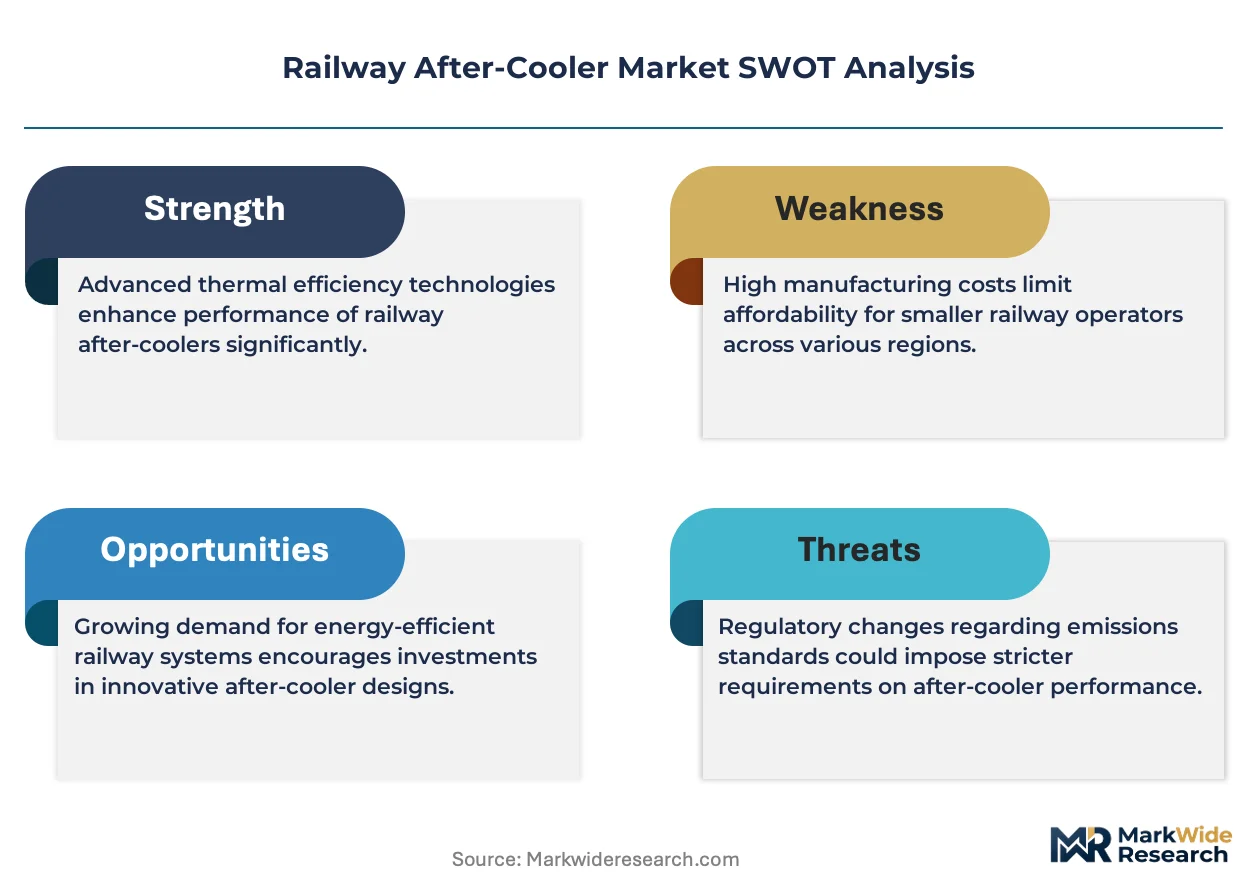
EPA Tier 4 and EU Stage V emissions standards are compressing thermal management margins for diesel-electric locomotives, forcing foundries to requalify aluminum heat exchanger production lines for railway-certified duty cycles.
Growth Catalysts
- Freight Fleet Modernization:North American freight operators are expanding locomotive overhaul programs that mandate after-cooler replacement as part of engine emissions compliance packages.
- EU Green Deal Implementation:The F-Gas Regulation is accelerating refrigerant transitions across European rail networks, requiring upgraded thermal system architectures in retrofit applications.
- GB Standards Certification:China's MIIT enforcement of rolling stock component certification is creating captive replacement demand as domestic suppliers absorb multinational aftermarket share.
Market Restraints
- Aluminum Price Volatility:Heat exchanger core fabrication depends on primary aluminum ingot costs that swing with LME trading patterns and Chinese smelter output curbs.
- Foundry Concentration Risk:Railway-certified aluminum casting capacity clusters in Zhejiang province foundries, creating single-geography supply vulnerability for European and North American OEMs.
- Copper Substitution Ceiling:Traction motor cooling specifications resist full aluminum conversion due to thermal conductivity requirements, limiting material cost reduction pathways.
Strategic Opportunities
- Hydrogen Traction Architectures:Fuel cell locomotive prototypes in Germany and Japan require novel charge air cooling configurations that eliminate legacy turbocharger staging.
- Maintenance Provider Consolidation:Third-party thermal system overhauls are capturing outsourced lifecycle extension contracts from freight operators compressing capex timelines.
- Water-Cooled Design Migration:High-speed train OEMs in France and Japan are specifying liquid-cooled after-coolers to resolve packaging constraints in underfloor equipment bays.
Industry Challenges
- Vibration Testing Bottlenecks:Railway certification requires 5-2000 Hz sinusoidal testing that exhausts limited third-party laboratory capacity in Germany and Japan.
- Legacy Fleet Integration:Pre-Tier 4 locomotive architectures lack sensor infrastructure for predictive thermal monitoring, complicating condition-based maintenance rollout.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway After-Cooler Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Cooled, Water Cooled, Oil Cooled, Gas Cooled End User: Freight Operators, Passenger Operators, OEMs, Maintenance Providers Application: Locomotives, High-Speed Trains, Light Rail, Metro Systems Technology: Standard, Advanced, Hybrid, Others |
| Companies Covered | Luvata, Sanden Holdings, Knorr-Bremse AG, CRRC Corporation Limited, Siemens Mobility, Alstom SA, Wabtec Corporation, Mitsubishi Heavy Industries Ltd., Liebherr-Transportation Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway After-Cooler Market Evolving Landscape
Additive manufacturing of aluminum fin structures is compressing prototype-to-production timelines for heat exchanger cores, enabling geometry optimization that was previously uneconomical at railway production volumes.
Topology-optimized aluminum lattices produced via laser powder bed fusion are rewriting thermal density benchmarks for compact after-cooler designs. European high-speed train OEMs are adopting these cores for underfloor installations where space constraints previously forced water-cooled alternatives. The technology is compressing the performance gap between air-cooled and liquid-cooled architectures in premium applications.
The EU F-Gas Regulation is mandating refrigerant phase-down schedules that cascade into auxiliary cooling system redesigns. Rolling stock thermal packages must now accommodate lower-GWP working fluids with altered thermodynamic properties. German and French fleet operators are absorbing retrofit costs earlier than regulatory deadlines to align with infrastructure renewal windows.
Freight operators are unbundling thermal system maintenance from locomotive overhaul contracts and awarding standalone agreements to specialized providers. This procurement fragmentation is displacing OEM-captive service models in North American Class I railroads. The pattern is most visible in Union Pacific and BNSF territory where asset life extension programs concentrate aftermarket demand.
Railway After-Cooler Market Segmentation
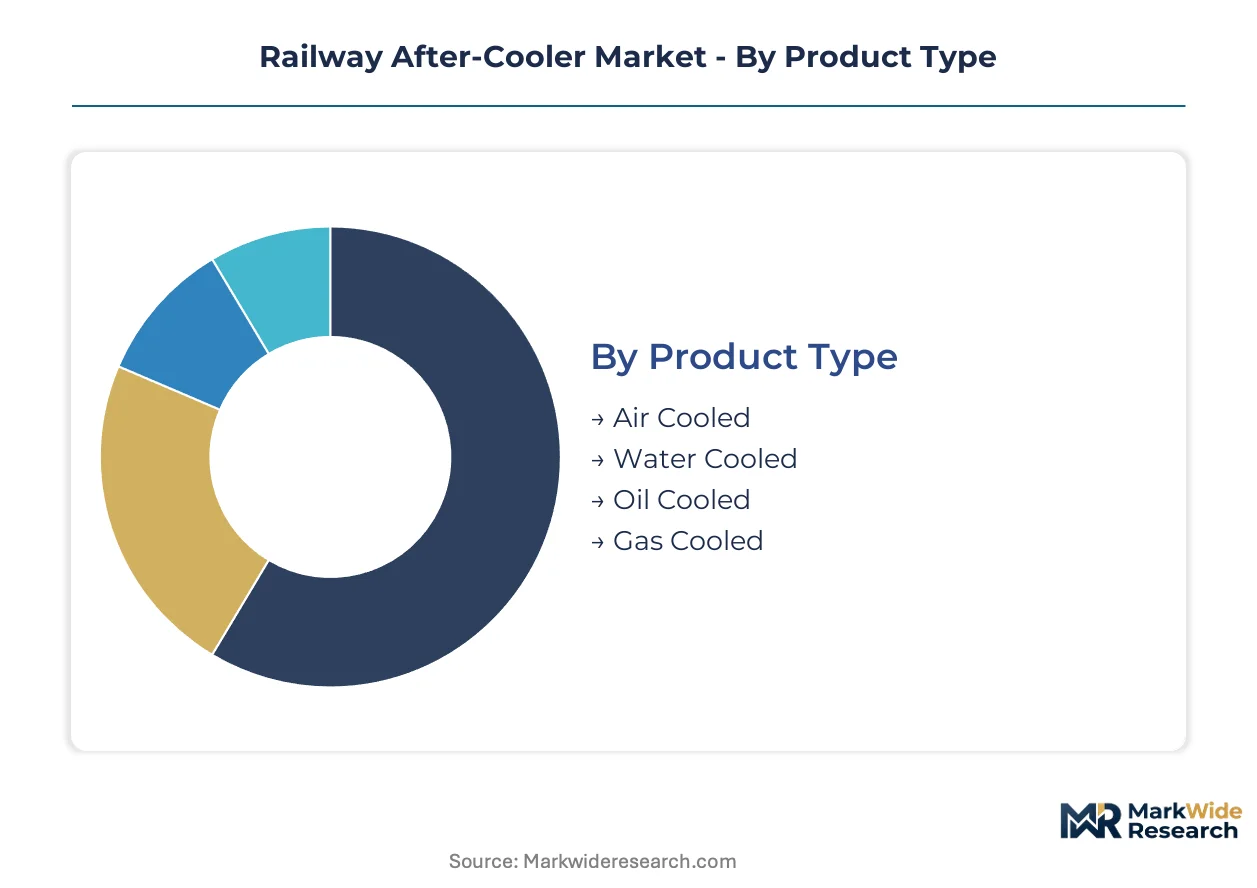
Railway after-cooler procurement splits sharply between retrofit replacement cycles and new-build specifications, with divergent technical requirements across each axis. Fleet operators prioritize certification compliance and lifecycle cost, while OEMs optimize for packaging density and thermal performance envelopes.
Product Type:
Buyers select cooling architectures based on thermal load density, available envelope space, and legacy infrastructure compatibility.
- Air Cooled:Aluminum fin-and-tube cores dominate legacy diesel-electric locomotive fleets across North American freight corridors. Deutsche Bahn's infrastructure renewal programs in Germany are absorbing the largest aftermarket replacement volumes for these units as Tier 4 compliance deadlines approach.
- Water Cooled:Compact shell-and-tube or plate heat exchanger designs resolve underfloor space constraints in high-speed train applications. French and Japanese OEMs are specifying liquid-cooled architectures for new-build contracts where thermal density requirements exceed 500 kW/m³.
- Oil Cooled:Specialized configurations serve auxiliary power unit cooling in hybrid locomotive prototypes.
- Gas Cooled:Emerging designs for hydrogen fuel cell traction systems eliminate traditional coolant circuits.
Volume sits with air-cooled systems; growth tilts toward water-cooled architectures.
End User:
Procurement authority is fragmenting as fleet operators unbundle thermal system maintenance from integrated overhaul contracts.
- Freight Operators:North American Class I railroads including Union Pacific and BNSF are driving aftermarket demand through asset life extension programs that mandate after-cooler replacement. These operators concentrate procurement in standalone thermal system agreements rather than OEM-captive service models.
- Maintenance Providers:Third-party specialists are capturing outsourced lifecycle extension contracts as freight operators compress capex timelines. German and French maintenance networks are consolidating thermal system overhaul capabilities to serve fragmented fleet operator demand.
- Passenger Operators:State-owned networks in China and Japan specify new-build cooling packages aligned with domestic certification requirements.
- OEMs:Locomotive manufacturers integrate after-cooler selection into platform engineering decisions early in design cycles.
Procurement authority is shifting from OEMs to independent maintenance providers; passenger operator specifications are expanding most quickly in Asia-Pacific markets.
Application:
Thermal load profiles and duty cycle intensity determine cooling architecture selection across rolling stock categories.
- Locomotives:Diesel-electric units in heavy-haul freight service impose the most severe thermal cycling demands, with charge air temperatures exceeding 200°C between turbocharger stages. EPA Tier 4 and EU Stage V compliance packages are forcing foundry requalification for aluminum heat exchanger cores rated to 10 bar pressure cycles.
- High-Speed Trains:Traction motor cooling requirements in 300+ km/h operation favor water-cooled after-cooler designs with topology-optimized aluminum lattices. Japanese Shinkansen and French TGV fleets are adopting additive-manufactured fin structures to compress underfloor packaging envelopes.
- Light Rail:Tram and streetcar applications specify compact air-cooled units with reduced vibration resistance requirements.
- Metro Systems:Underground operation drives corrosion-resistant coating specifications for heat exchanger cores exposed to tunnel humidity.
Locomotive applications anchor current volume; high-speed train specifications are gaining share fastest as European and Asian networks expand premium service corridors.
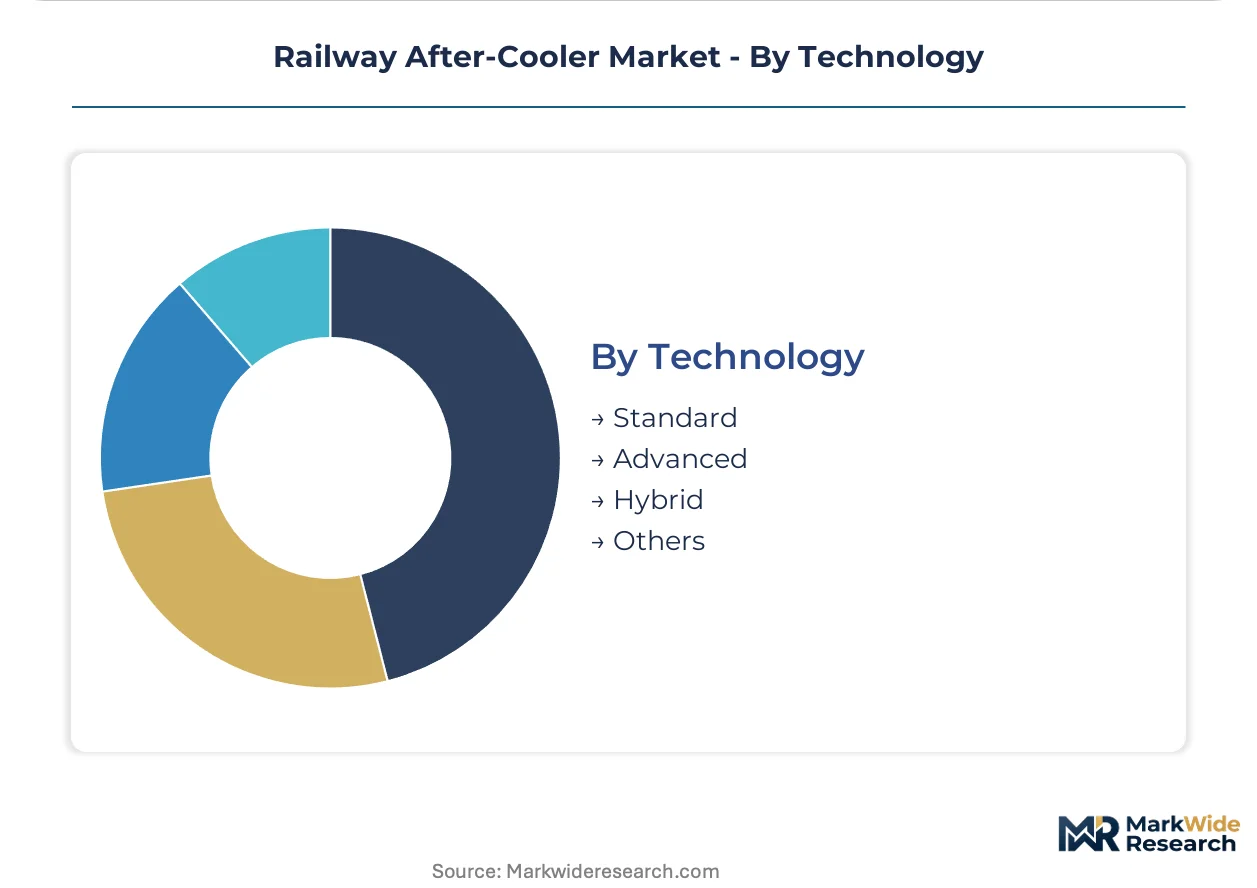
Technology:
Technology tier selection reflects the tradeoff between certification cost, performance headroom, and platform lifecycle expectations.
- Standard:Conventional aluminum fin-and-tube designs serve pre-Tier 4 locomotive fleets with established supply chains. These units lack sensor infrastructure for predictive thermal monitoring, complicating condition-based maintenance rollout in legacy North American freight assets.
- Advanced:Additive-manufactured aluminum lattice structures and optimized fin geometries are rewriting thermal density benchmarks. European high-speed train OEMs are qualifying these cores for underfloor installations where space constraints previously forced liquid-cooled alternatives.
- Hybrid:Dual-mode cooling architectures accommodate variable thermal loads in dual-fuel and battery-tender locomotive prototypes.
- Others:Experimental configurations including phase-change materials and microchannel designs remain in field trial phases.
Standard technology holds installed base dominance; advanced designs are climbing the fastest as certification bottlenecks for additive-manufactured cores resolve in Germany and Japan.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum ingot from Zhejiang province foundries supplies heat exchanger cores for diesel-electric locomotive fleets across three continents. Railway-certified casting capacity clusters along China's eastern seaboard, creating supply dependencies that reshape procurement geography for European and North American OEMs.
United States
Union Pacific and BNSF Railway drive aftermarket demand through asset life extension programs that mandate after-cooler replacement. EPA Tier 4 emissions compliance deadlines compress thermal system overhaul timelines. Chicago-area maintenance depots concentrate third-party thermal service providers capturing unbundled procurement contracts.
Germany
Deutsche Bahn's infrastructure renewal programs absorb the largest European aftermarket replacement volumes for air-cooled aluminum units. EU F-Gas Regulation mandates refrigerant transitions that cascade into auxiliary cooling system redesigns. Stuttgart industrial corridor hosts vibration testing laboratories certifying cores to 5-2000 Hz railway standards.
China
MIIT enforcement of GB standards for rolling stock component certification creates captive replacement demand. Domestic suppliers absorb multinational aftermarket share through state-directed procurement. Zhejiang province foundries requalify production lines for railway-certified aluminum heat exchanger duty cycles.
Japan
Shinkansen fleet operators specify additive-manufactured aluminum lattice cores for underfloor thermal packages. METI supports hydrogen fuel cell locomotive prototypes requiring novel charge air cooling configurations. Nagoya industrial cluster anchors topology-optimized heat exchanger development for 300+ km/h applications.
France
SNCF aligns thermal system retrofits with infrastructure renewal windows ahead of EU regulatory deadlines. TGV fleet expansion drives demand for liquid-cooled after-coolers resolving underfloor space constraints. Lyon-Grenoble industrial corridor concentrates high-speed train thermal engineering expertise.
Railway After-Cooler Market Competitive Landscape
Global majors compete with regional champions across certification pathways and captive integration strategies. Market structure tilts toward consolidated supply at the foundry level, with fragmented procurement authority shifting from OEMs to independent maintenance networks. Two archetypes dominate: vertically integrated rolling stock manufacturers with captive thermal divisions, and specialized heat exchanger fabricators serving aftermarket replacement cycles. Competitive moves concentrate on foundry capacity expansion in railway-certified aluminum casting and strategic partnerships bridging European design expertise with Asian manufacturing scale.
Among diversified industrial conglomerates, Mitsubishi Heavy Industries Ltd. and Siemens Mobility exemplify platform-integrated thermal system suppliers embedding after-cooler selection early in locomotive engineering cycles. Knorr-Bremse AG occupies a position within the brake-thermal integration archetype, leveraging captive system bundling to anchor aftermarket service relationships. These three represent contrasting strategic postures: scale-driven manufacturing breadth, rail-specific platform control, and subsystem integration specialization.
| Leading Market Players |
|---|
| Luvata |
| Sanden Holdings |
| Knorr-Bremse AG |
| CRRC Corporation Limited |
| Siemens Mobility |
| Alstom SA |
| Wabtec Corporation |
| Mitsubishi Heavy Industries Ltd. |
| Liebherr-Transportation Systems |
| Others |
Value Network & Pricing Analysis
Additive manufacturing adoption for aluminum lattice fin structures is compressing prototype economics while redistributing foundry bargaining power toward certified production lines. This production-method transition simultaneously elevates qualification costs for new suppliers and concentrates pricing leverage with railway-certified casting operations in Germany and Japan.
Pricing Analysis
Warranty and service-bundling arrangements separate OEM-captive contracts from standalone maintenance provider agreements. Contract-based long-term offtake dominates fleet operator procurement, with price differentiation driven by certification tier and volume scale. Cost compression in standard aluminum fin-and-tube units is intensifying because foundries in Zhejiang province absorb domestic demand spikes. Third-party maintenance providers exhibit highest price sensitivity; high-speed train OEMs in France and Japan demonstrate lowest sensitivity due to performance-critical specifications.
Supply Chain Analysis
China's MIIT enforcement of GB standards and domestic-content requirements is reshaping sourcing patterns for multinational suppliers. Railway-certified aluminum heat exchanger production concentrates in China, Germany, and Japan. Raw material flows draw from primary aluminum ingot, copper tubing for traction motor cooling, and additive manufacturing powder feedstock. Single-source vulnerability clusters in Zhejiang province foundry capacity. Distribution runs through OEM-integrated channels and independent maintenance networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The railway after-cooler market sits in a technology-transition phase as additive-manufactured aluminum lattices displace conventional fin-and-tube cores in premium applications.
For Market Incumbents: Anchor aftermarket service relationships through captive brake-thermal integration partnerships that resist unbundling trends. Expand railway-certified foundry capacity in Germany and Japan to defend against Zhejiang province supply concentration. Prioritize vibration testing laboratory investments to resolve certification bottlenecks for additive-manufactured cores.
For New Entrants and Emerging Players: Hydrogen fuel cell locomotive prototypes in Germany and Japan offer a technology-first wedge into unserved cooling configurations. Target standalone maintenance provider contracts in North American Class I railroad territory where procurement fragmentation is displacing OEM-captive models. Pursue qualification partnerships with Stuttgart-area testing laboratories to accelerate certification timelines.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by rolling stock manufacturers seeking thermal system integration capabilities. Long-term viability favors suppliers with additive manufacturing expertise and hydrogen traction cooling portfolios. Monitor Deutsche Bahn infrastructure renewal program acceleration as the inflection indicator for European aftermarket demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Certification Investment | Qualifies aluminum casting lines for 5-2000 Hz vibration testing required by EPA Tier 4 compliance. |
| Additive Manufacturing Scale-Up | Enables topology-optimized lattice cores that compress underfloor packaging for Shinkansen and TGV fleets. |
| Maintenance Provider Partnership | Captures unbundled thermal system contracts from Union Pacific and BNSF asset life extension programs. |
| Hydrogen Cooling Development | Positions suppliers for fuel cell locomotive prototypes eliminating legacy turbocharger staging configurations. |
| Vibration Testing Laboratory Expansion | Resolves certification bottlenecks in Germany and Japan for advanced aluminum core designs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with fleet maintenance directors, OEM thermal system engineers, foundry operations managers, and third-party certification laboratory staff combined with secondary validation from EPA locomotive emissions filings, EU F-Gas Regulation implementation reports, and MIIT GB standard documentation. Bottom-up and top-down triangulation cross-checked production volume estimates against procurement contract disclosures.
Granularity-level modeling distinguished air-cooled, water-cooled, oil-cooled, and gas-cooled architectures across locomotive, high-speed train, light rail, and metro applications. Standard, advanced, hybrid, and experimental technology tiers were projected separately across the analysis window. CAGRs derived from segmented volume trajectories weighted by replacement cycle timing and regulatory compliance deadlines. Forecast inputs incorporated aluminum ingot price volatility indices and foundry capacity utilization rates.
Several conditions sit outside the modeled scope, including phase-change material and microchannel experimental configurations still in field trials, and potential regulatory acceleration of hydrogen traction timelines. Forecasts reflect documented assumptions about certification laboratory capacity expansion and foundry requalification schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Railway Hydraulic Damper Market
Railway Transportation
Global Train Communication Gateways Systems Market
Railway Transportation
Railway Station Lighting Market
Railway Transportation
Railcar Movers Market
Railway Transportation
High Speed Rail Coating Market
Railway Transportation
Railway Roof Switches Market
Railway Transportation
Global Autonomous Trains Market
Railway Transportation
Japan Rail Freight Transport Market
Railway Transportation
Global Rail Freight Transport Market
Railway Transportation
China-Europe Rail Freight Transport Market
Railway Transportation
Point Machine Market
Railway Transportation
Railway Couplers Market
Railway Transportation
Rail Switch Point Heating System Market
Railway Transportation
Automatic Train Protection Signaling Market
Railway Transportation
Railway Li-Ion Battery Market
Railway Transportation
Germany Rail Freight Transport Market