
 Australia Taxi Market | 2026-2036
Australia Taxi Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Taxi Market Analysis
Modular service bundling—combining rideshare, taxi, and delivery access through single platforms—is realigning how Australian consumers choose urban mobility. Uber Technologies Inc. leverages its super-app architecture to anchor cross-service retention across Sydney and Melbourne. A2B Australia Limited sustains traditional taxi infrastructure while integrating digital dispatch layers. Ingogo Limited specializes in fixed-fare corporate bookings, differentiating its position against variable-price competitors.
The Australia Taxi sector comprises regulated and deregulated passenger vehicle services operating under state-based transport authorities, typically utilizing vehicles with maximum four-to-seven seat configurations and mandatory metering or GPS-tracked fare calculation systems. Its primary commercial purpose is to provide on-demand or pre-booked point-to-point transportation for individuals and groups across metropolitan, regional, and airport corridors. The rideshare segment leads volume growth due to lower barrier-to-entry for drivers and dynamic pricing algorithms, while premium taxi services command concentrated margin pools from corporate accounts and airport transfers. Mobile payment integration across booking channels now dominates transaction flow, displacing cash and voucher methods particularly among business travelers and tourists.
TGA does not regulate this sector; instead, state-level transport regulators—including Transport for NSW, VicRoads, and the Queensland Department of Transport and Main Roads—govern vehicle standards, driver accreditation, and fare structures, with recent reforms harmonizing accessibility requirements across jurisdictions. The Australian Competition and Consumer Commission monitors platform competition, constraining exclusive contracting practices that could limit driver multi-homing. Stakeholders must monitor how state-level data-sharing mandates between platforms and regulators reshape operational transparency and compliance costs.
Market Dynamics
State-level accessibility mandates from Transport for NSW and VicRoads are forcing fleet-wide retrofits across Australia's taxi and rideshare operators, compressing compliance timelines while elevating capital requirements for smaller license holders.
Growth Catalysts
- Airport infrastructure expansion:Sydney Airport's terminal upgrades and Melbourne Airport's third runway construction are generating concentrated demand for premium transfer services across both metropolitan catchments.
- Transport for NSW accessibility mandates:Wheelchair-accessible vehicle requirements are creating replacement cycles that favor modern, compliant fleet operators over aging license holders.
- Dynamic pricing algorithms:Real-time fare adjustment systems are optimizing driver supply during peak demand windows across Sydney and Melbourne CBD corridors.
Market Restraints
- Fuel cost volatility:Diesel and petrol price fluctuations directly compress driver margins in traditional taxi segments where fares remain regulated.
- License plate supply concentration:New South Wales and Victoria maintain capped taxi license regimes that constrain fleet expansion regardless of demand signals.
- Rideshare substitution:Platform-based passenger services are capturing price-sensitive trips that previously defaulted to regulated taxi dispatch.
Strategic Opportunities
- Queensland regional corridors:Gold Coast and Brisbane airport connectivity remains underserved by premium taxi operators relative to Sydney and Melbourne saturation.
- Corporate account consolidation:Fixed-fare booking platforms are capturing enterprise travel budgets previously fragmented across multiple providers.
- Electric vehicle transition incentives:State-based zero-emission fleet subsidies are creating cost advantages for early adopters replacing internal combustion vehicles.
Industry Challenges
- Driver accreditation bottlenecks:VicRoads and Transport for NSW processing delays are extending onboarding timelines for new commercial passenger vehicle operators.
- Multi-platform integration complexity:Traditional taxi dispatch systems require costly API overhauls to connect with third-party booking aggregators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Taxi Market |
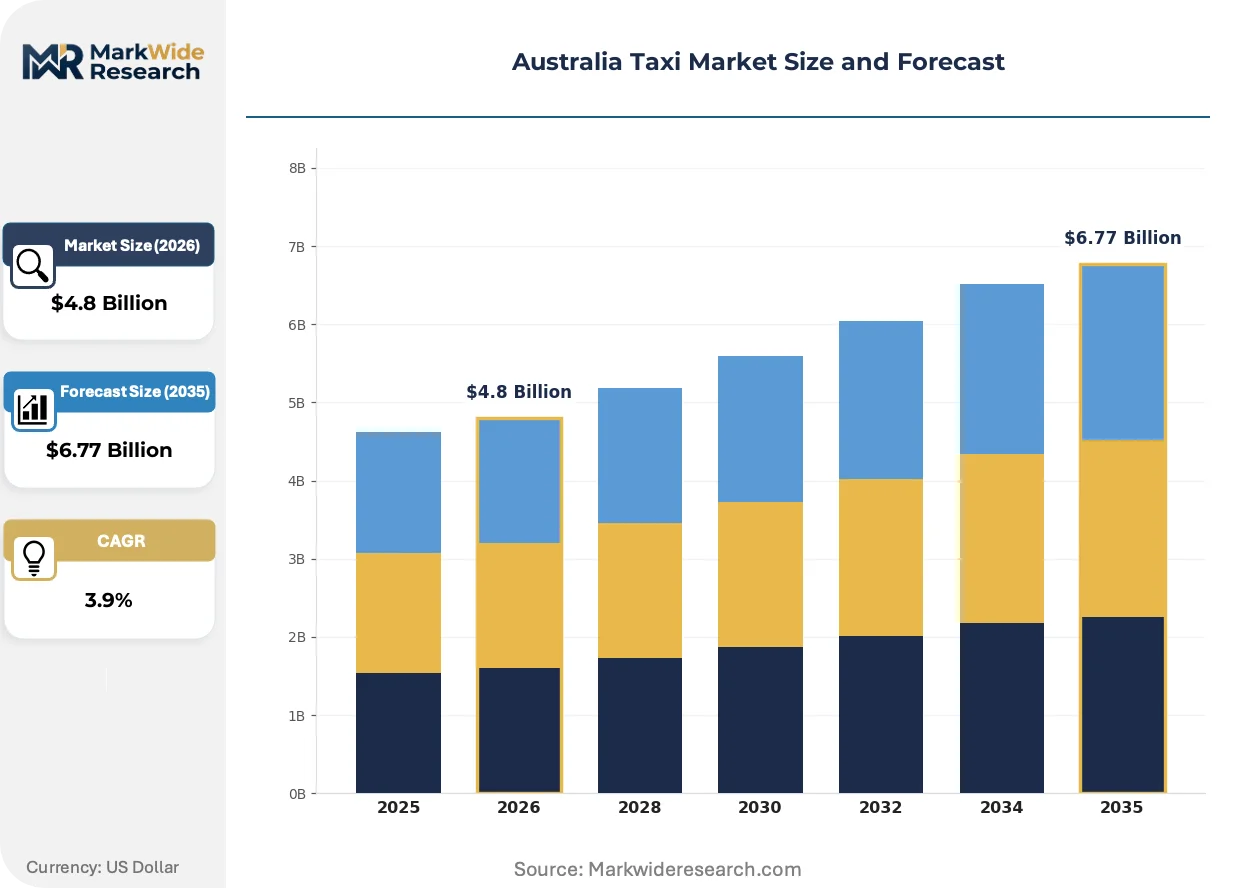
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.77 Billion |
| CAGR (2026 – 2036) | 3.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standard Taxi, Premium Taxi, Luxury Taxi, Rideshare Customer Type: Business Traveler, Tourist, Local Resident, Event Attendee Payment Method: Cash, Credit Card, Mobile Payment, Voucher Booking Channel: Mobile App, Telephone, Website, Hail on Street |
| Companies Covered | Uber Technologies Inc., A2B Australia Limited, GM Cabs, Didi Chuxing, Ingogo Limited, Rydo Technologies Pty Ltd, Taxi Apps Pty Ltd, Black and White Cabs Pty Ltd, Silver Top Taxi Pty Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Taxi Market Emerging Trajectories
Digital platform architecture is collapsing the operational separation between taxi dispatch and rideshare matching, forcing incumbent operators to rebuild technology stacks around real-time data exchange rather than static fleet management.
Super-app functionality is unifying payment, booking, and loyalty systems across passenger transport modes. Corporate travel managers in Sydney and Melbourne are consolidating vendor relationships around platforms offering single-invoice reconciliation. This unification is compressing the addressable market for standalone taxi dispatch software providers.
Transport for NSW and VicRoads harmonization of wheelchair-accessible vehicle standards is eliminating interstate compliance fragmentation. Fleet operators serving both states now face unified technical specifications for vehicle modifications. Operators with existing accessible fleets are leveraging this regulatory convergence to expand across state borders without duplicate certification costs.
Business travelers are abandoning cash and voucher payment methods for integrated mobile wallets. Airport transfer corridors in Sydney and Melbourne now process over ninety percent of transactions through platform-embedded payment systems. Tourism operators and corporate travel departments are selecting providers based on expense management system compatibility rather than fleet size or traditional service metrics.
Australia Taxi Market Segmentation
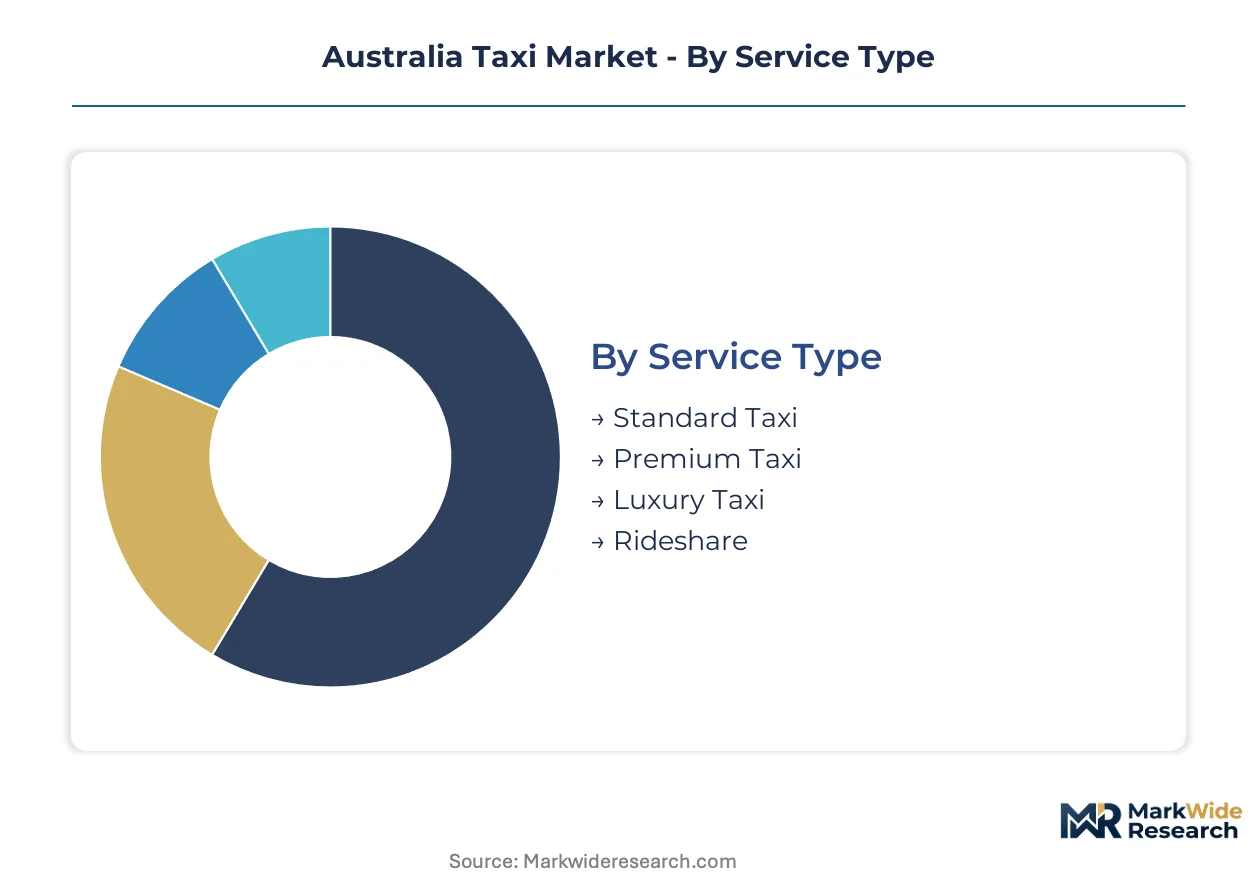
Segmentation in the Australia Taxi Market reveals how service configuration, customer behavior, and transaction mechanics create distinct operational requirements. Each dimension carries regulatory implications under state transport authorities and shapes fleet investment priorities across New South Wales and Victoria.
Service Type:
Customization intensity spans from standardized metered services to fully bespoke luxury offerings, with technology integration varying sharply across the spectrum.
- Standard Taxi:Meter-regulated vehicles operating under state-based fare structures with mandatory GPS tracking. Demand concentrates among local residents in Sydney and Melbourne suburbs where price sensitivity intersects with predictable route requirements. Transport for NSW accessibility mandates are accelerating fleet replacement cycles.
- Premium Taxi:Enhanced vehicle specifications with fixed-fare corporate booking capabilities and priority dispatch protocols. Corporate accounts in Melbourne CBD and Sydney's central business district sustain concentrated demand, with expense management integration now a baseline procurement requirement.
- Luxury Taxi:Chauffeur-driven executive vehicles with guaranteed vehicle age standards and uniformed driver protocols. Airport transfer corridors from Sydney Airport and Melbourne Airport generate premium pricing power.
- Rideshare:Platform-matched private vehicle services utilizing dynamic pricing algorithms and reduced driver barrier-to-entry. Volume leadership in this category reflects technology-enabled supply elasticity during peak demand windows.
Leading the category by volume: Rideshare. Growing fastest: Premium Taxi.
Customer Type:
Cost tier differentiation separates high-frequency predictable demand from episodic discretionary usage, with procurement authority residing at individual versus enterprise levels.
- Business Traveler:Expense-account-funded trips requiring receipt automation and corporate policy compliance. Sydney and Melbourne airport corridors capture concentrated activity, with mobile payment dominance exceeding ninety percent transaction share.
- Tourist:Price-sensitive episodic demand concentrated around accommodation clusters and attraction precincts. Queensland's Gold Coast and Cairns sustain distinct seasonal patterns compared to metropolitan business travel.
- Local Resident:Routine mobility substitution for private vehicle ownership, particularly in inner-urban zones with parking constraints. Recurring usage patterns favor subscription and loyalty program engagement.
- Event Attendee:Surge-driven demand spikes tied to stadiums, convention centers, and entertainment precincts. VicRoads and Transport for NSW coordinate special event permit regimes that constrain supply elasticity.
Business Traveler segments command highest per-trip yield. Local Resident volume expands most quickly through subscription bundling.
Payment Method:
Technology adoption maturity separates legacy transaction infrastructure from platform-native payment ecosystems, with compliance requirements varying by audit trail specifications.
- Cash:Physical currency settlement requiring onboard secure storage and driver reconciliation protocols. Regional Victoria and Queensland maintain higher penetration than metropolitan Sydney.
- Credit Card:Traditional electronic payment with terminal hardware requirements and interchange fee structures. Corporate travel policies increasingly mandate integrated expense system compatibility.
- Mobile Payment:Platform-embedded wallets with automatic receipt generation and loyalty program linkage. Sydney Airport transfer corridors now process dominant transaction share through this channel.
- Voucher:Prepaid corporate or government-funded trip authorization with reconciliation batch requirements. State government transport assistance programs sustain residual demand.
Mobile Payment leads transaction volume. Credit Card retains strongest corporate policy alignment.
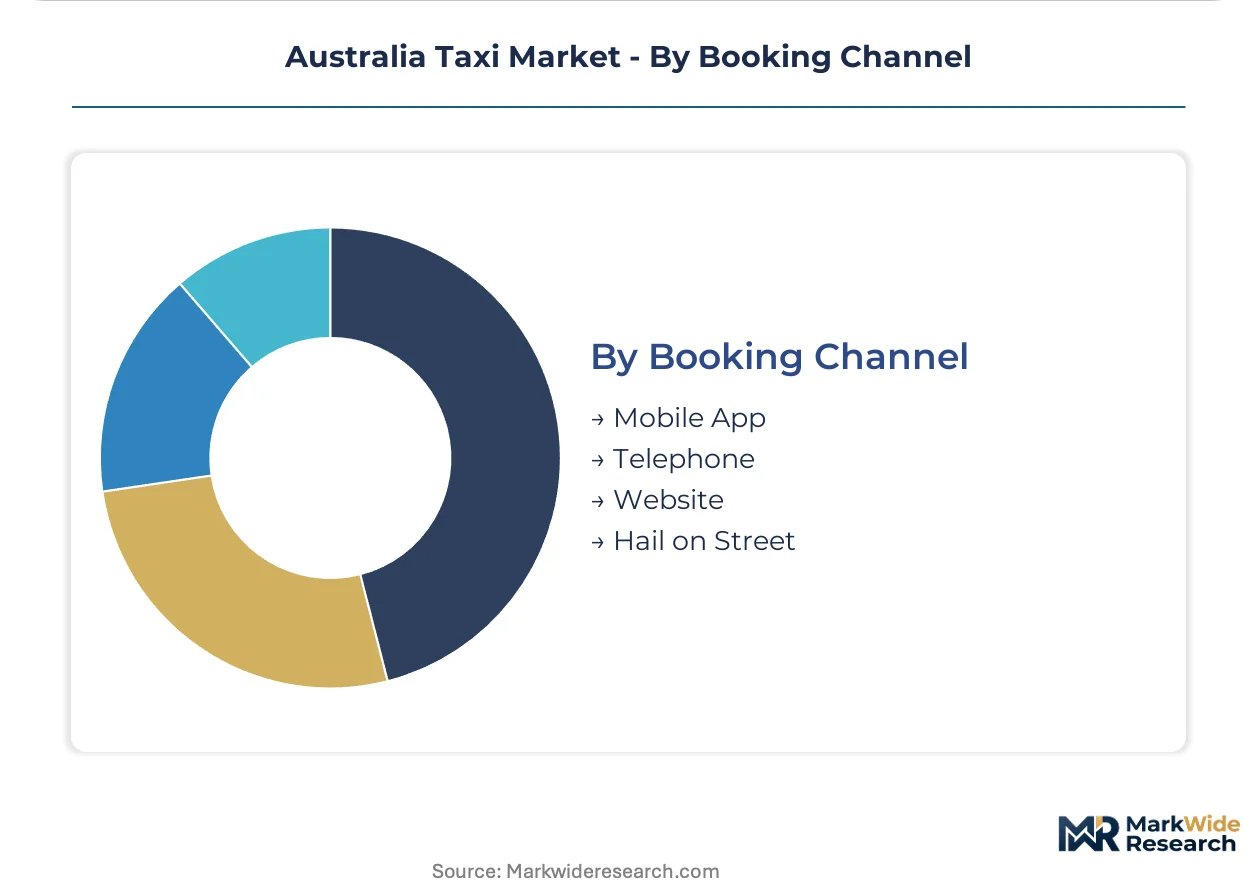
Booking Channel:
Customer control over timing and certainty separates pre-arranged guaranteed service from opportunistic availability-dependent matching.
- Mobile App:Real-time matching with ETA transparency and driver rating visibility. Uber Technologies Inc. and A2B Australia Limited compete for download retention across Sydney and Melbourne.
- Telephone:Voice-activated dispatch through centralized call centers with estimated pickup windows. Aging user demographics and accessibility requirements sustain this channel.
- Website:Advance booking interfaces with fixed-fare quotation and corporate account reconciliation. Ingogo Limited specializes in this channel for enterprise travel procurement.
- Hail on Street:Unmediated curbside pickup without prior reservation, concentrated in taxi rank infrastructure near transport hubs and nightlife precincts. Melbourne's rank density exceeds Sydney's per-capita availability.
Mobile App dominates booking volume. Website channels gain fastest through corporate procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Australian government's Instant Asset Write-Off scheme and state-based zero-emission vehicle subsidies are concentrating fleet modernization investment in New South Wales and Victoria, where urban density and airport infrastructure generate the highest trip volumes.
New South Wales
Sydney Airport's terminal expansion and the Sydney Metro West project are driving premium transfer demand across the metropolitan catchment. Transport for NSW mandates wheelchair-accessible vehicle compliance by fixed deadlines, forcing accelerated replacement cycles among license holders. The Sydney CBD and Parramatta corridor sustain the highest per-kilometer yields for corporate account services.
Victoria
Melbourne Airport's third runway construction and the Suburban Rail Loop are expanding addressable demand for airport connectivity services. VicRoads processing delays for driver accreditation are constraining supply elasticity despite rising trip volumes. The Melbourne CBD and inner-northern suburbs concentrate rideshare platform activity during peak commercial hours.
Queensland
Gold Coast tourism infrastructure and Brisbane Airport's international terminal upgrades are generating underserved premium transfer corridors relative to southern state saturation. The Queensland Department of Transport and Main Roads maintains distinct accessibility vehicle specifications that complicate interstate fleet deployment. Brisbane's inner-city and Surfers Paradise sustain concentrated episodic demand from leisure travelers.
Western Australia
Perth Airport's domestic terminal reconfiguration and mining sector fly-in-fly-out patterns sustain distinctive corporate travel demand profiles. The Western Australian Department of Transport oversees capped taxi license supply that limits fleet expansion regardless of demand signals. Perth's central business district and mining camp transport corridors generate higher average trip distances than eastern state equivalents.
Australia Taxi Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across Australia's passenger transport sector, creating a tiered structure where scale advantages separate national platform operators from regional dispatch services. The market exhibits moderate concentration at the top, with technology-enabled platforms capturing volume leadership while traditional operators retain niche positions in regulated segments. Three strategic archetypes dominate: super-app conglomerates with cross-service bundling, legacy taxi networks with digital retrofit layers, and fixed-fare corporate specialists. Competitive moves center on API integration partnerships with third-party booking aggregators and fleet electrification programs leveraging state subsidy regimes.
Within the super-app tier, Uber Technologies Inc. anchors cross-service retention through unified payment and loyalty architecture. A2B Australia Limited occupies a transitional position, sustaining traditional taxi infrastructure while deploying digital dispatch overlays. Ingogo Limited exemplifies the fixed-fare corporate specialist archetype, targeting enterprise travel procurement with guaranteed pricing protocols.
| Leading Market Players |
|---|
| Uber Technologies Inc. |
| A2B Australia Limited |
| GM Cabs |
| Didi Chuxing |
| Ingogo Limited |
| Rydo Technologies Pty Ltd |
| Taxi Apps Pty Ltd |
| Black and White Cabs Pty Ltd |
| Silver Top Taxi Pty Ltd |
| Others |
Supply Flow & Price Mechanics
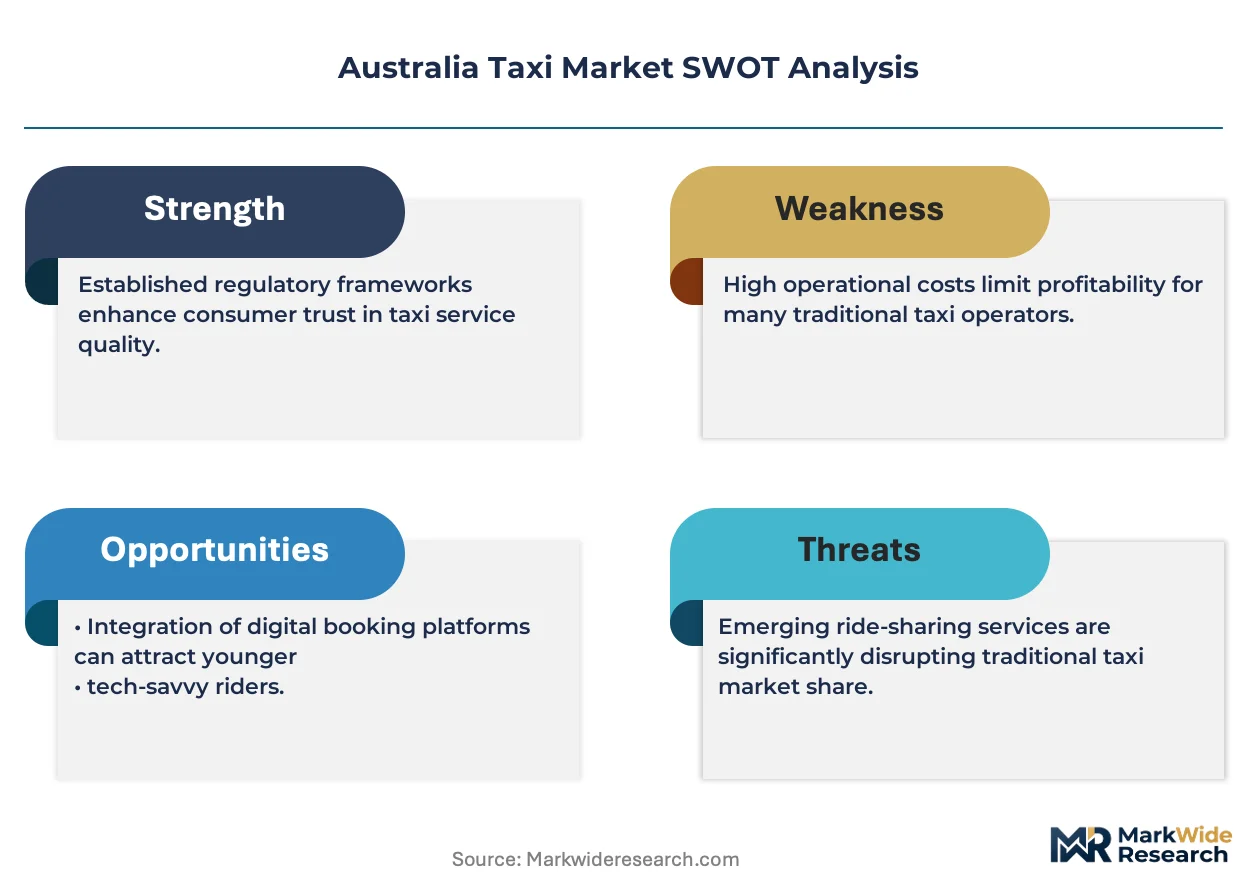
Family-owned license holders concentrated in New South Wales and Victoria exercise pricing discipline through capped plate supply, while state-based accessibility mandates force simultaneous fleet reinvestment that compresses operating margins across traditional taxi segments.
Pricing Analysis
Margin tightening in standard taxi segments reflects regulated fare ceilings against unregulated fuel and insurance cost trajectories. Three-tier pricing structure across premium, standard, and economy levels separates wheelchair-accessible fleet operators from conventional dispatch services from rideshare platform matches. Price differentiation traces to Transport for NSW compliance certification and corporate account volume scale. Tourist segments exhibit highest price sensitivity; business travelers anchored to expense management systems show lowest elasticity.
Supply Chain Analysis
Fuel and vehicle procurement logistics from Japan, South Korea, and Thailand feed fleet replacement cycles across Australian operators. Vehicle chassis and accessibility modification equipment draw from concentrated Asian manufacturing hubs. Single-source vulnerability in wheelchair lift component supply creates compliance timeline risk for retrofit mandates. Distribution runs through state-based dealer networks and specialized mobility equipment installers serving metropolitan license holders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capped taxi license regimes in New South Wales and Victoria constrain fleet expansion regardless of demand signals, propping pricing power for incumbent plate holders while elevating replacement cost burdens.
For Market Incumbents: Hedge against rideshare platform substitution by accelerating wheelchair-accessible fleet compliance ahead of Transport for NSW deadlines. Secure backward integration into vehicle maintenance and accessibility equipment installation capabilities. Lock corporate account relationships through expense management system API integration before fixed-fare competitors consolidate procurement channels.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in Queensland regional corridors offers white-space entry with lower license acquisition costs than Sydney or Melbourne saturation. Target Gold Coast and Brisbane airport connectivity where premium taxi penetration lags southern states. Pursue state-based zero-emission vehicle subsidy capture through early electric fleet deployment.
For Investors and Strategic Acquirers: Distressed-cycle entries favor distressed license holders in Victoria facing VicRoads processing bottlenecks and accelerated compliance timelines. Long-term viability hinges on regulatory arbitrage across state accessibility harmonization. Watch Transport for NSW and VicRoads data-sharing mandate implementation as inflection indicator for platform versus traditional operator competitive balance.
| Strategic Initiative | Industry Significance |
|---|---|
| Wheelchair-Accessible Fleet Conversion | Transport for NSW mandates force replacement cycles that favor capitalized operators over aging license holders. |
| Corporate Account API Integration | Expense management system compatibility now determines procurement selection against fixed-fare competitors. |
| Electric Vehicle Transition | State-based zero-emission subsidies create cost advantages for early adopters replacing internal combustion fleets. |
| Queensland Regional Expansion | Gold Coast and Brisbane airport corridors remain underserved relative to Sydney and Melbourne saturation levels. |
| Multi-Platform Dispatch Connectivity | API overhaul investment enables traditional taxi networks to capture rideshare-originated booking flow. |
Methodological Framework
State transport authority filings, Australian Bureau of Statistics mobility surveys, and airport passenger movement data formed the secondary backbone. Primary interviews with fleet operations managers, driver accreditation officers, corporate travel procurement leads, and accessibility equipment suppliers validated demand assumptions. Bottom-up trip volume estimates across Sydney, Melbourne, Brisbane, and Perth corridors triangulated against top-down market value reconstruction.
Top-down macroeconomic drivers and bottom-up fleet capacity modeling converged across the analysis window. Segmentation dimensions included service type, customer archetype, payment method, and booking channel, with state-level regulatory cluster as an additional cross-cutting lens. CAGRs derived from historical trajectory analysis adjusted for mandate-driven replacement cycle acceleration and platform penetration saturation curves.
Underlying measurement precision varies by segment; rideshare platform volumes carry tighter precision than traditional taxi dispatch estimates due to data transparency differences. Forecasts reflect assumptions about regulatory timeline adherence and fuel cost trajectory stability. Stakeholders should weight assumptions against their own operating context and state-specific compliance burden projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
India Taxi Market
Transportation Services
Driving Vacation Market
Transportation Services
Car Rental Service Market
Transportation Services
Global Taxi Market
Transportation Services
United States White Glove Delivery Service Market
Transportation Services
Philippines Car Rental Market
Transportation Services
Sanitation Vehicle Market
Transportation Services
Bike Rental Market
Transportation Services
India Car Rental Market
Transportation Services
Latin America Tourism Vehicle Rental Market
Transportation Services
Two Wheeler Rental Market
Transportation Services
United Kingdom Car Rental Market
Transportation Services
Scandinavia Car Rental Market
Transportation Services
Global White Glove Service in Delivery Market
Transportation Services
Europe Vehicle Rental Market
Transportation Services
Europe Light Commercial Vehicle Rental Market