
 Point Machine Market | 2026-2036
Point Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Point Machine Market Intelligence
High-reliability specification tiers is collapsing into the mainstream as rail operators demand MTBF ratings above one million cycles for critical junctions. Protolabs leverages digital manufacturing workflows to compress prototype-to-production timelines for custom point machine housings. Xometry sustains a distributed supplier network that matches regional rail gauge standards without captive foundry investments. Renjie Precision anchors its position through CNC machining specialization in hardened steel actuator components.
A point machine is an electromechanical or electrohydraulic trackside device that moves railway switch blades between diverging routes, typically generating throw forces between 3 kN and 7 kN and operating within temperature ranges from minus 40 to plus 70 degrees Celsius. Electromechanical variants now lead unit shipments across European and Asian networks where energy efficiency targets override first-cost considerations. Microprocessor-based technology segments capture disproportionate margin pools through predictive maintenance algorithms and remote diagnostic integration. Metro rail applications represent the fastest-expanding demand channel as urban transit agencies prioritize automated train operation compatibility.
The European Union Agency for Railways enforces interoperability standards through the CCS TSI specification, compelling manufacturers to certify control interfaces before accessing member-state procurement frameworks. India's Ministry of Railways mandates BIS certification for all point machines deployed on Indian Railways track, creating a compliance barrier for uncertified imports. China's NMPA-aligned rail equipment certification system requires domestic type testing for safety-critical signaling components. Stakeholders must weigh regional certification reciprocity against the cost of establishing parallel testing regimes when selecting market entry sequences.
Market Dynamics
Electromechanical actuation is displacing legacy hydraulic systems across European and Asian rail networks as energy efficiency mandates harden into procurement criteria. This technology pivot compresses supplier margins while elevating certification barriers for new entrants.
Growth Catalysts
- EU Green Deal rail modal shift targets:Member states must double rail freight volume by 2030, forcing infrastructure operators to replace aging switchgear with servo-driven alternatives that cut energy consumption.
- India's Dedicated Freight Corridor:The PLI scheme's localization mandates are channeling procurement toward domestic point machine assembly, creating captive demand for electromechanical variants.
- Microprocessor-based predictive maintenance:Remote diagnostic integration allows operators to schedule interventions before failures, reducing track possession costs and extending asset life cycles.
Market Restraints
- Hardened steel input cost volatility:Actuator component machining requires specialized alloys whose prices fluctuate with nickel and chromium spot markets, squeezing fabricator margins.
- Certification reciprocity gaps:China's NMPA-aligned rail equipment rules require redundant domestic type testing, blocking rapid market entry for certified EU or Indian suppliers.
- Legacy hydraulic installed base:Decades-old systems in North American freight corridors create switching inertia, as full electromechanical retrofits demand concurrent signal interlocking upgrades.
Strategic Opportunities
- Urban metro automation compatibility:Automated train operation mandates in Gulf Cooperation Council cities are generating demand for point machines with SIL-4 safety integrity and sub-second response times.
- CCS TSI interoperability certification:Early alignment with the European Union Agency for Railways specification opens access to cross-border procurement frameworks spanning Germany, France, and Poland.
- Digital manufacturing workflows:Distributed supplier networks using CNC machining specialization can match regional gauge standards without capital-intensive captive foundry investments.
Industry Challenges
- BIS certification timeline compression:India's Ministry of Railways mandates domestic testing for all track-mounted equipment, creating 18-24 month approval bottlenecks for imported designs.
- Signal interlocking integration complexity:Microprocessor-based point machines must interface with legacy relay-based control systems, requiring costly protocol translation hardware.
- MTBF specification escalation:Rail operators now demand one million cycle ratings for critical junctions, forcing redesigns of contactor and limit switch subassemblies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Point Machine Market |
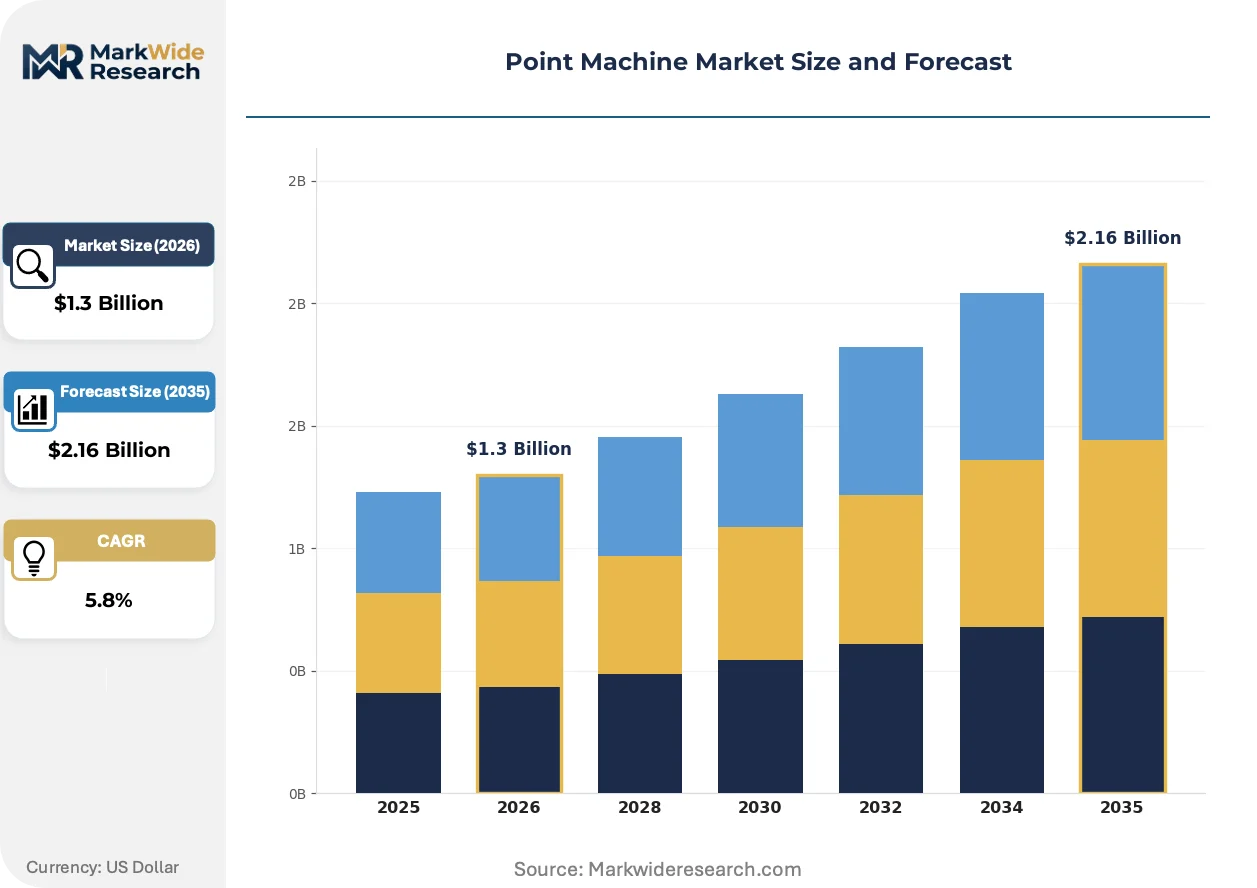
| Market Size in 2026 | $1.3 Billion |
| Market Size in 2035 | $2.16 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrohydraulic, Electromechanical, Manual, Pneumatic, Servo Technology: Relay-Based, Microprocessor-Based, Wireless Control, Hydraulic Control, Pneumatic Control Application: High-Speed Rail, Freight Rail, Metro Rail, Light Rail Transit, Monorail End User: Rail Infrastructure Managers, Maintenance Providers, Train Operators, Railway Contractors, Track Equipment Suppliers |
| Companies Covered | Rapid Axis, STAR Rapid, Protolabs, Renjie Precision, WayKen, Xometry, Fathom, QuickParts, Fictiv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Point Machine Market Strategic Shifts & Innovations
Digital thread integration from design to field deployment is compressing product development cycles while fragmenting traditional supplier hierarchies. This shift enables smaller specialized manufacturers to compete against integrated incumbents.
Servo-motor actuation with integrated position feedback is fragmenting the point machine technology landscape. Metro rail operators in Saudi Arabia and the UAE are specifying these variants for new automated lines. The technology is fragmenting procurement patterns by allowing operators to unbundle control system software from mechanical hardware.
The EU Green Deal's F-Gas Regulation is accelerating phase-out of hydraulic fluids with high global warming potential. Rail infrastructure managers in Germany and Austria face mandatory replacement timelines for legacy electrohydraulic units. This regulatory pressure is concentrating electromechanical supplier selection around energy efficiency certification data.
Buyers are consolidating maintenance contracts under long-term availability agreements that transfer obsolescence risk to manufacturers. European national rail incumbents in France and Italy are leading this shift away from transactional spare parts purchasing. The model is most visible in high-speed line extensions where uptime penalties dwarf capital equipment costs.
Point Machine Market Segmentation
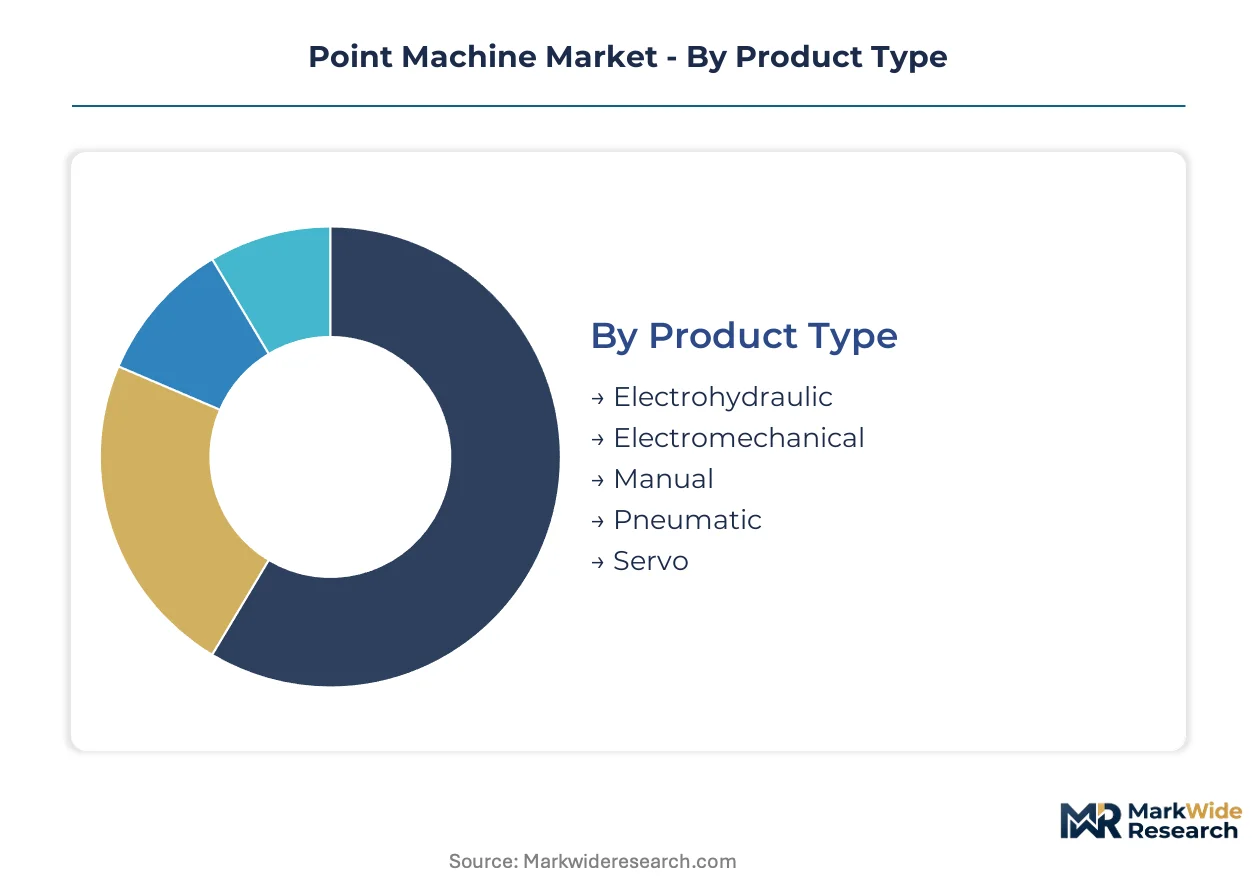
Point machine procurement patterns diverge sharply across actuation technologies and control architectures, with margin concentration shifting toward predictive maintenance-enabled systems. Understanding these fault lines reveals where suppliers can defend pricing power against commoditization pressures.
Product Type:
Electromechanical variants command the widest margin spreads as energy efficiency certification becomes a gatekeeping criterion for European tenders.
- Electrohydraulic:Legacy systems utilizing pressurized fluid actuation dominate North American freight corridors where retrofit budgets remain constrained. Decades-old installed base across Union Pacific and BNSF networks creates replacement inertia, though EU F-Gas Regulation timelines are forcing accelerated phase-outs in Germany and Austria.
- Electromechanical:Servo-motor architectures with integrated position feedback now lead unit shipments across European and Asian networks. India's Dedicated Freight Corridor project channels procurement toward these variants under PLI scheme localization mandates, while metro operators in Saudi Arabia and the UAE specify them for automated train operation compatibility.
- Manual:Hand-cranked backup systems persist in secondary track configurations and developing rail networks with intermittent electrification.
- Pneumatic:Compressed air actuation retains niche deployment in legacy industrial sidings and yard switching applications.
- Servo:Precision motor control variants with sub-second response times are gaining specification in high-speed junctions requiring SIL-4 safety integrity.
Electrohydraulic holds installed capacity across North American freight networks. Electromechanical is rotating up the share rankings as Green Deal procurement criteria harden.
Technology:
Control architecture selection determines aftermarket revenue potential, with microprocessor-based systems enabling recurring diagnostic service streams.
- Relay-Based:Electromechanical switching logic remains embedded in legacy interlocking systems across Eastern European and South Asian networks. Full electromechanical retrofits demand costly protocol translation hardware, preserving this segment's installed base despite functional obsolescence.
- Microprocessor-Based:Embedded computing platforms with predictive maintenance algorithms capture disproportionate margin pools through remote diagnostic integration. European national rail incumbents in France and Italy are consolidating maintenance contracts under long-term availability agreements that transfer obsolescence risk to manufacturers.
- Wireless Control:Radio-based actuation commands reduce cabling costs in remote track sections and temporary construction alignments.
- Hydraulic Control:Fluid power management systems persist in electrohydraulic point machine retrofits where full mechanical replacement is capital-prohibitive.
- Pneumatic Control:Air logic systems accompany pneumatic actuation in industrial rail environments with existing compressed air infrastructure.
Relay-based retains the deepest installed base. Microprocessor-based is climbing the fastest as uptime penalties on high-speed lines dwarf capital equipment costs.
Application:
Speed tier and automation requirements fragment demand specifications, with metro rail applications driving the steepest specification escalation.
- High-Speed Rail:Trackside equipment must sustain MTBF ratings above one million cycles for critical junctions where possession windows are measured in minutes. Asia-Pacific networks are expanding procurement of hardened steel actuator components as countries modernize signaling infrastructure.
- Metro Rail:Urban transit agencies prioritize automated train operation compatibility, generating demand for SIL-4 safety integrity and sub-second response times. Gulf Cooperation Council cities are specifying servo-motor variants for new automated lines, fragmenting procurement patterns by unbundling control software from mechanical hardware.
- Freight Rail:Heavy-haul corridors prioritize throw force reliability over response speed, with India's Dedicated Freight Corridor creating captive demand for electromechanical assembly.
- Light Rail Transit:Street-running configurations demand compact form factors and reduced noise signatures for urban integration.
- Monorail:Straddle-beam and suspended systems require specialized switch mechanisms adapted to unique guideway geometries.
Freight rail holds the largest installed base by track-kilometer coverage. Metro rail is gaining share fastest as urbanization concentrates transit investment in automated systems.
End User:
Contracting structure determines supplier margin durability, with availability-based agreements replacing transactional spare parts purchasing among infrastructure managers.
- Rail Infrastructure Managers:Network owners in Germany, France, and Poland are leading the shift toward long-term maintenance contracts that internalize obsolescence risk. CCS TSI interoperability certification opens access to cross-border procurement frameworks spanning these markets.
- Maintenance Providers:Third-party service contractors are consolidating around predictive diagnostic capabilities that reduce track possession costs and extend asset life cycles.
- Train Operators:Passenger and freight carriers influence point machine specification through uptime penalty clauses in infrastructure access agreements.
- Railway Contractors:Construction firms executing greenfield line extensions face aggressive localization mandates under India's PLI scheme and similar domestic content requirements.
- Track Equipment Suppliers:Component fabricators leverage CNC machining specialization in hardened steel to match regional gauge standards without captive foundry investments.
Rail infrastructure managers anchor procurement volume. Maintenance providers are rotating up the share rankings as outcome-based contracting displaces transactional spare parts purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in point machine equipment reveal a structural surplus concentrated in European and Asian manufacturing bases, while import dependency persists in emerging rail markets across the Middle East and Southeast Asia.
Germany
High-speed rail modernization and freight corridor electrification drive electromechanical point machine procurement across Deutsche Bahn's network. The EU Green Deal's F-Gas Regulation mandates accelerated phase-out of hydraulic fluids, compelling infrastructure managers to specify servo-driven alternatives. Industrial clusters in Bavaria and Baden-Württemberg host precision actuator component fabrication serving cross-border CCS TSI-certified supply chains.
India
The Dedicated Freight Corridor project generates captive demand for electromechanical assembly as track-kilometer expansion accelerates. BIS certification requirements under the Ministry of Railways create 18-24 month approval timelines that favor domestic assembly partnerships. Manufacturing concentration in Maharashtra and Gujarat aligns with PLI scheme localization mandates for critical signaling infrastructure.
China
High-speed rail network densification sustains procurement of microprocessor-based point machines with predictive maintenance integration. NMPA-aligned rail equipment certification requires domestic type testing for safety-critical components, blocking rapid entry for foreign-certified suppliers. Production clusters in the Yangtze River Delta and Beijing-Tianjin-Hebei corridor supply both domestic deployment and Belt and Road rail projects.
Saudi Arabia
Metro automation mandates in Riyadh and Jeddah generate specification demand for SIL-4 safety integrity and sub-second response times. MOHAP-equivalent rail safety oversight aligns procurement with international standards while permitting GCC-cross-border equipment mobility. Industrial zones in the Eastern Province concentrate track equipment assembly serving Gulf Cooperation Council urban transit expansions.
United States
Freight rail corridors across Union Pacific and BNSF networks preserve legacy electrohydraulic installed base where retrofit budgets remain constrained. FRA safety regulations govern point machine specification without mandating specific actuation technologies, preserving technology neutrality. Manufacturing activity concentrates in the Midwest rail belt spanning Illinois, Ohio, and Pennsylvania for heavy-haul component supply.
Point Machine Market Key Industry Players
Listed leaders compete with private specialists across certification and manufacturing velocity dimensions. The vendor base organizes into three tiers: integrated rail signaling incumbents with captive foundry capacity, digital manufacturing platforms leveraging distributed supplier networks, and precision machining specialists focused on hardened steel actuator components. Strategic moves concentrate on CCS TSI interoperability pre-certification and regional gauge standard adaptation without capital-intensive captive investments.
Among digital manufacturing platforms, Protolabs and Xometry exemplify the distributed supplier network archetype, compressing prototype-to-production timelines for custom point machine housings without regional foundry commitments. Renjie Precision anchors the precision machining specialist tier through CNC specialization in hardened steel actuator components. These three occupy distinct competitive positions: Protolabs represents rapid digital workflow integration, Xometry exemplifies supplier network orchestration, and Renjie Precision sits within component-level manufacturing depth.
| Leading Market Players |
|---|
| Rapid Axis |
| STAR Rapid |
| Protolabs |
| Renjie Precision |
| WayKen |
| Xometry |
| Fathom |
| QuickParts |
| Fictiv |
| Others |
Cost & Logistics Intelligence
Eighteen-month BIS certification timelines for Indian Railways procurement compress supplier cash conversion cycles and concentrate pricing power among domestic assembly partners with pre-approved testing capacity. This lead-time rigidity reinforces margin premiums for electromechanical variants that already cleared localization mandates, while foreign suppliers absorb carrying costs or cede share to certified incumbents.
Pricing Analysis
Rail infrastructure managers anchor pricing structure around long-term availability agreements that internalize obsolescence risk and shift supplier economics toward service-margin durability. Three-tier pricing stratifies across SIL-4 certified premium tiers, standard electromechanical mid-market units, and economy relay-based configurations for secondary track. Cost compression in standard tiers is intensifying as PLI scheme localization mandates force margin absorption by domestic assemblers. Maintenance providers prove least price-sensitive given uptime penalty exposure, while railway contractors face aggressive budget caps under greenfield line extensions.
Supply Chain Analysis
Twenty-four-week hardened steel alloy lead times tether inventory planning to nickel and chromium spot market volatility, forcing fabricators into forward-contracting or premium spot purchases. Manufacturing gravity centers on Germany, India, and China, with Bavarian precision clusters serving CCS TSI-certified cross-border demand, Maharashtra-Gujarat corridors fulfilling PLI scheme mandates, and Yangtze River Delta production feeding Belt and Road rail projects. Actuator component machining draws from specialized chromium-molybdenum alloys, microprocessor control modules, and servo-motor subassemblies. Single-source vulnerability concentrates in hardened steel forging capacity for million-cycle MTBF-rated junction components. Distribution runs through rail infrastructure manager procurement frameworks and maintenance provider consignment arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory moat business where BIS, CCS TSI, and NMPA certification entrenchment creates decade-plus incumbent advantage through switching costs that exceed equipment replacement economics.
For Market Incumbents: Fortify CCS TSI interoperability pre-certification to lock cross-border procurement frameworks spanning Germany, France, and Poland against emerging digital manufacturing platforms. Deepen backward integration into hardened steel actuator forging to offset alloy price volatility and deny margin leverage to specialized CNC machinists. Certification timeline compression in India presents the primary threat vector. For New Entrants and Emerging Players: Lead with servo-motor actuation variants for Gulf Cooperation Council metro automation mandates, where SIL-4 specification demand outpaces incumbent capacity allocation. Saudi Arabia and UAE greenfield lines offer the most penetrable geography given international standard alignment and absence of legacy retrofit inertia. Digital manufacturing workflows enable gauge-standard adaptation without captive foundry capital deployment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across microprocessor-based predictive maintenance segments as software-margin contribution expands relative to mechanical hardware. Five-to-ten year viability favors suppliers with diagnostic service revenue streams and long-term availability contract backlogs. Acquisition targets should display CNC machining depth in hardened steel paired with embedded computing integration capability. The signal to watch is consolidation of European maintenance contracts under outcome-based pricing.| Strategic Initiative | Industry Significance |
|---|---|
| CCS TSI Interoperability Pre-Certification | Unlocks cross-border procurement frameworks across Germany, France, and Poland. |
| Backward Integration into Hardened Steel Forging | Insulates margin from nickel-chromium alloy spot volatility and supply disruption. |
| Predictive Maintenance Platform Development | Captures recurring service revenue under long-term availability agreements. |
| PLI Scheme Domestic Assembly Partnership | Secures BIS certification pathway for India's Dedicated Freight Corridor procurement. |
| Servo-Motor Actuation Product Line Expansion | Addresses Gulf Cooperation Council metro automation specification demand. |
Research Approach
Desk research of EU Agency for Railways technical specifications, Indian Railways tender documentation, and China NMPA certification databases preceded structured interviews with rail infrastructure procurement directors, maintenance provider operations heads, and track equipment supplier engineering leads. Secondary validation drew from customs trade flows, railway operator annual reports, and signaling industry association technical bulletins. Bottom-up segment sizing triangulated against top-down infrastructure investment forecasts.
Variance decomposition across actuation technology, control architecture, and application speed tiers structured the analytical framework over the projection horizon. Modeled dimensions included electromechanical versus electrohydraulic product mix, relay-based versus microprocessor-based technology penetration, and metro rail versus freight rail demand intensity. CAGRs derived from infrastructure capital commitment trajectories and replacement cycle analysis. Forecast inputs incorporated EU Green Deal modal shift targets and India's PLI scheme localization enforcement.
Forecasts assume regulatory continuity in EU F-Gas Regulation timelines, BIS certification reciprocity stance, and China NMPA domestic testing requirements; material policy shifts would require re-modeling. Hardened steel alloy price volatility and certification approval bottlenecks represent specific revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Canada Rail Freight Transport Market
Railway Transportation
Urban Rail Transit Signaling Market
Railway Transportation
Global Railcar Leasing Market
Railway Transportation
Railway Couplers Market
Railway Transportation
Railway Fishplate Market
Railway Transportation
Australia Rail Freight Transport Market
Railway Transportation
Railway Li-Ion Battery Market
Railway Transportation
Global Train Communication Gateways Systems Market
Railway Transportation
Poland Rail Freight Transport Market
Railway Transportation
Train Transformer Market
Railway Transportation
Railcar Movers Market
Railway Transportation
Japan Rail Freight Transport Market
Railway Transportation
Rail Testing Vehicle Market
Railway Transportation
Railway Radiator Market
Railway Transportation
Germany Rail Freight Transport Market
Railway Transportation
Urban Rail Transit Market