
 Rail Switch Point Heating System Market | 2026-2036
Rail Switch Point Heating System Market Size, Share, and Industry Trends Forecast 2026-2036
Rail Switch Point Heating System Market Analysis
EN 50121 electromagnetic compatibility certification for railway applications is unwinding the competitive landscape, filtering out suppliers lacking validated European rail credentials. Thermon leverages its heat-trace engineering heritage to dominate North American freight routes. SAN Electro Heat anchors Nordic market share through extreme-temperature product validation. NIBE Element Railway Solutions specializes in integrated control architectures that reduce energy consumption across Scandinavian infrastructure managers.
Rail switch point heating systems are electromechanical assemblies designed to maintain switch blade and stock rail temperatures above freezing thresholds, typically employing resistive heating elements rated between 50 and 400 watts per meter alongside thermostatic or sensor-driven control units. These systems prevent ice accumulation that causes switching failures, ensuring continuous rail traffic flow in subzero environments. Electric heating products command the largest installed base due to straightforward retrofit compatibility, while smart heating systems represent the fastest-expanding technology category as rail operators prioritize remote diagnostics and predictive energy management. Conductor rail systems occupy a mature niche concentrated in legacy tram networks where third-rail electrification already exists.
The European Union Agency for Railways enforces interoperability standards that mandate thermal performance testing for switch heating equipment deployed on transnational corridors. In North America, the Federal Railroad Administration's winter operations guidelines indirectly shape procurement specifications by linking on-time performance metrics to switch reliability. China's National Railway Administration GB standards require domestic suppliers to certify heating systems for plateau and desert cold conditions. Stakeholders must monitor how decarbonization timelines in Germany and France convert fossil-heated switch installations to grid-powered alternatives without disrupting existing signaling infrastructure.
Market Dynamics
Electrification mandates across cold-climate rail networks are forcing infrastructure managers to retire gas-fired switch heating systems, creating a wholesale equipment replacement cycle that favors suppliers with validated electric heating architectures and integrated control platforms.
Growth Catalysts
- EU Agency for Railways Interoperability Mandates:Transnational corridor standards require thermal performance certification for switch heating equipment, filtering procurement toward pre-qualified electric system vendors.
- Heavy Freight Corridor Expansion:Canada's Arctic Gateway and Scandinavia's Malmbanan iron ore lines are procuring redundant heating units to eliminate winter service interruptions.
- Predictive Control Architectures:Sensor-driven heating management systems reduce energy consumption by modulating output against real-time weather data and rail temperature readings.
Market Restraints
- Copper and Aluminum Input Volatility:Resistive heating element production depends on conductor metal prices that swing with commodity cycles, compressing margin visibility for system integrators.
- Legacy Signaling Integration Risk:Retrofitting electric heating into existing switch machines risks electromagnetic interference with track circuits, requiring costly shielding redesigns.
- Specialized Installation Labor Scarcity:Qualified rail electricians capable of field-wiring heating systems in live track environments concentrate in mature European and North American markets.
Strategic Opportunities
- Russia's Trans-Siberian Modernization Zones:Network expansion east of the Urals lacks established heating infrastructure, opening first-mover positioning for electric system suppliers.
- France-Germany Decarbonization Timelines:National rail decarbonization commitments mandate fossil-heated switch conversion, creating sustained retrofit demand through the 2030s.
- Remote Diagnostics Convergence:Integration of heating controllers with centralized traffic management platforms enables predictive maintenance contracts and recurring software revenue streams.
Industry Challenges
- EN 50121 Electromagnetic Certification Timelines:European rail EMC validation requires 12-18 month test cycles, delaying market entry for new suppliers.
- Legacy Pneumatic System Interoperability:Mixed fleets of gas-fired and electric heating complicate maintenance training and spare parts logistics for infrastructure managers.
- Extreme Cold Validation Gaps:Laboratory testing at minus 40 degrees Celsius does not replicate wind-chill and ice-loading conditions found on exposed Nordic and Canadian routes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rail Switch Point Heating System Market |
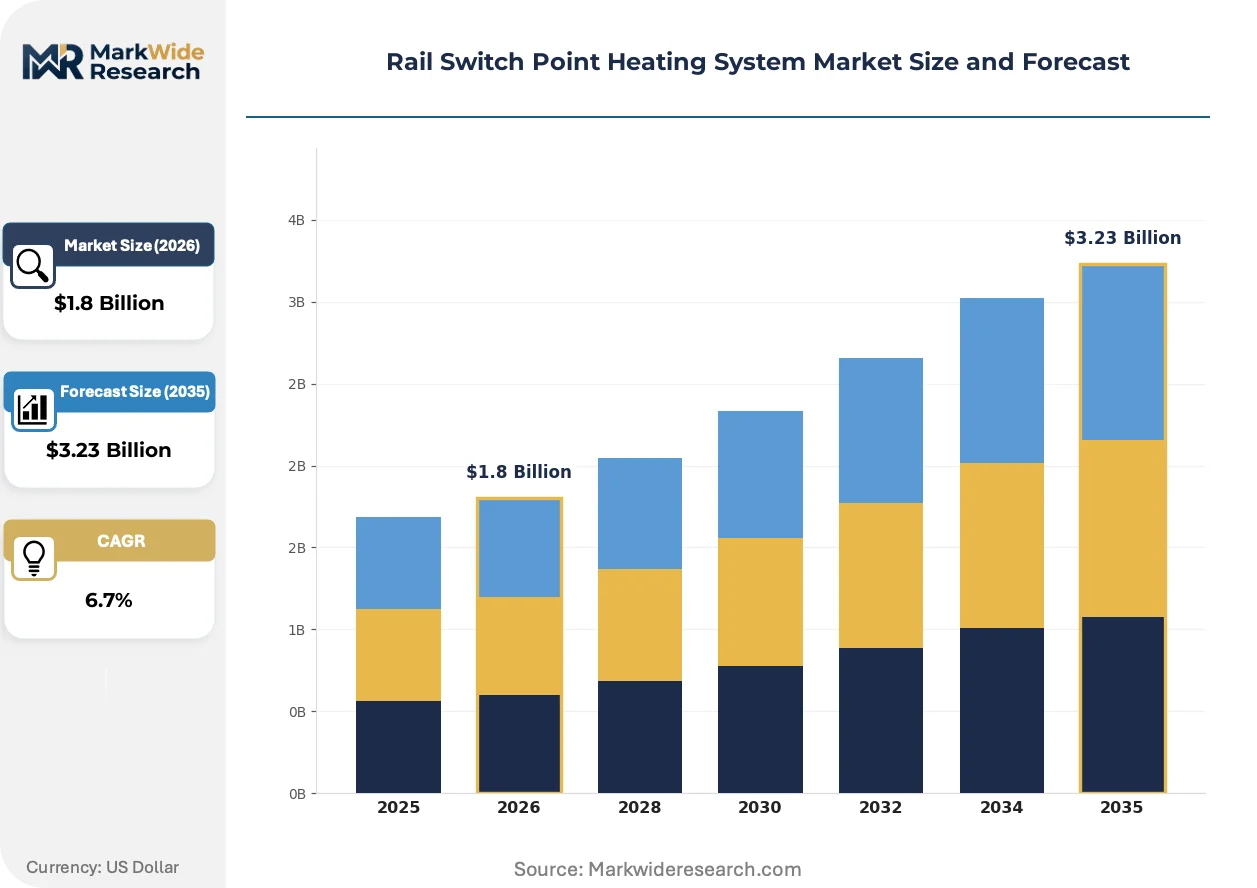
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Heating, Conductor Rail Systems, Infrared Heating, Fluid Heating Technology: Smart Heating Systems, Conventional Heating, Induction Heating, Heat Trace End User: Rail Operators, Infrastructure Managers, Construction Companies, Maintenance Services Installation: New Installations, Retrofits, Upgrades, Seasonal Maintenance |
| Companies Covered | Thermon, SAN Electro Heat, ORIGO SwitchPoint Heating, Caloplex GmbH, NIBE Element Railway Solutions, PINTSCH ABEN, GrayBar, Western Sierras, Hot Switch Heating Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rail Switch Point Heating System Market Emerging Trajectories
Digitalization of rail infrastructure is embedding intelligence into traditionally electromechanical heating systems, shifting competitive advantage toward vendors with software-defined control platforms and remote service capabilities.
Self-regulating polymer heating cables are supplanting fixed-resistance mineral-insulated elements in new installations. Scandinavian infrastructure managers including Trafikverket and Bane NOR have standardized procurement specifications around these adaptive conductor technologies. The shift is compressing demand for conventional constant-wattage systems while elevating suppliers with polymer extrusion and semiconductor doping expertise.
REACH restrictions on per- and polyfluoroalkyl substances are phasing out certain fluoropolymer cable jackets previously standard in heating element construction. European manufacturers are reformulating insulation compounds to maintain dielectric performance without restricted chemistries. Heating cable suppliers with in-house materials laboratories are securing preferential placement on Swedish and Norwegian rail authority approved vendor lists.
Performance-based maintenance contracts are displacing traditional equipment purchase-and-own models among Nordic infrastructure managers. Contractors now guarantee switch availability metrics rather than simply delivering hardware, transferring operational risk to system integrators. This restructuring concentrates procurement authority with full-service providers capable of remote monitoring and rapid-response field teams, most visible in Finland's VR Group and Norway's Bane NOR tendering patterns.
Rail Switch Point Heating System Market Segmentation
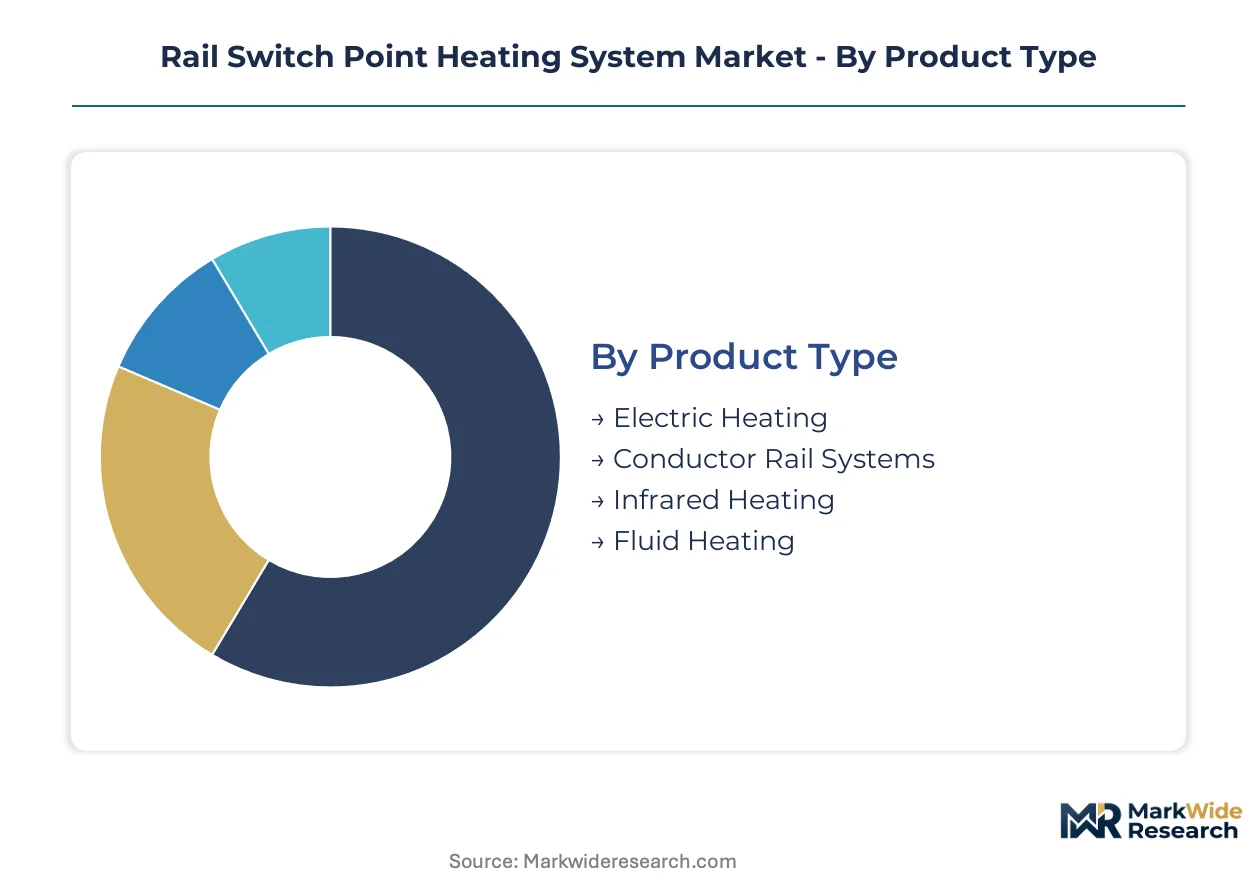
Rail switch point heating procurement fragments across four distinct category axes, each with divergent margin structures and technology maturity profiles. Infrastructure managers weight total lifecycle cost against electromagnetic compatibility certification requirements when selecting across these dimensions.
Product Type:
Margin pools concentrate in systems offering seamless retrofit compatibility and validated cold-climate performance documentation.
- Electric Heating:Resistive elements rated 50-400 watts per meter dominate installed base through straightforward integration with existing switch machines. Scandinavian infrastructure managers including Trafikverket and Bane NOR have standardized procurement around self-regulating polymer cable variants that modulate output against ambient temperature swings.
- Conductor Rail Systems:Third-rail heating configurations persist in legacy tram networks where electrification infrastructure already exists. Demand concentrates in Central European urban transit authorities maintaining century-old track configurations without budget for comprehensive switch replacement.
- Infrared Heating:Radiant panel installations serve specialized applications requiring targeted ice removal without direct element contact.
- Fluid Heating:Circulating glycol systems retain niche presence in extreme cold zones where resistive elements risk thermal runaway.
Electric Heating holds installed capacity. Smart polymer variants within this category are rotating up the share rankings.
Technology:
Revenue concentration tracks toward platforms enabling remote diagnostics and predictive energy modulation capabilities.
- Smart Heating Systems:Sensor-driven controllers integrate with centralized traffic management platforms, enabling condition-based maintenance contracts. Nordic rail operators prioritize these architectures for Malmbanan and Arctic Gateway corridors where winter service interruptions carry severe penalty clauses.
- Conventional Heating:Thermostatic on-off control units retain cost advantage in budget-constrained maintenance cycles. Eastern European infrastructure managers continue procurement where electromagnetic recertification costs outweigh efficiency gains.
- Induction Heating:Eddy-current warming eliminates direct element exposure to mechanical wear and corrosive de-icing chemicals.
- Heat Trace:Mineral-insulated cable assemblies persist in heavy freight applications requiring maximum watt density per meter.
Conventional Heating holds installed capacity. Smart Heating Systems are climbing the fastest as performance-based maintenance contracts displace equipment purchase models.
End User:
Procurement authority concentrates with entities bearing operational risk for winter service continuity.
- Infrastructure Managers:Track asset owners including Sweden's Trafikverket and Norway's Bane NOR specify heating systems within integrated switch machine tenders. These organizations transfer availability risk to contractors through outcome-based maintenance agreements.
- Rail Operators:Freight carriers on Canada's Arctic Gateway and Russia's Trans-Siberian network procure redundant heating units to protect on-time performance metrics.
- Maintenance Services:Specialized contractors source replacement elements for field deployment during seasonal preparation windows.
- Construction Companies:Greenfield high-speed rail projects in Nordic zones specify heating during initial trackbed commissioning.
Infrastructure Managers hold installed capacity. Rail Operators are gaining share fastest as corridor-specific reliability mandates tighten.
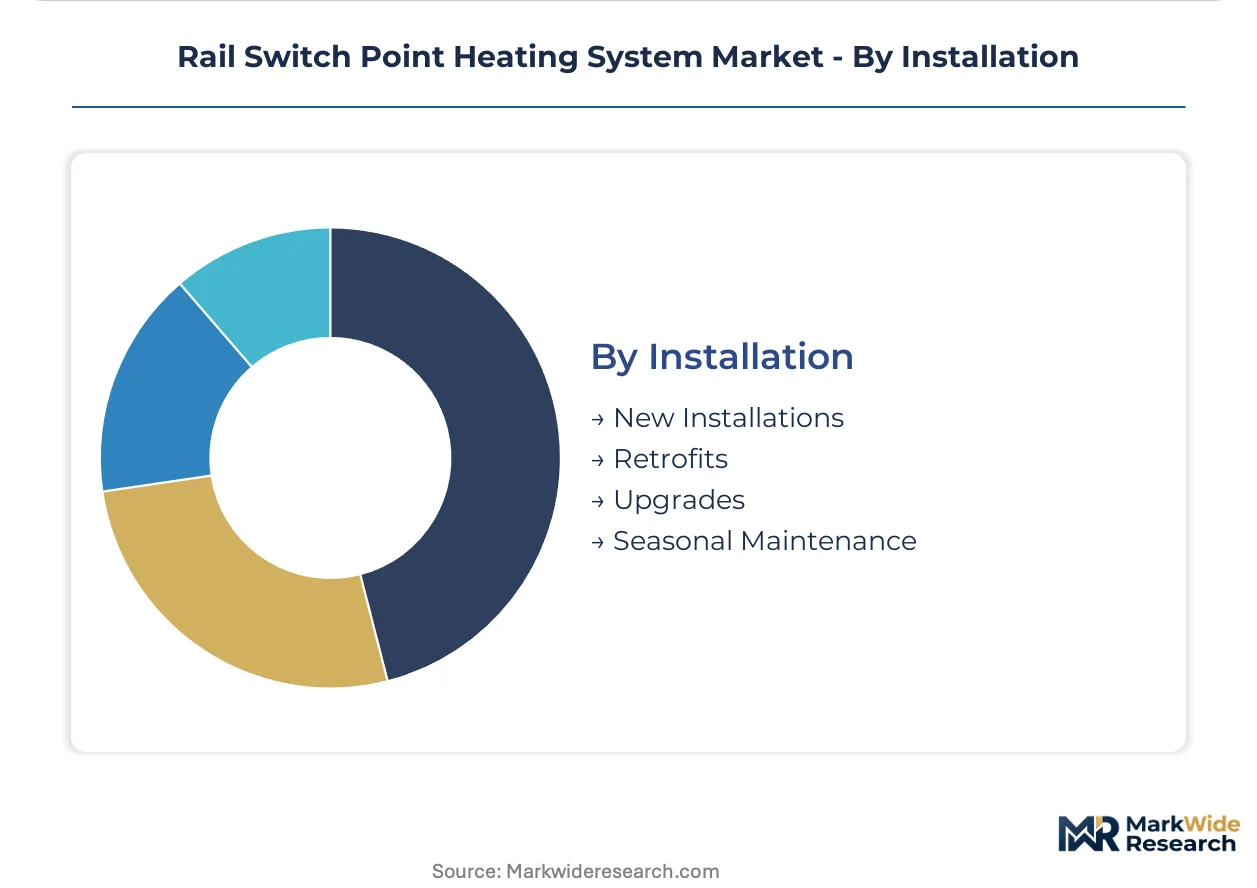
Installation:
Project margins diverge sharply between live-track retrofit complexity and greenfield commissioning efficiency.
- Retrofits:Electromagnetic interference shielding redesigns dominate cost structure when integrating electric heating into legacy switch machines with existing track circuits. France-Germany decarbonization timelines are sustaining retrofit demand through fossil-heated switch conversion programs.
- New Installations:Greenfield high-speed rail projects in Nordic zones and Russia's Trans-Siberian expansion east of the Urals specify integrated heating during initial construction. These installations avoid legacy signaling compatibility constraints.
- Upgrades:Control system replacements modernize heating management without full element renewal.
- Seasonal Maintenance:Element testing and controller calibration cycles generate recurring service revenue.
Retrofits hold installed capacity. New Installations are expanding most quickly in corridor expansion zones lacking established heating infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cold-climate rail electrification mandates are redirecting capital flows across northern latitudes. Infrastructure managers in Scandinavia, Russia, and Canada now prioritize switch heating procurement within integrated winter reliability programs.
Sweden
Trafikverket's Malmbanan iron ore corridor requires redundant heating units to eliminate freight interruptions below minus 30 degrees Celsius. The Swedish Transport Administration mandates EN 50121 electromagnetic compatibility for all new switch installations. Luleå and Kiruna anchor procurement concentration as Arctic Gateway freight volumes expand.
Norway
Bane NOR's performance-based maintenance contracts transfer operational risk to heating system integrators. The Norwegian Railway Directorate enforces extreme-temperature validation protocols exceeding standard laboratory testing. Bergen-Oslo corridor electrification drives retrofit demand through fossil-heated switch conversion.
Canada
CN Rail and CP Kansas City procure switch heating for Arctic Gateway heavy freight routes. Transport Canada's winter operations guidelines link on-time performance metrics to switch reliability specifications. Edmonton and Winnipeg concentrate installation activity where prairie wind-chill conditions exceed design thresholds.
Russia
Russian Railways expands heating infrastructure east of the Urals along Trans-Siberian modernization zones. The national rail operator's technical regulations require plateau and desert cold certification for heating equipment. Novosibirsk and Irkutsk emerge as procurement hubs where established heating infrastructure remains absent.
Germany
Deutsche Bahn's decarbonization timeline mandates conversion of gas-fired switch heating to grid-powered alternatives. The Federal Railway Authority enforces interoperability standards for transnational corridor equipment. Bavaria and North Rhine-Westphalia concentrate retrofit activity where legacy signaling integration risks complicate electromagnetic shielding redesigns.
Rail Switch Point Heating System Market Vendor Landscape
Player mix skews toward specialized heating engineering firms with validated rail credentials rather than diversified industrial conglomerates. Market structure concentrates procurement authority with vendors holding pre-qualified status on Scandinavian and North American infrastructure manager approved lists. Two archetypes dominate: heat-trace engineering heritage companies and integrated control architecture specialists. Competitive moves center on electromagnetic certification pre-qualification and performance-based maintenance contract capture.
Among Nordic specialists, SAN Electro Heat and NIBE Element Railway Solutions exemplify the extreme-temperature validation archetype. Thermon anchors North American positioning through freight corridor relationships. Caloplex GmbH occupies the integrated control systems tier alongside PINTSCH ABEN, which represents the Central European signaling heritage segment. These three anchors—Thermon, SAN Electro Heat, and NIBE Element Railway Solutions—sit within distinct geographic and technological positioning brackets.
| Leading Market Players |
|---|
| Thermon |
| SAN Electro Heat |
| ORIGO SwitchPoint Heating |
| Caloplex GmbH |
| NIBE Element Railway Solutions |
| PINTSCH ABEN |
| GrayBar |
| Western Sierras |
| Hot Switch Heating Systems |
| Others |
Supply Flow & Price Mechanics
EN 50121 electromagnetic compatibility certification gates both supplier qualification and price differentiation in rail switch point heating procurement. Infrastructure managers filter procurement toward pre-qualified vendors while paying premiums for validated extreme-temperature performance documentation.
Pricing Analysis
Certification level creates the primary spread across pricing tiers, with EN 50121-validated systems commanding substantial premiums over uncertified alternatives. Project-based pricing dominates, with differentiation driven by cold-climate validation depth and integrated control architecture sophistication. Cost compression in conventional constant-wattage segments intensifies as self-regulating polymer technologies displace legacy mineral-insulated elements. Eastern European infrastructure managers exhibit highest price sensitivity, while Nordic corridor operators prioritize availability guarantees over unit economics.
Supply Chain Analysis
Specialized polymer extrusion capacity concentrates in Germany, Sweden, and Norway, creating input bottlenecks for self-regulating cable production. Resistive heating element manufacturing draws from copper and aluminum conductor feedstocks sourced through European metal exchanges. Single-source vulnerability runs through semiconductor doping facilities supplying temperature-responsive polymer cores. Distribution runs through rail authority approved vendor lists that pre-qualify integrators for tender participation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across cold-climate corridors creates niche positioning opportunities for specialized heating engineering firms. Electrification mandates and decarbonization timelines fragment demand across retrofit, greenfield, and upgrade installation categories.
For Market Incumbents: Consolidate certification pre-qualification status through accelerated EN 50121 validation investments to defend against emerging polymer specialists. Deepen backward integration into semiconductor-doped polymer extrusion to capture margin pools shifting from mineral-insulated legacy architectures. Lock in performance-based maintenance contracts with Nordic infrastructure managers before control platform convergence commoditizes hardware differentiation.
For New Entrants and Emerging Players: EN 50121 fast-track validation programs in Central European test laboratories open corridor-specific positioning without full 18-month certification cycles. Target Russia's Trans-Siberian expansion zones east of the Urals where established heating infrastructure remains absent and first-mover positioning is achievable. Lead with remote diagnostics integration as the primary go-to-market wedge against incumbent hardware-centric positioning.
For Investors and Strategic Acquirers: France-Germany decarbonization timelines reshape the acquisition landscape toward electric heating specialists with fossil-to-grid conversion expertise. Five-to-ten-year viability favors full-service providers capable of outcome-based maintenance contracts rather than pure equipment manufacturers. Monitor tender patterns from Finland's VR Group and Norway's Bane NOR as early signals of performance-based contract standardization across Nordic markets.
| Strategic Initiative | Industry Significance |
|---|---|
| EN 50121 Certification Acceleration | European rail EMC validation pre-qualifies vendors for transnational corridor procurement. |
| Polymer Extrusion Integration | Backward control over self-regulating cable production secures margin in fastest-growing technology segment. |
| Remote Diagnostics Platform Development | Software-defined control architectures enable recurring revenue through predictive maintenance contracts. |
| Performance-Based Maintenance Contracting | Outcome-based agreements with Bane NOR and Trafikverket transfer operational risk to system integrators. |
| Trans-Siberian Corridor Market Entry | First-mover positioning in Russian Railways expansion zones captures greenfield installation demand. |
Methodological Framework
A spread of perspectives from infrastructure procurement directors, rail authority technical specifications leads, heating system integrators, and polymer materials engineers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through European Union Agency for Railways interoperability documentation, national rail administration tender databases, and supplier certification registries. Bottom-up installation volume estimates triangulated against top-down infrastructure capital expenditure allocations across the analysis window.
Segmentation dimensions modeled include product type, technology architecture, end-user category, and installation context across the projection horizon. CAGRs derived from corridor-specific procurement pipelines weighted by electrification mandate enforcement timelines. Forecast inputs incorporated weather severity indices for Nordic and Canadian routes alongside regulatory compliance deadline schedules.
Underlying assumptions cover sustained electrification policy enforcement and copper price stability, with deviation risk concentrated in electromagnetic certification timeline extensions and legacy signaling integration complexity. Practitioners should keep alternative scenarios live as Russia's Trans-Siberian expansion pacing and EU decarbonization subsidy allocation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Railway Roof Switches Market
Railway Transportation
Railway Station Lighting Market
Railway Transportation
Train Transformer Market
Railway Transportation
Point Machine Market
Railway Transportation
China-Europe Rail Freight Transport Market
Railway Transportation
Railway Couplers Market
Railway Transportation
Railway Li-Ion Battery Market
Railway Transportation
Global Rail Freight Transport Market
Railway Transportation
Automatic Train Protection Signaling Market
Railway Transportation
Canada Rail Freight Transport Market
Railway Transportation
Urban Rail Transit Market
Railway Transportation
United States Rail Freight Transport Market
Railway Transportation
Rail Fasteners Market
Railway Transportation
Australia Rail Freight Transport Market
Railway Transportation
Radar and Lidar Technology for Railways Application Market
Railway Transportation
Autonomous Train Technology Market