
 Automotive Displacement Sensor Market | 2026-2036
Automotive Displacement Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Displacement Sensor Market Intelligence
The ISO 26262 functional safety standard is hardening the design and validation requirements for automotive-grade sensors, increasing development costs. This environment favors established suppliers with extensive R&D capabilities. For instance, Bosch leverages its scale in automotive electronics to meet stringent validation protocols. TE Connectivity differentiates through its specialization in harsh-environment sensor interconnectivity, while Continental competes on integrated system solutions for powertrain and safety applications.
An automotive displacement sensor is an electromechanical device that measures the linear or angular position of a vehicle component, converting physical movement into an electrical signal. These sensors operate on principles including inductive, capacitive, or optical methods to provide precise feedback for control units. Within the market, non-contact technologies like inductive and magnetic sensors are displacing older potentiometric types due to superior durability. Application demand is led by powertrain systems for throttle and pedal positioning, but suspension systems represent the fastest-growing segment for active ride control.
Regulatory frameworks directly influence sensor design and material selection. The EU’s REACH regulation restricts certain hazardous substances in electronic components, while US EPA emission standards necessitate high-precision sensors in powertrain management. In China, compliance with GB standards is mandatory for market access. The critical decision for Tier-1 suppliers and OEMs now revolves around optimizing the architecture between discrete, single-function sensors and integrated, multi-axis sensor fusion modules.
Market Dynamics
The transition toward higher levels of vehicle autonomy is the central force defining the automotive displacement sensor market. This evolution elevates sensors from simple component-position monitors to critical inputs for safety-certified advanced driver-assistance systems and active chassis controls.
Growth Catalysts
- Regulatory Mandates:Stricter vehicle safety standards, including the EU's General Safety Regulation, compel the integration of more sophisticated sensors for functions like electronic stability control and lane-keeping assist, directly driving sensor volume per vehicle.
- Technology Substitution:The shift to non-contact inductive and magnetic sensors from older potentiometric types enhances durability and reliability, particularly in harsh powertrain and chassis environments, expanding addressable applications.
- Application Expansion:Demand from suspension systems for active ride control applications is accelerating, creating new growth vectors beyond traditional throttle and pedal position sensing in internal combustion and electric vehicles.
Market Restraints
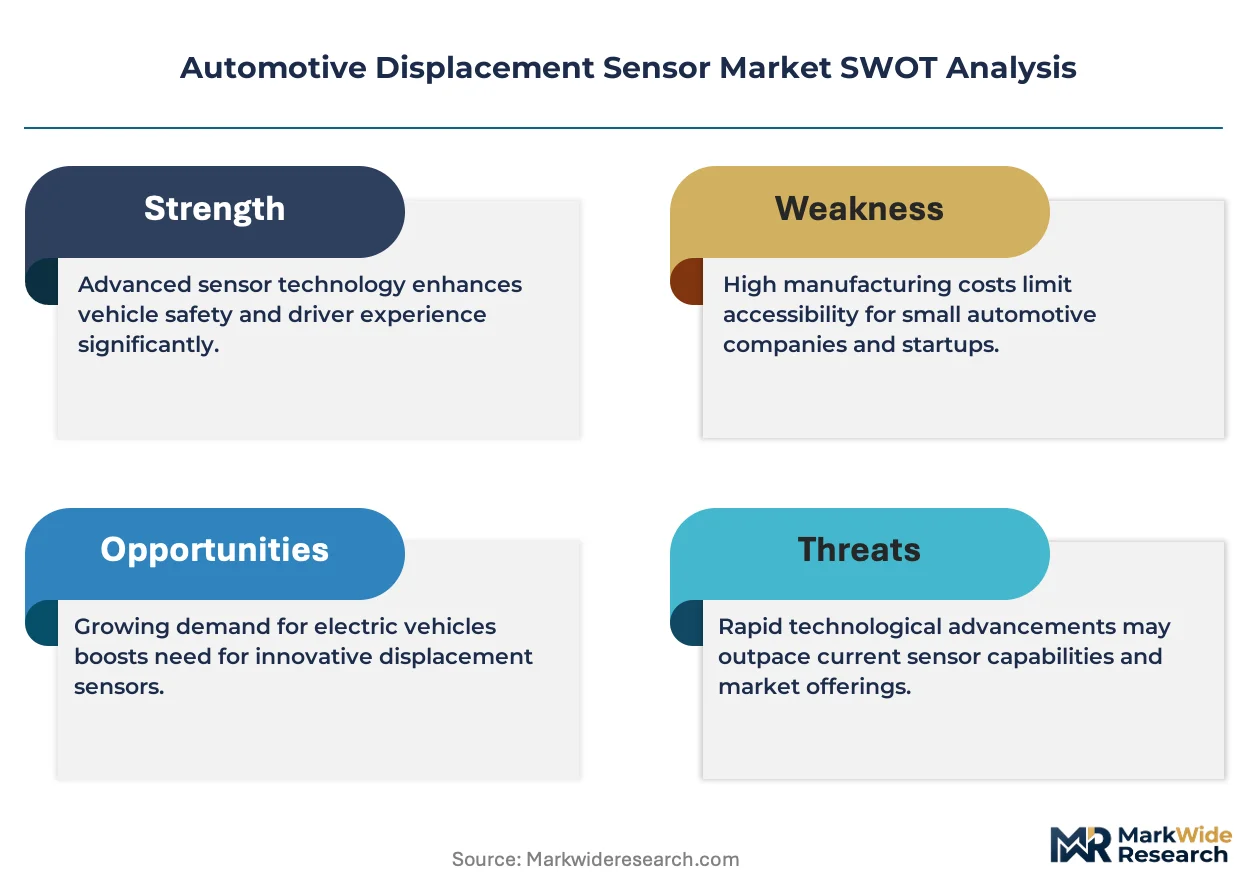
- High Validation Costs:The ISO 26262 functional safety standard imposes rigorous and costly design, testing, and validation protocols, creating high barriers to entry for suppliers without extensive R&D capabilities and automotive certification experience.
- Substitution by Integrated Modules:The development of multi-axis sensor fusion modules, which combine multiple sensing functions into a single unit, presents a substitution threat to discrete, single-function displacement sensors in certain vehicle architectures.
- Material and Substance Regulations:Environmental directives such as the EU's REACH regulation restrict the use of certain hazardous substances in electronic components, complicating material sourcing and sensor manufacturing processes for suppliers.
Strategic Opportunities
- Electric Vehicle Systems:The growth of electric vehicles opens new applications in battery thermal management and electric motor position sensing, areas requiring high-precision and durable displacement measurement for optimal efficiency and safety.
- Sensor Fusion Development:An opportunity exists for suppliers to develop smart sensor modules that integrate displacement data with other inputs like temperature and pressure, offering OEMs a more comprehensive data package for vehicle health monitoring.
- Emerging Market Safety Adoption:Growing vehicle production and nascent safety regulations in markets like India and Brazil create opportunities for suppliers to offer proven, cost-effective sensor solutions aligned with evolving regional standards.
Industry Challenges
- System Integration Complexity:Integrating advanced sensor data into legacy electronic control unit (ECU) architectures is a significant technical hurdle, often requiring substantial software redevelopment and validation efforts by automotive OEMs.
- Stringent Certification Pathways:The time and capital required to achieve automotive-grade qualifications and demonstrate compliance with functional safety standards for new sensor designs can delay market entry and strain R&D budgets.
- Specialized Engineering Talent:A shortage of engineers with cross-disciplinary expertise in mechatronics, embedded software, and functional safety standards constrains the ability of suppliers to innovate and scale production of complex sensor systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Displacement Sensor Market |
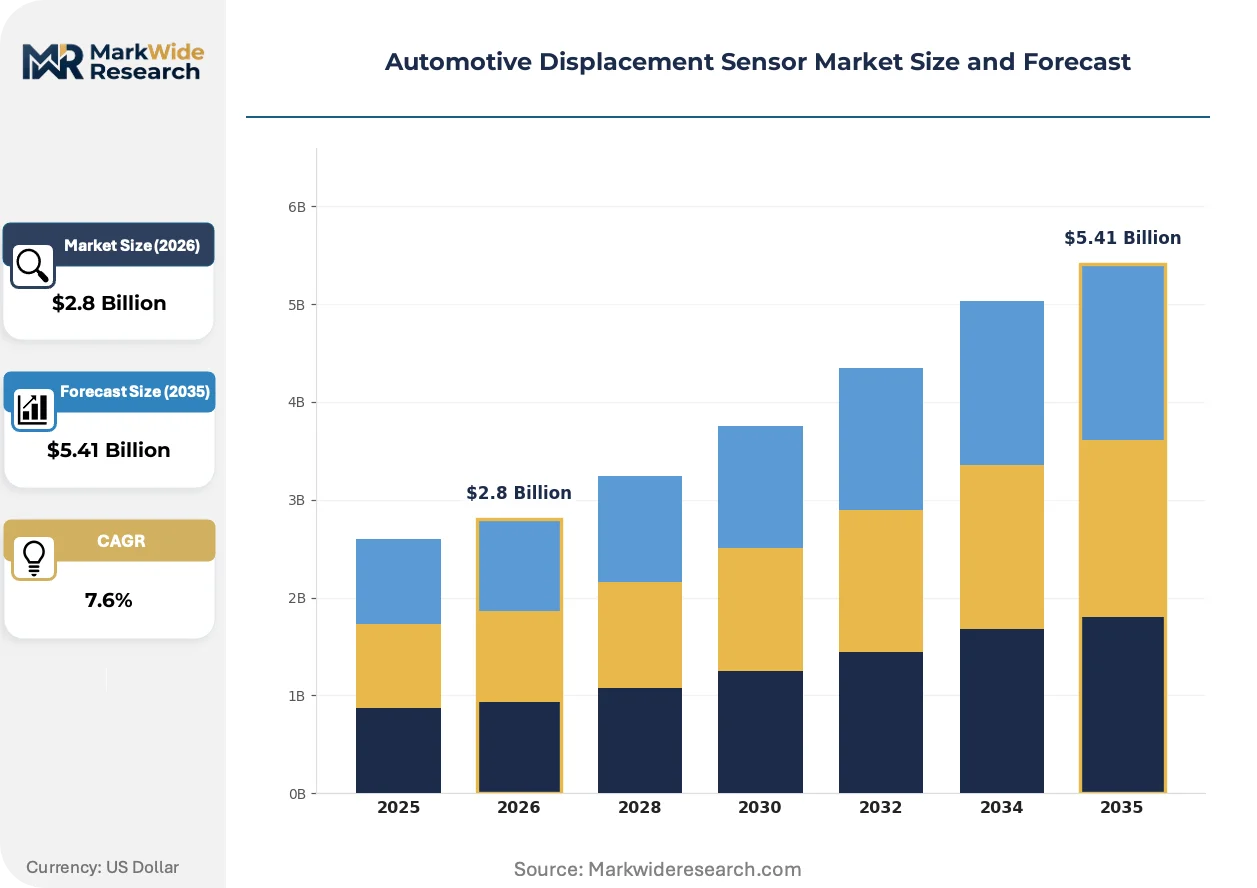
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Potentiometric Sensors, Capacitive Sensors, Inductive Sensors, Ultrasonic Sensors, Eddy Current Sensors Technology: Contact Sensors, Non-Contact Sensors, Magnetic Sensors, Optical Sensors, Piezoelectric Sensors Application: Powertrain Systems, Suspension Systems, Safety Systems, Body Electronics, HVAC Systems End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Tier-1 Suppliers |
| Companies Covered | Bosch, Continental, Denso, Sensata Technologies, TE Connectivity, Honeywell, Infineon Technologies, NXP Semiconductors, Analog Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Displacement Sensor Market Strategic Shifts & Innovations
The market's evolution is defined by a move from component-level measurement to system-level intelligence. This shift is driven by the increasing complexity of vehicle electronics and the software-defined capabilities required for next-generation automotive platforms.
Sensor fusion algorithms are a key enabling technology that combines data from multiple, disparate sensors. Tier-1 suppliers and OEMs are rapidly adopting these algorithms for ADAS and autonomous driving applications. This technology is automating the process of creating a cohesive and reliable perception of the vehicle's environment from numerous individual data points.
Mandatory compliance with China's GB standards for vehicle safety and emissions directly impacts sensor design and market access. These regulations set specific performance and durability criteria for components used in powertrain and safety-critical systems. Consequently, sensor suppliers must invest in localized testing and validation to sell into the world's largest automotive market.
Automotive OEMs are altering their purchasing behavior by sourcing complete, pre-validated subsystems rather than individual discrete components. This trend challenges specialized sensor manufacturers who lack the resources to offer integrated solutions combining hardware and software. The shift is most apparent in Germany and Japan, where the system complexity of premium vehicles drives demand for integrated Tier-1 partnerships.
Automotive Displacement Sensor Market Segmentation
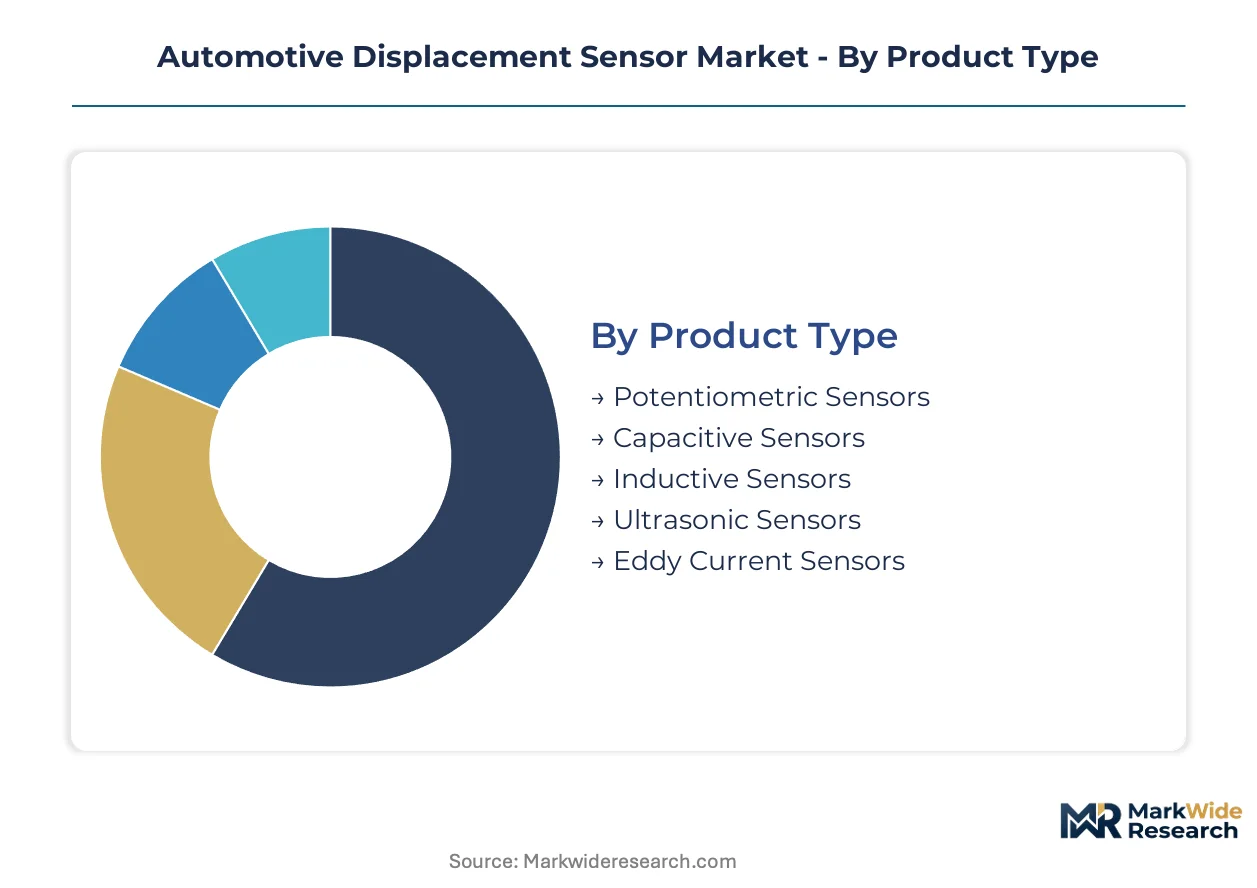
Understanding the Automotive Displacement Sensor Market's segmentation reveals how diverse technological requirements and application demands shape supplier strategies. This analysis highlights the specific product types, underlying technologies, critical vehicle applications, and key end-user groups driving market evolution. Precise segmentation helps stakeholders identify high-growth areas and refine product development efforts across the automotive value chain.
Product Type:
The selection of a displacement sensor product type often hinges on the specific performance requirements for durability, precision, and environmental resilience in automotive systems. Each sensor technology offers distinct advantages for various vehicle functions.
- Inductive Sensors:These non-contact devices operate by measuring changes in an electromagnetic field caused by a moving metallic target, offering exceptional durability and resistance to harsh conditions. Demand is concentrating in powertrain systems and active suspension in Germany and Japan due to their robustness and accuracy.
- Capacitive Sensors:These sensors detect changes in electrical capacitance as a target moves, providing high resolution and precise measurement over short distances. Their application is expanding in advanced driver-assistance systems (ADAS) and occupant detection in South Korea and the US for integrated safety features.
- Potentiometric Sensors:Relying on mechanical contact with a resistive element, these older sensor types offer cost-effectiveness but exhibit lower durability compared to non-contact alternatives.
- Ultrasonic Sensors:These sensors use sound waves to measure distance, finding application in parking assist systems and blind-spot monitoring within vehicle body electronics.
- Eddy Current Sensors:These non-contact sensors detect changes in eddy currents induced in a conductive target, primarily used for high-precision, short-range measurements in specific engine components.
Inductive Sensors leads on scale due to widespread adoption; Capacitive Sensors leads on momentum with increasing integration into advanced vehicle architectures.
Technology:
The underlying sensing technology dictates the operational principles and environmental suitability of automotive displacement sensors for diverse vehicle applications. Technological advancements are driving a shift towards more robust and precise solutions.
- Non-Contact Sensors:These technologies, including inductive and magnetic types, measure displacement without physical contact, ensuring superior longevity and reliability in harsh operating environments. Their adoption is accelerating in chassis control and powertrain management across Europe and Asia.
- Magnetic Sensors:Utilizing Hall effect or magnetoresistive principles, these non-contact sensors provide highly accurate and stable position feedback, particularly valuable for steering and transmission systems. Demand is strong in hybrid and electric vehicle applications in China and the US.
- Contact Sensors:These sensors require physical interaction with the moving component, historically used in throttle position and pedal sensing.
- Optical Sensors:Employing light-based measurement, these sensors offer high precision for specific applications like rotary encoders in steering systems or specific interior controls.
- Piezoelectric Sensors:Generating an electrical charge under mechanical stress, these sensors are used for vibration and force sensing, often in engine knock detection or active suspension.
The shift towards Non-Contact Sensors reflects evolving vehicle architectures, while Contact Sensors maintain foundational importance in cost-sensitive legacy applications.
Application:
Application segments delineate where displacement sensors are integrated within a vehicle, reflecting varying levels of criticality, environmental exposure, and performance requirements. Each area contributes uniquely to overall vehicle functionality and safety.
- Suspension Systems:Displacement sensors here monitor wheel position and ride height, enabling active and semi-active suspension control for enhanced comfort and handling. This segment represents the fastest-growing trajectory due to increasing demand for sophisticated ride control in premium vehicles in Germany and the US.
- Powertrain Systems:Sensors in this segment measure throttle position, pedal travel, and transmission gear selection, crucial for engine management and efficient power delivery. This application holds the largest volume share, particularly in traditional internal combustion engine vehicles across Asia and Europe.
- Safety Systems:Displacement sensors contribute to electronic stability control, brake-by-wire, and airbag deployment, providing critical position data for occupant protection.
- Body Electronics:This segment includes sensors for power windows, seat adjustment, and sunroof position, enhancing convenience and comfort features within the vehicle cabin.
- HVAC Systems:Sensors in heating, ventilation, and air conditioning measure flap positions for precise climate control, optimizing passenger comfort and energy efficiency.
Demand concentration is highest in Powertrain Systems, with Suspension Systems showing significant expansion driven by advanced chassis technologies.
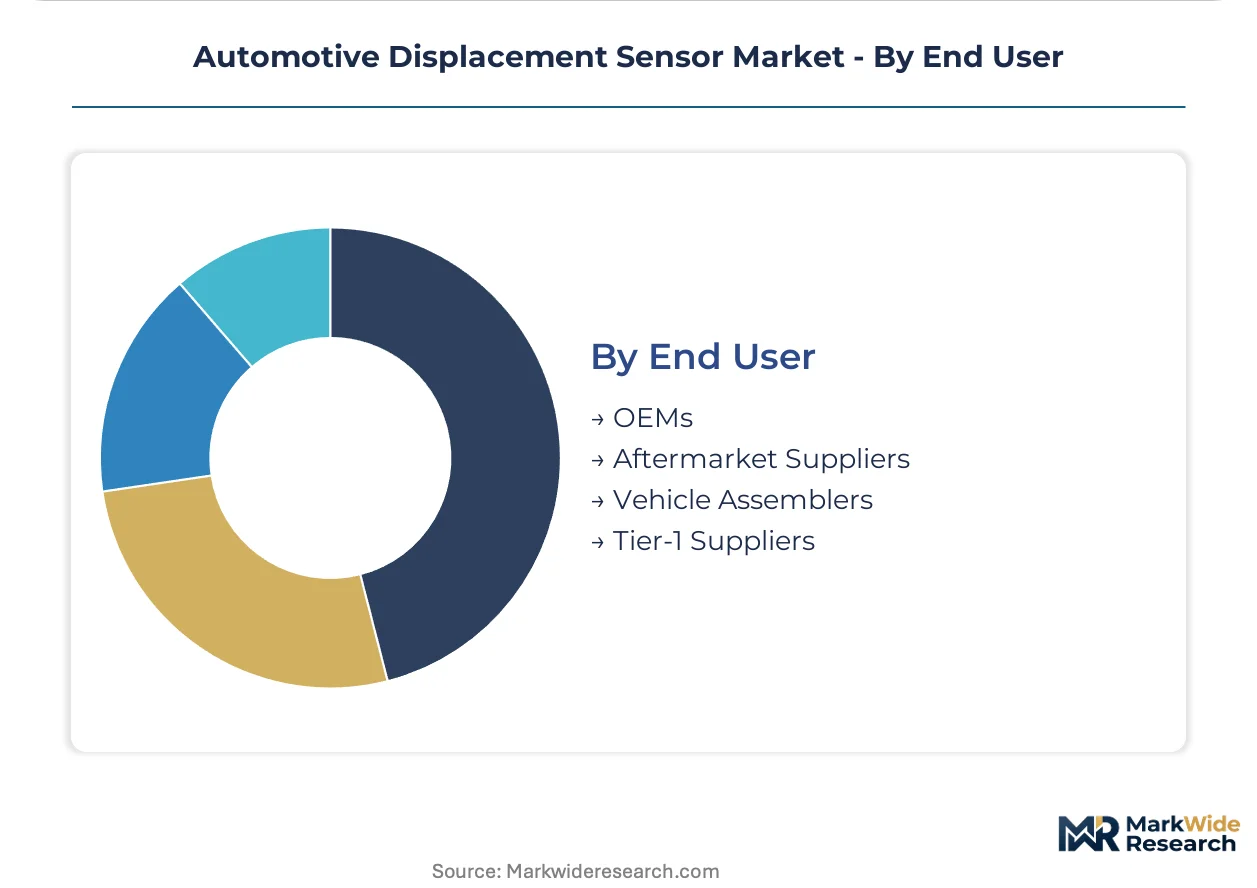
End User:
The end-user landscape illustrates the primary buyers and integrators of automotive displacement sensors, influencing product specifications, volume requirements, and supply chain dynamics. Each user group plays a distinct role in sensor procurement and deployment.
- OEMs:Original Equipment Manufacturers directly integrate displacement sensors into their vehicle designs and production lines, demanding high-volume supply, stringent quality, and functional safety compliance. Major procurement hubs are in Germany, Japan, and the US for new vehicle platforms.
- Tier-1 Suppliers:These companies act as system integrators, purchasing sensors from component manufacturers and delivering pre-validated subsystems to OEMs. They are crucial for developing complex modules for ADAS and powertrain control in regions like Europe and China.
- Aftermarket Suppliers:These entities provide replacement displacement sensors for vehicle repair and maintenance, focusing on compatibility with existing vehicle models.
- Vehicle Assemblers:These players focus on the final assembly of vehicles, procuring sensors as part of larger modules or pre-assembled components from Tier-1 suppliers.
The procurement landscape is dominated by OEMs, with Tier-1 Suppliers influencing component specifications through system integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The concentration of highly skilled automotive engineers and R&D talent anchors significant innovation in automotive displacement sensors. This talent pool drives advanced sensor development for next-generation vehicle platforms. Global automotive production centers leverage this expertise to meet evolving safety and performance standards.
Germany
Germany's engineering workforce drives demand for inductive sensors in powertrain systems and active suspension. The EU's General Safety Regulation compels sophisticated sensor integration for electronic stability control. The Stuttgart region, a premium vehicle hub, advances sensor integration for active ride control.
Japan
Japanese manufacturers prioritize durable inductive sensors for powertrain and active suspension applications. Compliance with JIS standards mandates specific performance criteria for critical components. Nagoya's automotive cluster develops integrated sensor solutions for advanced driver-assistance systems.
South Korea
South Korean OEMs integrate capacitive sensors into ADAS and occupant detection systems. MFDS regulations influence rigorous validation protocols for automotive safety components. Seoul's technology parks foster innovation in sensor fusion modules for integrated safety features.
China
China's expanding electric vehicle market creates demand for magnetic sensors in motor position sensing. Compliance with GB standards is mandatory for market access and component performance. The Yangtze River Delta region drives magnetic sensor adoption for new energy vehicle powertrains.
United States
United States vehicle manufacturers prioritize advanced displacement sensors for active ride control in suspension systems. NHTSA mandates influence the integration of sophisticated sensors for enhanced vehicle safety. Detroit's automotive corridor actively develops sensor-driven chassis controls for premium vehicles.
Automotive Displacement Sensor Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists for market share in automotive displacement sensors. The market exhibits a tiered structure, with large automotive electronics suppliers offering integrated solutions. Smaller, specialized sensor manufacturers focus on niche applications or specific sensor technologies. Companies pursue strategic partnerships and portfolio diversification to enhance their market position.
Within the integrated system solutions tier, Bosch and Continental represent established suppliers leveraging extensive automotive electronics portfolios. These companies exemplify the trend towards offering comprehensive subsystems rather than discrete components to OEMs. TE Connectivity, on the other hand, occupies a position as a specialist in harsh-environment sensor interconnectivity, anchoring solutions for demanding automotive applications. These players continuously adapt their offerings to meet evolving functional safety standards and complex integration requirements for advanced vehicle architectures, driving continuous innovation.
| Leading Market Players |
|---|
| Bosch |
| Continental |
| Denso |
| Sensata Technologies |
| TE Connectivity |
| Honeywell |
| Infineon Technologies |
| NXP Semiconductors |
| Analog Devices |
| Others |
Cost & Logistics Intelligence
Specialized raw material costs for advanced sensor components, such as rare earth elements for magnetic sensors, directly influence the final pricing for OEMs. These upstream material expenses propagate through Tier-1 suppliers, impacting their ability to offer competitive prices for safety-critical modules.
Pricing Analysis
Bundled solutions, encompassing integrated sensor modules with software, command different pricing structures compared to unbundled discrete components. Contract-based long-term offtake agreements dominate transactions between Tier-1 suppliers and OEMs, with price differentiation stemming from ISO 26262 certification levels and order volume scale. Pricing softness reflects intense competition among established suppliers, particularly for high-volume powertrain applications. While OEMs exhibit high price sensitivity for standard components, they prioritize performance and reliability for safety-critical ADAS applications.
Supply Chain Analysis
Reverse logistics for automotive displacement sensors primarily involves end-of-life recycling and failure analysis, rather than widespread refurbishment, due to safety criticality. Supply concentration for advanced sensors is anchored in Germany, Japan, and China, drawing from specialized semiconductor foundries and rare earth element suppliers. Single-source vulnerability for highly specialized components poses a structural risk, compounded by material restrictions like the EU's REACH regulation. Distribution runs through direct channels to OEMs and Tier-1 integrators, bypassing broad aftermarket networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive displacement sensor market acts as a regulatory compounder, with demand significantly amplified by mandates like the EU's General Safety Regulation. This regulation compels the integration of advanced sensors for critical vehicle safety functions.
For Market Incumbents: Hedge against substitution by integrated sensor fusion modules through strategic R&D investment into advanced multi-axis designs. Deepen OEM partnerships by offering pre-validated, software-defined subsystems to meet stringent ISO 26262 compliance requirements. Expand capacity in established automotive production centers like Germany to secure high-volume contracts. Focus R&D on next-generation non-contact technologies that offer superior durability and precision. For New Entrants and Emerging Players: Launch via strategic partnerships with emerging EV manufacturers in China, targeting applications like battery thermal management and motor position sensing. Focus on providing cost-effective, GB standard-compliant magnetic sensor solutions for new energy vehicles. The most penetrable segment lies in specific EV applications where established players face legacy system integration challenges. Develop specialized expertise in niche areas requiring high-precision measurement, such as active ride control for specific vehicle platforms. For Investors and Strategic Acquirers: Consolidation pressure builds where functional safety compliance and integration complexity favor larger, full-stack providers. The market exhibits long-term viability, underpinned by the indispensable role of sensors in advancing ADAS and autonomous driving capabilities for the next five to ten years. Target specialized sensor manufacturers with proprietary non-contact sensing technologies or proven ISO 26262 certification expertise. Practitioners should monitor increasing OEM investment in integrated sensor fusion platforms as a key inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Invest in ISO 26262 Certification | Ensures compliance with stringent functional safety standards, critical for market access in Europe and North America. |
| Develop Sensor Fusion Modules | Offers OEMs comprehensive data packages, reducing integration complexity and enhancing ADAS performance. |
| Expand Non-Contact Sensor Production | Addresses demand for durable, reliable sensors in harsh powertrain and chassis environments. |
| Target EV Battery Management | Captures growth in electric vehicles, requiring high-precision thermal and position sensing. |
| Form OEM Integration Partnerships | Secures long-term contracts and influences vehicle architecture design for next-generation platforms. |
Research Approach
Multiple input streams—primary interviews, secondary research, and proprietary databases—were reconciled to construct a robust market view. Primary engagement included automotive OEM platform engineers, Tier-1 supplier R&D directors, and functional safety specialists. Secondary data sources comprised vehicle production databases, IHS Markit registration data, and relevant regulatory body publications. This approach integrated bottom-up market sizing with top-down validation through expert consensus.
Historical data was cross-referenced with expert panel input to project market trajectory across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, application, end user, and regional vehicle production clusters. Compound annual growth rates derived from regression analysis incorporated anticipated ADAS penetration rates and electric vehicle sales projections. This provided a detailed outlook for the automotive displacement sensor market.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant shifts in global trade policies or unforeseen material supply disruptions. The forecasts reflect current regulatory frameworks and anticipated technological development assumptions. Practitioners should monitor evolving functional safety standards for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Tipper Body Equipment Market
Vehicle Components
GCC Automotive Connectors Market
Vehicle Components
Automotive Sensors Market
Vehicle Components
Trailer Brake Controllers Market
Vehicle Components
Car Sunshade Market
Vehicle Components
4x4 Vehicle Parts and Accessories Market
Vehicle Components
Automotive Rubber Molded Components Market
Vehicle Components
Vehicle-To-X Products Market
Vehicle Components
Thrust Bearings Market
Vehicle Components
Wheel Chocks Market
Vehicle Components
Automotive Position Sensor Market
Vehicle Components
Steering Stabilizers Market
Vehicle Components
Global Automotive Constant Vehicle Joint Boots Market
Vehicle Components
Exhaust Manifolds and Downpipes Market
Vehicle Components
Global Automotive Carbon Fiber Composites Market
Vehicle Components
Global Automotive Rain, Light, Humidity Sensor Market