
 Canada Rail Freight Transport Market | 2026-2036
Canada Rail Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Rail Freight Transport Market Outlook
Mining sector demand for heavy haul capacity is hardening across western corridors. Canadian National Railway leverages its Prairie-to-Pacific network to dominate metallurgical coal and potash movements. Canadian Pacific Kansas City anchors cross-border agricultural flows through integrated U.S.-Mexico routing. Fastfrate competes in the less-than-carload segment through terminal density in Ontario and Quebec.
Canada rail freight transport encompasses the movement of bulk commodities, containerized goods, and specialized cargo via heavy-haul locomotives operating on standard-gauge track at axle loads up to 286,000 pounds, primarily serving resource extraction, manufacturing supply chains, and international trade gateways. Intermodal service leads volume growth as port-rail connectivity deepens at Vancouver and Prince Rupert, while bulk retains the largest revenue pool tied to grain and energy minerals. Predictive analytics is displacing legacy maintenance schedules across Class I networks, reducing downtime through sensor-driven component monitoring.
Transport Canada enforces rail safety standards under the Railway Safety Act, mandating positive train control adoption and track integrity protocols that elevate capital requirements for operators. Environment and Climate Change Canada carbon pricing mechanisms pressure fleet modernization toward lower-emission locomotives. Stakeholders must monitor how CPKC's single-network U.S.-Mexico reach reshapes routing economics against CN's dedicated northern corridor strategy.
Market Dynamics
Positive train control mandates from Transport Canada are forcing capital redeployment across Class I networks, while mining sector demand for heavy haul capacity hardens pricing power on western corridors. This regulatory- demand convergence is restructuring fleet modernization priorities and corridor investment decisions.
Growth Catalysts
- Transport Canada Safety Mandates:Railway Safety Act enforcement accelerates track integrity investments and positive train control adoption, elevating operational standards across Prairie-to-Pacific corridors.
- Metallurgical Coal Extraction:Western Canadian mining operations require dedicated heavy haul infrastructure, sustaining long-term contract volumes for bulk carriers.
- Vancouver-Prince Rupert Port Deepening:Pacific gateway container terminal expansion tightens intermodal connectivity, pulling rail freight demand toward Asia-Pacific trade lanes.
Market Restraints
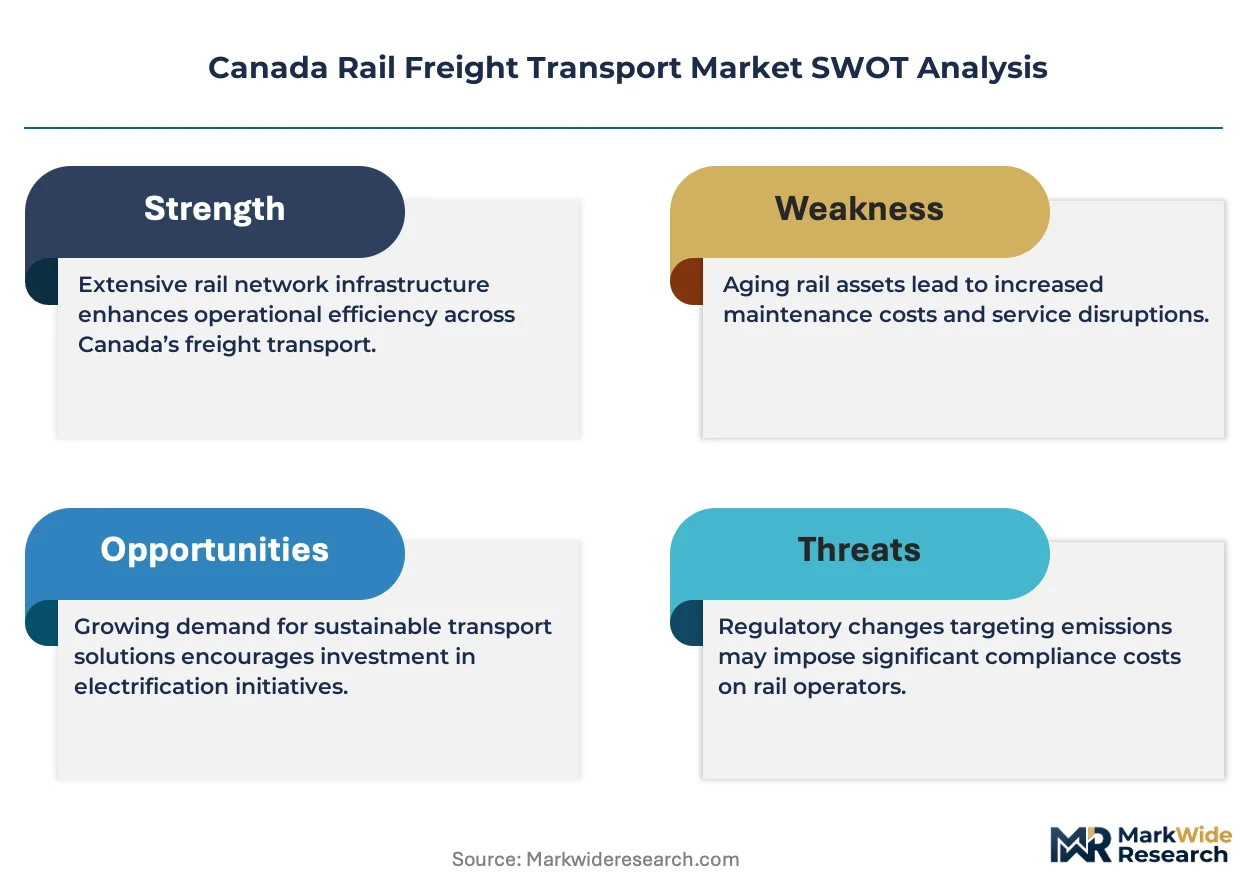
- Locomotive Fleet Electrification Costs:Environment and Climate Change Canada carbon pricing mechanisms impose capital intensity on diesel-to-battery or hydrogen transition timelines.
- Prairie Corridor Concentration:Bulk commodity flows concentrate on limited east-west trunk lines, creating bottleneck vulnerability during peak harvest and energy shipment windows.
- Track Gauge Standardization:Canadian standard-gauge interoperability with U.S. networks limits flexibility for equipment sourcing and maintenance standardization.
Strategic Opportunities
- Cross-Border Agricultural Routing:Integrated U.S.-Mexico corridor access through mid-continent gateways opens volume diversification beyond traditional bulk commodities.
- Predictive Maintenance Analytics:Sensor-driven component monitoring converges with cloud-based fleet management platforms, reducing unplanned downtime across heavy haul operations.
- Ontario-Quebec Terminal Density:Less-than-carload segment consolidation in eastern manufacturing corridors captures manufacturing supply chain reconfiguration toward nearshoring.
Industry Challenges
- Locomotive Engineer Certification Pipeline:Transport Canada-mandated qualification timelines constrain crew availability during peak seasonal demand surges.
- Legacy Signaling System Integration:Positive train control overlay on century-old track infrastructure creates interoperability testing complexity and deployment delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Rail Freight Transport Market |
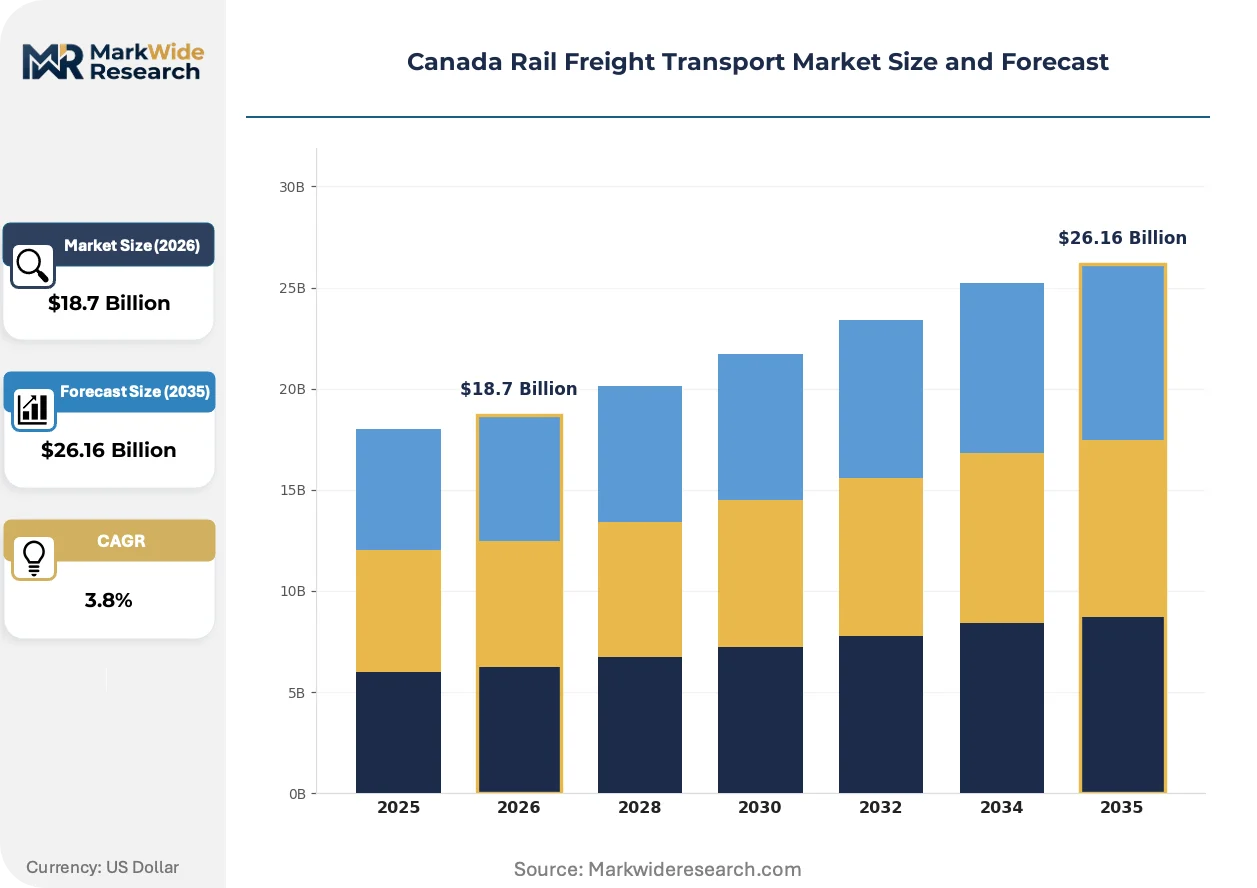
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Intermodal, Bulk, Liquid, Carload End User: Agriculture, Mining, Manufacturing, Retail Technology: GPS Tracking, Autonomous Trains, Predictive Analytics, Rail-Safety Systems Application: Freight Shipping, Supply Chain Logistics, Transit Operations, Heavy Haul Services |
| Companies Covered | eShipper, Fastfrate, Canadian National Railway, Alpha Logistiques, Excel Transportation, Canadian Pacific Kansas City, M3 Transport, Liberate Logistics, Paige Logistics Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Rail Freight Transport Market Strategic Shifts
Battery-electric and hydrogen fuel cell propulsion systems are actively reshaping locomotive procurement criteria, while digital freight matching platforms compress shipper-carrier transaction cycles. These shifts are redrawing capital allocation and service model boundaries.
Hybrid battery-diesel locomotive technology is electrifying yard switching and short-haul corridor operations, cutting idle emissions in Vancouver port terminals and Calgary intermodal facilities. Canadian National Railway and Canadian Pacific Kansas City are piloting fuel cell variants on Prairie branch lines. This electrification is compressing the payback period for fleet modernization against rising carbon compliance costs.
Environment and Climate Change Canada carbon pricing mechanisms are tightening locomotive emission intensity thresholds, forcing accelerated retirement of pre-Tier 4 diesel units. Tier 4 Final compliance deadlines compress equipment replacement windows for operators with aging fleets. Bulk carriers serving mining and agricultural corridors face the steepest retrofit obligations given duty cycle demands.
Shippers are consolidating procurement under multi-year dedicated train contracts, displacing spot market spot transactions on grain and potash corridors. Large agricultural cooperatives and mining operators now prioritize guaranteed capacity over price flexibility. This concentration is most visible across Saskatchewan and Alberta bulk terminals where harvest timing creates acute capacity competition.
Canada Rail Freight Transport Market Segmentation
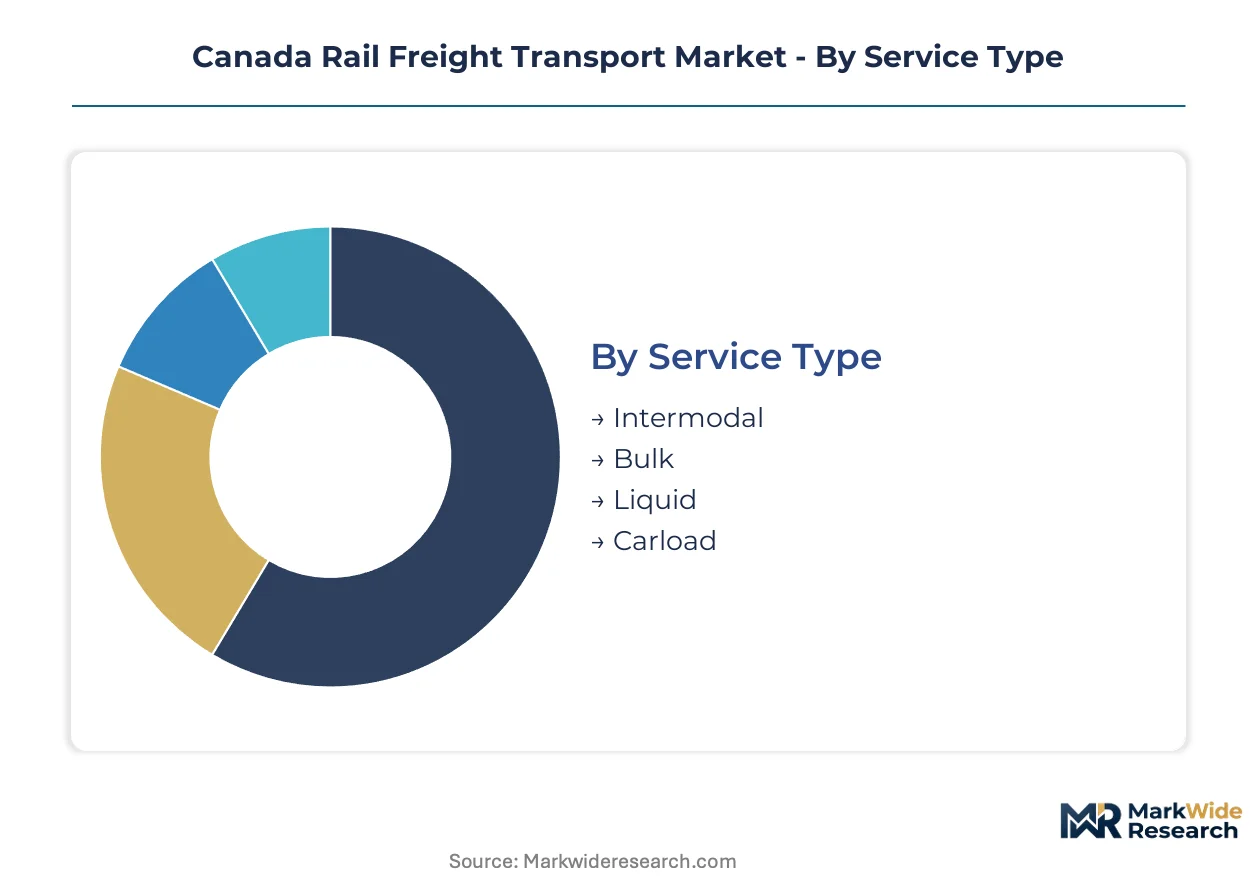
Canada's rail freight market segments along operational, customer, and technology dimensions that determine capital allocation and corridor investment priorities. Service type selection drives equipment procurement cycles, while end-user concentration shapes contract structures and pricing power across Prairie and Pacific corridors.
Service Type:
Shippers select service tiers based on cargo density, velocity requirements, and terminal access economics rather than pure rate minimization.
- Intermodal:Containerized movements combine truck flexibility with rail line-haul economics, serving Vancouver and Prince Rupert port gateways. Asian import volumes through Pacific terminals are hardening demand for dedicated intermodal stack trains.
- Bulk:Unit trains dedicated to single-commodity movements dominate metallurgical coal, potash, and grain corridors with 100-plus car configurations. Saskatchewan and Alberta mining operations sustain long-term contract structures with minimum volume guarantees.
- Liquid:Specialized tank car fleets handle crude oil, refined products, and chemicals with pressure-vessel specifications. Western Canadian energy production requires heated coil cars for heavy crude viscosity management.
- Carload:Mixed manifest services aggregate smaller shipments from multiple shippers into single train consists. Ontario and Quebec manufacturing clusters generate less-than-trainload volumes requiring classification yard processing.
Bulk leads on scale; intermodal leads on momentum.
End User:
Customer sector concentration determines route density and equipment specialization across the Canadian network.
- Mining:Metallurgical coal and potash extraction in British Columbia and Saskatchewan demands 286,000-pound axle load infrastructure. Heavy haul duty cycles accelerate rail and wheel wear, concentrating maintenance spend on western corridors.
- Agriculture:Grain cooperatives and oilseed processors time movements around harvest windows and export vessel loading schedules. Prairie elevator consolidation is lengthening truck hauls to high-throughput terminal elevators.
- Manufacturing:Automotive parts and finished vehicle movements require enclosed autorack equipment with damage-resistant interiors. Ontario assembly plant proximity to U.S. border crossings favors cross-border routing integration.
- Retail:Big-box distribution centers and e-commerce fulfillment nodes drive intermodal demand for time-definite delivery. Toronto and Montreal consumer markets pull container volumes from Pacific gateway terminals.
Mining leads on scale; retail is expanding most quickly.
Technology:
Capital deployment across technology categories reflects regulatory mandates and operational efficiency targets rather than discretionary innovation spending.
- Predictive Analytics:Sensor networks on locomotive traction motors and freight car bearings enable condition-based maintenance scheduling. Canadian National Railway and Canadian Pacific Kansas City have deployed cloud-based fleet monitoring platforms across heavy haul corridors.
- Rail-Safety Systems:Transport Canada mandates positive train control overlay on legacy signaling infrastructure, requiring interoperability testing with century-old track circuits. Deployment timelines compress capital budgets across Class I networks.
- GPS Tracking:Real-time location visibility supports customer service and asset utilization optimization. Intermodal containers and high-value carload shipments carry satellite-linked monitoring devices.
- Autonomous Trains:Remote-controlled yard switching and mainline pilot programs reduce crew costs on low-density branch lines. Regulatory frameworks for unattended mainline operation remain under Transport Canada review.
Rail-safety systems lead on scale; predictive analytics is gaining share fastest.
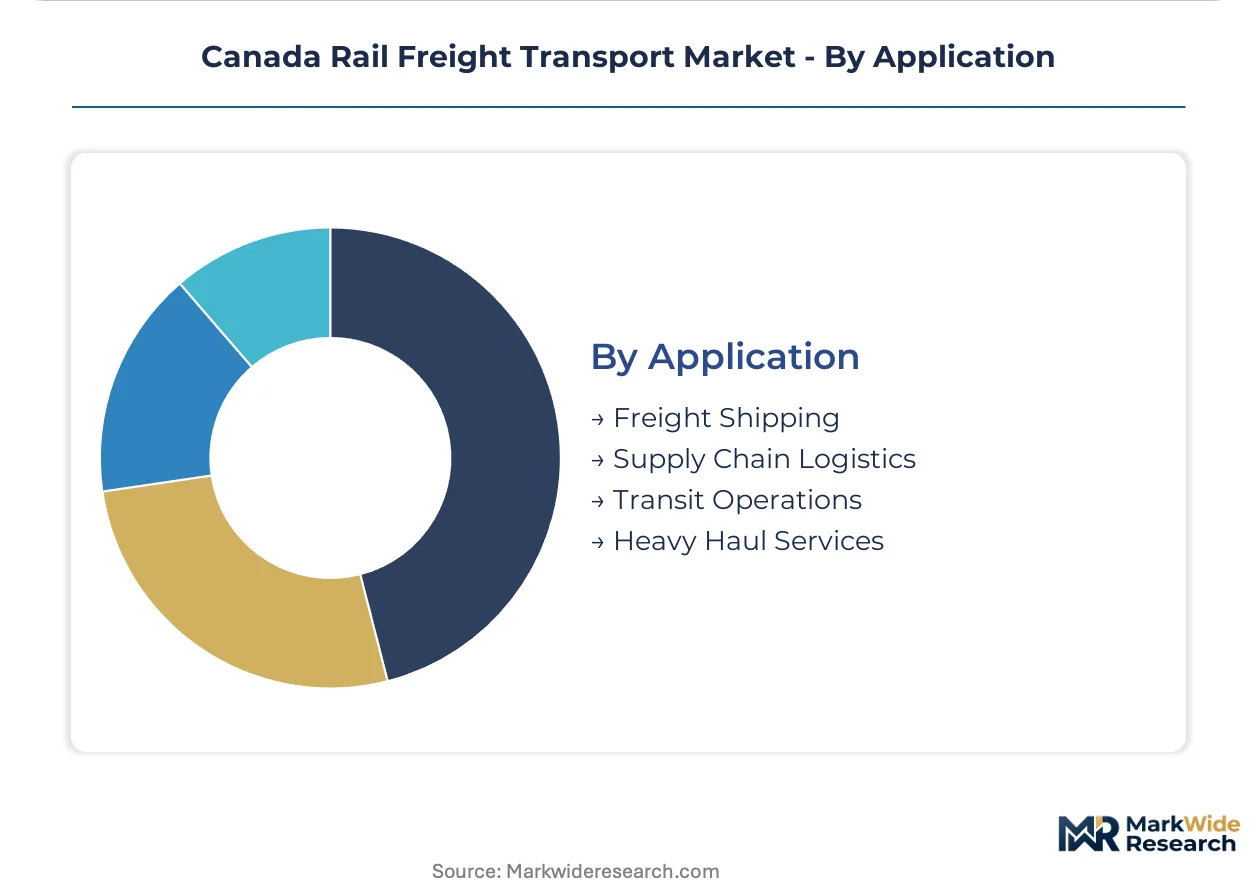
Application:
Functional use cases determine service design and equipment configuration across the operational network.
- Heavy Haul Services:Dedicated bulk corridors operate at maximum permissible axle loads with distributed power configurations managing train momentum across mountain grades. Western Canadian mining and energy movements define infrastructure standards.
- Freight Shipping:Point-to-point carload and intermodal movements constitute core revenue generation for Class I operators. Contract structures range from spot market transactions to multi-year dedicated train agreements.
- Supply Chain Logistics:Integrated door-to-door service bundles rail movement with drayage, transloading, and customs clearance. Third-party logistics providers consolidate procurement across multiple rail carriers.
- Transit Operations:Passenger rail corridor sharing and commuter service access agreements generate trackage rights revenue. Toronto, Montreal, and Vancouver commuter authorities negotiate priority scheduling on freight-owned infrastructure.
Freight shipping leads on scale; supply chain logistics shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are minimal across Canadian provinces given uniform federal rail safety standards under Transport Canada, yet sub-regional demand patterns and infrastructure density create distinct operational economics for carriers serving Prairie bulk corridors versus Ontario-Quebec manufacturing clusters.
Ontario
Toronto and Hamilton manufacturing nodes generate dense less-than-carload volumes for automotive parts and finished vehicles. Transport Canada-mandated positive train control overlays are accelerating capital deployment across the Windsor-Quebec City corridor. The Golden Horseshoe concentration is pulling intermodal demand from Pacific gateway terminals through Chicago routing integration.
Quebec
Montreal port-rail connectivity and aluminum smelting in Saguenay-Lac-Saint-Jean sustain specialized flatcar and tank car movements. Environment and Climate Change Canada carbon pricing mechanisms are pressuring fleet modernization timelines for Quebec-based short-line operators. Quebec City-Trois-Rivières industrial corridor density supports dedicated automotive parts trains to U.S. border crossings.
Alberta
Bitumen upgrading and oil sands extraction require heated coil car fleets for heavy crude viscosity management. Transport Canada track integrity protocols are elevating maintenance spend on Edmonton-Calgary heavy haul infrastructure. The Industrial Heartland northeast of Edmonton concentrates petrochemical movements with dedicated unit train configurations.
British Columbia
Vancouver and Prince Rupert container terminal expansion is hardening demand for dedicated intermodal stack trains to Prairie distribution nodes. Transport Canada safety mandates on mountain grade operations are forcing distributed power configuration upgrades across the Thompson and Fraser Canyon corridors. Lower Mainland port-rail connectivity is tightening vessel-to-train transfer windows for Asia-Pacific import volumes.
Prairie Provinces
Saskatchewan potash and Alberta metallurgical coal extraction sustain 286,000-pound axle load infrastructure standards across CN and CPKC western networks. Transport Canada-mandated crew certification timelines are constraining availability during peak harvest windows. Saskatchewan elevator consolidation is lengthening truck hauls to high-throughput terminal elevators at Unity and Melville.
Canada Rail Freight Transport Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated Class I networks dominating bulk corridors while regional consolidators capture fragmented less-than-carload demand. The market structure concentrates around two national carriers with Prairie-to-Pacific reach, supplemented by Ontario-Quebec terminal density players. Three archetypes define competitive positioning: heavy haul bulk specialists, intermodal port-connectivity integrators, and short-line less-than-carload consolidators. Capacity expansion and strategic partnerships represent the dominant competitive moves, with corridor access agreements and terminal acquisition activity accelerating.
Among the integrated Class I carriers, Canadian National Railway and Canadian Pacific Kansas City occupy positions anchoring national network economics through Prairie bulk corridor dominance and cross-border routing integration. Fastfrate represents the regional consolidator archetype, exemplifying terminal density strategies in Ontario and Quebec manufacturing corridors. These three entities collectively illustrate how scale-driven infrastructure control coexists with niche density-focused service models across distinct geographic and operational segments.
| Leading Market Players |
|---|
| eShipper |
| Fastfrate |
| Canadian National Railway |
| Alpha Logistiques |
| Excel Transportation |
| Canadian Pacific Kansas City |
| M3 Transport |
| Liberate Logistics |
| Paige Logistics Ltd |
| Others |
Value Chain & Pricing Dynamics
The West Texas Intermediate crude benchmark and Prairie grain futures indices cascade through Canadian rail freight pricing tiers, compressing margins on energy corridors while amplifying contract premiums on harvest-dependent agricultural movements. This commodity-price transmission mechanism stratifies carrier pricing power across bulk and intermodal segments.
Pricing Analysis
Distributor margins on third-party logistics arrangements compress pricing transparency for shippers accessing Class I networks through intermediaries. Three-tier pricing structure across premium, standard, and economy levels separates dedicated train contracts with volume guarantees from spot-market manifest services and terminal-access fees. Cost compression in the less-than-carload segment is intensifying because Fastfrate terminal density advantages erode competitor rate cards. Agricultural cooperatives exhibit highest price sensitivity due to harvest-window inflexibility, while mining operators demonstrate lowest sensitivity given metallurgical coal's irreplaceable heavy-haul infrastructure requirements.
Supply Chain Analysis
Single-source vulnerability sits with U.S.-manufactured locomotive power assemblies and Chinese-produced rail fasteners, concentrating procurement risk on trans-Pacific shipping lanes. Equipment sourcing draws from Mexico for rolling stock components, the United States for traction motors, and domestic Canadian foundries for rail steel. Tariff exposure on steel and aluminum inputs threatens fleet modernization timelines under Environment and Climate Change Canada carbon compliance mandates. Distribution runs through Calgary and Winnipeg intermodal terminals as consolidation nodes for Prairie bulk movements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rail freight margin expansion in Canada rests on predictive maintenance analytics reducing unplanned downtime costs and mining sector contract structures hardening toward premium-tier dedicated capacity guarantees.
For Market Incumbents: Cement corridor control through accelerated positive train control deployment on Thompson Canyon mountain grades before Transport Canada enforcement deadlines tighten. Secure backward integration into terminal elevator assets across Saskatchewan to capture grain volume aggregation from cooperative shippers facing Fastfrate intermodal competition. Battery-electric locomotive pilot programs represent the critical R&D lever for carbon pricing compliance. For New Entrants and Emerging Players: The mid-tier pricing gap between premium dedicated-train contracts and economy spot-manifest rates opens white-space entry through short-haul drayage integration at Vancouver and Prince Rupert port terminals. Ontario-Quebec manufacturing corridors offer the most penetrable geography given automotive parts distribution fragmentation. Target third-party logistics procurement consolidation as the go-to-market angle, bundling rail movement with customs clearance and transloading services. For Investors and Strategic Acquirers: Consolidation pressure builds where short-line operators face Tier 4 Final locomotive retrofit obligations exceeding their capital access. Long-term viability favors vertically integrated networks with Prairie-to-Pacific reach and cross-border U.S.-Mexico routing integration. The acquisition target archetype is regional terminal-density players with captive manufacturing corridor access. Watch Transport Canada crew certification pipeline expansion as the signal for capacity constraint relief.| Strategic Initiative | Industry Significance |
|---|---|
| Positive Train Control Deployment | Transport Canada mandates accelerate capital deployment across Class I mountain corridor infrastructure. |
| Battery-Electric Locomotive Pilot Programs | Environment and Climate Change Canada carbon pricing compresses payback periods for fleet modernization. |
| Terminal Elevator Acquisition | Saskatchewan grain cooperative consolidation lengthens truck hauls to high-throughput aggregation points. |
| Cross-Border Routing Integration | CPKC single-network U.S.-Mexico reach reshapes agricultural flow economics against CN northern corridor strategy. |
| Predictive Maintenance Platform Deployment | Sensor-driven component monitoring reduces unplanned downtime across heavy haul operations. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Class I network operations directors, short-line carrier executives, agricultural cooperative logistics managers, mining sector procurement leads, and Transport Canada regulatory affairs specialists with secondary validation through Transport Canada safety filings, Environment and Climate Change Canada emissions disclosures, Canadian National Railway and Canadian Pacific Kansas City securities filings, and Prairie grain terminal throughput statistics. Bottom-up volume modeling and top-down macroeconomic anchoring triangulated market size estimates.
Historical reference periods anchored the projection horizon to pre-pandemic baseline volumes and post-2023 regulatory implementation trajectories. The analytical framework modeled segmentation across service type, end-user sector, technology adoption tier, and regional corridor density. CAGRs derived from equipment procurement cycle analysis and commodity flow elasticity assumptions. Forecast inputs incorporated mining sector capital expenditure pipelines and intermodal container terminal expansion timelines at Vancouver and Prince Rupert.
Caveats apply where Transport Canada crew certification pipeline expansion delays or metallurgical coal demand shifts could materially shift the outlook. Forecasts reflect assumptions about carbon pricing compliance timelines and positive train control deployment schedules. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Rail Testing Vehicle Market
Railway Transportation
Composites in Passenger Rail Market
Railway Transportation
Railway Couplers Market
Railway Transportation
Railway Hydraulic Damper Market
Railway Transportation
Railway Air Conditioning System Market
Railway Transportation
Global Railway Wiring Harness Market
Railway Transportation
Railway Roof Switches Market
Railway Transportation
Global Rail Freight Transport Market
Railway Transportation
Train Transformer Market
Railway Transportation
Railway Traction Inverter Market
Railway Transportation
Railway Li-Ion Battery Market
Railway Transportation
Digital Axle Counter Market
Railway Transportation
Brazil Rail Freight Transport Market
Railway Transportation
Radar and Lidar Technology for Railways Application Market
Railway Transportation
Railway Sleepers Market
Railway Transportation
China-Europe Rail Freight Transport Market