
 Germany Rail Freight Transport Market | 2026-2036
Germany Rail Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Rail Freight Transport Market Foresight
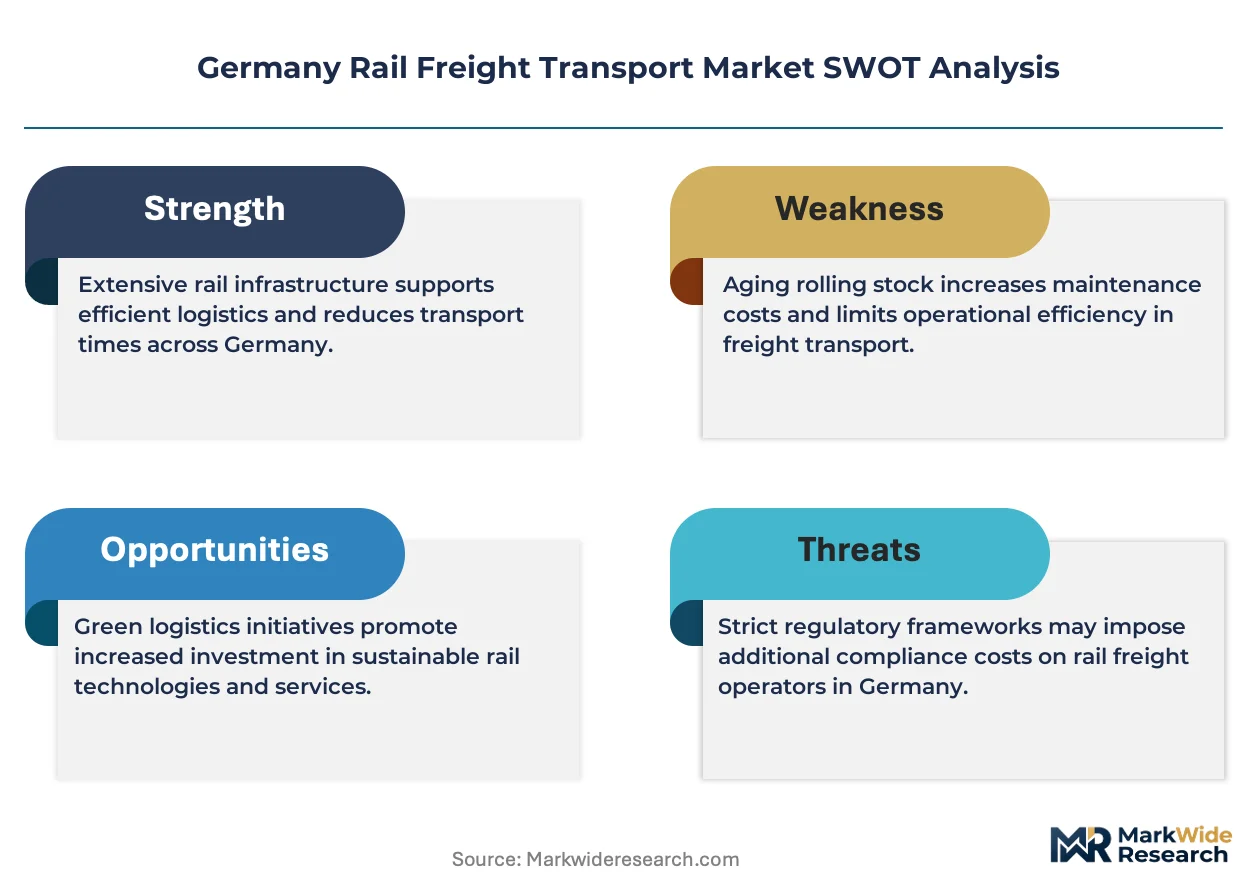
Locomotive engineer shortages and digital signaling expertise deficits is bifurcating the competitive landscape between capital-rich incumbents and agile specialists. DB Cargo AG leverages its integrated terminal network to dominate domestic wagonload flows. TX Logistik AG competes aggressively on cross-border intermodal lanes into Italy and Scandinavia. Captrain anchors its position through specialized chemical tank car services along the Rhine corridor.
Rail freight transport encompasses the movement of goods via steel-wheel-on-steel-rail infrastructure using diesel, electric, or hybrid traction units with axle loads typically ranging from 22.5 to 25 tonnes across European standard gauge networks. Its primary commercial purpose centers on providing cost-efficient, high-volume land bridge alternatives to long-haul trucking for heavy and bulk commodities. Intermodal service now captures the dominant share of new capacity investments as shippers seek seamless container transfers between maritime terminals and inland distribution points. Wagonload operations retain structural importance for chemical and petroleum flows despite slower growth, while electrified rail technology leads capital deployment as operators respond to carbon pricing mechanisms and infrastructure subsidy conditions.
KBA vehicle approval standards and EU F-Gas Regulation jointly shape locomotive procurement specifications and refrigerant handling protocols for temperature-controlled freight. Germany's Federal Network Agency (Bundesnetzagentur) enforces track access charges and network usage conditions that directly alter operator cost structures and route economics. Stakeholders must monitor how the EU Green Deal's forthcoming carbon border adjustments redirect modal choices for steel, cement, and chemical imports arriving through Hamburg and Bremerhaven.
Market Dynamics
Germany's Energiewende electrification mandates are compressing diesel locomotive residual values while forcing capital reallocation toward dual-mode traction assets. Operators face simultaneous pressure from carbon border adjustments and track access charge reforms that alter route profitability calculations across the Rhine-Ruhr corridor.
Growth Catalysts
- Chemical corridor expansion:Hazardous material shippers along the Rhine are consolidating liquid bulk movements onto dedicated tank car circuits to reduce road transport exposure and insurance liabilities.
- EU Green Deal carbon border mechanism:Steel and cement import flows through Hamburg and Bremerhaven are redirecting toward rail hinterland connections to preempt emissions reporting requirements.
- Port automation integration:Automated container handling at Bremerhaven and Wilhelmshaven is compressing dwell times and enabling synchronized train-ship transfers.
Market Restraints
- Copper and rare earth input volatility:Traction motor and battery pack manufacturing costs fluctuate with commodity markets, squeezing procurement budgets for fleet electrification programs.
- DB Netz track access concentration:Single infrastructure provider status for core corridors limits competitive route alternatives and amplifies price negotiation asymmetries.
- Trucking modal substitution:Flexible road haulage retains cost advantages for sub-300 kilometer distances and time-sensitive automotive parts movements.
Strategic Opportunities
- Baltic-Scandinavian intermodal lanes:Underdeveloped container rail connections from Lübeck and Rostock toward Sweden and Finland offer first-mover positioning for temperature-controlled goods.
- Hydrogen shunting locomotive pilots:Federal transport ministry funding programs support zero-emission yard operations at Munich-Riem and Mannheim terminals.
- Digital automatic coupling:EU-wide standardization mandates for freight wagon interoperability are creating upgrade cycles for fleet modernization services.
Industry Challenges
- ETCS signaling certification timelines:European Train Control System migration requirements are stretching engineering resources and delaying network capacity releases.
- Locomotive engineer demographic gaps:Retirement waves among qualified drivers are colliding with lengthy vocational training periods, constraining operational expansion.
- Legacy wagon fleet integration:Mixed-technology rail yards must accommodate both conventional screw couplings and new digital automatic systems during transition phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Rail Freight Transport Market |
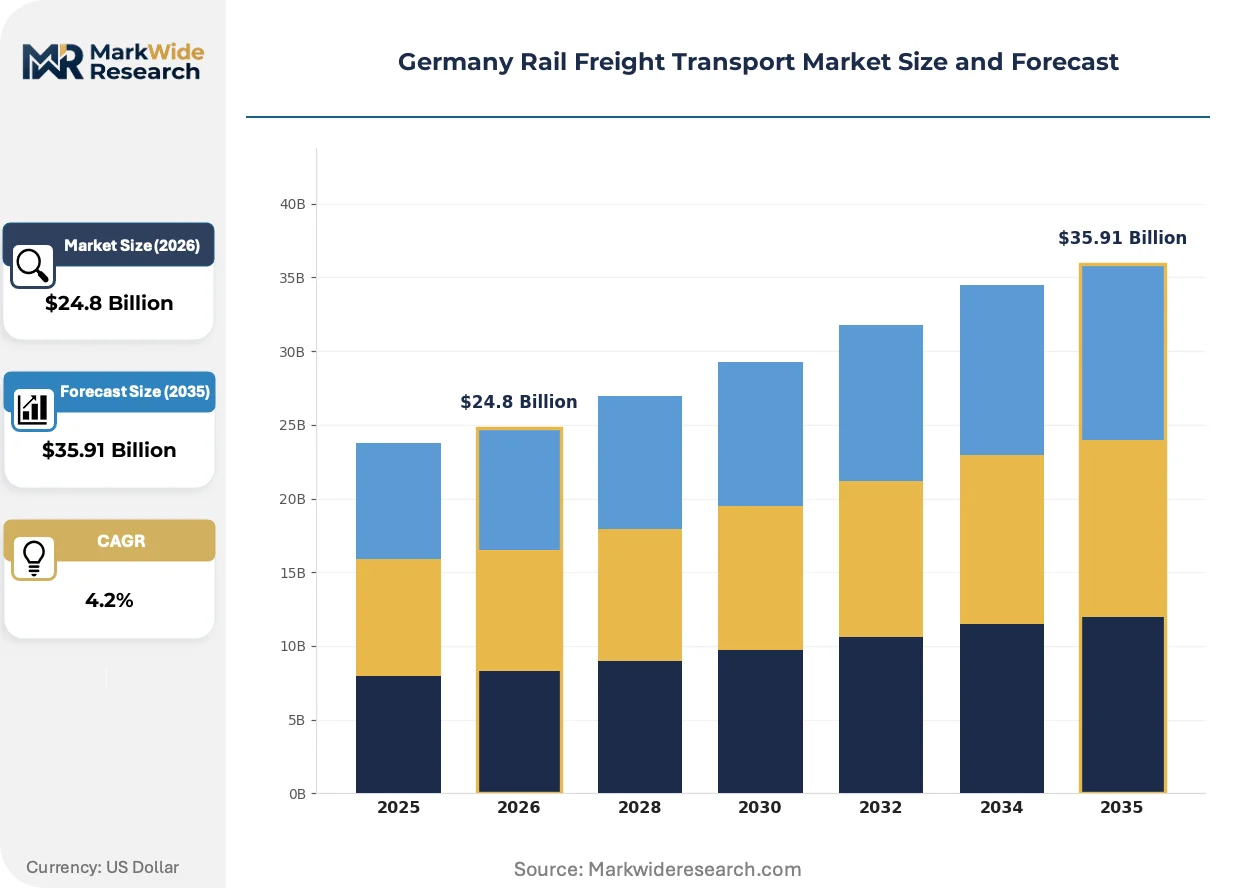
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $35.91 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Intermodal, Wagonload, Bulk Transport, Express Freight, Parcel Freight Freight Type: Containers, Petroleum Products, Automobiles, Chemicals, Agricultural Products, Machinery Customer Type: Manufacturers, Logistics Providers, Distributors, Contractors, Exporters, Importers Technology: Electrified Rail, Diesel Locomotives, Hybrid Engines, Automated Control Systems, GPS Tracking |
| Companies Covered | DB Cargo AG, SBB Cargo Deutschland GmbH, TX Logistik AG, Metrans, Captrain, boxXpress, Crossrail, BLS Cargo Nord, Container Terminal Dortmund GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Rail Freight Transport Market Shifts & Advancements
Digitalization and alternative traction technologies are decomposing traditional fleet management economics while creating new service layer opportunities. Operators must now integrate predictive maintenance platforms with energy management systems to retain margin competitiveness.
Last-mile autonomous shunting technology is decomposing terminal labor cost structures. Port operators at Hamburg and Bremerhaven are piloting remotely operated locomotives for container yard movements. This capability is compressing gate-to-berth transfer times and enabling round-the-clock operations without shift labor premiums.
Germany's Federal Network Agency track access charge reforms are restructuring operator cost allocations. The Bundesnetzagentur is implementing performance-based pricing that penalizes schedule unreliability. Chemical and intermodal segments are responding with precision scheduling investments and buffer time reductions.
Shippers are unbundling transport procurement from terminal handling contracts. Large manufacturing clusters in Baden-Württemberg are negotiating direct rail service agreements independent of traditional forwarding intermediaries. This pattern concentrates volume commitments with asset-owning operators and compresses intermediary margins across southern Germany.
Germany Rail Freight Transport Market Segmentation
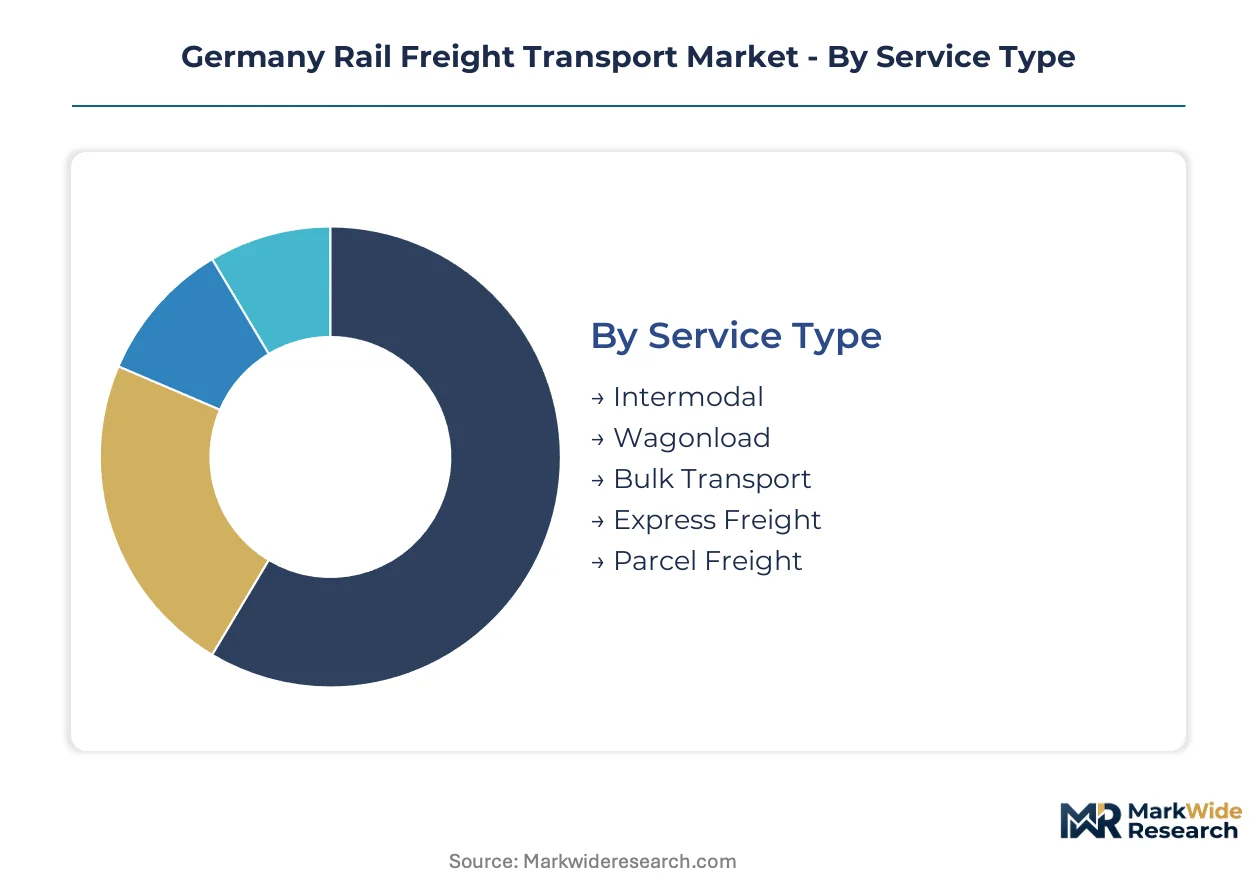
Rail freight segmentation in Germany reflects divergent pressure from trucking substitution across service modes and cargo categories. Understanding these fracture lines helps operators allocate capital between defensive wagonload positions and offensive intermodal expansion.
Service Type:
Trucking substitution pressure varies sharply across service modes, with time-definite segments facing the most aggressive road competition while bulk circuits retain modal lock-in.
- Intermodal:Container movements between maritime terminals and inland distribution points dominate new capacity investments. Demand concentrates within the Rhine-Ruhr corridor and Hamburg hinterland as shippers seek seamless ship-to-rail transfers at Bremerhaven and Wilhelmshaven.
- Wagonload:Single-car shipments for chemical and petroleum flows retain structural importance despite slower growth. BASF and Covestro facilities along the Ludwigshafen-Mannheim axis anchor dedicated tank car circuits that resist road encroachment through hazardous material handling requirements.
- Bulk Transport:Coal, ore, and grain movements utilize dedicated hopper and gondola fleets on high-volume corridors.
- Express Freight:Time-sensitive automotive parts and electronics shipments compete directly with premium trucking services.
- Parcel Freight:Small-package rail services serve postal and e-commerce distribution networks.
Wagonload anchors the volume base while intermodal gains share at the steepest rate.
Freight Type:
Margin structures across cargo categories separate commodity flows with thin spreads from specialized movements commanding premium pricing.
- Containers:Standardized box movements enable equipment pooling and terminal automation. Hamburg and Bremerhaven port automation investments compress dwell times and synchronize vessel-train transfers.
- Petroleum Products:Refined fuels and lubricants move via dedicated tank car fleets with pressure discharge capabilities. Rhine corridor refineries at Karlsruhe and Cologne depend on rail for inland distribution beyond pipeline reach.
- Automobiles:Finished vehicle transport utilizes specialized autorack wagons with multiple decks.
- Chemicals:Hazardous liquid and powder movements require tank cars with corrosion-resistant linings and thermal insulation.
- Agricultural Products:Grain and feed shipments exhibit seasonal volume spikes tied to harvest cycles.
- Machinery:Oversized and heavy industrial equipment demands flatcars with distributed load configurations.
Petroleum products anchor the volume base while containers climb the fastest.
Customer Type:
Procurement sophistication divides customers between integrated manufacturers seeking direct rail access and intermediaries aggregating fragmented demand.
- Manufacturers:Industrial producers with captive sidings negotiate direct service agreements. Baden-Württemberg automotive clusters bypass traditional forwarders to contract asset-owning operators for inbound parts and outbound finished vehicles.
- Logistics Providers:Multimodal forwarders aggregate shipper demand across fragmented lanes. Kuehne+Nagel and DHL Freight bundle rail legs with trucking and warehousing into integrated supply chain contracts.
- Distributors:Wholesale and retail supply chain operators utilize rail for replenishment flows.
- Contractors:Construction material suppliers move aggregates and cement via bulk services.
- Exporters:Goods producers shipping to international markets depend on port-connecting corridors.
- Importers:Inbound cargo owners prioritize hinterland connectivity from Hamburg and Bremerhaven.
Logistics providers anchor the volume base while manufacturers gain share at the steepest rate.
Technology:
Capital deployment intensity separates mature traction technologies from emerging systems requiring infrastructure co-investment.
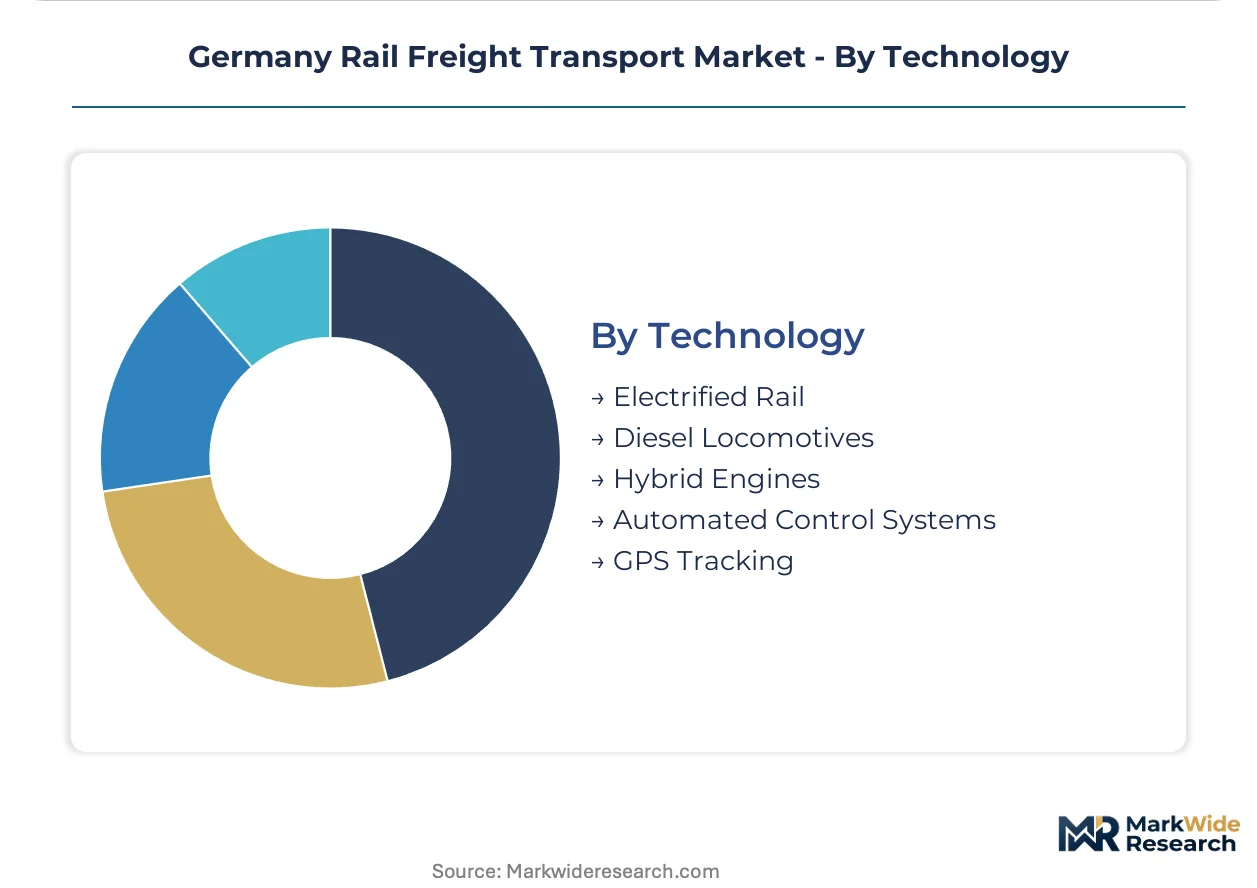
- Electrified Rail:Overhead catenary systems power locomotives on core corridors with 15 kV AC infrastructure. Energiewende mandates accelerate fleet conversion as carbon pricing mechanisms penalize diesel operations on high-traffic routes.
- Diesel Locomotives:Non-electrified branch lines and shunting yards retain diesel traction for operational flexibility. Residual values compress as dual-mode and hybrid alternatives reach procurement parity.
- Hybrid Engines:Dual-power locomotives switch between electric and diesel operation. Federal transport ministry subsidies support pilot deployments on corridors with partial electrification.
- Automated Control Systems:ETCS signaling upgrades enable higher speeds and shorter headways.
- GPS Tracking:Real-time location and condition monitoring supports predictive maintenance.
Diesel locomotives anchor the volume base while electrified rail gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
KBA vehicle approval standards and the Bundesnetzagentur's track access charge reforms anchor Germany's regulatory framework for rail freight, while sub-regional industrial clusters concentrate demand across distinct freight corridors.
North Rhine-Westphalia
The Rhine-Ruhr industrial corridor generates dense chemical and steel movements between Duisburg, Cologne, and Dortmund. KBA enforces locomotive certification standards that shape fleet procurement decisions for operators serving this corridor. BASF and Covestro facilities at Ludwigshafen anchor dedicated tank car circuits that resist road modal shift.
Bavaria
Automotive manufacturers in Munich and Ingolstadt drive time-sensitive parts movements requiring precision scheduling. Federal transport ministry funding supports hydrogen shunting locomotive pilots at Munich-Riem terminal. The Nuremberg freight hub connects southern Germany to Czech and Austrian rail networks.
Baden-Württemberg
Stuttgart's automotive cluster and Mannheim's chemical complex generate diversified freight demand across container and tank car segments. EU F-Gas Regulation shapes refrigerant handling protocols for temperature-controlled movements through this region. Shippers in this manufacturing belt increasingly negotiate direct rail service agreements bypassing traditional forwarders.
Lower Saxony
Bremerhaven and Wilhelmshaven port automation investments compress container dwell times and synchronize vessel-train transfers. The Bundesnetzagentur's performance-based pricing reforms penalize schedule unreliability on these critical hinterland connections. Grain movements from northern agricultural zones utilize dedicated hopper fleets during seasonal harvest peaks.
Hamburg Metropolitan Region
Europe's third-largest port anchors intermodal flows connecting maritime terminals to inland distribution points across central Europe. Carbon border adjustment mechanisms redirect steel and cement import flows toward rail hinterland connections to preempt emissions reporting requirements. Remotely operated locomotive pilots at container yards compress gate-to-berth transfer times.
Germany Rail Freight Transport Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with market structure reflecting infrastructure access advantages and corridor-specific expertise concentration. Two strategic archetypes dominate: asset-owning operators with captive terminal networks, and agile specialists competing on cross-border lanes and niche cargo categories. Competitive moves center on fleet electrification programs and digital automatic coupling upgrades to capture EU standardization mandates.
Among integrated infrastructure holders, DB Cargo AG exemplifies the terminal-network archetype through its domestic wagonload dominance. TX Logistik AG and Captrain occupy positions at the specialist tier, with the former competing aggressively on cross-border intermodal lanes and the latter anchoring chemical tank car services along the Rhine corridor. These three operators collectively illustrate how capital access and corridor focus determine competitive positioning.
| Leading Market Players |
|---|
| DB Cargo AG |
| SBB Cargo Deutschland GmbH |
| TX Logistik AG |
| Metrans |
| Captrain |
| boxXpress |
| Crossrail |
| BLS Cargo Nord |
| Container Terminal Dortmund GmbH |
| Others |
Supply & Pricing Matrix
High fixed-cost infrastructure economics concentrate pricing power among operators with captive terminal networks and dense corridor utilization. Scale advantages in the Rhine-Ruhr corridor enable DB Cargo AG to maintain rate floors that smaller competitors cannot match without sacrificing asset turns. The Bundesnetzagentur's performance-based track access charges compress margins for unreliable operators while rewarding precision scheduling investments.
Pricing Analysis
Rhine corridor rates command premiums over northern port hinterland lanes due to chemical tank car specialization and hazardous material handling requirements. Contract-based long-term offtake agreements dominate, with pricing stratifying across premium temperature-controlled, standard intermodal, and economy bulk tiers. Cost compression in standard intermodal is intensifying because trucking retains flexibility advantages for sub-300 kilometer distances. Logistics providers exhibit highest price sensitivity due to thin forwarding margins, while chemical manufacturers accept premium rates for dedicated tank car circuits that reduce insurance exposure.
Supply Chain Analysis
Strategic stockpiling of copper windings and rare earth magnets prevails among locomotive manufacturers facing commodity volatility, while rail operators prefer just-in-time traction motor deliveries to minimize working capital. Supply concentrates in China for battery pack assembly, Germany for traction motor production, and Poland for freight wagon fabrication. Procurement draws from steel mills in the Ruhr, semiconductor foundries in Dresden, and braking system suppliers in Italy. Single-source vulnerability around ETCS signaling components from Swiss and Austrian specialists poses structural risk. Distribution runs through DB Netz's centralized infrastructure allocation system with limited competitive alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Freight rail services increasingly attach predictive maintenance platforms and energy management subscriptions that expand recurring revenue faster than locomotive hardware sales. Digital service layers now capture margin premiums that pure asset ownership cannot replicate.
For Market Incumbents: Compound terminal network advantages by integrating automated shunting technology at Munich-Riem and Mannheim yards before agile specialists replicate the capability. Deepen backward integration into digital automatic coupling manufacturing to capture EU standardization upgrade cycles. Defend against TX Logistik AG's cross-border expansion by locking long-term volume commitments with Baden-Württemberg automotive clusters.
For New Entrants and Emerging Players: Lead with hydrogen shunting locomotive pilots at partially electrified terminals where federal transport ministry subsidies offset capital intensity. Target Baltic-Scandinavian intermodal lanes from Lübeck and Rostock as underdeveloped corridors with limited incumbent presence. Build direct relationships with temperature-controlled goods shippers seeking alternatives to road haulage for Swedish and Finnish destinations.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors operators with dual-mode traction fleets and ETCS certification capabilities that align with electrification mandates. Long-term viability hinges on exposure to carbon border adjustment mechanisms redirecting steel and cement flows toward rail. Watch for ETCS signaling certification delays as inflection indicator for network capacity constraints and operator margin pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Automatic Coupling Deployment | EU standardization mandates create fleet modernization service opportunities across German operators. |
| Hydrogen Shunting Locomotive Pilots | Federal transport ministry funding supports zero-emission yard operations at priority terminals. |
| Cross-Border Intermodal Expansion | Underdeveloped Baltic-Scandinavian lanes offer first-mover positioning for temperature-controlled goods. |
| Predictive Maintenance Platform Integration | Energy management subscriptions attach recurring revenue to traditional asset-heavy operations. |
| Direct Manufacturer Service Agreements | Baden-Württemberg automotive clusters bypass forwarders to contract asset-owning operators directly. |
Research Methodology
A standing panel of locomotive fleet managers, terminal operations directors, Bundesnetzagentur regulatory specialists, chemical shipper procurement leads, and intermodal forwarders provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation against customs trade data, Deutsche Bahn AG infrastructure disclosures, KBA vehicle approval filings, and EU transport statistics. Bottom-up volume modeling across service types, freight categories, and customer segments triangulated with top-down macroeconomic drivers.
Consistency checks validated projections against external benchmarks including infrastructure investment pipelines, electrification subsidy allocations, and port automation deployment schedules. The analytical framework modeled intermodal, wagonload, bulk, express, and parcel service types across container, petroleum, automotive, chemical, and agricultural freight categories. CAGRs were derived from trend extrapolation of corridor-specific volume data, fleet utilization rates, and modal shift elasticities relative to trucking alternatives.
The analysis sits within stated boundaries; outcomes outside sustained federal electrification funding or stable copper and rare earth input costs would require recalibration. Forecasts reflect documented assumptions regarding ETCS migration timelines, carbon border adjustment implementation scope, and trucking regulatory cost trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Composites in Passenger Rail Market
Railway Transportation
Global Rail Freight Transport Market
Railway Transportation
Global Railcar Leasing Market
Railway Transportation
Brazil Rail Freight Transport Market
Railway Transportation
Urban Rail Transit Signaling Market
Railway Transportation
Japan Rail Freight Transport Market
Railway Transportation
Railway Air Conditioning System Market
Railway Transportation
Railway Roof Switches Market
Railway Transportation
Global Train Signalling System Market
Railway Transportation
Railway Control Stands Market
Railway Transportation
Urban Rail Transit Market
Railway Transportation
Poland Rail Freight Transport Market
Railway Transportation
Point Machine Market
Railway Transportation
Rail Pads Market
Railway Transportation
Railway Couplers Market
Railway Transportation
Global Train Communication Gateways Systems Market