
 Railway Hydraulic Damper Market | 2026-2036
Railway Hydraulic Damper Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Hydraulic Damper Market Analysis
Aftermarket service revenue is narrowing as original equipment manufacturers extend lifecycle contracts into refurbishment and predictive maintenance. Dellner Components leverages its Nordic manufacturing base to control aftermarket channels for Scandinavian rail operators. Knorr-Bremse AG sustains R&D intensity across electro-hydraulic damping architectures for high-speed applications. ZF Friedrichshafen AG anchors European supply through captive production of precision valve assemblies for Tier 1 integrators.
A railway hydraulic damper is a sealed fluid-mechanical device that dissipates kinetic energy through controlled oil flow across precision-machined orifices, typically operating at pressures exceeding 200 bar and temperatures from minus 40 to plus 120 degrees Celsius to stabilize bogie oscillation and passenger ride quality. Conical dampers dominate legacy freight and commuter fleets where cost engineering outweighs performance optimization, while tuned mass dampers capture expanding share in high-speed rail where resonant frequency management determines operational safety certification. Retrofit solutions constitute the fastest-growing installation category as operators defer full fleet replacement amid capital budget constraints.
The EU's F-Gas Regulation and EN 15227 crashworthiness standards shape product design mandates for European suppliers, while China's NMPA-aligned rail certification and GB standards enforce localized testing protocols for market access. India's RDSO specifications and PLI scheme for rail component manufacturing are redirecting procurement toward domestic assembly requirements. Stakeholders must monitor regulatory divergence between European harmonized standards and emerging national certification regimes to align product development roadmaps with regional compliance timelines.
Market Dynamics
Fleet operators across Germany, Japan, and China are compressing replacement cycles as EN 15227 and GB/T crashworthiness mandates harden performance thresholds for bogie stabilization systems.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of fluorinated greenhouse gases forces damper manufacturers toward sealed hydraulic architectures with synthetic oil formulations that eliminate refrigerant leakage risks.
- China's intercity corridor expansion:Dedicated passenger routes between Beijing-Tianjin, Shanghai-Nanjing, and Guangzhou-Shenzhen generate concentrated demand for tuned mass dampers managing resonant frequencies above 300 km/h.
- Predictive maintenance integration:IoT sensor deployment across high-speed fleets enables condition-based damper replacement, converting historical breakdown maintenance into scheduled lifecycle revenue streams.
Market Restraints
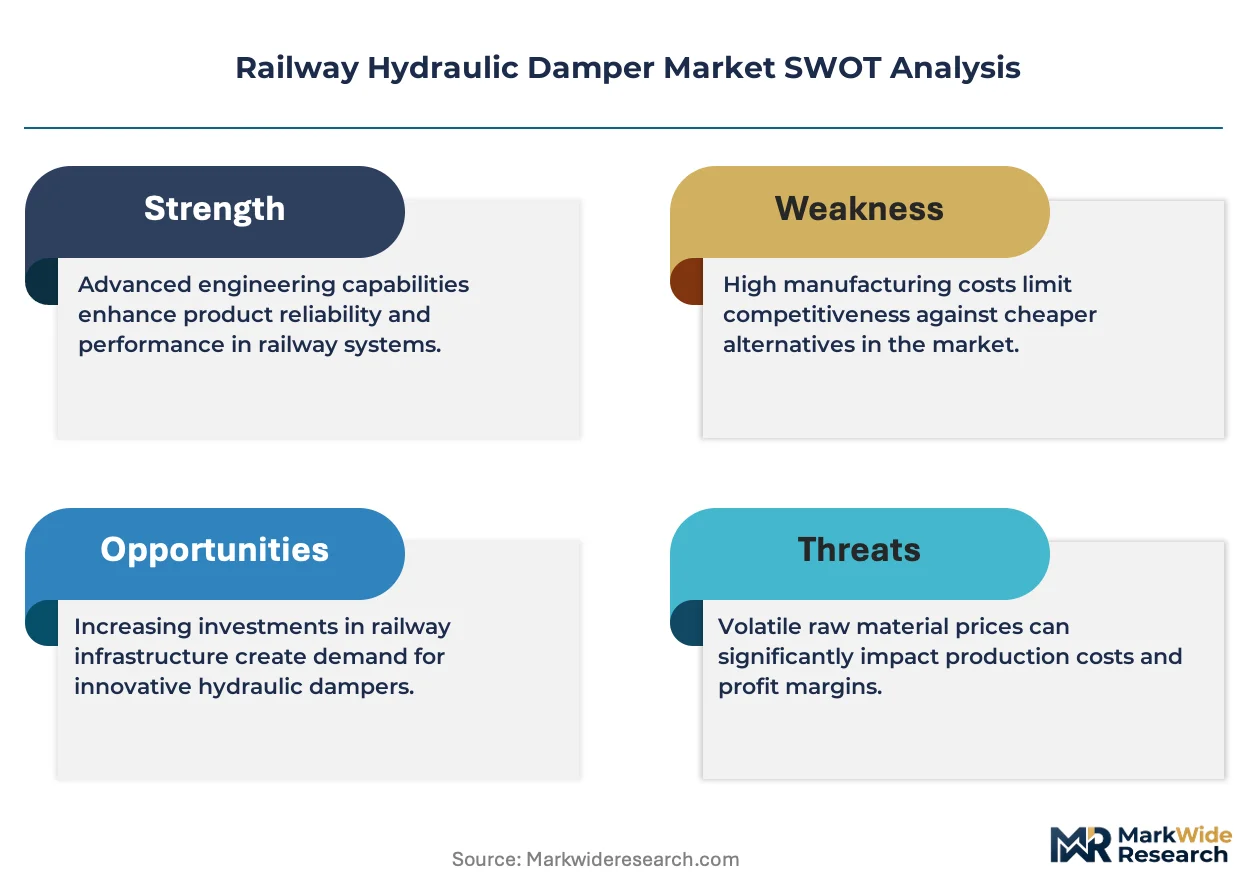
- Specialized steel alloy costs:Precision-machined piston rods require vacuum-remelted chromium-molybdenum grades whose spot pricing fluctuates with aerospace and defense contract cycles.
- Single-source valve assembly concentration:Captive production of high-pressure orifice plates concentrates in southwestern Germany, creating geographic vulnerability to energy-intensive manufacturing disruptions.
- Electromagnetic active suspension substitution:Magnetorheological damper architectures from automotive motorsport applications threaten hydraulic dominance in next-generation tilting train designs.
Strategic Opportunities
- India's PLI scheme for rail components:Production-linked incentives redirect procurement toward domestic assembly, opening captive supply partnerships with RDSO-certified fabricators in Uttar Pradesh and Tamil Nadu.
- Retrofit solution penetration:Capital-constrained operators in Eastern Europe and Southeast Asia defer full fleet replacement, creating aftermarket demand for modular damper cartridges compatible with legacy bogie frames.
- Digital twin convergence:Integration of finite element analysis with real-time track condition data enables preemptive damping coefficient adjustment before resonance damage accumulates.
Industry Challenges
- Multi-standard certification timelines:Parallel EN 15227, GB/T, and RDSO testing protocols extend product validation cycles, delaying revenue recognition for platform variants.
- Legacy fleet integration complexity:Conical damper replacement in 1980s-era freight wagons requires custom mounting bracket fabrication, fragmenting production economics across low-volume SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Hydraulic Damper Market |
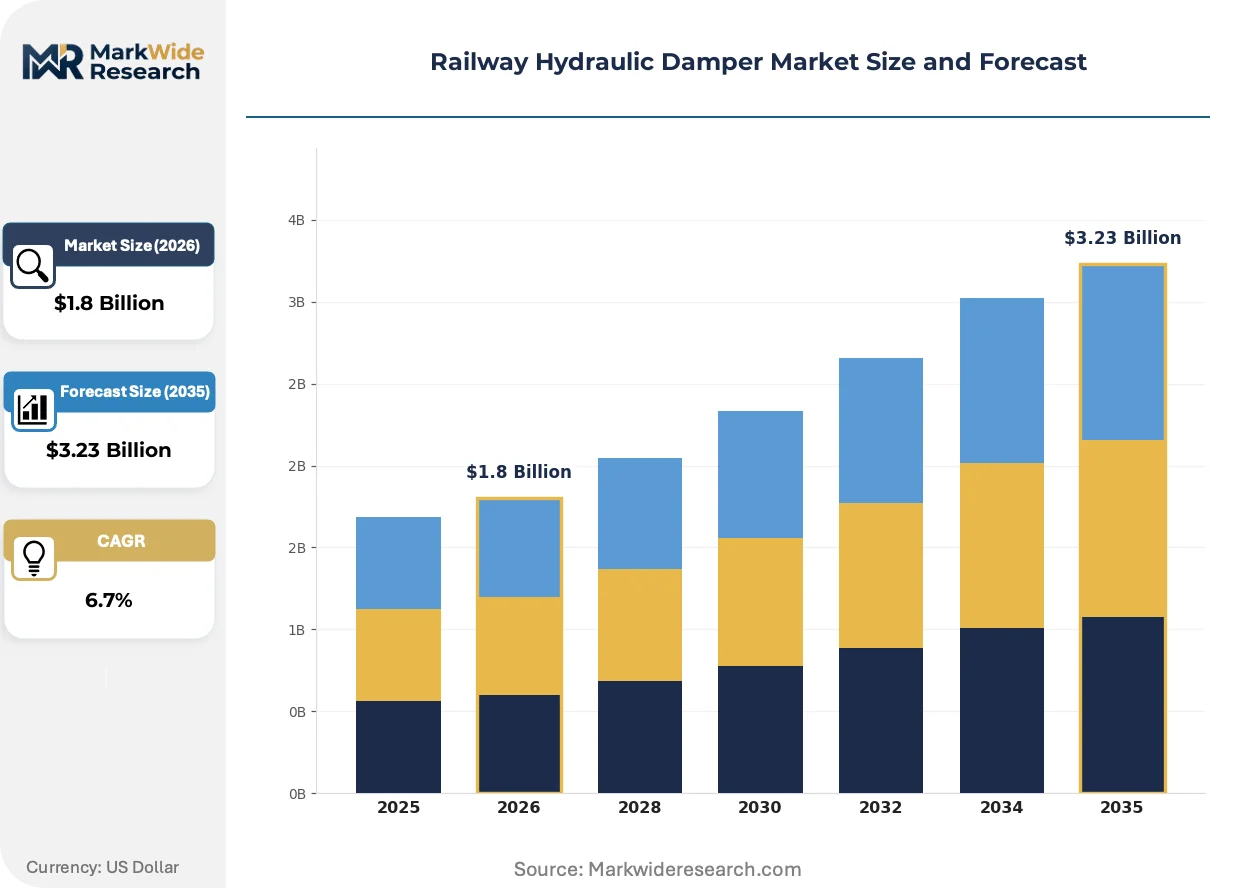
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conical Dampers, Viscous Dampers, Friction Dampers, Tuned Mass Dampers End User: Passenger Services, Freight Transport, Light Rail, High-Speed Rail Installation Type: Fixed Installation, Mobile Installation, Retrofit Solutions, Custom Solutions Usage Area: Urban Transit, Intercity Rail, Heavy Haul, Maintenance of Way |
| Companies Covered | Dellner Components, Oleo International, Knorr-Bremse AG, Suomen Vaimennin, Escorts Limited, ZF Friedrichshafen AG, Siemens AG, Vibratech TVD, ITT Inc. (KONI), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Hydraulic Damper Market Emerging Trajectories
Electro-hydraulic architectures and virtualized testing protocols are compressing development cycles while regulatory divergence between European harmonized standards and national certification regimes fragments compliance roadmaps.
Digital twin simulation is virtualizing damper validation workflows. Tier 1 integrators in Germany and Japan now model oil flow dynamics across temperature and pressure extremes before physical prototyping. High-speed rail OEMs in China adopt these virtualized environments to accelerate GB/T certification timelines. The technology is virtualizing traditional test-track validation, reducing prototype iteration costs and compressing supplier qualification periods.
REACH substance restrictions and the EU F-Gas Regulation are reshaping material selection mandates. Hydraulic fluid formulations containing short-chain chlorinated paraffins face sunset dates, forcing reformulation toward polyalphaolefin and ester-based alternatives. European suppliers stockpile compliant chemistries ahead of enforcement windows. Sealing material suppliers accelerate fluoroelastomer-to-hydrogenated nitrile transitions to maintain permeation resistance without perfluorinated compounds.
Lifecycle contracting now unbundles hardware procurement from refurbishment obligations. Scandinavian and Japanese operators negotiate throughput-guaranteed service agreements where damper suppliers assume residual value risk. Channel intermediaries lose margin to direct OEM-customer relationships. This restructuring concentrates most visibly in Germany's ICE fleet renewals, where Deutsche Bahn negotiates twenty-year total cost of ownership frameworks with integrated damping system providers.
Railway Hydraulic Damper Market Segmentation
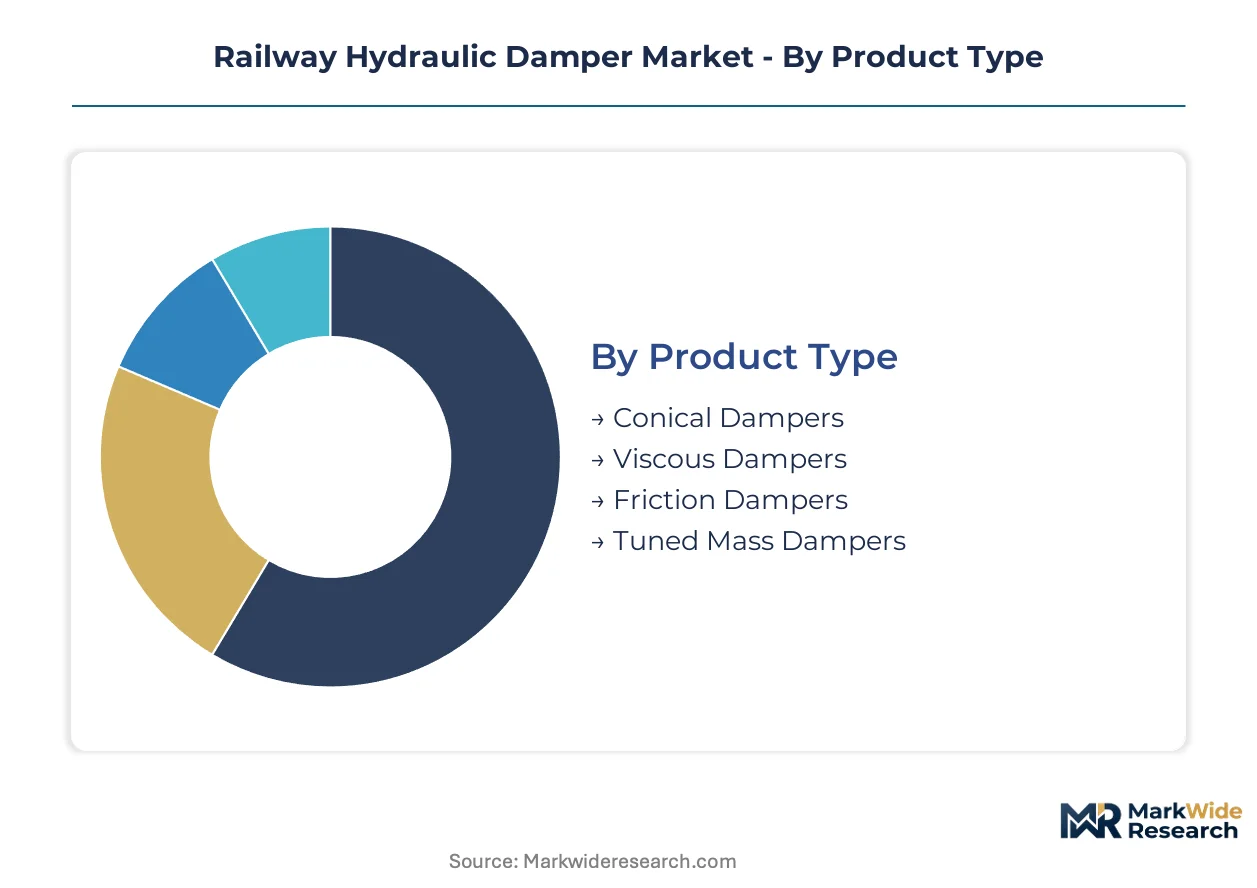
Railway hydraulic damper segmentation reflects divergent engineering priorities across speed regimes and duty cycles. Product architecture, installation constraints, and operational intensity each reshape supplier economics and certification requirements. Understanding these dimensions clarifies where margin pools concentrate and where commodification pressures intensify.
Product Type:
Cost tier differentiation separates legacy mechanical designs from precision-tuned architectures serving high-speed corridors.
- Conical Dampers:Cylindrical steel housings with single-orifice flow paths dominate freight wagon bogies where capital cost minimization outweighs damping coefficient precision. Demand concentrates in India's dedicated freight corridors and Eastern European bulk cargo fleets where RDSO and EN 15227 compliance requirements remain less stringent than passenger applications. Replacement cycles extend to eight-to-ten years in these operating environments.
- Tuned Mass Dampers:Resonant-frequency-optimized assemblies with adjustable mass blocks and variable-rate hydraulic circuits manage oscillation in trains operating above 250 km/h. China's Beijing-Tianjin and Shanghai-Nanjing intercity routes generate concentrated procurement as GB/T standards harden ride quality mandates. Certification testing spans temperature extremes from minus 40 to plus 120 degrees Celsius.
- Viscous Dampers:Silicone-fluid shear devices provide velocity-proportional energy dissipation for light rail and metro applications.
- Friction Dampers:Spring-preloaded pad assemblies deliver displacement-dependent damping for legacy rolling stock refurbishment.
Conical dampers command the established base. The steepest expansion runs through tuned mass dampers.
End User:
Application intensity determines specification grade and service contract structure across passenger and cargo operations.
- High-Speed Rail:Precision-tuned damping systems with real-time adjustability manage track-induced vibration in trains exceeding 300 km/h. Japan's Shinkansen renewal programs and China's expanding intercity network drive specification escalation toward electro-hydraulic architectures. Deutsche Bahn's ICE fleet transitions toward twenty-year total cost of ownership contracts that bundle hardware with predictive maintenance.
- Freight Transport:Heavy-haul wagons operating at axle loads above 25 tonnes require robust conical dampers with extended seal life. India's Eastern Dedicated Freight Corridor and Australian iron ore routes concentrate demand where maintenance access intervals stretch to quarterly cycles. Capital constraints in Eastern European operators sustain price competition.
- Passenger Services:Commuter and regional trains balance ride quality with lifecycle cost across varied track conditions.
- Light Rail:Street-running trams demand compact damper envelopes with corrosion-resistant finishes for urban environments.
Freight transport absorbs the highest unit volumes. High-speed rail captures the fastest margin expansion.
Installation Type:
Customer type and capital availability reshape procurement modality between new build and aftermarket channels.
- Retrofit Solutions:Modular damper cartridges designed for legacy bogie frames enable fleet modernization without full vehicle replacement. Operators in Southeast Asia and Eastern Europe defer capital expenditure amid budget constraints, creating aftermarket demand for adapter brackets and compatibility kits. Channel intermediaries lose margin to direct supplier-operator relationships in Scandinavia and Germany.
- Fixed Installation:Permanent mounting configurations for OEM new-build programs require integrated design with bogie structural analysis.
- Mobile Installation:Quick-exchange damper units support maintenance-of-way vehicles with intermittent deployment patterns.
- Custom Solutions:Bespoke engineering for specialty rolling stock addresses non-standard axle loads or gauge constraints.
Fixed installation anchors OEM revenue stability. Retrofit solutions are climbing the fastest as fleet operators extend asset lifecycles.
Usage Area:
Geography and infrastructure maturity determine duty cycle severity and specification harmonization requirements.
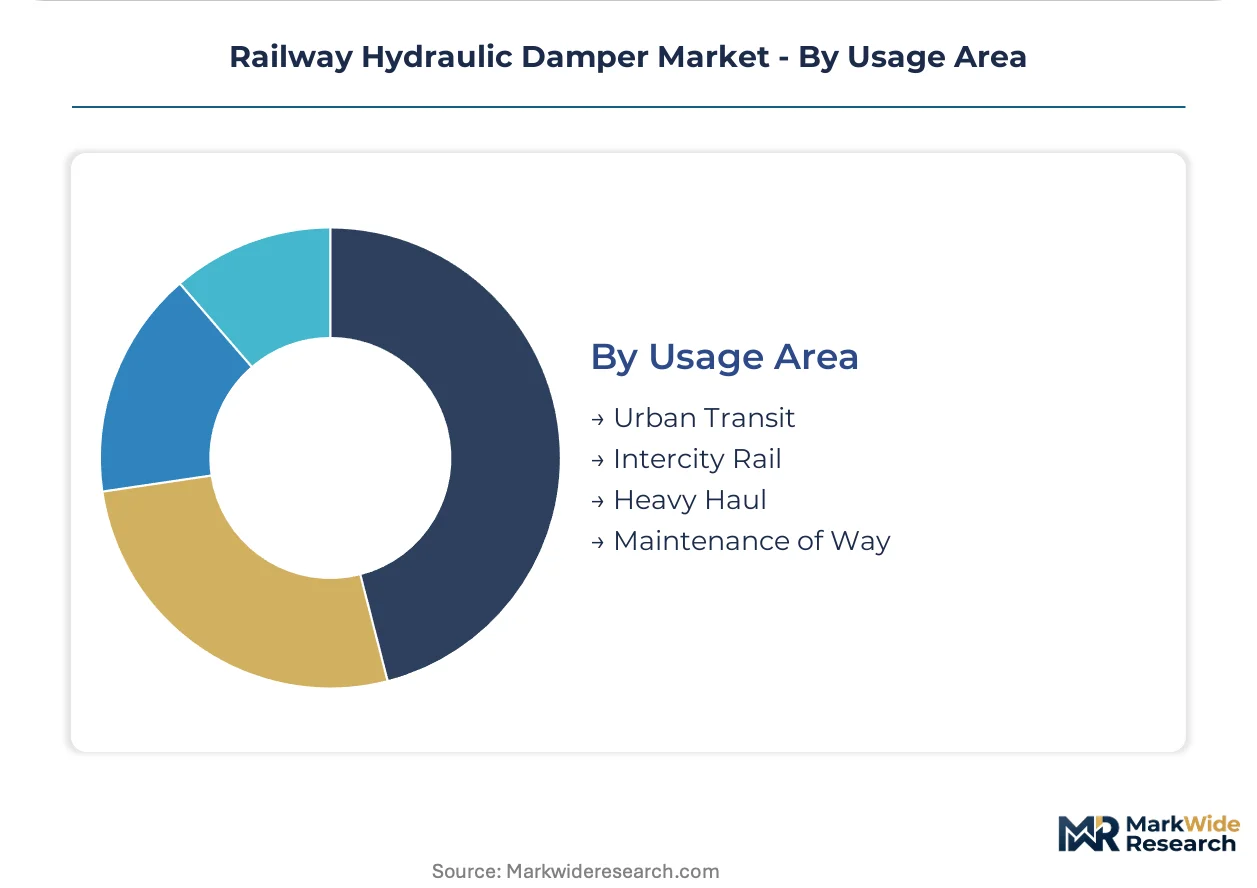
- Intercity Rail:Medium-distance passenger routes with mixed traffic patterns require dampers balancing comfort and durability. China's Guangzhou-Shenzhen corridor and Germany's ICE network concentrate procurement where EN 15227 and GB/T standards overlap. Track condition variability between jurisdictions complicates coefficient calibration.
- Heavy Haul:Mineral and bulk commodity routes with high axle loads and long train configurations stress damper thermal capacity. Australian Pilbara operations and South African coal corridors drive demand for high-displacement architectures with enhanced oil cooling.
- Urban Transit:Metro and suburban networks with frequent stop-start cycles prioritize rapid response damping.
- Maintenance of Way:Track-laying and inspection vehicles require specialized dampers for low-speed high-impact operating modes.
Intercity rail holds the largest installed base. Heavy haul gains share fastest where mining export volumes expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across procurement contexts. Capital-constrained operators in Eastern Europe and Southeast Asia prioritize retrofit cartridges over new-build systems. Premium-tier buyers in Germany, Japan, and China absorb specification escalation for crashworthiness-certified architectures.
Germany
Deutsche Bahn's ICE fleet renewals drive twenty-year total cost of ownership contracting. EN 15227 crashworthiness mandates harden bogie stabilization thresholds. The southwestern industrial corridor around Stuttgart anchors captive production of high-pressure orifice plates for Tier 1 integrators.
China
Beijing-Tianjin and Shanghai-Nanjing intercity corridors concentrate tuned mass damper procurement for 300 km/h operations. GB/T rail specifications enforce localized testing protocols for market access. The Yangtze River Delta manufacturing base supplies precision valve assemblies to domestic high-speed rail OEMs.
Japan
Shinkansen renewal programs sustain specification escalation toward electro-hydraulic architectures. METI-aligned industrial policy supports domestic R&D intensity in resonant frequency management. The Kanto region around Tokyo hosts integrated damping system providers serving JR Central and JR East.
India
The Eastern Dedicated Freight Corridor and Western Dedicated Freight Corridor generate heavy-haul damper demand at axle loads above 25 tonnes. RDSO specifications and the PLI scheme for rail components redirect procurement toward domestic assembly in Uttar Pradesh and Tamil Nadu. Chennai-based fabricators qualify for RDSO certification to supply state-owned fleet operators.
United States
Class I freight railroads defer full fleet replacement amid capital budget constraints, sustaining aftermarket channel demand. FRA safety regulations govern bogie component performance without mandating specific damper architectures. The Chicago rail hub concentrates maintenance-of-way vehicle procurement requiring specialized low-speed high-impact damping systems.
Railway Hydraulic Damper Market Vendor Landscape
Capability concentration sits with precision-machining specialists; scale advantage sits with diversified automotive-industrial conglomerates. The vendor base stratifies across three tiers: Nordic-focused aftermarket service providers, German-Japanese electro-hydraulic architecture leaders, and diversified Tier 1 integrators with captive damping divisions. Consolidation pressure runs through lifecycle contract bundling and predictive maintenance platform integration. Geographic expansion and backward integration into sealing materials represent the dominant competitive moves.
Among diversified industrial conglomerates with rail divisions, Knorr-Bremse AG and ZF Friedrichshafen AG occupy positions anchored in German automotive-industrial ecosystems. Dellner Components exemplifies the Nordic specialist archetype with concentrated aftermarket channel control. These three entities represent distinct strategic postures: diversified technology breadth, precision manufacturing depth, and regional service integration respectively.
| Leading Market Players |
|---|
| Dellner Components |
| Oleo International |
| Knorr-Bremse AG |
| Suomen Vaimennin |
| Escorts Limited |
| ZF Friedrichshafen AG |
| Siemens AG |
| Vibratech TVD |
| ITT Inc. (KONI) |
| Others |
Supply Flow & Price Mechanics
Single-source valve assembly concentration in southwestern Germany determines both pricing tier spreads and supply chain shape, compressing margins for Tier 2 fabricators while amplifying negotiation leverage for Deutsche Bahn and JR Central procurement officers. This geographic chokepoint forces aftermarket channel intermediaries to absorb cost volatility from vacuum-remelted chromium-molybdenum alloy spot pricing, which fluctuates with aerospace contract cycles.
Pricing Analysis
Extended lifecycle service contracts now drive lifetime value capture for original equipment manufacturers, displacing transactional parts revenue. Three-tier pricing structure across premium, standard, and economy levels separates electro-hydraulic architectures with predictive maintenance integration from conical dampers for freight applications. Cost compression in the economy tier is intensifying because Indian PLI scheme beneficiaries in Uttar Pradesh and Tamil Nadu undercut European labor costs. Freight operators in Eastern Europe exhibit highest price sensitivity; high-speed rail procurement officers in China and Japan prioritize crashworthiness certification over unit cost.
Supply Chain Analysis
Extended payment terms from Scandinavian fleet operators now finance working capital for precision-machining specialists in the Nordic manufacturing base. Supply concentration sits in Germany, China, and Japan, with captive production of high-pressure orifice plates anchoring Tier 1 integrator relationships. The supply chain draws from vacuum-remelted chromium-molybdenum steel alloys, synthetic polyalphaolefin hydraulic fluids, and hydrogenated nitrile sealing compounds. Single-source vulnerability in southwestern German valve assembly production creates exposure to energy-intensive manufacturing disruptions. Distribution runs through direct OEM-operator relationships in Germany and Scandinavia, with channel intermediaries retaining relevance in Southeast Asia and Eastern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where predictive maintenance data streams and digital twin convergence are redefining competitive moats around interoperability rather than hardware specification alone.
For Market Incumbents: Insulate core revenue by deepening captive control over precision valve assembly production in southwestern Germany and accelerating RDSO certification timelines for Indian PLI scheme participation. Magnetorheological damper substitution from automotive motorsport applications threatens hydraulic dominance in next-generation tilting train designs; vertical integration into sealing material supply hedges REACH substance restriction exposure. For New Entrants and Emerging Players: Build out retrofit solution capabilities for legacy conical damper replacement in Eastern European and Southeast Asian freight fleets, where capital constraints defer full vehicle procurement. India's Eastern and Western Dedicated Freight Corridors offer the most penetrable geography given PLI scheme procurement redirection toward domestic assembly. Partner with RDSO-certified fabricators in Uttar Pradesh and Tamil Nadu to bypass incumbent channel control. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision-machining specialists with captive aftermarket channel relationships. Long-term viability hinges on lifecycle contract bundling and predictive maintenance platform integration rather than hardware volume. Acquisition targets should demonstrate backward integration into sealing materials or valve assembly production. Monitor EN 15227 and GB/T certification timeline convergence as inflection indicator for platform standardization opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sealing Materials | REACH substance restrictions are forcing fluoroelastomer-to-hydrogenated nitrile transitions without perfluorinated compounds. |
| Digital Twin Platform Development | Finite element analysis integration with real-time track condition data enables preemptive damping coefficient adjustment. |
| RDSO Certification Investment | India's PLI scheme redirects procurement toward domestic assembly in Uttar Pradesh and Tamil Nadu. |
| Lifecycle Service Contract Expansion | Deutsche Bahn's twenty-year total cost of ownership frameworks bundle hardware with predictive maintenance. |
| Electro-Hydraulic Architecture R&D | High-speed rail OEMs in China and Japan specify real-time adjustability for operations above 300 km/h. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and OEM procurement disclosures. Interviews with fleet maintenance directors, Tier 1 supplier procurement teams, RDSO certification officers, and aftermarket service heads inform demand-side validation. Secondary sources include EN 15227 and GB/T standard documentation, EU F-Gas Regulation impact assessments, and Indian PLI scheme administrative records. Bottom-up unit economics triangulate against top-down market sizing across product type, end user, and installation modality.
Forecast inputs span fleet renewal program announcements, crashworthiness mandate implementation timelines, and raw material spot price trajectories. Segmentation dimensions modeled include product architecture, speed regime, installation type, and regional certification cluster. CAGRs derive from regression analysis of historical replacement cycle compression and predictive maintenance adoption curves. Industry-specific inputs incorporate high-speed rail corridor expansion schedules and dedicated freight corridor axle load escalation.
Practitioners should monitor regulatory divergence between European harmonized standards and emerging national certification regimes for early signals of platform fragmentation or convergence. Forecasts reflect assumptions around EN 15227 compliance timeline adherence and GB/T testing protocol stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Train Transformer Market
Railway Transportation
Digital Railway Market
Railway Transportation
Global Railway Wiring Harness Market
Railway Transportation
Composites in Passenger Rail Market
Railway Transportation
Railway Roof Switches Market
Railway Transportation
Railway Traction Inverter Market
Railway Transportation
Global Rail Freight Transport Market
Railway Transportation
Railway After-Cooler Market
Railway Transportation
Point Machine Market
Railway Transportation
Global Autonomous Trains Market
Railway Transportation
Autonomous Train Technology Market
Railway Transportation
China-Europe Rail Freight Transport Market
Railway Transportation
Poland Rail Freight Transport Market
Railway Transportation
Japan Rail Freight Transport Market
Railway Transportation
Railway Air Conditioning System Market
Railway Transportation
Germany Rail Freight Transport Market