
 Railway Station Lighting Market | 2026-2036
Railway Station Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Station Lighting Market Insights
High-efficiency LED specification tiers is rotating through the replacement cycle as railway operators retire mercury-bearing and low-efficacy luminaires. Signify leverages its Interact connected lighting platform to anchor large platform contracts across European hubs. Siemens Mobility competes through integrated rail infrastructure packages that bundle lighting with signaling and electrification systems. Acuity Brands Lighting specializes in architectural-grade waiting area fixtures that differentiate on color quality and glare control.
Railway station lighting encompasses engineered luminaire systems designed for transit environments, typically rated for vibration resistance, ingress protection, and emergency battery backup with maintained output levels. These installations serve dual purposes of passenger safety wayfinding and operational visibility for platform edge detection during low-ambient conditions. LED product types now dominate procurement specifications due to lumen maintenance advantages and reduced relamping frequency in high-ceiling concourses. Smart lighting technology is expanding fastest among technology segments as operators deploy centralized dimming and occupancy-based scheduling across platform and parking area applications. Fluorescent categories retain residual share in budget-constrained retrofit phases but face structural margin compression from material restrictions and disposal compliance costs.
Europe's Ecodesign Directive and REACH substance restrictions are accelerating removal of mercury-containing lamps from railway procurement frameworks. India's Bureau of Energy Efficiency mandates and BIS certification requirements for LED luminaires are reshaping supplier qualification criteria for metro and station redevelopment tenders. Stakeholders must monitor evolving photobiological safety standards and cybersecurity protocols for connected lighting networks as digital infrastructure convergence deepens.
Market Dynamics
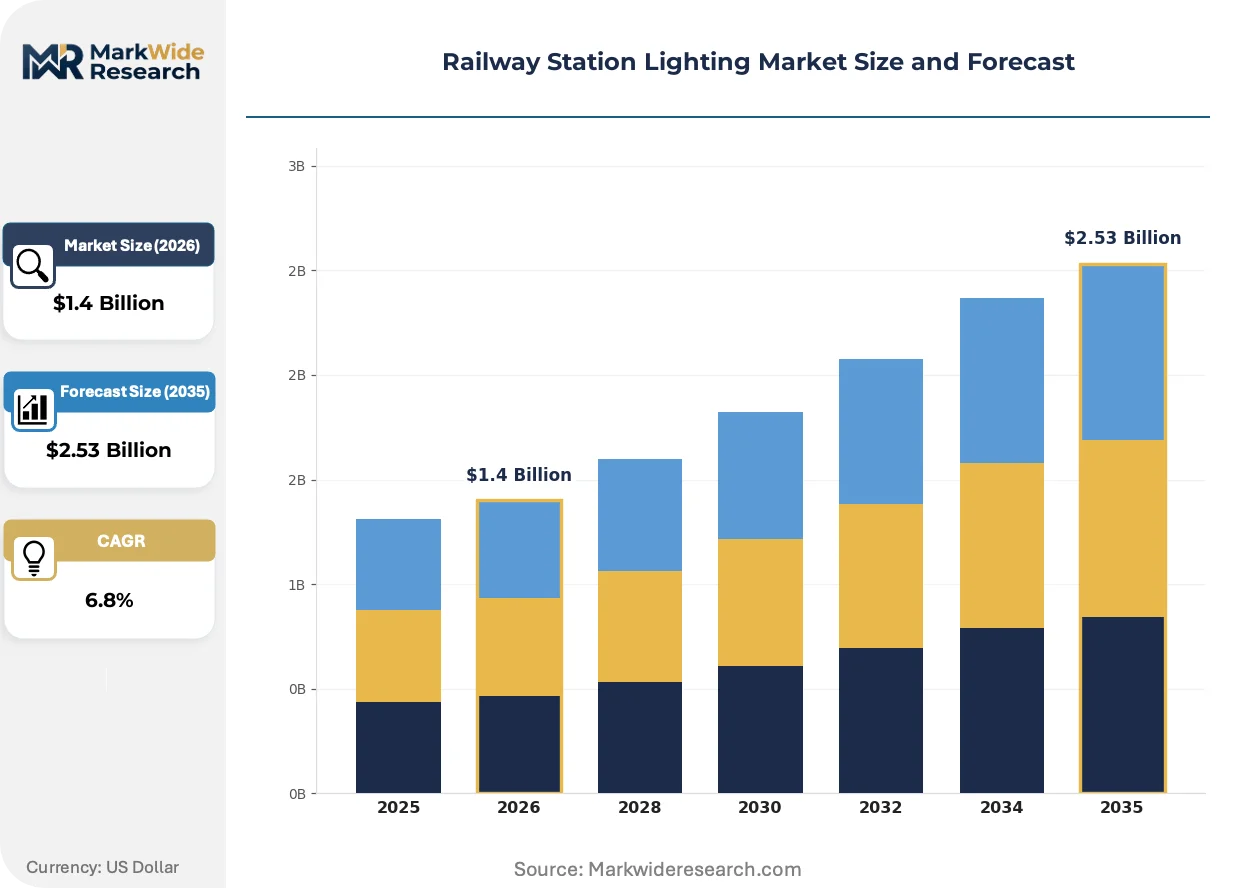
The Railway Station Lighting Market pivots on regulatory mandates forcing mercury-lamp retirement and platform electrification programs accelerating LED specification. Asia's high-speed rail operators and European Ecodesign Directive enforcement are compressing replacement cycles simultaneously.
Growth Catalysts
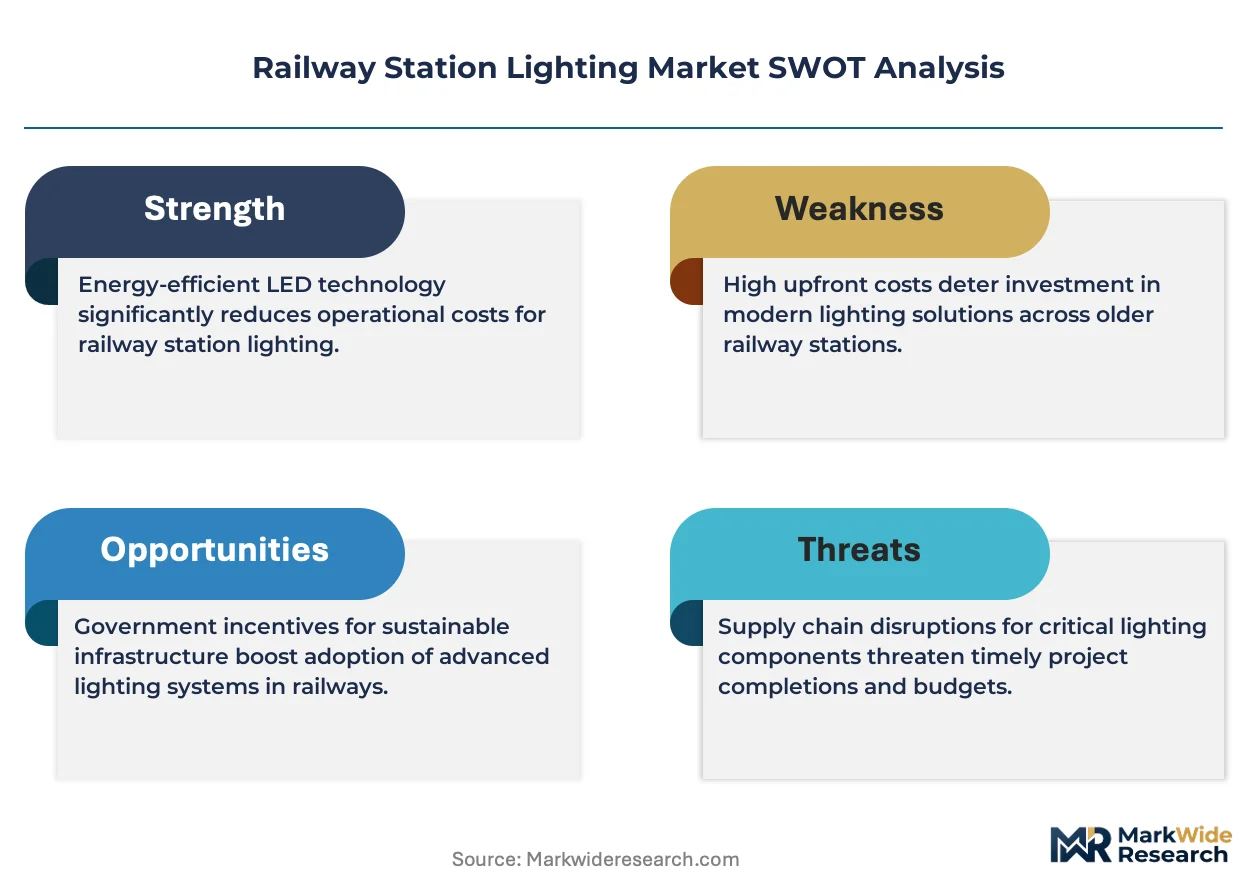
- LED efficacy thresholds:Lumen maintenance advantages in high-ceiling concourses reduce relamping frequency. Railway operators specify solid-state platforms for 24/7 operational visibility.
- India's Bureau of Energy Efficiency mandates:BIS certification requirements for LED luminaires reshape supplier qualification criteria across metro and station redevelopment tenders.
- Platform modernization programs:High-speed rail operators in Japan, China, and South Korea accelerate specification of vibration-resistant, IP-rated fixtures with emergency battery backup.
Market Restraints
- Phosphor and rare-earth price volatility:LED component supply concentrates in Chinese processing facilities, exposing procurement budgets to input cost swings.
- Legacy fluorescent disposal compliance:REACH substance restrictions impose mercury-bearing lamp collection and treatment costs that compress retrofit project margins.
- Technical limitation in extreme climates:Maintained output levels in sub-zero or high-humidity environments require specialized thermal management that extends lead times.
Strategic Opportunities
- Smart lighting convergence:Centralized dimming platforms integrating occupancy-based scheduling with building management systems open platform and parking area applications.
- India's dedicated freight corridors:Greenfield rail infrastructure creates specification windows unencumbered by legacy fixture compatibility constraints.
- Photobiological safety standard evolution:IEC 62471 certification requirements for blue-light hazard assessment differentiate premium suppliers in European hub tenders.
Industry Challenges
- Cybersecurity protocol gaps:Connected lighting network deployment outpaces IEC 62443 industrial control system security implementation, exposing operational technology infrastructure.
- Integration friction with legacy signaling:New LED installations must maintain electromagnetic compatibility with existing platform edge detection and track circuit systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Station Lighting Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Fluorescent, Halogen, Incandescent Application: Platform Lighting, Waiting Areas, Ticket Counters, Parking Areas Technology: Smart Lighting, Conventional Lighting, Solar-Powered, Motion Sensor End User: Railway Operators, Facility Managers, Contractors, Government Entities |
| Companies Covered | Philips Lighting (Signify), General Electric Company, Osram Licht AG, Siemens Mobility, Eaton Corporation, Zumtobel Group, Hubbell Incorporated, Acuity Brands Lighting, Schreder Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Station Lighting Market Trends and Innovations
Digital infrastructure convergence is reshaping how railway operators specify, procure, and maintain lighting systems. Three developments are compressing traditional equipment-supply models and elevating service-integrated offerings.
Human-centric lighting specification is bifurcating procurement tiers across European and Asian hub stations. Tunable white systems with circadian rhythm programming now anchor premium waiting area contracts, while basic platform illumination faces commoditization. Operators in Germany, the Netherlands, and Singapore are mandating melanopic lux metrics for staff facilities, compressing margins for suppliers lacking spectral engineering capabilities.
Europe's Ecodesign Directive and F-Gas Regulation are accelerating removal of mercury-containing lamps from railway procurement frameworks. The industrial consequence is a structural margin squeeze on fluorescent retrofit specialists facing material restrictions and disposal compliance cost inflation. India's metro networks are responding fastest, embedding BIS certification and energy performance standards into tender evaluation criteria that disqualify non-compliant bidders.
Specification authority is migrating from facilities departments to chief digital officers as lighting networks become data collection nodes. European operators now bundle sensor deployment with illumination contracts, displacing pure equipment vendors. This pattern concentrates in German and Swiss hub redevelopments where Interact-style connected platforms anchor multi-year service agreements.
Railway Station Lighting Market Segmentation
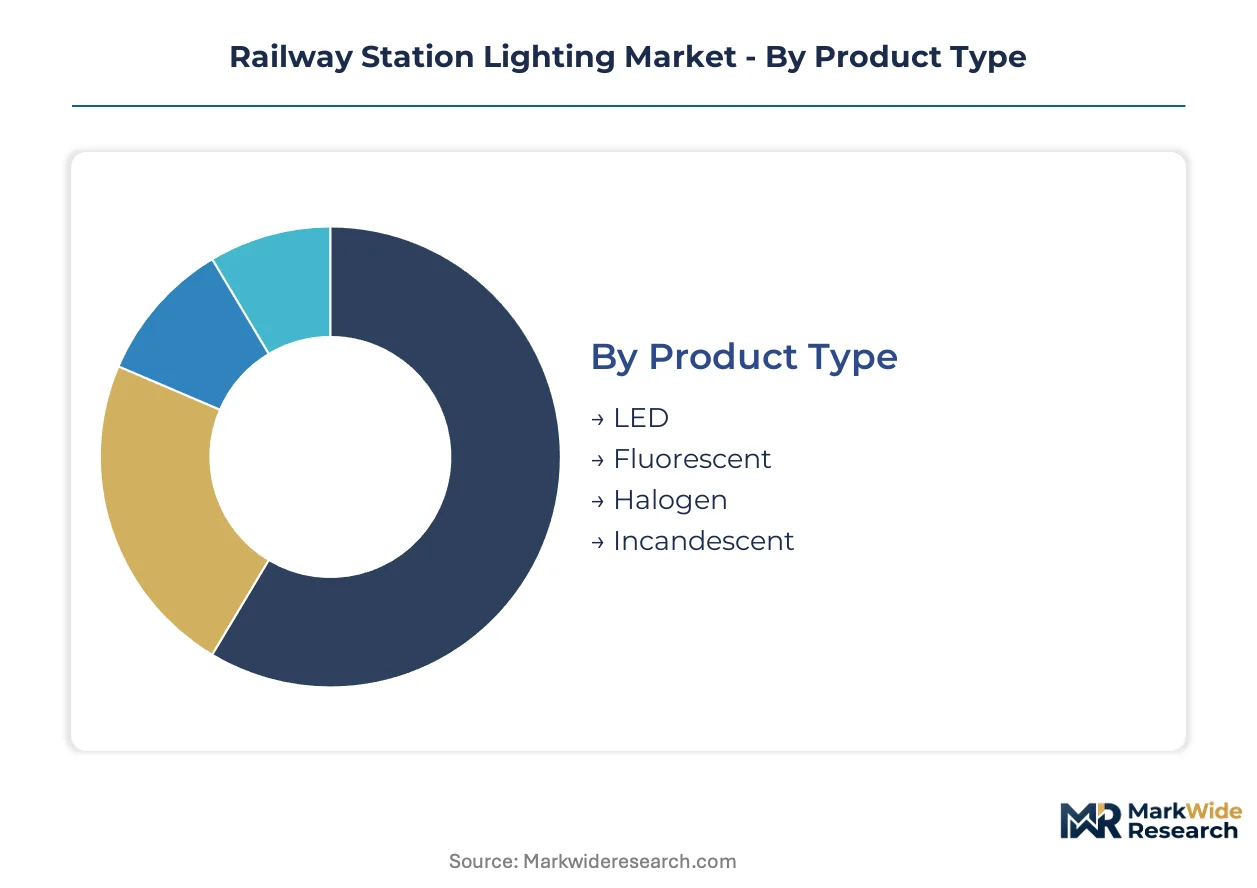
Railway station lighting procurement splits across four dimensions that shape vendor positioning and margin capture. Product type determines replacement cycle timing. Application dictates ingress protection and emergency backup specifications. Technology tier separates connected infrastructure from commodity supply. End user category influences contract structure and financing terms.
Product Type:
LED specification tiers face accelerating substitution pressure as mercury-bearing alternatives face regulatory phase-out across European and Asian procurement frameworks.
- LED:Solid-state platforms deliver lumen maintenance above 50,000 hours in high-ceiling concourses. Indian metro networks specify BIS-certified LED luminaires for platform edge visibility under Bureau of Energy Efficiency mandates.
- Fluorescent:Linear tube installations retain residual share in budget-constrained retrofit phases. REACH substance restrictions impose mercury collection costs that compress retrofit margins for facility managers in Germany and the Netherlands.
- Halogen:Tungsten-halogen sources persist in directional accent applications requiring precise beam control. Swiss and Austrian alpine stations specify these for cold-start reliability in sub-zero platform conditions.
- Incandescent:Filament technology survives only in heritage station restoration projects where aesthetic authenticity overrides efficiency metrics. British Rail and SNCF maintain limited procurement for listed building compliance.
LED retains volume leadership across all major procurement channels; halogen holds the steepest contraction trajectory as thermal efficiency standards tighten.
Application:
Cost tier differentiation separates safety-critical platform edge systems from amenity-focused waiting area specifications.
- Platform Lighting:Vibration-resistant IP65-rated fixtures with maintained emergency output serve dual purposes of passenger wayfinding and operational visibility. Japanese and Chinese high-speed rail operators specify these for 24-hour service corridors.
- Waiting Areas:Architectural-grade luminaires prioritize glare control and color quality for extended passenger dwell times. German and Dutch hub redevelopments mandate melanopic lux metrics for circadian rhythm programming.
- Ticket Counters:Task-optimized illumination balances staff visual comfort with transaction security requirements. Indian Railways embeds these specifications into station modernization tenders.
- Parking Areas:Wide-area flood and canopy systems integrate occupancy-based dimming to reduce energy consumption during low-traffic periods. Singapore MRT deploys smart controls across multi-story facility networks.
Platform lighting commands the highest specification intensity; parking area applications are expanding most quickly through smart retrofit programs.
Technology:
Customer type stratification separates digital infrastructure adopters from conventional equipment buyers.
- Smart Lighting:Centralized dimming platforms with sensor integration enable occupancy-based scheduling and building management system convergence. European hub redevelopments bundle multi-year service agreements with connected infrastructure.
- Conventional Lighting:Standalone switching systems persist in smaller stations and budget-limited maintenance programs. Rural Indian railway divisions specify these for freight corridor waypoints.
- Solar-Powered:Off-grid photovoltaic arrays with battery storage serve remote platform installations lacking grid connectivity. Australian and Saudi Arabian desert rail lines deploy these for signaling and perimeter illumination.
- Motion Sensor:Passive infrared and microwave detection systems trigger illumination on demand in low-traffic ancillary spaces. South Korean metro operators specify these for maintenance tunnels and storage areas.
Smart lighting captures the premium contract tier; solar-powered systems are gaining share fastest in greenfield corridor development.
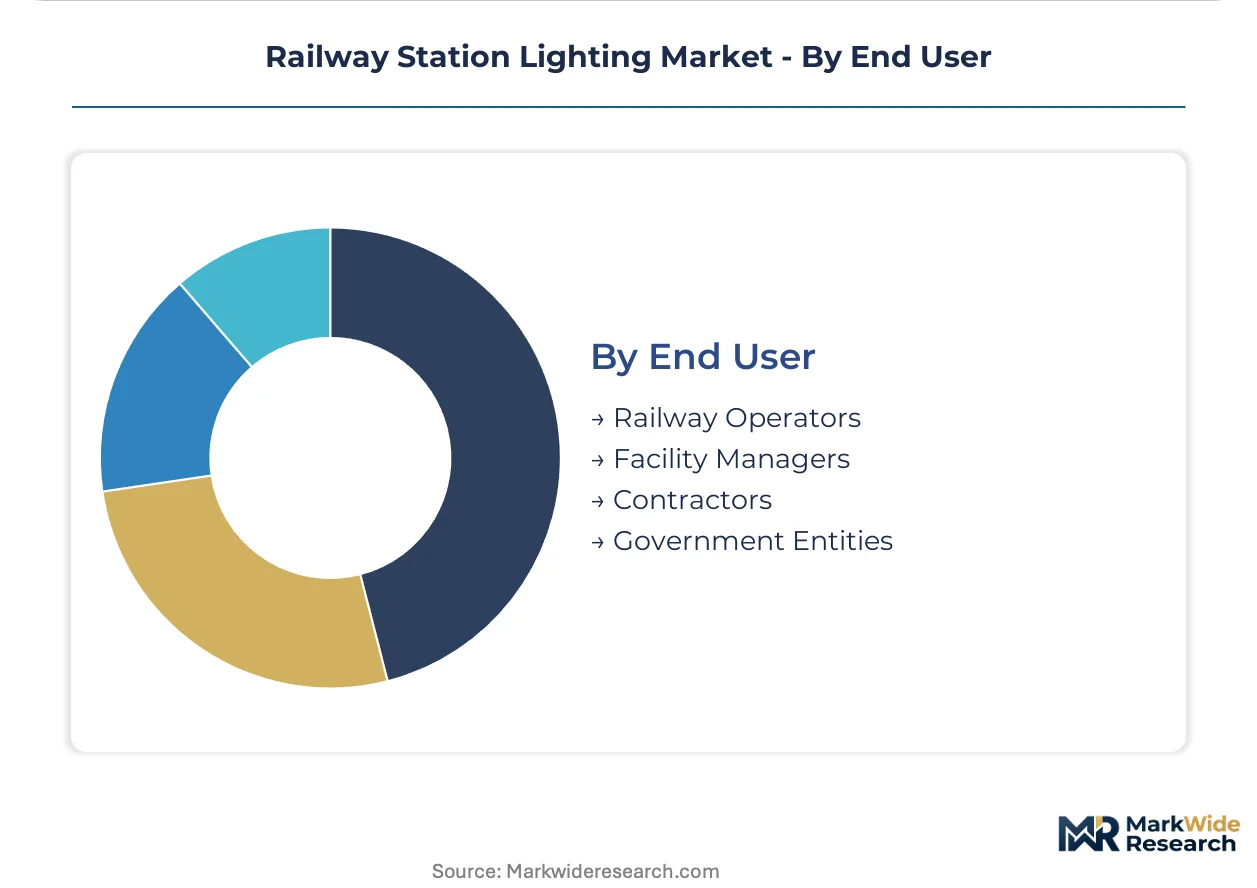
End User:
Supply concentration varies sharply between integrated rail infrastructure packages and fragmented maintenance procurement.
- Railway Operators:National and regional rail authorities specify lighting as component of platform electrification and safety system upgrades. Deutsche Bahn and JR East bundle lighting with signaling contracts.
- Facility Managers:Station concession holders and maintenance contractors prioritize relamping frequency reduction and energy cost control. Dutch NS Stations and British Network Rail outsource these decisions to facility service providers.
- Contractors:Construction and engineering firms specify lighting during new-build and major renovation projects. Indian dedicated freight corridor developers procure through EPC contract structures.
- Government Entities:Municipal and transport ministry procurement frameworks embed certification requirements and domestic content rules. Indian Bureau of Energy Efficiency and European Ecodesign Directive compliance gates shape vendor qualification.
Railway operators retain specification authority in safety-critical applications; facility managers are expanding their influence fastest through service-integrated contracting models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian railway operators demonstrate the highest price elasticity in platform lighting procurement, while German hub redevelopments prioritize melanopic lux certification over unit cost. This demand-elasticity contrast shapes supplier qualification criteria across procurement frameworks.
Germany
Deutsche Bahn's station modernization program specifies tunable white systems with circadian rhythm programming for staff facilities. The Ecodesign Directive and F-Gas Regulation enforce mercury-lamp retirement timelines that compress fluorescent retrofit margins. Berlin Hauptbahnhof and Munich Central Station anchor premium-tier specification clusters for human-centric lighting.
India
Bureau of Energy Efficiency mandates and BIS certification requirements reshape vendor qualification for metro and dedicated freight corridor tenders. LED luminaires dominate platform edge visibility specifications across Indian Railways station redevelopment programs. Mumbai Metro, Delhi Metro, and Dedicated Freight Corridor Corporation procurement concentrates volume in western and northern corridors.
China
High-speed rail operators accelerate vibration-resistant IP-rated fixture specification across 24-hour service corridors. The country's national standardization administration embeds energy performance thresholds into railway infrastructure procurement frameworks. Beijing, Shanghai, and Guangzhou-Shenzhen high-speed rail hubs concentrate smart lighting deployment with building management system integration.
Japan
JR East and JR Central bundle lighting with signaling and electrification contracts through integrated rail infrastructure packages. METI efficiency standards and JIS certification requirements govern platform luminaire specification for earthquake-resistant installations. Tokyo Station, Osaka Station, and Nagoya Station anchor premium specification clusters for passenger wayfinding systems.
Netherlands
NS Stations and ProRail mandate centralized dimming platforms with occupancy-based scheduling across platform and parking applications. REACH substance restrictions impose mercury-bearing lamp collection costs that disqualify non-compliant retrofit vendors. Amsterdam Centraal, Rotterdam Centraal, and Utrecht Centraal concentrate connected lighting service agreements with multi-year maintenance contracts.
Railway Station Lighting Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Railway Station Lighting Market. The vendor base stratifies into three tiers: integrated rail infrastructure providers bundling lighting with signaling systems, connected lighting specialists anchoring multi-year service agreements, and architectural-grade fixture manufacturers differentiating on color quality and glare control. Dominant competitive moves include strategic partnerships between lighting vendors and building management system providers, plus geographic expansion through hub station redevelopment tenders in Asia and Europe.
Within the integrated infrastructure tier, Siemens Mobility represents the bundled-system archetype combining lighting with electrification and platform safety systems. Signify anchors the connected lighting specialist position through its Interact platform deployment across European hub contracts. Acuity Brands Lighting exemplifies the architectural-grade differentiation archetype, occupying a position in premium waiting area specifications where melanopic lux metrics and circadian programming command contract premiums.
| Leading Market Players |
|---|
| Philips Lighting (Signify) |
| General Electric Company |
| Osram Licht AG |
| Siemens Mobility |
| Eaton Corporation |
| Zumtobel Group |
| Hubbell Incorporated |
| Acuity Brands Lighting |
| Schreder Group |
| Others |
Pricing and Supply Chain Analysis
LED chip fabrication scale economies in Chinese processing facilities anchor both supply concentration and price floors across procurement tiers. Railway operators purchasing BIS-certified luminaires for Indian metro networks face rigid cost structures that resist downward negotiation despite volume commitments.
Pricing Analysis
Europe's Ecodesign Directive dictates the pricing tier structure by mandating mercury-lamp retirement timelines that compress fluorescent retrofit margins. Three-tier pricing structure across premium, standard, and economy levels separates human-centric tunable white systems from basic platform illumination. Cost compression in the fluorescent retrofit tier is intensifying because REACH substance restrictions impose mercury collection and treatment compliance burdens. Facility managers in budget-constrained Indian railway divisions exhibit the highest price sensitivity, while German hub redevelopments prioritize melanopic lux certification over unit cost.
Supply Chain Analysis
Rare-earth element processing chokepoints in Chinese refining facilities expose LED phosphor supply to input cost volatility. Component manufacturing concentrates in China, South Korea, and Taiwan, with final assembly drawing from Mexican and Vietnamese facilities for North American delivery. Raw material dependencies span aluminum substrates, gallium nitride wafers, and emergency battery cells. Single-source vulnerability in phosphor supply creates procurement risk for European operators facing Ecodesign enforcement deadlines. Distribution runs through EPC contractors on greenfield corridor projects and facility service providers on retrofit programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capability scarcity in spectral engineering and IEC 62471 photobiological safety certification is concentrating contract awards among suppliers with in-house testing infrastructure. Railway operators now bundle sensor deployment with illumination contracts, displacing pure equipment vendors lacking digital integration competencies.
For Market Incumbents: Secure multi-year service agreements with European hub operators before specification authority migrates fully to chief digital officers. Invest in backward integration into gallium nitride wafer supply to buffer phosphor price volatility from Chinese processing facilities. Defend against connected lighting specialists by embedding cybersecurity protocols that satisfy IEC 62443 industrial control system requirements. For New Entrants and Emerging Players: Anchor in India's dedicated freight corridor greenfield tenders where legacy fixture compatibility constraints do not apply. Target solar-powered platform illumination for Australian and Saudi Arabian desert rail lines lacking grid connectivity. Pursue BIS certification early to qualify for Delhi Metro and Mumbai Metro procurement frameworks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among connected lighting platform providers with Interact-style building management system integration. Long-term viability over the next decade hinges on service-integrated contract structures that displace transactional equipment sales. Monitor BIS certification backlog and Ecodesign Directive enforcement intensity as inflection indicators for supplier qualification windows.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Lighting Platform Integration | Signify's Interact deployment across Amsterdam Centraal anchors multi-year service agreements with sensor bundling. |
| Photobiological Safety Certification | IEC 62471 compliance differentiates premium suppliers in Deutsche Bahn tenders for Berlin Hauptbahnhof redevelopment. |
| Backward Integration into LED Components | Captive gallium nitride wafer supply buffers procurement budgets from rare-earth processing volatility in Chinese facilities. |
| Greenfield Corridor Specification Capture | Indian Dedicated Freight Corridor Corporation tenders create windows unencumbered by legacy fluorescent compatibility constraints. |
| Cybersecurity Protocol Development | IEC 62443 implementation closes gaps as connected lighting network deployment outpaces industrial control system security standards. |
Research Methodology
Initial hypotheses were tested against primary input from railway procurement officers, facility management directors, lighting specification consultants, and EPC contract managers and refined through secondary validation. Railway operator tender documents, BIS certification registries, Ecodesign Directive implementation guidance, and customs import records for LED luminaires anchored quantitative sizing. Bottom-up project pipeline analysis and top-down infrastructure spending forecasts were triangulated to constrain variance.
Variance decomposition across product type, application, technology tier, and end user category shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro rail infrastructure investment trajectories. Forecast inputs incorporated Bureau of Energy Efficiency mandate timelines, high-speed rail platform modernization program announcements, and REACH substance restriction phase-out schedules.
Decision-makers should treat outputs as directional under stable regulatory enforcement and commodity input cost assumptions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as Ecodesign Directive implementation intensity and phosphor supply chain configuration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
United States Rail Freight Transport Market
Railway Transportation
Railway Hydraulic Damper Market
Railway Transportation
Brazil Rail Freight Transport Market
Railway Transportation
Railway Sleepers Market
Railway Transportation
Digital Axle Counter Market
Railway Transportation
China-Europe Rail Freight Transport Market
Railway Transportation
Global Train Signalling System Market
Railway Transportation
Japan Rail Freight Transport Market
Railway Transportation
Railroad Tank Car Market
Railway Transportation
Automatic Train Protection Signaling Market
Railway Transportation
Urban Rail Transit Market
Railway Transportation
Railway Fishplate Market
Railway Transportation
Railway Air Conditioning System Market
Railway Transportation
Global Autonomous Trains Market
Railway Transportation
Railway Control Stands Market
Railway Transportation
Overhead Catenary System Market