
 Auto Parts Manufacturing Market | 2026-2036
Auto Parts Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Auto Parts Manufacturing Market Intelligence
The tier-1 supplier-to-OEM procurement channel is reshaping as vehicle assemblers consolidate vendor lists and demand modular subsystem deliveries. Robert Bosch GmbH leverages its electronics integration depth to anchor long-term contracts for electric powertrain controllers. Continental AG competes through its specialized brake-by-wire and sensor fusion portfolios. Magna International sustains manufacturing scale across multiple geographies, giving it flexibility as regional content rules tighten.
Auto parts manufacturing encompasses the industrial production of vehicle subsystems and components, typically involving precision machining, stamping, casting, and injection molding of metals and polymers to tolerances measured in micrometers, with primary purpose of assembling reliable, safety-critical modules for passenger and commercial vehicles. Engine components and electrical systems represent the most mature revenue pools, while brake systems for regenerative energy recovery applications are expanding fastest as hybrid and electric architectures proliferate. Aluminum as a material category is gaining share against traditional steel as OEMs pursue mass reduction targets without sacrificing structural integrity.
The EPA, NHTSA, and EU Green Deal collectively dictate emissions thresholds, crashworthiness standards, and lifecycle carbon accounting that determine which suppliers qualify for platform business. REACH and RoHS frameworks in Europe restrict hazardous substances in electrical systems, compelling parts makers to reformulate coatings and solder compositions. Stakeholders must monitor how battery-specific safety certifications and evolving autonomous vehicle liability standards will redraw qualification barriers for component vendors.
Market Dynamics
The transition to electric vehicle platforms is compressing supplier qualification timelines while simultaneously demanding entirely new material competencies in aluminum forming and battery thermal management systems.
Growth Catalysts
- EU Green Deal carbon accounting:Lifecycle emissions mandates are pulling OEM procurement toward low-carbon aluminum and recycled polymer feedstocks, rewarding suppliers with verified Scope 3 reduction pathways.
- China EV verticalization:Domestic battery-electric brands are consolidating captive supplier networks around Shenzhen and Ningbo, creating concentrated demand pools for chassis and enclosure specialists.
- Regenerative braking hardware:Electrified powertrains require integrated brake-by-wire systems that recover kinetic energy, expanding addressable content per vehicle for friction material and sensor suppliers.
Market Restraints
- Lithium and rare earth price volatility:Battery enclosure manufacturers face margin compression when cathode material costs spike, as OEM contracts rarely pass through full raw material exposure.
- Single-source semiconductor dependency:Advanced driver-assistance system controllers rely on concentrated wafer fabrication in Taiwan, creating supply vulnerability for sensor fusion modules.
- REACH substance restrictions:European chemical frameworks are phasing out hexavalent chromium coatings and specific solder alloys, forcing reformulation investments before alternatives achieve scale economics.
Strategic Opportunities
- India PLI scheme for auto components:Production-linked incentives are attracting stamping and casting investments to Tamil Nadu and Gujarat as domestic OEMs expand EV assembly capacity.
- Battery second-life refurbishment:End-of-service EV packs are creating aftermarket demand for diagnostic equipment and cell replacement modules outside original OEM channels.
- Sensor fusion convergence:Lidar, radar, and camera data integration is opening white space for tier-1 suppliers capable of delivering unified perception hardware-software stacks.
Industry Challenges
- Aluminum extrusion and joining expertise gap:Battery enclosure welding and structural adhesive application require technician certifications that outpace vocational training program throughput.
- UN ECE R100 battery safety certification:Thermal runaway propagation testing timelines extend 14-18 months, delaying platform qualification for new enclosure designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Auto Parts Manufacturing Market |
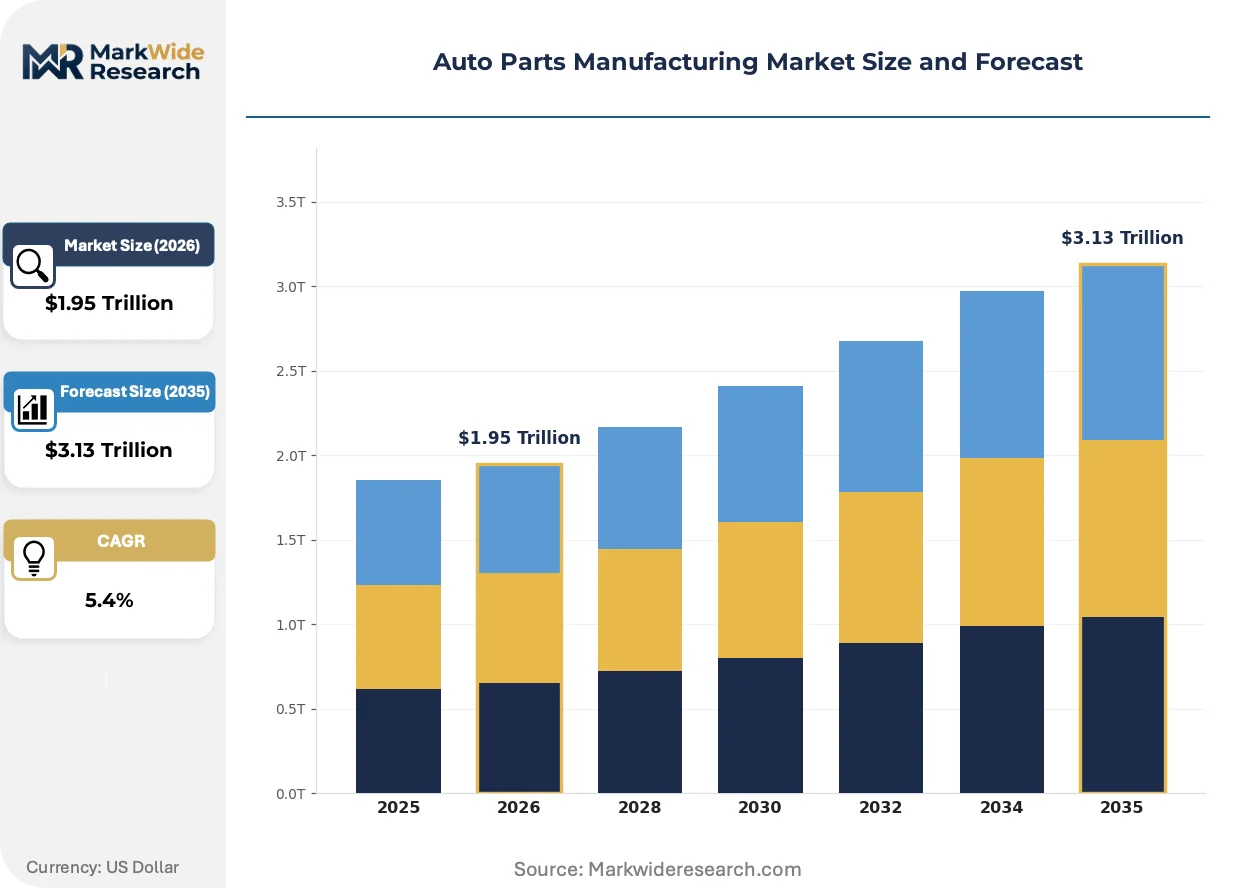
| Market Size in 2026 | $1.95 Trillion |
| Market Size in 2035 | $3.13 Trillion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Parts, Brake Systems, Electrical Systems Material: Aluminum, Steel, Plastic, Composite End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Manufacturing Stage: Design, Prototyping, Production, Assembly |
| Companies Covered | ZF Friedrichshafen, Bridgestone Corp, Robert Bosch GmbH, Continental AG, Sumitomo Electric Industries, Denso Corp, Aisin Corporation, Lear Corporation, Magna International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Auto Parts Manufacturing Market Strategic Shifts & Innovations
Digital thread integration across design, simulation, and production is collapsing development cycles while enabling mass customization of safety-critical components at automotive scale.
Digital twin simulation is digitizing how suppliers validate crashworthiness and thermal performance before physical prototyping. Tier-1 engineering teams in Germany and Japan are deploying real-time co-simulation environments that compress validation schedules by integrating finite element analysis with live sensor feedback from test fleets. This capability is digitizing the traditional build-test-iterate sequence that previously consumed 18-24 months for new platform qualification.
EPA tailpipe standards and NHTSA fuel economy mandates are tightening concurrently, forcing powertrain suppliers to optimize every subsystem for efficiency gain. The regulatory pressure is accelerating investment in variable displacement oil pumps and active grille shutter mechanisms that reduce parasitic losses. Suppliers serving the US pickup and SUV segments are most exposed, as these high-margin platforms face the steepest compliance cost escalation.
Fleet operators and mobility service providers are consolidating component procurement through long-term total-cost-of-ownership contracts rather than per-unit spot purchasing. This purchasing model shift is compressing supplier margins while demanding guaranteed uptime performance and predictive maintenance integration. The transformation is most advanced in European commercial vehicle markets where logistics operators operate centralized procurement functions for multi-brand fleets.
Auto Parts Manufacturing Market Segmentation

Segmentation in auto parts manufacturing determines which suppliers capture platform-level contracts versus commodity spot orders. Material choices and manufacturing stage capabilities increasingly separate vendors qualified for electric vehicle architectures from legacy internal combustion suppliers.
Product Type:
After-sales service intensity varies dramatically across product categories, with brake systems requiring frequent replacement and engine components demanding specialized diagnostic tooling.
- Engine Components:Pistons, cylinder heads, and crankshafts machined to micrometer tolerances from cast aluminum or forged steel. Demand concentrates in commercial vehicle fleets across the US and Germany as operators extend service intervals to minimize downtime. EPA emissions compliance is forcing redesigns of piston ring coatings to reduce friction losses.
- Transmission Parts:Gear sets, clutch packs, and torque converters for both automatic and dual-clutch architectures. Procurement is shifting toward integrated mechatronic modules as OEMs outsource complete transmission assembly to Magna and ZF Friedrichshafen. Dual-clutch penetration in European passenger cars sustains precision forging demand.
- Brake Systems:Friction materials, calipers, and brake-by-wire actuators with regenerative energy recovery integration. Replacement cycles create steady aftermarket revenue pools.
- Electrical Systems:Wiring harnesses, power distribution modules, and high-voltage connectors for electrified architectures. Copper conductor specifications are tightening as ampacity requirements rise.
Engine components hold the largest share; momentum sits with brake systems.
Material:
Cost tier stratification separates premium lightweight alloys from commodity steel grades, with composite materials commanding price premiums in motorsport-derived road car applications.
- Aluminum:Extruded and cast alloys for chassis structures, battery enclosures, and thermal management systems. Demand is climbing fastest in China as BYD and NIO expand aluminum-intensive platform production. The EU Green Deal carbon accounting favors low-carbon primary aluminum from hydro-powered smelters in Norway and Iceland.
- Steel:High-strength and ultra-high-strength grades for crash structures and body-in-white assemblies. ArcelorMittal and POSCO dominate advanced high-strength steel supply to German and Korean OEMs respectively.
- Plastic:Injection-molded polypropylene and polyamide for interior trim, underhood shields, and fluid reservoirs. Recycled content mandates in California and the EU are reformulating feedstock specifications.
- Composite:Carbon fiber reinforced polymers for structural battery enclosures and aerodynamic elements. BMW and Porsche programs in Germany sustain prepreg autoclave capacity utilization.
Steel maintains volume leadership; aluminum is expanding most quickly.
End User:
Customer type determines contract structure, with OEMs demanding long-term capacity guarantees and aftermarket providers prioritizing inventory velocity over technical integration.
- OEMs:Original equipment manufacturers specifying proprietary designs with exclusive tooling investments. Volkswagen Group and Toyota Motor Corporation maintain the most stringent supplier qualification protocols.
- Aftermarket Providers:Independent distributors and service chains sourcing reverse-engineered or licensed replacement parts. The US and Germany harbor the most consolidated aftermarket distribution networks.
- Tier-1 Suppliers:System integrators like Robert Bosch GmbH and Continental AG consolidating component procurement from sub-tier vendors. Their module-level deliveries to vehicle assemblers compress supplier margins while reducing OEM engineering overhead.
- Vehicle Assemblers:Contract manufacturers including Magna Steyr and Valmet Automotive purchasing components for third-party brand production. Their flexible capacity models favor suppliers with multi-platform tooling adaptability.
Tier-1 suppliers command the deepest supplier relationships; aftermarket providers deliver the steadiest replacement demand.
Manufacturing Stage:
Volume concentration in production-stage stamping and casting contrasts with high-margin prototyping services where engineering hours dominate cost structures.
- Design:CAD modeling, topology optimization, and design-for-manufacturing consulting. Siemens Digital Industries Software and Dassault Systèmes anchor this segment with integrated PLM platforms.
- Prototyping:CNC machining, 3D printing, and soft-tool injection molding for pre-production validation. Lead times here determine overall platform development schedules.
- Production:High-volume stamping, die casting, and injection molding with automated quality inspection. This stage captures the majority of capital deployment and employment in the sector.
- Assembly:Module integration, testing, and sequencing for just-in-time delivery to vehicle plants. Proximity to OEM assembly locations dictates facility location decisions.
Production absorbs the greatest capital investment; prototyping commands the highest margin per revenue dollar.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT anchors the dominant geography, where dual carbon goals and NEV mandates are restructuring supplier qualification protocols. The EU Green Deal and EPA tailpipe standards create parallel compliance corridors across three continents. Industrial clustering follows battery-electric platform investments.
China
Domestic EV brands BYD and NIO are consolidating captive supplier networks around Shenzhen and Ningbo, pulling chassis and enclosure demand toward aluminum specialists. MIIT's dual carbon goals mandate lifecycle emissions disclosure from tier-1 vendors. The Yangtze River Delta hosts the densest concentration of battery enclosure welding facilities, where technician certification programs lag behind production ramp schedules.
Germany
Volkswagen Group and BMW are enforcing EU Green Deal carbon accounting across their procurement networks, favoring low-carbon aluminum from Norwegian hydro-powered smelters. KBA administers UN ECE R100 battery safety certification timelines that extend 14-18 months for new enclosure designs. Baden-Württemberg's Stuttgart region maintains the deepest concentration of brake-by-wire engineering talent, where Continental AG and Robert Bosch GmbH anchor sensor fusion development.
United States
EPA tailpipe standards and NHTSA fuel economy mandates are forcing powertrain suppliers to optimize subsystems for efficiency gain in pickup and SUV segments. The Inflation Reduction Act's domestic content requirements are reshaping supplier location decisions for battery components. Michigan's Detroit-Toledo corridor retains stamping and casting capacity serving Ford and General Motors, though aluminum extrusion expertise concentrates in newer southern facilities.
Japan
Toyota Motor Corporation and Honda are maintaining stringent supplier qualification protocols while transitioning hybrid architectures toward full electrification. METI's battery safety frameworks align with UN ECE standards, creating compliance continuity with European exports. The Aichi Prefecture around Nagoya hosts Denso Corp and Aisin Corporation's integrated mechatronic module production, where sensor fusion hardware converges with legacy powertrain expertise.
India
Domestic OEMs Tata Motors and Mahindra are expanding EV assembly capacity, attracting stamping and casting investments through the PLI scheme for auto components. The country's national automotive regulator mandates AIS standards that parallel UN ECE frameworks for battery safety. Tamil Nadu and Gujarat harbor the fastest-growing supplier ecosystems, where vocational training programs for aluminum joining techniques remain underdeveloped relative to production timelines.
Auto Parts Manufacturing Market Key Industry Players
Integrated system architects and specialized component fabricators split the market along module-complexity lines. Tier-1 suppliers consolidate sub-tier procurement into delivered subsystems, compressing margins while reducing OEM engineering overhead. Three archetypes dominate: electronics-integrated powertrain specialists, multi-material structural component suppliers, and sensor fusion convergence players. Competitive positioning hardens through long-term platform contracts and geographic proximity to assembly plants.
Among German-based integrated suppliers, Robert Bosch GmbH and Continental AG exemplify the electronics-anchored archetype, while Magna International occupies a position spanning multiple material categories and geographies. These three represent divergent strategic postures within the tier-1 supplier tier: Bosch leverages controller integration depth, Continental competes through brake-by-wire specialization, and Magna sustains manufacturing scale across flexible capacity models. The archetype fragmentation reflects how electric platform transitions reward distinct capability bundles rather than uniform scale advantages.
| Leading Market Players |
|---|
| ZF Friedrichshafen |
| Bridgestone Corp |
| Robert Bosch GmbH |
| Continental AG |
| Sumitomo Electric Industries |
| Denso Corp |
| Aisin Corporation |
| Lear Corporation |
| Magna International |
| Others |
Cost & Logistics Intelligence
Taiwanese wafer fabrication concentration for ADAS controllers feeds directly into margin compression for European brake-by-wire module suppliers, as semiconductor pass-through limitations in OEM contracts trap tier-1 vendors between fixed pricing and volatile input costs.
Pricing Analysis
Chinese battery enclosure manufacturers quote 15-25% below German counterparts for equivalent aluminum extrusion specifications, though UN ECE R100 certification premiums sustain price stratification across premium, standard, and economy tiers. Price differentiation hinges on low-carbon aluminum verification and technician welding certification density. Cost compression in standard-grade chassis components is intensifying because domestic Chinese brands are consolidating captive supplier networks. Aftermarket distributors exhibit the highest price sensitivity, while OEM platform engineers prioritize qualification reliability over unit cost.
Supply Chain Analysis
Aluminum smelting capacity draws from China, Norway, and Iceland, with hydro-powered Nordic facilities commanding carbon-accounting premiums under EU Green Deal procurement rules. Lithium carbonate, rare earth magnets, and high-purity copper conductors anchor tier-1 dependency lists. Single-source vulnerability concentrates in Taiwanese semiconductor wafer fabrication for sensor fusion controllers. Distribution runs through just-in-time module sequencing direct to vehicle assembly plants, with proximity radius requirements tightening under Inflation Reduction Act domestic content rules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The auto parts manufacturing sector is cycling through a post-pandemic inventory restocking phase, with EV platform conversion timelines extending replacement demand for legacy internal combustion components through the mid-decade transition window.
For Market Incumbents: Entrench aluminum extrusion and battery thermal management capabilities through backward integration into low-carbon smelter offtake agreements, while consolidating brake-by-wire engineering talent in Stuttgart and Nagoya clusters against emerging Chinese sensor fusion competitors. Prioritize UN ECE R100 certification pipeline investments to maintain platform qualification velocity.
For New Entrants and Emerging Players: Establish a beachhead in India's Tamil Nadu and Gujarat supplier corridors, where PLI scheme incentives and underdeveloped aluminum joining training infrastructure create entry windows for certified welding program providers. Target battery second-life diagnostic equipment as the most penetrable aftermarket segment, leveraging independent service channel relationships outside OEM captive networks.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed brake system specialists holding fragmented European aftermarket distribution positions, where regenerative braking hardware convergence with sensor fusion creates strategic optionality. Long-term viability hinges on aluminum forming expertise transferability across ICE and EV architectures. Watch MIIT dual carbon disclosure mandates as the signal for supplier qualification barrier elevation in China.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Locks in cathode material capacity for enclosure manufacturers serving BYD and NIO expansion. |
| Software-Defined Vehicle Investment | Positions brake-by-wire suppliers for sensor fusion integration with Continental AG and Robert Bosch GmbH. |
| Geographic Manufacturing Footprint | Aligns stamping capacity with Inflation Reduction Act domestic content thresholds for US assembly. |
| Platform Standardization | Reduces tooling amortization across multiple OEM programs for Magna International flexible capacity model. |
| Charging Infrastructure Partnership | Creates aftermarket service channel access for battery diagnostic and refurbishment equipment providers. |
Research Approach
The analysis maps engine component machining, brake system integration, electrical system harnessing, and aluminum chassis forming, each validated through tier-1 supplier procurement officers, OEM platform engineers, aftermarket distribution managers, and vocational training program directors. Primary interview insights triangulate against vehicle production databases, IHS Markit registration data, SEC 10-K filings from listed suppliers, and EU ETS carbon disclosure registries. Bottom-up segment sizing and top-down macroeconomic anchoring cross-validate volume and value estimates.
Assumptions hold EPA tailpipe standard trajectories and EU Green Deal carbon accounting frameworks fixed while varying EV penetration rates and regional content rule stringency across scenarios. The projection framework segments by propulsion architecture, material category, manufacturing stage, and end-user type, with CAGRs derived from regression against historical platform conversion cycles and battery-electric production ramp schedules. Aluminum intensity per vehicle and technician certification throughput constraints feed directly into capacity modeling.
Sensitivities concentrate around lithium price volatility, semiconductor fab utilization rates, and UN ECE R100 testing timeline extensions. Forecasts reflect these documented assumptions; cross-checking against IEA critical minerals supply projections and MIIT NEV mandate enforcement patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Bevel Gearbox Market
Automotive Parts
Global Automotive Plastic Fuel Tank Market
Automotive Parts
Mexico Automotive Parts Aluminum Die Casting Market
Automotive Parts
Engine Fogging Oil Market
Automotive Parts
UK Automotive Parts Zinc Die Casting Market
Automotive Parts
France Passenger Vehicles Lubricants Market
Automotive Parts
Nigeria Automotive Lubricants Market
Automotive Parts
Bumper Beam Market
Automotive Parts
UK Automotive Parts Aluminium Die Casting Market
Automotive Parts
Automotive Control Arms Market
Automotive Parts
Global Automotive Jacks Market
Automotive Parts
Electric Vehicle Brake Pad Market
Automotive Parts
Motorcycle Catalyst Market
Automotive Parts
Automotive Mechanical Control Cable Market
Automotive Parts
Global Automotive Ignition Market
Automotive Parts
Automotive Piston Engine System Market