
 Railway Li-Ion Battery Market | 2026-2036
Railway Li-Ion Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Li-Ion Battery Market Insights
Battery lifecycle management services is rebalancing how rail operators contract energy assets, shifting capital expenditure toward performance-based agreements. Saft Batteries leverages its European service infrastructure to anchor long-term maintenance contracts across French and German networks. GS Yuasa competes through specialized thermal management systems that extend operational ranges in cold-climate corridors. Toshiba Infrastructure Systems dominates the Japanese market with integrated power electronics that reduce retrofit complexity for existing rolling stock.
Railway Li-Ion batteries are rechargeable electrochemical storage systems engineered with lithium iron phosphate, lithium nickel manganese cobalt, or lithium manganese oxide cathode chemistries, typically configured in 400-800 volt architectures to deliver sustained discharge rates for traction and auxiliary loads. These systems replace diesel generators and overhead catenary dependence in hybrid locomotives, metro trains, and trackside backup installations. Lithium iron phosphate chemistry leads in installed volume due to superior thermal stability and cycle life under continuous rail duty cycles, while lithium nickel manganese cobalt occupies premium positioning where energy density maximizes range in non-electrified corridors. Application demand fragments across high-speed trains adopting auxiliary power units for emergency propulsion and urban trams pursuing full battery-electric operation without overhead lines.
Europe's ECHA REACH framework and F-Gas Regulation restrict hazardous material content and fluorinated greenhouse gas use in battery thermal management systems, compelling manufacturers toward water-glycol cooling and solid-state electrolyte research. The EU Green Deal's rail modal shift targets reinforce these product standards by embedding carbon intensity thresholds into fleet procurement criteria. Japan's METI JIS standards and China's GB/T rail battery specifications create parallel compliance corridors that fragment certification requirements for multinational suppliers. Stakeholders must monitor how divergent safety testing protocols between these jurisdictions reshape product development roadmaps and regional manufacturing footprints.
Market Dynamics
Diesel-phaseout mandates across European rail networks are forcing operators to restructure propulsion procurement around battery-electric hybrids, compressing traditional rolling stock replacement cycles and redrawing supplier relationships around energy service capabilities rather than hardware transactions.
Growth Catalysts
- ECHA REACH framework:Chemical safety protocols are accelerating substitution of lead-acid and nickel-cadmium traction batteries with lithium-ion systems certified for hazardous material compliance in EU rolling stock.
- Urban tram networks:Catenary-free operation requirements in historic city centers are mandating onboard energy storage for full battery-electric routes without overhead infrastructure.
- Lithium iron phosphate cathodes:Superior thermal runaway resistance and 4,000-plus cycle life under continuous rail duty are displacing cobalt-rich chemistries in high-availability commuter applications.
Market Restraints
- Cathode active material concentration:Chinese processing dominance for lithium carbonate and cobalt sulfate creates input cost volatility and supply security exposure for European cell assemblers.
- Cell thermal management complexity:Water-glycol cooling system integration adds 15-20% pack mass overhead versus passive air-cooled alternatives, constraining energy density in weight-critical high-speed applications.
- Fluorinated gas restrictions:F-Gas Regulation phaseout timelines for hydrofluorocarbon-based cooling are forcing premature redesign of thermal architectures before next-generation solid-state electrolytes reach commercial maturity.
Strategic Opportunities
- Indian regional rail electrification:Dedicated Freight Corridor Corporation and suburban network modernization programs are creating first-mover positioning for traction battery system integrators outside established European supply chains.
- Second-life stationary storage:Decommissioned rail traction packs with 70-80% remaining capacity are redirecting toward trackside backup power and grid stabilization applications through circular economy service models.
- EU Green Deal modal shift incentives:Embedded carbon intensity thresholds in fleet procurement criteria are favoring battery-electric bids over hydrogen and overhead electrification in medium-density corridor tenders.
Industry Challenges
- Battery management system firmware certification:SIL 4 functional safety validation for traction control integration extends development timelines 18-24 months beyond hardware qualification.
- Electrolyte formulation standardization:Divergent JIS, GB/T, and EN fire-testing protocols force region-specific pack architectures that fragment manufacturing scale economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Li-Ion Battery Market |
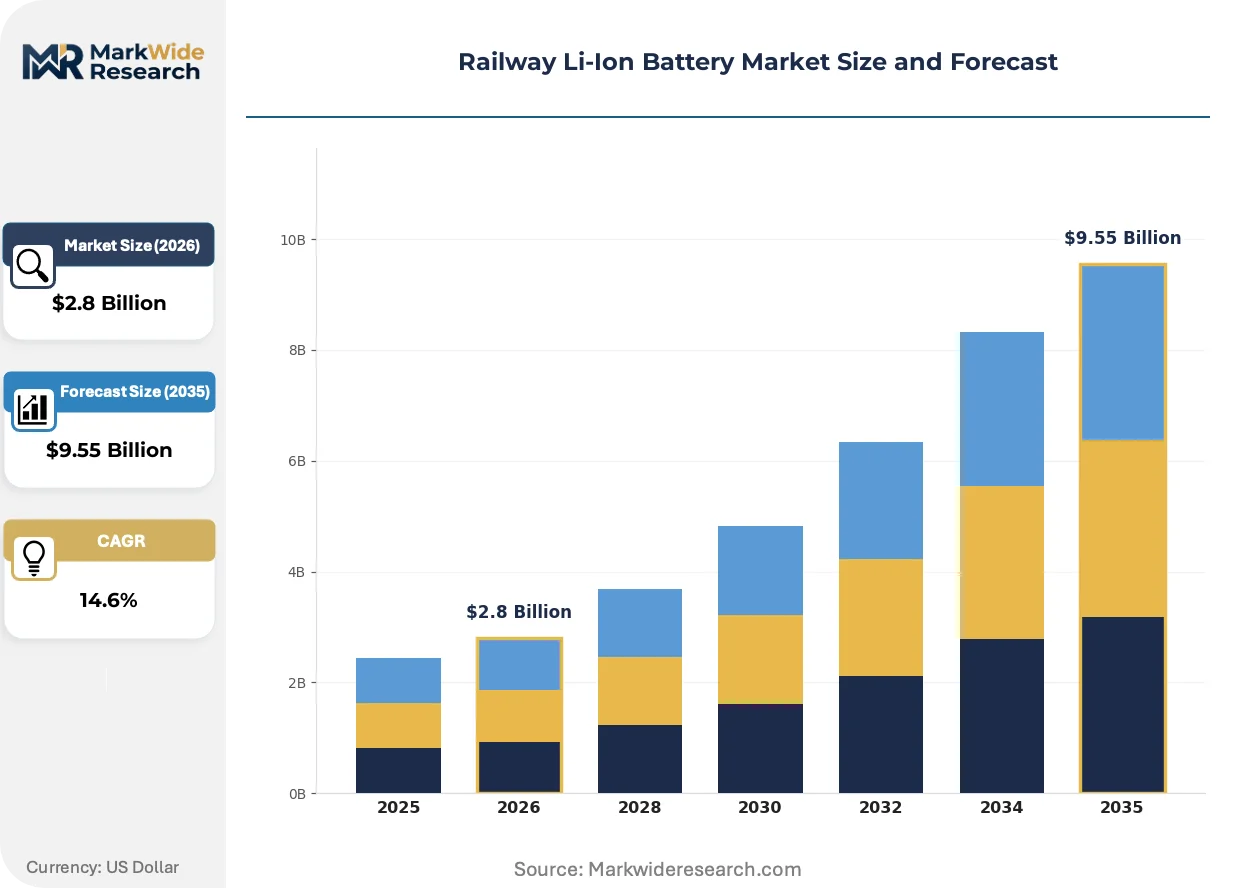
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium Iron Phosphate, Lithium Cobalt Oxide, Lithium Manganese Oxide, Lithium Nickel Manganese Cobalt Application: High-Speed Trains, Freight Trains, Urban Trams, Auxiliary Power Units End User: Rail Operators, Government Agencies, Private Rail Companies, Maintenance Providers Capacity: 100-200 Ah, 200-300 Ah, 300-400 Ah, 400-500 Ah |
| Companies Covered | Saft Batteries, GS Yuasa, Hoppecke, Toshiba Infrastructure Systems, Hitachi Rail, Leclanché, AKASOL AG, Kokam, Contemporary Amperex Technology Co. Limited (CATL), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Li-Ion Battery Market Trends and Innovations
Solid-state electrolyte development and silicon-anode integration are compressing the performance gap between rail traction requirements and automotive-derived cell formats, while regulatory carbon accounting is embedding battery lifecycle data into procurement scoring.
Silicon-carbon composite anodes are electrifying energy density benchmarks in next-generation traction cells by replacing graphite with 10x theoretical capacity material. German regional operators are piloting 400 Wh/kg prototypes for non-electrified corridor range extension. This chemistry is electrifying the economics of battery-diesel hybrid locomotives by reducing pack mass fractions below 12% of total vehicle weight.
F-Gas Regulation phaseout schedules are forcing immediate thermal architecture transitions in European rolling stock. Water-glycol cooling loops and phase-change material buffering are displacing hydrofluorocarbon refrigerants in battery pack climate control. High-speed train auxiliary power units face the most compressed redesign timelines as existing HVAC-integrated cooling circuits require complete re-engineering before 2027 compliance deadlines.
Performance-based service contracting is displacing capital purchase models for traction energy assets. French and German operators are unbundling battery hardware ownership from availability-guaranteed propulsion service agreements. This restructuring concentrates most visibly in Saarland and Bavaria regional networks where infrastructure funds prefer operational expenditure treatment over balance-sheet asset recognition.
Railway Li-Ion Battery Market Segmentation
Railway Li-Ion battery procurement decisions hinge on duty-cycle severity, thermal constraints, and ownership structure. Segment boundaries reflect how operators balance capital intensity against operational flexibility across electrification strategies.
Product Type:
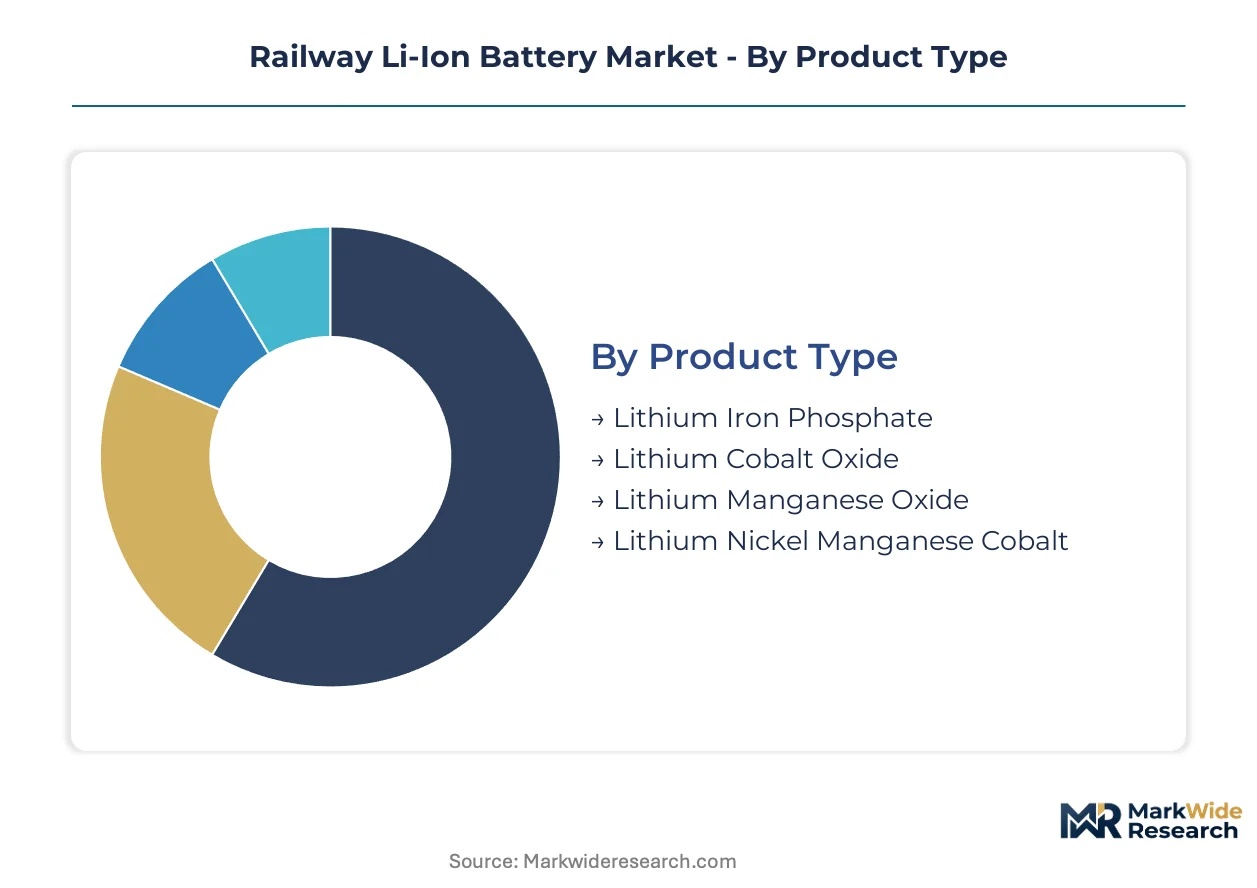
Cell chemistry selection determines thermal stability margins, cycle life economics, and compliance pathways under divergent national safety regimes.
- Lithium Iron Phosphate:Iron-phosphate cathode chemistry delivers 4,000-plus cycle durability and superior thermal runaway resistance under continuous rail duty. German regional operators specify this chemistry for commuter fleet modernization where catenary gaps demand predictable degradation curves.
- Lithium Nickel Manganese Cobalt:Nickel-rich layered oxide cathodes maximize gravimetric energy density for range-critical applications. French high-speed auxiliary power units adopt NMC packs to minimize mass penalties in emergency propulsion configurations where every kilogram affects traction performance.
- Lithium Cobalt Oxide:High-voltage cobalt oxide cells occupy niche positioning in premium auxiliary systems requiring compact form factors.
- Lithium Manganese Oxide:Spinel-structured manganese cathodes balance cost and safety for lower-duty backup power installations.
Lithium Iron Phosphate leads on scale; Lithium Nickel Manganese Cobalt leads on momentum.
Application:
Deployment context dictates pack architecture, discharge rate requirements, and integration complexity with legacy rolling stock.
- Urban Trams:Catenary-free operation in historic city centers demands onboard storage capable of sustaining full-route battery-electric propulsion. Italian and Belgian heritage tram networks are removing overhead infrastructure, concentrating procurement around 400-800 volt architectures with rapid opportunity charging interfaces.
- High-Speed Trains:Auxiliary power units for emergency propulsion and hotel loads require compact, fault-tolerant designs. Japanese Shinkansen operators specify SIL 4-certified battery management systems for traction control integration.
- Freight Trains:Heavy-haul hybrid locomotives utilize traction batteries for yard switching and last-mile diesel displacement.
- Auxiliary Power Units:Standalone energy storage for HVAC, lighting, and control systems operates independently of main propulsion.
Urban Trams command the steepest expansion trajectory; High-Speed Trains anchor current installed value.
End User:
Contracting structure—capital purchase versus performance-based service—varies sharply across ownership models and public funding mechanisms.
- Rail Operators:State-owned incumbents in Germany and France are unbundling battery ownership from availability-guaranteed propulsion services, shifting capital expenditure to operational expenditure treatment.
- Government Agencies:Infrastructure funds in Bavaria and Saarland prefer service contracts that remove assets from balance sheets.
- Private Rail Companies:Open-access freight operators prioritize total-cost-of-ownership optimization over upfront capital constraints.
- Maintenance Providers:Third-party servicers are capturing lifecycle management contracts as operators outsource thermal management and cell replacement.
Rail Operators dominate procurement volume; Maintenance Providers are gaining contract share fastest.
Capacity:
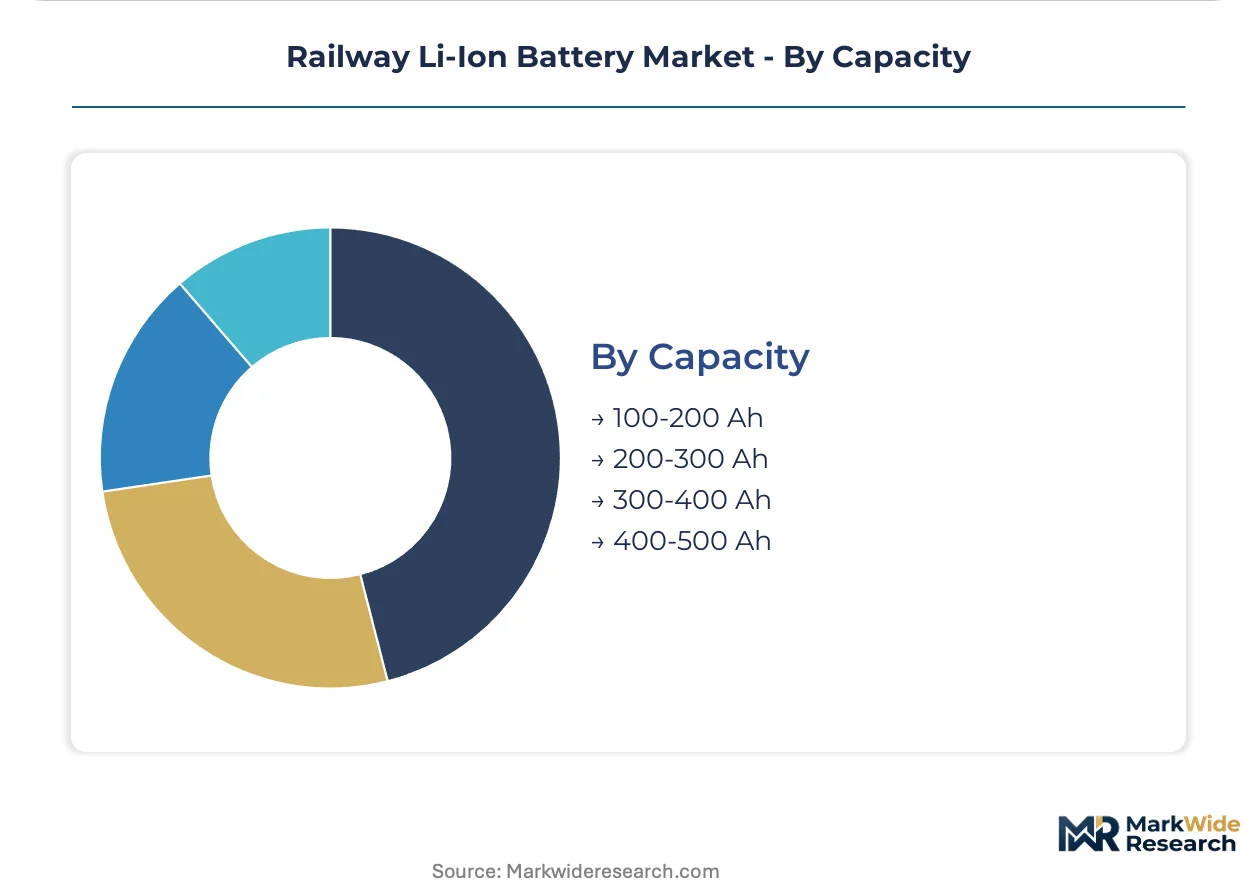
Energy storage scale determines vehicle range, charging frequency, and pack mass fraction relative to total vehicle weight.
- 300-400 Ah:Mid-range configurations balance energy density against thermal management complexity for regional commuter routes. German S-Bahn networks specify this tier for hybrid multiple-units operating on partially electrified corridors.
- 400-500 Ah:Maximum-capacity packs enable extended catenary-free operation. Indian Dedicated Freight Corridor pilots are testing 500 Ah systems for heavy-haul diesel-electric hybrids on non-electrified branch lines.
- 100-200 Ah:Compact auxiliary storage serves backup power and emergency propulsion functions.
- 200-300 Ah:Entry-level traction configurations address light-rail and tram applications with moderate range requirements.
300-400 Ah holds the broadest deployment base; 400-500 Ah shows the sharpest demand acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as European environmental compliance costs push cell assembly toward jurisdictions with streamlined chemical safety protocols. Producers are relocating final pack integration to avoid F-Gas Regulation thermal management redesign expenses.
Germany
Regional rail modernization programs in Bavaria and Saarland are procuring traction-grade battery systems for diesel-phaseout timelines. The KBA enforces ECE R100 battery safety certification for rolling stock homologation. Stuttgart's industrial cluster hosts thermal management specialists serving Deutsche Bahn's hybrid locomotive tenders.
Japan
Shinkansen auxiliary power unit retrofits are driving demand for SIL 4-certified battery management systems. METI JIS standards create parallel compliance corridors distinct from European EN protocols. Nagoya's Chubu region concentrates integrated power electronics manufacturers reducing retrofit complexity for existing rolling stock.
India
The Dedicated Freight Corridor Corporation and suburban network modernization programs are creating first-mover positioning for traction battery system integrators. BIS rail battery specifications under CEA oversight establish domestic content thresholds. Gujarat's manufacturing corridor is attracting pack assembly investments targeting regional rail electrification tenders.
France
High-speed auxiliary power units are adopting nickel-rich cathode chemistries to minimize mass penalties in emergency propulsion configurations. The EU Green Deal's rail modal shift targets embed carbon intensity thresholds into SNCF fleet procurement criteria. Auvergne-Rhône-Alpes hosts service infrastructure specialists anchoring long-term maintenance contracts.
China
GB/T rail battery specifications and dual carbon goals are accelerating domestic production scale for export-oriented manufacturers. MIIT standards on cell thermal runaway testing diverge from EN fire-testing protocols. The Yangtze River Delta concentrates cathode active material processing capacity for lithium carbonate and cobalt sulfate supply.
Railway Li-Ion Battery Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with European incumbents dominating service-integrated contracts while Asian fabricators capture cell supply tiers. The vendor base concentrates around three strategic archetypes: vertically integrated chemistry developers, thermal management system specialists, and lifecycle service operators. Consolidation pressures are intensifying through strategic partnerships between rolling stock OEMs and battery integrators, alongside capacity expansion into non-electrified corridor markets.
Within the European service-anchored tier, Saft Batteries and Leclanché exemplify long-term maintenance contract positioning across French and German networks. GS Yuasa occupies a distinct geography-first position among Japanese manufacturers, while Toshiba Infrastructure Systems represents integrated power electronics specialization reducing retrofit complexity. Contemporary Amperex Technology Co. Limited anchors the scale-driven chemistry supply tier for multinational cell procurement.
| Leading Market Players |
|---|
| Saft Batteries |
| GS Yuasa |
| Hoppecke |
| Toshiba Infrastructure Systems |
| Hitachi Rail |
| Leclanché |
| AKASOL AG |
| Kokam |
| Contemporary Amperex Technology Co. Limited (CATL) |
| Others |
Pricing and Supply Chain Analysis
Silicon-carbon composite anode adoption simultaneously compresses cell cost curves and redraws supplier power toward cathode active material processors in China and South Korea. This chemistry transition feeds pricing volatility through lithium carbonate and cobalt sulfate contract structures while opening margin recovery pathways for pack integrators with captive thermal management capabilities.
Pricing Analysis
Distributor margins in European traction battery procurement typically run 8-12% for cell supply, compressing to 3-5% for direct-to-OEM volume contracts above 50 MWh annual offtake. Three-tier pricing structure across premium SIL 4-certified, standard EN-compliant, and economy-grade regional variants separates buyers by functional safety requirements rather than energy density alone. Pricing pressure stems from Chinese cell oversupply in automotive formats spilling into rail-adjacent procurement, with spot lithium carbonate declines feeding buyer renegotiation leverage. Private freight operators exhibit highest price sensitivity due to unregulated tariff exposure, while government-funded regional networks absorb premium tiers for balance-sheet treatment advantages.
Supply Chain Analysis
Reverse-logistics networks for decommissioned rail traction packs are formalizing through second-life stationary storage channels, with 70-80% residual capacity cells redirecting toward trackside backup power before eventual recycling. Cathode active material supply concentrates in China's Yangtze River Delta and South Korea's industrial southeast, with European pack assemblers drawing from these hubs for lithium iron phosphate and nickel manganese cobalt inputs. Single-source vulnerability runs through Chinese lithium carbonate refining, where processing concentration creates input cost volatility independent of mining output. Distribution runs through rolling stock OEM captive channels for high-speed and heavy-haul segments, while urban tram procurement fragments across municipal tender platforms and regional infrastructure funds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Railway Li-ion battery margins are expanding through performance-based service contracting that captures lifecycle value beyond hardware shipment, with silicon-anode chemistry transitions enabling pack mass reduction premiums in non-electrified corridor applications.
For Market Incumbents: Extend service infrastructure footprints into Indian regional rail modernization and Eastern European diesel-phaseout corridors before emerging Asian integrators establish local certification capabilities. Lock in long-term cathode active material offtake agreements with Chinese and South Korean processors to defend against input cost volatility from battery-grade lithium carbonate spot market swings. Prioritize SIL 4 firmware certification investment as a barrier to automotive-format competitors lacking rail-specific functional safety validation timelines. For New Entrants and Emerging Players: Open-access freight operators in North American and Australian heavy-haul corridors represent the most penetrable buyer archetype, with these segments prioritizing total-cost-of-ownership optimization over incumbent brand loyalty and accepting shorter warranty terms for upfront capital relief. Target Indian Dedicated Freight Corridor and suburban electrification tenders where domestic content thresholds under BIS specifications favor local pack assembly partnerships over direct European import. Enter through thermal management subsystem supply to established integrators, building rail-specific track records before pursuing full traction system bids. For Investors and Strategic Acquirers: Roll-up economics work for regional service specialists with lifecycle management contracts because rail operator preference for operational expenditure treatment concentrates recurring revenue streams and creates sticky switching costs around availability-guaranteed performance agreements. Acquire targets with SIL 4-certified battery management system platforms and existing Deutsche Bahn or SNCF maintenance relationships, as these certifications require 18-24 month validation cycles that new entrants cannot shortcut. Monitor F-Gas Regulation compliance deadline acceleration and solid-state electrolyte pilot announcements as inflection signals for thermal architecture obsolescence risk and next-generation chemistry transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Active Material | Captive lithium iron phosphate processing insulates European assemblers from Chinese carbonate price volatility and supply security exposure. |
| Performance-Based Service Contracting | Availability-guaranteed propulsion agreements shift capital expenditure to operational expenditure treatment for German infrastructure funds. |
| Solid-State Electrolyte Pilot Programs | Water-glycol thermal architecture pre-positioning captures F-Gas Regulation compliance timelines before 2027 deadlines. |
| Second-Life Stationary Storage Partnerships | Circular economy service models extract residual value from decommissioned traction packs through trackside backup power redeployment. |
| Indian Regional Rail Electrification Joint Venture | Domestic pack assembly investments satisfy BIS content thresholds for Dedicated Freight Corridor and suburban network tenders. |
Research Methodology
Direct dialogue with rolling stock procurement directors, battery system engineering leads at Tier 1 integrators, thermal management specialists, and regional infrastructure fund managers grounded qualitative findings in operational decision-making realities. Secondary validation drew from Deutsche Bahn tender documentation, SNCF fleet procurement criteria, ECHA REACH substance restriction updates, METI JIS standard revision notices, and BIS rail battery specification drafts. Bottom-up cell deployment estimates by chemistry and application triangulated against top-down rail electrification investment forecasts from national infrastructure plans.
Bottom-up modeling tracked individual procurement events across German regional rail modernization, Indian Dedicated Freight Corridor expansion, and Japanese Shinkansen auxiliary power unit retrofit programs. Segmentation dimensions included cell chemistry, application type, capacity tier, and contracting structure. CAGRs were derived from installed base growth rates adjusted for replacement cycle compression under diesel-phaseout mandates. Industry-specific inputs incorporated F-Gas Regulation thermal architecture transition timelines and silicon-anode prototype energy density benchmarks from German regional operator pilot programs.
Inputs from rolling stock OEM engineering disclosures and national rail infrastructure procurement portals were available through the study window; gaps in pre-commercial solid-state electrolyte cost curves and second-life storage resale value data introduce uncertainty bands around long-term chemistry transition timing. Forecasts reflect assumptions regarding regulatory compliance deadline adherence and cathode active material supply chain stability. Practitioners should monitor ECHA substance restriction expansion proposals, MIIT cell thermal runaway testing protocol harmonization initiatives, and Indian PLI scheme rail battery eligibility clarifications for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Railway Hydraulic Damper Market
Railway Transportation
Poland Rail Freight Transport Market
Railway Transportation
Railway Air Conditioning System Market
Railway Transportation
Global Railway Wiring Harness Market
Railway Transportation
Japan Rail Freight Transport Market
Railway Transportation
High Speed Rail Coating Market
Railway Transportation
Global Rail Freight Transport Market
Railway Transportation
Railway Track Fittings Market
Railway Transportation
Canada Rail Freight Transport Market
Railway Transportation
Railway After-Cooler Market
Railway Transportation
Railway Control Stands Market
Railway Transportation
Radar and Lidar Technology for Railways Application Market
Railway Transportation
Overhead Catenary System Market
Railway Transportation
Australia Rail Freight Transport Market
Railway Transportation
Railway Station Lighting Market
Railway Transportation
Digital Railway Market