
 United States Rail Freight Transport Market | 2026-2036
United States Rail Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
United States Rail Freight Transport Market Analytics
Precision railroading specifications is collapsing the traditional service-cost tradeoff for bulk commodity shippers. BNSF Railway leverages its Southern California intermodal gateway dominance to control trans-Pacific container flows. Union Pacific Railroad anchors its competitive position through captive access to Powder River Basin coal and Wyoming soda ash deposits. CSX Transportation differentiates via concentrated Appalachian energy and chemical corridor density.
United States Rail Freight Transport encompasses the movement of goods via locomotive-hauled rolling stock over fixed-track infrastructure, typically operating at axle loads of 33-36 tons and train lengths exceeding 7,000 feet on mainline corridors. The system serves as the backbone for heavy, long-distance movements where rail's fuel efficiency of approximately 470 ton-miles per gallon outperforms over-the-road alternatives. Intermodal freight leads volume growth as manufacturing and retail shippers convert highway loads to rail for hauls exceeding 500 miles. Bulk commodities sustain the largest revenue pool despite slower expansion, reflecting entrenched agricultural and energy extraction dependencies across the Midwest and Great Plains. Carload services face structural pressure from trucking digitization yet retain defensive positions in non-containerized metals and construction materials.
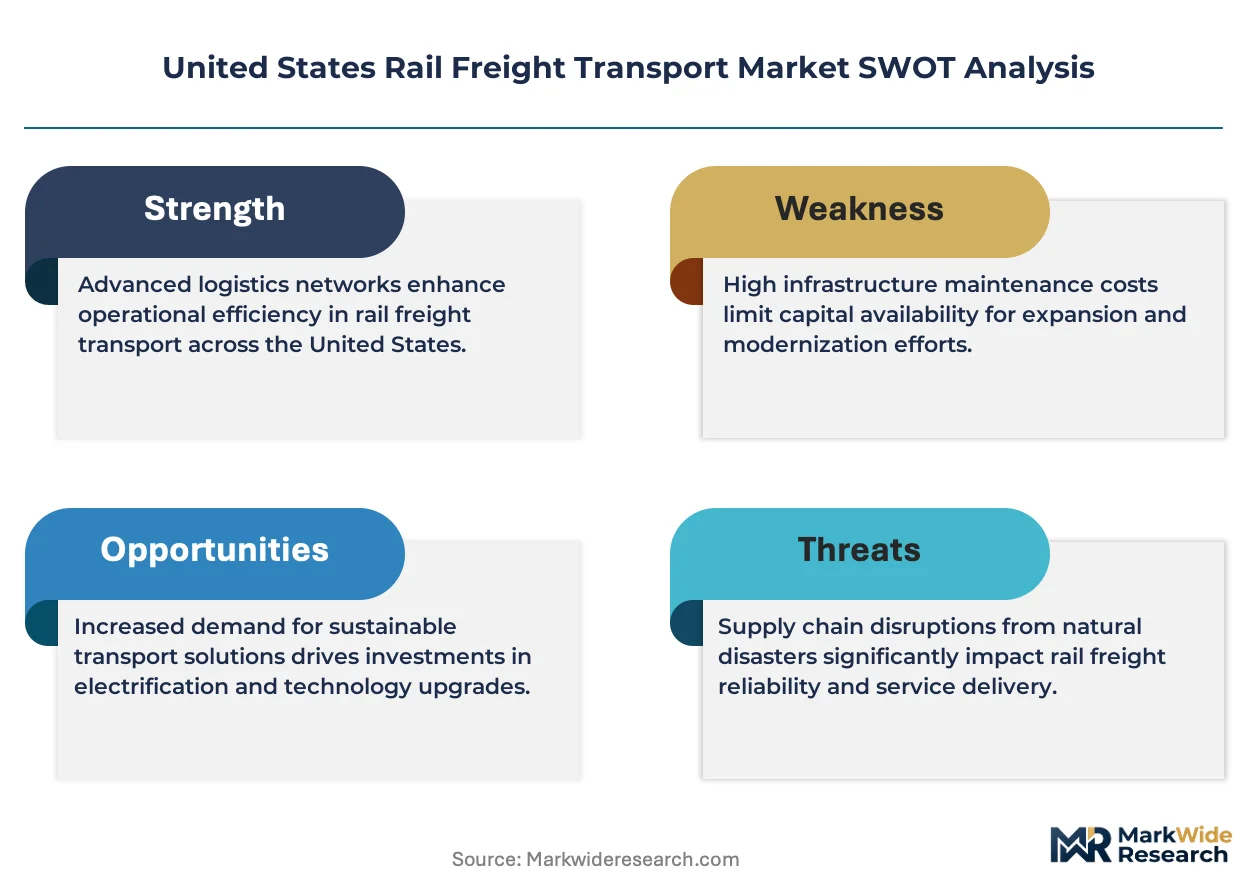
The Surface Transportation Board governs rate reasonableness and merger oversight for Class I carriers, while the Federal Railroad Administration enforces safety standards through Positive Train Control mandates and track integrity regulations. The EPA's locomotive emissions tiers and emerging state-level carbon disclosure requirements are redirecting capital toward battery-electric and hydrogen switcher pilots. Stakeholders must monitor STB regulatory appetite for reciprocal switching mandates and their potential to reshape network economics for captive shippers.
Market Dynamics
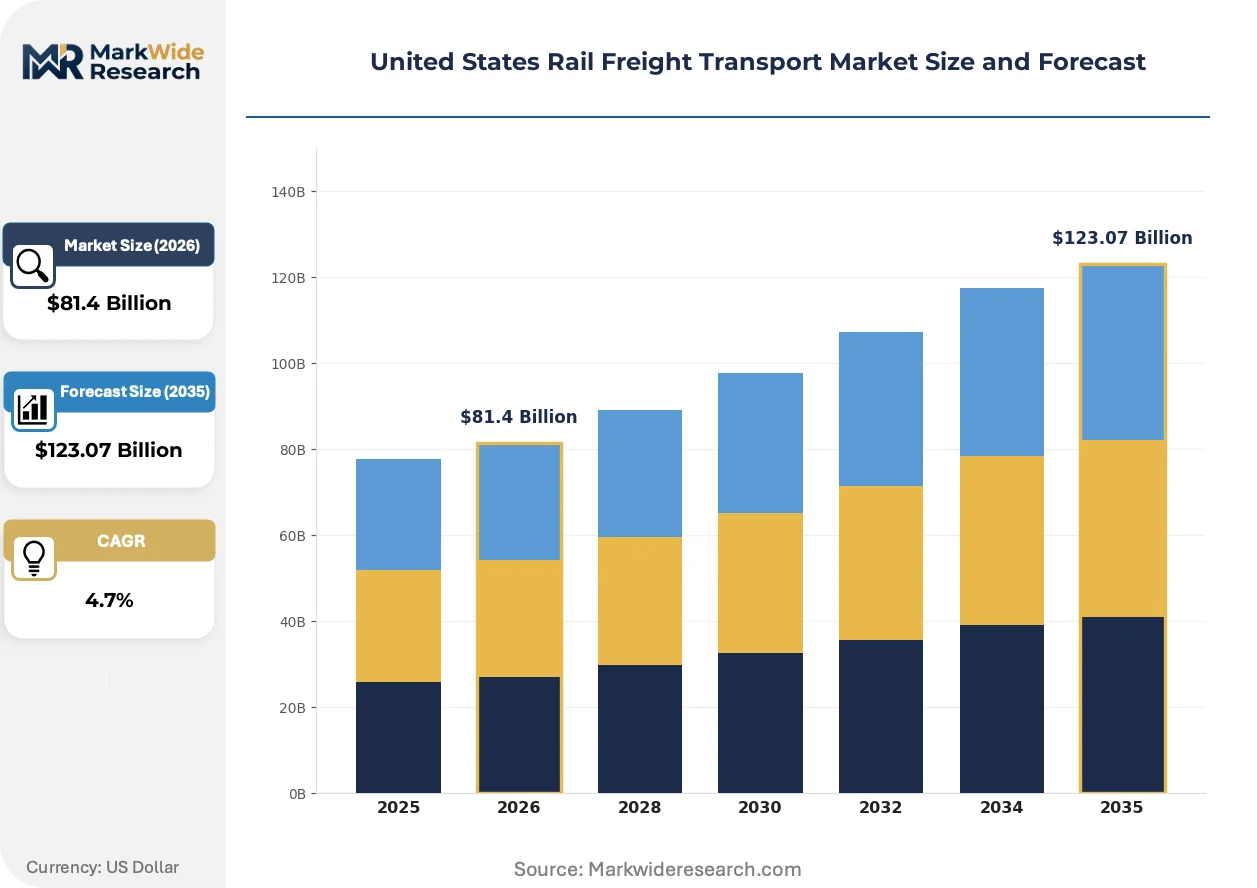
Precision Scheduled Railroading is collapsing traditional service-cost tradeoffs across Class I networks, forcing bulk commodity shippers to renegotiate long-term contracts around velocity guarantees rather than tariff rates.
Growth Catalysts
- Intermodal Conversion:Retail shippers exceeding 500-mile haul thresholds are converting highway freight to rail at accelerating rates, driven by diesel price volatility and chassis availability constraints at maritime ports.
- IRA Clean Energy Provisions:Federal tax credits for carbon capture infrastructure are stimulating newbuild pipeline-rail interchanges across the Permian Basin and Gulf Coast petrochemical corridors.
- Positive Train Control Mandates:FRA-mandated PTC deployment completion has unlocked mainline capacity through tighter headways, enabling 7,500-foot train operations on previously capacity-constrained corridors.
Market Restraints
- Labor Concentration Risk:Negotiated crew size minimums and conductor certification timelines constrain operational flexibility during demand surges, particularly in the Chicago terminal complex.
- Steel Input Volatility:Rail and wheelset procurement costs fluctuate with scrap metal and alloy pricing, compressing maintenance capital budgets during commodity upcycles.
- Trucking Substitution:Digitized freight brokerage platforms and autonomous truck pilots threaten 300-500 mile rail-competitive lanes, especially in the Southeast manufacturing belt.
Strategic Opportunities
- Texas Gulf Coast Expansion:Petrochemical export terminal buildouts at Corpus Christi and Houston are creating demand for unit train services serving ethylene and methanol producers.
- Battery-Electric Switching:EPA Tier 4 locomotive emissions standards are accelerating pilot deployments of battery-electric yard engines at California and Texas intermodal terminals.
- First-Mile Agriculture Integration:Short-line railroads serving Iowa and Illinois grain elevators are deploying mobile loading technology to capture corn and soybean flows currently moving by truck to river terminals.
Industry Challenges
- Locomotive Engineer Pipeline:Class I carriers face 18-24 month certification backlogs at Federal Railroad Administration-approved training centers, constraining crew availability during volume recoveries.
- Legacy Signal System Integration:PTC overlay installation on 1950s-era CTC territories requires custom engineering, delaying capacity expansion projects on secondary mainlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Rail Freight Transport Market |
| Market Size in 2026 | $81.4 Billion |
| Market Size in 2035 | $123.07 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Freight Type: Intermodal, Bulk, Carload, Auto Service Type: Long Haul, Short Haul, Transloading, Yard Operations End User: Agriculture, Manufacturing, Retail, Energy Technology: GPS Tracking, ELD, Automation, IoT |
| Companies Covered | BNSF Railway, Union Pacific Railroad, CSX Transportation, Norfolk Southern Railway, Canadian National Railway, Canadian Pacific Kansas City, Genesee & Wyoming, Patriot Rail Company, Watco Companies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Rail Freight Transport Market Evolving Landscape
Digitization of asset tracking and predictive maintenance is compressing equipment turnaround cycles, while emissions regulations redirect capital toward alternative propulsion pilots.
Distributed power technology is fragmenting traditional locomotive deployment models across heavy-haul bulk corridors. Unit train operators in Powder River Basin coal and northern Plains grain are adopting mid-train and rear-end helper configurations to manage in-train forces on 8,000-foot consists. This distributed architecture is fragmenting historical locomotive utilization patterns and reshaping maintenance scheduling around distributed asset pools rather than terminal-based fleets.
EPA locomotive emissions tiers are tightening particulate and NOx standards for newbuild and remanufactured engines, effective 2024-2027. The regulation forces premature retirement of pre-Tier 0 switcher fleets and redirects capital toward Tier 4-compliant line-haul acquisitions. California Air Resources Board companion rules are accelerating the same transition in Los Angeles Basin and San Joaquin Valley corridors, where air quality non-attainment designations trigger additional state-level compliance obligations.
Shippers are consolidating procurement authority under centralized transportation management systems, displacing decentralized plant-level rail buying. Large agricultural processors and chemical manufacturers are aggregating regional volumes to negotiate master service agreements with guaranteed capacity commitments. This concentration is most visible across Midwest manufacturing and processing facilities, where enterprise TMS platforms now govern modal selection and carrier allocation decisions previously managed by site logistics managers.
United States Rail Freight Transport Market Segmentation
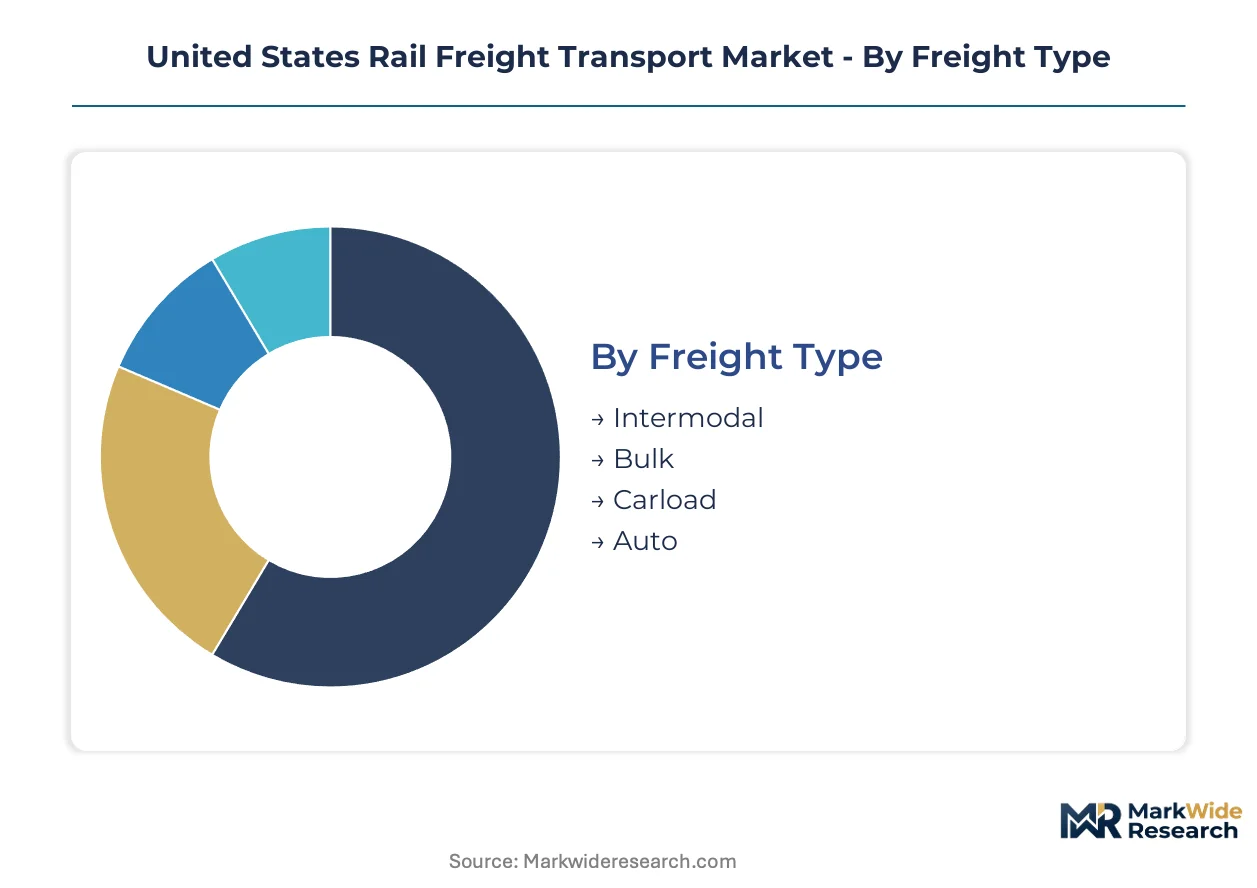
Rail freight segmentation reveals distinct operational economics across freight types, with each category demanding specialized equipment and terminal infrastructure. Service configurations and technology adoption patterns vary sharply between bulk commodity corridors and intermodal networks.
Freight Type:
Intermodal containers and bulk unit trains flow through fundamentally different channel structures, with the former relying on maritime port drayage and the latter on captive mine-to-plant circuits.
- Intermodal:Double-stack container movements combine ocean freight, rail haul, and truck drayage into integrated door-to-door service. Demand concentrates in the Chicago hub and Southern California gateway corridors, driven by retail inventory restocking cycles and trans-Pacific import volumes.
- Bulk:Commodity-specific hopper and tank car movements handle coal, grain, and chemicals in dedicated unit train configurations. Powder River Basin coal shipments and Gulf Coast petrochemical flows anchor revenue concentration, though coal volumes face structural decline from utility fuel switching.
- Carload:Mixed merchandise shipments in single-car or small-block configurations serve metals, forest products, and construction materials. Automotive parts and finished vehicle movements sustain dedicated service lanes from Michigan assembly plants to coastal distribution centers.
By volume, Bulk leads. By growth pace, Intermodal is ahead.
Service Type:
Cost tier differentiation separates premium velocity-guaranteed services from baseline tariff offerings, with margin structures widening between scheduled intermodal and opportunistic carload.
- Long Haul:Mainline movements exceeding 750 miles exploit rail's fuel efficiency advantage over trucking. Transcontinental intermodal services between West Coast ports and Midwest distribution centers command premium pricing through guaranteed transit windows.
- Short Haul:Regional movements under 500 miles compete directly with truckload carriers on lanes where terminal costs erode rail economics. Feeder services from inland ports to manufacturing clusters retain defensive positions in heavy commodity corridors.
- Transloading:Intermodal transfer facilities bridge incompatible equipment types, converting bulk commodities to containerized formats for final-mile delivery. Gulf Coast plastic pellet exports and Midwest grain containerization drive facility investment.
- Yard Operations:Classification, blocking, and switching activities within terminal complexes determine network velocity. Chicago's terminal congestion constrains national system capacity despite Precision Scheduled Railroading reforms.
Long Haul captures the revenue concentration. Short Haul is gaining share fastest through regional intermodal expansion.
End User:
Application-specific requirements shape equipment specifications, with agriculture demanding seasonal surge capacity and energy sector customers prioritizing unit train reliability.
- Agriculture:Seasonal grain movements from Iowa and Illinois elevators to Pacific Northwest export terminals and Gulf Coast processors. Harvest period volume spikes strain covered hopper availability and crew scheduling.
- Manufacturing:Just-in-time components and raw materials for automotive, steel, and chemical production. Indiana and Ohio industrial corridors generate dense carload demand for metals and plastics.
- Retail:Containerized consumer goods moving from West Coast ports to inland distribution centers. Big-box retailers negotiate multi-year capacity commitments during contract renewal cycles.
- Energy:Coal, crude oil, and frac sand movements tied to power generation and extraction activity. Permian Basin crude-by-rail volumes fluctuate with pipeline takeaway capacity constraints.
Energy historically dominated carload revenue. Retail intermodal now climbs the fastest as e-commerce fulfillment reshapes import logistics.
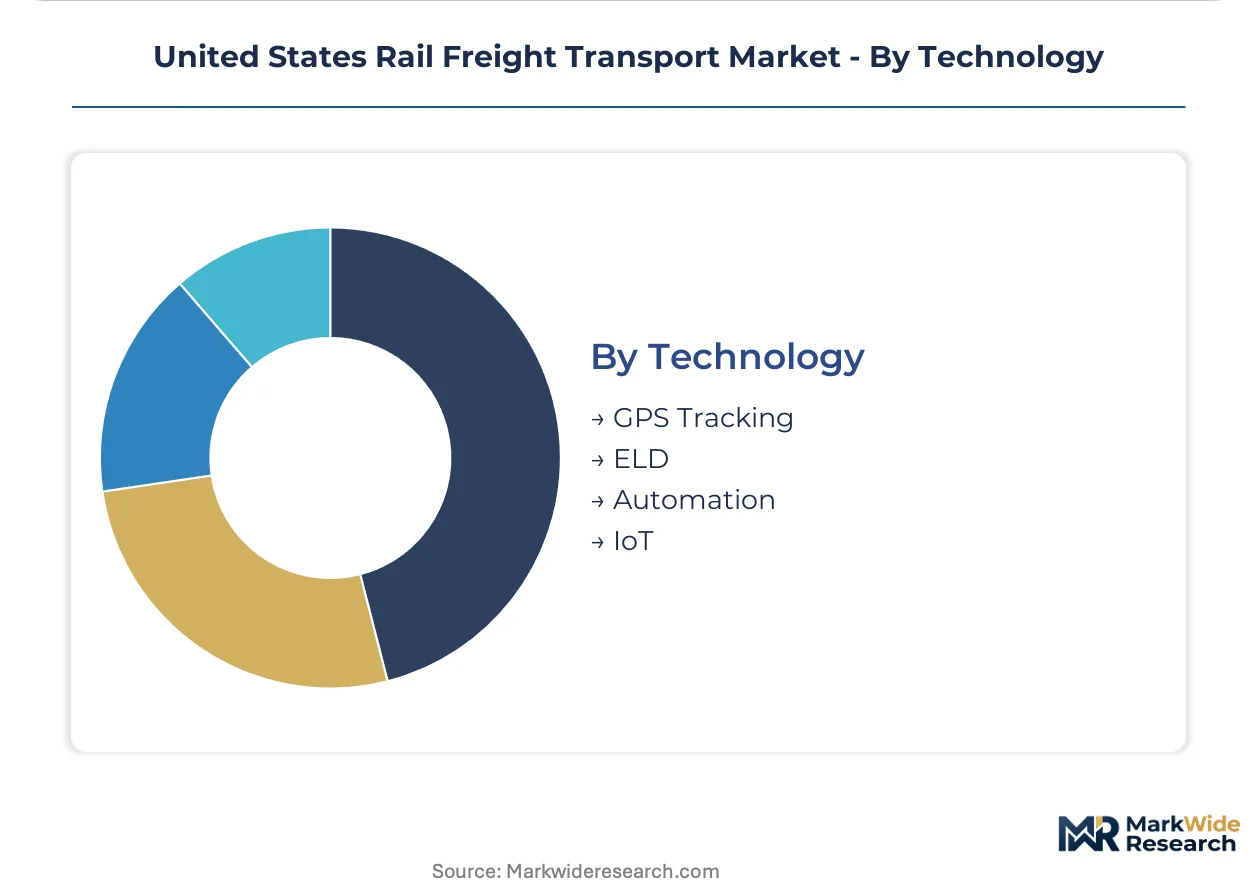
Technology:
Customer type segmentation separates asset-heavy Class I carriers investing in fleet-wide systems from short-line operators targeting point solutions.
- GPS Tracking:Real-time location monitoring of locomotives and rolling stock enables predictive arrival notifications and crew dispatch optimization.
- ELD:Electronic logging devices enforce hours-of-service compliance for operating crews, replacing paper logbooks with automated duty-time tracking.
- Automation:Autonomous track inspection vehicles and drone-based infrastructure monitoring reduce manual survey requirements.
- IoT:Sensor networks on bearings, brakes, and couplings generate predictive maintenance alerts before in-service failures.
GPS Tracking holds the widest deployment. IoT is expanding most quickly through component-level sensor standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States rail freight corridors channel agricultural exports from the Midwest to Pacific Northwest terminals and petrochemical flows from Texas to Gulf Coast ports. The Surface Transportation Board governs interstate rate disputes and merger approvals nationwide. Regional performance varies sharply across five freight-dense sub-regions.
Texas Gulf Coast
Petrochemical export terminals at Corpus Christi and Houston generate unit train demand for ethylene and methanol producers. EPA emissions tiers and Texas Commission on Environmental Quality permits govern locomotive operations in ozone non-attainment zones. The Houston Ship Belt corridor anchors heavy-haul chemical movements serving Mont Belvieu storage and processing complexes.
Chicago Hub
Transcontinental intermodal traffic converges at the nation's largest rail classification complex, handling container flows between West Coast ports and Eastern distribution centers. Federal Railroad Administration track safety standards and STB service metrics apply to terminal bottleneck remediation. Cook County and Northwest Indiana yard facilities process over 25,000 daily carloads despite persistent velocity constraints.
Powder River Basin
Wyoming coal deposits and soda ash reserves sustain bulk commodity movements via Union Pacific and BNSF captive routes. Mine Safety and Health Administration oversight combines with Surface Transportation Board rate reasonableness reviews for captive shippers. Campbell County and Big Horn Basin extraction sites feed unit trains to Midwest utilities and export terminals.
Pacific Northwest
Grain export terminals at Portland and Seattle receive corn and soybean unit trains from Iowa and Illinois elevators during harvest surges. Washington State Department of Ecology spill prevention rules supplement Coast Guard vessel traffic coordination. Columbia River Gorge corridors handle agricultural, energy, and intermodal flows through constrained mountain topography.
Southeast Manufacturing Belt
Automotive assembly plants in Tennessee and South Carolina generate finished vehicle and parts movements to coastal distribution centers. Federal Motor Carrier Safety Administration hours-of-service rules indirectly affect rail-truck competition on 300-500 mile lanes. Piedmont Atlantic freight corridors connect Charleston and Savannah ports with inland manufacturing clusters.
United States Rail Freight Transport Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and network scale dimensions. Seven Class I carriers dominate interstate commerce through consolidated mainline infrastructure, while short-line and regional operators fragment across 600+ localized networks. Strategic archetypes separate transcontinental integrators, captive corridor specialists, and asset-light terminal operators. Competitive moves concentrate on precision scheduled railroading implementation and intermodal terminal expansion.
Within the transcontinental integrator tier, BNSF Railway and Union Pacific Railroad occupy positions defined by Western corridor dominance and Southern California gateway control. CSX Transportation exemplifies the Eastern density archetype through concentrated Appalachian energy and chemical corridor access. Norfolk Southern Railway anchors Southeastern automotive and intermodal positioning. Canadian National Railway and Canadian Pacific Kansas City represent cross-border network extension strategies. Among short-line specialists, Genesee & Wyoming and Watco Companies sit within the regional aggregation model.
| Leading Market Players |
|---|
| BNSF Railway |
| Union Pacific Railroad |
| CSX Transportation |
| Norfolk Southern Railway |
| Canadian National Railway |
| Canadian Pacific Kansas City |
| Genesee & Wyoming |
| Patriot Rail Company |
| Watco Companies |
| Others |
Value Network & Pricing Analysis
Sixty-day locomotive delivery lead times from GE and Wabtec manufacturing facilities concentrate pricing power among Class I carriers with fleet-scale procurement leverage, while smaller regional operators face cost compression from equipment scarcity and steel input volatility. This inventory-to-pricing dynamic tightens most acutely during railcar manufacturing backlogs, when Powder River Basin coal shippers and intermodal retailers compete for constrained rolling stock capacity.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with Union Pacific and BNSF Railway negotiating tariff-plus-fuel-surcharge frameworks that tie rates to diesel price indices. Price differentiation separates velocity-guaranteed intermodal services from baseline bulk commodity movements, with retail shippers absorbing premiums for Chicago hub bypass routing. Cost compression in carload segments is intensifying because digitized freight brokerage platforms erode rail's competitiveness on 300-500 mile lanes. Agricultural processors exhibit highest price sensitivity due to seasonal volume spikes and alternative barge transport options, while petrochemical producers demonstrate lowest sensitivity given captive unit train infrastructure.
Supply Chain Analysis
Strategic stockpile preferences dominate rail equipment procurement, with Class I carriers maintaining 15-20% spare locomotive ratios to buffer against GE Transportation and Wabtec production delays. Manufacturing concentrates in the United States, Mexico, and Canada, with railcar fabrication anchored in tank car-specialized facilities across Texas and grain hopper production centered in Midwest industrial corridors. Steel plate, wheelsets, and braking systems constitute critical component dependencies, with alloy pricing volatility transmitting directly to maintenance capital budgets. Single-source vulnerability concentrates in positive train control signaling hardware, where limited certified suppliers constrain network expansion timelines. Distribution runs through captive terminal infrastructure, with Chicago classification yards and Southern California intermodal gateways functioning as irreversible chokepoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision Scheduled Railroading implementation creates a service-attach opportunity as velocity-guaranteed contracts expand faster than baseline tariff revenue, with shippers paying premiums for transit time certainty rather than commodity handling alone.
For Market Incumbents: Shield core intermodal corridors from trucking substitution by embedding sensor-based cargo monitoring into standard service tiers, converting commodity rail movements into differentiated logistics products. Lock in Powder River Basin and Texas Gulf Coast captive routes through backward integration into terminal infrastructure, neutralizing short-line competitive threats. Prioritize EPA Tier 4 locomotive certification investments to preempt California Air Resources Board compliance exclusions. For New Entrants and Emerging Players: Federal Railroad Administration conductor certification fast-tracks offer regulatory arbitrage opportunities for crew-constrained markets. Target battery-electric switcher deployments at California and Texas intermodal terminals, where emissions mandates create equipment replacement urgency underserved by incumbent locomotive lessors. Penetrate through first-mile agriculture integration, deploying mobile loading technology at Iowa and Illinois grain elevators currently bypassed by Class I networks. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-utility play because rail corridor access functions as irreplicable real estate with regulatory moats against greenfield competition. Acquisition targets should concentrate on short-line railroads with captive industrial park access and reciprocal switching rights into Class I networks. Monitor Surface Transportation Board service metric enforcement as the inflection signal—mandated velocity improvements would force capital deployment that compresses free cash flow yields.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Scheduled Railroading Expansion | Union Pacific and CSX velocity guarantees renegotiate shipper contracts around reliability metrics rather than tariff rates. |
| Battery-Electric Switcher Deployment | EPA Tier 4 compliance deadlines at California and Texas terminals accelerate pilot programs beyond incumbent fleet replacement cycles. |
| Intermodal Terminal Capacity Addition | Corpus Christi and Houston petrochemical export buildouts create unit train demand for ethylene and methanol producers. |
| First-Mile Agriculture Integration | Mobile loading technology at Iowa and Illinois grain elevators captures corn and soybean flows from truck-to-barge competition. |
| Positive Train Control Overlay Completion | FRA-mandated signaling upgrades unlock mainline capacity through tighter headways on previously constrained corridors. |
Research Methodology
Initial hypotheses were tested against primary input from Class I carrier operations executives, short-line railroad presidents, shipper logistics directors, and Surface Transportation Board regulatory staff, then refined through secondary validation against FRA safety filings, STB rate reasonableness dockets, and Association of American Railroads traffic statistics. Bottom-up equipment deployment models triangulated against top-down revenue concentration analysis across the seven Class I networks.
Variance decomposition across the projection horizon isolates volume drivers (intermodal conversion rates, bulk commodity demand) from pricing effects (fuel surcharge formulas, velocity premium adoption). Segmentation modeling incorporates freight type, service tier, end-use industry, and technology adoption dimensions. CAGRs derive from equipment replacement cycles, regulatory compliance deadlines, and shipper contract renewal patterns rather than extrapolated trend lines.
Underlying assumptions cover sustained diesel price volatility, EPA emissions tier enforcement timelines, and STB regulatory appetite for reciprocal switching mandates, with deviation risk concentrated in trucking substitution acceleration and locomotive engineer certification backlogs. Revision becomes warranted when autonomous truck pilot deployments cross commercial viability thresholds or federal infrastructure spending shifts modal subsidy balances.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Global Railway Wiring Harness Market
Railway Transportation
Composites in Passenger Rail Market
Railway Transportation
Germany Rail Freight Transport Market
Railway Transportation
Railway After-Cooler Market
Railway Transportation
Railway Traction Inverter Market
Railway Transportation
High Speed Rail Coating Market
Railway Transportation
Global Train Signalling System Market
Railway Transportation
Digital Axle Counter Market
Railway Transportation
Brazil Rail Freight Transport Market
Railway Transportation
Urban Rail Transit Market
Railway Transportation
Canada Rail Freight Transport Market
Railway Transportation
Radar and Lidar Technology for Railways Application Market
Railway Transportation
Digital Railway Market
Railway Transportation
Railway Radiator Market
Railway Transportation
Railway Air Conditioning System Market
Railway Transportation
Train Transformer Market