
 Global Train Signalling System Market | 2026-2036
Global Train Signalling System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Train Signalling System Market Outlook
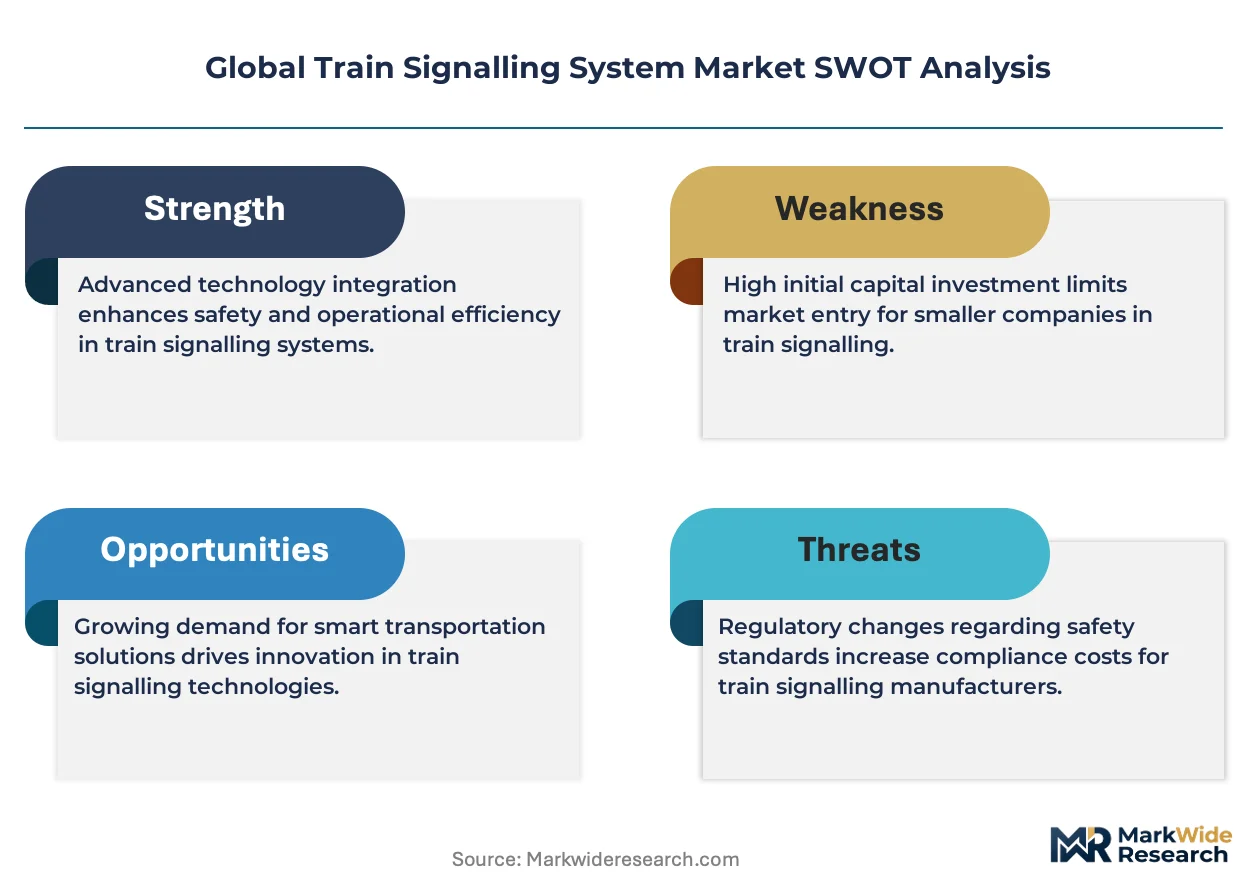
Fiber-optic cabling is recalibrating legacy copper-based signalling economics across mainline networks. Alstom leverages its integrated platform portfolio to dominate European high-speed corridors. Siemens Mobility anchors its position through deep backward integration into wayside control hardware. Thales Group differentiates via cybersecurity-hardened communication layers for urban transit operators.
Train signalling systems encompass the integrated hardware, software, and communication infrastructure that governs train movement authorization, speed enforcement, and route interlocking across rail networks, typically operating through redundant radio-frequency or track-circuit transmission protocols with sub-second response thresholds. The primary purpose is collision prevention and throughput maximization on shared infrastructure. European Train Control System deployment leads technology segmentation as cross-border interoperability mandates harden, while Positive Train Control captures North American replacement cycles. Urban Transit application segment concentrates margin pools where Communications-Based Train Control retrofits command premium pricing against constrained installation windows.
The Federal Railroad Administration enforces Positive Train Control compliance timelines across US Class I railroads, while the European Union Agency for Railways administers European Train Control System certification under EU interoperability frameworks. India's Ministry of Railways mandates indigenous signalling content thresholds through its phased manufacturing program. Stakeholders must monitor how digital signalling cybersecurity standards crystallize across jurisdictions before committing platform architectures.
Market Dynamics
Fiber-optic transmission protocols are displacing copper-based track circuits across mainline networks, recalibrating lifecycle economics and procurement specifications for infrastructure operators.
Growth Catalysts
- European Train Control System mandates:EU interoperability frameworks compel cross-border corridor upgrades, generating sustained procurement pipelines for rolling stock and wayside equipment across member states.
- Urban metro densification:Communications-Based Train Control retrofits in constrained installation windows command premium pricing from operators seeking capacity expansion without infrastructure footprint growth.
- India's Dedicated Freight Corridor:Ministry of Railways investment in dedicated freight infrastructure absorbs substantial signalling capital, with indigenous content thresholds reshaping supplier qualification requirements.
Market Restraints
- Copper cable replacement cycles:Legacy copper-based track circuits impose extended depreciation timelines, delaying full-fiber adoption despite superior performance characteristics.
- Specialized engineering labor scarcity:Radio-frequency protocol expertise concentrates among a limited pool of certified system integrators, constraining deployment velocity.
- Interoperability certification friction:European Union Agency for Railways certification timelines extend platform validation periods, compressing supplier revenue recognition windows.
Strategic Opportunities
- Southeast Asian greenfield metro networks:Vietnam, Indonesia, and the Philippines are accelerating urban rail procurement without legacy system encumbrance, enabling native CBTC deployment.
- Cybersecurity-hardened communication layers:Urban transit operators are prioritizing encrypted train-to-wayside protocols, creating differentiation space for suppliers with certified security architectures.
- Performance-based maintenance contracts:Availability-guarantee service models are displacing traditional time-and-materials arrangements in European high-speed corridors.
Industry Challenges
- Legacy system integration complexity:Hybrid architectures combining ETCS Level 2 with legacy national systems require bespoke interface engineering, extending project timelines.
- Radio spectrum allocation coordination:GSM-R successor bands remain contested across jurisdictions, forcing dual-mode radio investments pending regulatory clarity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Train Signalling System Market |
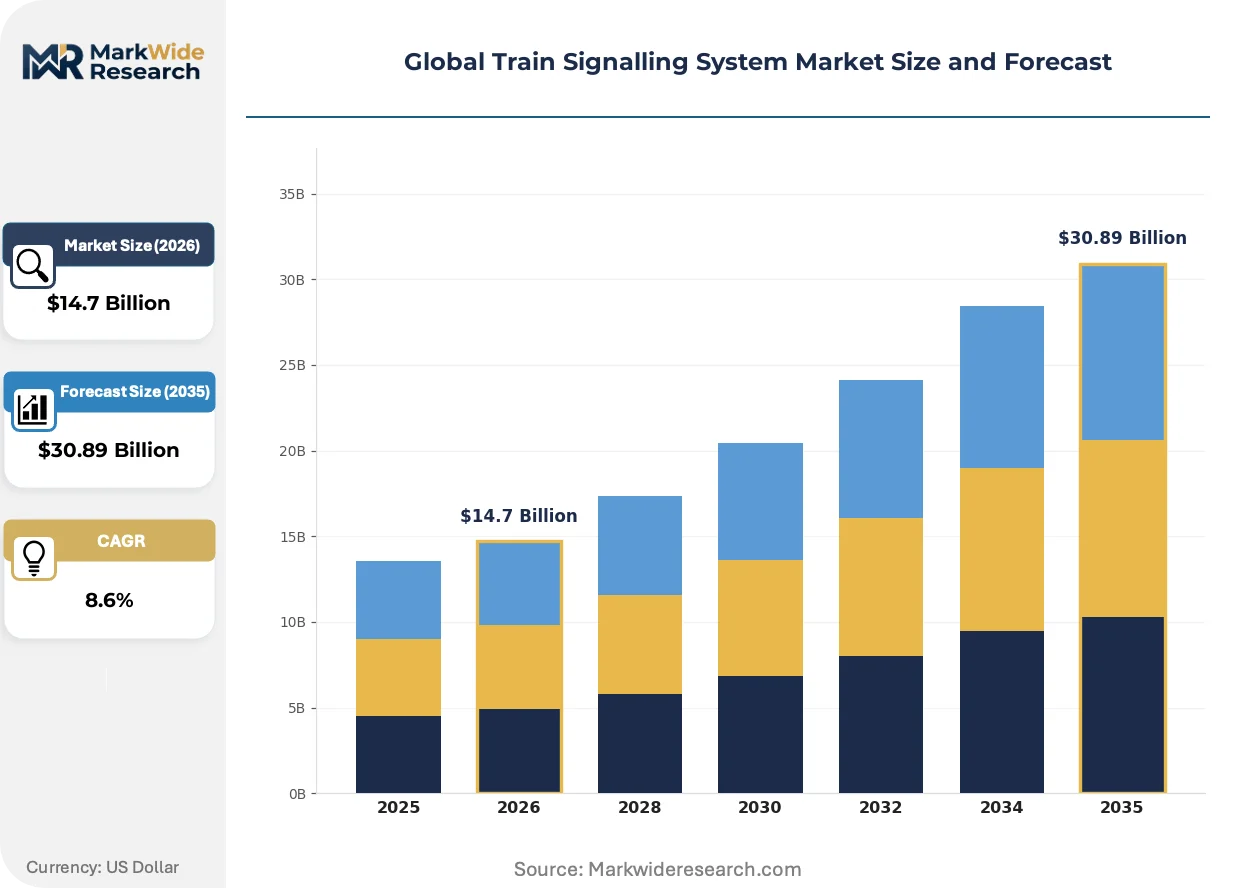
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Automatic Train Protection, Centralized Traffic Control, European Train Control System, Positive Train Control Application: Urban Transit, Freight Transportation, High-Speed Rail, Intercity Rail Component: Signals, Track Circuit, Control Center Equipment, Communication Systems Installation Type: Onboard Systems, Wayside Equipment, Integrated Systems, Standalone Solutions |
| Companies Covered | Alstom, Siemens Mobility, Thales Group, Hitachi Rail Limited, Cisco Systems, Huawei Technologies, Wabtec Corporation, Belden, Nokia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Train Signalling System Market Strategic Shifts
Digital signalling architectures are fragmenting traditional hardware-centric supply relationships, with software-defined functionality and cloud-based traffic management compressing equipment replacement cycles.
Moving-block signalling technology is modularizing train separation logic, enabling variable headway optimization based on real-time braking performance rather than fixed block occupancy. Urban transit operators in Singapore and Dubai are deploying these systems to achieve 90-second peak headways. The technology is modularizing supplier value capture toward software licensing and away from proprietary wayside hardware.
EU cybersecurity requirements for rail signalling are hardening under the Network and Information Security Directive implementation timelines. Critical infrastructure classification now mandates incident reporting and supply chain security attestations for signalling component vendors. European mainline operators are responding by embedding security specifications into tender documents ahead of formal certification availability.
Consolidated procurement consortia among national rail operators are displacing fragmented purchasing patterns. France's SNCF, Germany's DB, and Italy's Trenitalia have established joint framework agreements for ETCS onboard units, compressing supplier margins through volume aggregation. This concentration is most visible in European high-speed rolling stock programmes where standardization reduces per-unit engineering overhead.
Global Train Signalling System Market Segmentation
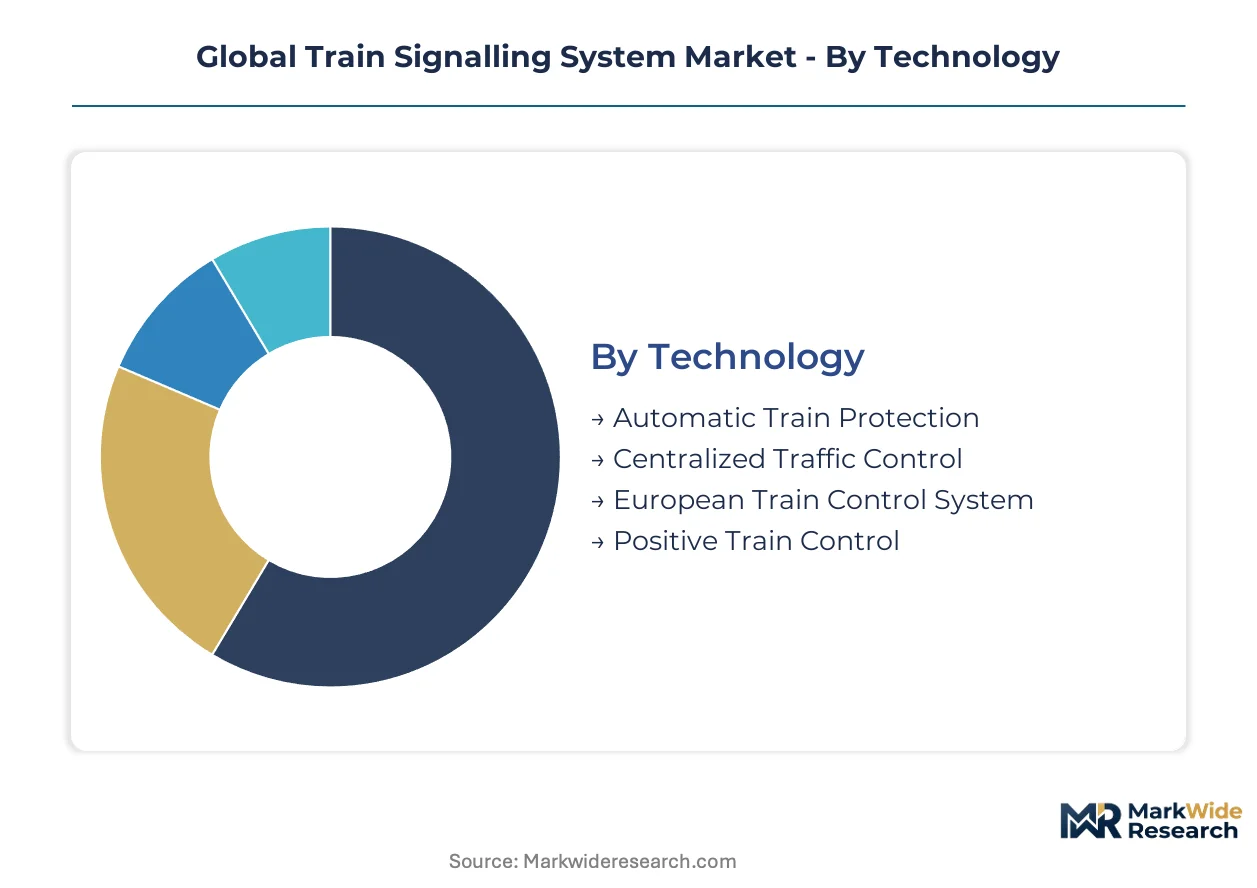
Signalling procurement specifications diverge sharply across deployment contexts, with certification requirements from the European Union Agency for Railways, Federal Railroad Administration, and India's Ministry of Railways each favoring distinct technology configurations. Component selection and installation architecture decisions cascade through lifecycle cost structures, maintenance protocols, and interoperability boundaries.
Technology:
Certification burdens cluster around cross-border mandates, with EU interoperability frameworks and US federal compliance timelines dictating validation scope for each platform variant.
- European Train Control System:Standardized train-to-ground communication protocols enable seamless cross-border operations across EU member states. Deployment concentrates in France, Germany, and Italy where national rail operators coordinate joint procurement frameworks. The European Union Agency for Railways administers baseline specifications and module certification.
- Positive Train Control:GPS-augmented enforcement systems mandate automatic speed compliance and collision avoidance on US Class I railroads. Federal Railroad Administration interoperability standards require dual-band radio architecture pending spectrum reallocation. Deployment focuses on Union Pacific, BNSF, and Norfolk Southern corridor densification.
- Automatic Train Protection:Legacy speed supervision systems remain entrenched in British and Japanese mainline networks requiring backward-compatible upgrades.
- Centralized Traffic Control:Dispatcher-centric route management dominates North American freight dispatch centers with centralized signal control.
European Train Control System sits at the top of the volume ranking, with Positive Train Control climbing the fastest.
Application:
Cost tier differentiation separates capital-intensive greenfield metro deployments from constrained retrofit budgets in mature networks.
- Urban Transit:Communications-Based Train Control retrofits in Mumbai, Delhi, and Singapore demand premium installation pricing against limited overnight maintenance windows. High-frequency operations prioritize sub-90-second headways and platform screen door integration.
- Freight Transportation:India's Dedicated Freight Corridor absorbs substantial signalling investment with indigenous content thresholds reshaping supplier qualification. Heavy-haul corridors in Western Australia and Brazil emphasize distributed power control and longitudinal train dynamics monitoring.
- High-Speed Rail:ETCS Level 2 deployment on Spanish, Turkish, and Saudi Arabian corridors requires dedicated radio block centres.
- Intercity Rail:Mixed-traffic mainlines in the United Kingdom and Netherlands balance passenger throughput with freight slot allocation.
Urban Transit commands the highest margin tier, while Freight Transportation shows the steepest expansion trajectory.
Component:
Supply concentration varies by hardware complexity, with control center equipment consolidating among integrated platform vendors and track circuits fragmenting across regional electrical contractors.
- Control Center Equipment:Integrated traffic management servers consolidate interlocking logic, automatic route setting, and disturbance recovery algorithms. Procurement clusters among Alstom, Siemens Mobility, and Thales Group framework agreements in France, Germany, and Italy.
- Communication Systems:Encrypted train-to-wayside protocols prioritize cybersecurity-hardened architectures for urban transit operators. EU Network and Information Security Directive implementation drives security specification embedding in tender documents.
- Signals:LED wayside indicators replace incandescent units across Indian and Southeast Asian networks.
- Track Circuit:Axle counters and audio-frequency jointless circuits dominate legacy replacement cycles in British and Japanese infrastructure.
Control Center Equipment captures the largest revenue share, with Communication Systems gaining share fastest.
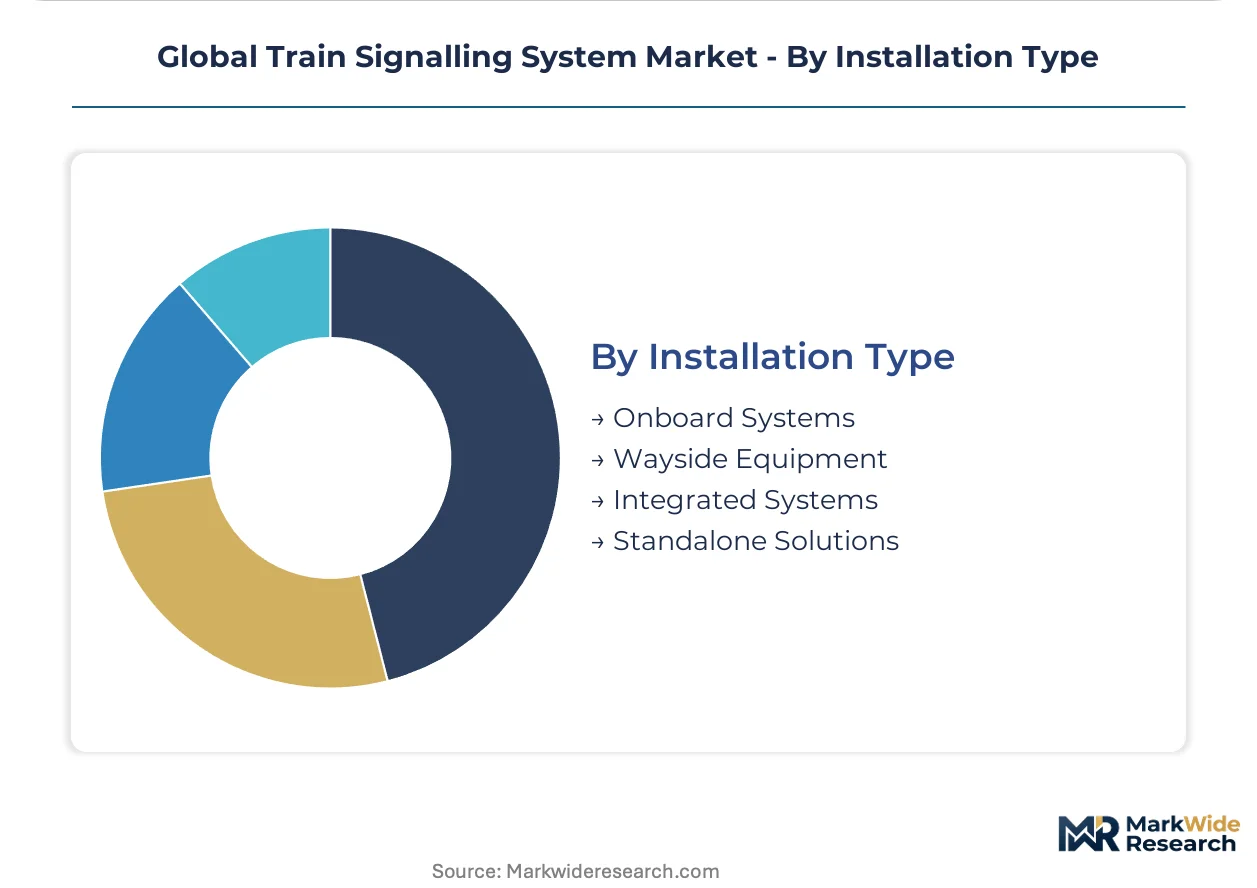
Installation Type:
Customer type segmentation separates rolling stock OEM integrations from infrastructure operator direct procurement, with diverging contract structures and warranty terms.
- Onboard Systems:ETCS onboard units with standardized European Vital Computer architecture enable interoperability across multinational rolling stock fleets. SNCF, DB, and Trenitalia joint framework agreements compress supplier margins through volume aggregation.
- Wayside Equipment:Radio block centres, balise groups, and lineside electronic units require civil engineering coordination and electromagnetic compatibility certification. Deployment in India's Dedicated Freight Corridor and Vietnam's metro greenfields proceeds without legacy encumbrance.
- Integrated Systems:Turnkey design-build-operate contracts combine onboard, wayside, and control centre elements under single-vendor accountability.
- Standalone Solutions:Point replacement of obsolete interlockings persists in budget-constrained regional networks.
Wayside Equipment leads installation expenditure, with Onboard Systems expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Dedicated Freight Corridor industrial cluster anchors signalling investment intensity across India's rail modernization programs. Federal mandates in the United States and European Union reshape procurement specifications through interoperability compliance timelines. Metro densification in Southeast Asian cities accelerates Communications-Based Train Control deployment without legacy system encumbrance.
United States
Class I railroad corridor densification drives Positive Train Control retrofit demand across Union Pacific, BNSF, and Norfolk Southern networks. The Federal Railroad Administration enforces automatic speed compliance and collision avoidance mandates through interoperability standards requiring dual-band radio architecture. Chicago rail hub concentration absorbs substantial wayside equipment investment for freight throughput optimization.
Germany
Deutsche Bahn coordinates joint framework agreements for European Train Control System onboard units with France and Italy, compressing supplier margins through volume aggregation. The European Union Agency for Railways administers baseline specifications and module certification under EU interoperability frameworks. Bavaria's high-speed rolling stock programs standardize ETCS Level 2 deployment across cross-border corridors.
India
Dedicated Freight Corridor projects and metro rail expansions in Mumbai, Delhi, and Bangalore absorb substantial signalling capital from domestic and international suppliers. The Ministry of Railways mandates indigenous content thresholds through its phased manufacturing program, reshaping supplier qualification requirements. Western Dedicated Freight Corridor deployment proceeds without legacy encumbrance, enabling native radio block centre installation.
China
Urban metro densification in Beijing, Shanghai, and Guangzhou accelerates Communications-Based Train Control platform procurement against constrained installation windows. The Ministry of Industry and Information Technology oversees rail communication standards under national interoperability frameworks. Yangtze River Delta high-speed corridors concentrate ETCS-compatible deployment for cross-border freight integration.
France
SNCF anchors European joint procurement frameworks for standardized onboard units, consolidating purchasing power across multinational rolling stock fleets. The French national rail safety authority oversees ETCS certification timelines extending platform validation periods. Île-de-France urban transit operators prioritize cybersecurity-hardened communication layers for encrypted train-to-wayside protocols.
Global Train Signalling System Market Competitive Environment
Joint procurement framework participation dominates the current landscape among European national rail operators. The vendor base concentrates around integrated platform providers with deep backward integration into wayside control hardware, cybersecurity-certified communication layers, and traffic management software stacks. Three archetypes define positioning: full-stack system integrators, communication infrastructure specialists, and component-tier electrical contractors. Competitive intensity centers on strategic partnerships for spectrum coordination and geographic expansion into Southeast Asian greenfield metros.
Among European-integrated platform providers, Alstom, Siemens Mobility, and Thales Group exemplify the full-stack archetype through framework agreement anchoring. These France-based and Germany-based entities occupy positions spanning onboard units, radio block centres, and control centre equipment under single-vendor accountability structures. Their representation of the premium-tier vector reflects certification depth rather than pricing differentiation alone.
| Leading Market Players |
|---|
| Alstom |
| Siemens Mobility |
| Thales Group |
| Hitachi Rail Limited |
| Cisco Systems |
| Huawei Technologies |
| Wabtec Corporation |
| Belden |
| Nokia |
| Others |
Value Chain & Pricing Dynamics
European national rail operator consortiums anchoring joint framework agreements for ETCS onboard units compress supplier margins through volume aggregation, forcing project-based pricing with availability-guarantee service overlays to displace traditional time-and-materials arrangements.
Pricing Analysis
Input-cost pass-through from specialized radio-frequency engineering labor and cybersecurity-certified communication components shapes contract structures. Project-based pricing dominates, with three-tier pricing structure across premium, standard, and economy levels separating integrated turnkey systems from standalone component supply. Pricing pressure stems from consolidated procurement consortia among SNCF, Deutsche Bahn, and Trenitalia. Freight operators in India and heavy-haul corridors in Western Australia exhibit highest price sensitivity, while European high-speed rail tenders prioritize certification depth over unit economics.
Supply Chain Analysis
India's Ministry of Railways phased manufacturing program and indigenous content thresholds reshape supplier qualification requirements, forcing localization of radio block centre and balise group production. Critical inputs draw from Germany, France, and China for European Vital Computer architecture, fiber-optic transmission modules, and encrypted communication chipsets. Single-source vulnerability concentrates in certified system integrator capacity for ETCS Level 2 validation. Distribution runs through national rail operator framework agreements and rolling stock OEM direct procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Train Signalling System Market functions as a geographic-arbitrage play where India's indigenous content mandates create cost-advantaged sourcing bases absent from European certification-heavy procurement.
For Market Incumbents: Cement framework agreement anchoring through deeper backward integration into wayside control hardware production in India and Vietnam. Alstom, Siemens Mobility, and Thales Group face margin compression from consolidated European procurement; counter by embedding cybersecurity-hardened communication layers as non-negotiable tender specifications ahead of formal EU Network and Information Security Directive certification availability. For New Entrants and Emerging Players: Enter via Southeast Asian greenfield metro networks in Vietnam, Indonesia, and Philippines where Communications-Based Train Control deployment proceeds without legacy system encumbrance. Target performance-based maintenance contracts in Singapore and Dubai where availability-guarantee service models displace traditional arrangements. Lead with encrypted train-to-wayside protocol specialization as regulatory cybersecurity requirements harden. For Investors and Strategic Acquirers: Communication infrastructure specialists with certified security architectures are the most active acquirer targets in this space for full-stack system integrators seeking capability gap closure. Long-term viability hinges on spectrum coordination partnerships for GSM-R successor bands and cloud-based traffic management software stacks. Watch for ETCS Level 3 moving-block standardization as the inflection signal for platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | EU Network and Information Security Directive mandates embed security specifications into tender documents ahead of formal availability. |
| Joint Procurement Framework Participation | SNCF, Deutsche Bahn, and Trenitalia volume aggregation compresses supplier margins while locking in multi-year revenue pipelines. |
| Localized Production Footprint | India's phased manufacturing program thresholds force radio block centre and balise group domestic assembly qualification. |
| Spectrum Coordination Partnership | GSM-R successor band allocation contests across jurisdictions demand dual-mode radio investments pending regulatory clarity. |
| Performance-Based Maintenance Contracting | Availability-guarantee service models displace time-and-materials arrangements in European high-speed and Asian metro corridors. |
Study Parameters
Bottom-up urban transit and freight corridor modeling reconciled against top-down integrated platform vendor shipment tracking forms the analytical core. Primary interviews with signalling system procurement directors at national rail operators, ETCS certification engineers at the European Union Agency for Railways, Ministry of Railways project directors in India, and CBTC deployment managers at Southeast Asian metro authorities combined with secondary validation from FRA interoperability standards filings, EU Agency for Railways module certification databases, and Indian railway tender documentation.
Input-output matrix framing connects ETCS Level 2/Level 3 deployment velocity, CBTC retrofit installation window constraints, and indigenous content threshold compliance across technology, application, component, and installation type segmentations. CAGRs derive from penetration curve analysis against corridor densification timelines and regulatory mandate enforcement schedules. Forecast inputs include radio spectrum reallocation proceedings and cybersecurity directive implementation trajectories across the projection horizon.
Inputs from European national operator procurement disclosures and Indian Ministry of Railways tender awards were available through the study window; gaps in Southeast Asian greenfield metro contract finalization introduce uncertainty bands around Communications-Based Train Control volume assumptions. Forecasts reflect documented regulatory enforcement timelines and infrastructure investment commitment credibility. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Railway Li-Ion Battery Market
Railway Transportation
Railway Air Conditioning System Market
Railway Transportation
Global Train Communication Gateways Systems Market
Railway Transportation
Urban Rail Transit Market
Railway Transportation
Global Railway Wiring Harness Market
Railway Transportation
Australia Rail Freight Transport Market
Railway Transportation
Railway After-Cooler Market
Railway Transportation
Canada Rail Freight Transport Market
Railway Transportation
Railway Couplers Market
Railway Transportation
Rail Pads Market
Railway Transportation
Point Machine Market
Railway Transportation
Radar and Lidar Technology for Railways Application Market
Railway Transportation
Railway Fishplate Market
Railway Transportation
High Speed Rail Coating Market
Railway Transportation
Automatic Train Protection Signaling Market
Railway Transportation
Railroad Tank Car Market