
 Global Rail Freight Transport Market | 2026-2036
Global Rail Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rail Freight Transport Market Outlook
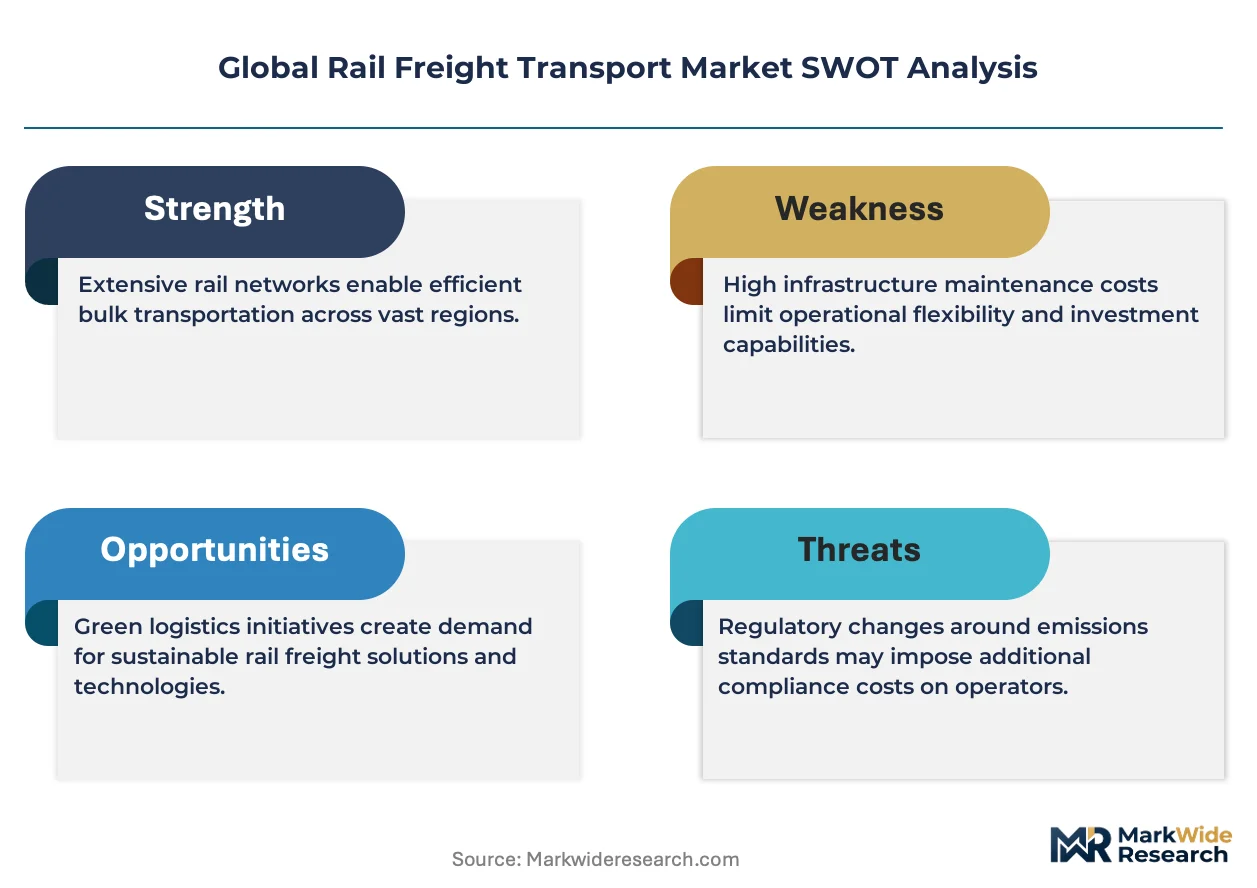
A global shortage of certified locomotive engineers and signaling technicians is collapsing capacity expansion timelines across major networks. Deutsche Bahn AG leverages its integrated DB Cargo division to sustain end-to-end control over European intermodal flows. Union Pacific Railroad anchors transcontinental bulk movements through its Sunset Route corridor dominance. BNSF Railway competes aggressively on agricultural export volumes from the US Midwest to Pacific Northwest terminals.
Rail freight transport denotes the movement of goods via steel-wheel-on-rail infrastructure using diesel-electric or electric locomotives hauling consists typically ranging from 50 to 200 cars at operating speeds of 25–70 mph depending on cargo class and track grade. Its primary purpose centers on moving high-volume, low-value-density commodities and containerized manufactured goods over distances exceeding 500 miles where fuel efficiency per ton-mile exceeds road alternatives by three- to four-fold. Intermodal transport leads segment value generation due to its capture of international trade flows, while bulk cargo sustains the highest absolute tonnage base anchored by coal, ore, and grain movements. Automated systems within the technology dimension are attracting disproportionate capital allocation as Class I railroads pursue precision scheduled railroading protocols to optimize asset turns and crew utilization.
The US Federal Railroad Administration enforces strict hours-of-service and positive train control mandates that shape crew scheduling economics and technology deployment timelines. The EU F-Gas Regulation and broader EU Green Deal frameworks are accelerating electrification retrofits and modal shift incentives across European corridors. China's MIIT and national rail administration coordinate dual carbon goals with freight corridor expansion plans. Stakeholders must monitor how divergent regulatory stringency on emissions and crew autonomy across Washington, Brussels, and Beijing reshapes competitive parity between regional operators and determines where capital deployment earns acceptable returns.
Market Dynamics
Precision scheduled railroading is compressing asset turns and crew utilization across Class I networks, forcing capital reallocation toward automation and away from legacy scheduling paradigms. This operational discipline is reshaping competitive economics between integrated operators and regional carriers.
Growth Catalysts
- EU Green Deal modal shift mandates:Brussels-directed infrastructure subsidies are redirecting container flows from road haulage to electrified corridors across Germany, Poland, and the Netherlands.
- Iron ore export corridors:Mining majors in Western Australia and Brazil's Carajás basin are expanding dedicated heavy-haul lines to port terminals.
- Battery-electric locomotive retrofits:California Air Resources Board incentives are accelerating zero-emission switcher deployments at Los Angeles Basin intermodal yards.
Market Restraints
- Copper and steel input volatility:Overhead catenary and rolling stock manufacturers face margin compression from commodity price swings.
- Signaling equipment supply concentration:European corridor modernization depends on a narrow base of certified signaling vendors.
- Last-mile road dependency:Intermodal terminals require drayage trucking for origin-destination connectivity, diluting rail's emissions advantage.
Strategic Opportunities
- India's Dedicated Freight Corridors:The Eastern and Western DFC routes offer greenfield access to industrial hinterlands previously served by congested mixed-traffic lines.
- Digital freight matching platforms:Algorithmic load consolidation is reducing empty backhaul miles for small and mid-sized shippers.
- EU F-Gas Regulation phase-down:Refrigerated intermodal operators must retrofit cooling systems, creating aftermarket service contracts.
Industry Challenges
- Certified locomotive engineer scarcity:Federal Railroad Administration hours-of-service rules and demographic retirements are collapsing training pipeline capacity.
- Positive train control integration:Legacy dispatch systems require costly middleware to interface with federally mandated collision-avoidance networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rail Freight Transport Market |
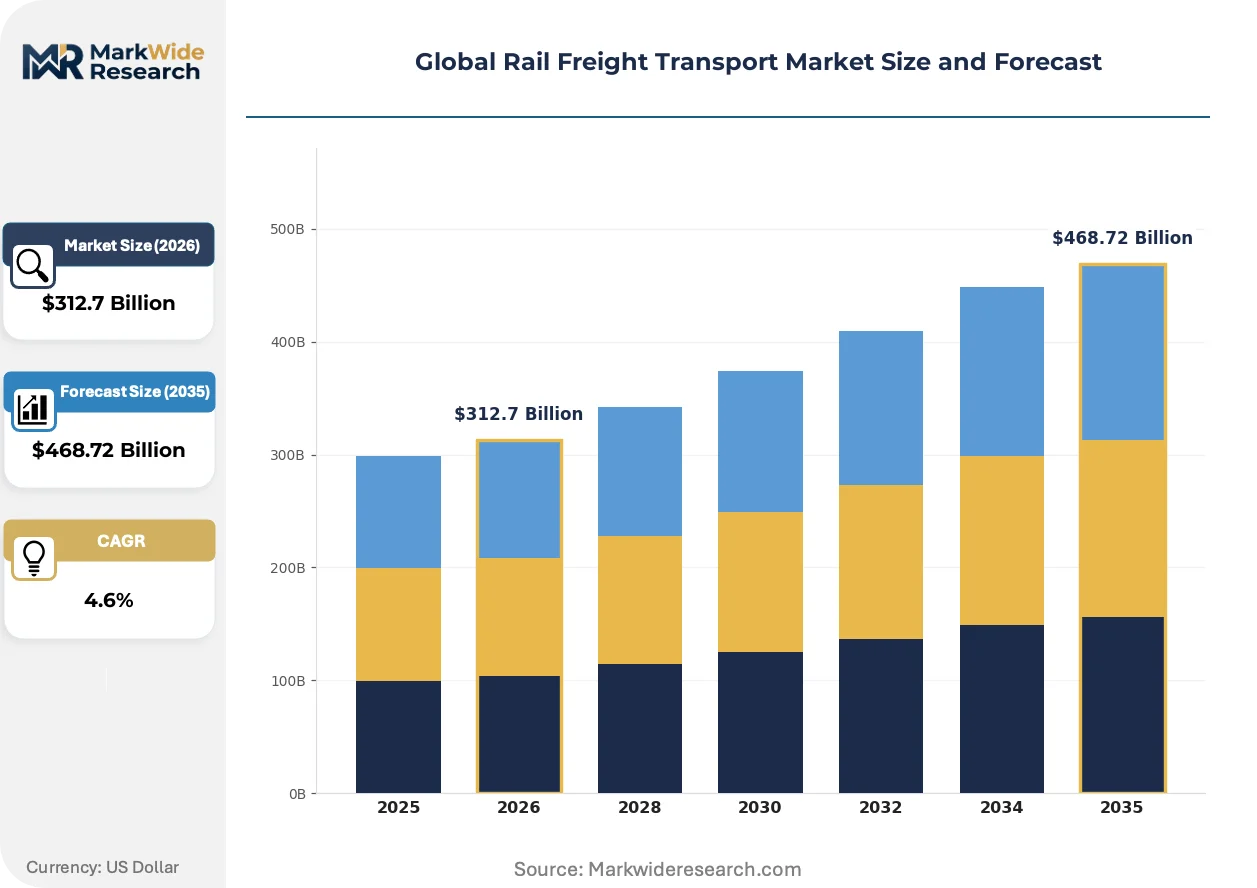
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $468.72 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Intermodal Transport, Bulk Cargo, Containerized Freight, Car Shipment End User: Manufacturers, Retailers, Importers, Exporters Technology: Automated Systems, GPS Tracking, Rail Optimization, Cold Chain Container Type: Flat Rack, Tank Containers, Open Top, Specialized Containers |
| Companies Covered | Norfolk Southern Railway, Deutsche Bahn AG, Union Pacific Railroad, Canadian Pacific Railway, Russian Railways, BNSF Railway, Canadian National Railway, DB Cargo, CSX Transportation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rail Freight Transport Market Strategic Shifts
Automation and alternative propulsion are splitting capital allocation between efficiency-maximizing software and hardware decarbonization. Rail operators must now sequence technology bets across diverging regulatory timelines.
Autonomous train operation is bifurcating deployment strategies across freight corridors. Rio Tinto's Pilbara iron ore network has operated driverless heavy-haul since 2019. European freight operators are pursuing supervised automation under EU safety frameworks. This technology is compressing crew costs and enabling 24-hour operations on mineral routes while mixed-traffic lines await regulatory clarity.
The EU F-Gas Regulation is accelerating refrigerant transitions in cold-chain intermodal. Operators must replace hydrofluorocarbon cooling units with CO2 or ammonia systems by mandated phase-down dates. Refrigerated container lessors in the Netherlands and Germany are retrofitting fleets ahead of compliance deadlines to capture green shipping premiums.
Shippers are consolidating procurement around integrated door-to-door contracts. Large retail and automotive manufacturers are bypassing traditional freight forwarders to negotiate directly with rail operators and their drayage partners. This pattern is most visible in North American cross-border corridors where Union Pacific and Canadian National compete on end-to-end transit reliability.
Global Rail Freight Transport Market Segmentation
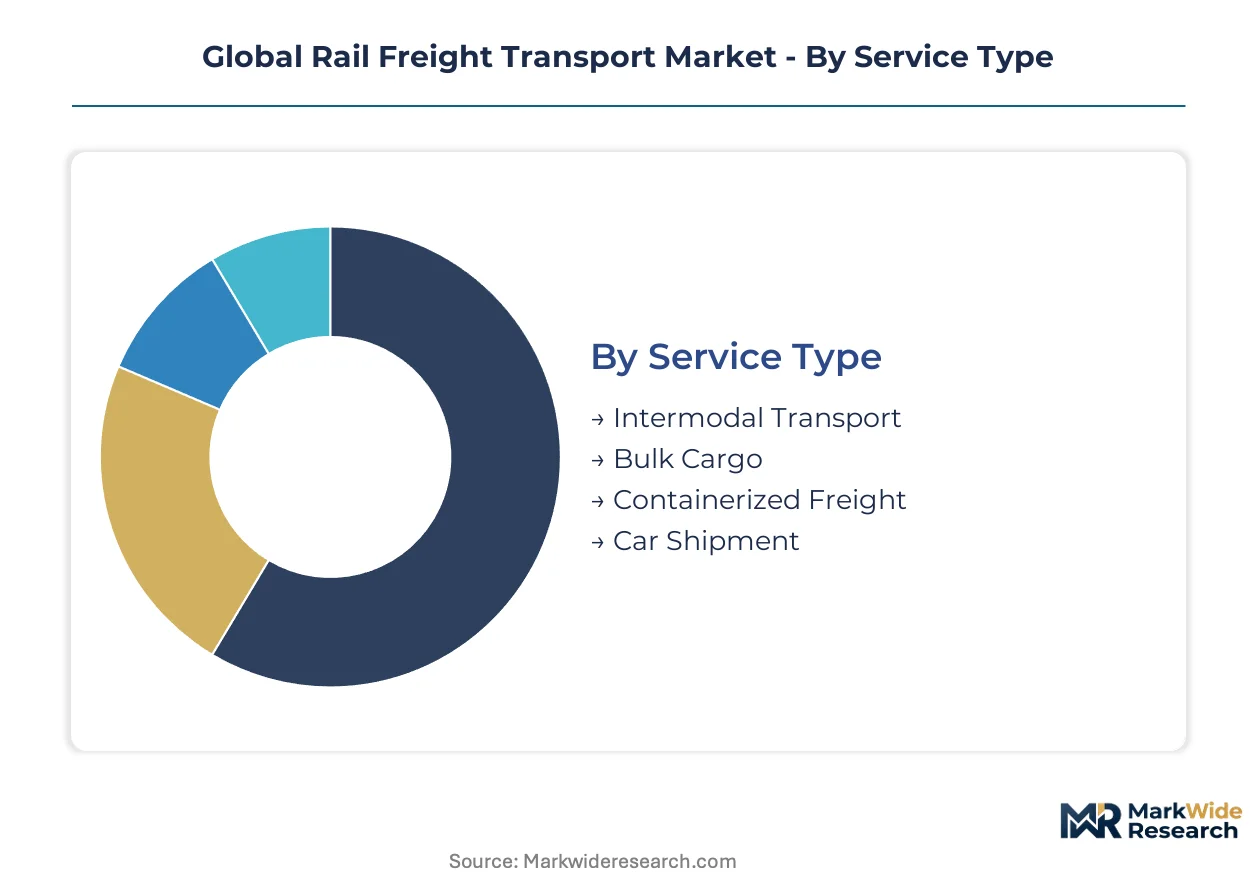
Rail freight segmentation reveals divergent regulatory pressures across service modes and technology tiers. Each dimension carries distinct compliance burdens and capital intensity profiles that reshape operator economics and shipper procurement priorities.
Service Type:
EU Green Deal modal shift mandates and US Federal Railroad Administration hours-of-service rules create asymmetric compliance costs across service categories.
- Intermodal Transport:Combines rail trunk haul with drayage trucking for door-to-door container movements. California Air Resources Board incentives for zero-emission switchers at Los Angeles Basin yards are accelerating electrification investments here, though last-mile road dependency dilutes emissions advantages.
- Bulk Cargo:Dedicated heavy-haul movements of coal, ore, and grain using unit trains of 100-plus cars. Mining corridors in Western Australia and Brazil's Carajás basin anchor absolute tonnage, with autonomous train operation compressing crew costs on mineral routes.
- Containerized Freight:Standardized box movements capturing international trade flows through port-rail interfaces.
- Car Shipment:Finished vehicle logistics using multi-level autorack cars for automotive OEM distribution networks.
Established volume favors Bulk Cargo; emerging adoption favors Intermodal Transport.
End User:
Customer scale and contract structure determine access to integrated pricing and priority capacity allocation.
- Manufacturers:Automotive and industrial producers negotiating direct rail contracts bypassing freight forwarders. These shippers concentrate procurement around door-to-door reliability metrics on North American cross-border corridors.
- Retailers:Big-box and e-commerce operators with high-velocity inventory requirements driving precision scheduled railroading adoption for predictable transit windows.
- Importers:Containerized cargo owners dependent on port-rail intermodal gateways for hinterland distribution.
- Exporters:Agricultural and mining shippers originating bulk movements to coastal terminals.
Contract concentration favors Manufacturers; spot market liquidity favors Importers.
Technology:
Capital allocation splits between efficiency-maximizing software and hardware decarbonization with diverging regulatory timelines.
- Automated Systems:Precision scheduled railroading protocols and autonomous train operation. Rio Tinto's driverless Pilbara network demonstrates 24-hour mineral corridor operations, while European operators pursue supervised automation under EU safety frameworks.
- GPS Tracking:Real-time consist visibility and predictive maintenance analytics. Asset utilization gains here are reshaping competitive economics between integrated operators and regional carriers.
- Rail Optimization:Algorithmic scheduling and crew management platforms.
- Cold Chain:Temperature-controlled intermodal for pharmaceuticals and perishables. EU F-Gas Regulation refrigerant phase-downs are forcing CO2 and ammonia system retrofits ahead of compliance deadlines.
Near-term ROI favors Rail Optimization; longest payback horizon favors Cold Chain.
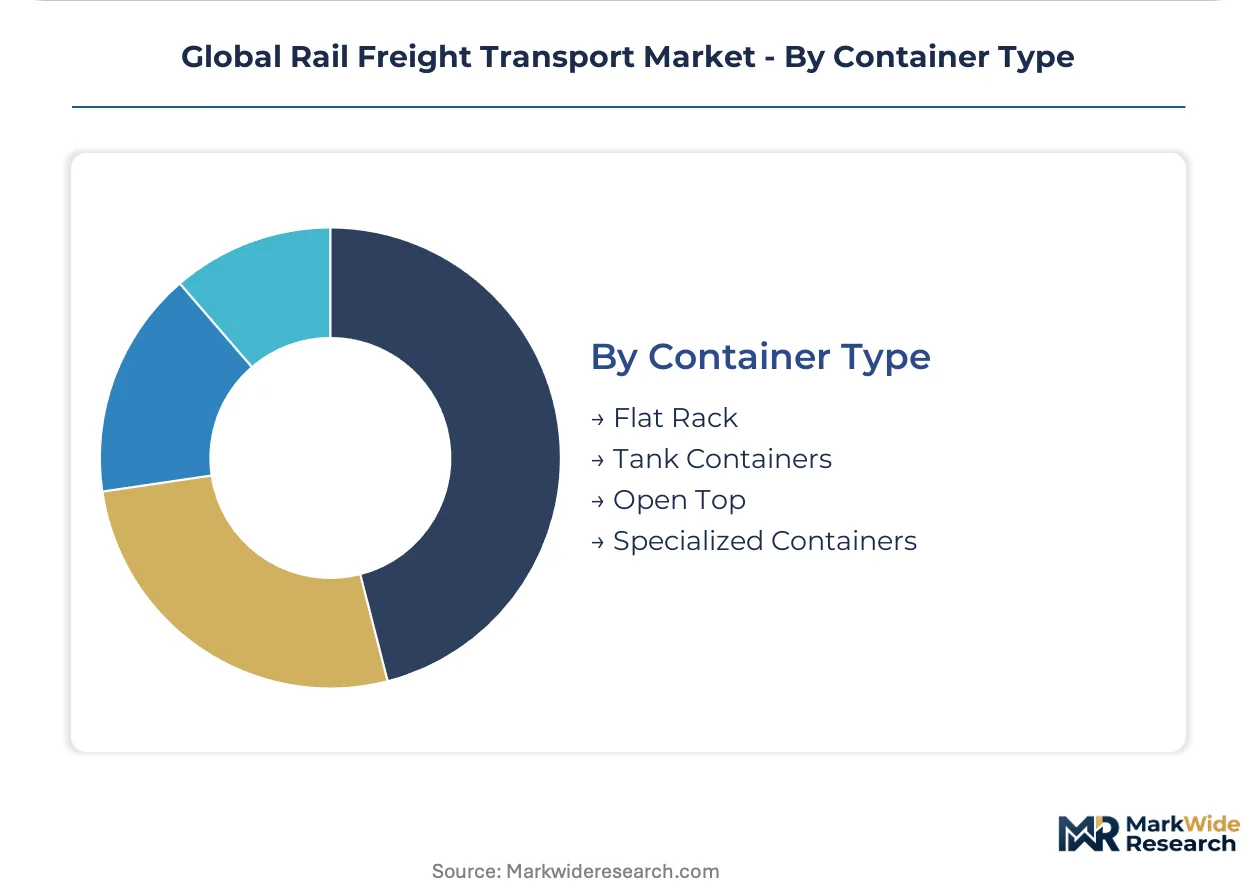
Container Type:
Equipment specialization correlates with cargo value density and handling complexity premiums.
- Flat Rack:Collapsible side containers for oversized machinery and project cargo. Industrial corridor expansion in India's Dedicated Freight Corridors is opening greenfield access for heavy-lift movements previously constrained by mixed-traffic congestion.
- Tank Containers:Intermodal liquid bulk units for chemicals and food-grade products. DGFT regulations in India and hazardous materials frameworks in Germany shape certification requirements for cross-border deployment.
- Open Top:Roofless containers for bulk commodities and tall loads.
- Specialized Containers:Custom units for refrigerated, hazardous, or high-security cargo.
Volume scale favors Open Top; margin premium favors Specialized Containers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Federal Railroad Administration anchors regulatory stringency in the United States, where hours-of-service rules and positive train control mandates reshape crew economics across transcontinental networks. Divergent compliance timelines across Washington, Brussels, and Beijing fragment competitive parity and capital deployment returns.
United States
Union Pacific Railroad and BNSF Railway anchor transcontinental bulk movements through Sunset Route corridor dominance and Midwest agricultural export volumes. The Federal Railroad Administration enforces strict hours-of-service and positive train control mandates that compress training pipeline capacity and reshape crew scheduling economics. Chicago and Los Angeles Basin intermodal terminals concentrate container flows, where California Air Resources Board incentives accelerate zero-emission switcher deployments.
Germany
Deutsche Bahn AG leverages its integrated DB Cargo division to sustain end-to-end control over European intermodal flows through electrified corridors. The EU Green Deal and F-Gas Regulation redirect infrastructure investment toward modal transfer from road to rail across member states. The Rhine-Ruhr industrial cluster anchors container movements, where precision scheduled railroading protocols optimize asset turns and crew utilization.
China
MIIT and the national rail administration coordinate dual carbon goals with freight corridor expansion plans across heavy-haul mineral routes. National standards and state-directed investment prioritize electrification retrofits and automated dispatch systems on coal and ore corridors. The Yangtze River Delta manufacturing belt drives intermodal demand, where algorithmic load consolidation reduces empty backhaul miles for containerized exports.
India
Dedicated Freight Corridors on the Eastern and Western routes offer greenfield access to industrial hinterlands previously served by congested mixed-traffic lines. DGFT regulations and hazardous materials frameworks shape certification requirements for cross-border tank container deployment. The Delhi-Mumbai Industrial Corridor concentrates manufacturing logistics, where rail-linked bulk cargo movements anchor domestic supply chain architecture.
Australia
Mining companies in Western Australia expand rail-linked bulk cargo movements as their primary logistics backbone for iron ore export corridors. National safety frameworks accommodate autonomous train operation on mineral routes, compressing crew costs and enabling 24-hour operations. The Pilbara region hosts driverless heavy-haul networks, where Rio Tinto's automated systems demonstrate operational discipline at scale.
Global Rail Freight Transport Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with Class I railroads commanding transcontinental density while regional carriers capture niche corridor economics. Consolidation around precision scheduled railroading protocols separates asset-turn optimizers from legacy scheduling operators. Three archetypes dominate: integrated end-to-end providers, heavy-haul mineral specialists, and intermodal platform operators. Competitive moves concentrate on automation licensing partnerships and corridor-specific capacity expansion.
Among North American integrated operators, Union Pacific Railroad and BNSF Railway occupy positions exemplifying scale-driven transcontinental dominance, while Canadian National Railway and Canadian Pacific Railway represent cross-border consolidation archetypes. Deutsche Bahn AG anchors European integrated logistics through its DB Cargo division. Norfolk Southern Railway and CSX Transportation exemplify eastern US corridor concentration, while Russian Railways occupies a position reflecting state-directed network control across Eurasian corridors.
| Leading Market Players |
|---|
| Norfolk Southern Railway |
| Deutsche Bahn AG |
| Union Pacific Railroad |
| Canadian Pacific Railway |
| Russian Railways |
| BNSF Railway |
| Canadian National Railway |
| DB Cargo |
| CSX Transportation |
| Others |
Value Chain & Pricing Dynamics
Heavy-haul corridor density in Western Australia and Brazil's Carajás basin compresses unit costs below thresholds achievable by fragmented regional operators, concentrating pricing power among integrated mining-logistics consortia while forcing price floors higher for smaller shippers lacking volume scale.
Pricing Analysis
Trans-Pacific bulk freight spreads diverge sharply from European intermodal rates due to diverging electrification subsidies and crew cost structures. Contract-based long-term offtake dominates mining corridors, while intermodal operators deploy three-tier pricing structure across premium, standard, and economy levels differentiated by transit reliability and customs pre-clearance. Price erosion runs through standard-tier container movements as digital freight platforms compress broker margins. Importers dependent on spot market liquidity exhibit highest price sensitivity; automotive manufacturers with dedicated fleet contracts show lowest.
Supply Chain Analysis
Strategic stockpiling of steel rail and copper catenary wire prevails over just-in-time procurement as commodity volatility and signaling equipment lead times stretch procurement horizons. Manufacturing concentrates in China, Germany, and the United States for rolling stock; Australia, Brazil, and Canada anchor ore-grade steel inputs. Single-source vulnerability concentrates in European signaling vendors certified for ETCS deployment. Distribution runs through port-rail intermodal terminals requiring drayage trucking for final-mile connectivity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service contracts for locomotive maintenance and signaling system upgrades are expanding faster than rolling stock sales as fleet operators prioritize uptime guarantees over capital expenditure.
For Market Incumbents: Shield corridor dominance by securing exclusive track access agreements on India's Dedicated Freight Corridors before greenfield capacity saturates. Accelerate backward integration into battery-electric locomotive powertrain production to capture California Air Resources Board incentive flows and defend against emerging Chinese equipment suppliers. For New Entrants and Emerging Players: Digital freight matching platforms represent the most penetrable service-layer gap, with algorithmic load consolidation reducing empty backhaul miles for small and mid-sized shippers underserved by Class I railroads. Target India's fragmented industrial hinterlands with asset-light booking platforms aggregating regional carrier capacity. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated operators with captive maintenance divisions and long-term haulage contracts. Prioritize acquisition targets with precision scheduled railroading deployment experience and established EU Green Deal compliance infrastructure. Watch for inflection when autonomous train operation regulatory frameworks clarify outside mineral corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Train Operation Licensing | Rio Tinto's Pilbara deployment proves 24-hour mineral corridor viability without crew cost inflation. |
| Battery-Electric Locomotive Retrofit | California Air Resources Board incentives accelerate zero-emission switcher adoption at Los Angeles Basin yards. |
| Dedicated Freight Corridor Access | India's Eastern and Western DFC routes unlock greenfield industrial hinterlands previously constrained by mixed-traffic congestion. |
| Digital Freight Matching Platform | Algorithmic load consolidation reduces empty backhaul miles for small and mid-sized shippers bypassing traditional brokers. |
| Cold Chain Refrigerant Retrofit | EU F-Gas Regulation phase-down forces CO2 and ammonia system upgrades ahead of compliance deadlines. |
Study Parameters
The analysis maps intermodal transport, bulk cargo, containerized freight, and car shipment segments, each validated through locomotive fleet managers, intermodal terminal operators, mining logistics directors, and signaling system procurement leads. Primary fieldwork combined structured interviews with secondary validation against Federal Railroad Administration safety filings, EU transport infrastructure databases, Indian Railways DFC project disclosures, and Australian mining export statistics. Bottom-up volume modeling triangulated against top-down macroeconomic freight demand indicators.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation dimensions modeled include service type, end-user contract structure, technology tier, and container specialization. CAGRs derived from curve-fitting historical corridor expansion rates against projected infrastructure investment flows. Forecast inputs incorporated hours-of-service rule changes, electrification subsidy trajectories, and autonomous operation regulatory clarity timelines.
Underlying assumptions cover modal shift policy continuity, copper and steel input price bands, and certified engineer training pipeline recovery, with deviation risk concentrated in regulatory delays for positive train control mandates and EU F-Gas compliance enforcement intensity. Revision becomes warranted when autonomous operation safety frameworks cross adoption thresholds outside controlled-access mineral corridors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Overhead Catenary System Market
Railway Transportation
Brazil Rail Freight Transport Market
Railway Transportation
Railway Radiator Market
Railway Transportation
Rail Switch Point Heating System Market
Railway Transportation
Railway Traction Inverter Market
Railway Transportation
Automatic Train Protection Signaling Market
Railway Transportation
Urban Rail Transit Market
Railway Transportation
Composites in Passenger Rail Market
Railway Transportation
Railway Connectors Market
Railway Transportation
Railway Station Lighting Market
Railway Transportation
Global Railway Wiring Harness Market
Railway Transportation
Urban Rail Transit Signaling Market
Railway Transportation
Railway Track Fittings Market
Railway Transportation
High Speed Rail Coating Market
Railway Transportation
Global Railcar Leasing Market
Railway Transportation
Autonomous Train Technology Market