
 Automotive Speed Alert System Market | 2026-2036
Automotive Speed Alert System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Speed Alert System Market Intelligence
Embedded software engineering talent scarcity is redrawing competitive boundaries across the speed alert ecosystem. Continental leverages its captive sensor fusion architecture to dominate European OEM supply chains. Bosch anchors its position through backward integration into radar chip design and manufacturing scale. Denso competes by specializing in real-time processing modules calibrated for Japanese and Southeast Asian vehicle platforms.
An automotive speed alert system comprises integrated sensor arrays, processing units, and human-machine interface outputs that detect vehicle speed relative to posted limits and generate audible, haptic, or visual warnings to the driver. Camera-based and radar-based product types currently lead installation volumes in passenger vehicles, though lidar-based configurations are gaining traction in premium segments where redundancy requirements are tightening. Machine learning and sensor fusion technologies command the deepest margin pools because algorithm training datasets and calibration intellectual property create defensible competitive moats. Commercial fleets and passenger vehicles represent the largest application segments, with fleet operators prioritizing cloud connectivity for centralized driver behavior monitoring.
The European Union's General Safety Regulation mandates ISA compliance, while NHTSA in the United States evaluates speed-limiting technologies for heavy commercial vehicles. Japan's METI promotes cooperative intelligent transport systems that integrate vehicle-to-infrastructure speed data. Stakeholders must monitor divergence between mandatory European installation requirements and voluntary North American adoption patterns when allocating R&D and production capacity across regional supply networks.
Market Dynamics
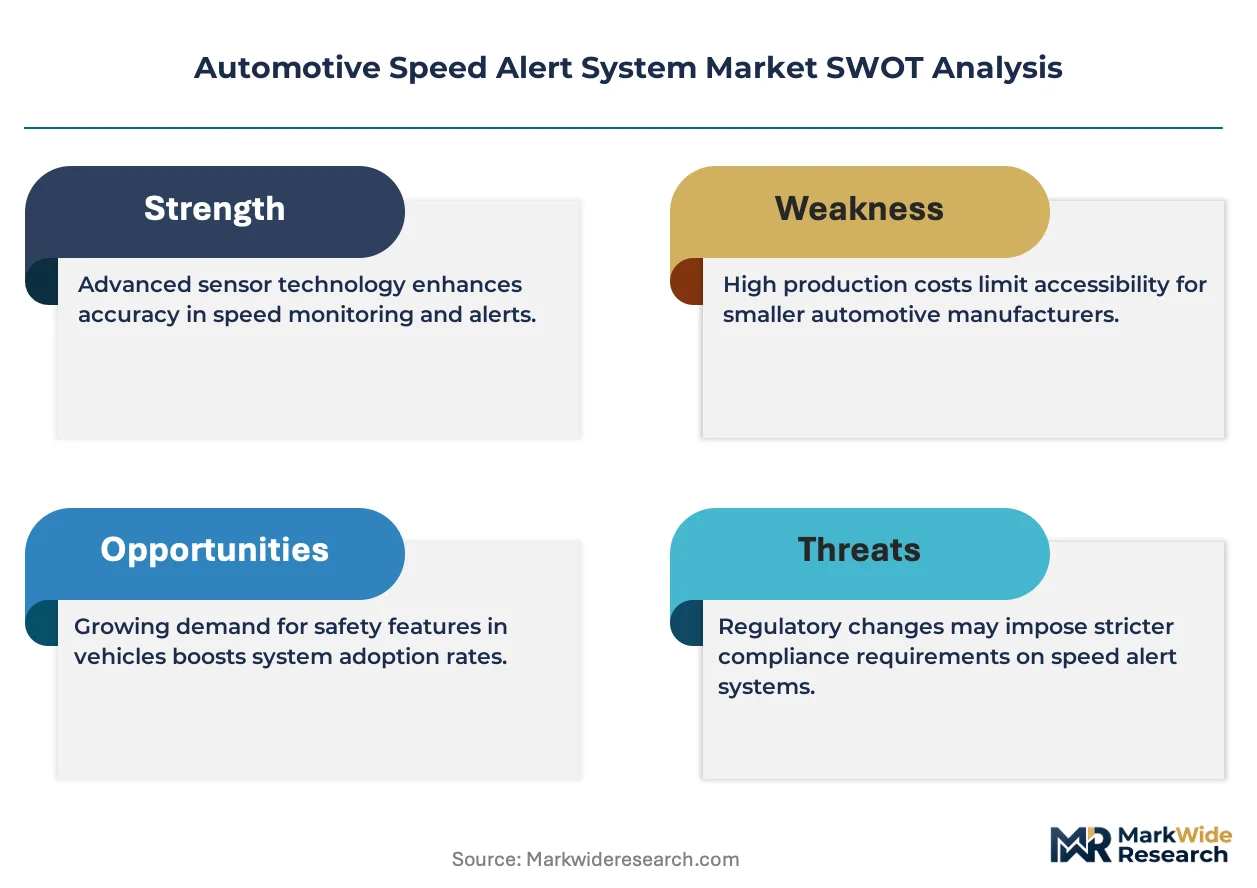
The European Union's mandatory Intelligent Speed Assistance requirements under the General Safety Regulation are compressing installation timelines and forcing tier-1 suppliers to reallocate sensor fusion engineering capacity toward ISA-compliant module architectures.
Growth Catalysts
- EU General Safety Regulation:Mandatory ISA compliance creates guaranteed installation volumes across all new vehicle types sold in member states, eliminating demand uncertainty for alert system manufacturers.
- Commercial fleet liability reduction:Fleet operators deploy speed alert systems to lower insurance premiums and exposure from driver-related incidents, generating sustained replacement demand.
- Sensor fusion algorithm training:Proprietary datasets and calibration IP for camera-radar fusion create defensible margin pools that attract sustained R&D investment from component suppliers.
Market Restraints
- Semiconductor input volatility:Radar chip and processing unit supply concentrates among a limited fabrication base, exposing module assemblers to allocation risk and price swings.
- Technical calibration complexity:Multi-sensor fusion requires extensive real-world validation across road types and weather conditions, lengthening product development cycles.
- Substitution by autonomous braking:Advanced automatic emergency braking systems with integrated speed management reduce standalone alert system value in premium vehicle segments.
Strategic Opportunities
- Underpenetrated Southeast Asian passenger vehicle fleet:Rising vehicle ownership in Indonesia and Vietnam creates first-fit installation demand as domestic assembly scales and safety regulations mature.
- Vehicle-to-infrastructure data integration:Cooperative intelligent transport systems promoted by Japan's METI enable dynamic speed limit updates that require upgraded alert hardware.
- Cloud-connected fleet monitoring:Centralized driver behavior analytics platforms create recurring software revenue streams beyond hardware sales to commercial vehicle operators.
Industry Challenges
- Embedded software engineering scarcity:Real-time processing and machine learning optimization skills concentrate among automotive tier-1 suppliers, constraining module vendor expansion.
- Multi-regulatory certification timelines:Divergent approval processes between EU type-approval requirements and NHTSA evaluation protocols fragment engineering resources.
- Legacy vehicle integration friction:Retrofit alert system installation requires compatibility with aging CAN bus architectures and analog instrument clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Speed Alert System Market |
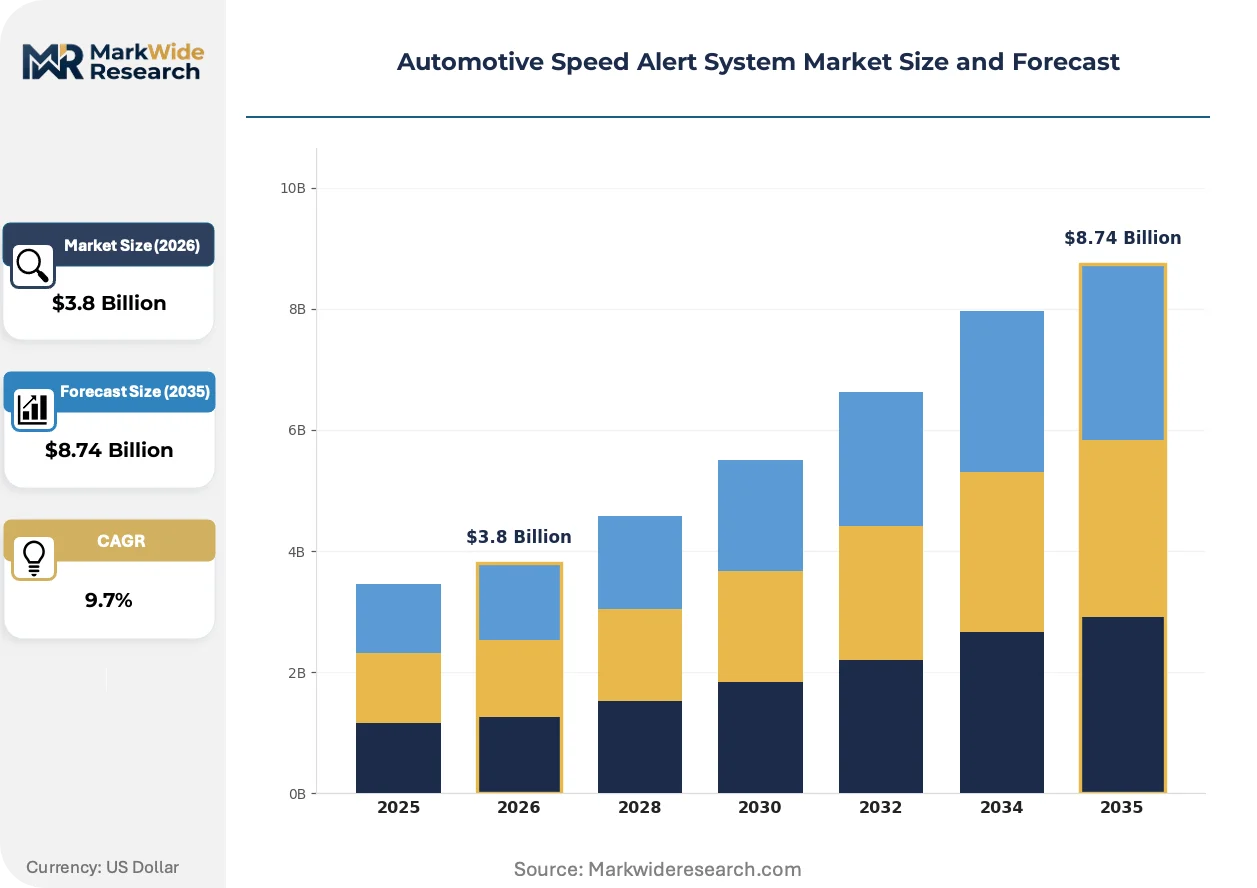
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GPS-Based, Radar-Based, Lidar-Based, Camera-Based, Ultrasonic Sensors Technology: Machine Learning, Computer Vision, Sensor Fusion, Real-Time Processing, Cloud Connectivity Application: Commercial Fleets, Passenger Vehicles, Public Transportation, Emergency Service Vehicles, Delivery Trucks End User: Fleet Operators, Vehicle Manufacturers, Logistics Providers, Ride-Hailing Companies, Municipal Agencies |
| Companies Covered | ZF, WABCO, Bosch, AISIN, Hitachi Metal, Continental, Delphi, Denso, MOBIS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Speed Alert System Market Strategic Shifts & Innovations
Three intersecting developments are compressing hardware footprints while expanding functional scope across the speed alert ecosystem. Technology miniaturization, regulatory harmonization pressures, and procurement model evolution are forcing suppliers to restructure both product architectures and customer engagement approaches.
Lidar-based speed alert configurations are miniaturizing from roof-mounted units to embedded bumper modules, enabling redundancy-compliant installations in premium passenger vehicles without aesthetic compromise. German and Japanese OEMs are accelerating validation programs for these compact units. The structural consequence is a compression of the premium-mid-market feature gap as costs fall.
REACH and RoHS substance restrictions in Europe are forcing sensor module manufacturers to reformulate solder alloys and encapsulant materials, adding qualification overhead but creating regulatory compliance as a competitive differentiator. Suppliers with pre-certified material libraries capture accelerated OEM sourcing decisions. Heavy commercial vehicle segments face the tightest compliance timelines.
Fleet procurement is consolidating around integrated telematics contracts that bundle speed alert hardware with driver monitoring software and insurance partnerships. Tier-1 suppliers are responding with subscription-enabled modules that unlock feature tiers remotely. This shift is most visible in Germany and the United Kingdom where commercial auto insurance markets have embraced usage-based pricing.
Automotive Speed Alert System Market Segmentation
Speed alert system procurement channels diverge sharply between OEM integration programs and aftermarket retrofit installations. Understanding which segments flow through captive supply chains versus open distribution determines pricing power and margin capture for component vendors.
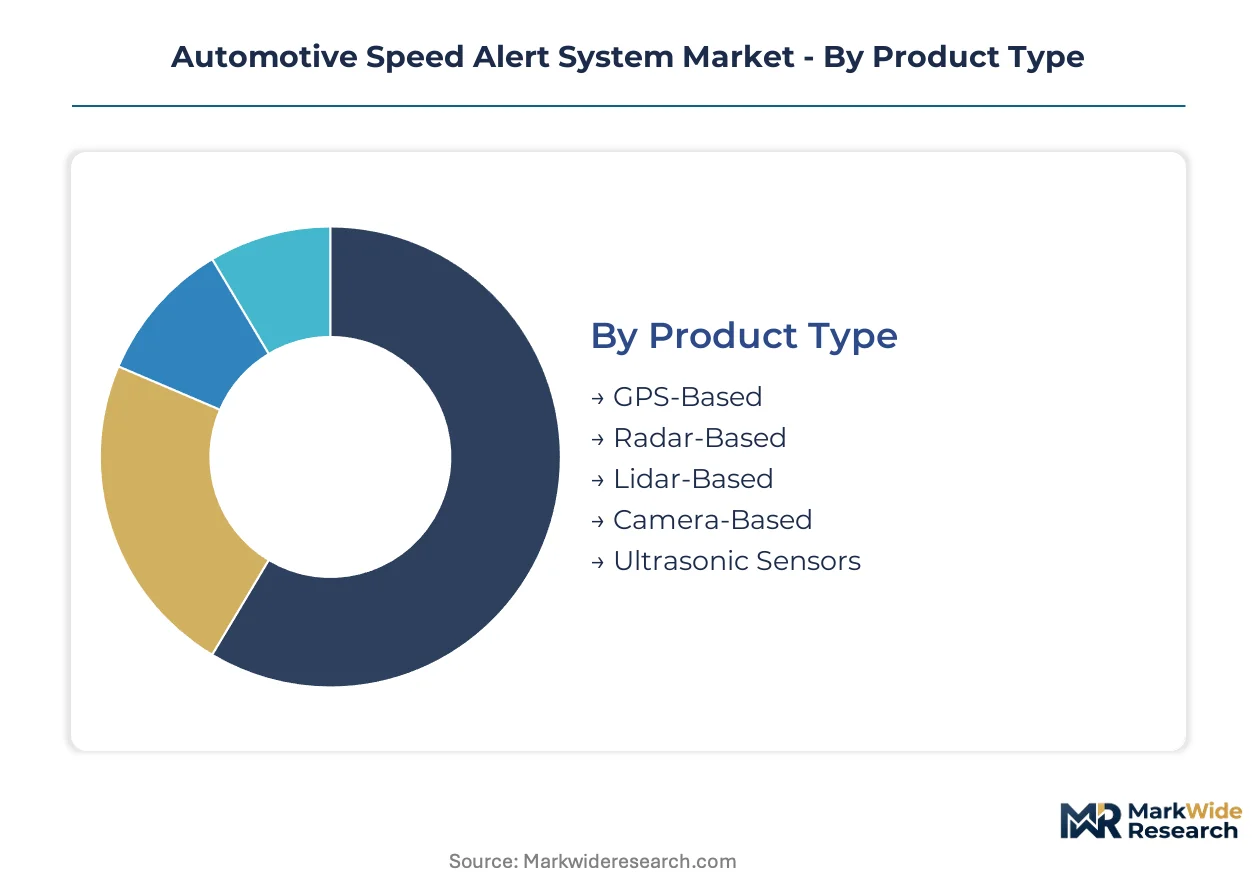
Product Type:
Camera-based and radar-based modules dominate OEM supply agreements with tier-1 electronics manufacturers, while GPS-based units concentrate in fleet aftermarket procurement through telematics distributors.
- Camera-Based:Image sensors paired with traffic sign recognition algorithms detect posted speed limits through windshield-mounted units. German OEMs and tier-1 suppliers in Stuttgart and Ingolstadt are scaling fused camera-radar modules to meet EU General Safety Regulation mandates.
- Radar-Based:Doppler sensors measure vehicle velocity independently of satellite positioning, enabling reliable operation in tunnels and urban canyons. Japanese vehicle platforms prioritize radar-centric architectures for all-weather redundancy.
- GPS-Based:Satellite positioning cross-referenced with digital map databases provides cost-effective speed limit awareness for commercial fleet retrofits.
- Lidar-Based:Laser scanning modules are miniaturizing from roof-mounted prototypes to embedded bumper configurations for premium vehicle redundancy.
- Ultrasonic Sensors:Short-range acoustic detection supplements primary speed measurement in low-speed urban maneuvering scenarios.
By volume, camera-based systems lead. By growth pace, lidar-based configurations are climbing the fastest.
Technology:
Margin concentration aligns with algorithmic complexity, where real-time processing and machine learning optimization command premium pricing from fleet operators and luxury OEMs alike.
- Machine Learning:Neural networks trained on region-specific road sign datasets improve limit recognition accuracy across variable lighting and weather conditions. Proprietary training data from German autobahn and rural road networks creates defensible IP moats for European suppliers.
- Sensor Fusion:Kalman filtering and probabilistic state estimation combine camera, radar, and GPS inputs into unified speed limit confidence scores. Japanese METI cooperative transport initiatives are accelerating validation of fusion architectures for vehicle-to-infrastructure integration.
- Computer Vision:Edge-based image processing pipelines extract sign geometry and text without cloud dependency.
- Real-Time Processing:Dedicated automotive-grade SoCs execute warning generation within deterministic latency bounds.
- Cloud Connectivity:Over-the-air map updates and fleet-wide speed policy synchronization enable centralized compliance monitoring.
Sensor fusion captures the steepest margin expansion trajectory, while cloud connectivity is gaining share fastest among fleet-focused vendors.
Application:
Installation scale varies by vehicle duty cycle intensity, with commercial fleets amortizing hardware costs across higher utilization rates than private passenger vehicles.
- Commercial Fleets:Long-haul trucking and delivery operations deploy speed alert systems to reduce insurance premiums and liability exposure from driver-related incidents. German fleet operators are bundling hardware with usage-based insurance partnerships.
- Passenger Vehicles:EU General Safety Regulation mandates ISA compliance across all new vehicle types, eliminating demand uncertainty for OEM-integrated alert modules.
- Public Transportation:Municipal bus operators face tightening speed compliance requirements in urban cores.
- Emergency Service Vehicles:Ambulance and fire apparatus require conditional override capabilities for urgent response scenarios.
- Delivery Trucks:Last-mile logistics providers prioritize compact retrofit units compatible with mixed-vintage vehicle pools.
Commercial fleets generate the highest per-unit software attach rates, while passenger vehicles provide the largest absolute installation base.
End User:
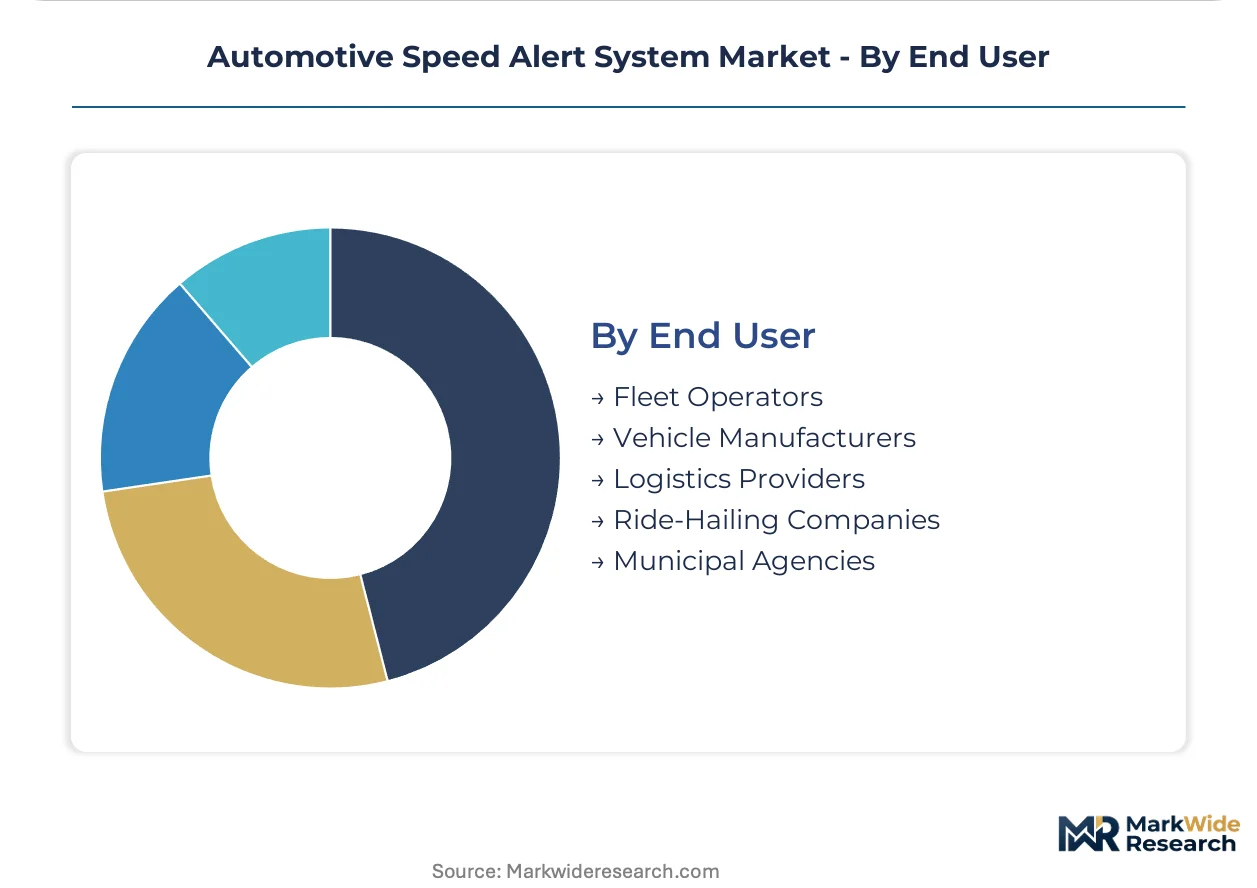
Procurement sophistication separates enterprise fleet operators with dedicated telematics procurement teams from municipal agencies constrained by public tender processes.
- Fleet Operators:Large trucking and logistics companies negotiate integrated contracts spanning hardware, software, and insurance linkages. UK commercial auto insurers have embraced usage-based pricing models that reward alert system deployment.
- Vehicle Manufacturers:OEMs source ISA-compliant modules through multi-year supply agreements with tier-1 electronics suppliers.
- Logistics Providers:Third-party fulfillment operators balance retrofit costs against contractually mandated delivery time guarantees.
- Ride-Hailing Companies:Platform operators face regulatory pressure to monitor driver speed compliance across contractor vehicle pools.
- Municipal Agencies:Public transit authorities navigate budget cycles and vendor qualification requirements for bus fleet upgrades.
Fleet operators are expanding most quickly as a customer segment, while vehicle manufacturers retain the largest contract values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European Union's General Safety Regulation mandating Intelligent Speed Assistance anchors the dominant geography, with Germany, France, the United Kingdom, Japan, and the United States representing the critical national markets where regulatory frameworks and industrial capacity intersect.
Germany
Commercial fleet operators in Germany deploy speed alert systems to reduce insurance premiums and liability exposure from driver-related incidents. The KBA enforces EU type-approval requirements for ISA-compliant modules across all new vehicle registrations. Stuttgart and Ingolstadt host tier-1 electronics manufacturers scaling production of fused sensor modules for both domestic assembly and export programs.
France
French automotive suppliers accelerate camera-radar fusion development to meet the EU General Safety Regulation's mandatory installation timeline. ANSM oversees technical compliance for vehicle safety systems entering the European market. The Île-de-France region concentrates R&D facilities where algorithm training datasets for traffic sign recognition are being compiled.
United Kingdom
UK commercial auto insurers have embraced usage-based pricing models that reward fleet operators for alert system deployment. The Driver and Vehicle Standards Agency enforces speed compliance monitoring requirements for heavy goods vehicles. Midlands-based logistics providers negotiate integrated telematics contracts bundling hardware with driver behavior analytics platforms.
Japan
Japanese vehicle platforms prioritize radar-centric speed alert architectures for all-weather redundancy in domestic and Southeast Asian export markets. METI promotes cooperative intelligent transport systems that integrate vehicle-to-infrastructure speed data. Nagoya-area electronics manufacturers specialize in real-time processing modules calibrated for regional road conditions.
United States
NHTSA evaluates speed-limiting technologies for heavy commercial vehicles while voluntary adoption patterns dominate passenger vehicle segments. California-based fleet operators pilot cloud-connected monitoring systems for centralized driver compliance management. Detroit-area OEMs source ISA-compliant modules through multi-year supply agreements with tier-1 suppliers.
Automotive Speed Alert System Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the speed alert ecosystem. The market structure consolidates around tier-1 automotive electronics suppliers with captive sensor fusion capabilities, while mid-scale module vendors compete on retrofit fleet pricing. Three archetypes dominate: diversified automotive electronics conglomerates with backward integration into semiconductor design, specialized real-time processing module developers, and telematics-integrated fleet solution providers. Competitive moves concentrate on strategic partnerships for algorithm licensing and capacity expansion for ISA-compliant production lines.
Among diversified automotive electronics conglomerates, Continental AG and Robert Bosch GmbH exemplify the technology leadership archetype through captive sensor fusion architectures and radar chip design capabilities. Denso Corporation occupies a position within the specialized processing tier, with its Japanese corporate structure reflecting regional platform calibration strengths. These three companies anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| ZF |
| WABCO |
| Bosch |
| AISIN |
| Hitachi Metal |
| Continental |
| Delphi |
| Denso |
| MOBIS |
| Others |
Cost & Logistics Intelligence
EU General Safety Regulation type-approval requirements gate both module qualification and price differentiation simultaneously, forcing tier-1 suppliers to absorb certification overhead while OEMs tier procurement by ISA compliance grade.
Pricing Analysis
German OEM supply contracts command 40-60% premiums over Southeast Asian fleet retrofit pricing for functionally equivalent camera-radar fusion modules. Three-tier pricing structure across premium ISA-compliant, standard OEM-integrated, and economy aftermarket levels stratifies by certification investment and volume commitment. Cost compression in economy tiers is intensifying because Chinese module assemblers are scaling GPS-based alternatives for price-sensitive fleet operators. Commercial fleet operators exhibit highest price sensitivity due to hardware amortization across thin-margin logistics contracts.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes have elevated inbound logistics costs for radar chip shipments from Taiwan and South Korea. Module assembly concentrates in Germany, Japan, and Mexico, drawing from semiconductor fabrication in Taiwan, South Korea, and the United States. Raw material dependencies span gallium arsenide for radar front-ends, automotive-grade SoCs from TSMC, and specialized lens polymers for camera housings. Single-source vulnerability in radar chip fabrication exposes tier-1 suppliers to allocation risk. Distribution runs through captive OEM supply agreements for new vehicles and telematics distributors for fleet retrofit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Speed alert system economics are inflecting toward platform-based recurring revenue as fleet telematics bundles subsume standalone hardware procurement, accelerated by Japan METI's cooperative transport interoperability standards.
For Market Incumbents: Shield embedded software engineering capacity through captive hiring pipelines and acquisition of machine learning optimization boutiques in Stuttgart and Nagoya. ISA compliance certification investment represents the priority defensive lever against Chinese module assemblers eroding mid-market pricing. Backward integration into radar chip design secures supply allocation during semiconductor constraint periods.
For New Entrants and Emerging Players: CE marking fast-track for ISA-compliant camera modules opens white-space penetration in UK commercial fleet retrofit channels where usage-based insurance partnerships reduce customer acquisition friction. Vietnam and Indonesia passenger vehicle assembly plants offer the most penetrable geography as domestic safety regulations mature toward EU-equivalent standards. Target cloud-connected fleet monitoring software attach rather than hardware-only positioning.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sensor fusion algorithm development as training dataset compilation and real-world validation cycles lengthen. Five-to-ten-year viability favors acquisition targets with proprietary calibration IP and existing OEM qualification relationships. Monitor divergence between mandatory European installation volumes and voluntary North American adoption patterns as the critical inflection signal for capacity allocation decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| ISA Compliance Certification Investment | KBA type-approval accelerates OEM sourcing decisions for German tier-1 suppliers. |
| Sensor Fusion Algorithm Licensing | Proprietary camera-radar calibration IP creates defensible margin pools against commoditization. |
| Fleet Telematics Platform Integration | UK usage-based insurance partnerships bundle hardware with recurring software revenue streams. |
| Southeast Asian Manufacturing Footprint | Indonesia and Vietnam assembly scale reduces logistics cost for regional OEM supply programs. |
| Vehicle-to-Infrastructure Data Partnership | Japan METI cooperative transport initiatives enable dynamic speed limit update capabilities. |
Research Approach
A standing panel of Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and fleet telematics operators provided ongoing calibration across the analysis window. Primary interview findings were cross-validated against vehicle production databases, IHS Markit registration data, EU type-approval filings, and customs trade records. Bottom-up module shipment estimates and top-down OEM integration forecasts were triangulated to derive market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation by product type, technology tier, vehicle application, and regional regulatory cluster. CAGRs were derived from installation volume trajectories, content-per-vehicle trends, and pricing elasticity assumptions. Industry-specific inputs included ISA mandate compliance timelines, fleet insurance partnership penetration rates, and semiconductor allocation forecasts.
The analysis sits within stated boundaries; outcomes outside EU regulatory enforcement levels, Southeast Asian vehicle ownership growth trajectories, or semiconductor supply normalization would require recalibration. Forecasts reflect documented assumptions regarding OEM integration rates, fleet retrofit replacement cycles, and cloud connectivity adoption curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Inflatable Seat Belt Market
Automotive Safety and Security Systems
Global Automotive Intelligent Door System Market
Automotive Safety and Security Systems
Asia Pacific Lane Departure Warning Systems Market
Automotive Safety and Security Systems
Global Car Radar Detectors Market
Automotive Safety and Security Systems
Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Automotive Seat Belt Pretensioner Market
Automotive Safety and Security Systems
Global Electronic Brake Force Distribution System Market
Automotive Safety and Security Systems
Europe Adaptive Steering Market
Automotive Safety and Security Systems
Automotive Crash Barriers Market
Automotive Safety and Security Systems
Automotive Knock Sensor Market
Automotive Safety and Security Systems
Collision Mitigation Technology Market
Automotive Safety and Security Systems
Driving Helmet Market
Automotive Safety and Security Systems
Hill-Start Assist System Market
Automotive Safety and Security Systems
North America Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Anti-Lock Braking System (ABS) Market
Automotive Safety and Security Systems
Emergency Vehicle Lights Market