
 Rail Wheel and Axle Market | 2026-2036
Rail Wheel and Axle Market Size, Share, and Industry Trends Forecast 2026-2036
Rail Wheel and Axle Market Outlook
European steel forging capacity is consolidating as producers scale billet-to-finished-axle operations to serve rising locomotive OEM demand. ArcelorMittal leverages its integrated European mills to control raw material flow into wheel production. Bharat Forge Limited anchors South Asian supply through its heavy forging complexes serving domestic and export rail contracts. Lucchini RS specializes in premium wheel grades for high-speed applications across Mediterranean networks.
Rail wheels and axles are forged or cast rotating components, typically manufactured from pearlitic steel grades with Brinell hardness between 260 and 320 HB, that transmit vehicle weight and traction forces to the railhead while sustaining cyclic bending and contact stresses. Their primary purpose is to ensure safe, reliable rolling contact over millions of load cycles at speeds up to and beyond 300 km/h. High-speed wheels command premium positioning due to ultrasonic testing mandates and residual stress control requirements that limit qualified suppliers. Freight wheels constitute the volume base but face margin compression from standardized EN 13262 specifications and price-sensitive procurement by Class I railroads.
The Association of American Railroads (AAR) governs wheel and axle interchange standards across North American freight networks, enforcing material traceability and fatigue test protocols that shape supplier qualification timelines. ECHA's REACH framework and the EU's F-Gas Regulation constrain lubricant and surface treatment chemistries used in European wheelset maintenance, redirecting demand toward compliant coating systems. China's GB/T 8601 and GB/T 8602 national standards, administered by SAMR, set dimensional and metallurgical benchmarks that dominate procurement specifications across Asia-Pacific rail projects. Stakeholders must monitor evolving hydrogen embrittlement test protocols and cross-border certification reciprocity as procurement regionalizes around distinct regulatory blocs.
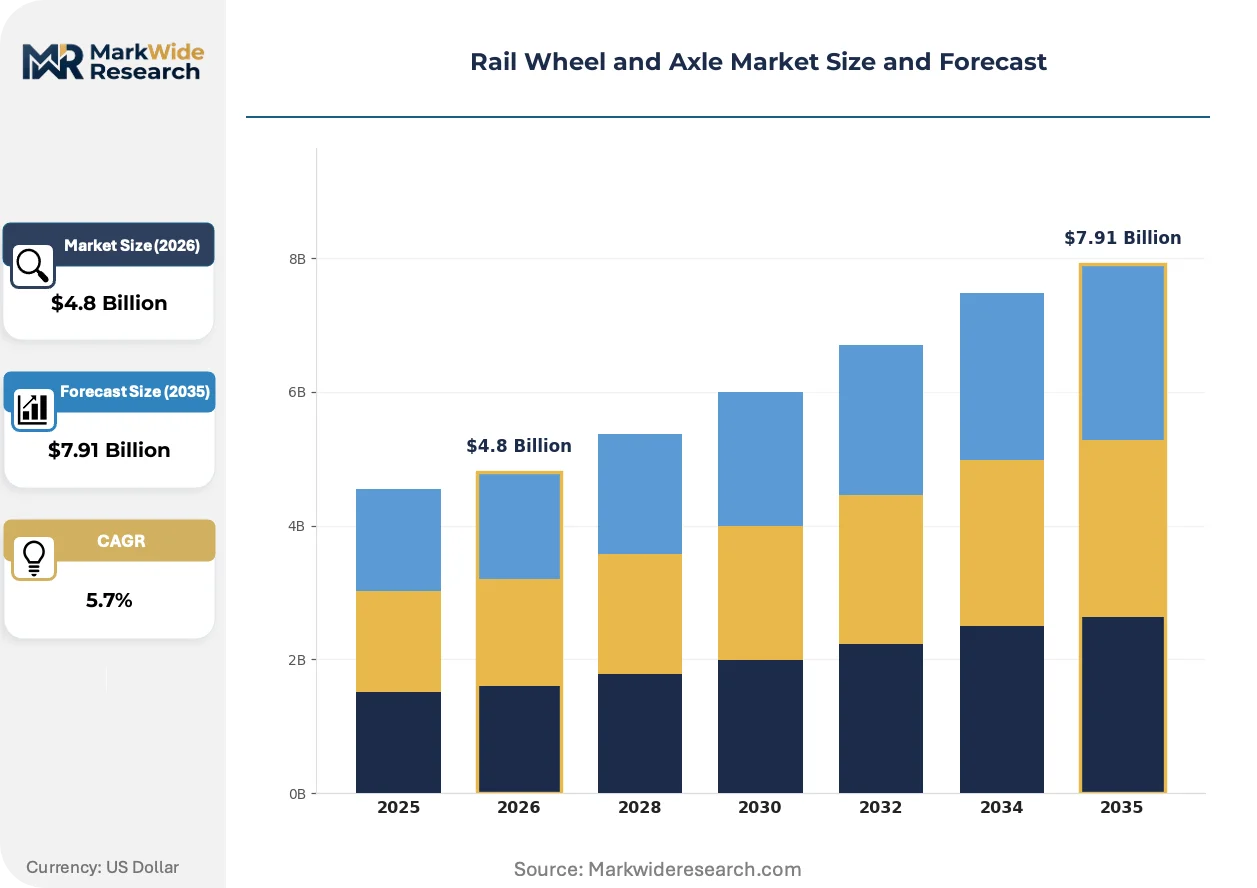
Market Dynamics
Fleet renewal cycles across North American freight networks are compressing supplier lead times while EU fatigue-testing mandates force metallurgical upgrades that disqualify legacy forging capacity.
Growth Catalysts
- Freight fleet modernization:Class I railroads in the United States are accelerating wheelset replacement schedules to address fatigue failures in 30-year-old axles, pulling forward procurement volume from planned 2030 timelines.
- F-Gas Regulation compliance:The European Union's tightened restrictions on fluorinated greenhouse gases in rail maintenance operations are redirecting demand toward water-based surface treatments and compliant coating chemistries.
- Micro-alloyed steel adoption:Pearlitic grades with vanadium and niobium micro-additions are displacing conventional carbon steels in high-speed applications due to superior residual stress control and extended inspection intervals.
Market Restraints
- Scrap steel price volatility:Electric arc furnace operators face margin compression when shredded scrap premiums spike above hot-rolled coil spreads, squeezing billet-to-axle conversion economics.
- Qualified supplier concentration:Ultrasonic testing mandates for wheels above 250 km/h operation limit certified production to a handful of European and Asian forging complexes with in-house heat-treatment capability.
- Interchange standard fragmentation:Misalignment between AAR M-107/M-208 specifications and EN 13262 testing protocols forces dual-certification investments that extend supplier qualification timelines by 18-24 months.
Strategic Opportunities
- Urban transit expansion in India:Metro rail projects in Mumbai, Delhi, and Bangalore are generating procurement volume for forged wheels in 760-840 mm diameters with noise-dampening profiles.
- Digital twin integration:Convergence of ultrasonic inspection data with predictive maintenance platforms is enabling condition-based wheelset replacement that extends operational life beyond fixed-mileage schedules.
- Green steel procurement mandates:State-backed rail operators in Germany and France are incorporating Scope 3 emissions criteria into tender evaluations, favoring suppliers with hydrogen-reduced billet supply chains.
Industry Challenges
- Non-destructive testing technician shortage:Qualified personnel capable of interpreting ultrasonic defect signatures in pearlitic microstructures are concentrated at legacy forging sites with limited training pipeline capacity.
- Residual stress certification delays:EN 13262-4 validation protocols for new heat-treatment cycles require 12-18 months of field testing, blocking commercialization of process innovations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rail Wheel and Axle Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Wheels, Freight Wheels, High-Speed Wheels, Axles Material: Steel, Aluminum, Composite, Alloy End User: Rail Operators, Freight Companies, Manufacturers, Maintenance Providers Application: Urban Transit, Intercity Transport, Cargo Handling, High-Speed Rail |
| Companies Covered | ArcelorMittal, Bharat Forge Limited, Amsted Rail, Interpipe, CRRC Sifang, NSSMC, Lucchini RS, Kolowag, GHH-BONATRANS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rail Wheel and Axle Market Strategic Shifts
Digital inspection technologies and metallurgical process controls are compressing the gap between forged component performance and predictive maintenance capabilities across passenger and freight rail networks.
Additive manufacturing of brake shoe mounting interfaces and sensor housings is rewriting maintenance economics for specialized rolling stock. European high-speed operators are piloting topology-optimized titanium brackets that reduce unsprung mass while preserving fatigue resistance. This convergence of powder-bed fusion with traditional forging supply chains is compressing spare parts lead times from 16 weeks to 72 hours for low-volume configurations.
The EU's F-Gas Regulation is eliminating hydrofluorocarbon-based cleaning chemistries from wheelset maintenance depots. REACH-registered alternatives in aqueous alkaline formulations are displacing solvent degreasing across French and German rail networks. Freight operators with cross-border fleets are consolidating maintenance at compliant facilities in Poland and Romania to avoid regulatory friction.
Condition-based procurement contracts are displacing fixed-schedule wheelset replacement in North American coal and intermodal corridors. Union Pacific and BNSF are unbundling wheel supply from mounting services, directing volume toward independent maintenance providers with in-track profiling capability. This behavioral shift is most visible in Powder River Basin coal routes where real-time hollow-wear detection triggers just-in-time replacement orders.
Rail Wheel and Axle Market Segmentation
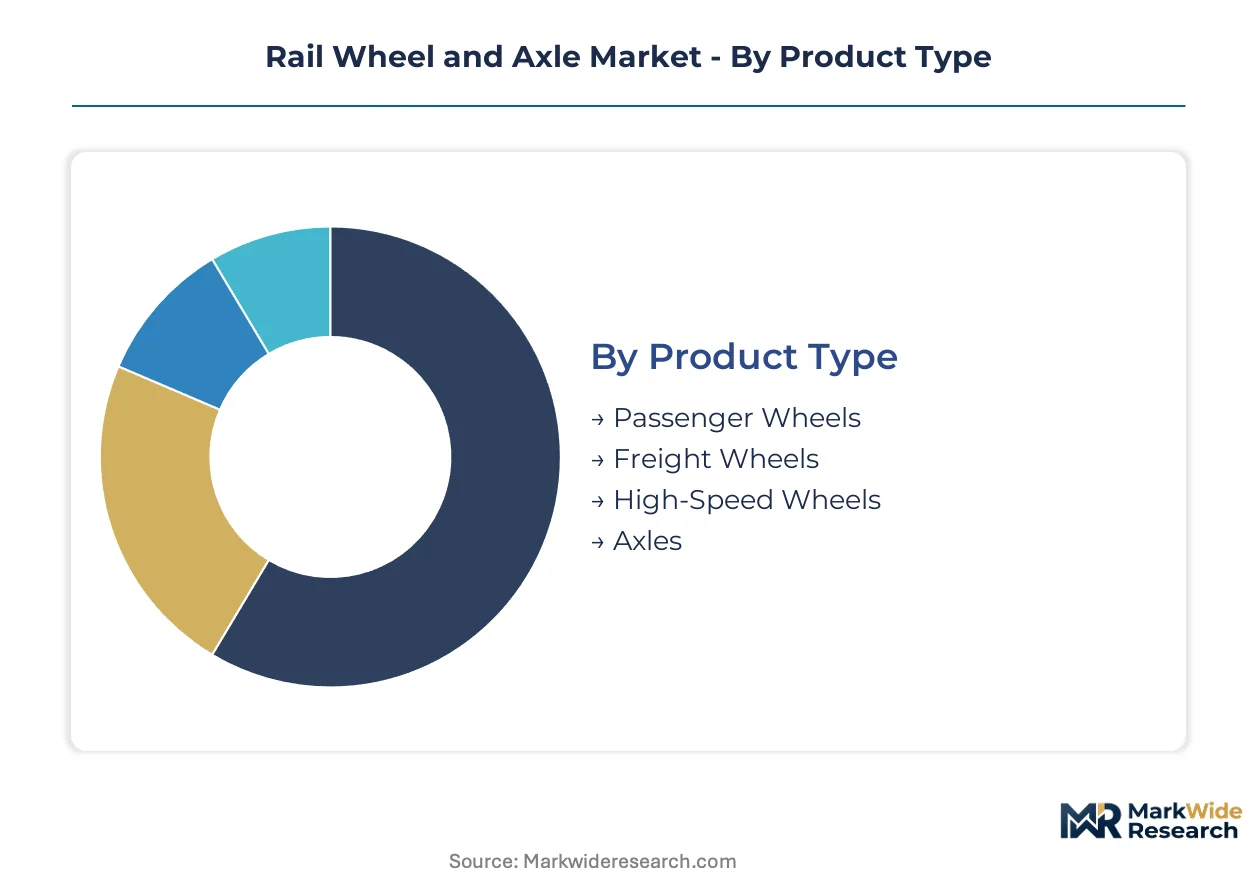
Rail wheel and axle procurement splits across four distinct axes that shape supplier qualification requirements and capital deployment strategies. Product type determines metallurgical complexity and testing mandates. Material selection governs heat-treatment infrastructure investments. End-user structure concentrates volume among state-backed operators versus fragmented maintenance providers. Application context sets speed ratings that filter supplier pools.
Product Type:
Capital intensity peaks in segments requiring in-house ultrasonic testing bays and residual stress certification facilities.
- Passenger Wheels:Forged pearlitic steel wheels in 760-920 mm diameters serve commuter and regional networks with Brinell hardness specifications between 260-300 HB. Demand clusters in India's metro expansion corridors and Germany's S-Bahn renewal programs where noise-dampening profiles are now mandatory.
- Freight Wheels:Heavy-section cast or forged wheels tolerate 35-tonne axle loads across millions of load cycles. Procurement volume concentrates with Union Pacific and BNSF in the United States as 30-year axle replacement cycles compress lead times.
- High-Speed Wheels:Require EN 13262-4 compliant heat-treatment with controlled residual stress profiles for operation above 250 km/h.
- Axles:Solid forged shafts in EA1N or EA4T grades transmit bending moments and bearing seats with fatigue-tested fillet radii.
Most installed capacity flows through Freight Wheels. Expansion is steepest in High-Speed Wheels.
Material:
Cost tier stratification separates commodity grades from premium micro-alloyed formulations with extended inspection intervals.
- Steel:Pearlitic carbon and micro-alloyed grades dominate through ArcelorMittal's integrated European mills and Bharat Forge's Indian forging complexes. Vanadium and niobium micro-additions are displacing conventional carbon steels in Chinese high-speed procurement.
- Aluminum:Lightweight forged alloys reduce unsprung mass in urban transit applications with frequent acceleration cycles.
- Composite:Polymer-matrix formulations for brake interfaces and noise-dampening layers.
- Alloy:Chrome-molybdenum grades for extreme duty cycles in heavy-haul mining corridors.
Steel commands the production base. Aluminum is gaining share fastest in metro fleet specifications.
End User:
Customer type determines contract structure, with state operators favoring multi-year framework agreements and freight railroads unbundling supply from mounting services.
- Rail Operators:Deutsche Bahn and SNCF incorporate Scope 3 emissions criteria into tender evaluations, favoring hydrogen-reduced billet supply chains.
- Freight Companies:Class I railroads in the United States are accelerating wheelset replacement schedules and directing volume toward independent maintenance providers with in-track profiling capability.
- Manufacturers:CRRC Sifang and Alstom source certified wheelsets for new-build rolling stock with integrated brake systems.
- Maintenance Providers:Independent depots in Poland and Romania consolidate cross-border fleet servicing to avoid EU F-Gas regulatory friction.
Rail Operators hold the procurement volume. Maintenance Providers are expanding most quickly as operators unbundle services.
Application:
Speed rating and duty cycle requirements filter supplier qualification, with urban transit favoring noise-optimized profiles and high-speed rail mandating residual stress documentation.
- Urban Transit:Metro rail projects in Mumbai, Delhi, and Bangalore generate procurement volume for forged wheels with noise-dampening profiles and 760-840 mm diameters.
- Intercity Transport:Regional networks in France and Italy require wheels with intermediate hardness grades balancing wear resistance and RCF mitigation.
- Cargo Handling:Port and yard locomotives operate at low speeds with high tractive effort, prioritizing thermal fatigue resistance over high-speed integrity.
- High-Speed Rail:China's GB/T 8601 standards and EN 13262 protocols limit certified production to European and Asian forging complexes with in-house heat-treatment capability.
Urban Transit absorbs the most forging capacity. High-Speed Rail shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting forging capacity toward jurisdictions with streamlined certification reciprocity and lower compliance burdens for heat-treatment emissions. Producers are relocating residual stress testing infrastructure to exploit gaps between AAR and EN protocol enforcement.
United States
Class I railroads are compressing 30-year axle replacement cycles across Powder River Basin coal corridors and intermodal routes. The Federal Railroad Administration enforces brake system integrity standards that cascade into wheelset procurement specifications. Chicago-area maintenance depots are consolidating in-track profiling services as Union Pacific and BNSF unbundle supply from mounting contracts.
Germany
Deutsche Bahn's framework agreements incorporate Scope 3 emissions criteria that favor hydrogen-reduced billet supply chains for S-Bahn renewal programs. The EU F-Gas Regulation eliminates hydrofluorocarbon cleaning chemistries from wheelset maintenance depots. Ruhr Valley forging complexes are scaling ultrasonic testing bays to serve Mediterranean high-speed export contracts.
China
CRRC Sifang and state-backed maintenance networks are driving procurement volume for high-speed lines exceeding 300 km/h operation. SAMR-administered GB/T 8601 and GB/T 8602 standards set dimensional and metallurgical benchmarks across Asia-Pacific rail projects. Yangtze River Delta manufacturing clusters are integrating micro-alloyed vanadium grades to extend inspection intervals.
India
Metro rail expansions in Mumbai, Delhi, and Bangalore are generating demand for 760-840 mm diameter forged wheels with noise-dampening profiles. The Bureau of Indian Standards certifies pearlitic steel grades for domestic heavy-haul corridors. Bharat Forge's heavy forging complexes in Pune and Mundhwa anchor South Asian supply for export rail contracts.
Poland
Cross-border freight operators are consolidating maintenance at Polish depots to avoid EU F-Gas regulatory friction with non-compliant Eastern European facilities. The country's central rail corridor position enables just-in-time wheelset replacement for coal and container traffic between German ports and Ukrainian border crossings. Katowice-area forging sites are expanding residual stress certification capacity for EN 13262-4 compliance.
Rail Wheel and Axle Market Competitive Environment
European producers anchor the premium-tier segment with integrated mill-to-forge operations; Asian specialists hold volume positions through state-backed procurement networks. The vendor base stratifies across three tiers: integrated steelmakers with captive billet supply, independent forging houses serving maintenance providers, and rolling stock OEMs with in-house wheelset divisions. Competitive intensity centers on certification reciprocity investments and heat-treatment process patents rather than price alone. Capacity expansion and strategic partnerships represent the dominant competitive moves as producers seek to bridge AAR-EN protocol gaps.
Among integrated European steelmakers, ArcelorMittal exemplifies the backward-integrated archetype with controlled raw material flow into wheel production. Bharat Forge Limited occupies a position within the independent forging tier, anchoring South Asian supply through heavy forging complexes. CRRC Sifang represents the state-backed OEM archetype, integrating certified wheelset procurement with new-build rolling stock manufacturing. These three entities illustrate how geographic origin and corporate structure shape competitive positioning without converging on identical capability sets.
| Leading Market Players |
|---|
| ArcelorMittal |
| Bharat Forge Limited |
| Amsted Rail |
| Interpipe |
| CRRC Sifang |
| NSSMC |
| Lucchini RS |
| Kolowag |
| GHH-BONATRANS |
| Others |
Value Chain & Pricing Dynamics
EU F-Gas Regulation compliance gates both qualified supply and premium-tier pricing access, as maintenance depots without REACH-registered aqueous cleaning chemistries forfeit high-speed wheel contracts while certified operators command residual stress certification premiums.
Pricing Analysis
Distributor margins for independent maintenance providers sit at 12-18 points above direct OEM supply, compressing as Union Pacific and BNSF unbundle mounting services. Three-tier pricing structure across premium, standard, and economy levels separates EN 13262-4 certified high-speed wheels from AAR M-107 freight grades and unapproved import alternatives. Pricing pressure stems from scrap steel volatility squeezing electric arc furnace billet economics. Class I railroads exhibit highest price sensitivity through competitive tendering, while state-backed operators in Germany and France absorb green steel premiums for Scope 3 compliance.
Supply Chain Analysis
Single-source vulnerability sits with Ukrainian semi-finished billet supply disrupted by corridor instability, forcing European forgers to draw from ArcelorMittal's integrated mills and Bharat Forge's Indian complexes. Raw material dependencies center on pearlitic steel scrap, vanadium micro-alloying additions, and residual stress testing equipment. Supply chain risk concentrates in EN 13262-4 certification reciprocity gaps that block Asian forged wheels from European high-speed tenders. Distribution runs through state-backed procurement frameworks in China, consolidated maintenance depots in Poland, and unbundled independent providers across North American freight corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, justified by the demand-shift toward micro-alloyed vanadium grades with extended inspection intervals displacing conventional carbon steels.
For Market Incumbents: Lock in residual stress testing capacity at Katowice-area and Ruhr Valley forging sites before EN 13262-4 validation timelines extend supplier qualification bottlenecks. Secure captive billet supply through backward integration into hydrogen-reduced steel production to defend margin position against green steel procurement mandates from Deutsche Bahn and SNCF. For New Entrants and Emerging Players: Independent maintenance providers in Poland and Romania represent an underserved buyer archetype consolidating cross-border fleet servicing to avoid F-Gas regulatory friction. Target these depots with just-in-time wheelset replacement contracts for Powder River Basin coal routes, leveraging in-track profiling capability as the go-to-market wedge against incumbent supply bundling. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap forging houses with in-house heat-treatment capability because certification reciprocity investments create moats that extend payback periods for new greenfield capacity. Monitor hydrogen embrittlement test protocol harmonization between AAR and EN frameworks as the inflection signal for cross-border M&A viability.| Strategic Initiative | Industry Significance |
|---|---|
| Residual Stress Certification Expansion | EN 13262-4 validation capacity at Katowice sites captures Mediterranean high-speed export contracts. |
| Hydrogen-Reduced Billet Supply Chain | Green steel procurement mandates from Deutsche Bahn favor early movers with Scope 3 compliance. |
| Digital Twin Integration Partnership | Convergence with predictive maintenance platforms extends wheelset replacement intervals for Union Pacific. |
| Micro-Alloyed Grade Commercialization | Vanadium-niobium additions displace carbon steels in CRRC Sifang high-speed procurement. |
| Cross-Border Maintenance Consolidation | Polish depot networks exploit F-Gas regulatory arbitrage for German and French freight operators. |
Study Parameters
Bottom-up rail operator procurement modeling reconciled against top-down forging capacity tracking forms the analytical core, combining primary interviews with maintenance depot managers, OEM procurement leads, and metallurgical testing directors with secondary validation from AAR interchange standards filings, ECHA REACH registration databases, and SAMR GB/T standard publications.
Input-output matrices map product type, material grade, end-user structure, and application speed ratings against billet supply, heat-treatment capacity, and certification throughput across the projection horizon. CAGRs derive from segment-level volume trajectories adjusted for fleet renewal cycle compression and regulatory mandate timing, with freight wheel replacement schedules and high-speed line commissioning curves as rail-specific forecast inputs.
Underlying measurement precision varies by segment; high-speed wheels with certified supplier concentration carry tighter precision than fragmented freight maintenance markets. Forecasts reflect assumptions on scrap steel price corridors, certification reciprocity progress, and hydrogen embrittlement protocol adoption that could shift if Class I railroads accelerate replacement timelines or EN-AAR alignment stalls. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Fuel Sensor Market
Vehicle Components
US Group 2 Powered Mobility Devices Market
Vehicle Components
Railway Brake Pads Market
Vehicle Components
Wheel Seals Market
Vehicle Components
Locomotive Lighting Batteries Market
Vehicle Components
Automotive Exhaust Gas Sensor Market
Vehicle Components
US Automotive Sensors Market
Vehicle Components
UK Automotive Glass Fiber Composites Market
Vehicle Components
Automotive Rubber Molded Components Market
Vehicle Components
Forestry Trailers Market
Vehicle Components
Wheel Studs Market
Vehicle Components
Trailer Spindles Market
Vehicle Components
Global Automotive Carbon Fiber Composites Market
Vehicle Components
Global Electric Vehicle Parts and Components Market
Vehicle Components
Russia Automotive Composites Market
Vehicle Components
LAMEA Vehicle Exhaust Hose Market