
 Australia Rail Freight Transport Market | 2026-2036
Australia Rail Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Rail Freight Transport Market Outlook
The Australian government's net-zero emissions target is recalibrating buyer mandates across heavy industry supply chains. Aurizon leverages its east-west corridor dominance to capture coal and mineral volumes shifting from road transport. Pacific National sustains competitive pressure through intermodal terminal density along the Sydney-Melbourne-Brisbane triangle. SCT Logistics specializes in temperature-controlled and time-sensitive freight, carving differentiated positioning in agricultural logistics.
Australia rail freight transport encompasses the movement of goods via heavy-haul locomotives and wagon fleets across standard and narrow-gauge networks spanning thousands of kilometers of track. Trains typically haul bulk commodities at axle loads exceeding 25 tonnes on dedicated mining corridors, with double-stacked container services operating on interstate standard-gauge lines. Bulk freight dominates tonnage moved, reflecting the structural weight of iron ore and coal movements from Pilbara and Bowen Basin extraction zones. Intermodal services represent the fastest-expanding segment as retail and manufacturing supply chains seek alternatives to long-haul trucking on key corridors. Containerized grain exports from Western Australia and South Australia are gaining share as port infrastructure upgrades enable unit-train loading efficiencies.
The National Transport Commission sets fatigue management and safety standards that shape crew scheduling and operational economics across all carriers. Infrastructure Australia evaluates corridor investments against productivity benchmarks, while the Australian Rail Track Corporation manages access pricing on interstate lines. State-based environmental regulators in Queensland and Western Australia impose dust suppression and noise protocols on bulk haulage routes. Stakeholders must track how the Inland Rail completion timeline and state-level decarbonization mandates reshape corridor competitiveness and fleet investment priorities.
Market Dynamics
The Inland Rail corridor completion timeline is compressing modal competition economics between Melbourne and Brisbane, forcing bulk commodity producers to renegotiate long-term haulage contracts ahead of infrastructure commissioning.
Growth Catalysts
- Queensland coal corridor upgrades:Track capacity expansions on the Goonyella system enable larger unit trains from Bowen Basin mines to Gladstone port terminals.
- Western Australian grain network standardization:Narrow-to-standard gauge conversions at Esperance and Albany ports reduce double-handling costs for containerized cereal exports.
- Heavy-haul axle load protocols:Australian Rail Track Corporation approvals for 40-tonne axle loads on specific Pilbara corridors cut cycle times for iron ore producers.
Market Restraints
- Diesel price volatility:Fuel represents 25-35% of operating costs for long-haul operators, exposing margins to refined product import dependency.
- Track access bottleneck concentration:Australian Rail Track Corporation monopoly pricing on interstate standard-gauge lines limits carrier negotiation leverage.
- Driver certification pipeline constraints:National Transport Commission fatigue management rules extend training timelines for qualified locomotive crews.
Strategic Opportunities
- Tasmanian intermodal underpenetration:Bass Strait containerized freight remains road-dominated; rail-sea integration at Melbourne's Dynon terminal offers capture potential.
- Hydrogen locomotive pilot programs:Australian Renewable Energy Agency funding for zero-emission bulk haulage trials creates first-mover positioning in Pilbara corridors.
- Perth-Adelaide corridor reactivation:Containerized agricultural exports from South Australia's Eyre Peninsula lack direct rail connection; infrastructure consortium models are emerging.
Industry Challenges
- Signaling system integration complexity:European Train Control System rollout across interstate networks requires simultaneous fleet and infrastructure capex coordination.
- Maintenance workforce specialization gaps:Aging heavy-haul mechanical expertise in regional Queensland and Western Australia outpaces vocational training program outputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Rail Freight Transport Market |
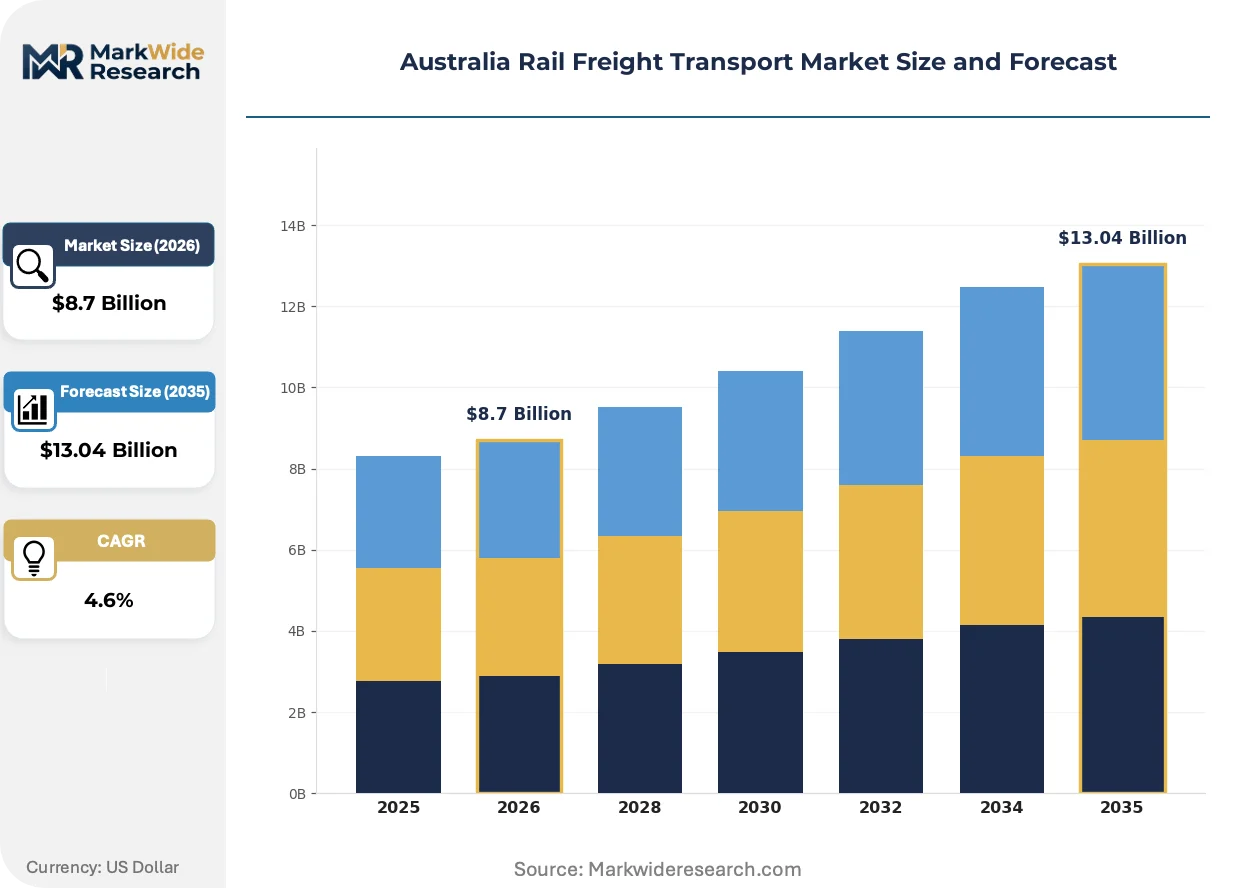
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Intermodal, Bulk Freight, Containerized, Dedicated Freight End User: Agriculture, Mining, Retail, Manufacturing Product Type: Cement, Coal, Grains, Liquids Capacity: Heavy Load, Standard Load, Light Load, Mixed Load |
| Companies Covered | Southern Shorthaul Railroad, Sadleirs Rail Freight, Aurizon, KTI, CTI Logistics, Pacific National, Toll Group, Rail First Asset Management, SCT Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Rail Freight Transport Market Strategic Shifts
Digitization of train control and asset monitoring is compressing operational response times across Australia's sparse rail networks. Corridor operators are deploying sensor arrays and predictive analytics to preempt rolling stock failures before they strand bulk commodity trains on single-track lines.
Positive train control systems are automating movement authority enforcement across Pilbara heavy-haul corridors. Rio Tinto and BHP have deployed autonomous haulage pilots that remove drivers from high-frequency iron ore shuttle routes. The technology is automating safety-critical decisions previously requiring human intervention, reducing collision risk on shared infrastructure.
The National Transport Commission's updated fatigue management standard tightens duty-cycle limits for multi-crew long-haul operations. Interstate container carriers face revised scheduling economics as maximum consecutive driving hours compress. SCT Logistics and Pacific National are restructuring rosters across the Sydney-Melbourne corridor to comply while maintaining service frequency commitments.
Supply chain managers at agricultural exporters are consolidating procurement around carriers offering integrated port-terminal-rail contracts. Grain handlers in Western Australia now specify performance-based pricing tied to vessel loading windows rather than traditional tonnage rates. This behavior shift is most visible in the Kwinana-Albany corridor where containerized cereal volumes have tripled since dedicated unit-train loading facilities commissioned.
Australia Rail Freight Transport Market Segmentation
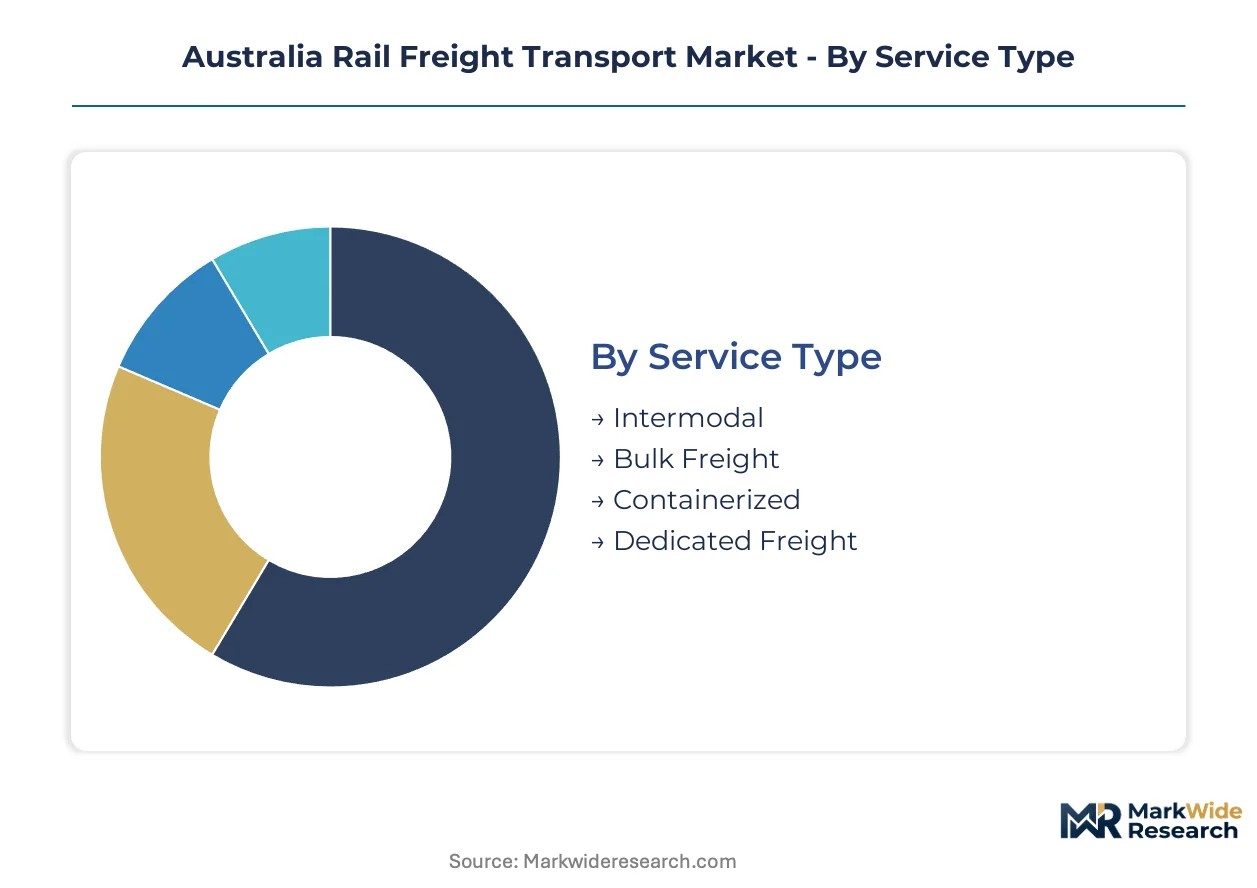
Rail freight segmentation in Australia reflects the divergence between commodity-driven bulk haulage and time-sensitive containerized logistics. Each category captures distinct operational economics, infrastructure requirements, and customer procurement behaviors across the country's sparse network topology.
Service Type:
Standardization dominates intermodal scheduling while bulk freight retains heavy customization around mine-to-port corridors.
- Intermodal:Double-stacked container services operating on standard-gauge interstate lines between Melbourne, Sydney, and Brisbane. Retail and manufacturing supply chains in the eastern seaboard corridor are shifting procurement from long-haul trucking to scheduled rail services as Inland Rail commissioning nears.
- Bulk Freight:Dedicated unit-train operations hauling iron ore, coal, and minerals at axle loads exceeding 25 tonnes on narrow-gauge mining corridors. Pilbara iron ore producers and Bowen Basin coal miners negotiate long-term take-or-pay contracts with corridor operators.
- Containerized:Single-stack and curtain-sided container movements for agricultural exports and manufactured goods. Grain handlers in Western Australia specify vessel loading window performance rather than traditional tonnage rates.
- Dedicated Freight:Captive fleet arrangements serving single commodity producers on private track infrastructure. Mining majors in the Pilbara deploy autonomous haulage pilots on high-frequency shuttle routes.
Leading the category by volume: Bulk Freight. Expanding most quickly: Intermodal.
End User:
Volume concentration tilts toward extractive industries while agricultural logistics demands specialized equipment and scheduling flexibility.
- Mining:Iron ore, coal, and mineral producers generate the majority of rail freight tonnage through mine-to-port unit trains. Rio Tinto and BHP have deployed driverless haulage systems on Pilbara corridors to compress cycle times.
- Agriculture:Grain, livestock feed, and horticultural exporters require temperature-controlled and time-sensitive service configurations. Containerized cereal volumes from Western Australia's Kwinana-Albany corridor have tripled since dedicated loading facilities commissioned.
- Retail:Big-box and e-commerce distribution centers source interstate container services for non-perishable inventory replenishment. Pacific National and SCT Logistics compete on terminal density across the Sydney-Melbourne-Brisbane triangle.
- Manufacturing:Industrial input supply chains for steel, chemicals, and construction materials utilize scheduled block-train services. Just-in-time procurement patterns are forcing carriers to tighten delivery windows.
Highest volume concentration: Mining. Steepest expansion trajectory: Agriculture.
Product Type:
Commodity density and handling requirements determine equipment specification and corridor routing economics.
- Coal:Thermal and metallurgical coal movements from Queensland's Bowen Basin and New South Wales' Hunter Valley dominate tonnage. Track capacity expansions on the Goonyella system enable larger unit trains to Gladstone port terminals.
- Grains:Wheat, barley, and canola exports from Western Australia and South Australia require specialized hopper wagons and fumigation protocols. Narrow-to-standard gauge conversions at Esperance and Albany ports reduce double-handling costs.
- Cement:Construction materials move in pneumatic pressure-discharged wagons from coastal manufacturing plants to inland distribution terminals. Clinker imports through Port Kembla feed grinding facilities in regional New South Wales.
- Liquids:Fuel, chemicals, and molasses transport in tank wagons with specialized safety and contamination controls. Refinery supply chains from Kwinana to Pilbara mining camps operate on dedicated circuits.
Dominant by tonnage: Coal. Gaining share fastest: Grains.
Capacity:
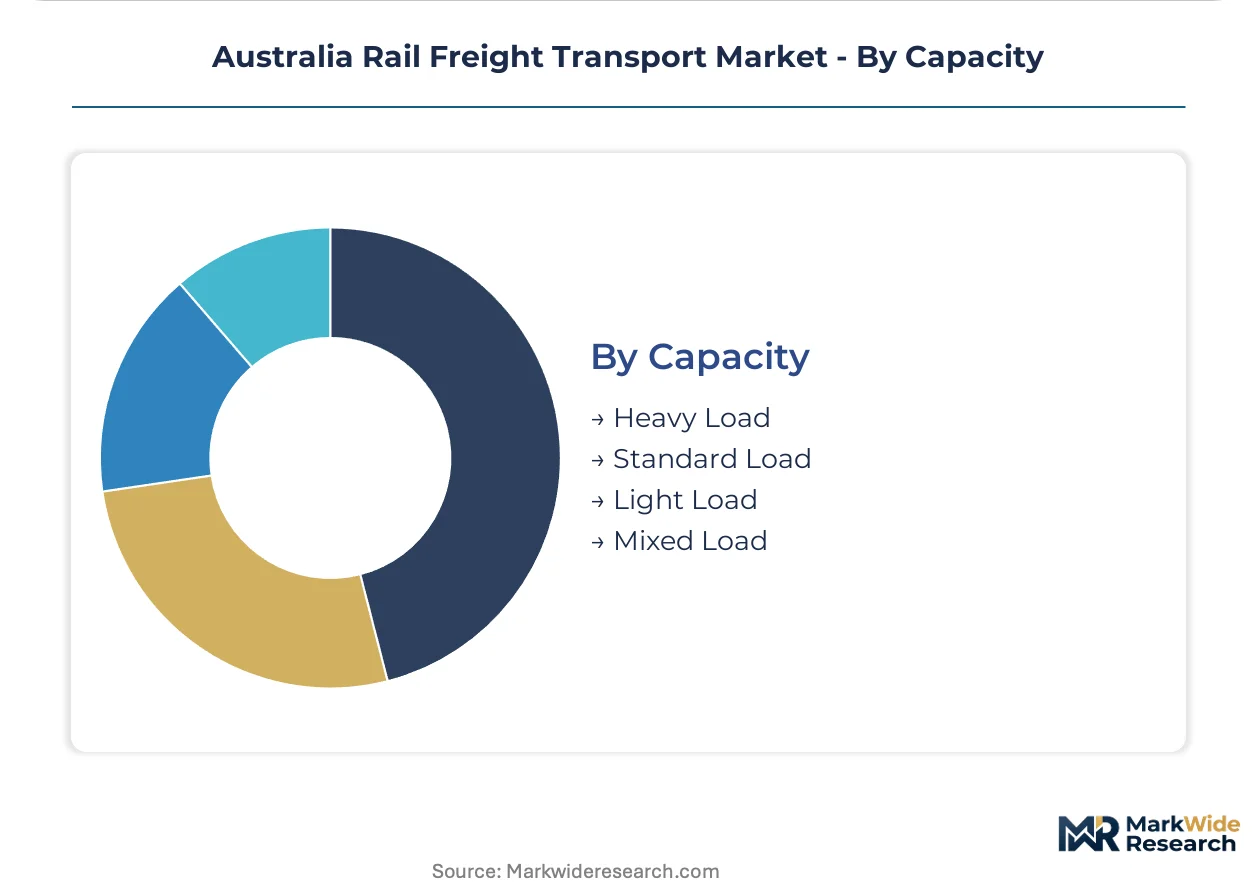
Axle load protocols and train length regulations segment operational capability across corridor infrastructure classes.
- Heavy Load:32-40 tonne axle loads on dedicated Pilbara and Hunter Valley mining corridors. Australian Rail Track Corporation approvals for 40-tonne axle loads cut cycle times for iron ore producers.
- Standard Load:23-25 tonne axle loads on interstate standard-gauge lines for containerized and general freight. Double-stacking clearances between Melbourne and Brisbane constrain maximum container weights.
- Light Load:Regional branch lines with restricted axle loads serving agricultural and industrial shippers. Western Australian grain network standardization is replacing light-load narrow-gauge infrastructure.
- Mixed Load:Combinations of container, flat-deck, and bulk wagon types on general freight services. Scheduling complexity increases as carriers optimize asset utilization across disparate cargo types.
Leading by absolute volume moved: Heavy Load. Infrastructure investment focus: Standard Load.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pilbara iron ore corridor anchors Australia's rail freight volume, with heavy-haul unit trains moving bulk commodities from mine sites to Port Hedland and Dampier terminals.
New South Wales
The Hunter Valley coal corridor generates substantial bulk freight tonnage through dedicated haulage routes to Newcastle port. Infrastructure Australia evaluates corridor investments against productivity benchmarks for this network. Sydney's intermodal terminal density supports containerized freight competition between Pacific National and SCT Logistics across the Sydney-Melbourne corridor.
Victoria
Melbourne's Dynon terminal serves as the critical integration point for Tasmanian intermodal freight and interstate container movements. The Australian Rail Track Corporation manages access pricing on standard-gauge lines connecting Victoria to South Australia. The Inland Rail project's Melbourne-Brisbane corridor is compressing modal competition economics ahead of infrastructure commissioning.
Queensland
The Goonyella system enables larger unit trains from Bowen Basin coal mines to Gladstone port terminals. State-based environmental regulators impose dust suppression protocols on bulk haulage routes through this corridor. Brisbane's intermodal facilities are repositioning for Inland Rail connectivity as the Melbourne-Brisbane link nears completion.
Western Australia
The Kwinana-Albany grain corridor has tripled containerized cereal volumes since dedicated unit-train loading facilities commissioned. The Australian Rail Track Corporation approved 40-tonne axle loads on specific Pilbara corridors to cut cycle times for iron ore producers. Esperance and Albany ports are completing narrow-to-standard gauge conversions to reduce double-handling costs for agricultural exports.
South Australia
The Eyre Peninsula's containerized agricultural exports lack direct rail connection to Perth-Adelaide corridors. Infrastructure consortium models are emerging to address this gap. Adelaide's position as a transshipment node depends on standard-gauge interoperability with western and eastern networks.
Australia Rail Freight Transport Market Competitive Environment
Premium-margin players sit above commodity-margin players across corridor access and specialized equipment dimensions in Australian rail freight. The market structure concentrates around heavy-haul bulk specialists and intermodal container operators serving distinct customer segments. Three archetypes dominate: mining-dedicated bulk haulers, interstate intermodal providers, and niche agricultural logistics specialists. Competitive moves center on long-term take-or-pay contract renegotiations ahead of Inland Rail commissioning, and fleet modernization programs targeting heavier axle load approvals.
Among established corridor operators, Aurizon anchors the heavy-haul bulk tier through east-west network dominance, while Pacific National occupies a central position in interstate intermodal density. SCT Logistics exemplifies the specialized agricultural and temperature-controlled segment, carving differentiated positioning through time-sensitive service configurations. These three represent the strategic archetype distribution across Australia's sparse rail network topology.
| Leading Market Players |
|---|
| Southern Shorthaul Railroad |
| Sadleirs Rail Freight |
| Aurizon |
| KTI |
| CTI Logistics |
| Pacific National |
| Toll Group |
| Rail First Asset Management |
| SCT Logistics |
| Others |
Value Chain & Pricing Dynamics
Diesel fuel costs, representing 25-35% of operating expenditure for long-haul operators, flow through from refined product import dependency into contract rate negotiations between carriers and bulk commodity producers across the Pilbara and Hunter Valley corridors.
Pricing Analysis
Throughput-based pricing anchors long-term take-or-pay contracts between mining majors and corridor operators, with rates indexed to tonnage moved rather than distance traveled. Price differentiation hinges on axle load certification tiers and dedicated fleet availability, with 40-tonne heavy-haul approvals commanding premium positioning over standard 23-25 tonne interstate services. Pricing pressure stems from Australian Rail Track Corporation monopoly pricing on interstate standard-gauge lines, compressing carrier margins. Agricultural exporters exhibit highest price sensitivity, negotiating vessel loading window performance guarantees, while mining majors prioritize uptime reliability over rate minimization.
Supply Chain Analysis
Locomotive and rolling stock supply rests on North American and European manufacturers, with Australian operators sourcing heavy-haul wagons from specialist producers in the United States, Germany, and China. Critical inputs include high-tensile steel for ore wagons, advanced braking systems for heavy-axle corridors, and European Train Control System signaling hardware. Single-source vulnerability concentrates in autonomous haulage technology pilots, where Rio Tinto and BHP depend on limited vendor pools for driverless system integration. Distribution runs through mine-to-port captive infrastructure for bulk commodities, while intermodal services utilize shared terminal access at Dynon, Acacia Ridge, and Moorebank facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia rail freight transport market has become a vertical-integration race, with carriers pursuing upstream control over terminal infrastructure and downstream capture of port loading operations to lock in contract renewals ahead of Inland Rail commissioning.
For Market Incumbents: Acquire intermodal terminal capacity in the Sydney-Melbourne-Brisbane triangle to preempt Pacific National's density advantage. Secure long-term track access agreements with Australian Rail Track Corporation before Inland Rail alters corridor economics. Threats from hydrogen locomotive pilots funded by Australian Renewable Energy Agency demand fleet modernization investment to defend coal and mineral volumes against zero-emission substitutes. For New Entrants and Emerging Players: Autonomous train control systems offer entry into Pilbara heavy-haul corridors where Rio Tinto and BHP seek technology partners for driverless expansion. Target Tasmanian intermodal underpenetration, where Bass Strait containerized freight remains road-dominated despite rail-sea integration potential at Melbourne's Dynon terminal. Go-to-market positioning should emphasize integrated port-terminal-rail contracts mirroring grain handler procurement consolidation in Western Australia. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized agricultural logistics operators in South Australia, where Eyre Peninsula rail connectivity gaps create acquisition targets for infrastructure consortium models. Long-term viability centers on carriers with diversified commodity exposure beyond thermal coal, given state-level decarbonization mandates. Watch Australian Renewable Energy Agency funding announcements for hydrogen locomotive pilots as inflection indicators for zero-emission bulk haulage transition timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Heavy-Haul Axle Load Expansion | Australian Rail Track Corporation approvals for 40-tonne loads cut Pilbara iron ore cycle times. |
| Inland Rail Corridor Integration | Melbourne-Brisbane link compression forces bulk commodity contract renegotiations ahead of commissioning. |
| Autonomous Haulage Deployment | Rio Tinto and BHP pilots remove drivers from high-frequency shuttle routes, reducing collision risk. |
| Hydrogen Locomotive Pilot Programs | Australian Renewable Energy Agency funding creates first-mover positioning in zero-emission bulk corridors. |
| Grain Network Standardization | Western Australian narrow-to-standard gauge conversions at Esperance and Albany reduce double-handling costs. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving corridor operations managers, locomotive fleet directors, grain handler procurement leads, and intermodal terminal operators. National Transport Commission fatigue management standards, Infrastructure Australia corridor investment evaluations, and Australian Rail Track Corporation access pricing disclosures provided regulatory and infrastructure benchmarks. Bottom-up tonnage estimates by commodity corridor triangulated against top-down market value reconstructions.
Granularity-level modeling operated at service type, end user, product type, and capacity tier dimensions across the projection horizon. Intermodal, bulk freight, containerized, and dedicated freight segments were separately forecasted with mining, agriculture, retail, and manufacturing end-use splits. CAGRs derived from corridor-specific volume growth trajectories, incorporating Inland Rail commissioning assumptions and Pilbara iron ore export demand elasticity. Heavy-haul axle load expansion timelines and hydrogen locomotive pilot scalability informed scenario boundaries.
Forecast precision tightens around the base case; tail outcomes carry wider variance under diesel price volatility spikes or accelerated state decarbonization mandates. Forecasts reflect assumptions regarding Inland Rail completion sequencing, European Train Control System rollout coordination, and mining major autonomous haulage adoption curves. Driver certification pipeline constraints and maintenance workforce specialization gaps in regional Queensland and Western Australia represent specific revision triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Autonomous Train Technology Market
Railway Transportation
Digital Axle Counter Market
Railway Transportation
Railway After-Cooler Market
Railway Transportation
Global Autonomous Trains Market
Railway Transportation
Canada Rail Freight Transport Market
Railway Transportation
Railway Couplers Market
Railway Transportation
Overhead Catenary System Market
Railway Transportation
Railcar Spill Containment Materials Market
Railway Transportation
Composites in Passenger Rail Market
Railway Transportation
Automatic Train Protection Signaling Market
Railway Transportation
Railway Li-Ion Battery Market
Railway Transportation
Railway Radiator Market
Railway Transportation
Germany Rail Freight Transport Market
Railway Transportation
Digital Railway Market
Railway Transportation
Global Train Signalling System Market
Railway Transportation
Railway Sliding Bearing Market