
 Radio Frequency Components Market | 2026-2036
Radio Frequency Components Market Size, Share, and Industry Trends Forecast 2026-2036
Radio Frequency Components Market Intelligence
The design window for experienced radio frequency integrated circuit (RFIC) engineers is collapsing under the pressure of accelerated 5G and satellite communication product cycles. Qualcomm Technologies Inc. leverages its deep system-level expertise in mobile chipsets to integrate more RF functionality. Broadcom Inc. sustains its market position through extensive R&D investment in high-performance filters and front-end modules.
Radio frequency components are electronic devices designed to operate on signals within the electromagnetic spectrum from 3 kHz to 300 GHz. These components, including filters and amplifiers, perform crucial functions like signal modulation, demodulation, and amplification in wireless communication systems. Amplifiers and switches represent core component types, with demand driven by the telecommunication application segment's infrastructure build-out. The automotive application segment, however, represents the fastest-growing area as vehicles integrate more sophisticated radar and connectivity systems.
Spectrum allocation and device certification are governed by national and regional bodies, including the US Federal Communications Commission (FCC) and China's Ministry of Industry and Information Technology (MIIT). Compliance with standards from organizations like the European Telecommunications Standards Institute (ETSI) is mandatory for market access in Europe, influencing component design and testing protocols. Component suppliers must navigate a complex and diverging set of regional frequency band and power output regulations to maintain market access.
Market Dynamics
The central force shaping the radio frequency components market is the accelerated deployment of 5G and satellite networks. This pressure shortens design windows and demands components, like those using Gallium Nitride, that offer higher power and frequency performance to enable next-generation connectivity.
Growth Catalysts
- Gallium Nitride (GaN) Adoption:The use of GaN technology in power amplifiers for 5G base stations enhances efficiency and supports higher frequency operation.
- Automotive V2X Systems:Demand from the automotive sectors in Germany and Japan for vehicle-to-everything communication systems requires advanced RF components for safety and connectivity.
- 5G Spectrum Auctions:Government-led auctions of new frequency bands for 5G services create immediate demand for filters and amplifiers tuned to these specific spectra.
Market Restraints
- Material Dependency:Reliance on specific rare earth materials for high-performance filters creates vulnerability to supply chain disruptions and price volatility concentrated in a few geographies.
- Thermal Management:Increasing component density within front-end modules creates significant heat dissipation challenges, which can limit power output and degrade system reliability.
- Divergent Regulations:Conflicting frequency band and power output regulations from bodies like the US FCC and China's MIIT complicate component design and increase validation costs.
Strategic Opportunities
- LEO Satellite Communications:The expansion of low-Earth orbit satellite constellations presents a new market for radiation-hardened and high-reliability RF components optimized for space applications.
- Industrial IoT in India:Government support for smart manufacturing in India creates an opportunity for RF components in industrial automation, asset tracking, and process control systems.
- Terahertz (THz) Frequencies:Research and development into components for the THz spectrum positions suppliers for future 6G wireless systems and advanced imaging applications.
Industry Challenges
- Talent Scarcity:A persistent shortage of experienced radio frequency integrated circuit (RFIC) design engineers constrains the ability of firms to meet compressed product development cycles.
- Complex Certification:Navigating lengthy and costly device certification processes with organizations like the European Telecommunications Standards Institute (ETSI) can delay market access.
- System Integration Complexity:Ensuring new RF components are compatible and performant within increasingly dense and complex front-end modules requires extensive system-level testing and co-design efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radio Frequency Components Market |
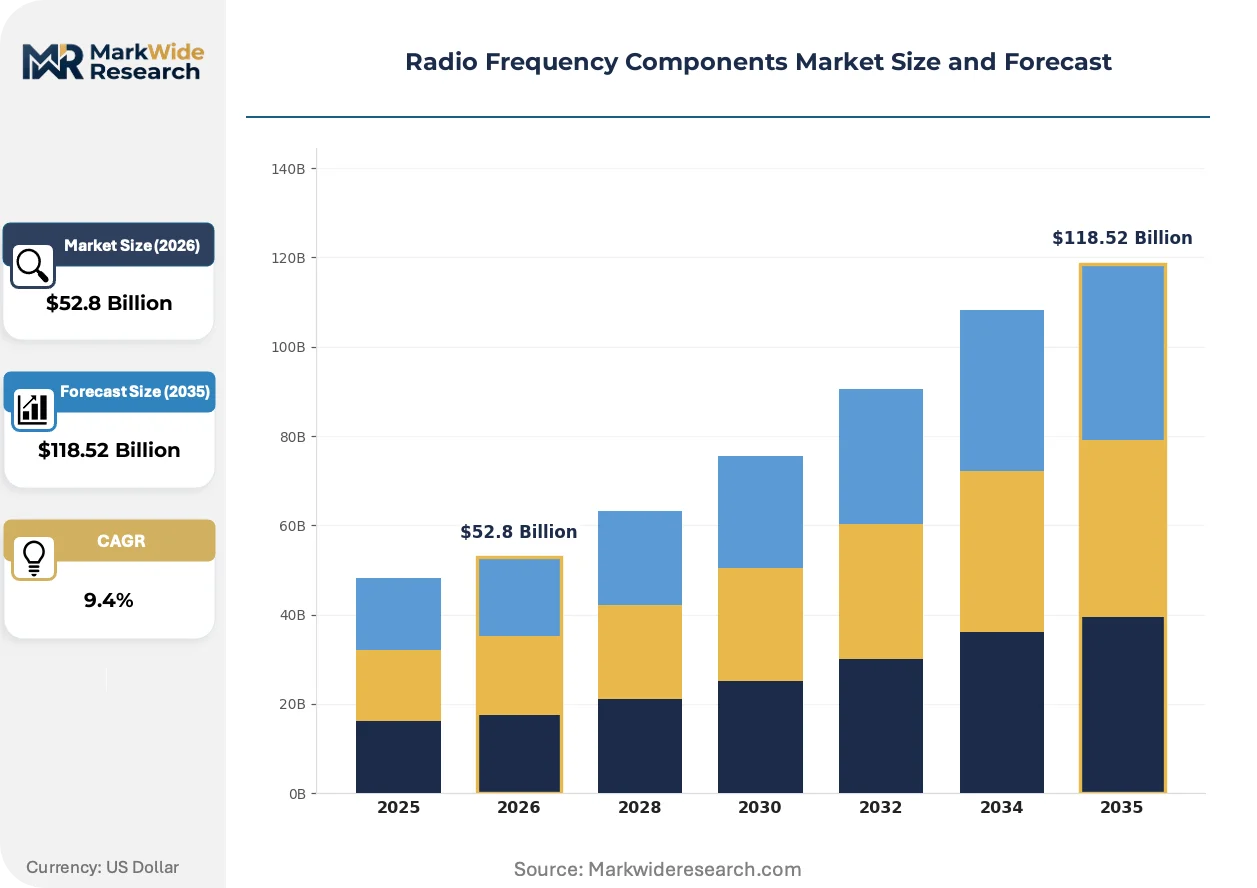
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $118.52 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Filters, Amplifiers, Oscillators, Switches Technology: Passive, Active, Analog, Digital Application: Telecommunication, Aerospace, Automotive, Medical End User: OEMs, System Integrators, Distributors, Contractors |
| Companies Covered | Broadcom Inc., Skyworks Solutions Inc., Qorvo Inc., Murata Manufacturing Co., Ltd., NXP Semiconductors N.V., Qualcomm Technologies Inc., Analog Devices Inc., Texas Instruments Inc., Renesas Electronics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radio Frequency Components Market Strategic Shifts & Innovations
Miniaturization and the push toward higher frequencies are the defining technical pressures in the radio frequency components sector. These forces compel innovation in materials, circuit integration, and thermal management to meet the performance demands of next-generation wireless systems.
Gallium Nitride on Silicon Carbide (GaN-on-SiC) technology provides superior power density and efficiency for high-frequency applications. Telecommunication equipment manufacturers are rapidly adopting it for 5G base station power amplifiers. As a result, GaN-on-SiC is displacing legacy LDMOS technology in new network infrastructure due to its performance advantages in compact designs.
Spectrum allocation policies from regulators like the US Federal Communications Commission (FCC) and China's MIIT are opening up new millimeter-wave bands. This action directly compels the design of components, such as filters and switches, optimized for these higher frequencies. Component suppliers are most affected, needing to align their product roadmaps with the specific bands being auctioned in key national markets.
Device manufacturers are shifting from buying discrete components to procuring highly integrated RF front-end modules (FEMs). This change favors suppliers that can offer complete, pre-validated system-in-package solutions over those selling individual parts. The trend is most visible in the smartphone sector, where board space is at an absolute premium and time-to-market is critical.
Radio Frequency Components Market Segmentation
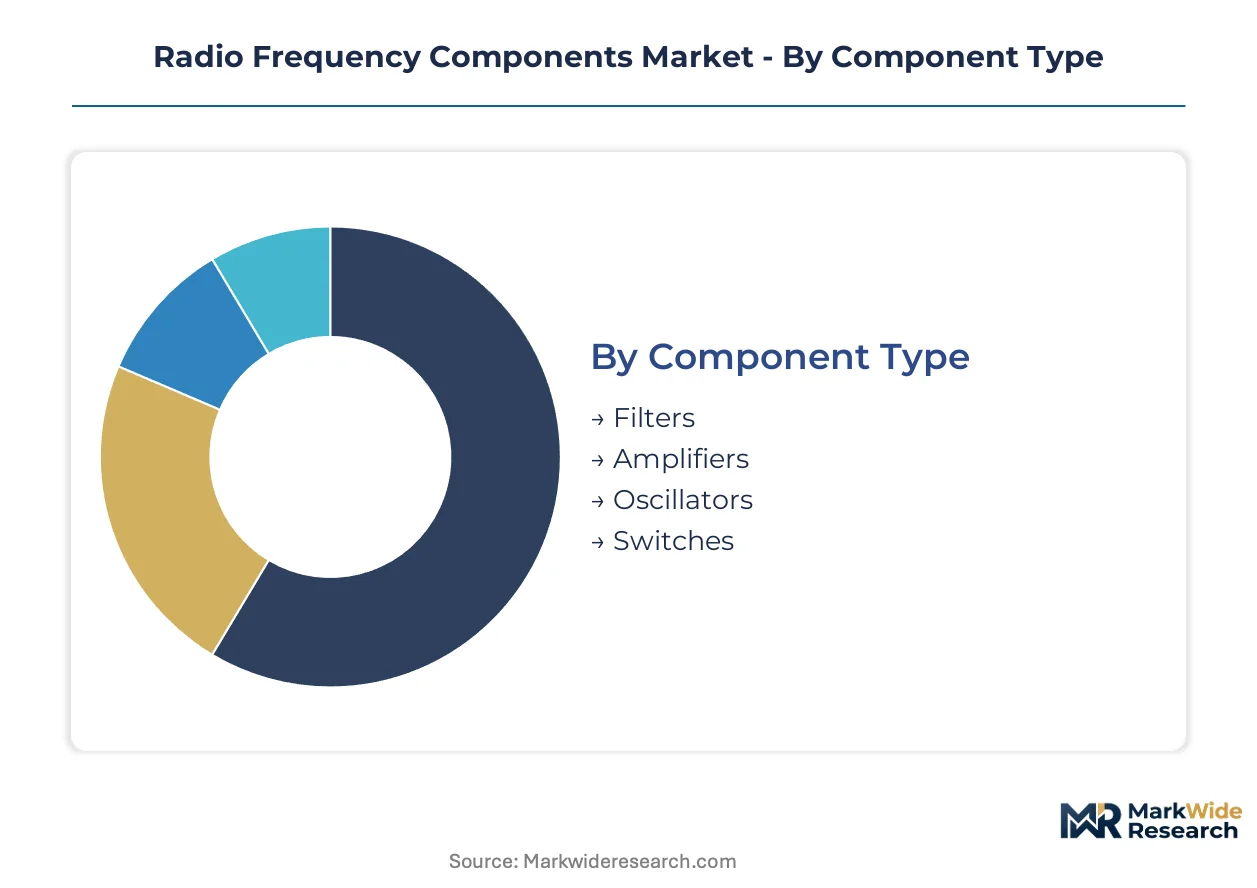
Segmentation of the Radio Frequency Components Market provides a granular understanding of how diverse component types, technologies, applications, and end-users influence market dynamics. This detailed breakdown highlights specific growth drivers and regulatory pressures impacting different market sub-sectors. Analyzing these segments reveals where innovation and investment are most concentrated.
Component Type:
Regulatory bodies like the US FCC and China's MIIT significantly differentiate their spectrum allocation policies, directly influencing the design and demand for specific RF component types. These regulations dictate permissible frequency bands and power outputs, shaping component development across regions.
- Filters:These components selectively pass or reject specific frequency bands, crucial for preventing interference and ensuring signal integrity in wireless systems. Demand is concentrating in 5G base stations and advanced radar systems, driven by the need for precise spectrum management in dense urban environments.
- Amplifiers:Amplifiers boost signal strength for transmission or reception, with power amplifiers being critical for long-range communication and high-speed data transfer. The telecommunication sector, particularly with 5G infrastructure build-out, drives significant demand for high-efficiency Gallium Nitride (GaN) power amplifiers.
- Oscillators:These components generate stable, high-frequency electrical signals, essential for timing and frequency generation in all wireless devices.
- Switches:RF switches control signal paths, directing signals between different antennas or circuit blocks in complex communication architectures.
Amplifiers handle the majority of throughput in high-power applications; filters are the fastest mover on share due to increasing spectrum complexity.
Technology:
The cost tier of manufacturing processes heavily influences the choice of RF technology, with different approaches offering varied performance and economic trade-offs for component suppliers. Material costs and fabrication complexity often dictate the commercial viability of a given technological approach.
- Passive:Passive RF components, such as resistors, capacitors, and inductors, do not require an external power source for their operation. These foundational elements are critical for impedance matching and signal conditioning in nearly all RF circuits, with demand sustained by their low cost and high reliability.
- Active:Active RF components, including transistors and diodes, require an external power source to operate and can amplify or switch signals. The integration of active components into highly compact front-end modules for smartphones and IoT devices is a major commercial trend.
- Analog:Analog RF technologies process continuous electrical signals, forming the backbone of traditional radio and wireless communication systems.
- Digital:Digital RF technologies convert analog signals into discrete digital representations, enabling advanced signal processing and software-defined radio capabilities.
Passive components remain fundamental to RF circuit design, while active technologies demonstrate the most significant potential for future performance gains and integration.
Application:
Customer type and their specific product requirements drive the differentiation across RF component applications, with each sector demanding unique performance characteristics and reliability standards. For instance, automotive clients prioritize robustness over extreme bandwidth in certain scenarios.
- Telecommunication:This segment includes infrastructure for cellular networks (2G, 3G, 4G, 5G), satellite communication, and Wi-Fi systems, demanding high-frequency, high-power, and efficient RF components. The global rollout of 5G networks, especially in China and the US, represents the primary demand driver for advanced filters and amplifiers.
- Aerospace:RF components in this sector support radar, navigation, and satellite communication systems for aircraft and spacecraft, requiring radiation-hardened and high-reliability designs. Demand for these specialized components is increasing with the expansion of LEO satellite constellations and defense modernization programs.
- Automotive:RF components enable vehicle-to-everything (V2X) communication, radar for ADAS, and in-car connectivity systems, focusing on reliability and harsh environment operation.
- Medical:This segment utilizes RF components in imaging equipment like MRI, therapeutic devices, and wireless patient monitoring systems, emphasizing precision and safety.
Telecommunication applications currently dominate the market, yet the automotive sector shows the steepest expansion trajectory due to increasing vehicle connectivity.
End User:
Supply concentration among major component manufacturers dictates the procurement patterns for various end-user segments, with large suppliers often offering integrated solutions to streamline the supply chain. This influences whether end-users purchase discrete components or complete modules.
- OEMs:Original Equipment Manufacturers integrate RF components directly into their final products, such as smartphones, base stations, and automotive radar units. These large-volume buyers often engage in long-term contracts and require custom-designed components that meet stringent performance and integration specifications.
- System Integrators:These firms combine various RF components and sub-systems from different manufacturers to deliver complete, tailored communication or radar solutions for specific projects. System integrators often serve specialized industries like defense or industrial IoT, where customized solutions are paramount.
- Distributors:Distributors act as intermediaries, supplying standard RF components to a broad range of smaller OEMs, research institutions, and repair facilities.
- Contractors:Contractors typically procure RF components for specific installation projects, such as building cellular towers or implementing smart city infrastructure.
OEMs represent the largest volume purchasers, while system integrators offer significant strategic value through their specialized integration capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Different regional market dynamics shape demand for radio frequency components, reflecting varied priorities in telecommunications and automotive sectors. Some regions prioritize 5G infrastructure build-out, while others focus on advanced vehicle connectivity systems. This divergence influences component design and market entry strategies across key national economies.
United States
The United States market experiences strong demand for high-performance RF components driven by extensive 5G network rollouts and defense modernization. US Federal Communications Commission (FCC) spectrum allocation policies directly compel the design of new filters and amplifiers for specific frequency bands. Advanced RFIC design and manufacturing are concentrated in Silicon Valley, California, supporting both commercial and aerospace applications.
China
China's market for radio frequency components is significantly propelled by its rapid 5G infrastructure deployment and expansive industrial IoT initiatives. The Ministry of Industry and Information Technology (MIIT) actively shapes component development through spectrum policies and local industry support. Major electronics manufacturing hubs in Shenzhen and the Yangtze River Delta drive high-volume production and integration of RF components.
Germany
German demand for RF components centers on advanced automotive V2X communication systems and sophisticated industrial automation applications. Compliance with European Telecommunications Standards Institute (ETSI) standards is mandatory for component design and market entry within Europe. The Stuttgart region, a hub for automotive innovation, requires robust RF components for next-generation vehicle connectivity.
Japan
Japanese automotive radar systems and high-frequency telecommunication infrastructure create specific demand for miniaturized and high-performance RF components. The Ministry of Economy, Trade and Industry (METI) supports research into new materials like Gallium Nitride for enhanced RF component capabilities. Research and development activities in the Tokyo metropolitan area focus on cutting-edge RF technologies for future wireless standards.
India
India's market for radio frequency components is expanding due to accelerated 5G network rollouts and government support for Industrial IoT. The country's national telecommunications regulator conducts spectrum auctions that create demand for filters tuned to new frequency bands. Bengaluru, a prominent technology hub, is a focal point for developing and integrating RF components into telecom and smart manufacturing solutions.
Radio Frequency Components Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the competitive landscape for radio frequency components. This tiered structure sees a few large semiconductor firms offering comprehensive RF front-end modules alongside numerous niche players specializing in specific component types. Strategic archetypes include diversified giants, focused component specialists, and emerging technology innovators. Competitive moves involve significant R&D investment in advanced materials and strategic partnerships to deliver integrated solutions.
On the premium-tier vector, Broadcom Inc. exemplifies a diversified semiconductor firm with extensive R&D capabilities across various RF component categories. Skyworks Solutions Inc. occupies a position as a specialist in highly integrated RF solutions, particularly for mobile and wireless applications. Qorvo Inc. further represents a leader in high-performance RF solutions, often anchoring the development of advanced front-end modules. These firms collectively define the competitive benchmarks for performance and integration in the radio frequency components market.
| Leading Market Players |
|---|
| Broadcom Inc. |
| Skyworks Solutions Inc. |
| Qorvo Inc. |
| Murata Manufacturing Co., Ltd. |
| NXP Semiconductors N.V. |
| Qualcomm Technologies Inc. |
| Analog Devices Inc. |
| Texas Instruments Inc. |
| Renesas Electronics Corporation |
| Others |
Cost & Logistics Intelligence
Component lead times for high-frequency filters, currently extending to 20-26 weeks, directly influence pricing power for specialized suppliers and shape OEM procurement strategies across the radio frequency components market.
Pricing Analysis
Long-term offtake agreements characterize pricing for high-volume RF components, particularly for established technologies. Performance differentiation, driven by factors like GaN-on-SiC efficiency and specific certification levels such as ETSI compliance, allows for premium pricing. Pricing softness is emerging in commoditized passive components due to increased competition. The telecommunication sector, especially large OEMs, exhibits the lowest price sensitivity for critical 5G infrastructure components, while smaller IoT device manufacturers are highly price-sensitive.
Supply Chain Analysis
Inbound logistics costs, particularly for specialized Gallium Nitride substrates and rare earth materials, impact the final price of RF components supplied to global markets. Geographic supply concentration for critical raw materials rests heavily in China and other Asian nations. Key component dependencies include high-purity silicon carbide wafers and specialized filter ceramics. A structural risk involves commodity price volatility for rare earth elements. Distribution runs through a hybrid model, combining direct sales to large OEMs with broader distributor networks for smaller integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a high-growth disruption, driven by the accelerated deployment of 5G and LEO satellite networks.
For Market Incumbents:Consolidate R&D efforts on advanced GaN-on-SiC technologies to maintain performance leadership against emerging material innovations. Strengthen system-level integration capabilities to offer complete front-end modules, mitigating competitive threats from specialized component suppliers. Invest in talent development for RFIC design engineers to address the persistent scarcity. Leverage existing relationships with major telecommunication OEMs for long-term supply contracts.
For New Entrants and Emerging Players:Lead with specialized solutions for emerging applications like Terahertz frequencies in future 6G systems. Target niche segments such as radiation-hardened components for LEO satellite communications, which offer higher margins and less direct competition. Focus on rapid prototyping and agile certification processes to gain market access quickly. Develop strong partnerships with system integrators serving industrial IoT in regions like India.
For Investors and Strategic Acquirers:Long-term, this sits as a technology-driven growth play because foundational RF component demand is expanding across diverse end-markets. Identify acquisition targets with proprietary GaN technology or unique intellectual property in millimeter-wave frequency solutions. A signal to watch is the increasing investment in advanced packaging technologies for RF front-end modules. Focus on firms demonstrating strong compliance with regional regulatory bodies.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquire specialized GaN-on-SiC foundries | Secures critical material supply and enhances control over high-performance component manufacturing. |
| Invest in Terahertz (THz) R&D | Positions the firm for future 6G wireless systems and advanced imaging applications. |
| Form partnerships for V2X system integration | Captures share in the rapidly expanding automotive connectivity segment. |
| Expand RFIC design engineering teams | Addresses talent scarcity and accelerates product development cycles for next-generation components. |
| Develop integrated RF front-end module solutions | Favors suppliers that can offer complete, pre-validated system-in-package solutions to OEMs. |
Research Approach
Cross-validation between primary interviews with RFIC design engineers and secondary analysis of FCC spectrum auction results anchors the qualitative findings. This study engaged with telecom procurement managers, automotive electronics engineers, satellite communication system architects, and component distributors. Secondary data sources included regulatory body reports from ETSI and MIIT, company financial filings, and academic research papers. Both bottom-up and top-down approaches triangulated market size and growth figures.
Sensitivity analysis across various 5G rollout scenarios informed the market projections over the forecast period. The analytical framework modeled market dynamics across component type, technology, application, end-user, and key geographic regions. Compound annual growth rates were derived from historical data and projected demand drivers for each segment. Key industry-specific forecast inputs included anticipated GaN adoption rates and vehicle-to-everything communication system integration timelines.
Forecasts assume regulatory continuity in key regimes like the US FCC and China's MIIT; material policy shifts would require re-modeling. Unforeseen global supply chain disruptions or significant breakthroughs in alternative wireless technologies represent critical risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Smart Antenna Market
RF Components
CATV RF Amplifiers Market
RF Components
High Power RF Amplifier Module Market
RF Components
Radio Frequency Front End Module Market
RF Components
GPS Low Noise Amplifier Market
RF Components
Multiband Booster Market
RF Components
UHF RFID Inlays Market
RF Components
RF-Microwave for 5G Market
RF Components
Ultra-Wideband (UWB) Market
RF Components
5G Millimeter Wave RF Transceiver Market
RF Components
Multi-Mode Receiver Market
RF Components
US RFID Tags Market
RF Components
RF Power Detector Market
RF Components
RFID Antenna Market
RF Components
RF Interconnect Market
RF Components
Stand-Alone Radio Receivers Market