
 RF-Microwave for 5G Market | 2026-2036
RF-Microwave for 5G Market Size, Share, and Industry Trends Forecast 2026-2036
RF-Microwave for 5G Market Outlook
South Korea's Pyeongtaek semiconductor corridor is reshaping supply dynamics for gallium nitride substrates used in 5G power amplifiers. Qorvo Inc. leverages captive wafer capacity to secure high-frequency die supply chains. Analog Devices Inc. anchors its position through precision beamforming IC portfolios. Infineon Technologies AG specializes in silicon-based RF switches that bridge cost-sensitive mid-band deployments.
RF-Microwave for 5G encompasses electromagnetic components operating between 600 MHz and 100 GHz, with power amplifiers typically delivering 10-100 watts using gallium nitride-on-silicon-carbide processes for base station transmit chains. These devices enable beam steering, carrier aggregation, and massive MIMO spatial multiplexing across sub-6 and millimeter-wave spectrum allocations. Amplifiers capture the dominant value pool given thermal management complexity and linearity requirements at higher order modulation schemes. GaN technology leads in macro infrastructure while CMOS RF front-ends penetrate small cell volume tiers where cost-per-channel dictates procurement decisions.
The FCC enforces Part 27 and Part 30 rules governing flexible-use spectrum, compelling manufacturers to certify equipment across multiple band classes before commercial deployment. ETSI harmonizes 5G NR radio specifications under the Radio Equipment Directive, creating a dual-gate compliance burden for vendors serving transatlantic operator procurement cycles. China's MIIT issues network access licenses that mandate domestic security testing protocols. Stakeholders must monitor spectrum auction calendars and material export controls to calibrate capacity investments against deployment velocity.
Market Dynamics
Massive MIMO deployment timelines are compressing procurement cycles for RF power amplifiers, forcing foundries to pre-position gallium nitride-on-silicon-carbide wafer capacity eighteen months ahead of base station installation schedules.
Growth Catalysts
- Millimeter-wave spectrum allocation:The FCC's Part 30 rules for flexible-use bands above 24 GHz are unlocking backhaul capacity for dense urban corridors. Equipment manufacturers must certify across multiple band classes simultaneously.
- China's coastal manufacturing clusters:Shenzhen and Suzhou electronics hubs concentrate substrate polishing, epitaxy, and test capabilities within a 200-kilometer radius. This density compresses component lead times.
- Gallium nitride thermal performance:GaN-on-SiC processes deliver power-added efficiency above 60 percent at 28 GHz. Base station operators specify these die for macro cell transmit chains to reduce cooling overhead.
Market Restraints
- Silicon carbide substrate scarcity:Six-inch SiC wafer supply concentrates among three Japanese and American producers. Foundry allocation queues extend to forty weeks during capacity ramps.
- EU electromagnetic compatibility thresholds:The Radio Equipment Directive's tightened spurious emission limits force redesigns of power amplifier bias networks. Certification retesting adds six to nine months to product launches.
- CMOS RF front-end substitution:Silicon-based small cell solutions from Infineon and others capture sub-6 GHz volume tiers where cost-per-channel dominates procurement scoring.
Strategic Opportunities
- Germany's industrial 5G private networks:Automotive and chemical plants in Bavaria and North Rhine-Westphalia are licensing localized spectrum. RF subsystem vendors can bypass operator procurement committees.
- Beamforming IC convergence:Integration of phase shifters, variable gain amplifiers, and switches into single-die solutions reduces board area for active antenna units. Analog Devices and Qorvo are repositioning portfolios around this architecture.
- South Korea's Seoul metropolitan corridor:The world's densest 5G subscriber penetration is driving replacement cycles for first-generation massive MIMO radios. Operators are specifying 64T64R configurations for stadium and transit hub overlays.
Industry Challenges
- GaN HEMT process engineering talent:Foundries in Taiwan and the United States compete for device physicists with compound semiconductor experience. Compensation inflation exceeds fifteen percent annually for senior epitaxy engineers.
- Multi-band certification complexity:Equipment must demonstrate compliance with FCC Part 27, ETSI EN 301 908, and MIIT network access license requirements concurrently. Test house capacity bottlenecks delay commercial launches.
- Active antenna integration:Antenna-filter-amplifier modules require thermal-mechanical co-design that legacy base station architectures never addressed. First-generation products experienced field failure rates above acceptable thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RF-Microwave for 5G Market |
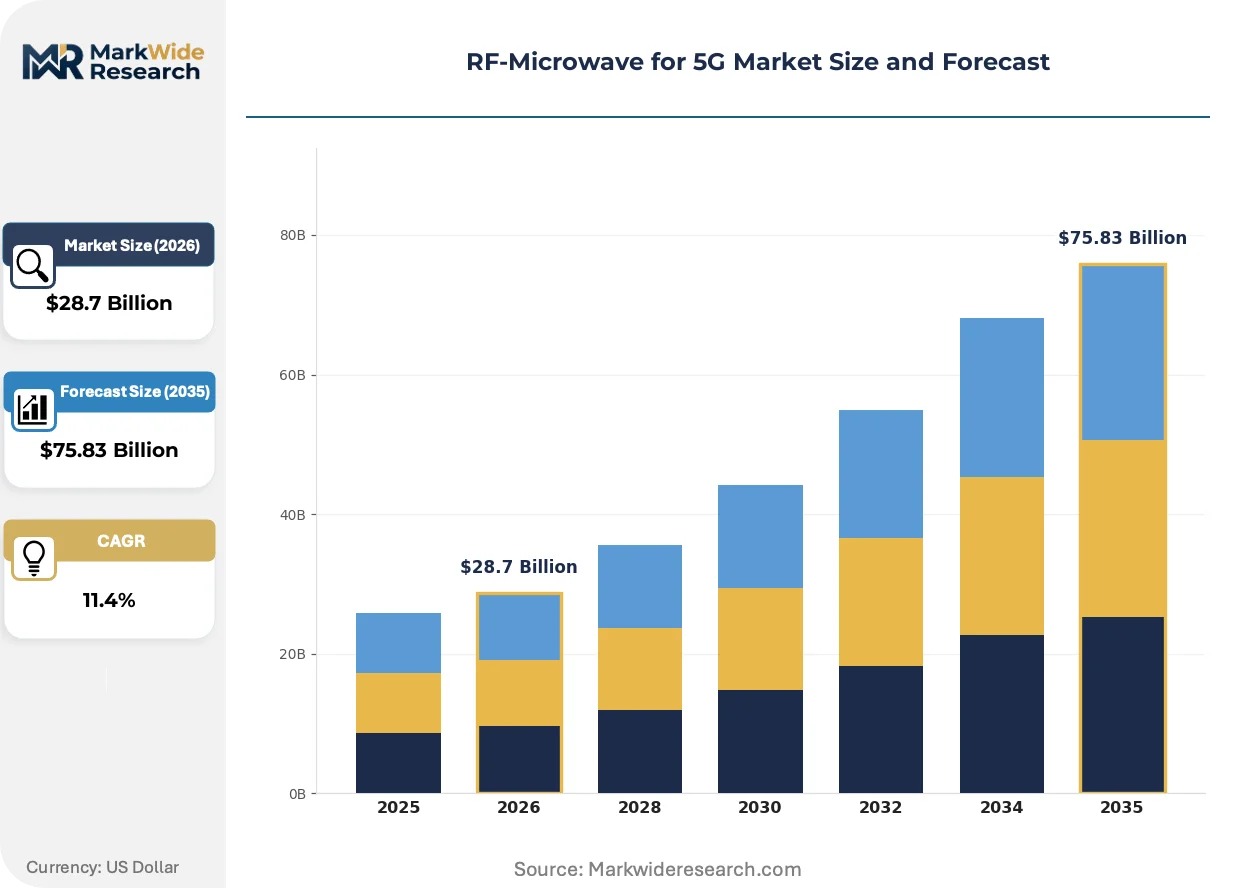
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $75.83 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amplifiers, Filters, Oscillators, Transmitters Technology: GaN, GaAs, CMOS, Hybrid Application: Base Stations, Antennas, Repeaters, Small Cells End User: Telecom Operators, Enterprises, Government, Military |
| Companies Covered | Qorvo Inc., Analog Devices Inc., Broadcom Inc., MACOM Technology Solutions Holdings Inc., Infineon Technologies AG, Qualcomm Incorporated, NXP Semiconductors N.V., Mitsubishi Electric Corporation, Skyworks Solutions Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RF-Microwave for 5G Market Strategic Shifts
Open RAN interfaces are fragmenting the RF supply chain, enabling specialized amplifier vendors to sell directly to operators rather than through integrated equipment manufacturers. This architectural shift is redistributing value capture across the ecosystem.
Digital pre-distortion algorithms are virtualizing linearization functions that previously required dedicated analog hardware in power amplifier chains. Base station original equipment manufacturers are adopting software-defined correction to reduce bill-of-materials cost. This compression is accelerating replacement of discrete analog predistortion circuits with FPGA-based implementations.
ETSI's harmonization of 5G NR radio specifications under the Radio Equipment Directive is creating a dual-gate compliance burden for vendors serving transatlantic procurement cycles. Manufacturers must maintain parallel certification tracks for FCC Part 27 and Part 30 rules alongside CE marking requirements. Small cell suppliers targeting both American and European operators are absorbing disproportionate regulatory overhead relative to revenue scale.
Direct RF sampling transceivers are displacing traditional heterodyne architectures in millimeter-wave baseband units. Defense contractors and commercial infrastructure vendors are converging on this technology for multi-gigahertz instantaneous bandwidth. South Korea's operator procurement specifications now explicitly favor direct-sampling implementations for 28 GHz small cell deployments.
RF-Microwave for 5G Market Segmentation
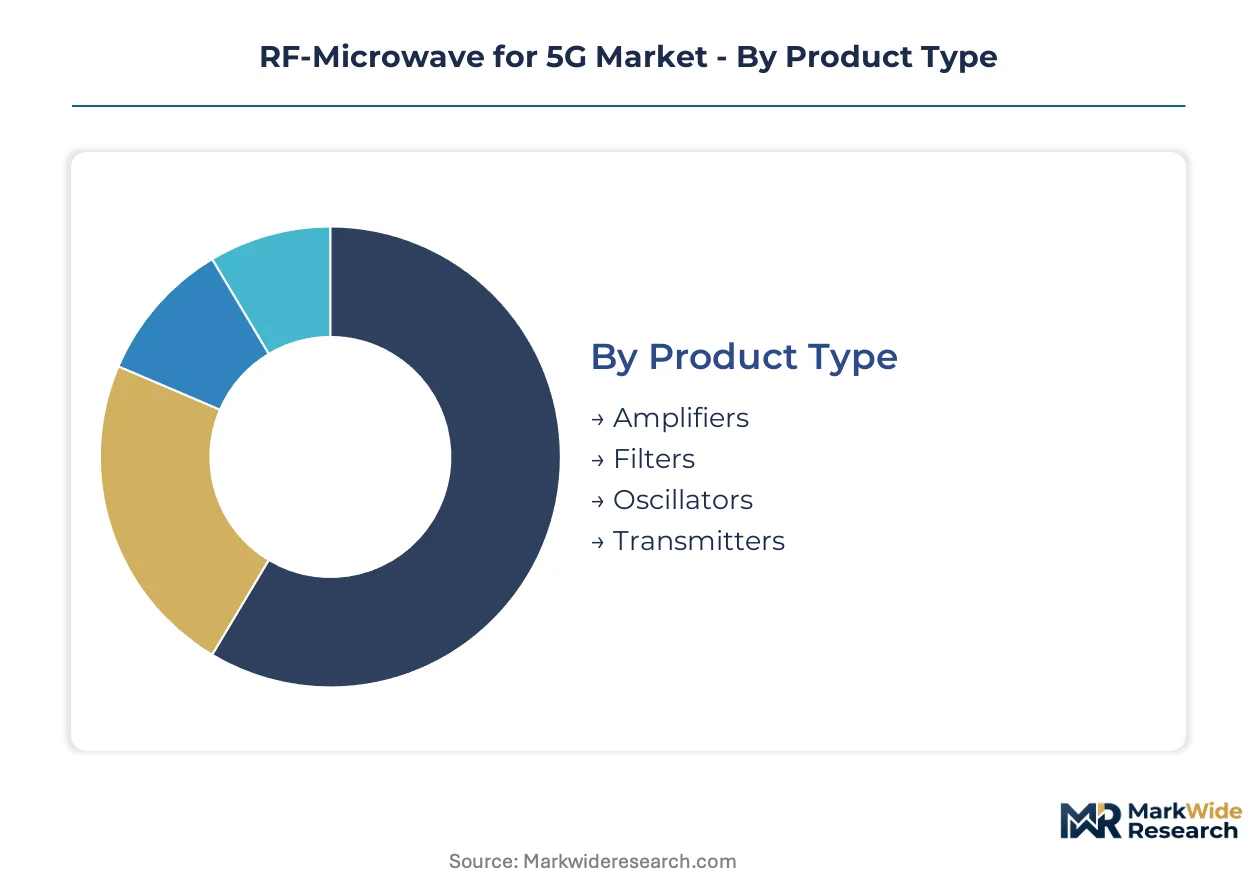
RF-Microwave component procurement diverges sharply across deployment scales, with macro infrastructure demanding GaN thermal performance while small cell volumes prioritize CMOS cost curves. Segmentation reveals how technology choices cascade through certification requirements, supply chain configurations, and after-sales service intensity.
Product Type:
After-sales service intensity varies dramatically by component complexity, with amplifiers requiring field calibration protocols that filters and oscillators rarely demand.
- Amplifiers:GaN-on-SiC power amplifiers deliver 10-100 watts with power-added efficiency above 60 percent at 28 GHz. Demand concentrates in China's coastal manufacturing clusters where substrate polishing and epitaxy capabilities compress lead times for macro base station transmit chains. Thermal management complexity drives recurring service contracts.
- Filters:Cavity and ceramic filters isolate carrier bands in massive MIMO arrays, with temperature drift specifications tightening under EU Radio Equipment Directive spurious emission limits. South Korea's Seoul metropolitan corridor specifies premium-grade units for stadium overlays where interference rejection is critical. Replacement cycles align with base station hardware refreshes.
- Oscillators:Temperature-compensated crystal oscillators provide reference clock stability for beamforming synchronization.
- Transmitters:Integrated transmit chains combine amplification, filtering, and upconversion for active antenna units.
Amplifiers hold the largest share; momentum sits with transmitters as active antenna integration accelerates.
Technology:
Cost tier stratification separates premium compound semiconductor processes from silicon-based volume solutions.
- GaN:Gallium nitride-on-silicon-carbide processes dominate macro infrastructure where linearity at higher-order modulation schemes justifies die cost premiums. Germany's industrial 5G private networks in Bavaria specify GaN for automotive plant coverage requiring high availability. Foundry allocation queues from Japanese and American substrate producers extend to forty weeks.
- GaAs:Gallium arsenide maintains position in mid-frequency small cells where efficiency requirements moderate.
- CMOS:Silicon RF front-ends from Infineon and others capture sub-6 GHz small cell tiers where cost-per-channel dictates procurement scoring.
- Hybrid:Multi-process modules combine GaN power stages with CMOS control logic for cost-optimized active antenna units.
GaN commands premium positioning; CMOS is expanding most quickly through small cell volume penetration.
Application:
Geographic deployment patterns concentrate demand in specific infrastructure archetypes.
- Base Stations:Macro cell installations drive GaN amplifier procurement with 64T64R configurations replacing first-generation massive MIMO radios in South Korea's densest corridors. FCC Part 27 and Part 30 certification requirements add six to nine months to product launches for transatlantic vendors.
- Antennas:Active antenna units integrate radiating elements with RF conditioning electronics, requiring thermal-mechanical co-design that legacy architectures never addressed.
- Repeaters:Signal regeneration equipment extends coverage in tunnel and stadium environments.
- Small Cells:Millimeter-wave and sub-6 GHz distributed units favor CMOS and GaAs for cost-sensitive dense urban deployments.
Base stations anchor revenue concentration; small cells are climbing the fastest as urban densification accelerates.
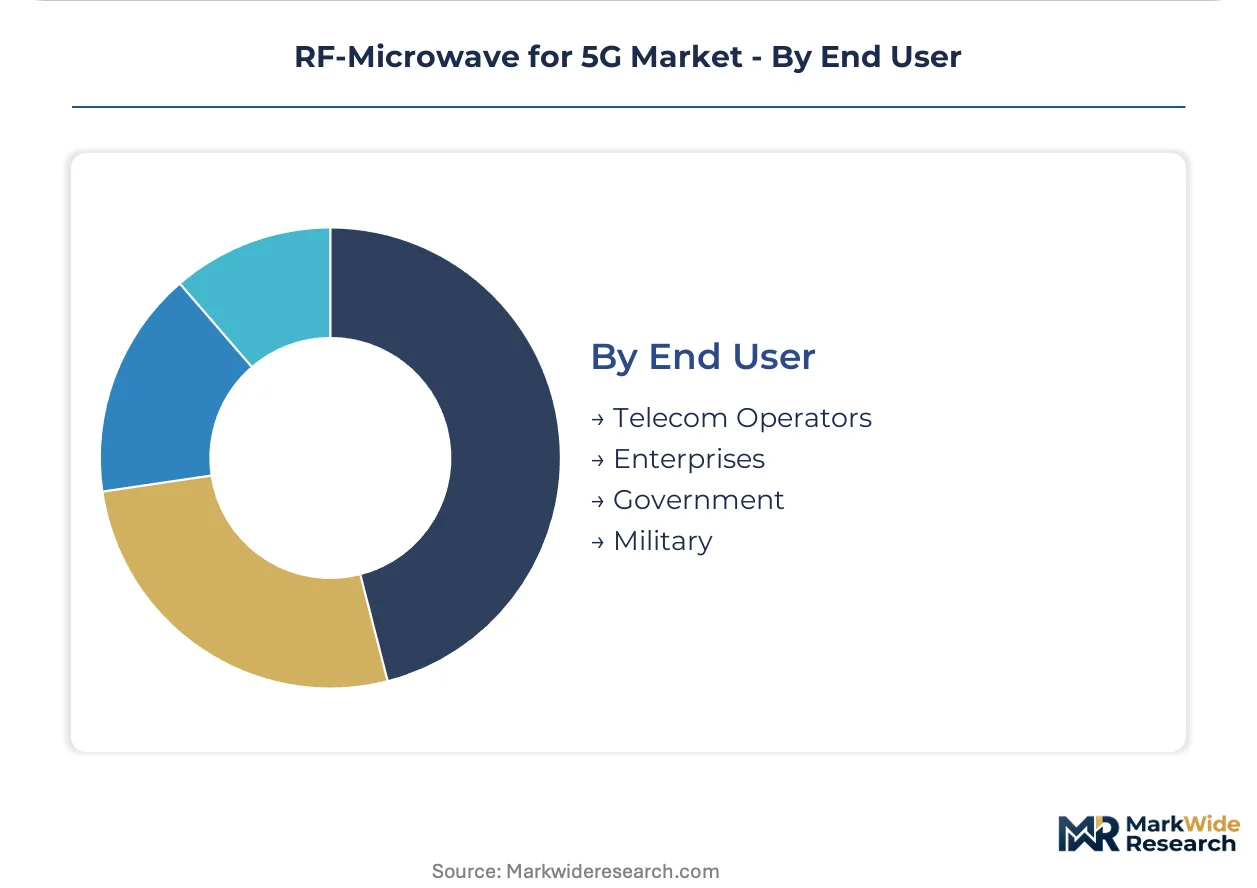
End User:
Customer type determines procurement authority structures and specification authority.
- Telecom Operators:Mobile network operators in South Korea and China drive volume procurement with centralized technical specifications and eighteen-month pre-positioning requirements for GaN wafer capacity. Open RAN interfaces are fragmenting traditional integrated equipment manufacturer relationships.
- Enterprises:Automotive and chemical plants in Germany's North Rhine-Westphalia region license localized spectrum for private 5G networks, bypassing operator procurement committees.
- Government:Public sector deployments emphasize security certification and domestic supply chain requirements.
- Military:Defense applications leverage direct RF sampling transceiver technology converging with commercial millimeter-wave infrastructure.
Telecom operators retain dominant procurement volume; enterprises are gaining share fastest through private network licensing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wafer fabrication capacity for gallium nitride-on-silicon-carbide concentrates among Japanese and American substrate producers, creating allocation bottlenecks that cascade through deployment timelines in operator procurement cycles.
United States
The FCC's Part 27 and Part 30 rules for flexible-use spectrum above 24 GHz are compressing certification timelines for millimeter-wave equipment. Domestic operators in dense urban corridors specify direct RF sampling transceivers for backhaul capacity. Silicon carbide substrate scarcity from American producers extends foundry allocation queues to forty weeks during capacity ramps.
China
MIIT network access licenses mandate domestic security testing protocols for base station equipment deployed across coastal manufacturing clusters. Shenzhen and Suzhou electronics hubs concentrate substrate polishing, epitaxy, and test capabilities within a 200-kilometer radius. This density compresses component lead times for massive MIMO array production.
Germany
Automotive and chemical plants in Bavaria and North Rhine-Westphalia are licensing localized spectrum under the EU Radio Equipment Directive for industrial 5G private networks. ETSI harmonization of 5G NR specifications creates compliance overlap with FCC rules for transatlantic vendors. RF subsystem suppliers bypass operator procurement committees to serve enterprise direct sourcing.
South Korea
The Seoul metropolitan corridor drives replacement cycles for first-generation massive MIMO radios with 64T64R configurations for stadium overlays. MFDS and national spectrum authorities coordinate procurement specifications with the world's densest 5G subscriber penetration. Pyeongtaek semiconductor corridor suppliers are reshaping gallium nitride substrate dynamics for power amplifier die.
Japan
METI industrial policy supports compound semiconductor foundry investment for GaN HEMT process engineering. Domestic producers of six-inch SiC wafers anchor supply-side concentration for macro infrastructure transmit chains. Device physicists with epitaxy experience command compensation inflation exceeding fifteen percent annually.
RF-Microwave for 5G Market Competitive Environment
Integrated RF front-end suppliers and specialized compound semiconductor foundries split the market along process-technology lines. The vendor base organizes around three strategic archetypes: captive wafer capacity owners, precision beamforming IC specialists, and silicon-based cost-optimized solution providers. Competitive moves center on foundry allocation queue positioning and active antenna unit integration partnerships.
Within the compound semiconductor tier, Qorvo Inc. and MACOM Technology Solutions Holdings Inc. exemplify captive supply strategies for high-frequency die. Analog Devices Inc. occupies a position among precision beamforming IC portfolios, while Infineon Technologies AG anchors silicon-based RF switch specialization for cost-sensitive mid-band deployments. These three represent divergent technology-commitment postures that structure procurement segmentation across operator and enterprise end users.
| Leading Market Players |
|---|
| Qorvo Inc. |
| Analog Devices Inc. |
| Broadcom Inc. |
| MACOM Technology Solutions Holdings Inc. |
| Infineon Technologies AG |
| Qualcomm Incorporated |
| NXP Semiconductors N.V. |
| Mitsubishi Electric Corporation |
| Skyworks Solutions Inc. |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Pyeongtaek-Tokyo maritime corridor carries gallium nitride substrate wafers whose freight cost volatility feeds directly into power amplifier pricing tiers, amplifying the margin compression that substrate scarcity already imposes on macro infrastructure deployments while forcing cost-sensitive small cell tiers toward CMOS alternatives.
Pricing Analysis
FCC Part 27 and Part 30 rules dictate the pricing tier structure across millimeter-wave and sub-6 GHz equipment categories, separating premium GaN-on-SiC macro base station amplifiers from standard CMOS small cell front-ends and economy-grade GaAs mid-band solutions. Price differentiation rests on certification grade—CE marking for EU Radio Equipment Directive compliance commands 15-20 point procurement scoring premiums—and thermal performance specifications that determine after-sales service bundling. Cost compression in CMOS tiers is intensifying because Infineon and Qualcomm are penetrating volume small cell markets with silicon-based RF switches. Telecom operators in South Korea and China exhibit the lowest price sensitivity due to centralized technical specifications and eighteen-month wafer pre-positioning requirements, while German industrial private network enterprises demonstrate acute cost-per-channel scrutiny.
Supply Chain Analysis
TSMC, GlobalFoundries, and Tower Semiconductor hold dominant foundry capacity for compound semiconductor processes, anchoring wafer fabrication concentration in Taiwan, the United States, and Israel. Raw material dependencies draw from Japanese and American six-inch silicon carbide substrate producers, South Korean epitaxy equipment suppliers, and Chinese rare earth processing for magnetic components in test fixtures. Single-source vulnerability concentrates in SiC wafer supply—three producers control allocation queues that cascade through deployment timelines. Distribution runs through integrated equipment manufacturers like Ericsson and Nokia for operator channels, while direct RF subsystem sales to German automotive and chemical enterprises are accelerating through private network licensing frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open RAN interface standardization is fragmenting buyer power across telecom operators, enterprises, and government procurement committees, creating procurement authority dispersion that favors specialized component vendors over integrated equipment manufacturers.
For Market Incumbents: Insulate GaN HEMT process engineering talent pools through captive epitaxy investments in Taiwan and the United States, where compensation inflation for senior device physicists exceeds fifteen percent annually. Deepen backward integration into six-inch SiC substrate supply through long-term offtake agreements with Japanese producers, neutralizing the forty-week allocation queue risk that threatens macro base station delivery schedules. Prioritize certification investment for dual-gate FCC Part 27/Part 30 and ETSI EN 301 908 compliance to maintain transatlantic operator procurement eligibility against emerging CMOS substitution threats from Infineon. For New Entrants and Emerging Players: Germany's Bavarian and North Rhine-Westphalian industrial 5G private networks represent the most penetrable entry point, bypassing operator procurement committees through direct enterprise RF subsystem sales to automotive and chemical plants. South Korea's Seoul metropolitan corridor replacement cycles for first-generation massive MIMO radios offer secondary white-space opportunity, with 64T64R stadium overlay specifications favoring beamforming IC convergence. Pursue platform integration partnerships with active antenna unit manufacturers to reduce board area through single-die phase shifter, variable gain amplifier, and switch combinations. For Investors and Strategic Acquirers: Precision beamforming IC specialists with direct RF sampling transceiver portfolios anchor the highest long-term viability profile across the 5G infrastructure refresh window, given South Korean operator procurement specifications now explicitly favoring these implementations for 28 GHz deployments. Monitor spectrum auction calendars and material export control announcements as early inflection indicators—MIIT network access license delays or Japanese SiC wafer export restrictions would trigger immediate capacity reallocation signals. Quarterly review of foundry allocation queue depth and Open RAN interface adoption rates is advised to detect vendor power redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| GaN-on-SiC Foundry Capacity Expansion | Secures wafer supply for macro base station transmit chains against Japanese and American substrate scarcity. |
| Dual-Gate Certification Investment | Enables concurrent FCC Part 27/Part 30 and ETSI EN 301 908 compliance for transatlantic operator procurement. |
| Beamforming IC Convergence | Integrates phase shifters, variable gain amplifiers, and switches to reduce active antenna unit board area. |
| Industrial Private Network Direct Sales | Bypasses operator procurement committees through localized spectrum licensing in Germany's automotive corridor. |
| Digital Pre-Distortion Algorithm Development | Virtualizes linearization functions to displace discrete analog predistortion circuits with FPGA-based implementations. |
Study Parameters
The analysis maps RF power amplifiers, filters, oscillators, and transmitters across GaN, GaAs, CMOS, and hybrid technology tiers, each validated through base station procurement managers, RF subsystem engineering directors, compound semiconductor foundry operations heads, and telecom operator network planning executives. Primary fieldwork combined structured interviews with secondary validation from FCC equipment authorization databases, ETSI harmonized standards filings, MIIT network access license records, and SEC 10-K supply chain disclosures from Qorvo, Analog Devices, and Infineon. Bottom-up component demand modeling triangulated against top-down operator capex projections across the analysis window.
Assumptions held spectrum allocation timelines and GaN HEMT process yields fixed while varying small cell densification rates, Open RAN adoption velocity, and SiC substrate supply elasticity. The projection framework segmented by product type, technology process, application scale, and end-user procurement authority, with CAGRs derived from deployment velocity curves tied to massive MIMO array installation schedules and millimeter-wave backhaul link commissioning. Industry-specific inputs included gallium nitride thermal performance specifications, electromagnetic compatibility threshold tightening under EU Radio Equipment Directive amendments, and active antenna unit thermal-mechanical co-design failure rate benchmarks.
Practitioners should monitor FCC spectrum auction calendars, Japanese METI industrial policy announcements on compound semiconductor foundry investment, and Chinese MIIT network access license processing timelines for early signals of capacity-demand imbalance. Forecasts reflect assumptions about sustained operator capex commitment and substrate supply expansion that material export controls or procurement authorization delays could revise. Quarterly review of foundry allocation queue depth, Open RAN interface standardization progress, and electromagnetic compatibility certification retesting duration is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
RF Components Market
RF Components
Small Signal Mosfets Market
RF Components
Dielectric Resonator Market
RF Components
RFID Antenna Market
RF Components
Smartphone RF Power Amplifier Market
RF Components
Radiofrequency Identification (RFID) Market
RF Components
Global Inductors Market
RF Components
Radio Frequency Front End Module Market
RF Components
Radio Frequency Front End Market
RF Components
Digital Radio Frequency Market
RF Components
Harness-Level EMI and Shielding Component Systems Market
RF Components
RF Tester Market
RF Components
RF Filters Market
RF Components
Digital Radio Frequency Memory Market
RF Components
Tunable Inductors Market
RF Components
Latin America RFID Tags Market