
 RF Power Detector Market | 2026-2036
RF Power Detector Market Size, Share, and Industry Trends Forecast 2026-2036
RF Power Detector Market Analytics
Silicon-germanium BiCMOS integration is reshaping RF power detector architectures, collapsing die size while extending frequency coverage past 40 GHz. Analog Devices leverages its precision analog heritage to dominate high-end instrumentation segments. Texas Instruments anchors its position through monolithic integration with envelope tracking power amplifiers. Skyworks Solutions specializes in handset-optimized detectors with sub-microsecond response times for 5G millimeter-wave modules.
RF power detectors measure incident electromagnetic power through diode-based rectification, logarithmic amplification, or temperature-compensated thermal sensing, with critical specifications including dynamic range, frequency response flatness, and temperature stability across −40°C to +85°C industrial grades. The device type landscape shows resistive and inductive architectures capturing premium margin pools in test and measurement, while capacitive variants lead volume in consumer electronics where cost minimization dominates. Hybrid technology segments are expanding fastest as designers combine analog front-end sensitivity with digital calibration to meet 3GPP carrier aggregation requirements.
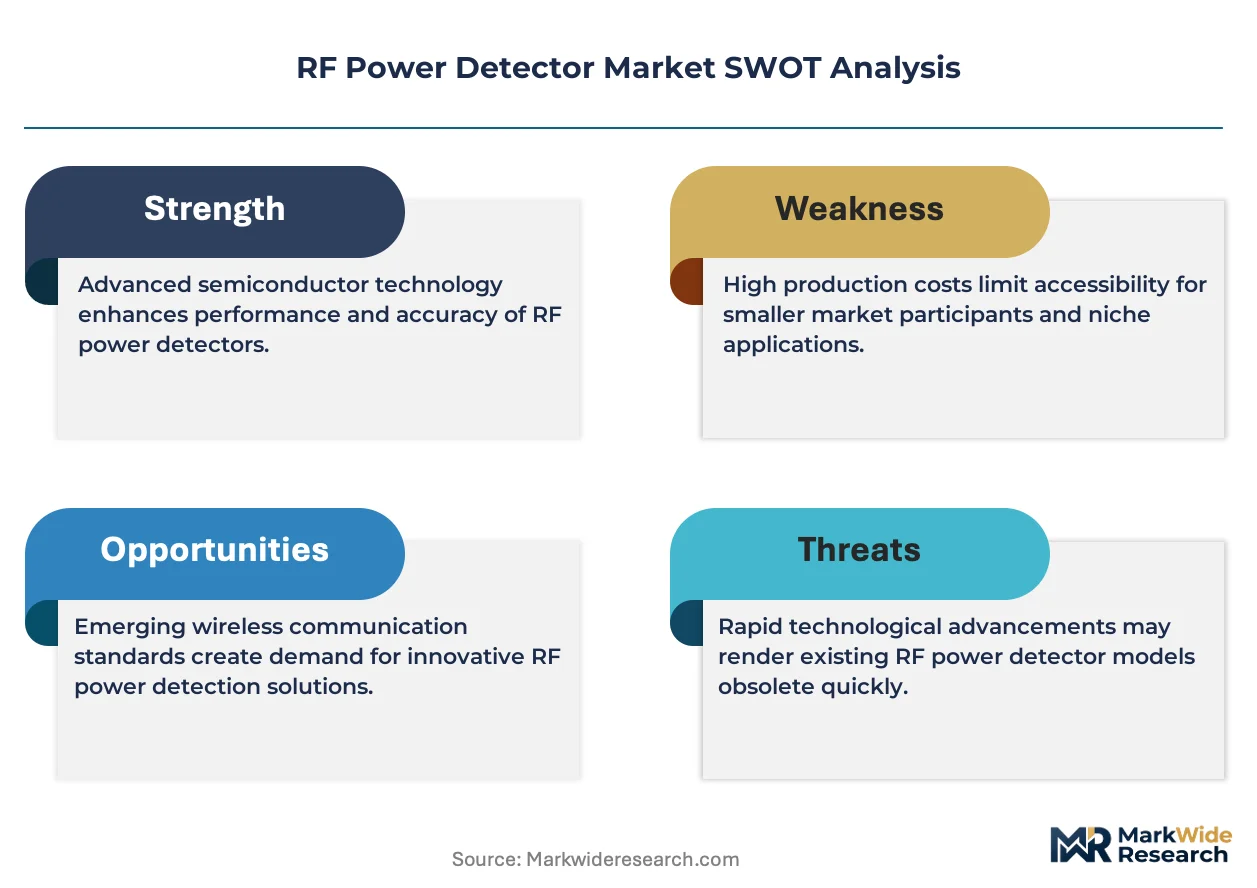
The FCC enforces strict Effective Isotropic Radiated Power limits under Part 15 and Part 27 rules, compelling detector accuracy improvements for transmit chain compliance. ETSI harmonized standards across EU member states mandate measurement uncertainty below 1 dB for base station certification, tightening vendor qualification thresholds. China's MIIT issues type approval requirements linking detector calibration to network equipment入网许可. Stakeholders must monitor how Open RAN disaggregation shifts detector procurement from integrated radio vendors toward specialized component suppliers.
Market Dynamics
Silicon-germanium BiCMOS integration is collapsing die footprints while extending frequency coverage past 40 GHz, forcing incumbent suppliers to rearchitect product portfolios around monolithic integration with envelope tracking power amplifiers.
Growth Catalysts
- 5G millimeter-wave base station deployment:Telecommunications infrastructure vendors in China are scaling domestic baseband chipset production, creating captive demand for sub-microsecond response time detectors.
- FCC Part 15 and Part 27 EIRP enforcement:Transmit power accuracy mandates in the United States are tightening certification thresholds for radio equipment manufacturers.
- Carrier aggregation requirements:3GPP specifications are driving hybrid technology adoption combining analog front-end sensitivity with digital calibration capabilities.
Market Restraints
- Wafer supply concentration:Advanced silicon-germanium substrate production clusters in specialized foundries, creating single-source vulnerability for fabless detector designers.
- Thermal sensing substitution:Temperature-compensated thermal architectures threaten diode-based rectification in industrial-grade applications requiring −40°C to +85°C stability.
- ETSI certification friction:EU harmonized standards mandating below 1 dB measurement uncertainty extend vendor qualification timelines for base station certification.
Strategic Opportunities
- Open RAN disaggregation:Radio access network virtualization is shifting detector procurement from integrated radio vendors toward specialized component suppliers in distributed architectures.
- Test and measurement premiumization:Resistive and inductive architectures command margin pools in instrumentation segments where dynamic range and frequency response flatness justify price premiums.
- India PLI scheme leverage:Production-linked incentives for telecom equipment manufacturing are attracting detector module assembly investments serving South Asian infrastructure buildouts.
Industry Challenges
- Millimeter-wave calibration expertise scarcity:Specialized RF characterization talent pools concentrate in legacy semiconductor hubs, constraining new entrant scaling.
- Multi-standard integration complexity:Simultaneous support for sub-6 GHz and millimeter-wave bands requires architecture compromises that degrade performance in specific operating regimes.
- MIIT type approval timelines:China's network equipment入网许可linking detector calibration to certification creates unpredictable market entry schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RF Power Detector Market |
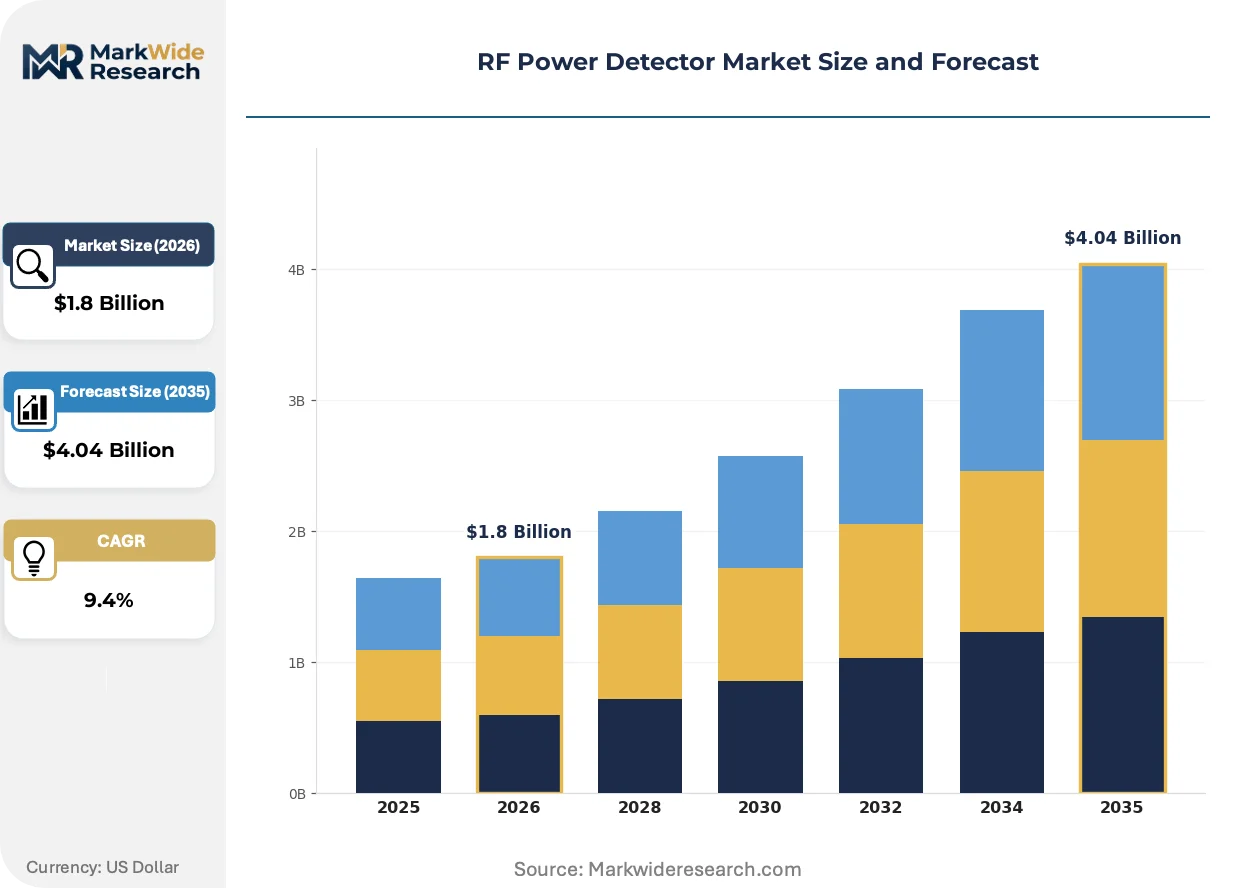
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Dynamo, Capacitive, Inductive, Resistive End User: Aerospace, Telecommunications, Automotive, Consumer Electronics Application: Signal Processing, Frequency Monitoring, Power Measurement, Network Testing Technology: Analog, Digital, Hybrid, RF Circuit |
| Companies Covered | Analog Devices, Texas Instruments, Broadcom, Skyworks Solutions, Infineon Technologies, NXP Semiconductors, STMicroelectronics, Qorvo, Renesas Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RF Power Detector Market Evolving Landscape
RF power detector architectures are converging around silicon-germanium integration while regulatory fragmentation across major economies complicates product platform strategies. Three forces dominate current innovation patterns.
Silicon-germanium BiCMOS is collapsing the traditional separation between detector front-ends and baseband processing. Base station original equipment manufacturers in China are adopting monolithic integration at unprecedented pace. This compression eliminates discrete component assembly steps while reducing bill-of-materials complexity for envelope tracking subsystems.
REACH substance restrictions and RoHS recast directives in the European Union are forcing material substitutions in detector packaging and thermal interface materials. Industrial equipment vendors serving EU markets must reformulate solder alloys and substrate coatings. Test and measurement suppliers with existing green chemistry portfolios capture accelerated qualification windows.
Radio access network procurement is fragmenting as Open RAN specifications enable mixing and matching of radio unit subcomponents. Traditional integrated radio vendors face disintermediation pressure from specialized detector suppliers offering digital calibration interfaces. This unbundling is most visible in South Korean 5G deployments where operators mandate multi-vendor interoperability testing.
RF Power Detector Market Segmentation
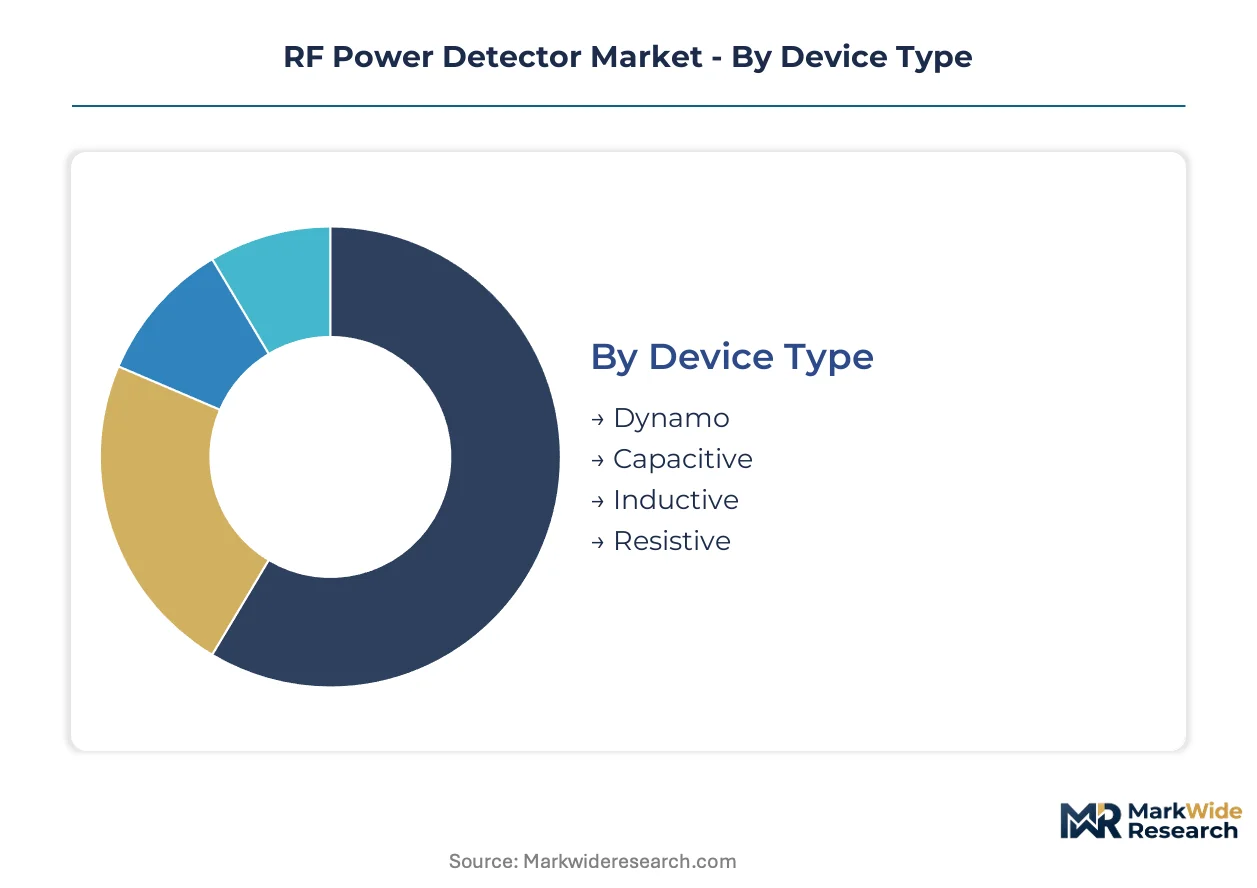
RF power detector segmentation reflects competing pressures between precision instrumentation requirements and mass-market cost minimization. Architecture choices determine frequency coverage, response latency, and integration complexity across deployment scenarios.
Device Type:
Mature resistive and inductive variants anchor high-margin instrumentation segments, while emerging capacitive architectures scale into consumer electronics volumes.
- Resistive:Thermal conversion elements deliver exceptional linearity across broadband frequency sweeps. Test equipment manufacturers in Germany specify these for calibration-grade measurement chains where absolute accuracy trumps unit cost.
- Inductive:Current-sensing coils coupled with precision amplifiers achieve superior dynamic range in power amplifier feedback loops. Telecommunications infrastructure vendors in South Korea deploy these for envelope tracking in 5G base stations.
- Capacitive:Charge-accumulation architectures dominate smartphone power management circuits.
- Dynamo:Rotational electromagnetic generators serve specialized industrial monitoring applications.
Resistive architectures handle the majority of instrumentation throughput; capacitive variants are expanding most quickly into handset volumes.
End User:
Application requirements diverge sharply between military-aerospace certification rigor and consumer electronics cost floors.
- Telecommunications:Base station OEMs demand sub-microsecond response times for real-time power control in carrier aggregation schemes. China's domestic baseband chipset production is scaling captive detector demand for Open RAN disaggregation.
- Consumer Electronics:Handset manufacturers prioritize die size reduction and envelope tracking integration. Skyworks Solutions and Qorvo compete on monolithic BiCMOS implementations for millimeter-wave modules.
- Aerospace:Radiation-hardened specifications and extended temperature grades dominate procurement criteria.
- Automotive:Radar module integration drives adoption for adaptive cruise control and collision avoidance systems.
Telecommunications commands the dominant revenue pool; automotive applications are climbing the fastest on share as radar deployment accelerates.
Application:
Functional specialization separates laboratory-grade precision from embedded monitoring tasks.
- Power Measurement:Absolute power reference applications demand traceable calibration chains. NIST-traceable standards in the United States anchor metrology laboratory procurement specifications.
- Network Testing:Field technicians require ruggedized handheld instruments with wide dynamic range. India's PLI scheme for telecom equipment is attracting module assembly investments serving South Asian infrastructure buildouts.
- Signal Processing:Real-time amplitude modulation extraction supports digital predistortion loops.
- Frequency Monitoring:Spectrum surveillance applications prioritize instantaneous bandwidth over absolute accuracy.
Power measurement retains the deepest margin structure; network testing is gaining share fastest on infrastructure deployment velocity.
Technology:
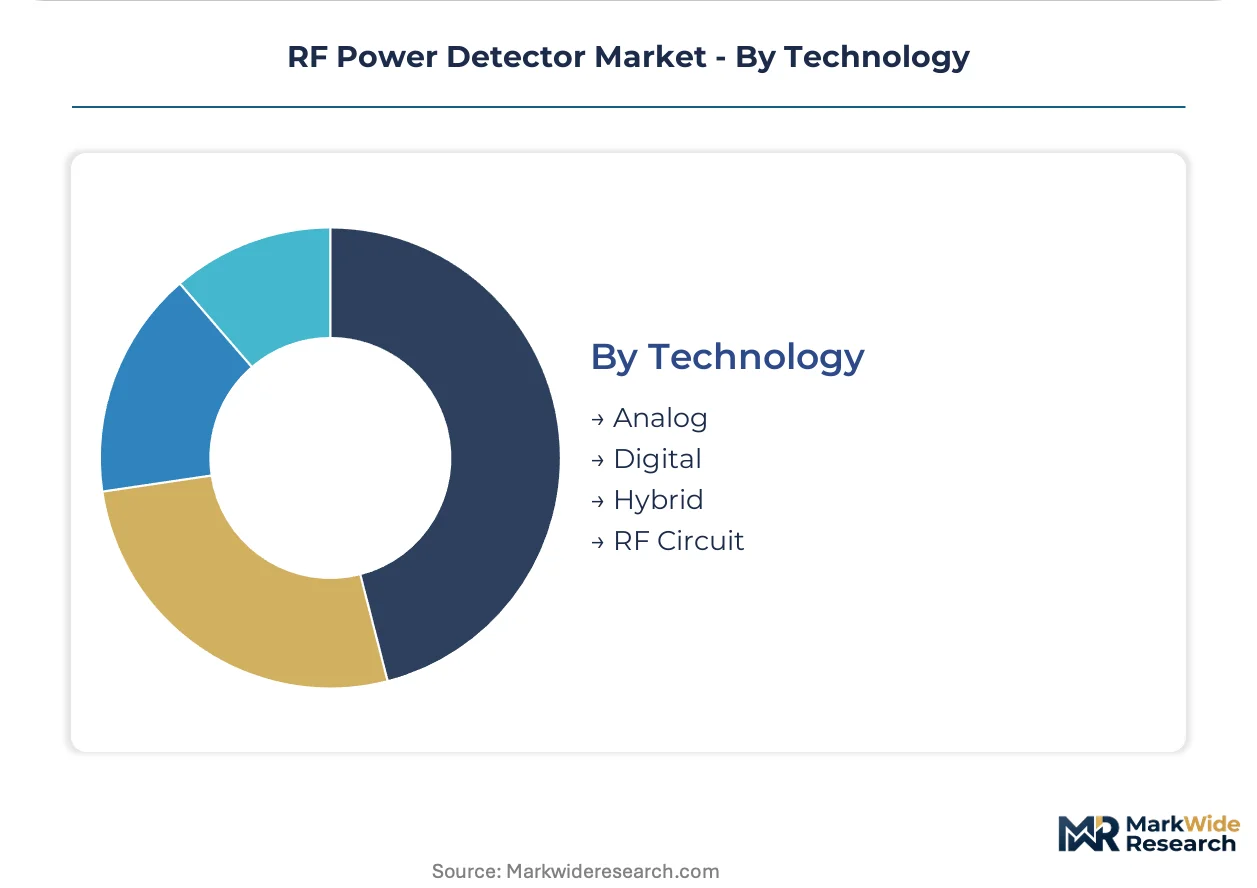
Integration philosophy separates discrete analog heritage from digitally calibrated futures.
- Hybrid:Analog front-end sensitivity combined with digital calibration meets 3GPP carrier aggregation requirements. Analog Devices leverages precision analog heritage to dominate this architecture in high-end instrumentation.
- Digital:Direct sampling architectures eliminate analog nonlinearities through DSP compensation. Texas Instruments anchors positioning through monolithic integration with envelope tracking power amplifiers.
- Analog:Diode-based rectification and logarithmic amplification persist in cost-sensitive applications.
- RF Circuit:Distributed element designs extend frequency coverage past 40 GHz for millimeter-wave systems.
Hybrid configurations capture the steepest expansion trajectory as base station OEMs adopt monolithic integration; pure analog maintains residual volume in legacy equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports RF power detector modules to telecommunications infrastructure vendors across South Korea and India, establishing the dominant trade corridor in Asia-Pacific. Germany ships precision instrumentation-grade detectors to calibration laboratories in the United States and Japan. The United Kingdom serves as a distribution hub for European Open RAN deployments.
United States
Telecommunications infrastructure vendors and aerospace contractors drive detector procurement for 5G base stations and radar systems. The FCC enforces Part 15 and Part 27 EIRP limits that mandate transmit power accuracy improvements. Boston and Austin host RF characterization facilities where millimeter-wave calibration expertise concentrates for defense and commercial applications.
China
Domestic baseband chipset production scales rapidly, creating captive demand for sub-microsecond response time detectors in base station manufacturing. The MIIT issues type approval requirements linking detector calibration to network equipment入网许可. Shenzhen and Shanghai anchor silicon-germanium BiCMOS foundry clusters serving integrated radio unit production.
Germany
Test equipment manufacturers specify resistive architectures for calibration-grade measurement chains requiring absolute accuracy. REACH substance restrictions and RoHS recast directives force material substitutions in detector packaging. Munich and Stuttgart host precision instrumentation vendors competing on NIST-traceable standards alignment.
South Korea
5G millimeter-wave deployments mandate multi-vendor interoperability testing, fragmenting procurement toward specialized detector suppliers. The national telecommunications regulator enforces certification standards aligned with ETSI harmonized requirements. Seoul anchors envelope tracking power amplifier integration facilities for handset-optimized detectors.
India
Production-linked incentives for telecom equipment manufacturing attract detector module assembly investments serving South Asian infrastructure buildouts. TRAI spectrum allocation policies accelerate 5G base station deployment timelines. Bengaluru and Hyderabad host network testing equipment vendors requiring ruggedized handheld instruments with wide dynamic range.
RF Power Detector Market Competitive Landscape
On the supply side, the industry is consolidating around monolithic integration capabilities while fragmenting across specialized application tiers. Precision analog heritage anchors high-end instrumentation positions. Volume handset optimization drives separate competitive dynamics. Strategic archetypes include silicon-germanium BiCMOS integrators, envelope tracking specialists, and test equipment precision vendors. Capacity expansion in advanced substrate foundries and strategic partnerships for Open RAN interoperability certification represent dominant competitive moves.
Within the precision instrumentation tier, Analog Devices exemplifies heritage analog capability leveraged toward hybrid technology architectures. Texas Instruments occupies a position integrating envelope tracking power amplifier subsystems. Skyworks Solutions represents handset-optimized specialization for millimeter-wave response latency requirements. These three anchors illustrate how competitive positioning stratifies across telecommunications infrastructure, consumer electronics, and test equipment end markets without overlapping core competencies.
| Leading Market Players |
|---|
| Analog Devices |
| Texas Instruments |
| Broadcom |
| Skyworks Solutions |
| Infineon Technologies |
| NXP Semiconductors |
| STMicroelectronics |
| Qorvo |
| Renesas Electronics |
| Others |
Value Network & Pricing Analysis
Shenzhen's silicon-germanium BiCMOS foundry cluster anchors global detector substrate capacity, translating wafer allocation tightness into asymmetric pricing power for integrated radio unit manufacturers over fabless designers.
Pricing Analysis
Legacy diode-based rectification architectures trade at substantial discounts against silicon-germanium BiCMOS generations, while next-generation digital calibration hybrids command instrumentation-grade premiums. Three-tier pricing structure across premium, standard, and economy levels separates NIST-traceable test equipment from industrial-grade base station components and consumer handset volumes. Cost compression in capacitive consumer variants is intensifying because die size reduction targets outpace yield learning curves. Handset manufacturers exhibit acute price sensitivity; metrology laboratories demonstrate inelastic demand for absolute accuracy.
Supply Chain Analysis
High-purity germanium feedstock and advanced silicon-on-insulator wafers flow predominantly from China, Germany, and the United States. Detector fabrication draws from specialized BiCMOS foundries, precision analog assembly houses, and calibration-grade test fixture suppliers. Single-source vulnerability concentrates in silicon-germanium substrate production where legacy semiconductor hubs monopolize technical talent pools. Distribution runs through integrated radio vendors for traditional base station procurement and specialized component distributors for Open RAN disaggregated architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open RAN interoperability mandates are transforming RF power detector procurement from bundled radio unit sales toward modular component platforms, reconfiguring value capture across the ecosystem.
For Market Incumbents: Insulate instrumentation-grade margins through NIST-traceable certification investments and captive silicon-germanium foundry capacity in legacy semiconductor hubs. Thermal sensing substitution threats and millimeter-wave calibration expertise scarcity demand defensive consolidation of precision analog talent pools in Boston and Austin clusters. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-supported telecom equipment assembly corridor, where production-linked incentives reduce effective entry costs for detector module manufacturing. Network testing equipment vendors in Bengaluru and Hyderabad represent the most penetrable buyer segment, accessible through ruggedized handheld instrument co-development partnerships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hybrid architecture specialists combining analog front-end sensitivity with digital calibration capabilities. Long-term viability hinges on Open RAN certification breadth and envelope tracking power amplifier integration depth. Monitor South Korean multi-vendor interoperability testing mandates as the definitive inflection signal for procurement fragmentation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon-Germanium Foundry Partnership | Secures captive substrate supply for envelope tracking power amplifier integration. |
| Open RAN Interoperability Certification | Unlocks procurement access to South Korean and Indian disaggregated base station deployments. |
| Precision Analog Talent Acquisition | Addresses millimeter-wave calibration expertise scarcity constraining new entrant scaling. |
| Hybrid Technology Platform Launch | Captures 3GPP carrier aggregation requirements through analog-digital convergence. |
| India PLI Scheme Manufacturing Footprint | Leverages production-linked incentives for South Asian infrastructure buildout access. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across telecommunications infrastructure vendors, base station OEM procurement teams, precision instrumentation manufacturers, and semiconductor foundry engineering directors. Primary interview findings were cross-validated against FCC Part 15 and Part 27 rulemakings, ETSI harmonized standards documentation, MIIT type approval databases, and SEC semiconductor segment disclosures. Bottom-up unit economics triangulated with top-down market sizing across device type, end user, application, and technology dimensions.
Calibration against historical silicon-germanium BiCMOS adoption curves and envelope tracking power amplifier penetration rates anchored growth trajectory assumptions across the analysis window. Segmentation modeling incorporated resistive, inductive, capacitive, and hybrid architectures; telecommunications, consumer electronics, aerospace, and automotive end users; power measurement, network testing, signal processing, and frequency monitoring applications; plus analog, digital, hybrid, and RF circuit technology philosophies. CAGRs were derived from regression analysis of base station deployment forecasts and handset millimeter-wave module ramp schedules.
Stress conditions across wafer supply concentration, REACH substance restriction timelines, and Open RAN procurement fragmentation velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding 5G millimeter-wave base station deployment cadence and domestic baseband chipset production scaling in China. Cross-checking against FCC equipment authorization databases and ETSI base station certification registries is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
China Small Signal Transistor Market
RF Components
Frequency Synthesizer Market
RF Components
Global Ceramic Dielectric Filters Market
RF Components
RF and Microwave Diodes Market
RF Components
Asia-Pacific Small Signal Transistor Market
RF Components
UHF RFID Inlays Market
RF Components
Global RF Power Semiconductor Market
RF Components
Dielectric Resonator Market
RF Components
Latin America RFID Tags Market
RF Components
High Power RF Amplifier Module Market
RF Components
Wireless Module Market
RF Components
Flat Panel Antenna Market
RF Components
LTCC Power Dividers Market
RF Components
Global Inductors Market
RF Components
CATV RF Amplifiers Market
RF Components
Multi-Mode Receiver Market