
 GPS Low Noise Amplifier Market | 2026-2036
GPS Low Noise Amplifier Market Size, Share, and Industry Trends Forecast 2026-2036
GPS Low Noise Amplifier Market Foresight
The RF component distribution channel is rewriting procurement patterns for precision navigation hardware. Infineon Technologies AG leverages its captive fab network to sustain supply continuity for automotive-grade die. Skyworks Solutions Inc. dominates the discrete amplifier segment through die-level packaging expertise. Qorvo Inc. anchors its position in defense-qualified GaAs devices with ITAR-controlled manufacturing lines.
A GPS low noise amplifier is a front-end RF component that amplifies weak satellite signals with minimal added noise, typically achieving noise figures below 1.5 dB across the L1/L2/L5 bands to preserve signal integrity for downstream digital processing. The device employs heterojunction bipolar transistors or pseudomorphic high-electron-mobility transistors in low-noise topologies, with impedance-matching networks optimized for 50-ohm system integration. Integrated product types lead volume shipments in consumer wearables where board space constraints dominate design tradeoffs, while GaAs technology sustains premium positioning in aerospace applications where radiation tolerance and linearity justify higher die costs. CMOS processes are displacing legacy BiCMOS in telecommunications infrastructure as foundry geometries shrink noise figures at consumer price points.
The FCC governs GPS receiver spurious emissions under Part 15 rules, while ETSI EN 303 413 mandates receiver sensitivity benchmarks for European automotive homologation. The EU AI Act's positioning requirements for autonomous systems are tightening traceability standards for GNSS signal chains. China's MIIT GB standards enforce domestic encryption protocols for BeiDou-integrated modules, fragmenting certification pathways for multiconstellation designs. Stakeholders must monitor how dual-use export controls on GaAs substrate technology reshape competitive access to defense-adjacent amplifier tiers.
Market Dynamics
Automotive OEMs are forcing a recalibration of GPS low noise amplifier specifications as autonomous positioning systems demand sub-meter accuracy under ETSI's tightening phase-noise mandates. The shift from discrete GaAs die to integrated CMOS modules is compressing traditional RF component margins while expanding addressable volume.
Growth Catalysts
- ETSI EN 303 413:The European automotive homologation standard mandates receiver sensitivity benchmarks that elevate demand for sub-1.5 dB noise figure amplifiers in ADAS-equipped vehicles.
- BeiDou-integrated modules:China's MIIT GB standards enforce domestic encryption protocols, creating captive demand for multiconstellation-qualified components within Shenzhen's electronics corridor.
- GaN-on-SiC substrates:Defense contractors are migrating to gallium nitride processes for radiation-hardened amplifiers in satellite payloads, opening premium pricing tiers beyond commercial silicon.
Market Restraints
- 6-inch GaAs wafer supply:ITAR-controlled substrate fabrication concentrates in US and Japanese foundries, creating bottleneck risk for defense-qualified amplifier tiers.
- Dual-use export controls:US Bureau of Industry and Security restrictions on pHEMT technology fragment competitive access to aerospace and military procurement channels.
- CMOS noise floor limitations:Silicon processes struggle to match InGaP HBT linearity at L5 band frequencies, constraining substitution in precision agriculture applications.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for telecom equipment manufacturing are drawing module integrators to establish RF packaging facilities near Bengaluru's design ecosystem.
- EU AI Act positioning requirements:Autonomous system traceability mandates are creating certified supply chain premiums for automotive-qualified GNSS signal chains.
- SiGe BiCMOS convergence:Silicon-germanium processes are bridging the performance gap between CMOS cost structures and GaAs linearity, enabling new consumer wearable form factors.
Industry Challenges
- Multiconstellation calibration:Engineers must validate simultaneous L1/L2/L5/E1/E5a reception across GPS, Galileo, and BeiDou constellations, extending qualification timelines.
- Flip-chip packaging expertise:Die-level assembly for automotive-grade modules requires specialized thermal management skills concentrated in Taiwan and South Korea.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GPS Low Noise Amplifier Market |
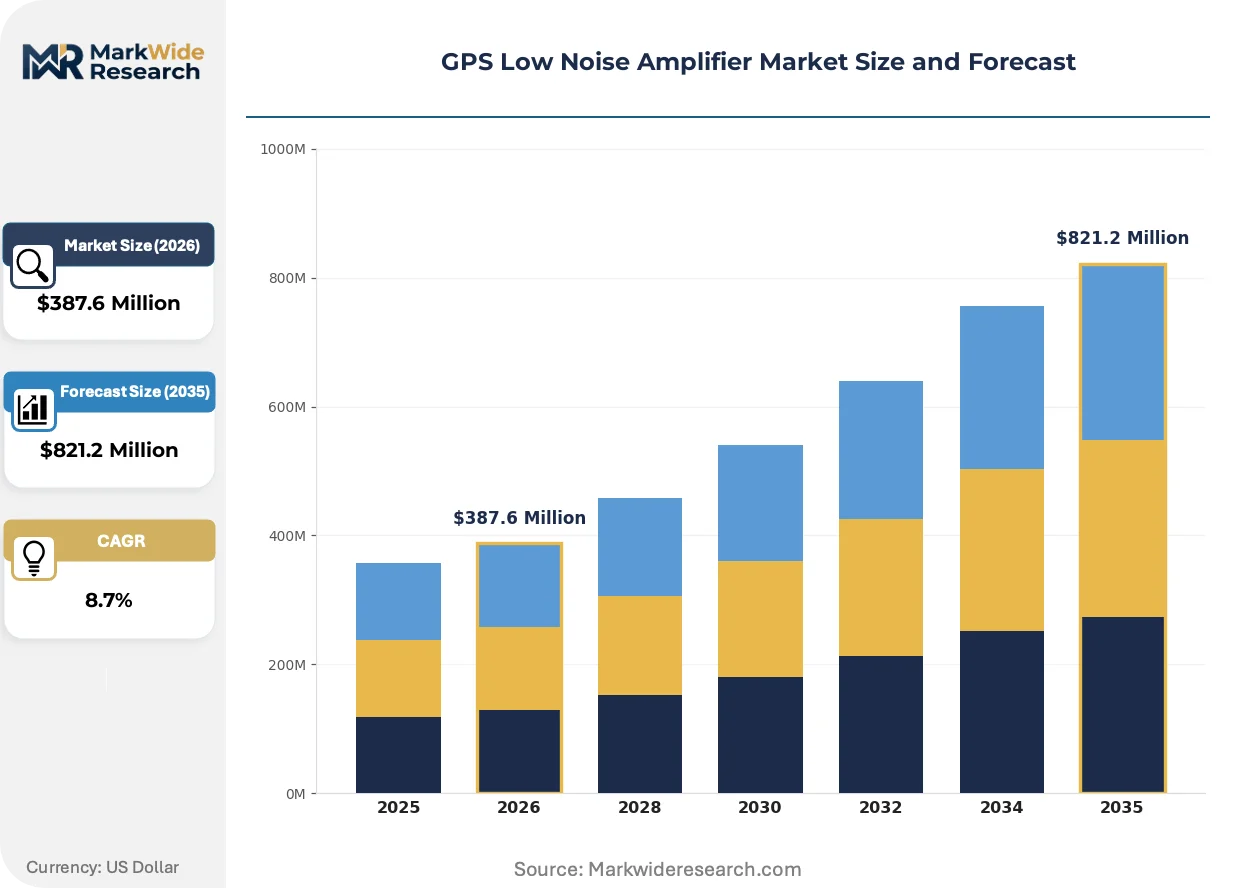
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated, Discrete, RF, Low Power Technology: CMOS, GaAs, BiCMOS, SiGe End User: Aerospace, Automotive, Telecommunications, Consumer Electronics Application: GPS Systems, Communication Systems, Radar Systems, Satellite Navigation |
| Companies Covered | Infineon Technologies AG, Texas Instruments Incorporated, Analog Devices Inc., Mini-Circuits, Panasonic Corporation, Skyworks Solutions Inc., NXP Semiconductors N.V., Broadcom Inc., Qorvo Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GPS Low Noise Amplifier Market Shifts & Advancements
RF front-end integration is collapsing traditional component boundaries as module makers bundle filtering, amplification, and switching functions into single-package solutions. This consolidation is rewriting procurement specifications and supplier qualification protocols across precision navigation hardware.
Silicon-germanium BiCMOS is digitizing receiver architectures by embedding analog-to-digital conversion closer to the antenna interface. Automotive tier-1 suppliers are adopting SiGe LNA-integrated modules for consolidated ECU designs. This integration is digitizing downstream signal processing chains and compressing discrete component bill-of-materials.
Europe's CSRD sustainability disclosure rules are mandating supply chain carbon accounting for electronic components sold into EU markets. Amplifier vendors must now document foundry energy consumption and substrate sourcing for automotive OEM compliance. German KBA type-approval processes are incorporating these disclosures into homologation checklists.
Direct procurement from foundry-integrated module houses is displacing traditional RF distributor relationships among high-volume wearable manufacturers. Shenzhen-based design houses now negotiate wafer starts directly with TSMC and GlobalFoundries for consumer-grade die. This channel compression is most visible in fitness tracker and smartwatch supply chains where board space constraints dominate design tradeoffs.
GPS Low Noise Amplifier Market Segmentation
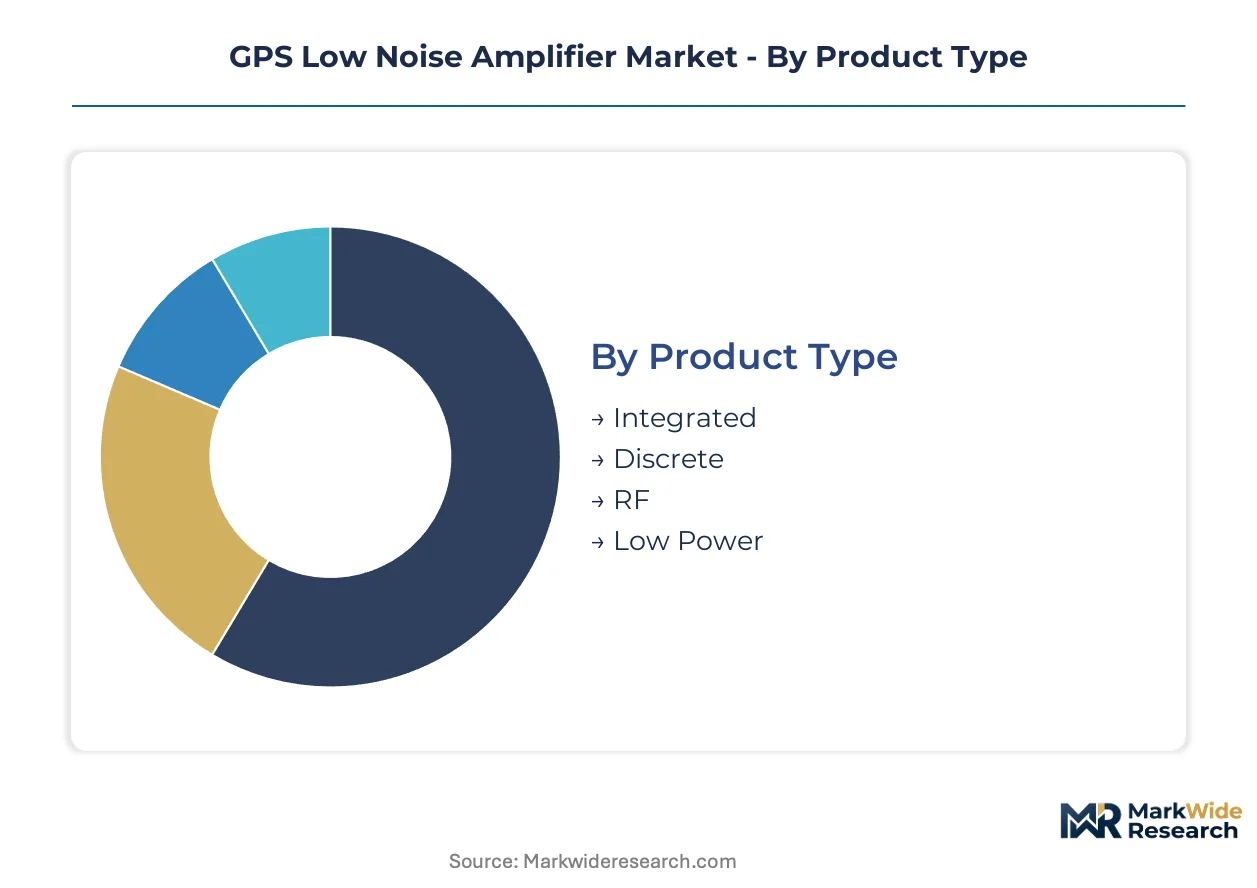
Segmentation in GPS low noise amplifiers reveals how performance requirements fracture across defense, automotive, and consumer tiers. Design cycles compress from years for aerospace qualification to months for wearable refreshes.
Product Type:
Integrated modules turn inventory fastest in Shenzhen's consumer electronics corridor, while discrete die sit in aerospace qualification pipelines for 18-24 months.
- Integrated:Multi-function modules combine amplification, filtering, and switching in single-package solutions. Automotive OEMs in Germany's KBA homologation track specify these for consolidated ECU designs where board space constraints dominate.
- Discrete:Standalone die-level components maintain premium positioning in defense applications where radiation tolerance and linearity justify longer procurement cycles. ITAR-controlled fabrication concentrates supply in US and Japanese foundries.
- RF:Specialized radio-frequency variants optimize impedance matching for 50-ohm system integration in base station infrastructure.
- Low Power:Sub-milliwatt consumption profiles enable always-on positioning in fitness trackers and smartwatches across Shenzhen's design houses.
Integrated modules dominate installed base in consumer wearables. Discrete die is where expansion concentrates for autonomous vehicle homologation.
Technology:
Process node economics stratify sharply: CMOS leverages foundry scale while compound semiconductors defend aerospace margins through radiation hardness.
- CMOS:Silicon processes exploit TSMC and GlobalFoundries geometries to shrink noise figures at consumer price points. Telecommunications infrastructure buyers are displacing legacy BiCMOS as die costs compress.
- GaAs:Gallium arsenide substrates deliver superior linearity at L5 band frequencies where precision agriculture applications demand sub-1.5 dB noise figures. ITAR-controlled pHEMT fabrication fragments competitive access.
- BiCMOS:Bipolar-CMOS hybrid processes retain niche positioning in legacy automotive modules requiring extended temperature ranges.
- SiGe:Silicon-germanium BiCMOS bridges performance gaps by embedding analog-to-digital conversion closer to antenna interfaces. German tier-1 suppliers adopt these for digitized receiver architectures.
CMOS commands volume leadership in consumer procurement. GaAs is gaining share fastest in defense-qualified tiers where radiation tolerance commands premium pricing.
End User:
Customer qualification intensity separates multiyear aerospace certification from quarterly wearable refresh cycles.
- Aerospace:Satellite payload applications mandate radiation-hardened GaN-on-SiC processes with extended temperature qualification. Defense contractors source through ITAR-restricted channels.
- Automotive:ETSI EN 303 413 homologation drives demand for sub-1.5 dB noise figure amplifiers in ADAS-equipped vehicles. German KBA type-approval incorporates CSRD carbon accounting disclosures.
- Telecommunications:Base station infrastructure procurement emphasizes CMOS cost structures for macrocell deployments.
- Consumer Electronics:Shenzhen-based module integrators negotiate direct wafer starts with foundries for fitness tracker and smartwatch die.
Consumer Electronics dominates shipment volumes. Automotive is climbing the fastest as ETSI phase-noise mandates tighten.
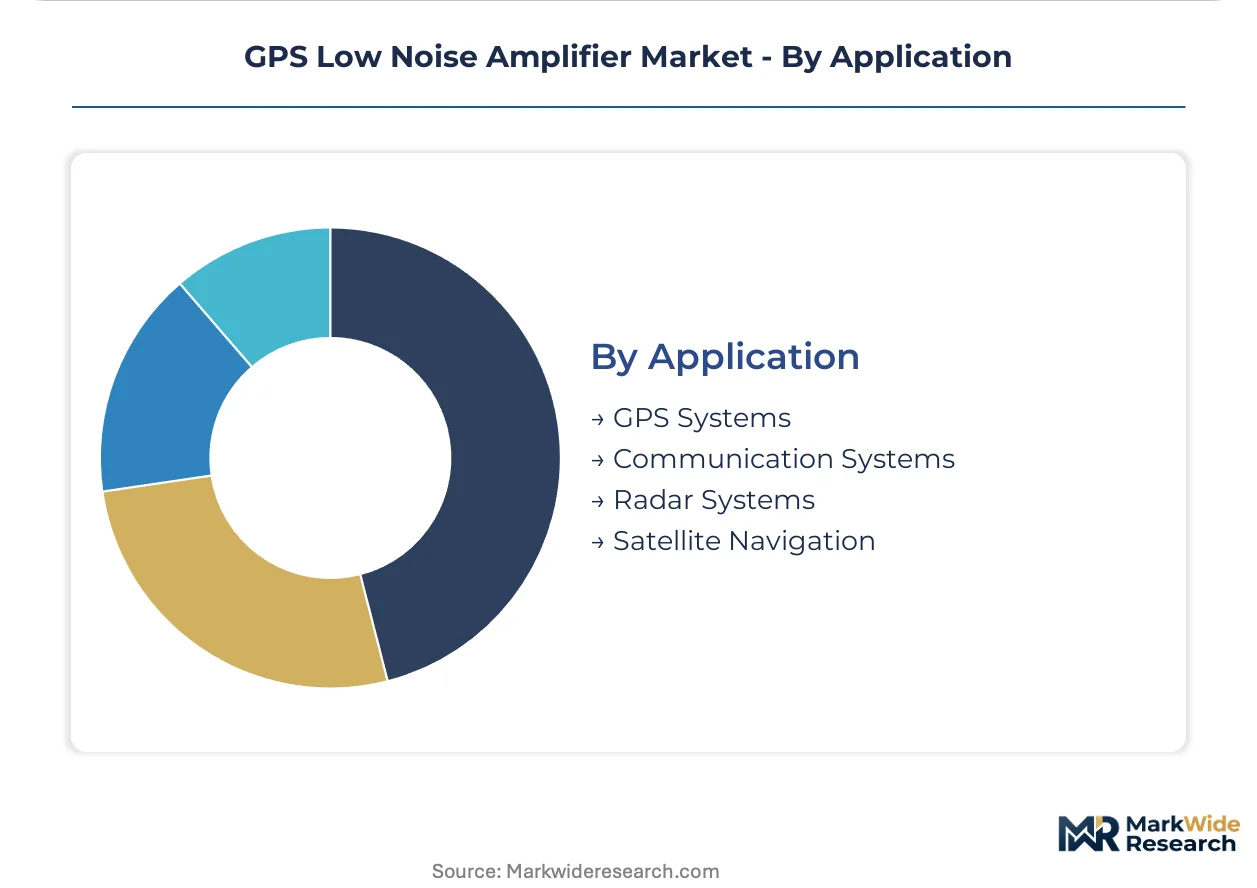
Application:
Signal chain complexity varies from single-frequency consumer reception to multiconstellation calibration across GPS, Galileo, and BeiDou.
- GPS Systems:L1/L2/L5 band reception requires simultaneous validation across multiple frequencies. China's MIIT GB standards enforce domestic encryption protocols for BeiDou-integrated modules.
- Communication Systems:Base station front-ends prioritize CMOS integration for macrocell and small cell density.
- Radar Systems:Defense applications specify GaAs linearity for electronic warfare and synthetic aperture processing.
- Satellite Navigation:Precision timing for financial networks and power grid synchronization demands temperature-compensated oscillators with integrated amplification.
GPS Systems anchor current installed base. Satellite Navigation shows steepest expansion trajectory as critical infrastructure timing requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shenzhen electronics corridor anchors Asia-Pacific supply chain throughput for precision RF components, with its port infrastructure handling substrate imports and finished module exports to automotive OEMs worldwide.
United States
Defense contractors drive demand for ITAR-controlled GaAs amplifiers in satellite payloads and electronic warfare systems. The FCC's Part 15 rules govern GPS receiver spurious emissions, tightening certification requirements for multiconstellation designs. Boston's defense technology cluster houses qualification laboratories for radiation-hardened component testing.
Germany
Automotive OEMs in Stuttgart and Munich mandate sub-1.5 dB noise figure amplifiers for ADAS-equipped vehicles under ETSI EN 303 413 homologation. The KBA type-approval process now incorporates CSRD carbon accounting disclosures for supply chain compliance. Bavaria's automotive tier-1 suppliers are consolidating ECU designs around integrated LNA modules.
China
Shenzhen's module integrators negotiate direct wafer starts with foundry partners for BeiDou-integrated consumer wearables. MIIT GB standards enforce domestic encryption protocols, fragmenting certification pathways for GPS-Galileo-BeiDou multiconstellation designs. The Yangtze River Delta hosts packaging facilities for flip-chip automotive-grade modules.
South Korea
Seoul-based RF houses specialize in thermal management for automotive-grade flip-chip assemblies. The country's national telecommunications regulator enforces receiver sensitivity benchmarks for 5G positioning infrastructure. Busan-Ulsan's packaging corridor supplies die-level assembly expertise for precision navigation hardware.
Japan
Tokyo's precision equipment manufacturers source GaAs substrates for aerospace applications requiring radiation tolerance. METI industrial standards coordinate with ETSI on automotive GNSS receiver phase-noise requirements. Kyushu's semiconductor materials cluster supplies high-purity substrates for defense-qualified amplifier tiers.
GPS Low Noise Amplifier Market Competitive Landscape
On the supply side, the industry is bifurcated between foundry-integrated module houses and specialized discrete component vendors. Compound semiconductor fabricators defend premium positioning through ITAR-controlled manufacturing lines, while silicon foundry partners capture consumer volume through CMOS geometry scaling. Three archetypes dominate: captive fab operators with automotive qualification track records, fabless design houses leveraging TSMC and GlobalFoundries capacity, and defense-qualified GaAs specialists with restricted substrate access. Competitive moves concentrate on backward integration into substrate supply and strategic partnerships with automotive tier-1 suppliers for consolidated ECU designs.
Among European captive fab operators, Infineon Technologies AG exemplifies the vertically integrated archetype with sustained supply continuity for automotive-grade die. Skyworks Solutions Inc. and Qorvo Inc. occupy positions within the compound semiconductor tier, with the former representing die-level packaging expertise and the latter anchoring defense-qualified GaAs device manufacturing. These three companies illustrate how geographic concentration of fabrication assets and regulatory qualification capabilities stratify competitive access across commercial and restricted market segments.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| Texas Instruments Incorporated |
| Analog Devices Inc. |
| Mini-Circuits |
| Panasonic Corporation |
| Skyworks Solutions Inc. |
| NXP Semiconductors N.V. |
| Broadcom Inc. |
| Qorvo Inc. |
| Others |
Supply & Pricing Matrix
The Shenzhen-Hong Kong port corridor's freight cost dynamics compress margins for consumer-grade CMOS die while amplifying price differentiation between automotive-qualified and commodity amplifier tiers. Supply concentration in Taiwan's foundry network and Japan's substrate fabrication feeds this divergence, as logistics exposure to South China Sea chokepoints shapes procurement risk premiums across buyer segments.
Pricing Analysis
Three-tier pricing structure across automotive-qualified, industrial-grade, and consumer-economy levels dominates transactional patterns. Price differentiation rests on ETSI EN 303 413 certification status and ITAR-controlled substrate access, with German OEMs absorbing premiums for KBA-homologated supply chains. Cost compression in the consumer tier intensifies as Shenzhen module houses negotiate direct wafer starts with TSMC and GlobalFoundries. Wearable manufacturers exhibit highest price sensitivity, while defense contractors show lowest elasticity due to radiation-hardening requirements.
Supply Chain Analysis
Tariff exposure between the United States and China fragments competitive access to pHEMT technology for aerospace applications. Supply concentrates in Taiwan's foundry capacity, Japan's GaAs substrate production, and South Korea's flip-chip packaging corridors. Raw material dependencies center on high-purity gallium arsenide wafers, silicon-germanium epitaxial layers, and ceramic laminate substrates. Single-source vulnerability in ITAR-controlled fabrication creates bottleneck risk for defense-qualified tiers. Distribution runs through automotive tier-1 suppliers consolidating ECU designs around integrated LNA modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GPS low noise amplifier market functions as a service-attach opportunity where calibration and qualification services expand faster than hardware shipments. Recurring revenue from automotive homologation support and defense qualification consulting outpaces die-level margin capture.
For Market Incumbents: Entrench automotive qualification track records through captive fab investments in Germany and Taiwan. Deepen backward integration into GaAs substrate supply to defend margin position against CMOS substitution in telecommunications infrastructure. Prioritize ETSI EN 303 413 certification maintenance as European OEMs consolidate supplier panels for ADAS-equipped vehicles.
For New Entrants and Emerging Players: Establish a beachhead in India's PLI-supported telecom equipment manufacturing corridor near Bengaluru's design ecosystem. Target consumer wearable module integration where board space constraints favor integrated LNA-filter-switch solutions. Pursue direct foundry partnerships with GlobalFoundries for SiGe BiCMOS geometries bridging CMOS cost and GaAs linearity.
For Investors and Strategic Acquirers: The EU AI Act's positioning requirements for autonomous systems reshapes the acquisition landscape toward certified supply chain capabilities. Five-to-ten year viability favors vertically integrated module houses with automotive qualification histories over fabless design shops. Signal to watch: KBA type-approval timelines for carbon accounting disclosures under CSRD sustainability rules.
| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Qualification Investment | KBA type-approval secures ADAS-equipped vehicle procurement from Stuttgart and Munich OEMs. |
| Backward Integration into Substrate Supply | Captive GaAs wafer access insulates margins from ITAR-controlled fabrication bottlenecks. |
| SiGe BiCMOS Process Development | German tier-1 suppliers adopt digitized receiver architectures for consolidated ECU designs. |
| India PLI Corridor Establishment | Bengaluru's design ecosystem attracts RF packaging facilities for telecom infrastructure demand. |
| CSRD Carbon Accounting Certification | European automotive OEMs mandate supply chain energy disclosure for homologation compliance. |
Research Methodology
Cross-validation between primary fieldwork with RF component procurement managers and secondary analysis of ETSI regulatory filings anchors the qualitative findings. Interviews with automotive tier-1 supplier engineers, defense contractor qualification leads, Shenzhen module house procurement directors, and foundry account managers inform demand-side dynamics. Secondary sources include FCC Part 15 rulemakings, MIIT GB standard disclosures, customs data for gallium arsenide substrate trade flows, and SEC filings from publicly traded semiconductor vendors. Bottom-up die shipment estimates triangulate against top-down automotive production forecasts for ADAS penetration.
Calibration against historical qualification timelines for aerospace and automotive components refines the projection framework. Segmentation dimensions span product type, process technology, end-user vertical, and regional regulatory cluster. CAGRs derive from fitted growth curves across the modeling period, with explicit modeling of ETSI phase-noise mandate adoption curves and China's BeiDou encryption protocol enforcement. Industry-specific inputs include foundry capacity utilization rates for GaAs and CMOS geometries, plus defense procurement budget trajectories for satellite payload applications.
Sensitivities concentrate around ITAR restriction tightening, ETSI standard revision schedules, and foundry node transition timing for SiGe BiCMOS. Forecasts embed assumptions about multiconstellation receiver adoption rates and automotive OEM consolidation of ECU designs. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
RF Spectrum Analyzer Market
RF Components
High Reliability Oscillators Market
RF Components
High-Power Microwave Source Market
RF Components
RF Passive Component Market
RF Components
Power Amplifier Market
RF Components
Global Gan RF Devices Market
RF Components
RF Gan Market
RF Components
Coaxial Connectors (RF) Market
RF Components
Japan Small Signal Transistor Market
RF Components
Global Inductors Market
RF Components
RF Antenna Market
RF Components
Tunable Inductors Market
RF Components
Radio Frequency Counter Market
RF Components
Gaas RF Switch Market
RF Components
SMD Resonator Market
RF Components
Smartphone RF Power Amplifier Market