
 Ring Panel Filters Market | 2026-2036
Ring Panel Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Ring Panel Filters Market Analytics
HEPA-grade specification upgrades is rotating demand toward higher-efficiency ring panel configurations in pharmaceutical and electronics cleanrooms. Camfil leverages its Nordic manufacturing base to supply validated filtration systems for EU-regulated drug production. Mann+Hummel anchors its position through backward integration into synthetic media production, controlling raw material quality for automotive and industrial applications. Donaldson Company competes on pleated filter geometries optimized for high-dust-load environments.
Ring panel filters are rigid-frame air filtration elements constructed from pleated media packs sealed into annular metal or cardboard housings, typically rated for MERV 11–16 efficiency or HEPA-class performance depending on media composition and pleat density. They function as primary or secondary stages in centralized air handling systems, capturing particulates to protect downstream equipment, process environments, or occupied spaces. Pleated and HEPA product types command the strongest margin pools, with pleated variants dominating volume in HVAC retrofit markets and HEPA configurations securing premium pricing in pharmaceutical and semiconductor cleanrooms. Synthetic media leads material innovation, displacing fiberglass in humidity-sensitive applications across electronics manufacturing and food processing end users.
EPA National Ambient Air Quality Standards, EU Ecodesign regulations for ventilation products, and ISO 16890 filtration testing protocols collectively tighten performance verification requirements and accelerate replacement cycles for non-compliant legacy installations. The EU F-Gas Regulation indirectly shapes demand by pushing HVAC system redesigns that integrate higher-efficiency filtration to compensate for refrigerant capacity constraints. Stakeholders must monitor evolving test standard harmonization between ASHRAE and ISO protocols, as divergent certification requirements threaten to fragment procurement specifications across multinational facility footprints.
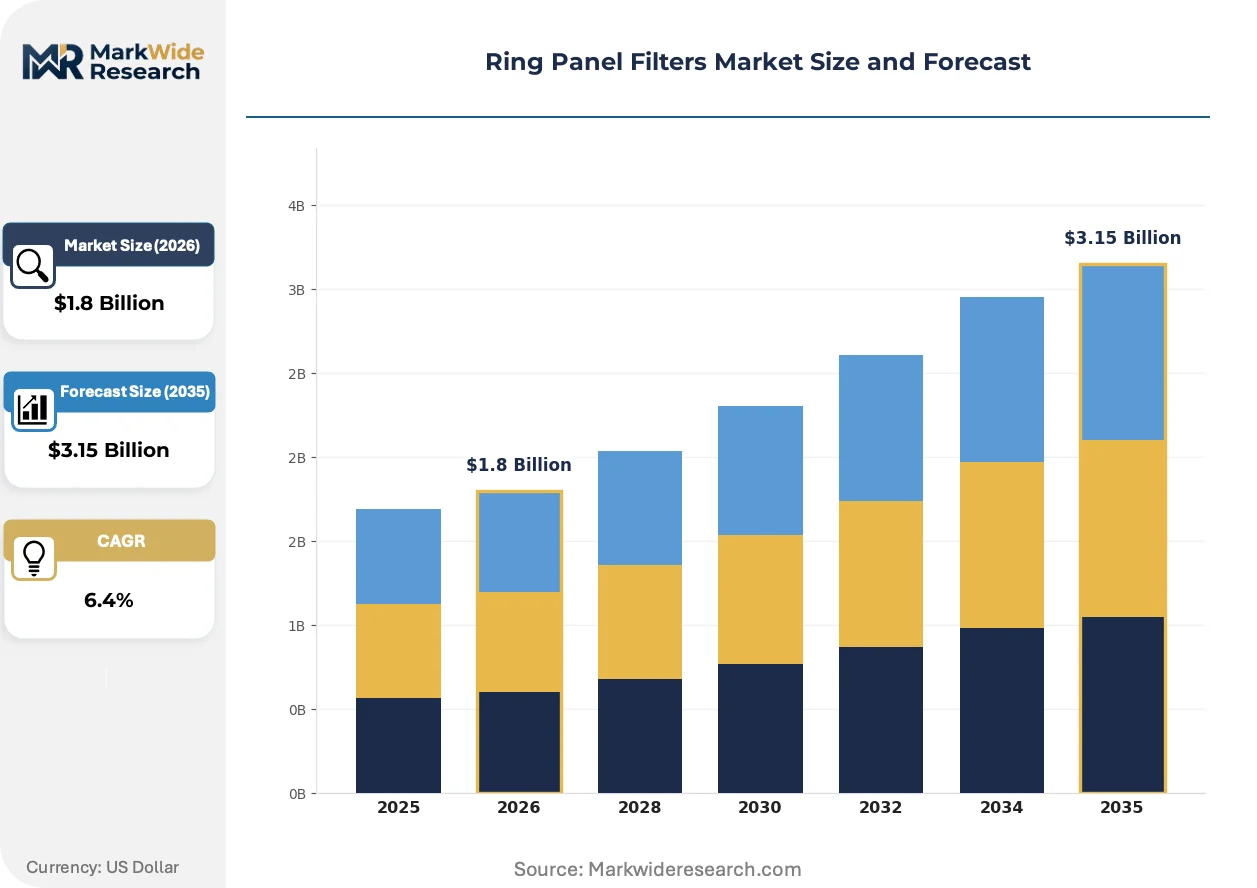
Market Dynamics
Semiconductor fabrication facilities are expanding their cleanroom filtration footprints while EPA's tightened National Ambient Air Quality Standards compel industrial operators to upgrade particulate capture systems. This dual pressure from process-driven demand and regulatory compliance is compressing replacement cycles and rotating specifications toward higher-efficiency configurations.
Growth Catalysts
- EPA National Ambient Air Quality Standards:Tightened particulate limits are forcing industrial operators across power generation and metal processing to retrofit existing air handling systems with higher-efficiency ring panel configurations.
- Synthetic media advancement:Humidity-resistant synthetic filter media are capturing share from fiberglass in electronics manufacturing and food processing applications where moisture stability determines performance longevity.
- China production capacity expansion:Domestic panel filter manufacturing clusters have scaled to serve Asia-Pacific electronics and pharmaceutical cleanroom demand, reducing import dependency for regional facility operators.
Market Restraints
- Glass microfiber supply concentration:High-grade HEPA media production remains concentrated among a limited supplier base in Germany and Japan, creating input bottlenecks for validated pharmaceutical filtration systems.
- EU F-Gas Regulation friction:HVAC system redesigns to accommodate refrigerant capacity constraints are extending project timelines and delaying filtration upgrade decisions in European commercial building retrofits.
- Electrostatic precipitator substitution:Heavy industrial applications in mining and cement production are migrating toward wet electrostatic precipitators for high-temperature gas streams where ring panel thermal limits create performance gaps.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO regulatory alignment with EU GMP standards is driving cleanroom construction in Hyderabad and Ahmedabad clusters, creating demand for validated HEPA ring panel systems.
- ISO 16890 test protocol harmonization:Convergence between ASHRAE and ISO filtration testing standards is enabling suppliers to certify once and sell across North American and European specifications.
- Condition-based monitoring integration:IoT pressure-drop sensors embedded in filter housings are enabling predictive replacement models that optimize lifecycle cost for data center and hospital operators.
Industry Challenges
- ASHRAE-ISO protocol divergence:Facilities with multinational footprints face fragmented procurement specifications where test standard misalignment forces redundant certification testing for identical filter constructions.
- Cleanroom validation timeline compression:Pharmaceutical operators requiring FDA or EMA qualification documentation are experiencing extended lead times for factory-acceptance testing and site-commissioning protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ring Panel Filters Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA, ULPA, Activated Carbon, Pleated Application: Industrial Air Quality, Cleanrooms, HVAC Systems, Odor Control Material: Fiberglass, Synthetic Media, Cellulose, Polyester End User: Manufacturing, Pharmaceuticals, Food Processing, Electronics |
| Companies Covered | AAF Flanders, Filtration Group, Camfil, Koch Filter, Mann+Hummel, Donaldson Company, Freudenberg Filtration, Nederman, Parker Hannifin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ring Panel Filters Market Evolving Landscape
Filtration media engineering and test standard evolution are compressing product development cycles while rotating procurement specifications toward performance-verified systems. These shifts are reshaping competitive positioning around validation capability rather than manufacturing scale alone.
Nanofiber surface-loading media is miniaturizing. This technology deposits sub-micron synthetic fibers onto conventional substrates to create gradient-density structures that capture fine particulates at lower pressure drop. Pharmaceutical and semiconductor cleanroom operators are specifying nanofiber-enhanced ring panels for extended service intervals. The technology is miniaturizing the physical footprint of high-efficiency filtration banks while maintaining HEPA-grade performance.
EU F-Gas Regulation is redirecting HVAC system architecture. The phasedown of hydrofluorocarbon refrigerants with high global warming potential is forcing equipment redesigns that integrate higher-efficiency filtration to compensate for reduced refrigerant capacity. Commercial building operators in Germany and France are selecting premium ring panel configurations that enable downsized compressor systems. The regulation is accelerating specification upgrades in European retrofit markets.
Facility operators are consolidating filter procurement through integrated facility management contracts. Single-source service providers are displacing direct manufacturer relationships in hospital and university campus environments. Bundled maintenance agreements now specify performance-based replacement triggers rather than calendar-based schedules. This consolidation is most visible in US healthcare systems where GPOs negotiate enterprise-wide filtration supply agreements.
Ring Panel Filters Market Segmentation
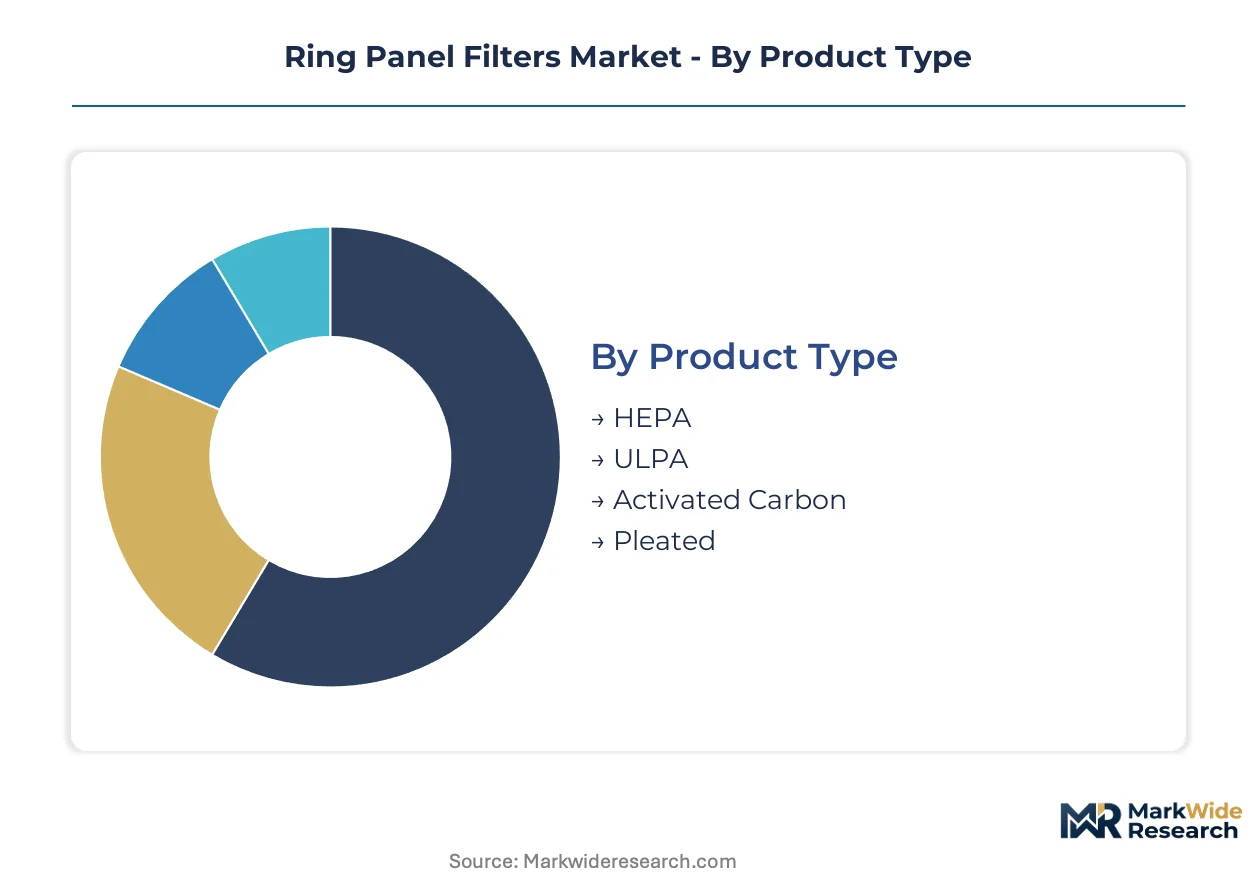
Ring panel filter procurement channels diverge sharply by specification rigor. Validated HEPA configurations flow through specialized cleanroom contractors, while standard pleated variants dominate distributor networks serving HVAC retrofit markets. Understanding these channel dynamics helps suppliers align certification investments with actual purchase pathways.
Product Type:
Channel concentration varies by efficiency tier. HEPA and ULPA specifications require factory-witnessed testing documentation, locking them into direct manufacturer relationships for pharmaceutical and semiconductor end users. Lower-efficiency pleated variants move through broad-line HVAC distributors with minimal technical pre-sale support.
- HEPA:High-efficiency particulate air configurations utilize glass microfiber media pleated to 99.97% efficiency at 0.3 microns. Demand concentrates in German pharmaceutical manufacturing clusters where EMA validation requirements mandate documented factory acceptance testing. The EPA's tightened ambient air standards are accelerating industrial adoption beyond traditional cleanroom applications.
- Pleated:Multi-layer synthetic or cellulose media constructed in rigid annular frames rated MERV 11–16. Volume concentrates in US commercial building retrofits where facility managers prioritize pressure-drop performance over absolute efficiency. The segment benefits from immediate distributor availability versus HEPA lead times.
- ULPA:Ultra-low penetration air specifications achieve 99.999% efficiency at 0.12 microns for semiconductor lithography bays. Japanese and South Korean fabrication facilities drive specification intensity.
- Activated Carbon:Impregnated media layers targeting molecular contamination and odor capture in food processing and municipal water treatment plants. Procurement runs through specialty chemical filtration distributors.
By volume, pleated configurations lead. By growth pace, HEPA specifications are climbing the fastest as EPA compliance deadlines compress replacement cycles.
Application:
Cost tier stratification separates premium validated systems from commodity replacements. Cleanroom applications command 4–6x unit pricing versus standard HVAC, with total cost of ownership calculations incorporating energy consumption and certification documentation.
- Cleanrooms:ISO 14644-compliant environments requiring continuous particulate monitoring and documented filter integrity. Indian pharmaceutical clusters in Hyderabad and Ahmedabad are expanding validated HEPA installations as CDSCO aligns with EU GMP standards. Factory acceptance testing and site commissioning protocols extend lead times but lock in multi-year supply agreements.
- HVAC Systems:Centralized air handling units in commercial buildings, hospitals, and educational facilities. US healthcare GPOs negotiate enterprise-wide supply agreements with performance-based replacement triggers replacing calendar schedules.
- Industrial Air Quality:Power generation and metal processing facilities responding to EPA National Ambient Air Quality Standards particulate limits. Retrofit demand is accelerating as compliance deadlines approach.
- Odor Control:Municipal wastewater treatment and food processing applications utilizing activated carbon or chemically impregnated media. Specification intensity varies by proximity to residential areas.
By margin contribution, cleanroom applications dominate. By volume scale, HVAC systems capture the largest unit throughput.
Material:
Supply concentration for high-grade glass microfiber creates input bottlenecks, while synthetic media production has regionalized around Asia-Pacific manufacturing clusters. Material selection increasingly determines channel access rather than merely performance characteristics.
- Synthetic Media:Polypropylene and polyester non-woven structures engineered for humidity stability and mechanical resilience. Electronics manufacturing in China's Yangtze River Delta and Pearl River Delta clusters specifies synthetic media to avoid fiberglass degradation in high-humidity cleanrooms. Domestic Chinese production capacity has scaled to serve regional demand with reduced import dependency.
- Fiberglass:Borosilicate glass microfiber achieving sub-micron filtration efficiency through depth-loading mechanisms. High-grade production remains concentrated in Germany and Japan, creating supply constraints for validated pharmaceutical filtration systems requiring documented media provenance.
- Cellulose:Wood-pulp based media for standard HVAC applications where cost sensitivity outweighs humidity performance requirements. Volume production has shifted to Southeast Asian mills.
- Polyester:Spunbond and meltblown synthetic structures for wash-resistant pre-filtration stages in heavy industrial environments. Demand tracks mining and cement production activity.
By installed base, fiberglass retains the largest share. By expansion trajectory, synthetic media is gaining share fastest in humidity-sensitive applications.
End User:
Customer type determines specification authority and procurement consolidation patterns. Pharmaceutical and electronics manufacturers retain direct technical relationships with filter suppliers, while food processing and general manufacturing increasingly delegate to integrated facility management contractors.
- Pharmaceuticals:FDA and EMA-regulated drug production facilities requiring filter validation documentation for batch release compliance. German and Swiss manufacturing clusters specify Nordic-produced filtration systems with full traceability chains. Site commissioning protocols and ongoing monitoring requirements create high switching costs.
- Electronics:Semiconductor fabrication and flat-panel display manufacturing with cleanroom classifications demanding continuous particulate control. South Korean and Taiwanese fabrication facilities specify nanofiber-enhanced configurations for extended service intervals in miniaturized filtration banks.
- Food Processing:Dairy, meat, and beverage facilities balancing hygiene requirements with moisture-laden process environments. Synthetic media specifications are displacing fiberglass in humidity-critical applications.
- Manufacturing:General industrial facilities including automotive assembly and metal fabrication responding to EPA ambient air standards. Procurement is consolidating through bundled maintenance agreements with performance-based replacement triggers.
By specification intensity, pharmaceuticals lead. By volume growth, electronics manufacturing is expanding most quickly as fabrication capacity scales across Asia-Pacific clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export dependency for high-grade glass microfiber media concentrates supply leverage in Germany and Japan, while China and India are scaling domestic synthetic media production to reduce import reliance. Filter assembly capacity is regionalizing around Asia-Pacific electronics and pharmaceutical manufacturing clusters.
United States
EPA National Ambient Air Quality Standards are compressing replacement cycles across power generation and metal processing facilities. Industrial operators in Ohio and Pennsylvania are retrofitting air handling systems ahead of compliance deadlines. Healthcare GPOs negotiate enterprise-wide filtration supply agreements with performance-based replacement triggers replacing calendar schedules.
Germany
EMA validation requirements for pharmaceutical filtration systems sustain demand for documented factory acceptance testing. EU F-Gas Regulation is accelerating HVAC system redesigns that integrate higher-efficiency ring panels to compensate for refrigerant capacity constraints. Cleanroom construction in Baden-Württemberg and Bavaria specifies Nordic-produced filtration systems with full traceability chains.
China
Domestic panel filter production capacity has expanded to serve Asia-Pacific electronics and pharmaceutical cleanroom demand. Yangtze River Delta and Pearl River Delta fabrication facilities specify synthetic media configurations to avoid fiberglass degradation in high-humidity environments. MEE enforcement of ambient air quality standards is driving industrial retrofit activity in Shandong and Jiangsu provinces.
India
CDSCO regulatory alignment with EU GMP standards is driving cleanroom construction in Hyderabad and Ahmedabad pharmaceutical clusters. Domestic filter assembly capacity is scaling to reduce import dependency for validated HEPA systems. Industrial air quality enforcement by state pollution control boards is accelerating particulate capture upgrades in Gujarat and Maharashtra manufacturing belts.
South Korea
Semiconductor lithography bay specifications for 99.999% efficiency at 0.12 microns sustain demand for ULPA ring panel configurations. Samsung and SK Hynix fabrication facilities in Gyeonggi Province specify nanofiber-enhanced configurations for extended service intervals. MFDS pharmaceutical manufacturing standards are expanding validated filtration demand beyond electronics into biologics production.
Ring Panel Filters Market Competitive Landscape
Concentration sits with diversified filtration conglomerates controlling synthetic media supply chains and specialized cleanroom validation providers serving regulated pharmaceutical production. The vendor base stratifies across three tiers: integrated media-to-filter manufacturers, regional assembly specialists, and validation-focused cleanroom contractors. Dominant competitive moves include backward integration into synthetic media production and geographic expansion through distributor network consolidation.
Within the integrated conglomerate tier, Mann+Hummel and Donaldson Company exemplify archetypes of upstream-controlled supply chains. Camfil occupies a position representing the validation-specialist vector for EU-regulated drug production. Among Nordic-based filtration providers, Nederman anchors the industrial air quality retrofit segment. These players sit within distinct competitive spaces defined by media control versus certification capability rather than direct product overlap.
| Leading Market Players |
|---|
| AAF Flanders |
| Filtration Group |
| Camfil |
| Koch Filter |
| Mann+Hummel |
| Donaldson Company |
| Freudenberg Filtration |
| Nederman |
| Parker Hannifin |
| Others |
Value Network & Pricing Analysis
Synthetic media displacement of fiberglass in humidity-sensitive electronics applications simultaneously redistributes supply geography toward China and compresses pricing premiums previously commanded by German and Japanese glass microfiber suppliers. This substitution dynamic collapses the traditional efficiency-cost tradeoff that anchored three-tier pricing structures across cleanroom and industrial segments.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing with volume scale and certification grade as the primary differentiation drivers. Three-tier pricing structure across premium HEPA-validated, standard pleated, and economy cellulose configurations stratifies procurement, with cost compression in the standard tier intensifying due to synthetic media localization. Pharmaceutical end users exhibit the lowest price sensitivity given batch release compliance requirements, while general manufacturing buyers prioritize immediate distributor availability over performance specifications.
Supply Chain Analysis
Germany and Japan anchor high-grade glass microfiber production for validated pharmaceutical filtration systems, while China scales domestic synthetic media capacity to serve Asia-Pacific electronics clusters. Raw material dependencies rest on borosilicate glass microfiber, polypropylene non-wovens, and cellulose pulp feeds, with single-source vulnerability concentrated in German HEPA media provenance documentation. Distribution runs through specialized cleanroom contractors for validated configurations and broad-line HVAC distributors for standard pleated variants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Validated filtration documentation capability represents the scarcest strategic asset in this market, with factory acceptance testing capacity and EMA qualification chains commanding premium positioning that manufacturing scale alone cannot replicate.
For Market Incumbents: Shield HEPA validation relationships through captive supply of synthetic media and expanded factory acceptance testing capacity in Nordic manufacturing bases. Electrostatic precipitator substitution in heavy industrial applications threatens ring panel volume in mining and cement segments, requiring defensive certification investment in pharmaceutical and semiconductor cleanrooms where validation switching costs lock in multi-year agreements. For New Entrants and Emerging Players: Predictive replacement service gaps in data center and hospital environments offer white-space entry points where IoT pressure-drop monitoring and condition-based maintenance contracts displace calendar-based procurement. India's pharmaceutical cleanroom construction in Hyderabad and Ahmedabad clusters presents the most penetrable geography, with CDSCO alignment to EU GMP standards creating demand for validated systems without incumbent relationship saturation. For Investors and Strategic Acquirers: The market sits at a regulatory compression phase that favors synthetic media specialists with backward integration into polymer fiber production. Long-term viability hinges on test standard harmonization outcomes between ASHRAE and ISO protocols, with acquisition targets centering on nanofiber surface-loading technology holders. The signal to watch is EPA enforcement intensity around National Ambient Air Quality Standards compliance deadlines as a volume inflection trigger.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Media | Captive polypropylene fiber production insulates margin pressure from glass microfiber supply bottlenecks. |
| Factory Acceptance Testing Capacity Expansion | EMA and FDA qualification documentation creates switching costs that lock in pharmaceutical supply agreements. |
| Nanofiber Surface-Loading Technology Licensing | Gradient-density structures extend service intervals for Samsung and SK Hynix lithography bay specifications. |
| Condition-Based Monitoring Platform Integration | IoT pressure-drop sensors enable predictive replacement contracts with US healthcare GPOs. |
| India Cleanroom Validation Partnership | CDSCO-aligned documentation capability captures Hyderabad and Ahmedabad pharmaceutical cluster demand. |
Research Methodology
Operator-level perspectives from cleanroom facility managers, pharmaceutical validation officers, HVAC procurement directors, and industrial maintenance engineers anchored the qualitative base. Primary interview insights combined with secondary validation from EPA enforcement records, EMA GMP inspection databases, ISO 16890 test protocol documentation, and customs trade data for filtration media imports. Bottom-up facility installation estimates and top-down manufacturing capacity assessments triangulated market sizing.
Sensitivity analysis across the projection horizon modeled efficiency tier, application segment, material composition, and end-user regulatory intensity as core segmentation dimensions. CAGRs derived from replacement cycle compression rates and specification upgrade trajectories, with semiconductor fabrication capacity expansion and EPA compliance deadline clustering as industry-specific volume inputs.
Underlying assumptions cover regulatory enforcement continuity and test standard convergence timelines, with deviation risk concentrated in EU F-Gas Regulation implementation pace and glass microfiber supply concentration persistence. Recalibration cycles align with material shifts in EPA ambient air standards enforcement and ISO-ASHRAE protocol harmonization outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Acousto Optic Devices Market
Optical Components
High Speed Fiber Optic Sensor Market
Optical Components
UAE Lithium Niobate Modulator Market
Optical Components
Erbium Oxide Market
Optical Components
Global Electrochromic Glass and Devices Market
Optical Components
Electronic Digital Magnifiers Market
Optical Components
Liquid Light Guides Market
Optical Components
Optical Encoder Market
Optical Components
North America Lithium Niobate Modulator Market
Optical Components
Portable Lenses Market
Optical Components
Spatial Light Modulator Market
Optical Components
Ellipsometer Market
Optical Components
CW Fiber Amplifier Market
Optical Components
Acousto Optical Cavity Dumper Market
Optical Components
Global Optical Network Hardware Market
Optical Components
RF-Over-Fiber (Rfof) Solution Market