
 RF Interconnect Market | 2026-2036
RF Interconnect Market Size, Share, and Industry Trends Forecast 2026-2036
RF Interconnect Market Intelligence
The fragmentation of the customer base, moving from consolidated defense contractors to a diverse array of telecommunications and automotive OEMs, is repositioning the competitive landscape. This shift demands greater agility in supply chain and product customization. Amphenol RF leverages its broad portfolio to serve these disparate end-markets. TE Connectivity specializes in high-reliability solutions for harsh automotive environments, while Rosenberger sustains its position through deep expertise in high-frequency test and measurement applications.
RF interconnects are components designed to transmit high-frequency signals between points in a circuit with minimal loss and distortion. These products, including coaxial cables and connectors, are engineered for specific impedance matching like 50 ohms to preserve signal integrity. While connectors and cable assemblies are mature product types, the millimeter wave technology segment is expanding quickly, driven by 5G and satellite communications. The defense application segment continues to provide stable, high-margin opportunities for specialized components.
Product design and market access are governed by standards like the FCC's rules on emissions in the United States and the EU's RoHS directive. These frameworks dictate material composition and electrical performance. Additionally, ISO 9001 certification is a common requirement for automotive and aerospace suppliers. Component selection will increasingly involve balancing the need for higher frequency performance against the cost constraints of new mass-market applications.
Market Dynamics
The expansion of 5G infrastructure creates a central tension between the need for high-performance millimeter wave components and the cost pressures of mass-market applications. This dynamic forces a trade-off between advanced material science and manufacturability at scale.
Growth Catalysts
- Millimeter Wave Adoption:The transition to higher frequency bands for 5G, satellite communications, and automotive radar systems requires new generations of coaxial connectors and cable assemblies engineered for minimal signal loss and high fidelity.
- Automotive Connectivity:Vehicle-to-everything (V2X) communication and advanced driver-assistance systems (ADAS) create substantial demand for rugged, high-reliability RF interconnects capable of operating in harsh automotive environments.
- National Infrastructure Initiatives:Government-backed 5G rollouts in countries including South Korea and China accelerate network deployments, generating large-scale, concentrated demand for RF components from telecommunications OEMs.
Market Restraints
- Signal Integrity at High Frequencies:As operating frequencies increase into the millimeter wave spectrum, RF signals become more susceptible to attenuation, reflection, and distortion, posing significant design and material science challenges.
- Material Cost Constraints:The high cost of specialized low-loss dielectric materials and precision-machined metals, necessary for high-frequency performance, limits adoption in price-sensitive consumer and mass-market applications.
- Technical Standardization Pace:The development and ratification of global standards for new wireless technologies can be a slow process, creating market uncertainty and delaying investment in compatible component manufacturing.
Strategic Opportunities
- LEO Satellite Constellations:The rapid build-out of low Earth orbit satellite networks for global broadband access presents a major new volume market for high-frequency interconnects in both space-based and ground terminal applications.
- Industrial IoT (IIoT):The deployment of private wireless networks in smart factories, particularly in industrial economies like Germany and Japan, opens a new application frontier for robust and reliable RF connectivity solutions.
- RF and Optical Convergence:Developing hybrid components that integrate RF and photonic technologies provides a pathway to overcome bandwidth limitations in data centers and high-performance computing, creating a high-value product category.
Industry Challenges
- Specialized Talent Scarcity:A shortage of RF engineers with deep expertise in millimeter wave design, simulation, and testing creates a bottleneck for innovation and slows down product development cycles across the industry.
- Supply Chain Agility:Managing a complex supply chain to serve the distinct requirements of defense, automotive, and telecommunications customers demands exceptional flexibility in manufacturing, logistics, and product customization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RF Interconnect Market |
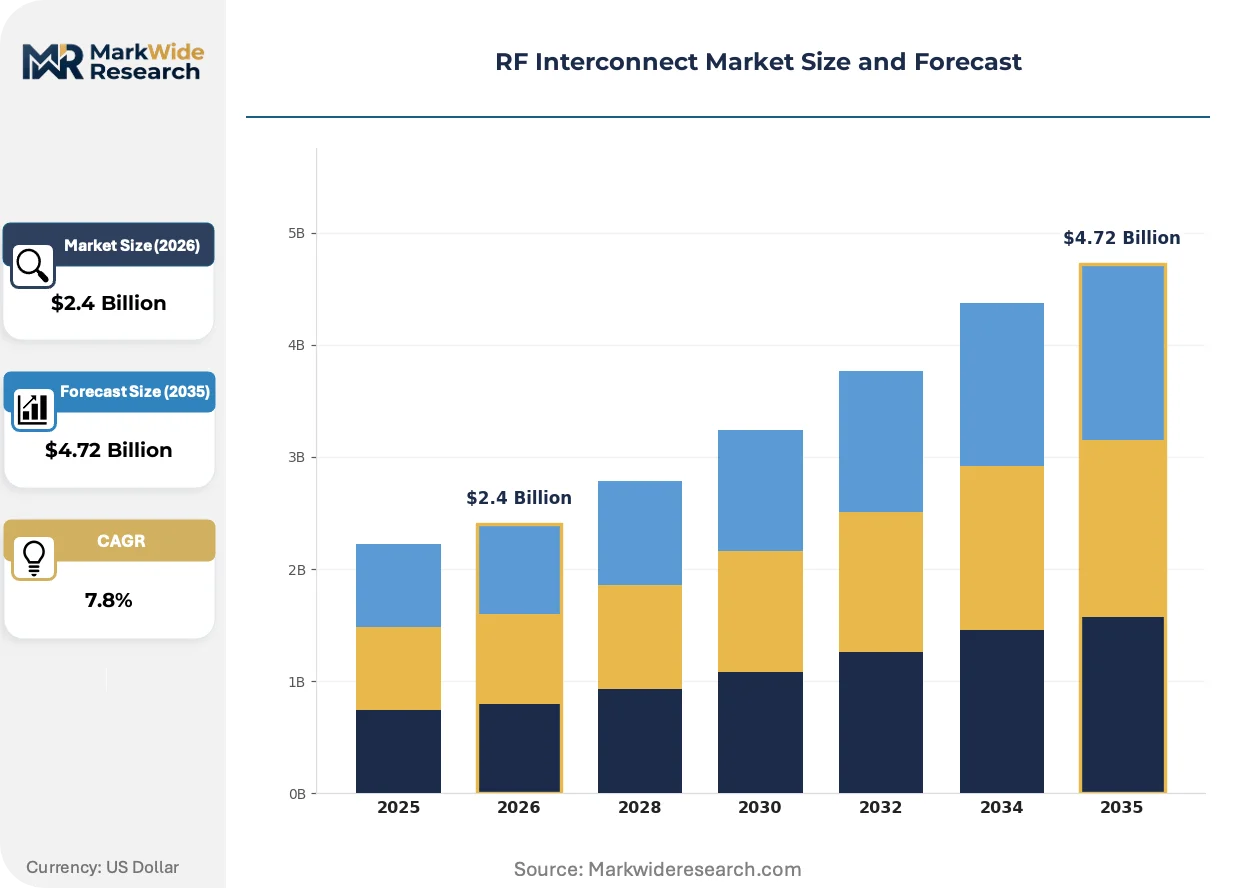
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cables, Connectors, Adapters, Assemblies Technology: Coaxial, Fiber Optic, Microwave, Millimeter Wave Application: Telecommunications, Aerospace, Automotive, Defense End User: Manufacturers, Service Providers, OEMs, System Integrators |
| Companies Covered | HUBER+SUHNER, Radiall, Amphenol RF, Corning Incorporated, Samtec, TE Connectivity, Rosenberger, Smiths Interconnect, Molex LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RF Interconnect Market Strategic Shifts & Innovations
Balancing high-frequency performance with mass-market cost constraints defines the market's evolution. Component design is shifting from specialized, high-margin applications toward standardized, high-volume production for new consumer and industrial use cases, reshaping supplier strategies.
System-in-Package (SiP) technology miniaturizes RF front-end modules by combining multiple active and passive components onto a single, compact substrate. The telecommunications and consumer electronics sectors are rapidly adopting SiP to reduce device footprints, lower power consumption, and improve performance. This technology is integrating antenna and interconnect functions directly into the semiconductor package, blurring the lines between discrete component and integrated system.
The EU's RoHS directive, which restricts the use of hazardous substances in electronic equipment, continues to shape material science across the supply chain. This regulation compels manufacturers to qualify lead-free and halogen-free alternatives for dielectrics and cable jackets without compromising electrical performance or reliability. The defense and aerospace sectors, while often granted exemptions, increasingly align with commercial standards to simplify procurement and reduce costs.
Co-development partnerships are displacing traditional off-the-shelf component purchasing models, particularly in complex system designs. Automotive and telecommunications OEMs now engage RF interconnect suppliers earlier in the design cycle to create custom solutions optimized for specific platforms. This collaborative procurement approach is most visible in North America and Europe, where system-level performance is a key competitive differentiator.
RF Interconnect Market Segmentation
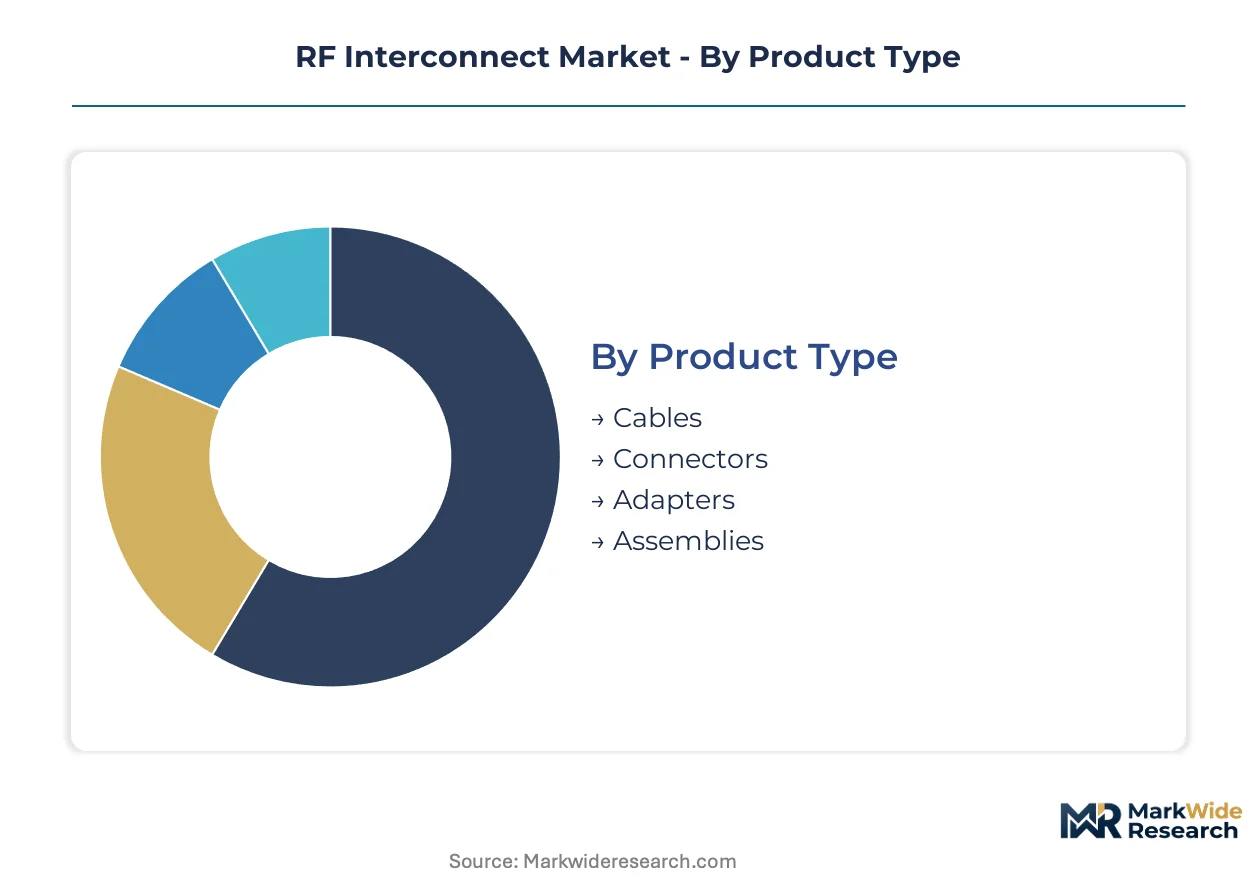
RF interconnect market segmentation highlights critical product and technology distinctions driving market expansion. This granular breakdown helps identify specific demand pockets and evolving customer requirements across diverse end-use sectors. Understanding these segments is crucial for strategic product development and market penetration.
Product Type:
The upgrade and replacement cycles of existing network infrastructure heavily influence demand for specific RF interconnect product types. New generations of communication systems necessitate performance enhancements.
- Connectors:Precision-engineered components facilitate signal transmission between cables and devices, ensuring impedance matching and minimal loss. Demand concentrates in advanced mobile network deployments within South Korea, driven by the need for high-frequency millimeter wave compatibility.
- Assemblies:Pre-assembled combinations of cables and connectors simplify installation and guarantee performance in complex systems like 5G base stations. These integrated solutions see strong demand from telecommunications OEMs in China, accelerating network rollouts.
- Cables:Coaxial cables transmit high-frequency signals, forming the backbone of many RF systems.
- Adapters:These components enable interface compatibility between different connector types in testing and deployment scenarios.
Volume placements concentrate in Cables; the faster expansion belongs to Assemblies.
Technology:
Supply concentration within the RF interconnect technology segment reflects specialized manufacturing capabilities and material science expertise. The transition to higher frequencies requires new design approaches.
- Millimeter Wave:This technology utilizes extremely high frequencies, enabling ultra-fast data rates for 5G and satellite communications. It requires advanced materials and precision engineering to overcome signal integrity challenges, with demand accelerating in North America for next-generation network infrastructure.
- Coaxial:Coaxial technology remains foundational for RF signal transmission, characterized by its shielded design for interference reduction. It provides robust performance for a wide range of applications, with consistent demand from industrial IoT deployments in Germany.
- Fiber Optic:Fiber optic technology offers high bandwidth and immunity to electromagnetic interference for long-distance data transmission.
- Microwave:Microwave technology supports various wireless communication links, including point-to-point backhaul and radar systems.
The Coaxial segment underpins traditional RF systems, while Millimeter Wave technology experiences the steepest expansion trajectory.
Application:
The market maturity of various RF interconnect applications dictates investment patterns and product development priorities. Established sectors maintain steady demand, while emerging areas drive innovation.
- Telecommunications:This segment covers RF interconnects for mobile networks, base stations, and data centers, driven by 5G build-out and increased data traffic. South Korea's rapid 5G deployment generates substantial, concentrated demand for high-performance components.
- Automotive:RF interconnects for vehicle-to-everything (V2X) communication, ADAS, and in-car infotainment systems require high reliability in harsh environments. European automotive OEMs are driving advancements in robust, temperature-resistant solutions.
- Aerospace:Aerospace applications require lightweight, high-performance RF interconnects for satellite communication and avionics systems.
- Defense:Defense applications demand highly specialized, ruggedized RF interconnects for military communication, radar, and electronic warfare systems.
Telecommunications currently commands the largest share of RF interconnect deployments, with Automotive applications gaining share fastest due to V2X and ADAS growth.
End User:
The procurement models adopted by different end-user types significantly influence supplier engagement and product customization requirements. Direct engagement with design teams is becoming more prevalent.
- Manufacturers:Component manufacturers utilize RF interconnects in their internal testing and production processes for various electronic devices. This segment requires reliable, high-volume supply for their production lines in countries like China.
- Service Providers:Telecommunication service providers deploy RF interconnects for network infrastructure, demanding high volume and consistent performance for wide-scale rollouts. Chinese network operators represent a significant volume consumer for these standardized components.
- OEMs:Original Equipment Manufacturers integrate RF interconnects into their final products, requiring close collaboration for custom solutions and early design-in. This segment drives demand for tailored components in North American telecommunications and automotive manufacturing.
- System Integrators:System integrators combine various components to deliver complete solutions, often sourcing specialized RF interconnects for complex projects.
OEMs represent a critical segment for product innovation, while Service Providers drive substantial volume procurement for network expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for RF interconnects is notably strong in countries leading advanced mobile network deployments and industrial digitalization. These regions drive significant investment in high-frequency components and infrastructure. The transition to 5G and advanced automotive systems fuels this focused demand.
South Korea
South Korea's rapid 5G deployment generates substantial, concentrated demand for high-performance components and millimeter wave compatibility. The Ministry of Science and ICT (MSIT) actively supports advanced mobile network infrastructure initiatives. The Seoul Capital Area drives innovation in telecommunications equipment manufacturing and network services.
China
China's large-scale 5G network rollouts and telecommunications OEMs create significant volume demand for RF interconnect assemblies. The Ministry of Industry and Information Technology (MIIT) supports extensive digital infrastructure expansion. The Yangtze River Delta region is a key hub for electronics manufacturing and network equipment production.
United States
North American demand for next-generation network infrastructure and LEO satellite constellations drives high-frequency interconnect innovation. The FCC's rules on emissions govern electrical performance and market access for new devices. Silicon Valley and other technology clusters concentrate research and development for advanced component design.
Germany
Industrial IoT deployments and a robust automotive sector in Germany create specific demand for reliable coaxial technology. The EU's RoHS directive influences material composition for electronic components, ensuring compliance. Bavaria and Baden-Württemberg host significant automotive and industrial electronics manufacturing clusters.
Japan
Japanese demand for industrial IoT applications and advanced automotive radar systems requires specialized high-frequency interconnect solutions. METI's initiatives support advanced manufacturing and industrial digitalization efforts. The Kanto region, including Tokyo, concentrates research and development for high-frequency technologies.
RF Interconnect Market Key Industry Players
North American producers anchor one tier; European specialists hold another, reflecting diverse market requirements. The RF interconnect market is fragmenting, shifting from consolidated defense contractors to a diverse array of telecommunications and automotive OEMs. This dynamic creates a tiered competitive landscape with distinct strategic archetypes. Companies increasingly pursue co-development partnerships and product customization to address evolving customer needs.
Within the high-reliability and specialized expertise segments, TE Connectivity and Rosenberger exemplify distinct strategic focuses. TE Connectivity occupies a position providing robust solutions for demanding automotive applications, including those in harsh environments. Rosenberger, a German-based company, anchors the high-frequency test and measurement sector with its deep expertise, particularly for high-frequency signal integrity. Amphenol RF, a US-based entity, represents broad portfolio diversification, leveraging its extensive product range to serve disparate end-markets including telecommunications and defense.
| Leading Market Players |
|---|
| HUBER+SUHNER |
| Radiall |
| Amphenol RF |
| Corning Incorporated |
| Samtec |
| TE Connectivity |
| Rosenberger |
| Smiths Interconnect |
| Molex LLC |
| Others |
Cost & Logistics Intelligence
Captive manufacturing capabilities for specialized components anchor a supplier's position, directly influencing pricing power for high-performance RF interconnects.
Pricing Analysis
Pricing for high-volume, standardized coaxial cables operates on tight transactional margins, driven by scale and manufacturing efficiency. Customization level and specific electrical performance certifications, such as ISO 9001, drive significant price differentiation for specialized components. Cost compression in mass-market applications, particularly for 5G telecommunications infrastructure, intensifies pricing pressure. Telecommunications OEMs exhibit higher price sensitivity compared to defense and aerospace customers, who prioritize reliability and performance over cost.
Supply Chain Analysis
Skilled RF engineering talent scarcity in key manufacturing hubs like the United States and Germany constrains specialized component production. The supply chain sources critical low-loss dielectric materials and precision-machined metals globally. Geographic concentration for assemblies in China and connectors in South Korea creates single-source vulnerability for certain high-volume components. Distribution runs through direct sales channels for large OEMs and system integrators, supplemented by specialized distributors for smaller volume customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The RF interconnect market is navigating a significant technology-transition phase, with millimeter wave solutions rapidly displacing legacy microwave components in high-bandwidth applications.
For Market Incumbents: Hedge against commoditization by investing in advanced material science for millimeter wave applications and System-in-Package (SiP) integration capabilities. Pursue co-development partnerships with telecommunications and automotive OEMs to lock in design wins early. Strengthen ISO 9001 certification and expand vertical integration into critical manufacturing processes to counter emerging specialized entrants and maintain margin control.
For New Entrants and Emerging Players: Millimeter wave component specialization offers a technology-first wedge into emerging 5G infrastructure and LEO satellite constellations. Target underserved Industrial IoT private network deployments in Germany and Japan as white-space opportunities. Forge collaborative procurement relationships with European automotive OEMs to integrate robust, temperature-resistant solutions for V2X and ADAS systems.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized technology firms with proprietary millimeter wave material expertise or unique SiP integration capabilities. The market exhibits strong long-term viability over the next 5-10 years, driven by persistent data demand and new wireless frontiers. Watch the acceleration of global LEO satellite deployment contracts as a key inflection indicator for high-frequency interconnect volume.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Millimeter Wave R&D | This deepens technical expertise for 5G and satellite communication components. |
| Expand SiP Integration Capabilities | This enables miniaturization and performance enhancement for telecommunications devices. |
| Form Co-development Partnerships | This secures early design-ins with North American telecommunications and automotive OEMs. |
| Strengthen Supply Chain Resilience | This mitigates single-source risks for specialized dielectric materials. |
| Target Industrial IoT Connectivity | This unlocks new application frontiers in Germany for robust RF solutions. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing a robust foundation for market sizing and trend analysis. Primary interviews with RF engineers, telecommunications OEMs, automotive Tier 1 suppliers, and material scientists validated initial findings. Bottom-up and top-down triangulation ensured data consistency across various market segments.
Market granularity was modeled across product types, technology segments, key applications, and major end-user archetypes at a country level for demand concentration. CAGRs were derived from historical growth patterns and projected technology adoption rates over the projection horizon. Key industry-specific forecast inputs included global 5G rollout schedules and automotive ADAS penetration rates.
Several conditions sit outside the modeled scope, including unforeseen geopolitical disruptions impacting raw material supply and rapid shifts in global economic policy. Forecasts reflect assumptions regarding technological stability and regulatory frameworks across the analysis window. Material deviation in these named triggers warrants pause and re-evaluation of current market projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
5G Driver Amplifier Market
RF Components
Harness-Level EMI and Shielding Component Systems Market
RF Components
Global RF and Microwave Power Transistors Market
RF Components
Radio Frequency Front End Module Market
RF Components
Americas Small Signal Transistor Market
RF Components
RF Power Amplifiers Market
RF Components
Tunable Capacitors Market
RF Components
RFID Tags Market
RF Components
High-Power Microwave Source Market
RF Components
RF Gan Market
RF Components
Global Gan RF Devices Market
RF Components
RFID Antenna Market
RF Components
Frequency Synthesizer Market
RF Components
Silicon Tuners Market
RF Components
Toroid Inductor Market
RF Components
Ultra-Wideband (UWB) Market