
 High Power RF Amplifier Module Market | 2026-2036
High Power RF Amplifier Module Market Size, Share, and Industry Trends Forecast 2026-2036
High Power RF Amplifier Module Market Outlook
The EU Green Deal is restructuring procurement criteria for high power RF amplifier modules across European defense and satellite ground stations. Qorvo Inc. leverages its GaN foundry partnerships to sustain technology leadership in L-band radar transmitters. NXP Semiconductors N.V. anchors European supply security through its dedicated RF manufacturing in the Netherlands. MACOM Technology Solutions Holdings Inc. differentiates via its dominance in pulsed radar applications for aerospace manufacturers.
High power RF amplifier modules are electronic subsystems that boost radio frequency signals to wattage levels exceeding hundreds or thousands of watts, typically employing gallium nitride or LDMOS transistor architectures with thermal management substrates and waveguide or coaxial output interfaces. Their primary purpose is enabling long-range transmission in radar, satellite uplink, and broadcast systems where signal integrity at distance determines operational effectiveness. Solid state technology leads volume shipments due to reliability advantages, while GaN technology captures the fastest expansion as thermal efficiency improvements reduce cooling system mass in mobile radar platforms. Vacuum tube amplifiers retain margin concentration in scientific research applications requiring multi-megawatt peak outputs.
FCC spectrum allocation rulings and the EU F-Gas Regulation jointly constrain thermal management refrigerant choices and electromagnetic emission profiles for domestically deployed RF systems. REACH substance restrictions and CE marking requirements under the EU MDR framework shape material selection and market access for modules entering European defense supply chains. Stakeholders must monitor evolving ITAR and EAR export control classifications that govern GaN-on-SiC wafer transfers to foundry partners outside allied nations.
Market Dynamics
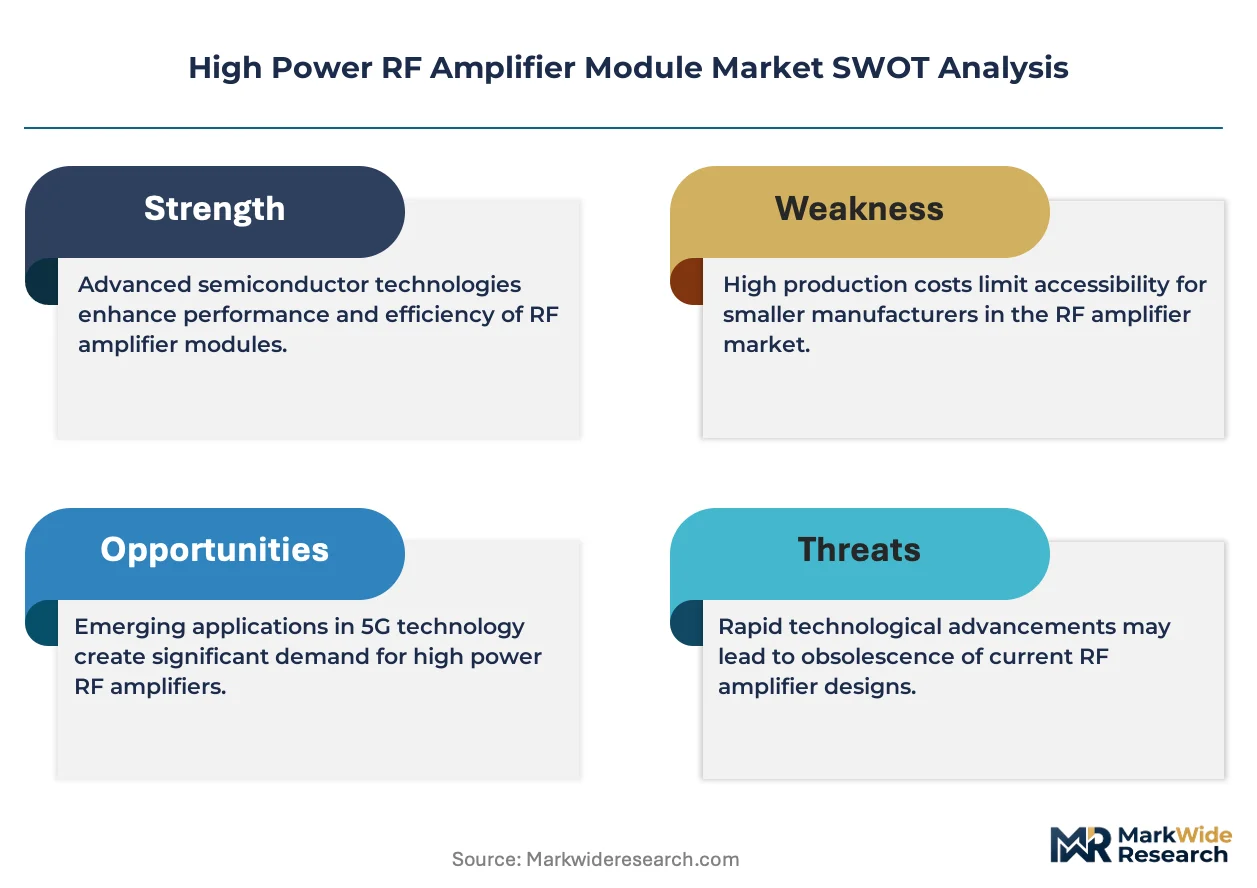
GaN-on-SiC thermal efficiency gains are compressing cooling system mass requirements across mobile radar platforms, forcing incumbent LDMOS suppliers to accelerate process node transitions or cede share in high-frequency segments.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of hydrofluorocarbon refrigerants is accelerating adoption of liquid-cooled GaN modules in satellite ground stations seeking compliant thermal management architectures.
- Defense radar modernization:NATO member states are prioritizing solid-state transmitters for active electronically scanned array upgrades, creating sustained demand for high-reliability amplifier modules.
- Gallium nitride bandgap advantages:Higher breakdown voltage and power density versus silicon LDMOS is enabling single-chip replacements of multi-transistor assemblies in pulsed applications.
Market Restraints
- Substrate supply concentration:GaN-on-SiC epitaxial wafer production concentrates among three merchant foundries, creating vulnerability to export control disruptions or capacity allocation decisions.
- REACH substance restrictions:Lead-free solder mandates and hazardous substance limitations under EU compliance frameworks elevate assembly costs and qualification timelines for European defense suppliers.
- Technical thermal dissipation ceilings:Power-combining losses and junction temperature limits constrain practical output power scaling beyond certain frequency-threshold boundaries without exotic cooling.
Strategic Opportunities
- India defense indigenization:The country's PLI scheme and domestic procurement preferences for critical RF subsystems create entry pathways for module suppliers establishing local assembly partnerships.
- Dual-use satellite ground stations:Commercial low-earth orbit constellation operators are adopting military-grade amplifier reliability standards, expanding addressable market beyond traditional defense contractors.
- 5G mmWave backhaul convergence:E-band and V-band power amplifier requirements for terrestrial wireless infrastructure overlap with radar frequency bands, enabling technology transfer between adjacent verticals.
Industry Challenges
- GaN process engineering talent scarcity:Foundry-level expertise in epitaxial growth and device modeling remains concentrated among a limited pool of specialists, constraining capacity expansion timelines.
- ITAR/EAR classification complexity:Evolving export control interpretations for wide-bandgap semiconductor substrates create compliance uncertainty for multinational supply chains with offshore packaging operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Power RF Amplifier Module Market |
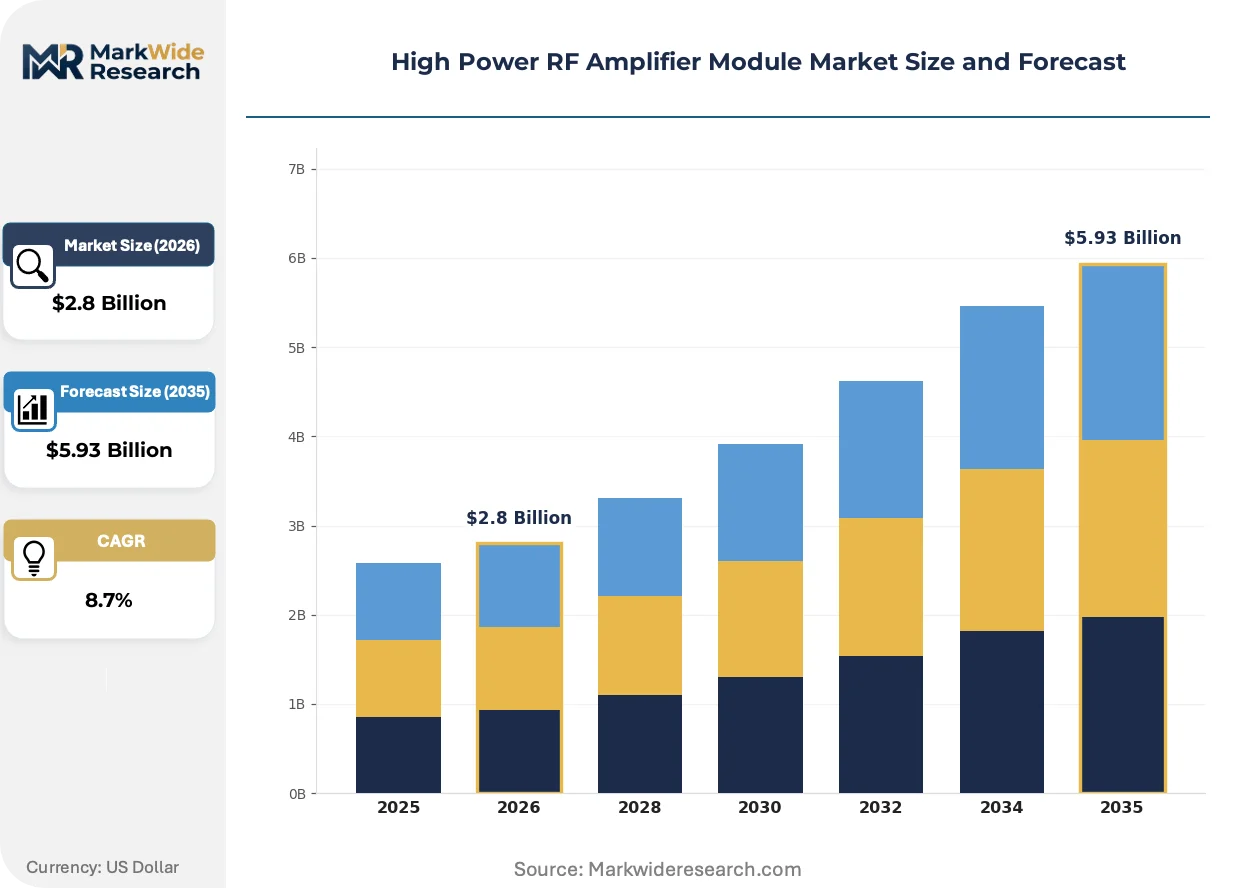
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid State, Vacuum Tube, Hybrid, Monolithic Microwave Integrated Circuit, Planar Technology: GaN, LDMOS, GaAs, SiGe, Si LDMOS Application: Telecommunication, Radar Systems, Satellite Uplink, Test & Measurement, Scientific Research End User: Defense Contractors, Satellite Operators, Broadcasting Stations, Research Institutions, Aerospace Manufacturers |
| Companies Covered | Keysight Technologies Inc., Qorvo Inc., NXP Semiconductors N.V., Ampleon Netherlands B.V., MACOM Technology Solutions Holdings Inc., Analog Devices Inc., Teledyne Technologies Incorporated, RFHIC Corporation, Renesas Electronics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Power RF Amplifier Module Market Strategic Shifts
Digital predistortion and envelope tracking techniques are penetrating transmitter architectures previously dominated by analog-only signal chains, compressing spectral regrowth margins and enabling closer channel spacing.
GaN HEMT devices with integrated gate drivers is automating bias sequencing and thermal protection functions previously implemented with discrete peripheral circuits. Radar prime contractors in Germany and the United States are specifying these intelligent amplifiers for unattended remote installations. The automation of protection logic is reducing field failure rates and enabling longer maintenance intervals in geographically dispersed assets.
The EU Green Deal's embodied carbon reporting requirements under CSRD are forcing module manufacturers to document supply chain emissions from substrate mining through end-of-life disposal. Defense contractors bidding on KBA-supervised infrastructure projects must now submit lifecycle assessments alongside technical proposals. This regulatory layer is favoring European-based packaging and test houses with verifiable renewable energy sourcing.
Consolidated procurement by satellite operators is compressing vendor qualification cycles and unbundling traditional hardware-service bundles. Ground station operators in the United States are moving toward direct amplifier sourcing from component specialists rather than full-system integrators, disintermediating legacy distribution channels. This pattern is most pronounced among low-earth orbit constellation providers operating high-volume gateway deployments.
High Power RF Amplifier Module Market Segmentation
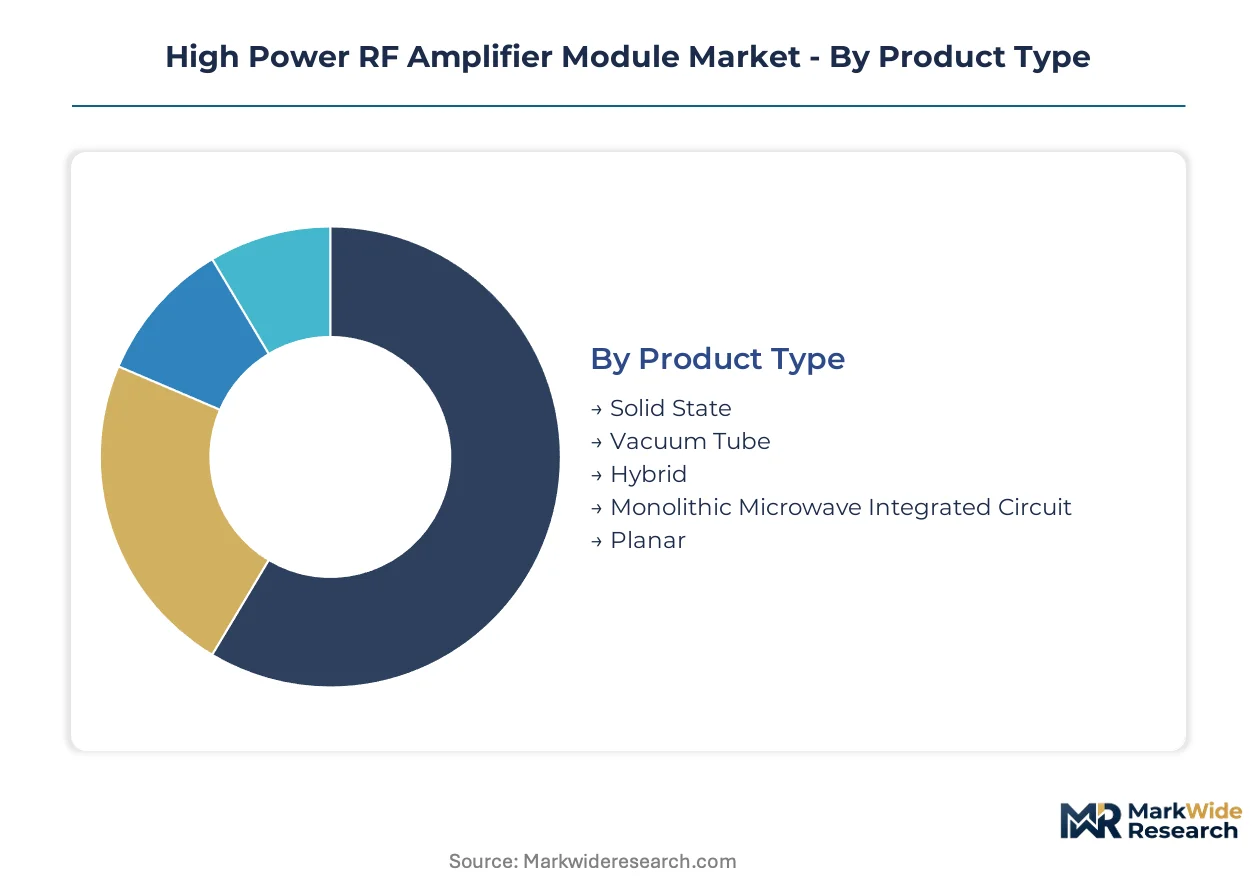
High power RF amplifier modules serve radically different thermal, frequency, and reliability requirements across defense radar, satellite ground stations, and broadcast infrastructure. Technology selection and packaging architecture directly determine operational envelope, maintenance interval, and qualification pathway for each deployment scenario.
Product Type:
Solid-state architectures dominate volume shipments through reliability advantages in fielded military systems, while vacuum tube technology retains niche concentration where peak power density exceeds solid-state thermal dissipation limits.
- Solid State:Gallium nitride and silicon LDMOS transistor arrays on thermally conductive substrates enable modular repair and graceful degradation in phased-array radar transmitters. NATO radar modernization programs in Germany and the United States specify solid-state transmitters for active electronically scanned array upgrades, creating sustained procurement volume for qualified suppliers.
- Vacuum Tube:Magnetron and klystron architectures deliver multi-megawatt peak outputs for scientific research applications including particle acceleration and fusion plasma heating. Demand concentrates at CERN in Switzerland and national laboratory facilities in the United States where legacy infrastructure and extreme power requirements perpetuate tube-based procurement.
- Hybrid:Combines solid-state driver stages with vacuum tube final amplifiers to balance efficiency and peak power in specialized broadcast transmitters.
- Monolithic Microwave Integrated Circuit:MMIC implementations integrate multiple gain stages on single chips for compact satellite uplink terminals and unmanned aerial vehicle payloads.
- Planar:Microstrip and stripline constructions on ceramic or organic laminates serve lower-power test equipment and laboratory instrumentation.
Mature deployment sits with Vacuum Tube technology in legacy scientific infrastructure. Newer deployment is concentrated in Solid State architectures for mobile radar platforms.
Technology:
Wide-bandgap semiconductor bandgap energy determines breakdown voltage, thermal conductivity, and switching frequency ceiling for each process node.
- GaN:Gallium nitride-on-silicon carbide HEMT devices achieve power densities exceeding silicon alternatives by factor of five, enabling single-chip replacements of multi-transistor LDMOS assemblies. Thermal efficiency gains compress cooling system mass in mobile radar platforms, with German defense contractors specifying GaN modules for KBA-supervised critical infrastructure.
- LDMOS:Laterally-diffused metal oxide semiconductor remains cost-optimized for UHF broadcast transmitters and lower-frequency radar bands where silicon process maturity sustains price competitiveness. European REACH compliance requirements for lead-free solder assembly favor established LDMOS packaging houses with qualified European manufacturing.
- GaAs:Gallium arsenide retains position in millimeter-wave satellite uplink amplifiers through established foundry infrastructure.
- SiGe:Silicon-germanium BiCMOS serves low-noise receiver front-ends and driver stages rather than final power amplification.
- Si LDMOS:Pure silicon variants without lateral diffusion optimization occupy cost-sensitive commercial broadcast applications.
Volume concentration remains with LDMOS in terrestrial broadcast infrastructure. Steepest expansion trajectory belongs to GaN as thermal efficiency improvements reduce cooling mass in mobile platforms.
Application:
Frequency allocation, duty cycle, and environmental exposure create divergent specification requirements across transmission scenarios.
- Telecommunication:Base station and backhaul amplifiers operate in continuous-wave mode with stringent adjacent-channel interference specifications. 5G mmWave E-band and V-band requirements overlap with radar frequency allocations, enabling technology transfer between verticals.
- Radar Systems:Pulsed operation with microsecond duty cycles demands rapid thermal cycling tolerance and bias sequencing protection. MACOM Technology Solutions dominates this segment through specialized pulsed radar module designs for aerospace manufacturers.
- Satellite Uplink:High-altitude operation and radiation exposure drive hermetic packaging and reliability screening. Commercial low-earth orbit constellation operators are adopting military-grade reliability standards, expanding addressable market beyond traditional defense contractors.
- Test & Measurement:Broadband, linear amplification for spectrum analyzers and signal generators requires flat gain response across octave bandwidths.
- Scientific Research:Extreme peak power for particle acceleration and plasma heating perpetuates vacuum tube dominance in this niche.
Established procurement volume centers on Radar Systems for defense modernization. Emerging deployment is concentrating in Satellite Uplink as commercial constellation operators multiply gateway requirements.
End User:
Procurement authority, qualification timeline, and supply security requirements segment demand across institutional categories.
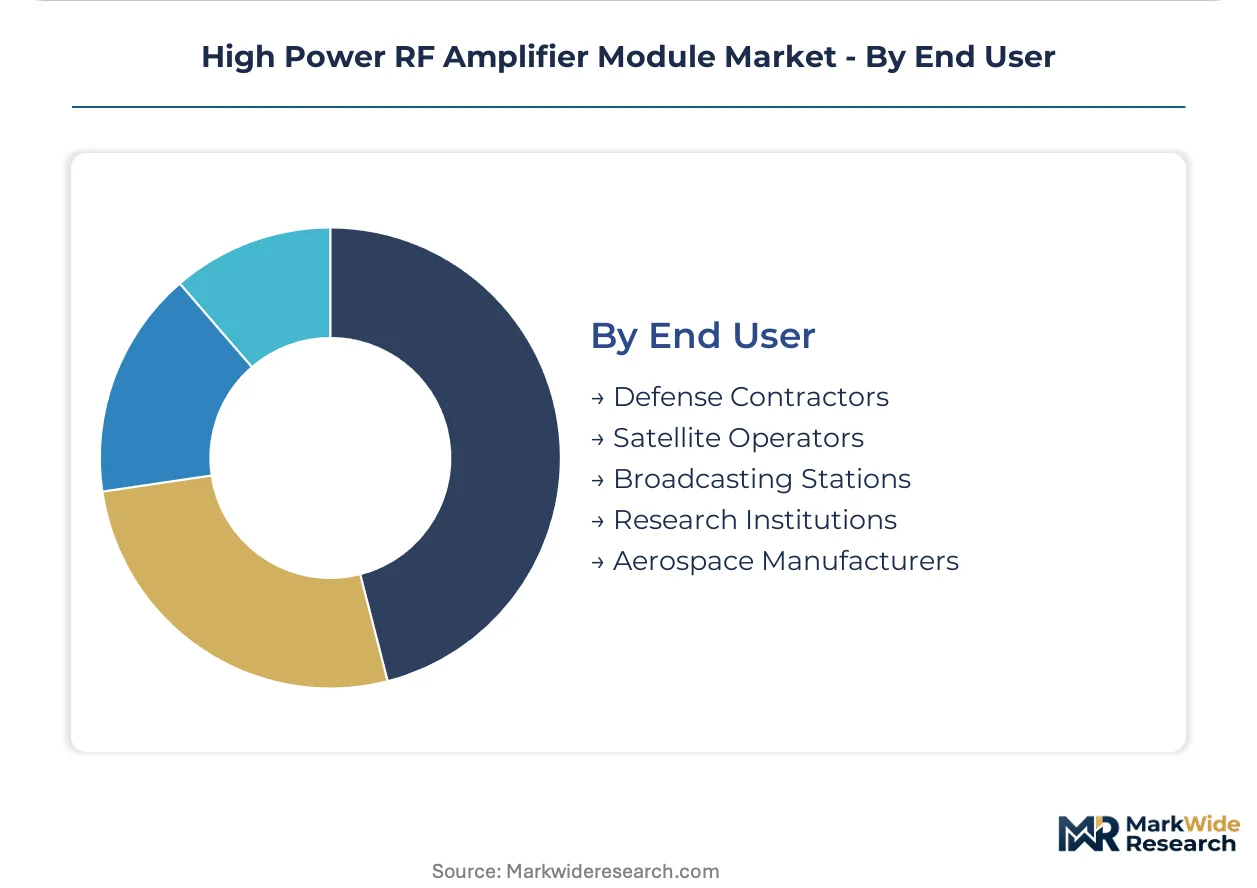
- Defense Contractors:Prime contractors for radar and electronic warfare systems impose ITAR and EAR compliance, extended qualification cycles, and domestic sourcing mandates. Qorvo leverages GaN foundry partnerships to sustain technology leadership in L-band radar transmitters for this customer set.
- Satellite Operators:Ground station procurement is consolidating among low-earth orbit constellation providers who disintermediate traditional system integrators. Direct amplifier sourcing from component specialists compresses vendor qualification cycles and unbundles hardware-service arrangements.
- Broadcasting Stations:Terrestrial television and radio transmitters operate under national spectrum licensing with decade-long replacement cycles.
- Research Institutions:National laboratories and university facilities procure through grant-funded acquisition with extended technical evaluation periods.
- Aerospace Manufacturers:Airframe integrators specify modules for weather radar and communications systems with DO-160 environmental qualification.
Contracted volume concentrates with Defense Contractors through multi-year radar platform programs. Fastest-growing procurement is emerging from Satellite Operators as constellation deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates among GaN-on-SiC foundries in the United States and Japan, while consumption tilts toward NATO defense procurement hubs in Germany and satellite gateway clusters in the United States and India.
United States
Defense radar modernization and commercial low-earth orbit constellation deployment drive procurement volume. FCC spectrum allocation rulings constrain electromagnetic emission profiles for domestically deployed RF systems. Gateway infrastructure in California and Texas anchors satellite uplink amplifier demand as SpaceX and Amazon Kuiper expand ground station networks.
Germany
KBA and BSI procurement standards favor domestic and near-shore module suppliers for critical infrastructure applications. EU Green Deal embodied carbon reporting requirements under CSRD force module manufacturers to document supply chain emissions. Bavaria-based defense contractors specify GaN modules for radar platforms supervised by federal security authorities.
Japan
METI industrial policy supports wide-bandgap semiconductor substrate production for export to allied defense supply chains. Domestic content requirements in telecommunications infrastructure protect local LDMOS packaging houses. Nagoya-area manufacturers supply hermetic amplifiers for satellite uplink terminals serving Asia-Pacific constellations.
India
The PLI scheme and domestic procurement preferences for critical RF subsystems create entry pathways for module suppliers establishing local assembly partnerships. TRAI spectrum management frameworks shape frequency allocation for 5G backhaul overlapping with radar bands. Bengaluru and Hyderabad clusters host emerging defense electronics integrators sourcing amplifiers for indigenous radar programs.
United Kingdom
Defense and Security Industrial Strategy prioritizes sovereign capability in RF subsystems for electronic warfare and radar applications. Export control alignment with ITAR and EAR classifications governs GaN wafer transfers to foundry partners. South England aerospace clusters specify qualified amplifiers for weather radar and communications systems on commercial airframes.
High Power RF Amplifier Module Market Competitive Environment
The competitive structure tilts toward integrated device manufacturers with captive GaN foundry access. Three tiers emerge: multinational semiconductor conglomerates with defense-qualified product lines, specialized RF component houses focused on pulsed radar applications, and regional packaging specialists serving broadcast infrastructure. Capacity expansion and strategic foundry partnerships constitute the dominant competitive moves as substrate supply concentration creates vulnerability to disruption.
Within the integrated-device-manufacturer tier, Qorvo Inc., NXP Semiconductors N.V., and MACOM Technology Solutions Holdings Inc. exemplify contrasting geographic and technological positioning. Qorvo represents the GaN-focused archetype leveraging foundry partnerships for L-band radar transmitters. NXP anchors European supply security through Netherlands-based RF manufacturing. MACOM occupies the pulsed radar specialization vector for aerospace manufacturers. These three entities illustrate how technology focus and geographic manufacturing placement segment competitive positioning in defense and satellite ground station procurement.
| Leading Market Players |
|---|
| Keysight Technologies Inc. |
| Qorvo Inc. |
| NXP Semiconductors N.V. |
| Ampleon Netherlands B.V. |
| MACOM Technology Solutions Holdings Inc. |
| Analog Devices Inc. |
| Teledyne Technologies Incorporated |
| RFHIC Corporation |
| Renesas Electronics Corporation |
| Others |
Value Chain & Pricing Dynamics
Defense contractor procurement concentration around NATO radar modernization programs sustains contract-based long-term offtake pricing with volume-scale discounts anchoring negotiations. German KBA-supervised infrastructure bids and U.S. Department of Defense sourcing requirements create qualified-supplier premiums that insulate incumbent GaN module manufacturers from spot-market volatility.
Pricing Analysis
Margin tightening in standard-grade LDMOS modules reflects accelerating process node transitions as silicon suppliers defend frequency segments against GaN displacement. Three-tier pricing structure across ITAR-qualified defense, CE-marked commercial, and uncertified industrial levels segments buyer access. Cost-down pressure on broadcast infrastructure amplifiers intensifies as terrestrial television replacement cycles extend. Satellite operators exhibit lowest price sensitivity due to reliability-weighted total cost of ownership calculations, while commercial 5G backhaul procurement shows highest sensitivity to per-unit capital expenditure.
Supply Chain Analysis
Direct-to-OEM channels handle defense prime contractor demand, while distribution through specialized RF component distributors serves broadcast and test equipment buyers. GaN-on-SiC epitaxial wafer production concentrates in the United States, Japan, and Germany, with substrate supply anchored in silicon carbide boule growers in these same markets. Raw material dependencies include high-purity gallium metal, silicon carbide substrates, and ceramic packaging materials. Single-source vulnerability around merchant GaN foundry capacity creates qualification timeline risk for module suppliers seeking second-source approval. Distribution runs through authorized distributors with ITAR compliance certification for defense-bound shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive GaN-on-SiC epitaxial capacity represents the decisive upstream lever as substrate supply concentration constrains competitor expansion timelines.
For Market Incumbents: Cement technology leadership through backward integration into GaN foundry partnerships or substrate supply agreements, insulating against export control disruptions. Defend qualified-supplier status in German KBA and U.S. defense procurement channels through sustained certification investment against emerging Asian packaging houses. For New Entrants and Emerging Players: Launch via local assembly partnerships in India under PLI scheme incentives, targeting indigenous radar programs with transferred LDMOS process expertise. Penetrate commercial low-earth orbit ground station procurement directly, disintermediating legacy system integrators through military-grade reliability positioning at commercial price points. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized pulsed radar module houses with established aerospace manufacturer qualifications in the United States and Germany. Long-term viability hinges on GaN process engineering talent retention and ITAR-compliant manufacturing footprint. Watch for inflection signals in India defense indigenization contract awards to foreign-qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Foundry Partnership | Secures substrate allocation priority from U.S. and Japanese merchant foundries for defense-qualified production. |
| ITAR Compliance Investment | Unlocks NATO radar modernization procurement channels requiring controlled technology handling certification. |
| India Local Assembly Partnership | Positions for PLI scheme incentives and domestic procurement preferences in indigenous defense programs. |
| Digital Predistortion Integration | Enables spectral efficiency gains that differentiate transmitter architectures for satellite ground station operators. |
| REACH-Compliant Packaging Transition | Satisfies EU Green Deal embodied carbon reporting for KBA-supervised critical infrastructure bids. |
Study Parameters
Document review covered SEC 10-K filings, EU defense procurement registers, and TRAI spectrum allocation notices, complemented by interviews with GaN foundry engineering directors, defense prime contractor procurement leads, satellite ground station operators, and RF component distribution channel managers. Bottom-up module shipment estimates triangulated against top-down defense budget allocation analysis across NATO member states.
Cross-referencing historical capacity expansion patterns with panel input from substrate manufacturers anchored the projection framework across the analysis window. Segmentation modeling incorporated technology node, application frequency band, end-user procurement authority, and regional regulatory cluster dimensions. CAGRs derived from fitted growth curves adjusted for qualification timeline delays and export control probability weighting.
The model assumes a particular technology adoption path; alternative pathways for silicon carbide substrate manufacturing would alter the outlook for GaN module cost trajectories. Forecasts reflect assumptions around REACH compliance timeline adherence and ITAR classification stability. Periodic stress-testing of base assumptions against foundry capacity allocation decisions and defense procurement cycle delays is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
UHF RFID Inlays Market
RF Components
RF Power Amplifiers Market
RF Components
High-Power Microwave Source Market
RF Components
RF Acoustic Wave Filters Market
RF Components
EMI Microwave Absorber Market
RF Components
Global RF and Microwave Power Transistors Market
RF Components
RF Interconnect Market
RF Components
Space Traveling Wave Tube Amplifiers Market
RF Components
RF and Microwave Diodes Market
RF Components
Toroid Inductor Market
RF Components
FBAR Devices Market
RF Components
Radio Frequency Duplexer Market
RF Components
Silicon Tuners Market
RF Components
Small Signal Mosfets Market
RF Components
RF Duplexer Market
RF Components
RF-Microwave for 5G Market